
 Nuclear Polar Crane Market | 2026-2036
Nuclear Polar Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Polar Crane Market Insights
Direct procurement channels between crane manufacturers and nuclear utilities is fragmenting as engineering-procurement-construction contractors and specialized nuclear service integrators capture intermediate margin pools. Konecranes leverages its aftermarket service network to sustain long-term maintenance contracts across European reactor sites. Dalian Huarui Heavy Industry anchors supply relationships with Chinese state-owned nuclear developers through localized manufacturing and domestic certification pathways.
A nuclear polar crane is a specialized overhead lifting system designed to traverse a circular rail mounted on the reactor building dome, typically rated for loads exceeding 300 tons and engineered to operate within containment radiation zones. Its primary function involves reactor pressure vessel head removal, steam generator replacement, and spent fuel cask handling during refueling outages. Fixed crane installations dominate capital expenditure allocation due to permanent integration with containment structures and higher seismic qualification requirements. Electric drive technology leads operational deployments, though hybrid systems are gaining traction where utilities seek to reduce standby power consumption during extended outage periods.
ASME NOG-1 standards govern overhead crane construction for nuclear facilities in the United States, while RCC-M codes apply across French-designed reactor fleets and their export markets. China's National Nuclear Safety Administration enforces HAF regulations that mandate domestic supplier qualification, creating market access barriers for foreign equipment vendors. Stakeholders must monitor evolving decommissioning liability frameworks and spent fuel storage expansion timelines to align crane fleet planning with reactor lifecycle transitions.
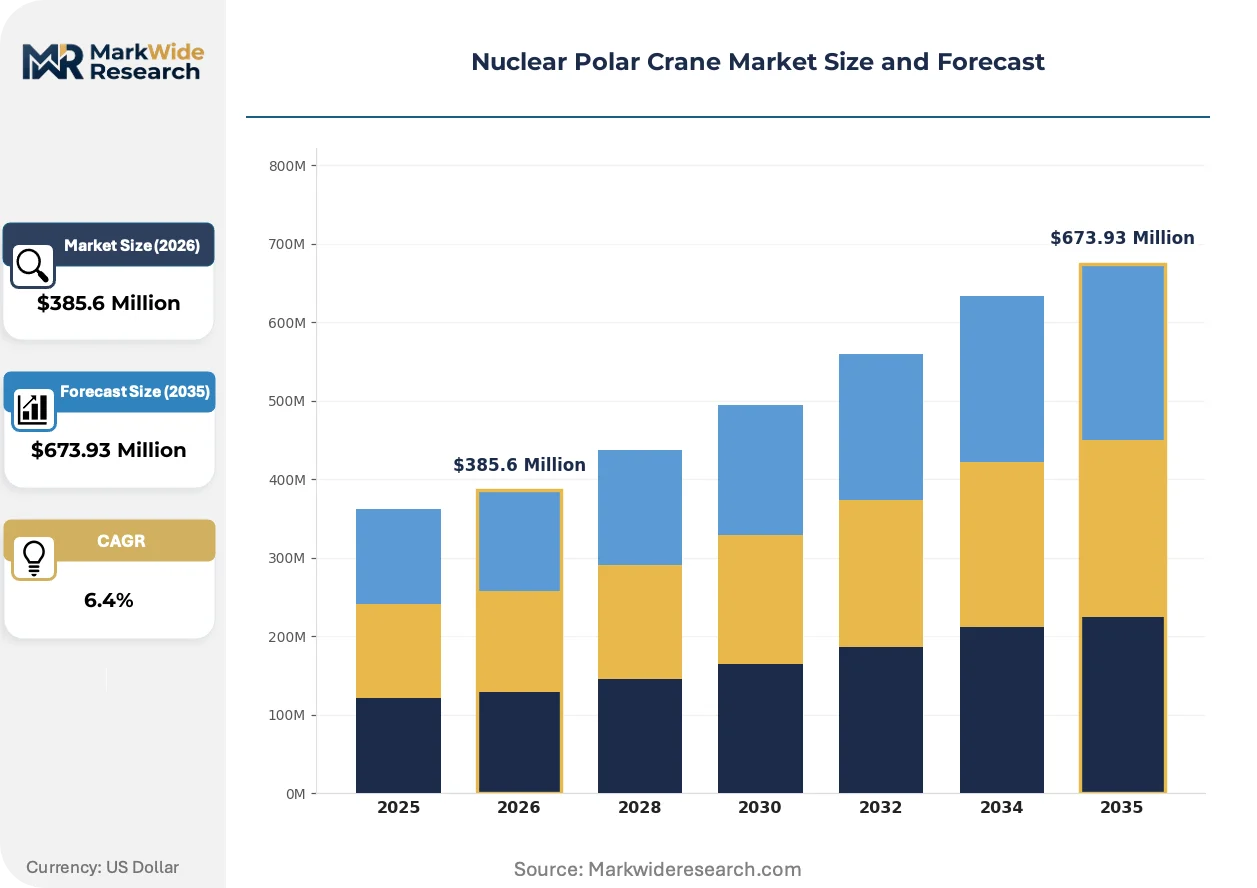
Market Dynamics
Reactor fleet aging across China, France, and the United States is forcing accelerated replacement cycles for containment-integrated lifting systems, with seismic requalification mandates under ASME NOG-1 and RCC-M codes driving procurement urgency.
Growth Catalysts
- ASME NOG-1 seismic requalification:US utilities face mandatory crane upgrades to meet post-Fukushima containment standards, triggering replacement demand at aging PWR and BWR sites.
- Fuel handling automation:Robotic cask positioning systems reduce outage duration and radiation exposure, incentivizing polar crane modernization at refueling-intensive facilities.
- China's HAF 604 certification pathway:Domestic supplier qualification requirements channel procurement toward locally certified manufacturers, expanding installed base across CNNC and CGN reactor fleets.
Market Restraints
- Specialized steel forging concentration:Reactor-grade structural steel for polar crane bridges concentrates among a limited supplier base in heavy-industry regions, creating input bottlenecks.
- Containment integration rigidity:Fixed crane installations require building-specific engineering, preventing modular standardization and inflating project-specific design costs.
- Decommissioning liability uncertainty:Ambiguous crane asset transfer protocols under national nuclear waste frameworks deter long-term maintenance investment at end-of-life plants.
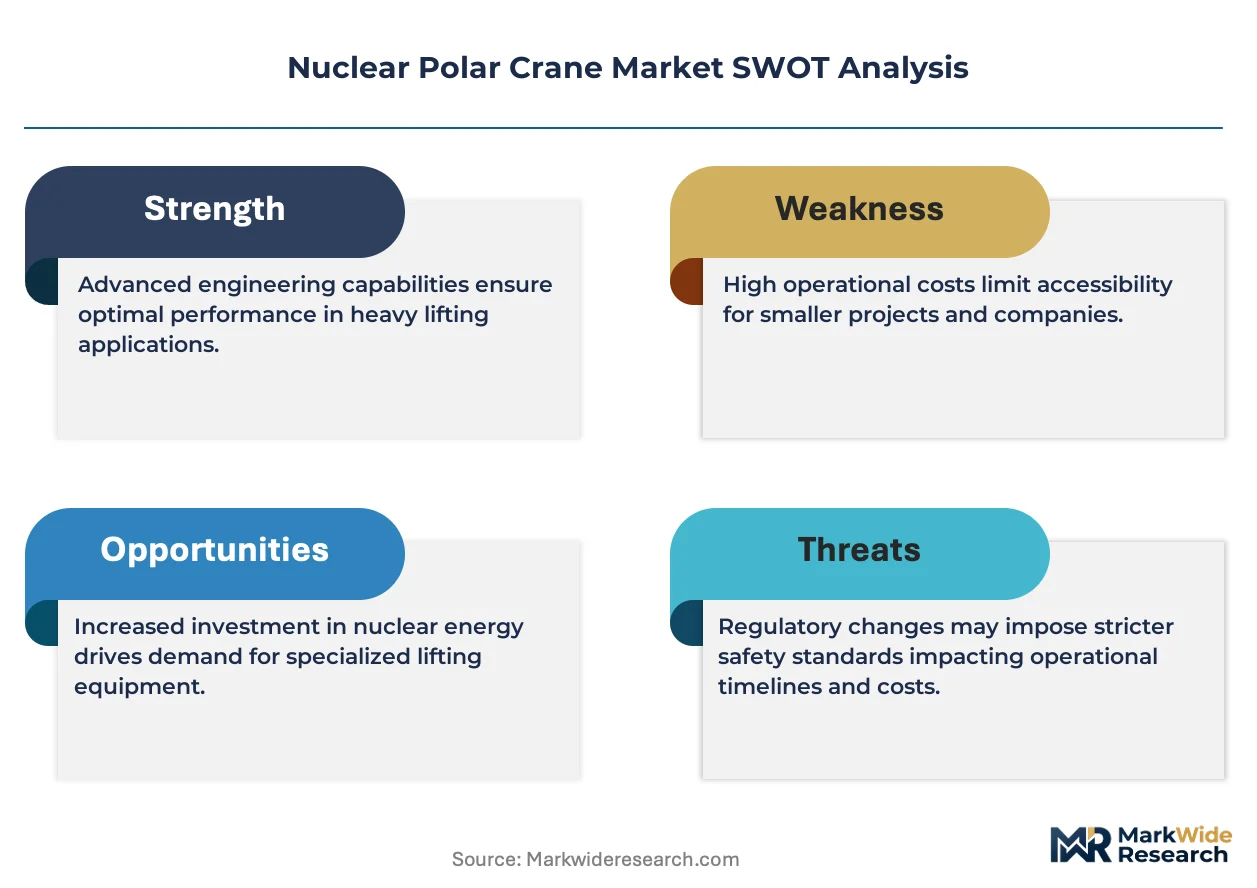
Strategic Opportunities
- Small modular reactor crane standardization:SMR containment designs offer pathways for pre-qualified polar crane platforms, reducing site-specific engineering overhead.
- Spent fuel dry cask handling expansion:Independent spent fuel storage installations create demand for secondary containment lifting systems outside reactor buildings.
- Digital twin integration:Physics-based crane simulation models enable predictive maintenance contracts, shifting revenue toward recurring service streams.
Industry Challenges
- Welding inspector certification scarcity:ASME Section III-qualified welders for nuclear crane fabrication face demographic retirement waves, constraining production capacity.
- Legacy analog control migration:Digital retrofitting of 1970s-era polar cranes requires simultaneous hardware replacement and software validation, extending outage windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Polar Crane Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Cranes, Fixed Cranes, Gantry Cranes, Overhead Cranes Technology: Electric, Hydraulic, Pneumatic, Hybrid End User: Nuclear Power Plants, Research Facilities, Decommissioning Services, Waste Management Companies Installation: On-Site, Off-Site, Temporary, Permanent |
| Companies Covered | PAR Systems, Dalian Huarui Heavy Industry, Konecranes, Whiting Corporation, Taiyuan Heavy Machinery, Liebherr, Westinghouse Electric, APCO Technologies, NKM Noell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Polar Crane Market Trends and Innovations
Electrification and digitalization are converging to reshape polar crane architecture, with hybrid drive systems and remote monitoring capabilities displacing conventional mechanical designs across outage-critical applications.
Hybrid electric-hydraulic drive technology is hybridizing polar crane propulsion architectures, combining high-torque hydraulic lifting with precision electric traverse control. European utilities with extended refueling schedules adopt these configurations to cut standby power draw during month-long outages. The technology is hybridizing vendor business models, compressing pure-equipment margins while expanding energy-efficiency service contracts.
France's RCC-M code revisions now mandate real-time load monitoring and automated emergency braking for all new containment crane installations. The regulation forces integration of sensor networks and edge computing into previously mechanical systems. French-designed EPR export projects in Finland and the United Kingdom must incorporate these specifications, elevating certification costs for non-European suppliers.
Utility procurement departments now unbundle crane supply from installation and long-term maintenance, creating discrete contract lots that specialized nuclear service integrators capture. Engineering-procurement-construction contractors fragment what were once direct manufacturer-utility relationships. This pattern concentrates in the United States, where outage management specialists like Westinghouse and Framatome extend service portfolios into crane logistics coordination.
Nuclear Polar Crane Market Segmentation
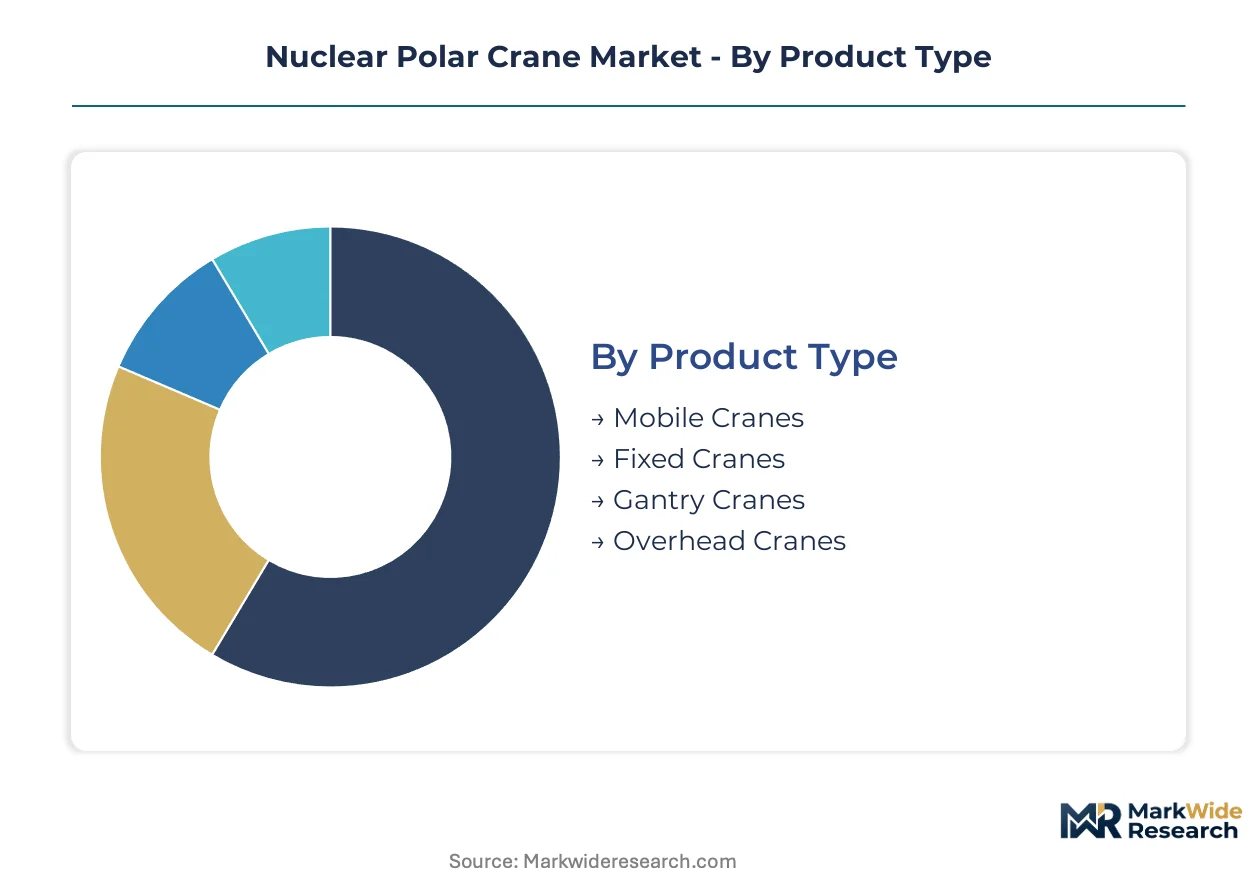
Segmentation in the nuclear polar crane market determines procurement pathways, certification requirements, and long-term service revenue streams. Crane architecture varies sharply across reactor containment designs, decommissioning stages, and national regulatory frameworks. Understanding these divisions clarifies where equipment margins concentrate versus where aftermarket contracts dominate lifetime value.
Product Type:
After-sales-service intensity diverges dramatically across product architectures, with fixed installations demanding decades of specialized maintenance while mobile units rotate through shorter replacement cycles.
- Fixed Cranes:Permanent containment-integrated systems rated for 300+ ton loads with seismic qualification under ASME NOG-1 or RCC-M codes. Demand clusters at aging PWR sites in France and the United States where reactor pressure vessel head replacement mandates structural permanence. These installations generate 20-30 year maintenance contracts that anchor manufacturer profitability.
- Mobile Cranes:Rail-mounted units with modular foundations enabling relocation between reactor buildings. Chinese utilities deploy these across CNNC and CGN fleets to maximize equipment utilization during staggered refueling outages. Flexibility reduces capital intensity per reactor but increases inspection frequency.
- Gantry Cranes:Linear rail systems spanning fuel handling buildings rather than circular containment domes. Spent fuel cask operations at independent storage installations in the United States drive procurement.
- Overhead Cranes:Standard bridge configurations for auxiliary buildings and turbine halls. Lower radiation tolerance limits deployment outside primary containment.
Fixed cranes hold the largest share; momentum sits with mobile configurations as fleet operators prioritize capital efficiency.
Technology:
Technology selection tracks containment radiation levels, outage duration patterns, and national grid stability priorities across operating utilities.
- Electric:AC motor drive systems with variable frequency control dominating operational deployments. Precision positioning for fuel assembly handling meets RCC-M automation mandates in French-designed reactors. Grid-connected baseload plants in China favor electric reliability.
- Hybrid:Combined electric traverse with hydraulic lifting modules reducing standby power draw during month-long outages. European utilities with extended refueling schedules adopt these for energy cost containment. The configuration is gaining share fastest among EPR export projects.
- Hydraulic:High-torque fluid power systems for heavy steam generator replacement loads. Legacy BWR sites in the United States retain hydraulic architectures for compatibility with existing maintenance protocols.
- Pneumatic:Compressed air drive for low-capacity auxiliary lifting in non-containment zones. Limited to turbine maintenance applications with minimal radiation exposure.
Electric systems dominate installed base; hybrid architectures represent the steepest expansion trajectory as outage efficiency gains priority.
End User:
End-user category determines regulatory scrutiny depth, procurement approval chains, and asset lifecycle planning horizons.
- Nuclear Power Plants:Operating reactor fleets requiring containment-integrated cranes for scheduled refueling and unplanned maintenance. Procurement flows through state-owned utilities in China and investor-owned operators in the United States with diverging contract structures.
- Decommissioning Services:Specialized contractors managing reactor dismantlement and component segmentation. Demand is accelerating in France and the United States where first-generation PWR retirements create specialized lifting requirements for activated vessel internals.
- Research Facilities:National laboratories and university reactors with smaller-scale containment designs. Lower tonnage ratings and experimental fuel handling protocols differentiate procurement specifications.
- Waste Management Companies:Independent spent fuel storage operators requiring secondary containment cranes for dry cask transfer. United States utilities facing pool capacity constraints drive segment expansion.
Power plant operators command the largest share; decommissioning services are climbing fastest as reactor fleet aging accelerates asset transitions.
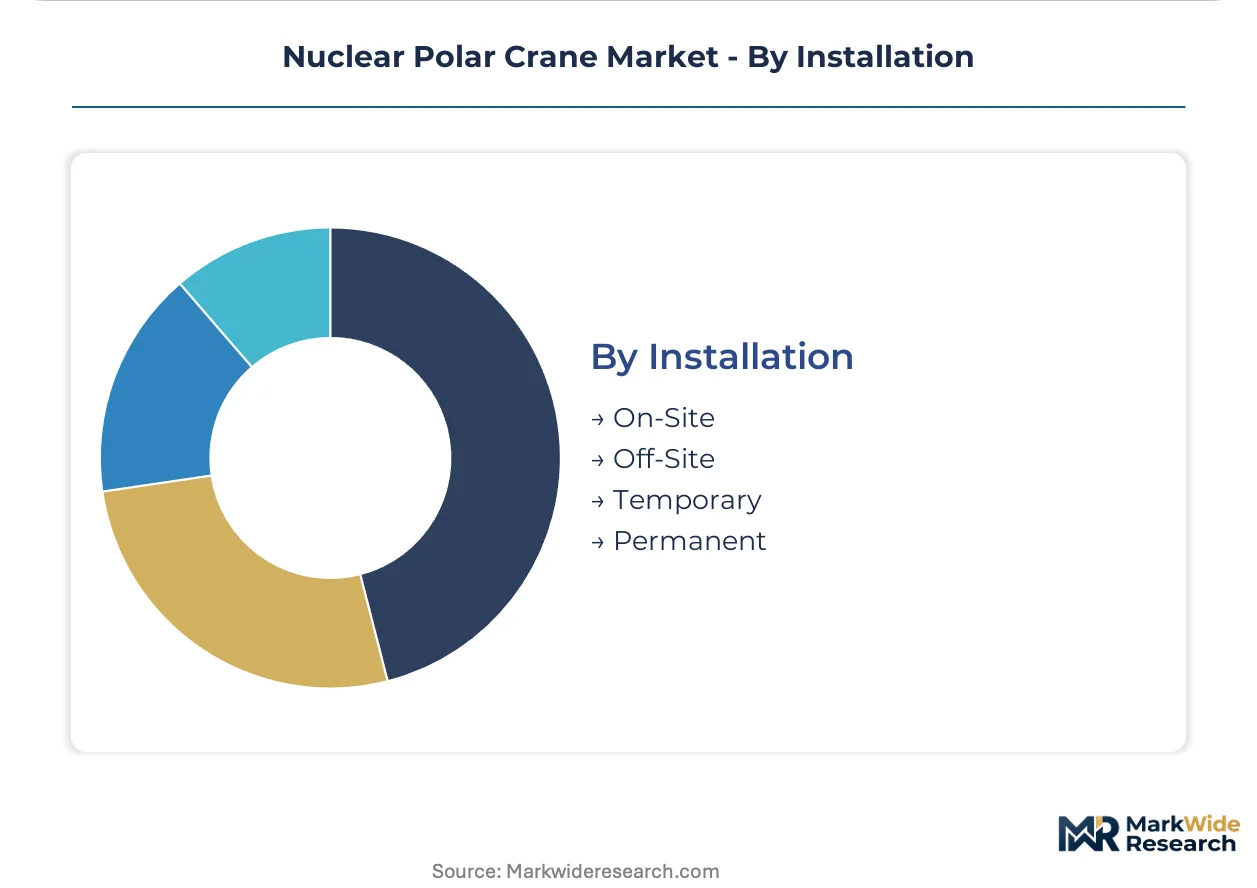
Installation:
Installation modality reflects project delivery structure, regulatory jurisdiction boundaries, and outage window constraints.
- Permanent:Containment-integrated foundations with reactor building structural co-design. Seismic qualification and radiation shielding integration dominate engineering costs. French EPR projects mandate this approach.
- On-Site:Assembly within containment boundaries during construction or major refurbishment. Chinese domestic reactor builds favor on-site integration to align with HAF 604 certification pathways.
- Temporary:Rental or lease configurations for decommissioning campaigns or emergency replacement. United States outage management specialists deploy these to avoid capital commitment for end-of-life plants.
- Off-Site:Modular fabrication with transport to final location. Limited application due to dimensional constraints of containment dome rail integration.
Permanent installations retain the largest share; temporary configurations are expanding most quickly as decommissioning uncertainty deters long-term capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in French and Chinese procurement channels where domestic certification requirements create supplier scarcity, while US utilities face cost premiums from seismic requalification mandates and limited qualified fabricator pools.
United States
Aging PWR and BWR fleets drive containment crane replacement cycles at over 90 operating reactor sites. ASME NOG-1 post-Fukushima amendments mandate seismic requalification for all polar crane installations. Fabrication clusters concentrate in Pennsylvania and Ohio where heavy-industry infrastructure supports reactor-grade steel forging.
China
CNNC and CGN reactor expansion programs sustain procurement volumes across 55+ operational and planned units. HAF 604 certification requirements channel orders toward domestically qualified suppliers, excluding most foreign vendors. Manufacturing gravity centers on Dalian and Shanghai port cities with heavy machinery specialization.
France
EDF's 56-reactor fleet generates sustained maintenance demand alongside Flamanville EPR completion. RCC-M code revisions mandate real-time load monitoring systems for all new installations. Engineering competence clusters in Grenoble and Lyon regions where nuclear supply chains have concentrated for decades.
Finland
Olkiluoto EPR commissioning and planned Loviisa replacements create demand for RCC-M qualified polar crane systems. Finnish nuclear regulator STUK enforces containment equipment standards aligned with French export specifications. Procurement flows through Helsinki-based engineering contractors coordinating European supply chains.
United Kingdom
Hinkley Point C EPR construction and Sizewell C development sustain long-term crane procurement pipelines. Office for Nuclear Regulation adoption of RCC-M derived standards elevates certification complexity for non-European suppliers. Fabrication activity concentrates in Cumbria and Somerset near reactor construction sites.
Nuclear Polar Crane Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying forged steel structures and drive mechanisms. The vendor landscape stratifies between full-scope containment crane providers and regional fabricators serving specific certification jurisdictions. Two archetypes dominate: vertically integrated heavy-industry conglomerates with captive forging capacity, and specialized nuclear service integrators bundling crane logistics with outage management. Competitive moves center on certification pathway capture in China and aftermarket service contract consolidation in Europe.
Among European platform integrators, Konecranes anchors the aftermarket service tier through long-term maintenance contracts, while NKM Noell occupies a position within French-qualified system integration. Dalian Huarui Heavy Industry exemplifies the China-centric archetype leveraging HAF 604 certification and domestic state-utility relationships. These three represent distinct competitive vectors: European service bundling, French regulatory alignment, and Chinese procurement channel capture.
| Leading Market Players |
|---|
| PAR Systems |
| Dalian Huarui Heavy Industry |
| Konecranes |
| Whiting Corporation |
| Taiyuan Heavy Machinery |
| Liebherr |
| Westinghouse Electric |
| APCO Technologies |
| NKM Noell |
| Others |
Pricing and Supply Chain Analysis
Dalian's heavy machinery cluster commands pricing leverage through captive forging capacity for reactor-grade structural steel, translating localized input control into premium capture on ASME NOG-1 and RCC-M certified systems. Chinese state-owned utilities absorb cost premiums through bundled procurement, while European and American operators face sharper price escalation from qualified fabricator scarcity.
Pricing Analysis
The customization-premium spread separates configured-to-order polar crane systems from standardized auxiliary building units. Project-based pricing dominates fixed containment installations, with price differentiation driven by seismic certification tier and after-sales service bundling. Cost compression in mobile crane configurations is intensifying as Chinese manufacturers expand HAF 604-qualified production capacity. Decommissioning services exhibit highest price sensitivity due to temporary deployment horizons, while EPR new-build projects show lowest sensitivity given regulatory-mandated specification rigidity.
Supply Chain Analysis
Reactor-grade structural steel feedstock concentrates in China, France, and the United States, with specialized forging capacity tethered to heavy-industry regions in each jurisdiction. Critical inputs include forged bridge girders, radiation-hardened drive mechanisms, and seismic isolation bearings. Single-source vulnerability pervades ASME Section III-qualified welding inspector pools facing demographic retirement. Distribution runs through engineering-procurement-construction contractors who fragment direct manufacturer-utility relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where digital twin integration threatens to displace pure-equipment vendors with predictive maintenance ecosystems. Interoperability between crane sensor networks and utility outage management systems is redefining competitive moats.
For Market Incumbents: Entrench certification pathway control by deepening backward integration into reactor-grade steel forging and expanding HAF 604 qualification coverage for Chinese market access. Defend against emerging nuclear service integrators by anchoring long-term maintenance contracts with digital twin-enabled predictive service offerings. Prioritize welding inspector apprenticeship pipelines to offset demographic capacity constraints.
For New Entrants and Emerging Players: United States decommissioning services present the most penetrable white-space target, where temporary crane deployment models circumvent capital barriers deterring established players. Secondary spent fuel storage installations offer modular gantry crane entry points outside containment-qualification complexity. Pursue partnership positioning with outage management specialists like Westinghouse and Framatome to bypass fragmented EPC contractor channels.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated heavy-industry conglomerates with captive forging capacity and established certification portfolios across multiple regulatory jurisdictions. Long-term viability hinges on crane fleet planning alignment with reactor lifecycle transitions spanning construction through decommissioning. Monitor SMR containment standardization progress as the critical inflection signal for pre-qualified platform scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Physics-based simulation models enable predictive maintenance contracts shifting revenue toward recurring service streams at EDF and CNNC sites. |
| SMR Platform Standardization | Pre-qualified polar crane designs for small modular reactor containment reduce site-specific engineering overhead at NuScale and Rolls-Royce projects. |
| HAF 604 Certification Investment | Domestic supplier qualification pathways unlock procurement access across CNNC and CGN reactor fleet expansion programs. |
| Spent Fuel Cask Handling Expansion | Independent storage installations in the United States create demand for secondary containment gantry systems outside reactor buildings. |
| Welding Inspector Pipeline Development | ASME Section III-qualified fabricator apprenticeships address demographic retirement waves constraining production capacity. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with nuclear utility procurement officers, EPC contractor project managers, crane manufacturer sales directors, and aftermarket service heads; and secondary validation through NRC regulatory filings, IAEA reactor databases, ASME certification records, and national nuclear safety administration disclosures. Bottom-up equipment shipment tracking and top-down reactor fleet analysis were triangulated against containment crane replacement cycle modeling.
Forecast inputs span product type segmentation across fixed, mobile, gantry, and overhead configurations; technology segmentation across electric, hybrid, hydraulic, and pneumatic drive systems; and end-user segmentation across power plant operators, decommissioning services, research facilities, and waste management companies. CAGRs were derived from reactor fleet aging curves, regulatory amendment timelines, and national nuclear expansion program announcements across the projection horizon. SMR deployment schedules and spent fuel storage expansion timelines served as scenario-weighting inputs.
Practitioners should monitor seismic code amendment trajectories, SMR standardization progress, and decommissioning liability framework clarifications for early signals of forecast revision. Cross-checking against IAEA reactor construction and retirement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Europe Hazardous Location Motors Market
Industrial Motors
Food Grade Hydraulic Oil Market
Industrial Motors
Japan AC Motor Market
Industrial Motors
Synchronous Electric Motor Market
Industrial Motors
Asia Pacific Safety Drives and Motors Market
Industrial Motors
US Electric Motor Market
Industrial Motors
AC Servo Motors and Drives Market
Industrial Motors
North America Refrigeration Oil Market
Industrial Motors
AC Motor Market
Industrial Motors
High Voltage Motor Sleeve Bearing Market
Industrial Motors
North America Induction Motor Market
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
Global Parallel Shaft Geared Motors Market
Industrial Motors
Smart Motors Market
Industrial Motors
Global Sliding Vane Air Motor Market