
 Industrial Hydraulic Filters Market | 2026-2036
Industrial Hydraulic Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Hydraulic Filters Market Analytics
ISO 4406 cleanliness codes are reorganizing supplier qualification across the Industrial Hydraulic Filters landscape. Parker Hannifin leverages its captive distribution network to dominate aftermarket service contracts. Hydac International anchors European demand through localized filter testing laboratories. Donaldson Company competes on pleated media R&D intensity for high-pressure mining applications.
Industrial hydraulic filters remove particulate contaminants from hydraulic fluid circuits through mechanical sieving, adsorption, or magnetic separation, typically rated at Beta ratios exceeding 200 for critical servovalve protection. Their primary purpose is extending component life in closed-loop fluid power systems operating at pressures from 3,000 to 6,000 PSI. Return line filters capture the largest volume share due to lower operating stress and standardized housing dimensions across OEM platforms. Synthetic fiber media represents the fastest-growing filtration category as thermal stability requirements exceed the limits of traditional cellulose paper. Pressure filters command premium positioning where servo-proportional valve tolerances demand sustained Beta efficiency above 1,000.
EPA emissions regulations for off-road diesel equipment indirectly tighten hydraulic system maintenance intervals, expanding filter replacement demand in construction and mining fleets. ISO 4406 and NFPA cleanliness standards create compliance thresholds that disqualify uncertified suppliers from OEM specification lists. NHTSA safety mandates for braking and steering hydraulics in commercial vehicles add secondary certification layers for filter integrity under dynamic load. Stakeholders must monitor how electrification of hydraulic actuators alters fluid cleanliness profiles and whether filter architectures designed for conventional systems translate to electro-hydraulic hybrid platforms.
Market Dynamics
ISO 4406 cleanliness code revisions are compressing supplier qualification timelines while electrification of hydraulic actuators forces filter architectures to adapt to electro-hydraulic hybrid fluid profiles. Construction equipment fleets in Germany's industrial corridor are accelerating replacement schedules under tighter particle count thresholds.
Growth Catalysts
- EPA Tier 4 Final emissions:Off-road diesel equipment maintenance intervals tighten, expanding filter replacement frequency in mining and construction fleets.
- Synthetic fiber media:Thermal stability requirements above 120°C exceed cellulose paper limits, driving material substitution in high-pressure circuits.
- Germany's manufacturing corridor:Localized filter testing laboratories anchor European demand concentration for certified hydraulic components.
Market Restraints
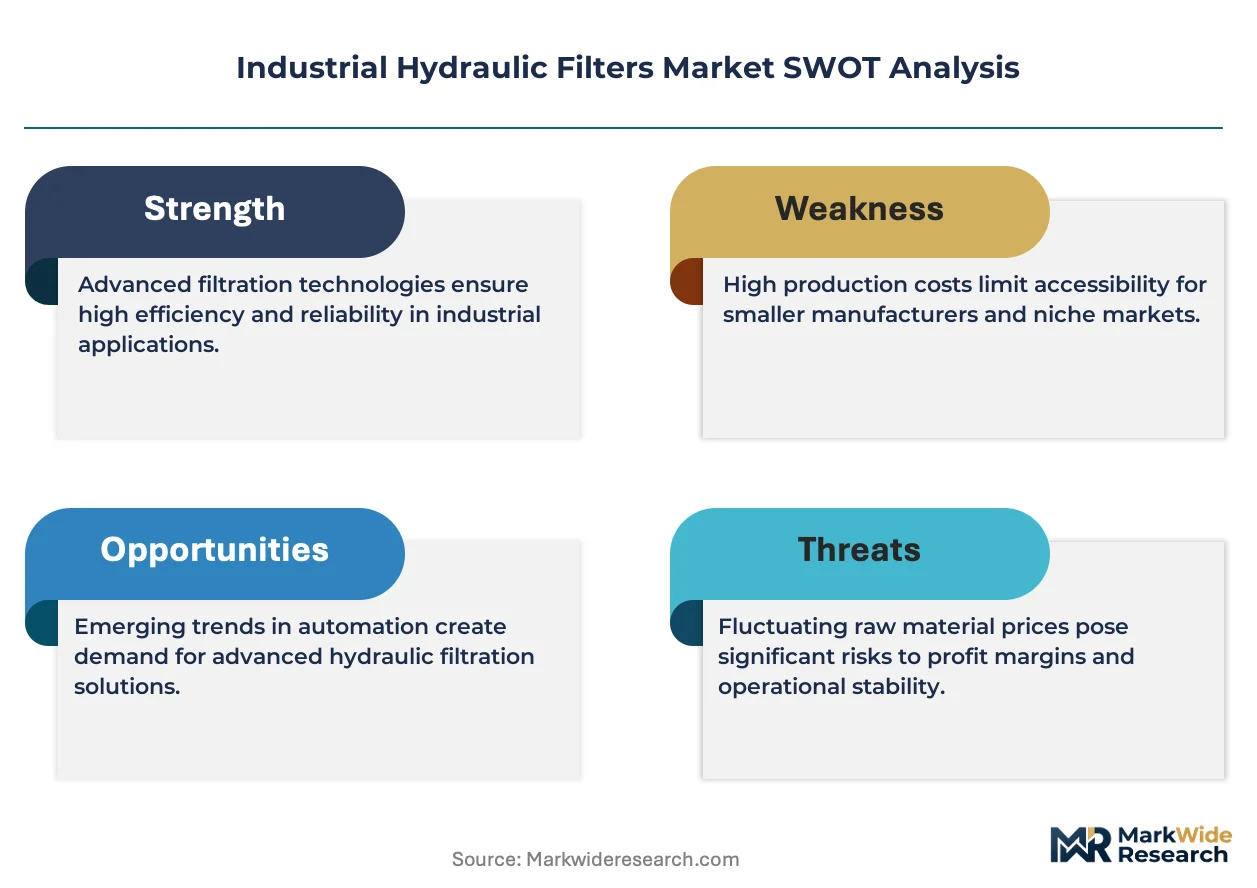
- Steel and specialty polymer input costs:Filter housing and media raw material volatility compresses margin buffers for non-integrated manufacturers.
- Return line filter standardization:OEM platform consolidation limits differentiation opportunities in the highest-volume product category.
- Electro-hydraulic actuator substitution:Full electrification of motion control eliminates hydraulic circuits entirely in select material handling applications.
Strategic Opportunities
- India's PLI scheme for construction equipment:Domestic manufacturing incentives create localized supply chain entry points for filter assemblers.
- Pressure filter premium tier:Servo-proportional valve tolerances above Beta 1,000 efficiency open high-margin specification tiers.
- IoT-enabled condition monitoring:Predictive contamination sensing converges with filter hardware to enable usage-based replacement models.
Industry Challenges
- ISO 4406 certification timelines:Multi-stage laboratory testing protocols extend supplier qualification cycles beyond 18 months for OEM approval.
- Legacy system integration:Electro-hydraulic hybrid platforms require filter architectures compatible with both conventional and electrified fluid power circuits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Hydraulic Filters Market |
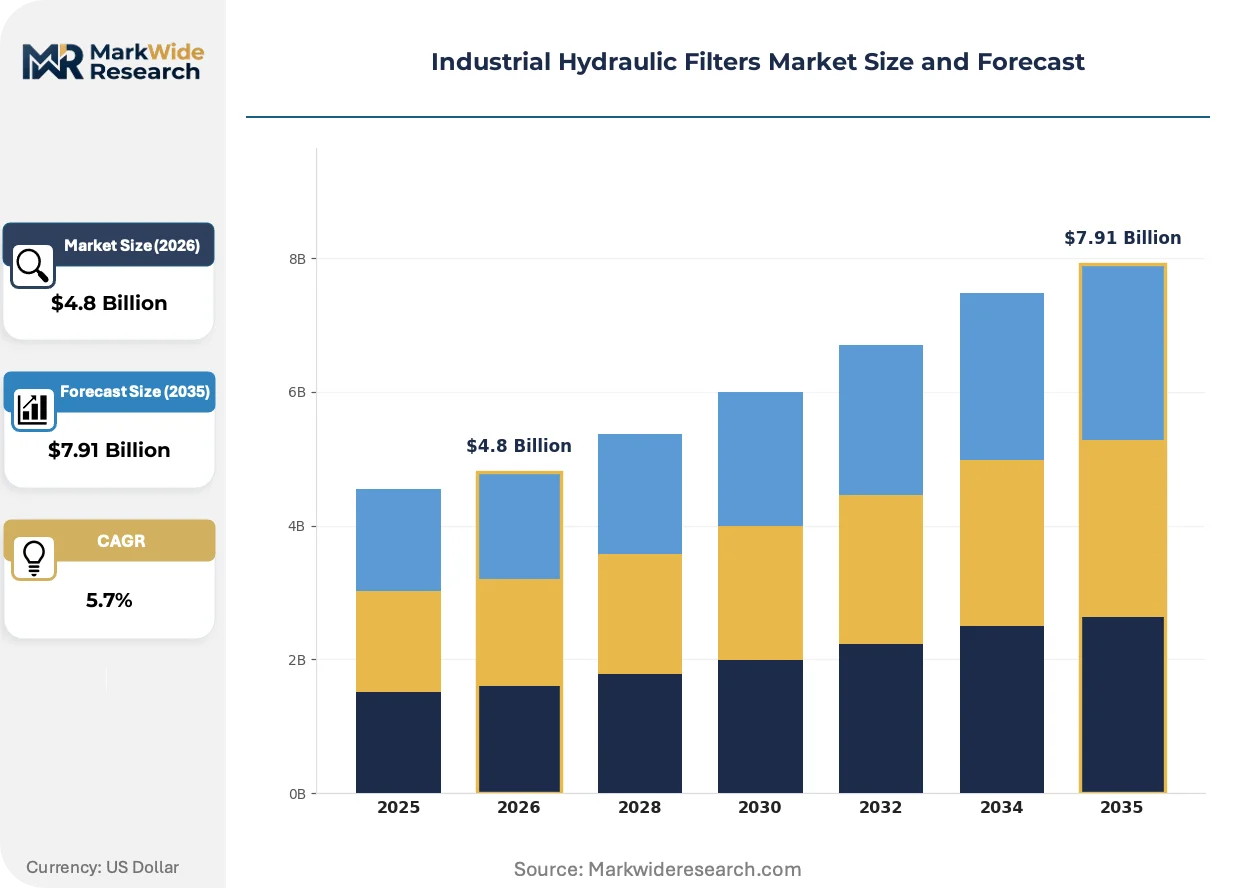
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Filters, Return Line Filters, Suction Filters, Pressure Filters Filtration Media: Pleated Paper, Stainless Steel, Synthetic Fiber, Wire Mesh End User: Manufacturing, Construction, Mining, Agriculture Installation Type: Permanent, Portable, Compact, Custom |
| Companies Covered | Parker Hannifin, Hydac International, Donaldson Company, Eaton Corporation, Mann+Hummel, Pall, Filtration Group, Schaeffler, Baldwin Filters, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Hydraulic Filters Market Evolving Landscape
Filtration media chemistry and real-time contamination sensing are restructuring how hydraulic systems manage fluid cleanliness. These shifts compress replacement cycles while enabling predictive maintenance architectures.
Multi-layer synthetic fiber media is fragmenting the traditional cellulose-dominated supply base. Mining operators in Western Australia adopt glass-synthetic blends for high-temperature underground applications. The technology is fragmenting incumbent media suppliers into specialty-grade and commodity-grade tiers.
REACH Annex XVII restrictions on perfluorinated compounds force reformulation of hydrophobic filter coatings used in mobile hydraulic equipment. European OEMs accelerate qualification of fluorine-free alternatives ahead of 2025 enforcement deadlines. Pressure filter manufacturers serving German construction equipment makers face the steepest reformulation timelines.
Condition-based filter replacement is displacing fixed-interval maintenance in fleet-managed construction equipment. Telematics-integrated particle counters enable usage-triggered service scheduling. This pattern is most visible in North American rental equipment fleets where uptime guarantees dominate contract terms.
Industrial Hydraulic Filters Market Segmentation
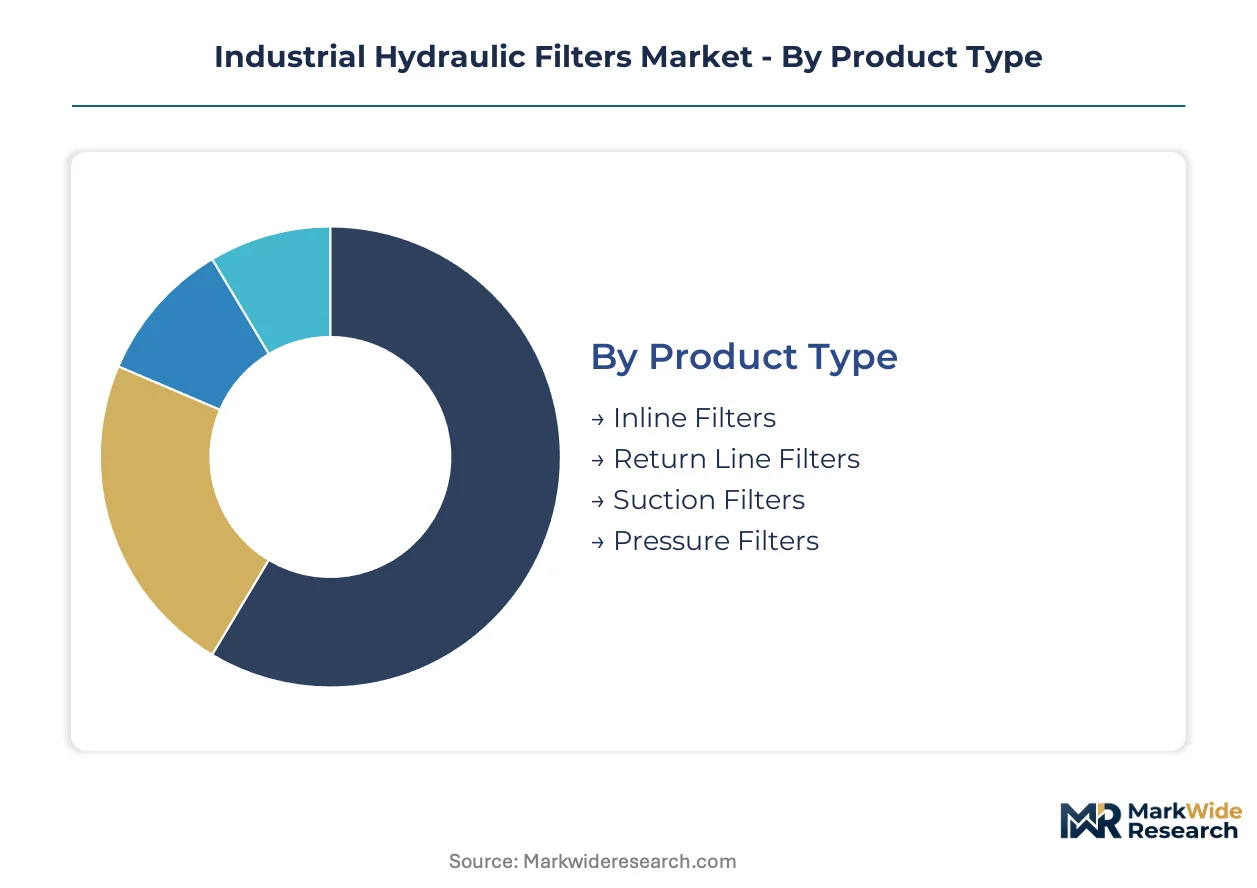
Industrial hydraulic filter segmentation reveals distinct procurement patterns across equipment types and operating environments. Product architecture, media chemistry, and installation constraints each create separate specification tiers that suppliers must navigate simultaneously.
Product Type:
Return line filters dominate domestic OEM supply chains in Germany's manufacturing corridor, while pressure filters anchor export specifications for mining equipment.
- Inline Filters:Positioned mid-circuit between pump and valve manifolds, these units handle continuous flow at moderate pressure differentials. German construction equipment makers specify inline configurations for excavator boom circuits under ISO 4406 compliance mandates.
- Return Line Filters:Capture the highest volume share through standardized housing dimensions across OEM platforms. Demand concentrates in domestic fleet replacement schedules where lower operating stress extends service intervals.
- Suction Filters:Protect pump inlets from coarse contamination in reservoir-fed systems. Agriculture equipment OEMs in India's PLI scheme zones specify suction-stage protection for tractor hydraulic circuits.
- Pressure Filters:Command premium positioning where servo-proportional valve tolerances demand sustained Beta efficiency above 1,000. Mining applications in Western Australia drive export demand for high-pressure specifications.
Return line filters hold the largest share; momentum sits with pressure filters.
Filtration Media:
Material selection tracks thermal stress gradients, with synthetic fiber commanding high-temperature applications and pleated paper retaining cost-sensitive volume.
- Pleated Paper:Cellulose-based media retains economy positioning in ambient-temperature construction fleets. German rental equipment operators specify pleated paper for scheduled replacement programs under fixed-interval maintenance contracts.
- Stainless Steel:Wire-sintered structures withstand cyclic pressure pulses in steel mill hydraulic systems. Demand clusters in Ruhr Valley manufacturing corridors where washdown compatibility matters.
- Synthetic Fiber:Glass-polymer blends exceed 120°C thermal limits, displacing cellulose in underground mining hydraulics. REACH Annex XVII fluorine restrictions accelerate fluorine-free coating qualifications for mobile equipment.
- Wire Mesh:Reusable metallic screens serve coarse pre-filtration in agriculture reservoir systems. India's domestic equipment assemblers specify wire mesh for suction-stage protection in cost-optimized tractor hydraulics.
Pleated paper retains volume leadership; synthetic fiber is expanding most quickly.
End User:
Construction and mining sectors drive specification intensity, while manufacturing and agriculture split between precision and cost-optimized tiers.
- Manufacturing:Machine tool OEMs specify pressure filters for servovalve protection in metal-cutting hydraulics. German automotive stamping presses demand ISO 4406 code 14/11 cleanliness thresholds.
- Construction:Fleet telematics integration accelerates condition-based replacement in rental equipment. EPA Tier 4 Final maintenance interval tightening expands filter consumption in diesel-hydraulic excavators.
- Mining:Underground operations in Western Australia specify synthetic fiber media for high-temperature continuous duty. Beta 1000+ efficiency requirements dominate procurement specifications.
- Agriculture:Tractor hydraulic systems prioritize suction and return line protection over pressure-stage precision. India's PLI scheme incentivizes domestic filter assembly for farm equipment supply chains.
Construction captures the largest share; mining maintains the steepest expansion trajectory.
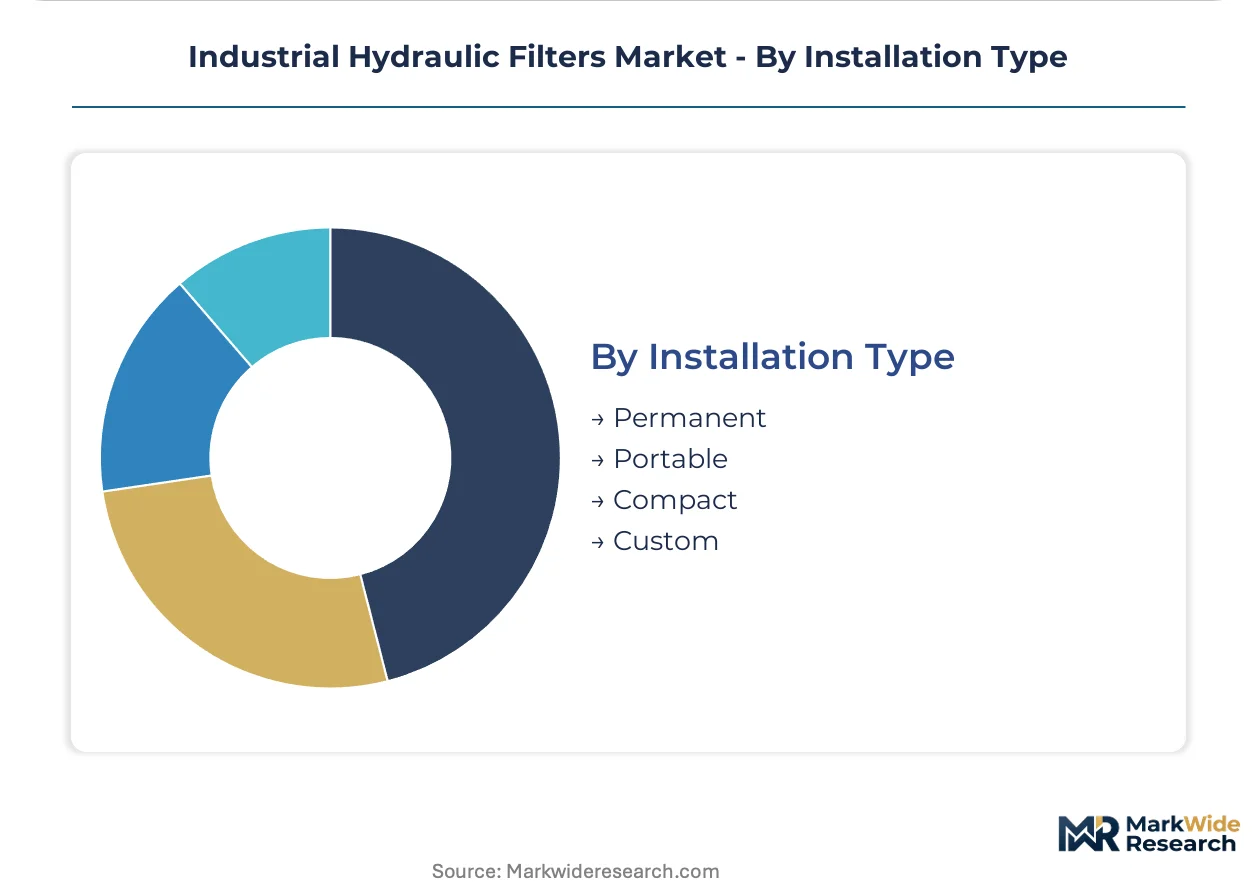
Installation Type:
Permanent mounting dominates OEM platforms, while portable and compact formats serve aftermarket retrofit and mobile equipment constraints.
- Permanent:Fixed manifold integration in machine tool and industrial press applications. German manufacturing corridor OEMs specify permanent housings for 10,000-hour design life.
- Portable:Offline filtration carts serve reservoir conditioning in maintenance depots. Construction fleet operators in North America deploy portable units for fluid reclamation.
- Compact:Space-constrained mobile hydraulics in mini-excavators and skid-steer loaders. Agriculture equipment makers specify compact return line filters for tractor rear hitch circuits.
- Custom:Engineered housings for non-standard port configurations in legacy mining equipment. Australian underground operators commission custom pressure filter manifolds for retrofitted longwall systems.
Permanent installation holds the largest share; compact formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's PLI-equivalent manufacturing incentives and India's Production Linked Incentive scheme for construction equipment are redirecting filter procurement toward domestic assembly hubs. EPA Tier 4 Final regulations in the United States and REACH Annex XVII enforcement in Europe reshape regional compliance requirements. Industrial clusters in Western Australia, the Ruhr Valley, and Maharashtra concentrate specification intensity for high-pressure mining and precision manufacturing applications.
Germany
Machine tool OEMs in Baden-Württemberg specify pressure filters for servovalve protection under ISO 4406 code 14/11 thresholds. KBA and ECHA REACH Annex XVII fluorine restrictions accelerate fluorine-free coating qualifications for mobile equipment. Hydac International anchors demand through localized filter testing laboratories in the Stuttgart industrial corridor.
United States
Construction fleet telematics integration accelerates condition-based replacement in North American rental equipment markets. EPA Tier 4 Final emissions regulations tighten maintenance intervals for off-road diesel-hydraulic excavators. Midwest manufacturing corridors specify return line filters for scheduled replacement programs under fixed-interval contracts.
India
Domestic manufacturing incentives under the PLI scheme for construction equipment create localized supply chain entry points for filter assemblers. BIS certification requirements and CEA industrial safety mandates shape procurement specifications for hydraulic components. Maharashtra and Gujarat industrial zones concentrate tractor hydraulic system demand for suction and return line protection.
Australia
Underground mining operations in Western Australia specify synthetic fiber media for high-temperature continuous duty exceeding 120°C. TGA-equivalent mining safety regulations and state-level occupational health mandates enforce Beta 1000+ efficiency requirements. Perth-based equipment distributors anchor export demand for high-pressure filter specifications.
China
MIIT industrial upgrading programs and GB standards for hydraulic component cleanliness expand domestic filter testing infrastructure. Yangtze River Delta manufacturing clusters concentrate demand for compact return line filters in mini-excavator production. SAMR quality certification requirements compress supplier qualification timelines for OEM specification lists.
Industrial Hydraulic Filters Market Competitive Landscape
Player mix skews toward diversified fluid power conglomerates with captive distribution networks and specialized filtration technology developers with R&D-intensive media portfolios. Market structure concentrates specification influence among vertically integrated manufacturers controlling upstream polymer fiber production and downstream service contracting. Two dominant strategic archetypes emerge: integrated fluid power suppliers leveraging aftermarket service lock-in, and focused filtration specialists competing on pleated media chemistry for extreme-pressure applications. Competitive moves center on M&A for geographic expansion into PLI-incentivized manufacturing zones and technology licensing for electro-hydraulic hybrid filter architectures.
Among diversified industrial conglomerates, Parker Hannifin and Eaton Corporation occupy positions anchoring aftermarket service contract dominance through captive distribution networks. Hydac International exemplifies the European specialist archetype with localized laboratory infrastructure for OEM qualification. Donaldson Company sits within the R&D-intensive tier competing on synthetic media development for mining applications. These three patterns represent the structural fault lines shaping competitive positioning across ISO 4406 certification tiers and electro-hydraulic hybrid platform transitions.
| Leading Market Players |
|---|
| Parker Hannifin |
| Hydac International |
| Donaldson Company |
| Eaton Corporation |
| Mann+Hummel |
| Pall |
| Filtration Group |
| Schaeffler |
| Baldwin Filters |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German synthetic fiber media plants shapes both supply concentration and price floors for pressure filter manufacturers. OEM qualification timelines exceeding eighteen months lock in incumbent positions, while spot-market cellulose paper pricing fluctuates with pulp futures.
Pricing Analysis
Certification level creates the primary spread between premium and commodity tiers. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 4406 code compliance, with Beta 1000+ specifications commanding substantial premiums over return line alternatives. Cost compression in cellulose-based pleated paper is intensifying because construction fleet operators consolidate purchase volumes under national rental chains. Manufacturing segments exhibit the highest price sensitivity due to fixed-interval maintenance contracts, while mining operators prioritize thermal stability over unit cost.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes constrains specialty polymer fiber inbound flows to filter media producers. Supply concentrates in Germany, China, and the United States for precision-wound filter elements, with raw material dependencies centering on glass microfiber, specialty polyamide resins, and cold-rolled steel housings. Single-source vulnerability from REACH Annex XVII fluorine compound restrictions threatens hydrophobic coating supplies. Distribution runs through captive OEM service networks for aftermarket contracts, with independent distributors serving spot replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electro-hydraulic actuator substitution threatens traditional filter architectures, forcing incumbents to defend circuit relevance through hybrid platform compatibility.
For Market Incumbents: Consolidate aftermarket service contracts through telematics-integrated condition monitoring offerings. Acquire synthetic fiber media capabilities to secure thermal stability supply chains against REACH-driven fluorine restrictions. Parker Hannifin's captive distribution model demonstrates how service lock-in defends position against commoditized return line filter competition. For New Entrants and Emerging Players: Differentiate on IoT-enabled predictive maintenance platforms for construction rental fleets. Target India's PLI scheme zones for domestic assembly partnerships with tractor OEMs. White-space exists in compact filter formats for mini-excavator platforms where incumbent tooling investments lag. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors filtration specialists with electro-hydraulic hybrid R&D pipelines over pure-play legacy suppliers. Long-term viability hinges on compatibility with electrified fluid power architectures. Watch for inflection when mining OEMs specify Beta 2000+ efficiency thresholds for autonomous underground equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Fiber Media | Secures thermal stability supply against REACH Annex XVII fluorine restrictions. |
| IoT-Enabled Condition Monitoring Platform | Converges filter hardware with predictive maintenance software for rental fleet contracts. |
| Geographic Expansion into PLI-Incentivized Zones | Establishes domestic assembly presence in India's construction equipment corridor. |
| Technology Licensing for Hybrid Architectures | Transfers filtration expertise to electro-hydraulic actuator manufacturers. |
| Long-Term Supply Agreement with Mining OEMs | Locks in Beta 1000+ specification demand from Western Australian underground operators. |
Research Methodology
The analysis maps return line filters, pressure filters, inline configurations, and suction-stage units, each validated through maintenance directors at construction fleets, OEM procurement teams, aftermarket service heads, and plant engineers at German manufacturing corridors. Primary interview findings triangulate against customs trade data, SEC filings from diversified fluid power conglomerates, ISO certification registries, and ECHA REACH substance restriction databases. Bottom-up equipment fleet sizing reconciles with top-down hydraulic component production estimates.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models product type, filtration media chemistry, end-user industry, and installation format dimensions. CAGRs derive from equipment replacement cycle analysis and cleanliness standard tightening trajectories. Key inputs include EPA Tier 4 Final maintenance interval impacts and synthetic fiber substitution elasticities.
Forecasts assume regulatory continuity in EPA emissions enforcement and ECHA REACH Annex XVII implementation; material policy shifts would require re-modeling. Commodity pulp pricing volatility and electro-hydraulic substitution rates represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Reciprocating Compressor Components Market
Valves
Hydraulic Diaphragm Valve Market
Valves
Flare Stack Monitoring Systems Market
Valves
Lined Valves Market
Valves
Fluid Transfer Solutions Market
Valves
Valve Manifold Box (VMB) Market
Valves
Global Valve Positioners Market
Valves
Electrohydraulic Servo Valves (Ehsvs) Market
Valves
Three Way Ball Valve Market
Valves
Choke and Kill Manifold Market
Valves
Emergency Shutdown Valves Market
Valves
Pipeline Strainers Market
Valves
GCC and MENA Valves Market
Valves
Safety Valve Market
Valves
Pigging Valves Market
Valves
Mobile Hydraulic Valves Market