
 Global Direct Current (DC) Motor Market | 2026-2036
Global Direct Current (DC) Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Direct Current (DC) Motor Market Foresight
Multi-source procurement for rare-earth magnet supply is shifting toward captive sourcing arrangements among tier-one motor producers. Nidec Corporation anchors permanent magnet motor production through integrated magnet processing capabilities in Japan and Vietnam. Johnson Electric Holdings Limited leverages its Dongguan manufacturing footprint to compete on cost in automotive actuator segments. Siemens AG dominates industrial servo applications through its SINAMICS drive-motor pairing architecture.
A direct current motor converts electrical energy into mechanical rotation through commutated electromagnetic interaction between stator windings and a rotor assembly, with brushless variants achieving efficiencies exceeding ninety percent through electronic commutation replacing mechanical brush-gear contact. Brushless DC motors lead volume growth as electric vehicle traction applications displace brushed designs in power ratings above two kilowatts. Coreless DC motors occupy premium margin pools in medical robotics and optical instrumentation where minimal rotor inertia enables sub-millisecond positioning response.
The US Department of Energy enforces minimum efficiency standards under NEMA MG-1 specifications, compelling industrial end users to replace legacy brushed motors with premium-efficiency brushless alternatives. China's MIIT implements GB 18613 efficiency tiers that phase out IE2-equivalent motors from manufacturing plant installations. REACH restrictions on neodymium supply chain traceability reshape European procurement patterns through ECHA compliance documentation requirements. Stakeholders must monitor rare-earth price volatility and regional content thresholds as these factors determine competitive positioning in electrified transportation and precision automation markets.
Market Dynamics
Brushless DC motor architectures are compressing replacement cycles across industrial automation and electric vehicle drivetrains as efficiency mandates harden and rare-earth supply chains consolidate around captive magnet processing.
Growth Catalysts
- China's GB 18613 efficiency tiers:MIIT-mandated IE3 minimums for industrial motors are forcing manufacturing plants to retire legacy brushed units ahead of depreciation schedules.
- Electric vehicle traction demand:Automakers specify brushless designs above two kilowatts to meet thermal management and regenerative braking integration requirements.
- Germany's precision automation cluster:Stuttgart and Munich industrial corridors concentrate servo motor procurement for robotics and CNC systems.
Market Restraints
- Neodymium price volatility:Permanent magnet cost exposure constrains margin stability for motor producers without backward integration into rare-earth processing.
- REACH traceability documentation:ECHA compliance requirements for magnet supply chains create procurement friction and extend vendor qualification timelines.
- Brushed motor residual inventory:IE2-equivalent stockpiles in developing manufacturing bases delay premium product penetration.
Strategic Opportunities
- Medical robotics miniaturization:Coreless DC motor demand for sub-millimeter positioning in surgical instruments and optical systems commands premium pricing.
- India's PLI scheme for advanced cell chemistry:Battery manufacturing scale-up creates adjacent demand for precision motor actuators in electrode winding and assembly.
- Digital twin integration:Siemens SINAMICS and competing drive-motor pairing architectures enable predictive maintenance service contracts.
Industry Challenges
- Power electronics integration:Combining motor and inverter design expertise strains engineering organizations historically segmented by mechanical and electrical disciplines.
- ISO 9001 and IATF 16949 certification timelines:Automotive qualification protocols extend eighteen to twenty-four months for new motor platform approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Direct Current (DC) Motor Market |
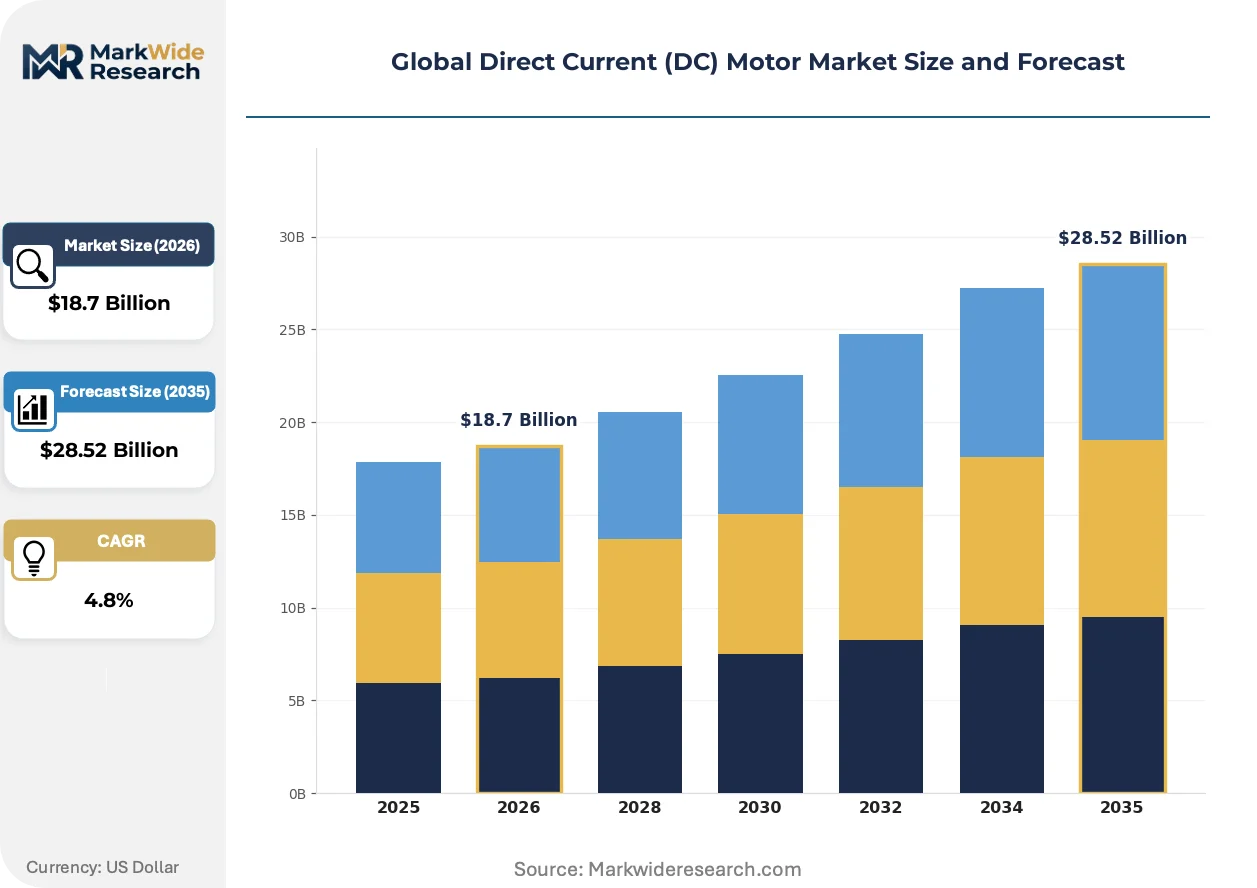
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushed DC Motor, Brushless DC Motor, Coreless DC Motor, Servo Motor Technology: Iron Core, Coreless, Slotless, Sensorless Application: Power Tools, HVAC Systems, Robotics, Consumer Electronics, Electric Vehicles End User: Manufacturing Plants, Research Institutions, Transportation Equipment Makers, Home Appliance Producers |
| Companies Covered | Johnson Electric Holdings Limited, Allied Motion Inc., Nidec Corporation, Oriental Motor, Maxon Motor, ABB, AMETEK Inc., Harmonic Drive LLC, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Direct Current (DC) Motor Market Shifts & Advancements
Electronic commutation is displacing mechanical brush-gear architectures across power classes, while software-defined motor control and integrated thermal management reshape product architectures.
Silicon carbide (SiC) power modules are automating inverter-motor integration by enabling higher switching frequencies and reduced thermal losses. Automotive tier-one suppliers specify SiC-based drivetrains for 800-volt architectures. This convergence is automating the obsolescence of discrete motor-inverter procurement models.
REACH restrictions on neodymium supply chain traceability are restructuring European procurement documentation requirements. Motor producers must now submit ECHA-compliant material passports for permanent magnet content. German and French industrial buyers are consolidating supplier lists to vendors with verified upstream magnet sourcing.
After-sales service unbundling is fragmenting traditional OEM maintenance contracts. Industrial end-users in Japan and South Korea now procure motors and predictive analytics separately, favoring third-party condition monitoring platforms over bundled service agreements. This disaggregation pressures integrated manufacturers to modularize software and hardware pricing.
Global Direct Current (DC) Motor Market Segmentation
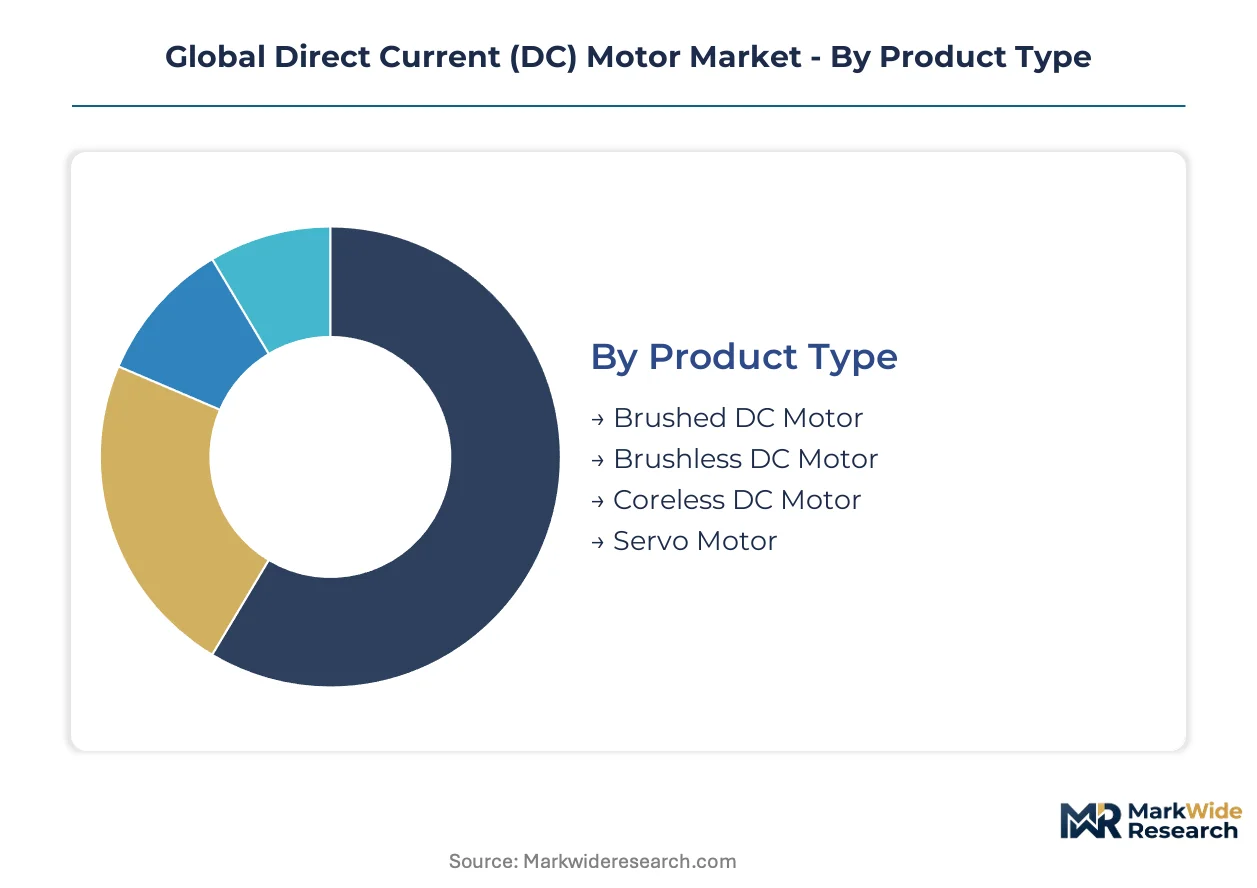
DC motor segmentation reveals distinct technology-performance tradeoffs across electromagnetic architectures, with commutation method and rotor construction determining efficiency ceilings and application suitability. Procurement patterns diverge sharply between cost-driven volume segments and precision-critical premium tiers.
Product Type:
Commutation technology separates segments by efficiency, maintenance burden, and power density, with electronic switching displacing mechanical contact across most power classes above fractional horsepower.
- Brushless DC Motor:Permanent magnet rotors with electronic commutation achieve efficiencies exceeding ninety percent while eliminating brush wear. Electric vehicle traction applications above two kilowatts specify these designs to meet regenerative braking integration and thermal management requirements. Brushless DC Motor leads on scale; Coreless DC Motor leads on momentum.
- Brushed DC Motor:Mechanical commutators with carbon brush-gear contact dominate fractional horsepower applications where controller simplicity outweighs efficiency penalties. Residual inventory in developing manufacturing bases delays replacement cycles despite efficiency mandates from MIIT and the US Department of Energy.
- Coreless DC Motor:Self-supporting copper coil rotors without iron cores minimize inertia for sub-millisecond positioning response in surgical robotics and optical instrumentation.
- Servo Motor:Closed-loop position feedback systems integrate encoders with brushless architectures for CNC machine tools and industrial robotics requiring precise motion control.
Brushless architectures command volume leadership; coreless designs capture the steepest expansion trajectory in medical miniaturization.
Technology:
Rotor construction and feedback methodology determine thermal performance, cogging torque, and control precision across electromagnetic designs.
- Iron Core:Laminated steel rotor assemblies concentrate magnetic flux for maximum torque density in industrial servo and traction applications. Germany's precision automation cluster in Stuttgart specifies iron-core servo motors for CNC systems demanding high peak torque.
- Coreless:Copper windings self-supported without magnetic steel eliminate cogging torque and enable sub-millisecond acceleration for optical scanners and surgical instruments.
- Slotless:Smooth stator bores with windings inserted into epoxy or fiber-reinforced slots reduce magnetic hysteresis losses for high-speed spindle applications.
- Sensorless:Back-EMF detection algorithms replace physical Hall sensors to reduce component count and improve reliability in cost-constrained consumer electronics and automotive actuators.
Iron Core dominates installed base; Sensorless technology is gaining share fastest through automotive cost reduction pressures.
Application:
End-use requirements for torque ripple, thermal cycling, and positioning precision dictate motor specification across industrial, consumer, and mobility segments.
- Electric Vehicles:Traction motors demand continuous-duty thermal management and regenerative braking compatibility. China's dual carbon goals accelerate brushless adoption in domestic EV manufacturing.
- Robotics:Servo-grade precision with minimal backlash requirements drives demand for encoder-integrated brushless systems in collaborative and industrial robot joints.
- Power Tools:High intermittent torque density favors compact brushless designs for cordless drills and angle grinders competing on battery runtime.
- HVAC Systems:Continuous-duty blower and compressor applications specify electronically commutated motors to meet DOE efficiency standards under NEMA MG-1.
- Consumer Electronics:Cost-optimized brushed and sensorless brushless motors populate cooling fans, hard drive spindles, and personal care devices.
Electric Vehicles anchor volume demand; Robotics exhibits the most rapid expansion in unit value terms.
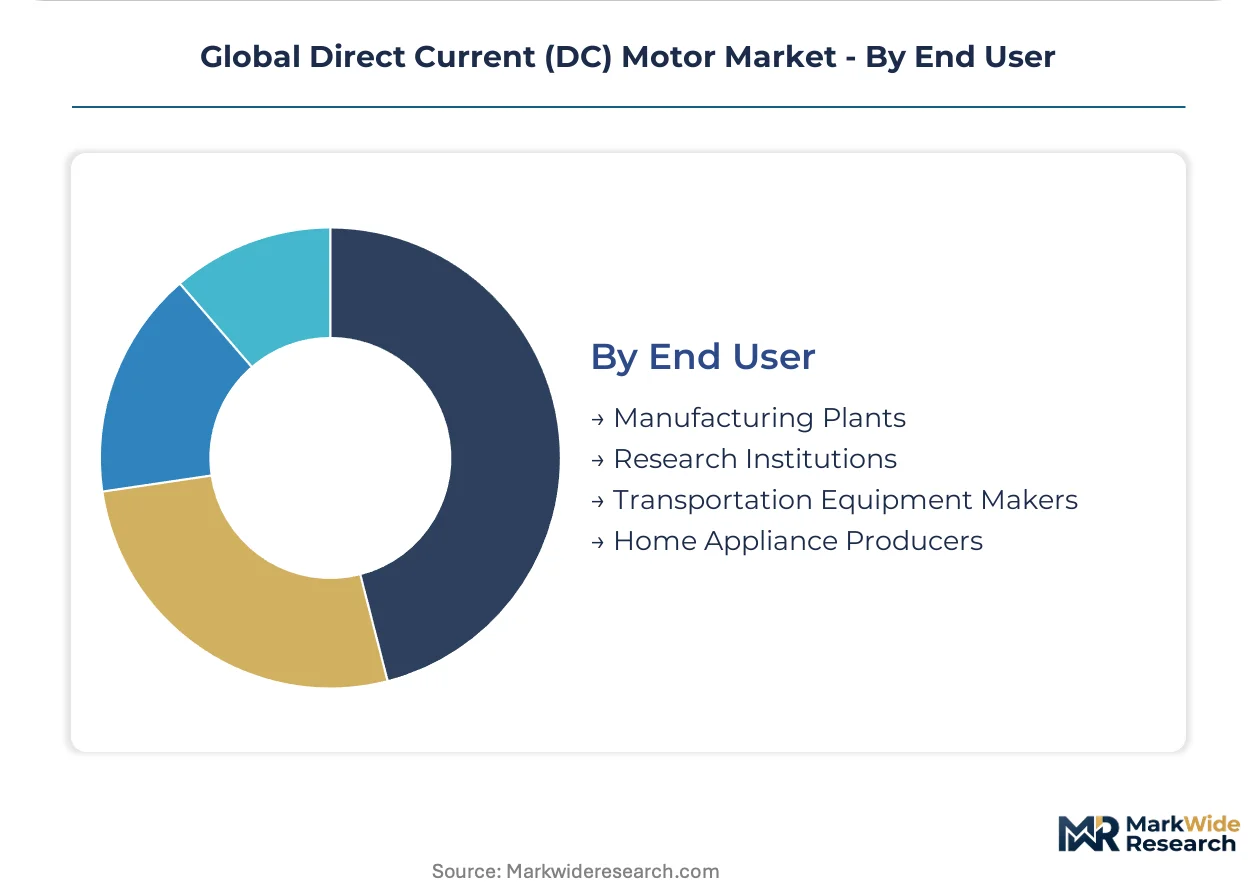
End User:
Procurement sophistication and technical specification authority vary dramatically between OEM integrators and institutional research buyers.
- Transportation Equipment Makers:Automotive and aerospace OEMs specify motors to IATF 16949 quality standards with eighteen to twenty-four month qualification timelines. Tier-one suppliers integrate SiC power modules for 800-volt architectures.
- Manufacturing Plants:Industrial end-users replace legacy brushed motors under GB 18613 and NEMA MG-1 efficiency mandates, consolidating supplier lists around vendors with verified magnet sourcing.
- Home Appliance Producers:White goods manufacturers specify cost-optimized brushless motors for compressors and fans to meet minimum efficiency regulations.
- Research Institutions:Universities and national laboratories procure custom coreless and slotless motors for prototype optical and surgical systems with low volume but high technical collaboration requirements.
Transportation Equipment Makers drive premium specification; Manufacturing Plants generate the largest replacement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision automation cluster concentrates servo motor demand for robotics and CNC systems, while efficiency mandates across multiple jurisdictions accelerate replacement cycles for legacy brushed designs.
China
Domestic electric vehicle manufacturing scales brushless traction motor procurement as BYD and CATL expand production capacity. MIIT enforces GB 18613 efficiency tiers that phase out IE2-equivalent motors from industrial installations. The Yangtze River Delta manufacturing corridor around Shanghai and Suzhou hosts dense concentrations of motor assembly operations serving export markets.
Germany
Stuttgart and Munich industrial corridors drive premium servo motor specification for automotive robotics and machine tool applications. ECHA REACH documentation requirements for neodymium traceability consolidate procurement around vendors with verified magnet sourcing. Baden-Württemberg's automation ecosystem anchors European demand for iron-core servo architectures in precision manufacturing.
United States
Transportation electrification and industrial automation sustain demand for high-efficiency brushless designs across automotive and HVAC applications. DOE enforces NEMA MG-1 minimum efficiency standards compelling manufacturing plants to retire legacy brushed units. The Midwest industrial belt around Michigan and Ohio concentrates motor procurement for automotive tier-one suppliers.
Japan
Precision manufacturing and robotics integration sustain demand for compact, high-reliability motor designs in factory automation. METI efficiency guidelines and JIS standards shape industrial procurement specifications for premium-efficiency units. The Chubu region around Nagoya hosts concentrated motor production serving Toyota and Honda supply chains.
India
Automotive component manufacturing and renewable energy equipment sustain expanding motor demand across industrial and mobility applications. PLI scheme incentives for advanced cell chemistry manufacturing create adjacent demand for precision actuators in battery assembly. Gujarat and Maharashtra industrial zones concentrate motor procurement for textile machinery and automotive component production.
Global Direct Current (DC) Motor Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue medical miniaturization and digital service unbundling. The market structure reflects moderate consolidation around integrated drive-motor pairing specialists and captive magnet processors, with fragmentation persisting in cost-optimized automotive actuator segments. Three archetypes dominate: vertically integrated rare-earth processors, precision servo specialists, and scale-driven automotive component suppliers. Competitive dynamics center on backward integration into magnet supply chains and SiC power module integration for 800-volt architectures.
Within the integrated processing tier, Nidec Corporation and Johnson Electric Holdings Limited represent contrasting geographic and structural approaches. Nidec anchors permanent magnet motor production through integrated capabilities spanning Japan and Vietnam. Johnson Electric leverages Dongguan manufacturing scale to compete in automotive actuator volume segments. Siemens AG exemplifies the drive-motor pairing architecture archetype, dominating industrial servo applications through bundled hardware-software systems.
| Leading Market Players |
|---|
| Johnson Electric Holdings Limited |
| Allied Motion Inc. |
| Nidec Corporation |
| Oriental Motor |
| Maxon Motor |
| ABB |
| AMETEK Inc. |
| Harmonic Drive LLC |
| Siemens AG |
| Others |
Supply & Pricing Matrix
Silicon carbide power module integration into 800-volt drivetrain architectures compresses motor-inverter procurement economics while concentrating supply leverage among tier-one automotive suppliers with captive semiconductor sourcing. This technology transition simultaneously elevates upfront system costs and eliminates discrete component pricing arbitrage across China's Yangtze River Delta and Germany's Baden-Württemberg manufacturing corridors.
Pricing Analysis
Neodymium magnet cost pass-through dominates pricing volatility for permanent magnet motor tiers, with backward-integrated producers capturing margin stability unavailable to contract-dependent competitors. Three-tier pricing structure across premium servo, standard industrial, and economy actuator levels separates vendors by certification depth and magnet traceability documentation. Price erosion runs through brushed motor residual inventory as China's MIIT and the US Department of Energy accelerate efficiency mandate enforcement. Manufacturing plants exhibit highest price sensitivity due to bulk replacement volumes, while research institutions tolerate premium positioning for custom coreless specifications.
Supply Chain Analysis
After-market refurbishment flows for industrial servo motors extend asset life cycles and fragment new-unit demand across Japanese and South Korean factory automation installations. Rare-earth magnet processing concentrates in China, Vietnam, and Japan, with sintered neodymium feedstock drawing from concentrated northern Chinese mining operations. REACH traceability documentation requirements impose single-source vulnerability for European automotive tier-one suppliers lacking ECHA-compliant material passports. Distribution runs through direct OEM contracts for electric vehicle traction applications and industrial distributor networks for replacement motor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DC motor market represents a late-cycle quality story as electric vehicle traction specifications harden thermal management and regenerative braking integration requirements beyond commodity motor capabilities.
For Market Incumbents: Cement magnet supply security through captive processing investments in Vietnam or Japan to offset neodymium price volatility exposure. Deepen SiC inverter integration partnerships with automotive tier-one suppliers before 800-volt architecture procurement consolidates around integrated drivetrain specialists. Reinforce position against emerging coreless motor entrants in medical robotics by accelerating encoder-integrated servo platform certifications. For New Entrants and Emerging Players: Direct-to-manufacturer digital procurement platforms offer lowest-friction entry into aftermarket replacement demand among North American and European manufacturing plants seeking transparent magnet traceability documentation. Target India's battery assembly equipment market under PLI scheme incentives where precision actuator demand outpaces established supplier presence. Pursue white-label coreless motor partnerships with surgical instrument OEMs seeking sub-millimeter positioning specifications. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap brushed motor producers with unconverted industrial installed bases and pending efficiency mandate exposure. Five-to-ten year viability favors backward-integrated permanent magnet specialists over discrete assemblers vulnerable to rare-earth supply consolidation. Watch for IATF 16949 certification timeline compression as inflection signal for automotive qualification bottleneck easing.| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Processing Backward Integration | Captive neodymium sourcing insulates margin stability against ECHA traceability requirements. |
| SiC Inverter-Motor System Integration | 800-volt drivetrain consolidation eliminates discrete procurement models among automotive OEMs. |
| Coreless Motor Miniaturization R&D | Sub-millimeter positioning capabilities unlock surgical robotics premium pricing pools. |
| Digital Twin Predictive Maintenance Platform | Siemens SINAMICS-style service unbundling captures recurring revenue from Japanese industrial users. |
| India Manufacturing Footprint Expansion | Gujarat and Maharashtra proximity to PLI scheme battery assembly creates adjacent actuator demand. |
Research Methodology
Coverage spans China, Germany, the United States, Japan, and India, with primary inputs from each market's industrial automation corridor. Motor procurement directors at automotive tier-one suppliers, plant engineers at manufacturing facilities, and biomedical equipment specialists at research institutions provided qualitative demand assessments. Secondary validation drew from MIIT efficiency standard filings, ECHA REACH documentation databases, NEMA MG-1 regulatory updates, and SEC filings from listed motor producers. Bottom-up unit demand modeling triangulated against top-down market value estimates from trade flow analysis.
Granularity-level modeling distinguished brushless, brushed, coreless, and servo architectures by power class, commutation technology, and end-use application. Segmentation dimensions included rotor construction type, feedback methodology, and regional regulatory cluster across the projection horizon. CAGRs derived from replacement cycle acceleration under GB 18613 and NEMA MG-1 mandates, electric vehicle traction motor content per vehicle trajectories, and medical robotics miniaturization adoption curves. Forecast inputs incorporated rare-earth price scenario modeling and SiC power module cost-down trajectories.
Neodymium supply disruption, efficiency mandate enforcement delays, and automotive platform electrification pace are the dominant revision risks to base-case projections. Forecasts reflect assumptions regarding magnet traceability documentation compliance timelines and industrial distributor channel stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
Explosion Proof Electric Motors and Actuators Sales Market
Industrial Motors
Safety Drives and Motors Market
Industrial Motors
Global Medium and High Power Motors Market
Industrial Motors
Variable Speed Drive Market
Industrial Motors
Asia Pacific Safety Drives and Motors Market
Industrial Motors
US Electric Motor Market
Industrial Motors
High Voltage Motor Sleeve Bearing Market
Industrial Motors
Smart Motors Market
Industrial Motors
Seamless Steel Gas Cylinders Market
Industrial Motors
Submersible Pump Motor Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Europe Induction Motor Market
Industrial Motors
Oil Mist Collector Market
Industrial Motors
Global Linear Motors Market
Industrial Motors
Global Switched Reluctance Motor Market