
 Oil and Gas Accumulators Market | 2026-2036
Oil and Gas Accumulators Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Accumulators Market Intelligence
API 16D certification for subsea blowout preventer control systems is collapsing the supplier base to qualified manufacturers. Bosch Rexroth AG leverages its integrated hydraulics portfolio to dominate deepwater accumulator contracts. Parker Hannifin Corp. sustains aftermarket revenue through its global service network for bladder and piston replacement. Eaton Corporation PLC competes on energy storage configurations for offshore platform hydraulic power units.
Oil and gas accumulators are pressure vessels storing hydraulic fluid under compressed gas—typically nitrogen at 3,000 to 5,000 psi—to deliver instantaneous energy for emergency shutdowns, motion compensation, and pressure surge damping. Bladder accumulators lead installed base volumes due to their compact form factor and rapid response in blowout preventer stacks, while piston accumulators capture higher-margin subsea applications requiring metal-sealed durability at extreme depths. Hydraulic technologies anchor the dominant technology position, though electronic controls are penetrating condition monitoring and predictive maintenance workflows.
API standards, ASME Boiler and Pressure Vessel Code Section VIII, and BSEE well control regulations collectively dictate material selection, welding qualifications, and testing protocols for offshore accumulator deployments. The US Environmental Protection Agency and Bureau of Safety and Environmental Enforcement enforce spill containment mandates that expand accumulator redundancy requirements on floating production facilities. Stakeholders must weigh captive nitrogen recharge infrastructure against third-party service dependencies as field electrification alters hydraulic power architectures.
Market Dynamics
API 16D certification requirements for subsea blowout preventer control systems are compressing the qualified supplier base and concentrating contract awards among integrated hydraulics specialists with captive testing infrastructure.
Growth Catalysts
- Deepwater expansion in the US Gulf of Mexico:Offshore drilling contractors are deploying redundant accumulator banks for blowout preventer stacks at depths exceeding 10,000 feet, tightening safety equipment density per wellhead.
- BSEE well control mandates:The Bureau of Safety and Environmental Enforcement enforces accumulator redundancy requirements on floating production facilities, mandating nitrogen-backed emergency shutdown capacity.
- Metal-sealed piston technology:Durability at extreme depths is displacing bladder accumulators in subsea applications, opening higher-margin contract categories for pressure-rated vessel manufacturers.
Market Restraints
- Nitrogen supply chain concentration:Industrial gas infrastructure clusters around Port Fourchon and Houston, creating third-party service dependencies for offshore recharge operations.
- ASME Section VIII compliance costs:Material selection and welding qualification protocols for pressure vessels extend fabrication timelines and compress margin structures for non-specialized fabricators.
- Field electrification substitution:All-electric subsea actuation architectures are eliminating hydraulic power units in greenfield developments, threatening accumulator demand in newbuild projects.
Strategic Opportunities
- Brazil pre-salt development:ANVISA and national oil company procurement standards are opening accumulator qualification pathways for manufacturers with existing API certification.
- Condition monitoring convergence:Electronic sensor integration with hydraulic accumulators enables predictive maintenance contracts and recurring revenue streams for bladder and piston replacement.
- EU Green Deal methane abatement:F-Gas Regulation compliance is accelerating accumulator deployments for emergency shutdown systems on North Sea platform retrofits.
Industry Challenges
- API 16D certification timeline compression:Subsea safety equipment qualification cycles now exceed 18 months, locking working capital in testing protocols before contract eligibility.
- Welding inspector scarcity:ASME-qualified pressure vessel welders and NDT technicians command premium wages in Houston and Aberdeen, constraining fabrication capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Accumulators Market |
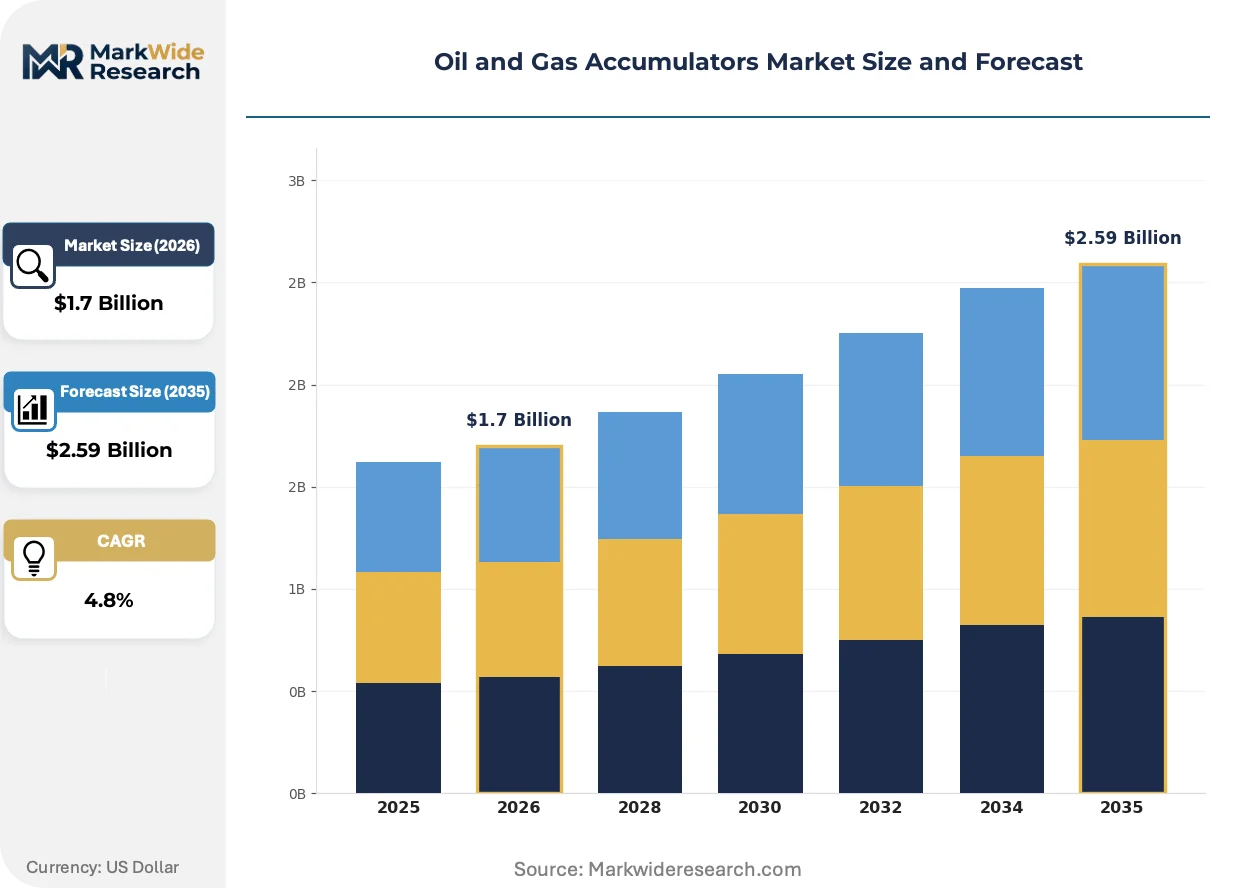
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $2.59 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bladder Accumulators, Piston Accumulators, Diaphragm Accumulators, Spring Accumulators End User: Exploration Companies, Drilling Contractors, Oil Refiners, Service Operators Application: Hydraulic Systems, Pressure Maintenance, Energy Storage, Shock Absorption Technology: Hydraulic Technologies, Pneumatic Systems, Electronic Controls, Mechanical Designs |
| Companies Covered | Accumulators Inc., Airmo Inc., Bosch Rexroth AG, Eaton Corporation PLC, Hydac International GmbH, Parker Hannifin Corp., Nippon Accumulator Co., Ltd, HAWE Hydraulik SE, Hydroll, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Accumulators Market Strategic Shifts & Innovations
Digital instrumentation is penetrating hydraulic accumulator systems, converting passive pressure vessels into data-generating assets that anchor predictive maintenance workflows for offshore operators.
Composite-wrapped pressure vessels are supplanting traditional steel accumulators in topside applications, cutting weight by 60% for floating platform installations. Offshore engineering contractors in the US Gulf Coast cluster are specifying carbon fiber overwrap for motion compensation systems. This material transition is compressing freight costs and enabling modular skidding configurations that reduce offshore crane time.
REACH substance restrictions are forcing reformulation of hydraulic fluids and elastomeric bladder compounds in European offshore deployments. ECHA candidate list screening now extends to accumulator seal materials, compelling manufacturers to maintain dual formulation inventories. North Sea operators are responding by consolidating procurement with suppliers holding EU-registered chemical dossiers.
Integrated service contracts are bundling accumulator supply with captive nitrogen recharge infrastructure, displacing transactional equipment sales. Offshore drilling contractors in Brazil and West Africa are specifying ten-year lifecycle agreements that internalize maintenance liability. This model compresses upfront capital outlays while locking in aftermarket revenue for qualified service networks.
Oil and Gas Accumulators Market Segmentation
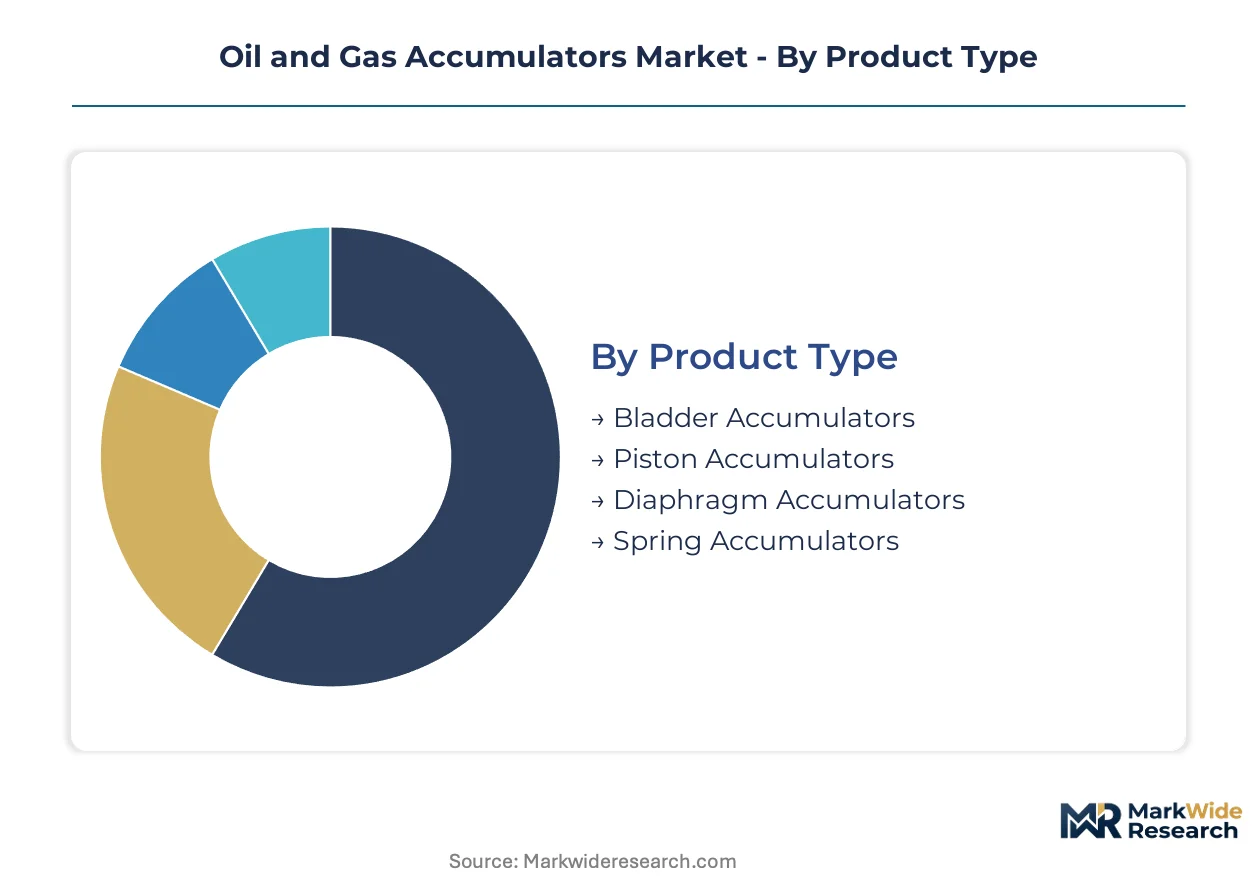
Oil and gas accumulator procurement channels diverge sharply by product complexity and certification burden. Bladder and piston accumulators for subsea blowout preventers flow through API-qualified integrators, while topside maintenance volumes sustain aftermarket distributors.
Product Type:
Bladder accumulators move through OEM-integrator channels for newbuild blowout preventer stacks, while piston units command project-direct sales for deepwater developments. Diaphragm and spring variants circulate through maintenance distributors serving platform retrofit markets.
- Bladder Accumulators:Elastomeric membrane separates nitrogen charge from hydraulic fluid, enabling rapid discharge rates critical for emergency shutdown sequences. Demand clusters around Houston fabrication yards supplying US Gulf of Mexico drillship fleets, where API 16D certification requirements compress the qualified supplier base.
- Piston Accumulators:Metal-sealed piston architecture withstands hydrostatic pressures exceeding 10,000 psi at extreme ocean depths. Norwegian and Brazilian deepwater projects specify these units for subsea production systems, displacing bladder technology in metal-to-metal sealing applications.
- Diaphragm Accumulators:Flexible membrane design suits compact installations on offshore platform topsides where weight constraints dominate.
- Spring Accumulators:Mechanical energy storage eliminates gas recharge dependencies for isolated wellhead protection systems.
Bladder accumulators dominate installed base. Piston accumulators are where expansion concentrates.
End User:
Procurement authority varies by contract structure—integrated drilling contractors consolidate accumulator purchasing for rig fleets, while national oil companies specify subsea safety equipment directly.
- Exploration Companies:Supermajors and independents define accumulator redundancy specifications for frontier drilling programs. Gulf of Mexico lease operators mandate nitrogen-backed emergency capacity exceeding BSEE minimums, concentrating procurement with API-certified fabricators.
- Drilling Contractors:Transocean, Seadrill, and Noble Corporation standardize accumulator configurations across floating rig fleets to simplify maintenance logistics and crew training protocols.
- Oil Refiners:Downstream processing facilities deploy accumulators for hydraulic power unit buffering in catalytic cracking units.
- Service Operators:Schlumberger and Halliburton well intervention divisions specify compact accumulator skids for coiled tubing and wireline units.
Drilling contractors control newbuild specification. Service operators drive replacement volume.
Application:
Application segmentation tracks the functional migration from pure energy storage toward integrated condition monitoring platforms.
- Hydraulic Systems:Blowout preventer control systems represent the dominant application, with redundant accumulator banks delivering instantaneous fluid volume for ram closure. US Gulf Coast fabrication clusters supply these configurations for ultra-deepwater drillships.
- Pressure Maintenance:Subsea production trees utilize accumulators to compensate for hydrostatic pressure variations during well intervention operations.
- Energy Storage:Motion compensation systems on floating platforms deploy accumulator arrays to dampen vessel heave effects on riser tensioners.
- Shock Absorption:Mud pump pulsation dampening protects downstream piping from pressure spikes during high-rate drilling.
Hydraulic systems anchor revenue. Energy storage is climbing the fastest.
Technology:
Technology segmentation reveals a bifurcation between mature hydraulic architectures and emerging electronic overlays.
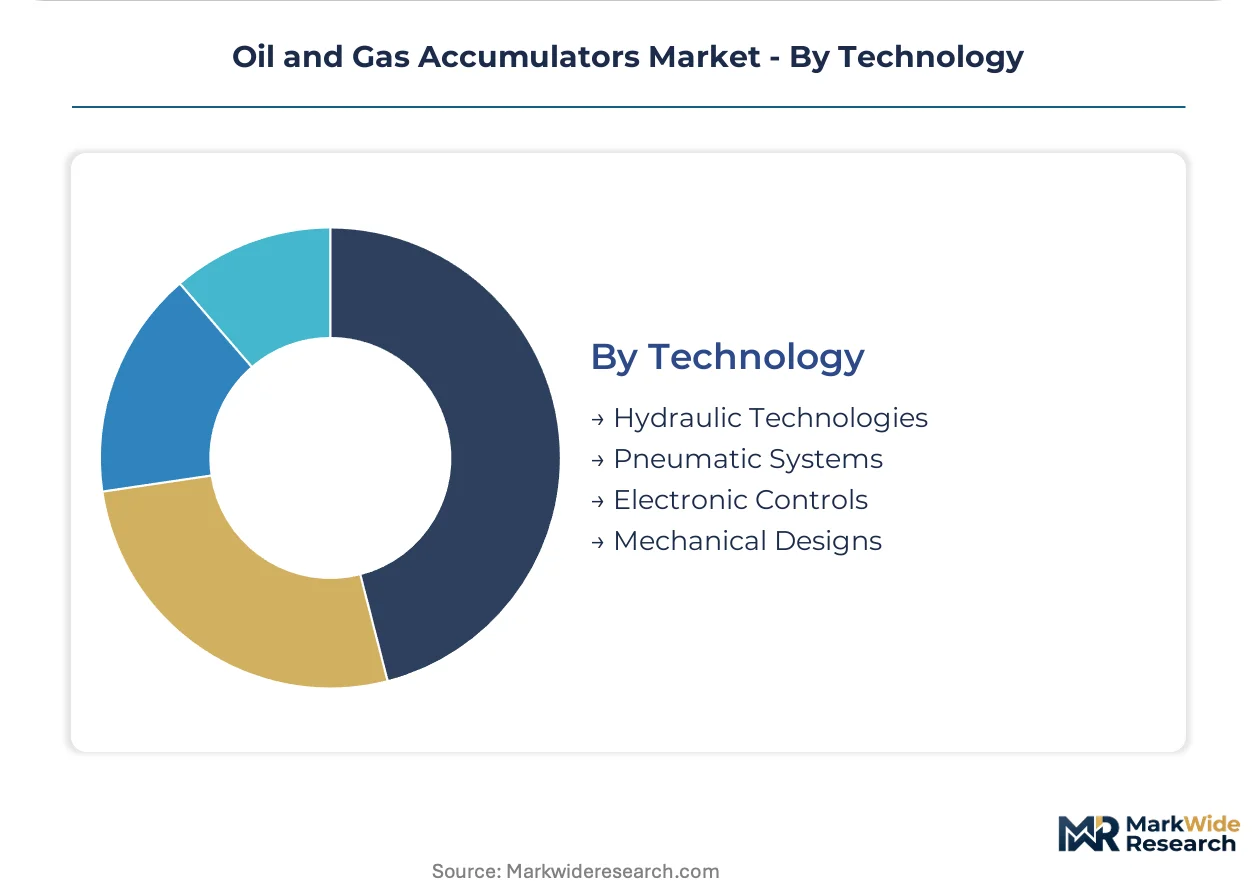
- Hydraulic Technologies:Nitrogen-charged pressure vessels remain the foundational architecture, with 3,000 to 5,000 psi operating pressures standardized across offshore applications. ASME Section VIII compliance dictates material selection and welding protocols.
- Pneumatic Systems:Compressed air alternatives serve onshore production facilities with lower pressure requirements and accessible recharge infrastructure.
- Electronic Controls:Pressure transducers and IoT-enabled monitoring modules convert passive accumulators into predictive maintenance assets. North Sea operators pilot these systems to optimize bladder replacement intervals.
- Mechanical Designs:Spring-loaded and weight-accumulator variants persist in safety-critical applications demanding absolute independence from external power or gas supplies.
Hydraulic technologies command installed base. Electronic controls are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BSEE well control mandates and ANVISA procurement standards are redirecting accumulator contract flows toward certified fabrication hubs in the Americas and North Sea. National regulators in Brazil, Norway, and the United States are tightening subsea safety equipment qualification timelines. Industrial clusters in Houston, Port Fourchon, and Aberdeen are expanding pressure vessel welding capacity to capture this contract migration.
United States
Ultra-deepwater drilling in the Gulf of Mexico is driving redundant accumulator bank deployments at depths exceeding 10,000 feet. BSEE enforces nitrogen-backed emergency shutdown capacity mandates on floating production facilities. Houston fabrication yards and Port Fourchon service bases concentrate API 16D-certified manufacturing and captive nitrogen recharge infrastructure.
Brazil
Pre-salt development programs are opening accumulator qualification pathways for manufacturers with existing API certification. ANVISA and Petrobras procurement standards require localized testing protocols for subsea blowout preventer control systems. Rio de Janeiro and Macaé industrial corridors host pressure vessel fabricators serving the Santos Basin drillship fleet.
Norway
North Sea platform retrofits under EU Green Deal methane abatement targets are accelerating emergency shutdown system deployments. The F-Gas Regulation compels accumulator seal material reformulation and REACH-compliant hydraulic fluid substitution. Stavanger and Bergen engineering clusters specialize in metal-sealed piston accumulators for subsea production trees at extreme ocean depths.
United Kingdom
Decommissioning delays and field life extension projects are sustaining accumulator replacement demand on legacy platform infrastructure. The Health and Safety Executive enforces pressure system safety regulations that tighten inspection intervals for hydraulic power units. Aberdeen's subsea engineering corridor maintains bladder and piston accumulator service networks for North Sea drilling contractors.
China
Offshore exploration in the South China Sea is expanding domestic accumulator fabrication capacity for state-owned drilling fleets. GB standards and MEE environmental regulations are converging with API certification requirements for export-qualified manufacturers. Dalian and Qingdao shipyard clusters are integrating accumulator skids into locally constructed semi-submersible drilling rigs.
Oil and Gas Accumulators Market Key Industry Players
Listed leaders compete with private specialists across certification infrastructure and aftermarket service density. The supplier base compresses around API 16D-qualified fabricators with captive pressure testing facilities, while non-certified players retreat to topside maintenance niches. Three archetypes dominate: integrated hydraulics conglomerates with global service networks, regional pressure vessel specialists with deepwater welding qualifications, and captive equipment divisions of offshore drilling contractors. Competitive moves center on backward integration into nitrogen recharge logistics and condition monitoring technology licensing.
Among Germany-based hydraulics conglomerates, Bosch Rexroth AG and Hydac International GmbH exemplify the integrated systems archetype with bundled accumulator and control component portfolios. Parker Hannifin Corp. represents the aftermarket service model through its global bladder and piston replacement network. These three anchors illustrate how certification burden and service density now determine contract eligibility more than unit pricing.
| Leading Market Players |
|---|
| Accumulators Inc. |
| Airmo Inc. |
| Bosch Rexroth AG |
| Eaton Corporation PLC |
| Hydac International GmbH |
| Parker Hannifin Corp. |
| Nippon Accumulator Co., Ltd |
| HAWE Hydraulik SE |
| Hydroll |
| Others |
Cost & Logistics Intelligence
Long-term lifecycle service contracts lock in both supply access and price visibility for offshore drilling contractors, compressing upfront capital outlays while internalizing nitrogen recharge logistics and predictive maintenance liability across ten-year agreements in Brazil and West Africa.
Pricing Analysis
Certification level creates the primary spread between API 16D-qualified fabricators and non-certified topside maintenance suppliers. Pricing stratifies across premium certified, standard industrial, and economy refurbishment tiers based on ASME Section VIII compliance depth and captive testing infrastructure ownership. Cost compression in the economy tier is intensifying because Port Fourchon nitrogen supply chain concentration forces third-party service dependencies. Exploration companies show least price sensitivity for subsea blowout preventer stacks, while downstream oil refiners drive hard bargaining on hydraulic power unit buffering systems.
Supply Chain Analysis
Strategic stockpiling of ASME-qualified welding capacity dominates inventory strategy, with Houston and Aberdeen fabricators maintaining eighteen-month order backlogs to absorb API 16D certification timeline compression. Manufacturing concentrates in the United States, Norway, and Brazil, drawing from specialty steel plate, nitrogen gas infrastructure, and elastomeric bladder compound feedstocks. Single-source vulnerability runs through certified pressure vessel welder scarcity in Houston and Aberdeen, where NDT technicians command premium wages. Distribution runs through API-qualified integrators for newbuild subsea contracts and aftermarket distributors for platform retrofit volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic control convergence with hydraulic accumulators is accelerating a structural shift from passive pressure vessels to data-generating predictive maintenance assets, tightening contract eligibility around condition monitoring capabilities.
For Market Incumbents: Shield installed base revenue by backward integration into captive nitrogen recharge infrastructure, eliminating third-party service dependencies that emerging competitors exploit. Accelerate ASME Section VIII welding capacity expansion in Houston and Aberdeen before inspector scarcity hardens into permanent bottleneck. Lock in ten-year lifecycle agreements with Brazilian and West African drilling contractors to preempt all-electric subsea actuation substitution in greenfield developments. For New Entrants and Emerging Players: Aftermarket condition monitoring service gaps in the North Sea offer immediate white-space penetration where incumbents under-serve legacy platform infrastructure. Target diaphragm and spring accumulator retrofit segments for offshore platform topsides, where weight constraints and compact installation requirements favor agile specialists over integrated hydraulics conglomerates. Pursue EU-registered chemical dossier compliance to capture REACH substance restriction-driven procurement consolidation among North Sea operators. For Investors and Strategic Acquirers: Regional pressure vessel specialists with deepwater welding qualifications and existing API 16D certification represent the most defensible acquisition archetype in a compressing supplier base. Frame long-term viability around electrification hedging—hydraulic architectures retain dominance in brownfield retrofits and emergency shutdown redundancy even as all-electric systems penetrate greenfield subsea developments. Watch BSEE regulatory tightening velocity as the primary inflection signal; accelerated well control mandate enforcement would extend certification backlog premiums for qualified fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| API 16D Certification Investment | Compresses qualified supplier base and locks in contract eligibility for ultra-deepwater blowout preventer systems. |
| Backward Integration into Nitrogen Logistics | Captures recurring revenue streams and eliminates third-party service dependencies in Port Fourchon and Houston clusters. |
| Condition Monitoring Technology Licensing | Converts passive pressure vessels into predictive maintenance assets for North Sea platform retrofit contracts. |
| Composite-Wrapped Pressure Vessel Transition | Reduces topside weight by sixty percent for floating platform motion compensation system deployments. |
| Long-Term Lifecycle Service Contracts | Internalizes maintenance liability and locks in aftermarket revenue across Brazilian pre-salt development programs. |
Research Approach
Initial hypotheses were tested against primary input from blowout preventer system engineers, offshore drilling contractor procurement directors, ASME-certified pressure vessel fabricators, and subsea safety equipment regulatory specialists, then refined through secondary validation against BSEE enforcement bulletins, API standards documentation, ANVISA procurement guidelines, and SEC filings from listed hydraulics conglomerates. Bottom-up project pipeline aggregation and top-down market sizing triangulation anchored volume estimates.
Variance decomposition across product type, application, technology, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro offshore drilling capex indicators. Modeled inputs included ultra-deepwater rig deployment schedules, nitrogen infrastructure capacity expansion timelines, and electrification substitution curves for subsea production systems.
Underlying assumptions cover BSEE mandate enforcement continuity, ASME welding capacity expansion rates, and API 16D certification timeline stability, with deviation risk concentrated in field electrification acceleration and REACH substance restriction scope expansion. Revision becomes warranted when all-electric subsea actuation penetration exceeds hydraulic redundancy thresholds in greenfield project awards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
Global Seismic Survey Market
Oil & Gas
Oil and Gas Separation Equipment Market
Oil & Gas
Leak Detection for Oil & Gas Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Offshore Oil and Gas Paints and Coatings Market
Oil & Gas
Asia Pacific Oil Storage Tank Service Market
Oil & Gas
Methane Hydrate Extraction Market
Oil & Gas
Europe Intelligent Pigging Market
Oil & Gas
Middle East Wireline Services Market
Oil & Gas
Geothermal Drilling Market
Oil & Gas
Oil and Gas Fittings Market
Oil & Gas
Flow Computer Oil Gas Market
Oil & Gas
Swellable Packers Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Rotary Steerable System Market