
 Breathing Battery Market | 2026-2036
Breathing Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Breathing Battery Market Analysis
Electrochemist talent scarcity is reorganizing competitive dynamics as specialized battery researchers command premium compensation across North America and East Asia. Phinergy leverages its aluminum-air expertise to anchor Israeli manufacturing scale in metal-air systems. PolyPlus Battery Company sustains deep R&D intensity around protected lithium electrodes for aqueous environments. IBM competes through computational materials science, applying quantum simulation to optimize cathode architectures for oxygen reduction kinetics.
Breathing batteries electrochemically reduce ambient oxygen at the cathode while oxidizing a metallic anode—typically lithium, aluminum, or zinc—achieving theoretical energy densities exceeding conventional intercalation chemistries by an order of magnitude. Their primary purpose is to extend range or duration in weight-constrained applications where refueling or mechanical replacement of the anode is operationally viable. Solid-state technology leads in patent filings but alkaline systems occupy the dominant share of near-term demonstration projects due to lower material costs. Grid storage application attracts the fastest-growing capital allocation as utilities evaluate multi-day discharge capability, while portable devices remain a mature segment with limited breathing battery penetration.
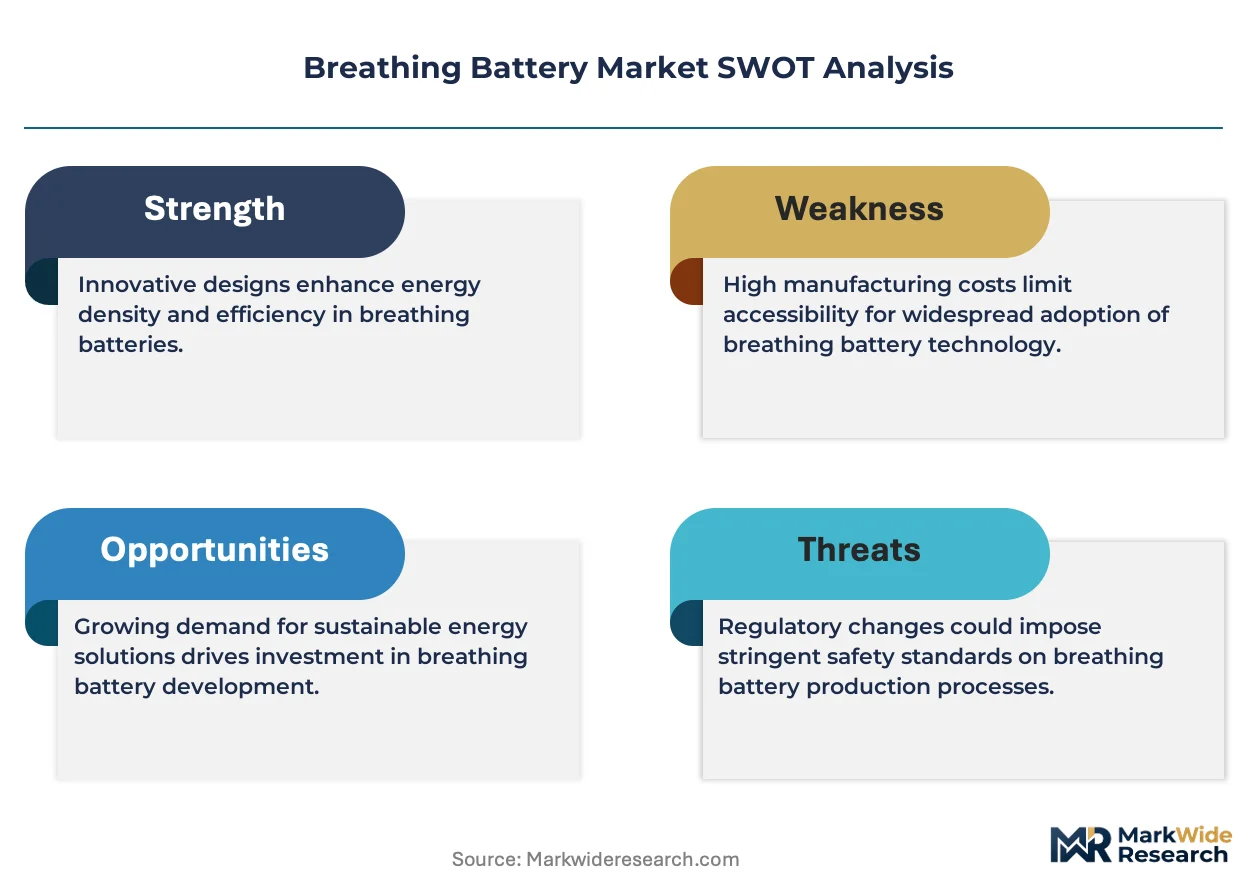
The EU Battery Regulation and ECHA REACH compliance frameworks are tightening carbon footprint disclosure and recycled content mandates for cells sold in Europe, directly shaping product design cycles and supply chain qualification. In the United States, the EPA and Department of Energy coordinate on stationary storage safety standards that influence utility procurement specifications. China's MIIT issues GB standards for electrochemical energy storage that constrain market access for non-compliant foreign suppliers. Stakeholders must monitor how evolving cathode catalyst cost curves and anode replacement logistics reshape total cost of ownership calculations against conventional lithium-ion benchmarks.
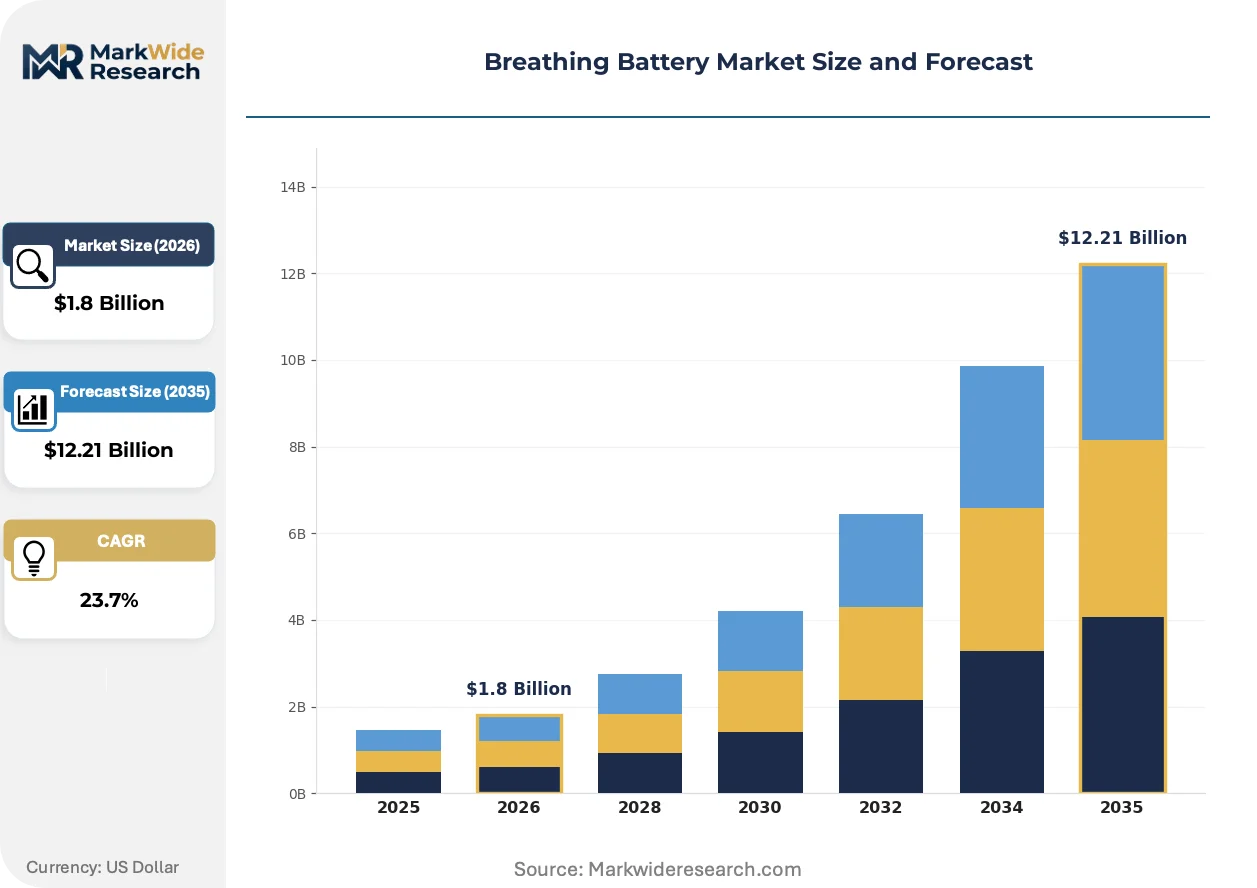
Market Dynamics
Metal-air architectures are forcing a recalibration of energy density benchmarks across weight-constrained mobility applications, with solid-state electrolyte research compressing traditional cathode development cycles and regulatory carbon accounting tightening supply chain qualification protocols.
Growth Catalysts
- EU Battery Regulation:Mandatory carbon footprint disclosure and recycled content thresholds are accelerating design-cycle investments in closed-loop anode recovery systems for European automotive OEMs.
- Grid storage capital reallocation:Utilities in Germany are prioritizing multi-day discharge demonstrations over lithium-ion duration limits, redirecting R&D funding toward alkaline system validation.
- Aluminum anode chemistry:Lower material costs versus lithium-metal precursors are enabling near-term pilot deployments in marine propulsion and backup power applications.
Market Restraints
- Electrochemist talent scarcity:Specialized battery researchers command premium compensation across North America and East Asia, compressing R&D margins for mid-scale developers.
- Cathode catalyst cost volatility:Platinum-group metal dependencies in oxygen reduction architectures expose system economics to precious metal price swings.
- Anode replacement logistics:Mechanical refueling infrastructure for spent metal cartridges remains undeveloped outside Israeli and German test corridors.
Strategic Opportunities
- India stationary storage:CEA grid modernization mandates and PLI scheme incentives for domestic cell manufacturing create entry points for metal-air technology licensors.
- Quantum simulation convergence:Computational materials science platforms are compressing cathode catalyst discovery timelines by integrating density functional theory with machine learning screening.
- Aqueous lithium protection:Protected electrode architectures enable underwater vehicle applications where conventional lithium-ion thermal runaway risks are prohibitive.
Industry Challenges
- GB standards compliance timeline:China's MIIT electrochemical storage certification requirements constrain market access for foreign suppliers lacking localized testing partnerships.
- REACH substance authorization:ECHA scrutiny of electrolyte additives and catalyst precursors extends product registration cycles by 18-24 months for European market entry.
- Interoperability with existing BMS:Voltage profile mismatches between metal-air discharge curves and lithium-ion battery management systems complicate hybrid pack integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breathing Battery Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $12.21 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Alkaline, Lithium-Ion, Solid-State, Redox Flow Application: Grid Storage, Electric Vehicles, Portable Devices, Renewable Energy End User: Residential, Commercial, Industrial, Automotive Form Factor: Cylindrical, Prismatic, Pouch, Modular |
| Companies Covered | IBM, Phinergy, PolyPlus Battery Company, Zinc8 Energy Solutions, Panasonic Corporation, Lithium Air Industries, Duracell, Energizer Holdings, Renata SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breathing Battery Market Emerging Trajectories
Solid-state electrolyte development is fragmenting traditional cathode material hierarchies while regulatory carbon accounting compresses supply chain disclosure standards across cell manufacturing.
Solid-state ceramic and polymer electrolyte architectures are fragmenting the incumbent liquid-electrolyte design paradigm for lithium-air systems. Automotive OEMs in Germany and Japan are accelerating pilot-line investments despite manufacturing yield challenges. This fragmentation is compressing the competitive window for alkaline aqueous systems that currently dominate demonstration project deployments.
The EU Battery Regulation's carbon footprint declaration requirements are forcing anode supply chain requalification for cells sold in Europe. Manufacturers must document upstream mining emissions and recycled content thresholds by chemistry family. German automotive clusters are responding by integrating aluminum-air prototypes into next-generation powertrain testing protocols ahead of 2027 compliance deadlines.
Utility procurement specifications are unbundling duration guarantees from capital expenditure commitments in grid storage tenders. European and North American independent system operators are piloting power-purchase agreements that compensate discharge capability separately from installed capacity. This restructuring favors metal-air architectures in Germany and California where multi-day resource adequacy requirements exceed lithium-ion economic limits.
Breathing Battery Market Segmentation
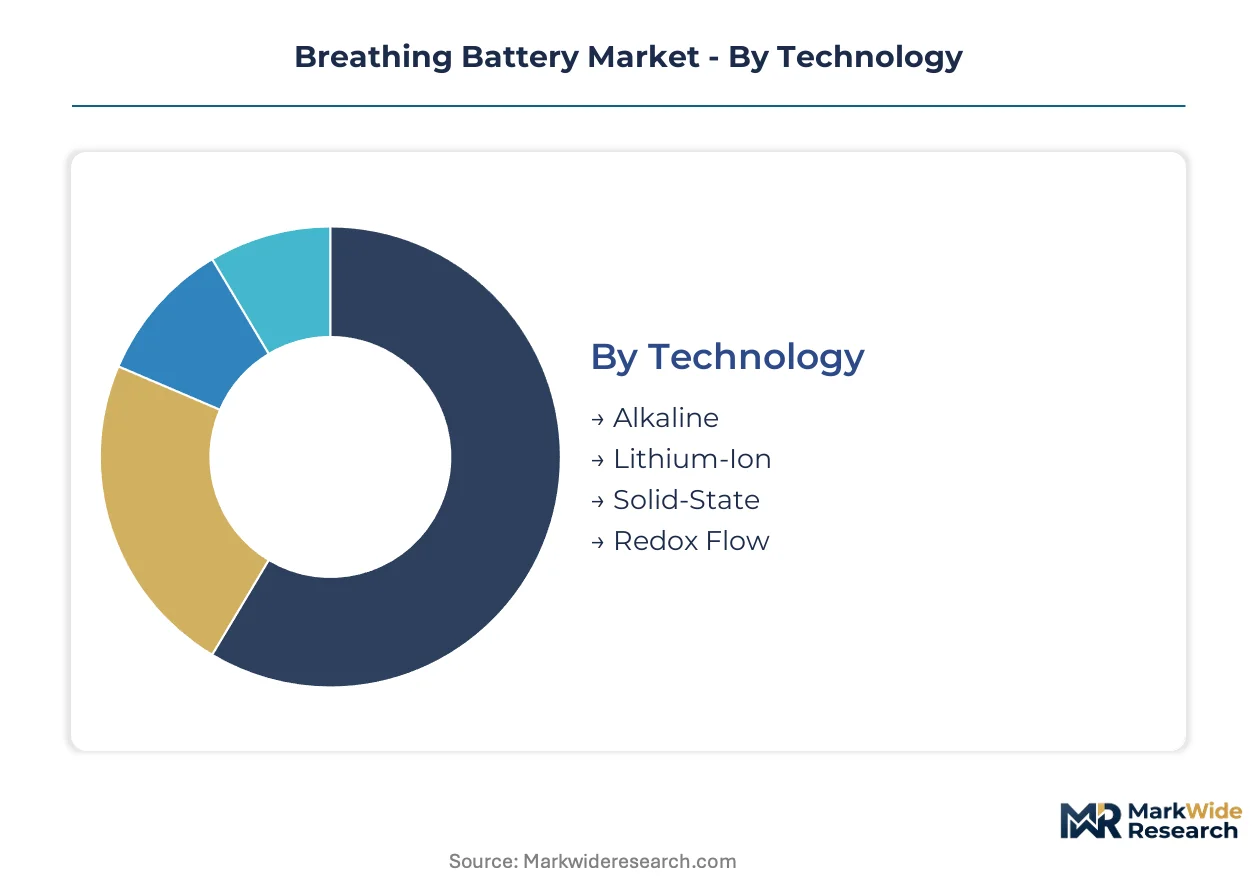
Breathing battery architectures exhibit divergent performance profiles across technology platforms and deployment contexts. Segmentation reveals how solid-state electrolyte research and alkaline system cost advantages are reshaping competitive boundaries across automotive, utility, and consumer applications.
Technology:
Alkaline systems concentrate near-term demonstration activity in Germany and Israel, while solid-state platforms attract export-oriented licensing from Japanese and Korean developers.
- Solid-State:Ceramic and polymer electrolyte architectures eliminate flammable liquid components, enabling lithium-air configurations with theoretical energy densities exceeding intercalation chemistries by an order of magnitude. German automotive OEMs anchor pilot-line investments despite manufacturing yield challenges, driven by EU Battery Regulation carbon footprint thresholds that favor closed-loop anode recovery.
- Alkaline:Aqueous electrolyte systems utilizing zinc or aluminum anodes dominate near-term deployments due to lower material costs and simplified manufacturing. Israeli test corridors and German marine propulsion pilots validate mechanical refueling logistics for weight-constrained mobility applications.
- Lithium-Ion:Conventional intercalation chemistries adapted with oxygen-permeable cathode membranes serve hybrid system bridging functions.
- Redox Flow:Liquid electrolyte architectures with dissolved metal species enable decoupled power-energy scaling for stationary duration extensions.
Alkaline holds the largest share; momentum sits with solid-state as manufacturing yields improve.
Application:
Cost tier stratification separates capital-intensive grid installations from consumer-accessible portable formats, with electric vehicle integration commanding premium R&D allocation.
- Grid Storage:Multi-day discharge capability addresses resource adequacy requirements exceeding lithium-ion economic limits in California and Germany. Utility procurement specifications now unbundle duration guarantees from capital commitments, favoring metal-air architectures in independent system operator pilot programs.
- Electric Vehicles:Range extension through mechanical anode replacement targets weight-constrained commercial fleets where refueling infrastructure investment is operationally viable. German automotive clusters integrate aluminum-air prototypes into next-generation powertrain testing ahead of regulatory compliance deadlines.
- Portable Devices:Limited penetration reflects consumer preference for electrical recharging over mechanical cartridge replacement.
- Renewable Energy:Behind-the-meter pairing with solar installations leverages multi-day storage to shift generation profiles across weather variability.
Grid storage commands the steepest expansion trajectory; electric vehicles absorb the dominant R&D share.
End User:
Customer type determines voltage scaling requirements and replacement logistics complexity, with industrial procurement driving standardization efforts.
- Automotive:OEM integration demands span passenger vehicle range extension to commercial fleet depot refueling, with German manufacturers validating aluminum-air prototypes in controlled test environments.
- Industrial:Manufacturing facilities and data centers prioritize backup power duration over cycling frequency, accepting mechanical anode replacement protocols.
- Commercial:Retail and office installations balance space constraints with multi-day resilience requirements.
- Residential:Consumer acceptance barriers around cartridge handling limit near-term addressable market scope.
Automotive captures the largest investment pool; industrial applications scale fastest with established procurement channels.
Form Factor:
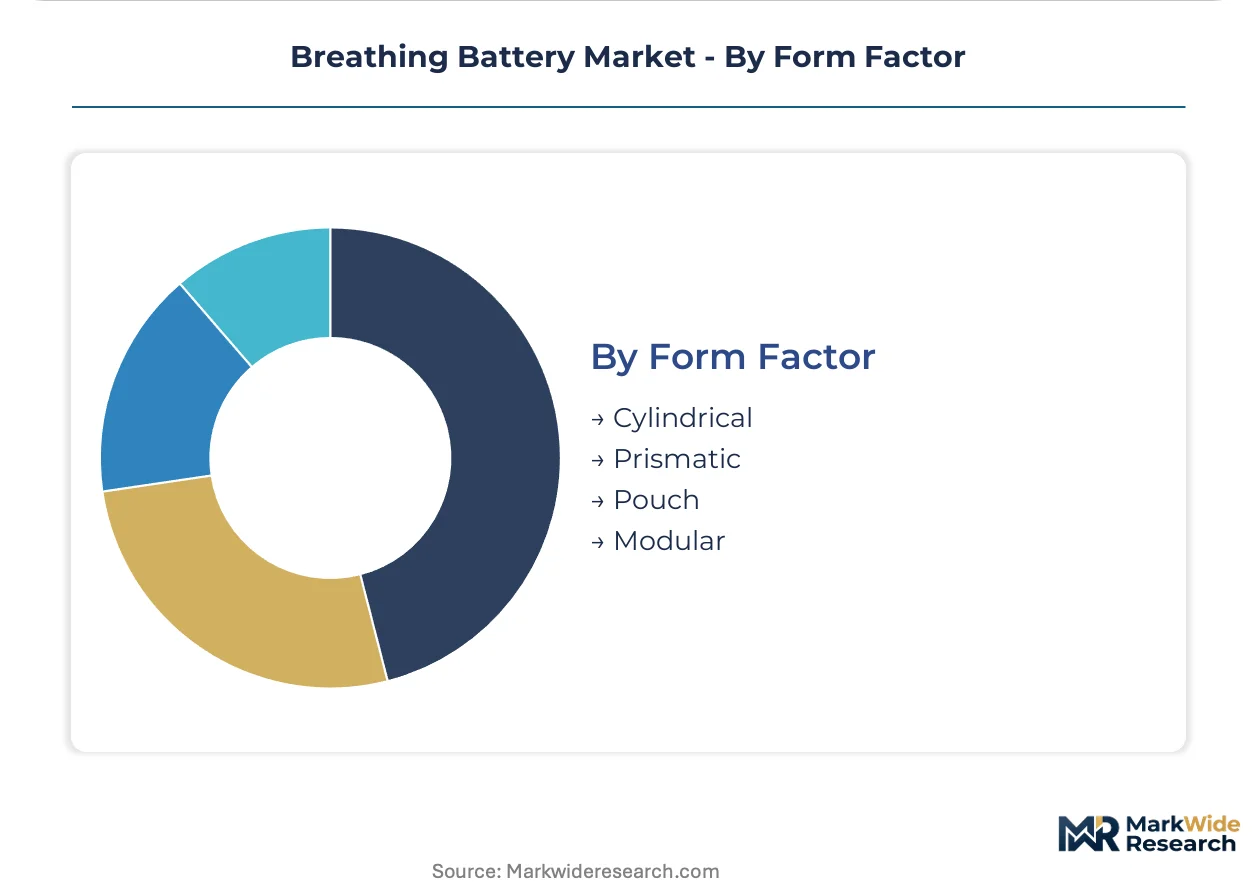
Volume and weight constraints drive packaging innovation, with modular architectures enabling field-replaceable anode cartridges.
- Modular:Stackable cell assemblies with standardized interfaces support hot-swappable anode replacement in marine and backup power applications. Israeli deployment corridors validate logistics for aluminum cartridge exchange.
- Pouch:Flexible polymer housings minimize dead volume in weight-constrained electric vehicle range extenders.
- Prismatic:Rigid rectangular enclosures optimize space utilization in stationary rack installations.
- Cylindrical:Conventional winding architecture leverages existing manufacturing equipment for early-stage production scaling.
Modular formats gain share fastest in marine and utility pilots; prismatic dominates stationary cost optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Battery Regulation anchors European demand trajectories, while Israel and Germany validate mechanical refueling corridors for metal-air systems. Regulatory carbon accounting and automotive OEM integration programs are concentrating investment in specific national clusters.
Germany
Automotive OEMs in Stuttgart and Munich are accelerating aluminum-air prototype testing for commercial fleet range extension. The EU Battery Regulation's carbon footprint disclosure mandates force anode supply chain requalification by 2027 compliance deadlines. Bavarian manufacturing clusters integrate breathing battery modules into next-generation powertrain validation programs.
Israel
Marine propulsion and backup power pilots validate aluminum cartridge exchange logistics in controlled deployment corridors. National energy security priorities support domestic metal-air manufacturing scale-up for grid-independent applications. Tel Aviv-area R&D facilities anchor electrochemist talent concentration for aqueous system optimization.
United States
California independent system operators pilot power-purchase agreements unbundling duration guarantees from capital commitments for multi-day storage. The EPA coordinates with the Department of Energy on stationary storage safety standards influencing utility procurement specifications. Silicon Valley computational materials science platforms compress cathode catalyst discovery timelines through quantum simulation integration.
China
MIIT GB standards for electrochemical energy storage constrain market access for foreign suppliers lacking localized testing partnerships. Domestic OEMs evaluate solid-state lithium-air architectures for weight-constrained mobility applications. Yangtze River Delta manufacturing hubs concentrate pilot-line investments despite ceramic electrolyte yield challenges.
India
CEA grid modernization mandates and PLI scheme incentives for domestic cell manufacturing create entry points for metal-air technology licensors. Multi-day discharge capability addresses resource adequacy requirements exceeding lithium-ion economic limits in renewable-rich states. Tamil Nadu and Gujarat industrial corridors prioritize backup power duration for manufacturing facilities and data centers.
Breathing Battery Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with technology licensors and materials science platforms occupying distinct competitive positions. The structure fragments across electrochemistry expertise, computational simulation capability, and manufacturing scale. Three archetypes dominate: aluminum-air system integrators, protected lithium electrode specialists, and quantum-enabled materials discovery platforms. Capacity expansion in Israeli and German test corridors and strategic technology licensing to automotive OEMs represent the dominant competitive moves.
Within the electrochemistry specialist tier, Phinergy anchors Israeli manufacturing scale in metal-air systems, PolyPlus Battery Company exemplifies protected lithium electrode R&D intensity for aqueous environments, and IBM occupies a position in computational materials science applying quantum simulation to cathode architecture optimization. These three entities represent divergent strategic vectors: mechanical refueling logistics, electrode protection chemistry, and algorithmic catalyst discovery.
| Leading Market Players |
|---|
| IBM |
| Phinergy |
| PolyPlus Battery Company |
| Zinc8 Energy Solutions |
| Panasonic Corporation |
| Lithium Air Industries |
| Duracell |
| Energizer Holdings |
| Renata SA |
| Others |
Supply Flow & Price Mechanics
Pilot-line utilization rates at German automotive clusters and Israeli marine corridors establish minimum viable scale thresholds that compress unit economics for alkaline system manufacturers while elevating entry barriers for solid-state developers. These scale effects concentrate pricing power among incumbent aluminum-air integrators and force mid-tier entrants toward cost-plus positioning in backup power niches.
Pricing Analysis
German procurement premiums exceed Israeli marine deployment costs by substantial margins due to EU Battery Regulation compliance documentation and automotive-grade certification requirements. Project-based long-term offtake contracts dominate grid storage tenders, while mechanical refueling services command separate fee structures from hardware sales. Price differentiation rests on certification tier (ISO 6469 for automotive, IEC 62619 for stationary) and volume scale, with utility buyers exhibiting highest sensitivity due to unbundled duration guarantees. Cost compression in alkaline aqueous systems is intensifying because aluminum anode suppliers are consolidating feedstock contracts.
Supply Chain Analysis
China and South Korea anchor ceramic electrolyte precursor production, while Israel and Germany concentrate aluminum-air cartridge manufacturing and mechanical refueling infrastructure deployment. Cathode catalyst supply draws from South African platinum-group metal refiners and Chinese manganese oxide processors, with polymer separator membranes sourcing from Japanese specialty chemical producers. Single-source vulnerability concentrates in solid-state ceramic powder supply, where limited qualified vendors constrain capacity expansion timelines. Distribution runs through automotive Tier 1 integrators for OEM programs and direct utility procurement channels for stationary storage deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward German automotive OEMs and California independent system operators as procurement consolidation around multi-year validation programs reduces vendor switching flexibility.
For Market Incumbents: Fortify captive supply of aluminum anode feedstock through backward integration into secondary smelting capacity, while accelerating EU Battery Regulation carbon footprint certification ahead of competitor qualification timelines. Defend position against solid-state lithium-air substitutes by expanding Israeli marine corridor deployments to establish mechanical refueling as the incumbent standard. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany opens automotive qualification pathways without full OEM validation cycles. Target India's CEA grid modernization mandates and PLI scheme incentives as the most penetrable geography, leveraging technology licensing rather than capital-intensive manufacturing scale. Pursue joint development agreements with industrial backup power integrators to bypass automotive certification barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors protected lithium electrode specialists with aqueous system patents over pure-play solid-state developers facing yield challenges. Five-to-ten year viability hinges on cathode catalyst cost curves and anode replacement logistics maturation. Signal to monitor: utility power-purchase agreement structures unbundling duration from capacity in California and Germany independent system operator filings.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Refueling Infrastructure Buildout | Israeli and German deployment corridors validate aluminum cartridge exchange logistics for marine and fleet applications. |
| Backward Integration into Anode Feedstock | Captive aluminum smelting capacity secures supply against commodity volatility and EU carbon footprint mandates. |
| Solid-State Electrolyte Pilot Line Investment | German automotive OEMs anchor manufacturing scale despite ceramic yield challenges and qualification timelines. |
| Technology Licensing to Grid Operators | Indian CEA mandates and PLI incentives create royalty revenue streams without capital-intensive domestic manufacturing. |
| Quantum-Enabled Catalyst Discovery Platform | Silicon Valley computational materials science compresses oxygen reduction kinetics optimization timelines for cathode architectures. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive OEM platform engineers, utility procurement officers at California and German independent system operators, electrochemistry R&D directors at metal-air developers, and marine propulsion system integrators. Secondary validation drew from MIIT GB standard filings, EPA stationary storage safety guidance, EU Battery Regulation delegated act drafts, and customs trade data for aluminum anode feedstock flows. Bottom-up unit economics modeling triangulated against top-down addressable market sizing across technology platforms.
Across the analysis window, projections incorporated segment-level adoption curves for solid-state, alkaline, and hybrid architectures alongside application-specific deployment timelines spanning electric vehicle range extension, grid storage duration guarantees, and marine propulsion pilots. Segmentation dimensions modeled include technology platform, application category, end-user type, and form factor, with CAGRs derived from installed capacity buildout assumptions and unit cost decline trajectories. Industry-specific inputs encompassed cathode catalyst cost curves, anode replacement logistics maturation, and regulatory compliance deadline effects on procurement timing.
Underlying assumptions cover EU Battery Regulation enforcement consistency, aluminum price volatility bands, and solid-state manufacturing yield improvement trajectories, with deviation risk concentrated in China MIIT standard acceleration and ECHA REACH substance authorization delays. Recalibration cycles align with material shifts in utility procurement specification restructuring and automotive OEM powertrain validation program milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Utility Battery Market
Batteries
ASEAN Countries Electric Vehicle Battery Electrolyte Market
Batteries
Flow Battery Market
Batteries
Lithium-Based Battery Charger Market
Batteries
High Temperature NiMH Battery Market
Batteries
Europe Battery Market
Batteries
India Lead-Acid Battery Separator for SLI Applications Market
Batteries
Global Automotive Lead Acid Batteries Market
Batteries
West Africa Battery Market
Batteries
North Europe Battery Market
Batteries
Asia Pacific Electric Vehicle Battery Electrolyte Market
Batteries
Nickel Cadmium Battery Market
Batteries
Asia-Pacific Primary Battery Market
Batteries
Italy Rechargeable Battery Market
Batteries
Portable Battery Market
Batteries
China Rechargeable Battery Market