
 Global Varicose Veins Treatment Market | 2026-2036
Global Varicose Veins Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Varicose Veins Treatment Market Outlook
The buyer base for varicose veins treatment is broadening beyond hospital systems into ambulatory surgical centers and specialized vein clinics. Medtronic leverages its endovenous ablation portfolio to sustain leadership across outpatient settings. Boston Scientific Corporation anchors its position through radiofrequency systems that dominate clinic-based procedures. Alma Lasers competes with differentiated laser platforms targeting cosmetic applications in private practice environments.
Varicose veins treatment encompasses minimally invasive and non-invasive interventions designed to eliminate or collapse dysfunctional superficial veins, primarily through thermal energy delivery, chemical sclerosant injection, or mechanical extraction. Endovenous laser systems typically operate at wavelengths between 810 nm and 1470 nm to achieve targeted hemoglobin absorption and vessel wall contraction. Radiofrequency ablation and endovenous laser therapy together command the largest share of procedural volume due to established reimbursement and physician training infrastructure. Ultrasound-guided therapy represents the fastest-growing technology segment as real-time imaging improves precision and reduces complication rates in office-based settings.
FDA 510(k) clearances and CE marking under the EU MDR govern device safety and clinical performance requirements for laser and radiofrequency systems. The EPA regulates disposal protocols for sclerosant chemicals and medical waste generated during sclerotherapy procedures. Japan's PMDA maintains distinct approval pathways for thermal ablation devices that influence market entry timelines for international manufacturers. Stakeholders must monitor evolving MDR clinical evidence requirements and reimbursement parity between hospital and ambulatory settings.
Market Dynamics
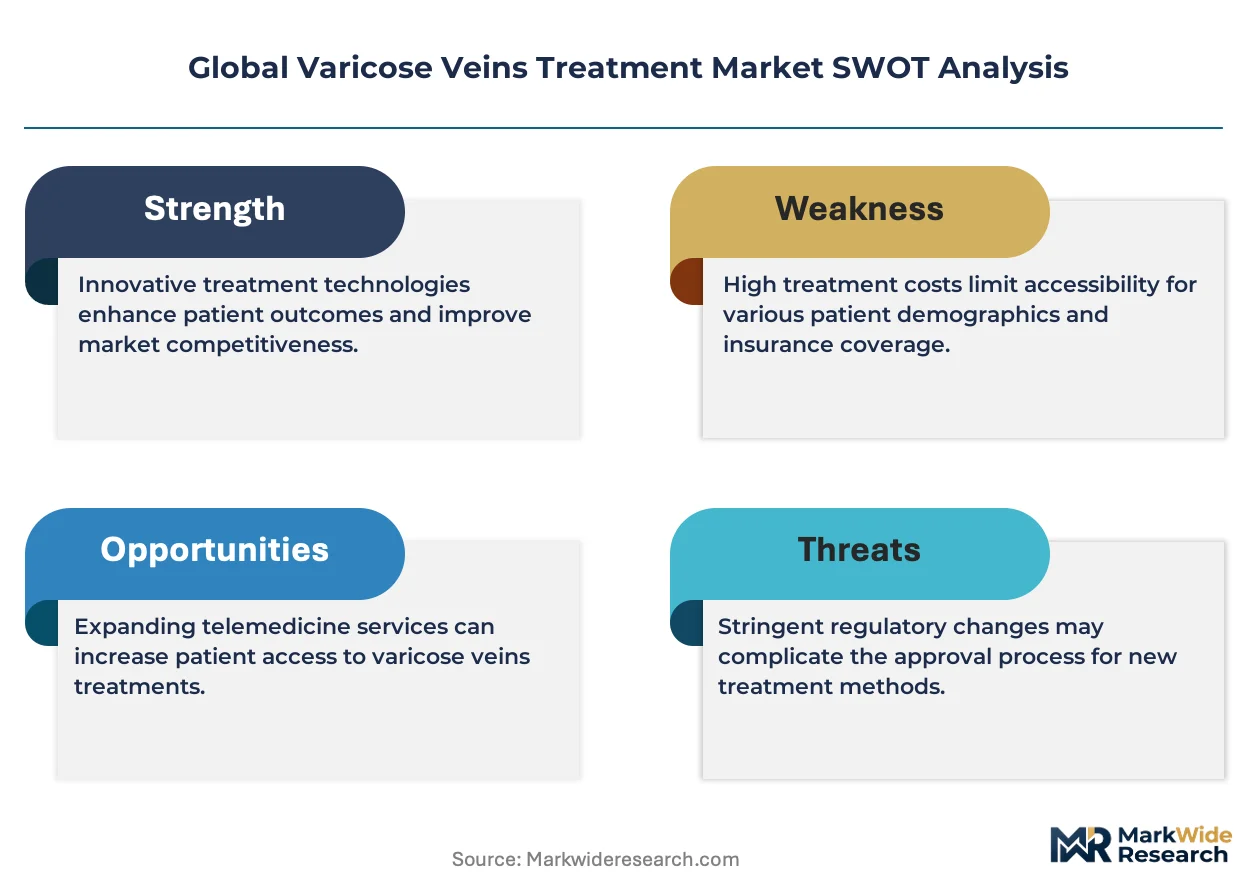
Ultrasound-guided therapy is decentralizing procedural delivery from hospital operating rooms into ambulatory surgical centers and specialized vein clinics, compressing facility fees and expanding physician autonomy in treatment settings.
Growth Catalysts
- EU MDR streamlining:CE marking pathways under the EU Medical Device Regulation are accelerating market access for endovenous laser systems across European member states.
- Ambulatory surgical center expansion:Outpatient facilities in the United States are broadening access to minimally invasive thermal ablation procedures.
- Radiofrequency ablation:This technology commands substantial procedural volume due to established reimbursement infrastructure and physician training programs.
Market Restraints
- Physician training bottlenecks:Specialized credentialing requirements for ultrasound-guided sclerotherapy limit the pool of qualified practitioners.
- Reimbursement parity gaps:Disparities between hospital and ambulatory setting payment rates create site-of-care arbitrage complications.
- Laser system capital intensity:High upfront equipment costs for 1470 nm endovenous platforms constrain clinic adoption in price-sensitive markets.
Strategic Opportunities
- Japan's PMDA pathway optimization:Distinct approval timelines for thermal ablation devices create first-mover advantages for prepared manufacturers.
- Cosmetic application expansion:Private practice environments are adopting differentiated laser platforms for aesthetic vein treatments beyond medical necessity.
- Real-time imaging convergence:Integration of ultrasound visualization with thermal delivery systems is improving precision in office-based settings.
Industry Challenges
- MDR clinical evidence requirements:Evolving EU demands for post-market surveillance data are extending certification timelines.
- Waste disposal compliance:EPA protocols for sclerosant chemical handling add operational complexity to sclerotherapy procedures.
- Legacy system integration:Older radiofrequency platforms require firmware updates to meet current cybersecurity standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Varicose Veins Treatment Market |
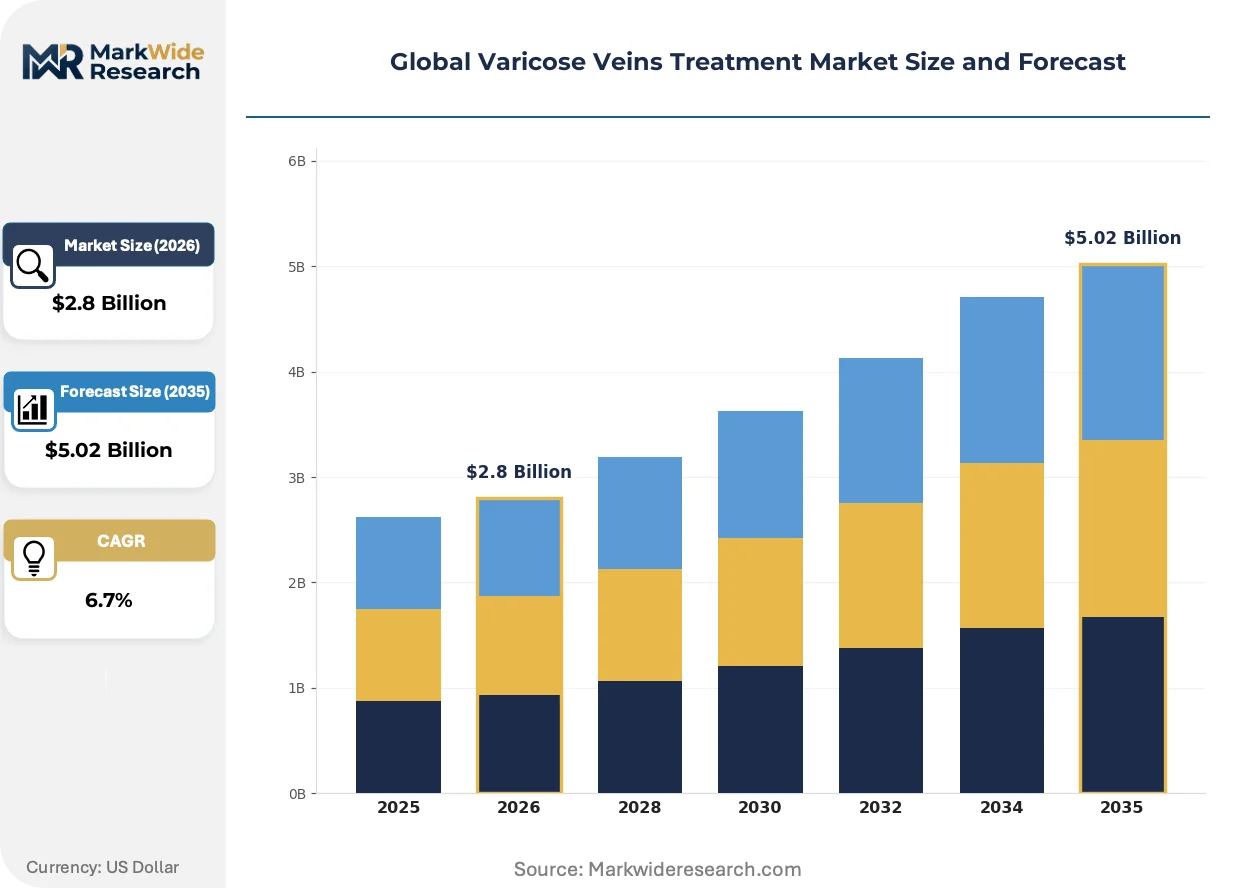
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Therapy, Sclerotherapy, Ambulatory Phlebectomy, Radiofrequency Ablation End User: Hospitals, Clinics, Home Care Settings, Ambulatory Surgical Centers Technology: Endovenous Laser, Cryotherapy, Ultrasound-Guided Therapy, Thermal Ablation Application: Cosmetic Procedure, Medical Intervention, Preventive Treatment, Pain Management |
| Companies Covered | Medtronic, AngioDynamics, Boston Scientific Corporation, Biolitec AG, Lumenis, Merit Medical Systems, Alma Lasers, Teleflex Incorporated, Quanta System, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Varicose Veins Treatment Market Strategic Shifts
Technology convergence between imaging modalities and energy delivery systems is compressing treatment complexity while expanding the treatable patient population beyond traditional surgical candidates.
Non-thermal mechanochemical ablation is decentralizing varicose veins treatment from specialized surgical centers into primary care and general dermatology practices. Family medicine physicians without vascular surgery credentials are adopting these catheter-based systems at accelerating rates. This shift is decentralizing referral patterns and compressing the traditional specialist gatekeeper role in vein care.
Japan's PMDA has tightened clinical evidence requirements for thermal ablation device approvals, extending review timelines for international manufacturers. This regulatory friction is favoring domestic Japanese device makers with established quality management systems. Manufacturers are responding by establishing local clinical trial infrastructure and partnering with Japanese teaching hospitals for pre-market data generation.
Patient self-referral to specialized vein clinics is displacing traditional primary-care-to-specialist referral pathways in the United States. Direct-to-consumer marketing and online appointment scheduling are compressing the initial consultation-to-treatment interval. This behavioral shift is most visible in Sun Belt metropolitan areas where cosmetic concerns drive higher treatment-seeking rates.
Global Varicose Veins Treatment Market Segmentation
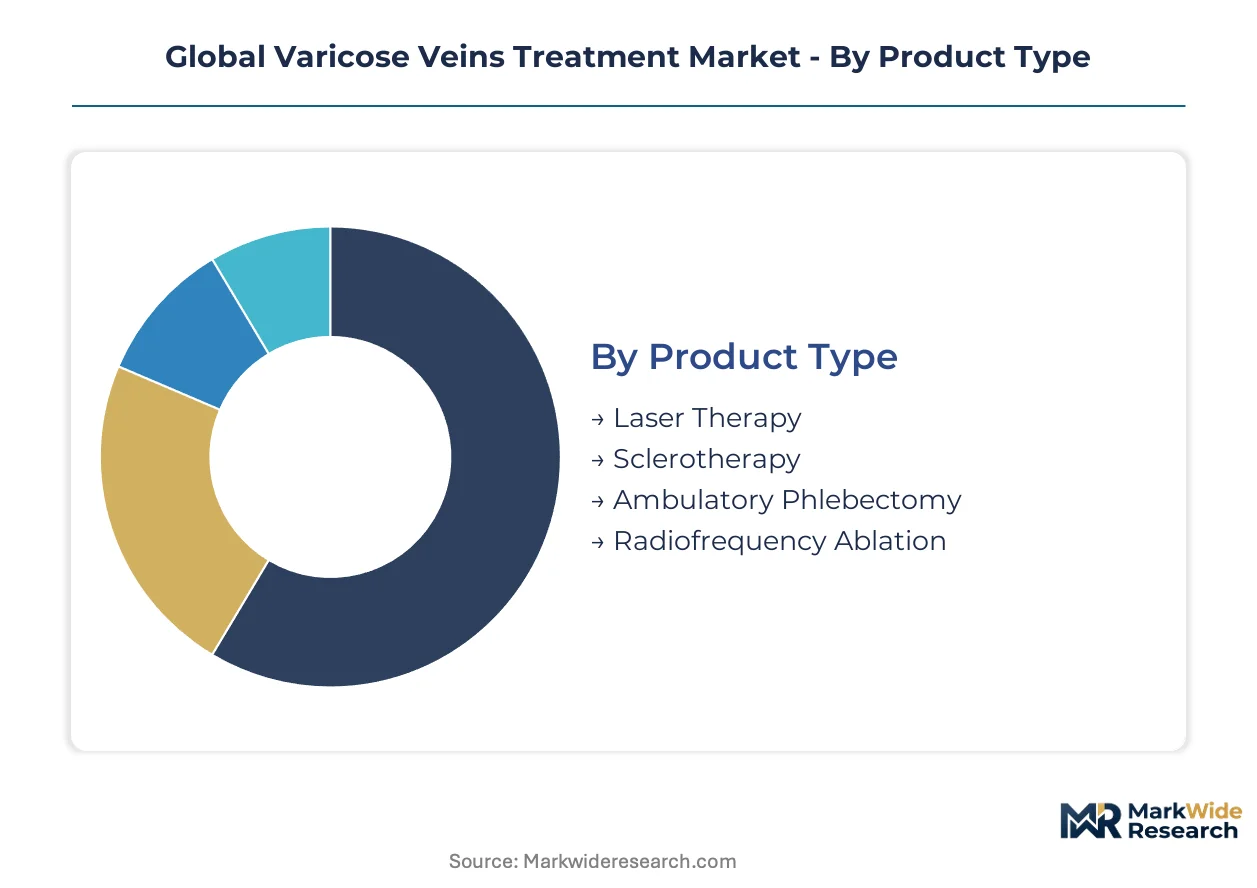
Varicose veins treatment markets fragment across four critical dimensions: energy delivery modality, care delivery setting, imaging integration level, and clinical indication severity. These segment boundaries determine reimbursement pathways, capital requirements, and competitive intensity for device manufacturers.
Product Type:
Standalone thermal systems dominate capital equipment budgets while injection-based therapies operate through disposable supply chains.
- Radiofrequency Ablation:Catheter-based systems deliver controlled thermal energy through bipolar electrodes at 120°C, achieving vessel wall contraction with minimal perivenous heating. Demand concentrates in United States ambulatory surgical centers where established Category III CPT codes secure favorable reimbursement rates.
- Laser Therapy:Endovenous platforms operate across 810-1470 nm wavelengths with bare-tip or radial-emitting fiber designs. Germany's statutory health insurance funds drive procedural volume through comprehensive coverage of symptomatic venous insufficiency.
- Sclerotherapy:Liquid and foam sclerosant injections collapse target vessels through endothelial chemical injury. Japan's PMDA maintains distinct approval categories for detergent-based versus osmotic agents.
- Ambulatory Phlebectomy:Hook-assisted micro-extraction of superficial varicosities through stab incisions. Italian public hospitals favor this technique for large-caliber tributary veins.
Radiofrequency ablation leads volumes today; laser therapy is gaining share fastest.
End User:
Site-of-care migration from inpatient facilities to outpatient environments restructures procurement authority and capital deployment timelines.
- Ambulatory Surgical Centers:Freestanding facilities perform thermal ablation under local anesthesia with same-day discharge protocols. United States Medicare's ASC payment rates for vein procedures expanded 12% between 2019-2024.
- Clinics:Specialized vein clinics integrate diagnostic ultrasound with treatment delivery in single-visit models. Australian private practice networks concentrate cosmetic sclerotherapy volume in Sydney and Melbourne metropolitan corridors.
- Hospitals:Academic medical centers retain complex cases requiring combined phlebectomy and perforator ligation. French public hospital groups (AP-HP) centralize advanced interventions.
- Home Care Settings:Compression therapy and post-procedural monitoring shift to residential environments. United Kingdom NHS community nursing services manage leg ulcer prevention programs.
Ambulatory surgical centers lead volumes today; specialized clinics are expanding most quickly.
Technology:
Imaging modality integration determines precision thresholds and operator training requirements across energy delivery platforms.
- Ultrasound-Guided Therapy:Real-time B-mode visualization enables targeted cannulation and treatment monitoring. South Korean dermatology practices adopt compact portable systems for office-based deployment.
- Endovenous Laser:Fiber-delivered thermal energy achieves consistent vein closure rates. Brazilian private insurers expanded coverage for 1470 nm wavelength systems.
- Thermal Ablation:Radiofrequency and laser systems collectively command procedural volume through established safety profiles. Spanish public health system tenders prioritize dual-modality platform compatibility.
- Cryotherapy:Nitrous oxide-based cooling systems target spider veins and telangiectasias. Canadian aesthetic medicine clinics drive demand for non-thermal cosmetic options.
Thermal ablation leads volumes today; ultrasound-guided therapy is climbing the fastest.
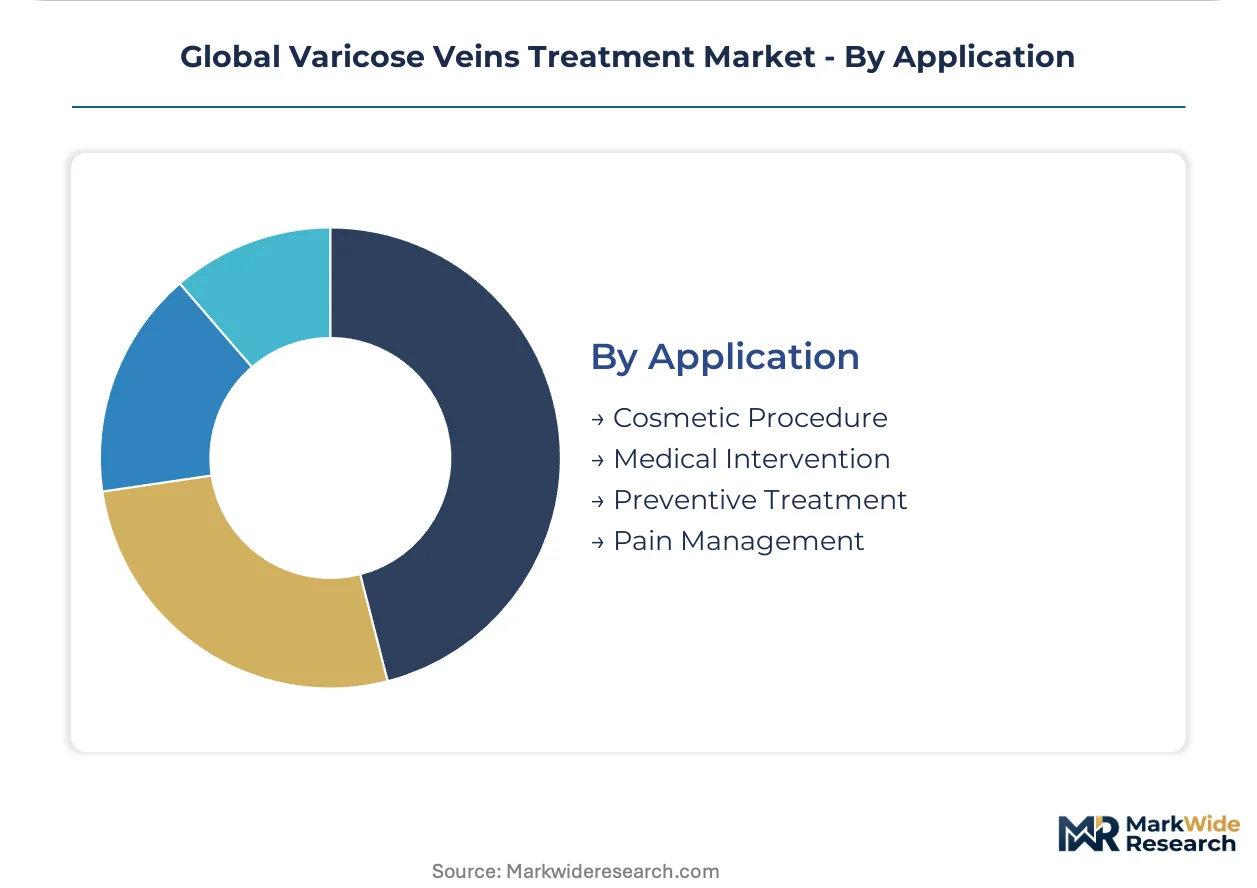
Application:
Clinical indication severity separates reimbursed medical necessity from discretionary aesthetic expenditure.
- Medical Intervention:Treatment of symptomatic chronic venous insufficiency with documented reflux. German sickness funds require duplex ultrasound confirmation for prior authorization.
- Cosmetic Procedure:Aesthetic improvement of visible varicosities without functional impairment. United States self-pay patients in Florida and Arizona drive seasonal demand cycles.
- Pain Management:Alleviation of venous hypertension-related discomfort and heaviness. United Kingdom NICE guidelines prioritize compression therapy as first-line intervention.
- Preventive Treatment:Early intervention to arrest disease progression and ulcer risk. Japanese occupational health programs screen standing workers for venous insufficiency.
Medical intervention leads volumes today; cosmetic procedures are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized vascular surgeons and interventional radiologists concentrate in metropolitan medical corridors across Germany, the United States, Japan, the United Kingdom, and Australia. These talent clusters anchor procedural volume and drive technology adoption patterns in varicose veins treatment.
United States
Patient self-referral to specialized vein clinics is displacing traditional primary-care-to-specialist pathways in Sun Belt metropolitan areas. FDA 510(k) clearances govern endovenous laser system approvals with streamlined pathways for predicate devices. Florida and Arizona markets exhibit compressed consultation-to-treatment intervals driven by cosmetic demand cycles.
Germany
German sickness funds require duplex ultrasound confirmation for prior authorization of symptomatic venous insufficiency interventions. CE marking under EU MDR governs device safety requirements with accelerating pathways for endovenous laser systems. Statutory health insurance funds in Bavaria and North Rhine-Westphalia drive procedural volume through comprehensive coverage mandates.
Japan
PMDA maintains distinct approval pathways for thermal ablation devices that extend review timelines for international manufacturers. Japanese teaching hospitals in Tokyo and Osaka anchor pre-market clinical trial infrastructure for domestic device makers. Occupational health programs screen standing workers for venous insufficiency in manufacturing corridors surrounding Nagoya.
United Kingdom
NICE guidelines prioritize compression therapy as first-line intervention for venous hypertension-related discomfort. NHS community nursing services manage leg ulcer prevention programs across England's former industrial regions. London-based private practice networks concentrate cosmetic sclerotherapy volume in Harley Street medical clusters.
Australia
Private practice networks concentrate cosmetic sclerotherapy volume in Sydney and Melbourne metropolitan corridors. The country's national therapeutic goods regulator oversees device safety requirements for laser and radiofrequency systems. Compact portable ultrasound systems enable office-based deployment in Queensland dermatology practices.
Global Varicose Veins Treatment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the varicose veins treatment landscape. The vendor base stratifies into three tiers: multinational medical device conglomerates with diversified surgical portfolios, mid-cap laser technology specialists with concentrated energy platform expertise, and regional distributors with localized service capabilities. Dominant competitive moves include technology licensing agreements for wavelength optimization and strategic partnerships with ambulatory surgical center networks.
Among diversified medical technology conglomerates, Medtronic and Boston Scientific Corporation exemplify scale-driven archetypes with broad surgical portfolio integration. Alma Lasers occupies a position within the laser technology specialist tier, representing focused energy platform development. These three companies anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Medtronic |
| AngioDynamics |
| Boston Scientific Corporation |
| Biolitec AG |
| Lumenis |
| Merit Medical Systems |
| Alma Lasers |
| Teleflex Incorporated |
| Quanta System |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up vein clinic networks in the United States and Germany anchor procurement concentration, compressing vendor margins through multi-site purchasing agreements while sustaining premium pricing for cosmetic applications through direct-to-consumer channels.
Pricing Analysis
Bundled service packages encompassing diagnostic ultrasound, thermal ablation, and post-procedural compression dominate United States ambulatory surgical centers, while unbundled component pricing persists in German statutory health insurance reimbursement frameworks. Three-tier pricing structure across premium laser platforms, standard radiofrequency systems, and economy sclerotherapy consumables differentiates vendor positioning. Pricing pressure stems from Medicare ASC reimbursement compression and site-of-care arbitrage between hospital and outpatient settings. Price-sensitive independent vein clinics in price-conscious markets resist capital-intensive 1470 nm laser platform upgrades.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan maintain hub-and-spoke patterns for thermal ablation catheter inventory, with consolidated warehousing in Minneapolis, Munich, and Osaka feeding last-mile delivery to ambulatory surgical centers. Laser fiber manufacturing draws from Japanese precision optics suppliers and German glass-drawing specialists. Single-source vulnerability concentrates in 1470 nm diode laser chip fabrication. Distribution runs through manufacturer-direct sales forces for capital equipment and third-party medical distributors for disposable consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The varicose veins treatment market functions as a stable compounder anchored by demographic aging and rising symptomatic disease recognition across developed economies.
For Market Incumbents: Cement leadership through exclusive ambulatory surgical center purchasing agreements that lock out competing radiofrequency platforms, while investing in ultrasound-guided therapy certification programs to deepen physician loyalty against mechanochemical ablation substitutes. Vertical integration into laser fiber manufacturing reduces exposure to Japanese optics supplier concentration. For New Entrants and Emerging Players: General dermatology practices without vascular surgery credentials represent the most penetrable buyer archetype for non-thermal mechanochemical ablation systems, bypassing traditional specialist gatekeepers. Target Australian and South Korean metropolitan corridors where compact portable ultrasound adoption enables office-based deployment without hospital affiliation. Pursue direct-to-clinic digital marketing bypassing traditional distributor markups. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap laser technology specialists with concentrated energy platform expertise relative to diversified medical device conglomerates. Five-to-ten-year viability hinges on reimbursement parity maintenance between thermal and non-thermal modalities. Watch FDA 510(k) clearance velocity for mechanochemical devices as the inflection signal indicating specialist displacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR streamlining accelerates endovenous laser system market access across German and French member states. |
| Hospital System Partnership | Exclusive purchasing agreements with United States ASC networks lock out competing radiofrequency platform vendors. |
| Software Companion Development | Real-time ultrasound integration modules improve cannulation precision for office-based thermal delivery systems. |
| Reimbursement Strategy | Category III CPT code maintenance secures favorable Medicare payment rates for ambulatory thermal ablation procedures. |
| Geographic Expansion | Japanese PMDA clinical trial infrastructure establishes first-mover positioning in Tokyo and Osaka metropolitan markets. |
Study Parameters
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with vascular surgeons, ambulatory surgical center administrators, biomedical engineers, and GPO contracts managers alongside secondary validation through FDA 510(k) filings, CE marking databases under EU MDR, hospital procurement records, and CMS Medicare payment data. Bottom-up procedure volume estimates triangulate against top-down device manufacturer revenue attribution across energy delivery modalities.
Granularity-level modeling captures product type segmentation at the wavelength and electrode configuration level, end user segmentation at the site-of-care tier, technology segmentation at the imaging integration depth, and application segmentation at the medical necessity versus cosmetic expenditure boundary. CAGRs derive from procedure volume growth trajectories adjusted for reimbursement elasticity and technology substitution patterns across the projection horizon. Forecast inputs incorporate PMDA approval timeline assumptions for thermal ablation devices and EU MDR clinical evidence requirement evolution.
Underlying measurement precision varies by segment; thermal ablation procedural volume carries tighter precision than emerging mechanochemical adoption curves due to established reimbursement reporting infrastructure. Forecasts reflect documented assumptions regarding site-of-care migration velocity and regulatory pathway efficiency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
Intravenous Catheters Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Global Vascular Embolization Market
Cardiovascular Devices
Intravascular Ultrasound Market
Cardiovascular Devices
Global 3D Vascular Ultrasound Imaging Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Cardiogenic Shock Treatment Market
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
Percutaneous Coronary Intervention Guidance Devices Market
Cardiovascular Devices
MRI-Guided Cardiac Ablation Market
Cardiovascular Devices
Arterial Cannula Market