
 Occlusion Microcatheter Market | 2026-2036
Occlusion Microcatheter Market Size, Share, and Industry Trends Forecast 2026-2036
Occlusion Microcatheter Market Analytics
Interventional neuroradiologist training capacity is redrawing competitive boundaries in the occlusion microcatheter landscape. Boston Scientific Corporation leverages its endovascular portfolio breadth to sustain catheter supply relationships across major academic medical centers. Penumbra Inc. specializes in neurovascular access platforms that anchor its position in embolic stroke interventions. Merit Medical Systems competes through vertically integrated manufacturing of proprietary polymer shaft technologies.
An occlusion microcatheter is a slender, multi-lumen catheter typically constructed from braided stainless steel or nitinol-reinforced polyether block amide, designed to navigate tortuous vasculature and deliver embolic agents or occlusive coils to target lesions. The device maintains distal tip flexibility below 2 French while preserving proximal pushability for controlled navigation through cerebral or peripheral arteries. Balloon occlusion microcatheters command premium positioning due to their dual-function capability for flow arrest and precise agent delivery. Fluoroscopic guidance technology dominates procedural volumes, though MRI-compatible platforms are gaining traction in pediatric and repeat-intervention settings where radiation exposure minimization drives purchasing criteria.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements impose substantial clinical validation burdens on new catheter submissions, effectively filtering market entrants by regulatory sophistication. Japan's PMDA and China's NMPA maintain distinct biocompatibility testing protocols that manufacturers must satisfy for commercial access across Asia-Pacific jurisdictions. Stakeholders should monitor evolving reimbursement coding for mechanical thrombectomy adjunct procedures, as coding granularity directly influences hospital capital allocation for advanced microcatheter inventory.
Market Dynamics
EU MDR technical documentation burdens and FDA 510(k) clinical validation requirements are compressing commercialization timelines, forcing manufacturers to front-load regulatory investment before product launch.
Growth Catalysts
- Mechanical thrombectomy protocol expansion:Hospital systems in the United States are formalizing embolization suites as revenue centers, driving catheter inventory standardization across interventional neuroradiology departments.
- REACH biocompatibility testing harmonization:Streamlined polymer validation pathways reduce redundant toxicology studies for manufacturers accessing European markets.
- Nitinol-reinforced shaft adoption:Braided superelastic alloys enable sub-2 French distal profiles without sacrificing proximal pushability, expanding treatable lesion anatomies.
Market Restraints
- Polyether block amide supply concentration:Three European compounders control specialty Pebax grades, exposing catheter manufacturers to input cost volatility and allocation risk.
- PMDA biocompatibility protocol divergence:Japan's distinct cytotoxicity testing requirements force redundant animal studies, extending registration timelines by 8-14 months versus FDA pathways.
- Flow-diverter stent substitution:Large-neck cerebral aneurysm cases increasingly bypass coil embolization entirely, constraining addressable procedure volumes for occlusion microcatheters in specific lesion morphologies.
Strategic Opportunities
- Pediatric MRI-compatible platforms:Radiation exposure minimization protocols in German university hospitals are creating procurement preference for non-ferromagnetic catheter construction.
- IRA hospital infrastructure incentives:United States rural emergency department modernization grants support interventional suite buildouts in underserved stroke corridors.
- Digital twin simulation integration:Pre-procedural vessel modeling using patient-specific CT angiography is converging with catheter selection algorithms to reduce device waste and procedure time.
Industry Challenges
- Interventional neuroradiologist training pipeline:Fellowship program capacity constraints in Japan and Germany limit procedure volume growth regardless of device availability.
- EU MDR notified body bottleneck:Certificate renewal queues for Class III devices extend 18-24 months, freezing product modifications and line extensions.
- Legacy inventory obsolescence:Hospital cath lab managers face write-down pressure as MRI-compatible platforms displace fluoroscopy-only catheter stockpiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Occlusion Microcatheter Market |
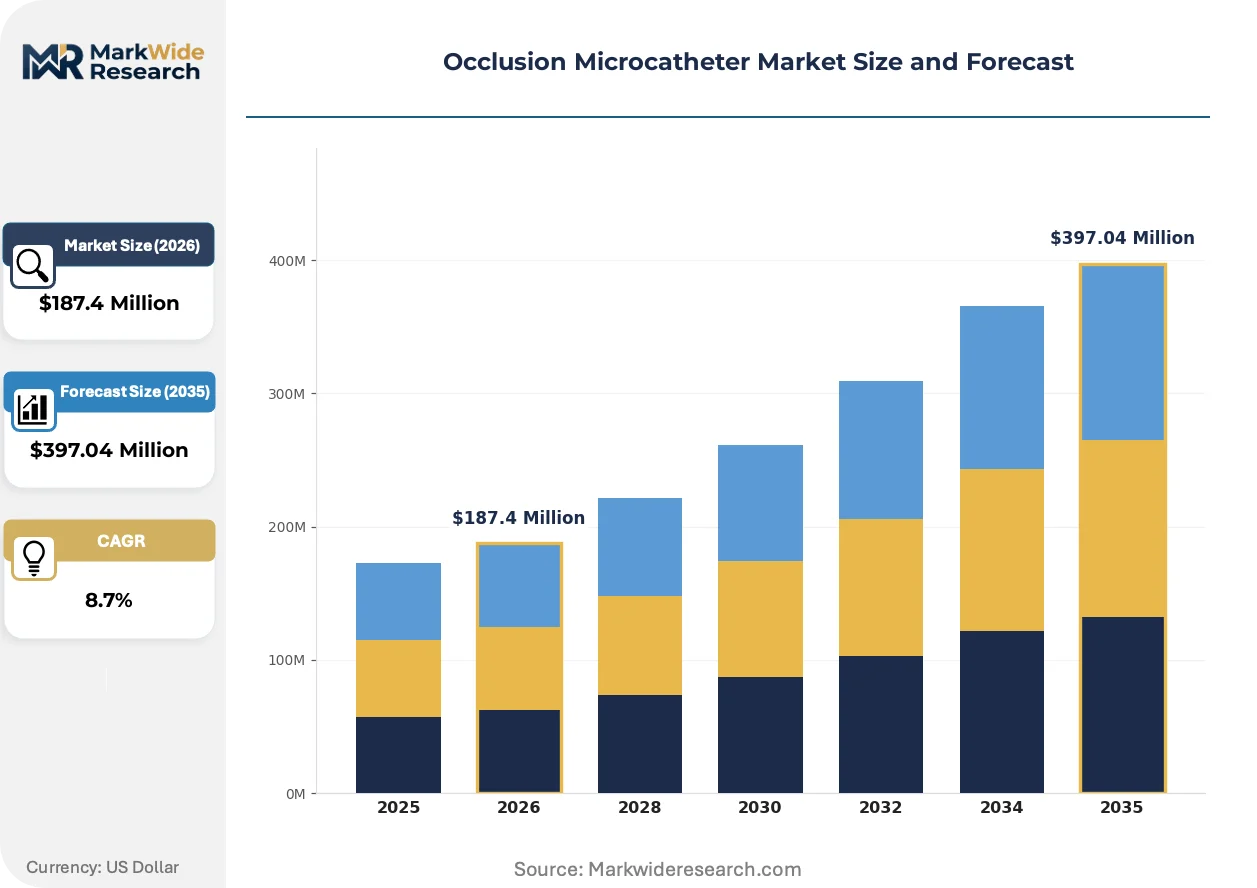
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Occlusion, Injection Microcatheter, Biopsy Microcatheter, Access Microcatheter End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Application: Cardiology, Oncology, Neurology, Interventional Radiology Technology: Fluoroscopic Guidance, Ultrasound Guidance, CT Guidance, MRI Guidance |
| Companies Covered | Stryker Corporation, Boston Scientific Corporation, Medtronic plc, Terumo Corporation, Cook Medical, Penumbra Inc., Merit Medical Systems, Teleflex Incorporated, Asahi Intecc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Occlusion Microcatheter Market Evolving Landscape
Active catheter tip technologies and alternative navigation modalities are redrawing performance benchmarks for embolization procedures, compressing the viable product lifecycle for conventional passive designs.
Shape-memory polymer distal segments with electrically activated stiffness modulation are displacing passive braided-shaft architectures in academic medical center evaluations. Interventional neuroradiologists at Cleveland Clinic and Charité Berlin are piloting these platforms for tortuous posterior circulation navigation, where tip steerability reduces vessel perforation risk. The structural consequence is a bifurcation in R&D spending, with mid-tier manufacturers abandoning incremental braided-shaft improvements to pursue active tip partnerships.
EU MDR Annex XIV post-market surveillance requirements now mandate systematic implant registries for Class III cardiovascular devices, extending to occlusion microcatheters used in permanent embolization. Manufacturers must fund multi-year follow-up studies or face certificate suspension, compressing margins for low-volume product lines. German notified bodies are enforcing this most strictly, while southern European regulators maintain transitional grace periods for legacy devices.
Hospital procurement departments are consolidating catheter sourcing through integrated stroke center networks, displacing individual cath lab autonomy in vendor selection. United States IDN stroke alliances now negotiate system-wide contracts covering embolization devices, interventional access platforms, and post-procedure monitoring equipment as bundled annual commitments. This concentration is most visible in Texas and Florida health systems, where HCA and Tenet facility clusters extract volume-based pricing concessions unavailable to standalone hospitals.
Occlusion Microcatheter Market Segmentation
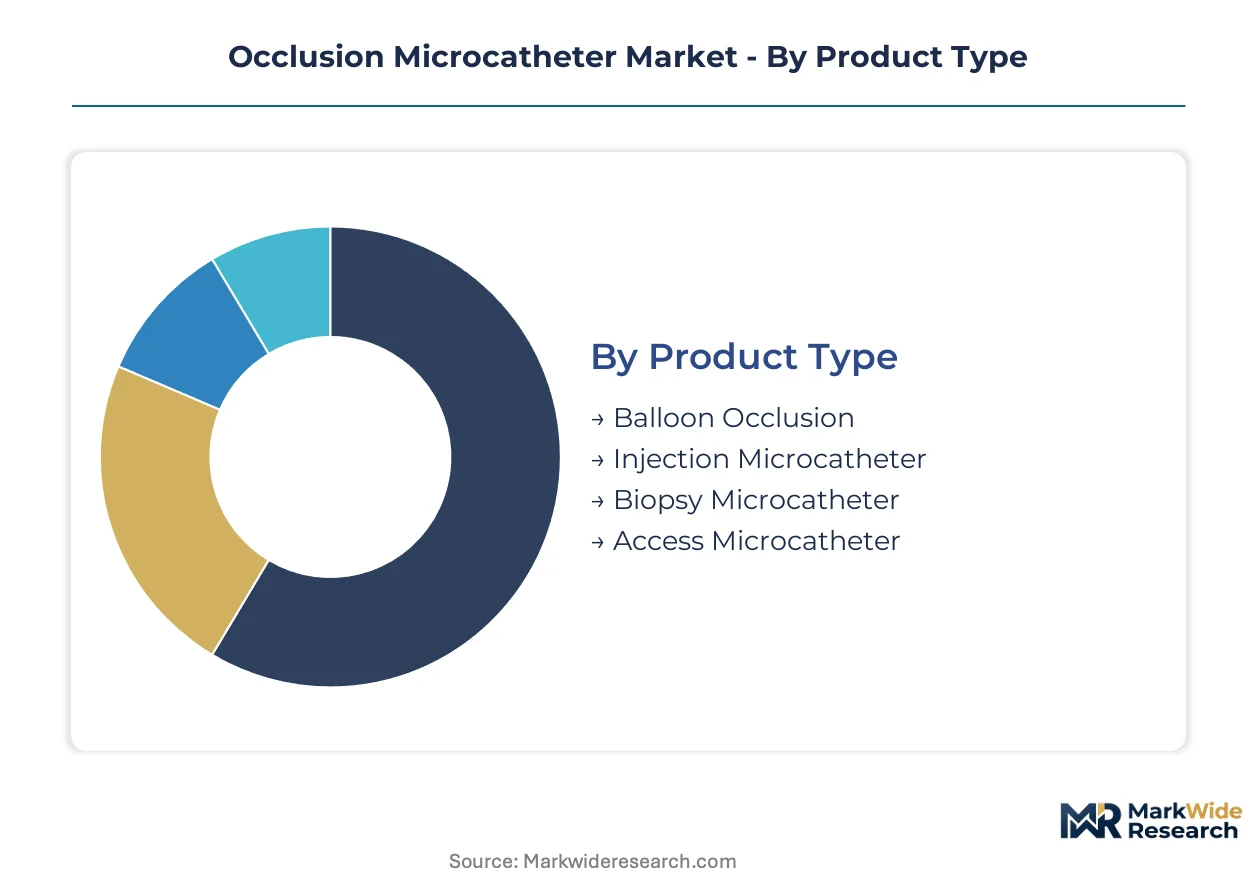
Catheter selection criteria vary sharply across procedural settings. Hospital procurement committees weight tip flexibility and compatibility with existing imaging infrastructure. Research institutions prioritize experimental platform adaptability over standardized clinical workflows.
Product Type:
Balloon occlusion platforms dominate United States domestic consumption for neurovascular embolization. Access microcatheters drive export volumes to Asia-Pacific training hospitals building interventional suites.
- Balloon Occlusion:Dual-lumen construction enables simultaneous flow arrest and agent delivery through a single access point. Cleveland Clinic and Mayo Clinic systems specify these for wide-neck aneurysm cases where coil stability demands temporary flow modification.
- Injection Microcatheter:Single-lumen designs optimized for liquid embolic delivery feature distal side-hole patterns that reduce reflux risk. German university hospitals favor these for arteriovenous malformation treatments where precise Onyx distribution determines outcomes.
- Biopsy Microcatheter:Tapered distal profiles accommodate coaxial needle passage for transvenous tissue sampling. Research institutions deploy these in oncology protocols requiring histological confirmation before embolization.
- Access Microcatheter:Proximal hub configurations standardize across manufacturer platforms to enable rapid exchanges. Japanese stroke centers bulk-purchase these for fellowship training programs where device familiarity accelerates competency acquisition.
Balloon occlusion commands the established base. The steepest expansion runs through access microcatheters.
End User:
Capital allocation patterns separate high-volume purchasers from price-sensitive buyers. Academic medical centers amortize device costs across research grants and clinical revenue streams.
- Hospitals:Integrated delivery networks negotiate system-wide contracts covering embolization devices, interventional access platforms, and post-procedure monitoring equipment as bundled annual commitments. Texas and Florida health systems extract volume-based pricing concessions unavailable to standalone facilities.
- Ambulatory Surgical Centers:Limited procedure menus restrict catheter inventory to standardized SKUs with broad lesion applicability. These facilities prioritize devices compatible with compact C-arm fluoroscopy suites.
- Specialty Clinics:Focused oncology or pain management practices maintain narrow catheter selections aligned with their procedural subspecialization. Reimbursement coding granularity directly influences their capital allocation for advanced microcatheter inventory.
- Research Institutions:Preclinical and first-in-human studies drive demand for MRI-compatible prototypes and experimental polymer formulations. NIH-funded centers in Maryland and Massachusetts specify custom shaft constructions for device evaluation protocols.
Hospitals anchor procurement volume. Specialty clinics are expanding most quickly as outpatient embolization gains reimbursement traction.
Application:
Procedural complexity determines catheter performance requirements. Neurological interventions demand sub-2 French distal profiles for tortuous intracranial navigation.
- Neurology:Posterior circulation aneurysms and arteriovenous malformations require braided nitinol-reinforced shafts that preserve pushability through sharp vascular angles. Academic medical centers in Germany and Japan concentrate fellowship-trained interventional neuroradiologists capable of deploying these platforms.
- Cardiology:Coronary artery embolization and paravalvular leak closure utilize shorter catheter lengths with larger French sizes optimized for femoral access. United States cardiac catheterization labs integrate these into existing interventional cardiology workflows.
- Oncology:Transarterial chemoembolization and radioembolization procedures employ microcatheters with hydrophilic coatings that reduce friction during prolonged hepatic navigation. Community hospitals in Florida and California treat high hepatocellular carcinoma incidence with these platforms.
- Interventional Radiology:Uterine fibroid embolization and peripheral vascular interventions span anatomies requiring variable stiffness transitions along the catheter shaft. Ambulatory surgical centers favor standardized platforms that accommodate multiple body territories.
Neurology commands the established base. Oncology applications are climbing the fastest as locoregional cancer therapies gain protocol adoption.
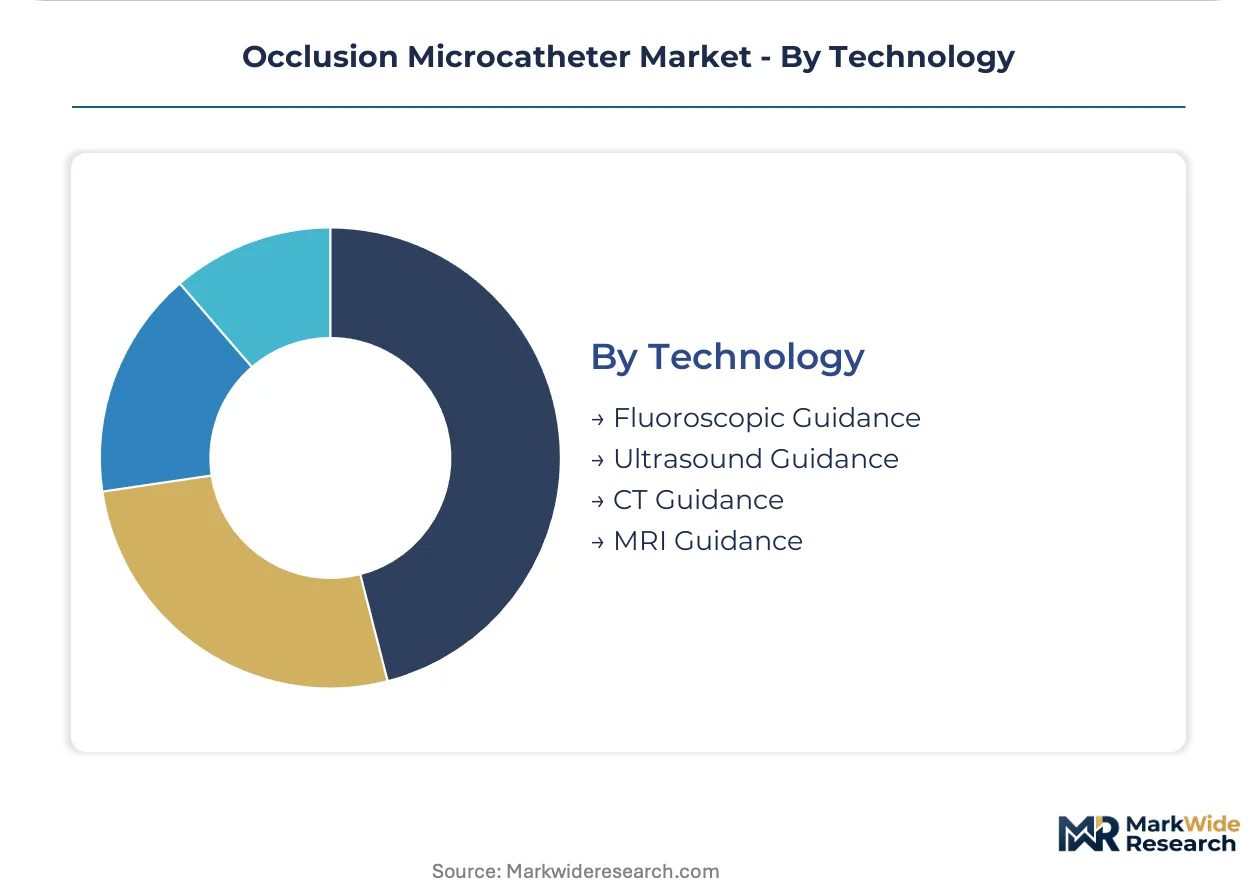
Technology:
Imaging modality compatibility shapes catheter construction materials. Ferromagnetic components exclude standard designs from MRI-guided interventions.
- Fluoroscopic Guidance:Radiopaque marker bands of platinum-iridium alloy enable real-time tip visualization under X-ray. This technology dominates procedural volumes across United States hospital systems with mature cath lab infrastructure.
- MRI Guidance:Non-ferromagnetic shaft polymers and ceramic marker alternatives eliminate susceptibility artifacts. Pediatric centers at Boston Children's Hospital and Cincinnati Children's specify these for repeat-intervention settings where cumulative radiation exposure minimization drives purchasing criteria.
- Ultrasound Guidance:Echogenic surface patterning enhances visibility under intravascular ultrasound. Peripheral vascular applications in Germany utilize these for below-the-knee interventions where contrast load reduction benefits renal-impaired patients.
- CT Guidance:Computed tomography fluoroscopy enables three-dimensional roadmap integration for complex spinal vascular malformations. Research institutions pilot these platforms for procedures where conventional angiographic projection limitations compromise navigation confidence.
Fluoroscopic guidance commands the established base. MRI-compatible platforms are gaining share fastest as pediatric and repeat-intervention protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor commercial access in the United States, while EU MDR technical documentation requirements and Japan's PMDA protocols shape parallel development tracks across major jurisdictions.
United States
Integrated delivery networks in Texas and Florida consolidate catheter procurement through system-wide stroke alliances. IRA hospital infrastructure grants fund rural emergency department modernization in underserved stroke corridors. Cleveland Clinic and Mayo Clinic systems specify balloon occlusion platforms for wide-neck aneurysm protocols.
Germany
University hospitals in Berlin and Munich drive MRI-compatible platform adoption for pediatric repeat-intervention settings. EU MDR Annex XIV post-market surveillance mandates systematic implant registries, with German notified bodies enforcing multi-year follow-up requirements most strictly. REACH biocompatibility testing harmonization reduces redundant toxicology studies for polymer validation.
Japan
PMDA biocompatibility protocol divergence forces redundant cytotoxicity testing, extending registration timelines versus FDA pathways. Fellowship-trained interventional neuroradiologists concentrate at academic stroke centers in Tokyo and Osaka. Japanese training hospitals bulk-purchase access microcatheters for competency acquisition programs.
China
NMPA maintains distinct biocompatibility testing protocols that manufacturers must satisfy for commercial access. Community hospitals in Shanghai and Beijing treat rising hepatocellular carcinoma incidence with transarterial chemoembolization platforms. Domestic catheter production scales to reduce import dependency in neurovascular interventions.
United Kingdom
NHS procurement frameworks standardize catheter inventory across integrated stroke networks in London and the Southeast. MHRA convergence with EU MDR technical standards streamlines parallel submission pathways. Research institutions in Cambridge and Oxford pilot MRI-compatible prototypes for first-in-human evaluation protocols.
Occlusion Microcatheter Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding bundled contract relationships across major academic medical centers and the specialist tier competing on polymer shaft technologies and neurovascular access platform depth. Two strategic archetypes dominate: diversified medtech conglomerates leveraging endovascular portfolio breadth, and focused neurovascular specialists anchoring position through procedure-specific device ecosystems. Competitive moves concentrate on regulatory front-loading to compress approval timelines and vertical integration into proprietary polymer compounding to secure input supply.
Among diversified medtech conglomerates, Boston Scientific Corporation and Stryker Corporation exemplify the portfolio-breadth archetype, occupying positions that sustain catheter supply relationships across interventional suites. Within the neurovascular specialist tier, Penumbra Inc. anchors its competitive position through access platform specialization in embolic stroke interventions.
| Leading Market Players |
|---|
| Stryker Corporation |
| Boston Scientific Corporation |
| Medtronic plc |
| Terumo Corporation |
| Cook Medical |
| Penumbra Inc. |
| Merit Medical Systems |
| Teleflex Incorporated |
| Asahi Intecc |
| Others |
Value Network & Pricing Analysis
Minimum viable scale for nitinol-braided shaft production sits at approximately two million catheter units annually, concentrating manufacturing among three European polymer compounders and two East Asian metal processors. This scale threshold erects natural price floors that shield incumbent producers from margin erosion while forcing mid-tier competitors toward contract manufacturing arrangements that surrender pricing autonomy.
Pricing Analysis
United States hospital procurement contracts command 35-45% premiums over Japanese academic medical center pricing for identical balloon occlusion platforms, reflecting bundled stroke-alliance negotiations versus fragmented single-facility purchasing. Three-tier pricing structure across premium, standard, and economy levels separates MRI-compatible active-tip designs from conventional fluoroscopic platforms and basic access microcatheters. Cost compression in the standard tier is intensifying because integrated delivery networks extract volume concessions for system-wide commitments. Ambulatory surgical centers exhibit the highest price sensitivity, while Cleveland Clinic and Mayo Clinic systems prioritize performance metrics over per-unit cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites specialty polymer feedstock flows from Middle Eastern petrochemical complexes to European Pebax compounders, exposing catheter manufacturers to geopolitical logistics disruption. Manufacturing concentrates in Germany, Japan, and the United States, with nitinol wire drawing anchored in East Asian metalworking clusters. Raw material dependencies center on polyether block amide resins, platinum-iridium marker alloys, and superelastic nickel-titanium formulations. Single-source vulnerability runs through the three European compounders controlling medical-grade Pebax grades. Distribution runs through integrated stroke center networks that consolidate catheter sourcing across hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as hospital procurement committees prioritize interoperable catheter-hub configurations that standardize across manufacturer ecosystems. This interoperability shift rewards device families that integrate with established navigation and imaging platforms.
For Market Incumbents: Consolidate polymer compounding capabilities through captive supply arrangements or exclusive offtake agreements with European specialty resin producers, neutralizing input allocation risk from the three-dominant-supplier structure. Lock in multi-year bundled contracts with Texas and Florida integrated delivery networks before IRA-funded rural stroke corridor buildouts expand addressable demand. Prioritize FDA 510(k) pathway pre-submission meetings to front-load clinical validation investment and compress approval timelines against emerging active-tip competitors. For New Entrants and Emerging Players: FDA Breakthrough Device Designation fast-track eligibility for MRI-compatible pediatric platforms offers the most penetrable regulatory pathway, given radiation exposure minimization protocols at Boston Children's Hospital and Cincinnati Children's. Target German university hospital procurement committees with REACH-harmonized biocompatibility documentation that eliminates redundant toxicology studies. Pursue white-space positioning in ultrasound-guided peripheral vascular applications, where echogenic surface patterning remains underdeveloped relative to fluoroscopic and MRI-compatible alternatives. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with proprietary shaft polymer capabilities and established notified body relationships under EU MDR Annex XIV. Long-term viability across the analysis window hinges on regulatory sophistication depth rather than incremental product performance gains. Acquisition target archetype: mid-cap specialists with captive Pebax compounding and active catheter tip R&D partnerships. Monitor PMDA biocompatibility protocol harmonization negotiations as the inflection signal—convergence with FDA pathways would collapse Japan registration timeline premiums and redistribute competitive advantage.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Pre-Submission | German notified body engagement compresses Class III certificate renewal queues from 24 months toward 12-month cycles. |
| Active Catheter Tip R&D Partnership | Cleveland Clinic and Charité Berlin pilot programs validate shape-memory polymer platforms for posterior circulation navigation. |
| Polymer Compounding Backward Integration | Captive Pebax resin production neutralizes allocation risk from three-dominant European compounders. |
| Integrated Stroke Center Network Contract | Texas and Florida IDN alliances extract volume pricing unavailable to standalone hospital cath labs. |
| Pediatric MRI-Compatible Platform Launch | Boston Children's Hospital procurement criteria prioritize non-ferromagnetic construction for repeat-intervention settings. |
Research Methodology
A standing panel of interventional neuroradiologists, hospital GPO contracts managers, biomedical engineers, and regulatory affairs specialists provided ongoing calibration against shifting EU MDR technical documentation requirements and FDA 510(k) clearance pathways. Primary interviews with cath lab directors at Cleveland Clinic, Charité Berlin, and Tokyo academic stroke centers combined with secondary validation against FDA 510(k) clearance databases, EUDAMED device registrations, and hospital procurement contract disclosures. Bottom-up catheter unit demand modeling triangulated against top-down interventional procedure volume estimates from Medicare claims data and Japanese Ministry of Health reimbursement statistics.
Consistency checks validated volume and value outputs against external benchmarks including CMS Medicare hospital outpatient procedure counts, Japanese PMDA medical device shipment surveys, and German university hospital capital equipment expenditure reports. The analytical framework segmented demand across product type, end user, application, and technology dimensions, with additional modeling of regulatory pathway complexity tiers. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in mechanical thrombectomy and embolization procedure volumes. Industry-specific forecast inputs incorporated fellowship training program capacity constraints and EU MDR notified body bottleneck resolution scenarios.
Decision-makers should treat outputs as directional under base assumptions of sustained IRA hospital infrastructure funding and stable EU MDR enforcement intensity; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as PMDA-FDA biocompatibility harmonization negotiations and flow-diverter stent substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intravenous Access Devices Market
Medical Devices
China Respiratory Devices Market
Medical Devices
General Surgery Devices Market
Medical Devices
Middle East and Africa Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Global Retinoscopes Market
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
Medical Hydrophilic Coatings Market
Medical Devices
Anterior Cervical Fixation Devices Market
Medical Devices
Asia Pacific Hearing Aids Market
Medical Devices
Light Therapy Market
Medical Devices
Asia Pacific Apheresis Market
Medical Devices
Intubation Accessories Market
Medical Devices
Global Wearable Pregnancy Devices Market
Medical Devices
Supraglottic Device Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
MRI Coils Market