
 North America Cardiac Assist Devices Market | 2026-2036
North America Cardiac Assist Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cardiac Assist Devices Market Analytics
Biocompatible polymer coatings are pivoting toward thromboresistant surfaces that reduce anticoagulant dependency and lower bleeding complications. Abbott Laboratories leverages its structural heart portfolio to integrate ventricular assist devices with catheter-based delivery platforms. Medtronic anchors North American distribution through established cardiac surgery sales channels. Getinge competes on perfusion technology adjacencies that complement its heart-lung machine installed base.
Cardiac assist devices comprise mechanical circulatory support systems that augment or replace native heart function through pneumatic, electric, or magnetic levitation drive mechanisms operating at blood flow rates of 5 to 10 liters per minute. These systems sustain patients with end-stage heart failure during recovery, as bridge-to-transplant, or as destination therapy when transplant is contraindicated. Ventricular assist devices occupy the largest revenue pool given their established reimbursement and expanding destination therapy indications, while total artificial heart applications remain concentrated in specialized cardiac centers with transplant capabilities. Emergency medical services represents the fastest-growing end user segment as pre-hospital cardiogenic shock protocols incorporate mechanical circulatory support earlier in care pathways.
The FDA maintains stringent premarket approval requirements under its breakthrough devices program, while Health Canada's medical device licensing framework governs cross-border commercialization. CMS national coverage determinations for ventricular assist devices directly shape hospital procurement decisions and patient access thresholds. Stakeholders must monitor evolving FDA guidance on durability testing standards as magnetic levitation and fully transcutaneous power technologies advance toward pivotal trials.
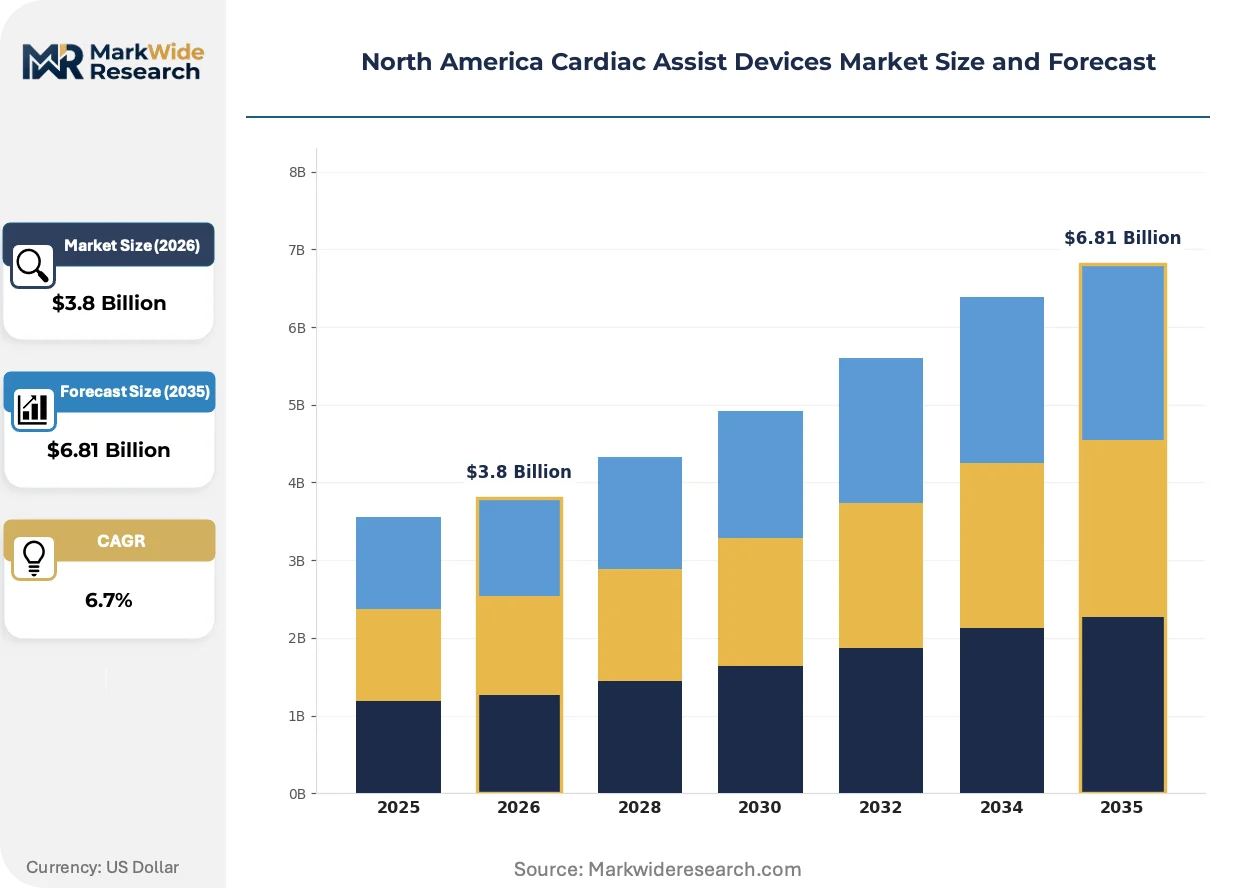
Market Dynamics
Magnetic levitation pump technology is compressing the competitive set by eliminating bearing wear as a failure mode, forcing incumbent axial-flow designs into defensive positioning around established reimbursement codes and surgeon familiarity.
Growth Catalysts
- Destination therapy expansion:CMS national coverage determinations now reimburse ventricular assist devices for patients ineligible for transplant, opening patient pools beyond bridge-to-transplant protocols at transplant centers across the United States.
- Pre-hospital cardiogenic shock protocols:Emergency medical services in the northeastern United States are deploying mechanical circulatory support earlier in care pathways, compressing time-to-implant and expanding addressable patient volume.
- FDA breakthrough device designation:The premarket approval pathway accelerates commercialization timelines for novel mechanical circulatory support technologies, reducing regulatory friction for magnetic levitation and transcutaneous power innovations.
Market Restraints
- Reimbursement concentration risk:CMS national coverage determinations directly shape hospital procurement decisions, creating single-point dependency on federal payment policy for patient access thresholds.
- Technical limitation in driveline infection:Percutaneous power cables remain the dominant infection vector, constraining long-term implant durability and destination therapy candidacy despite biocompatible polymer coating advances.
- Supply concentration in academic medical clusters:Transplant centers in Boston and New York maintain disproportionate implant volumes, leaving secondary markets with limited surgical expertise and program infrastructure.
Strategic Opportunities
- Underpenetrated southeastern United States:Florida and Texas transplant centers are expanding ventricular assist device programs with lower current implant density than northeastern academic clusters.
- Technology convergence of catheter-based delivery:Integration of ventricular assist devices with structural heart platforms enables less invasive implant procedures, expanding eligible patient populations beyond sternotomy candidates.
- Health Canada cross-border commercialization:Medical device licensing framework alignment allows United States manufacturers to access Canadian transplant centers with minimal regulatory duplication.
Industry Challenges
- Ventricular assist device coordinator workforce scarcity:Specialized nursing and perfusionist training programs cannot match program expansion pace, creating bottlenecks at emerging transplant centers.
- Durability testing standard evolution:FDA guidance on magnetic levitation and fully transcutaneous power technologies remains in draft form, forcing manufacturers to design against moving validation targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cardiac Assist Devices Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intra-aortic Balloon Pump, Ventricular Assist Device, Total Artificial Heart, Pulsatile Pump Technology: Mechanical Circulatory Support, BiVentricular Assist, Heart-Lung Machines, Retrograde Perfusion End User: Cardiac Centers, Hospitals, Home Care, Emergency Medical Services Application: Cardiac Surgery, Heart Failure Management, Transplant Support, Cardiogenic Shock |
| Companies Covered | LivaNova, Teleflex, Abiomed, Berlin Heart, Getinge, Abbott Laboratories, SynCardia Systems, Jarvik Heart, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cardiac Assist Devices Market Evolving Landscape
Thromboresistant surface engineering is eliminating anticoagulant dependency as a competitive differentiator, while regulatory pathways and procurement models compress simultaneously around value-based frameworks.
Magnetic levitation centrifugal pump technology eliminates mechanical bearings through electromagnetic suspension, reducing heat generation and hemolysis compared with axial-flow alternatives. Transplant centers in the northeastern United States are adopting these systems at accelerating pace for destination therapy indications. The technology is consolidating competitive positioning around durability claims, forcing axial-flow incumbents to defend on established clinical track records and surgeon training infrastructure.
FDA breakthrough device designation creates accelerated premarket approval timelines for mechanical circulatory support innovations meeting unmet clinical need criteria. The industrial consequence compresses development-to-commercialization cycles from historical decade-long benchmarks toward five-year windows. Ventricular assist device categories with established destination therapy indications face the most pressure, as newer entrants leverage streamlined pathways to challenge incumbent market positions.
Hospital procurement committees are bundling mechanical circulatory support decisions into broader cardiovascular service line contracts, displacing standalone device vendor relationships. Academic medical centers with transplant capabilities are consolidating purchasing authority under value-analysis committees that span structural heart and surgical divisions. This pattern concentrates most visibly in the northeastern United States, where major medical clusters negotiate multi-year supply agreements spanning ventricular assist devices, heart-lung machines, and perfusion consumables.
North America Cardiac Assist Devices Market Segmentation
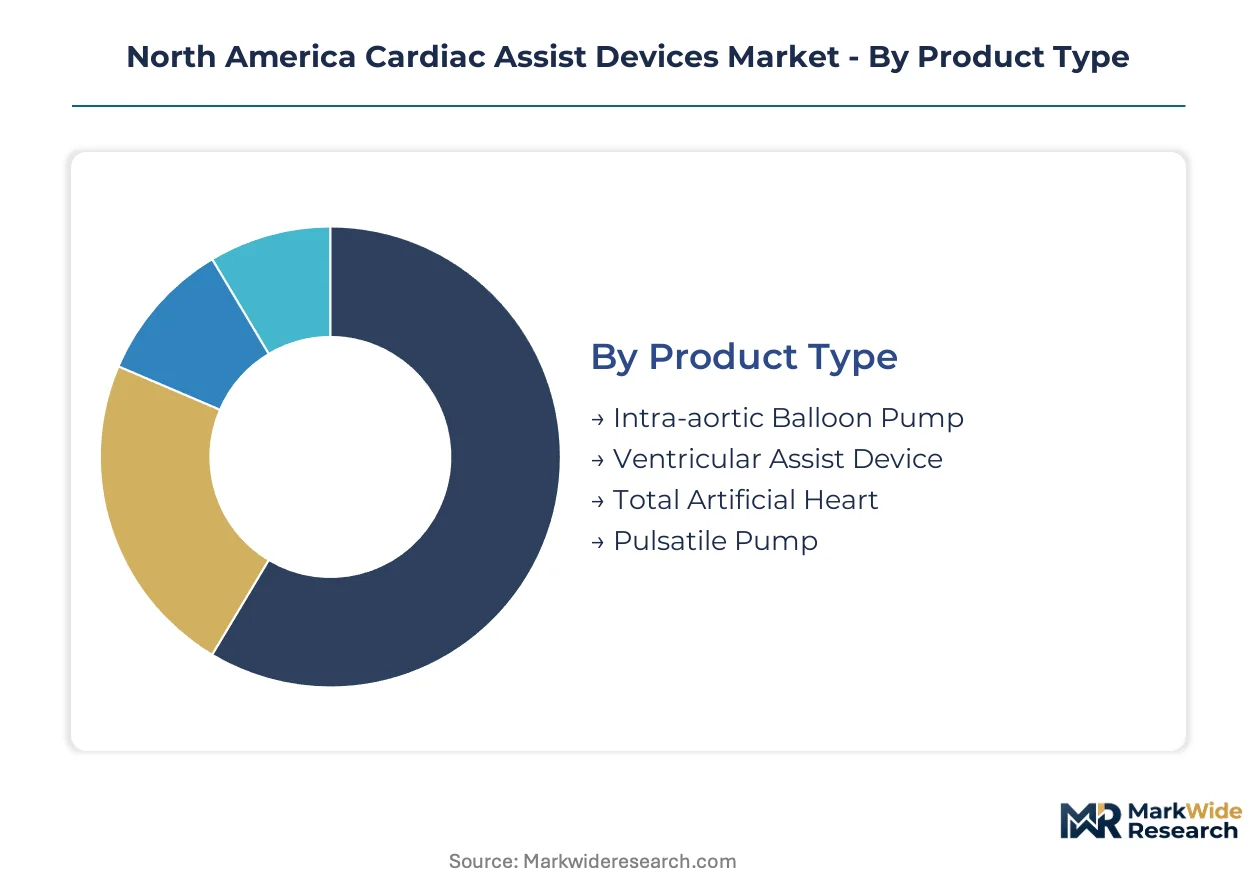
Mechanical circulatory support systems fragment across multiple technical axes that determine reimbursement pathways, implant settings, and patient candidacy. Product configuration and drive mechanism specifications directly shape procurement decisions at transplant centers and community hospitals.
Product Type:
Device classification follows functional replacement depth and circulatory support duration.
- Ventricular Assist Device:Electric or magnetic levitation pumps sustain systemic circulation at 5-10 liters per minute through left, right, or biventricular support. Demand concentrates in northeastern United States academic medical centers where destination therapy protocols now dominate bridge-to-transplant volumes.
- Total Artificial Heart:Orthotopic replacement systems eliminate native ventricular function entirely, requiring specialized surgical teams at high-volume transplant centers. FDA premarket approval pathways restrict deployment to institutions with established mechanical circulatory support programs and cardiothoracic surgery residency training.
- Intra-aortic Balloon Pump:Counterpulsation technology augments coronary perfusion through femoral artery access.
- Pulsatile Pump:Pneumatic drive systems maintain pulsatile flow patterns for myocardial recovery protocols.
Ventricular Assist Device leads on scale; Emergency Medical Services integration is gaining share fastest among deployment settings.
Technology:
Drive mechanism engineering determines durability profiles and anticoagulation requirements.
- Mechanical Circulatory Support:Continuous-flow centrifugal and axial pump architectures dominate implant volumes. Magnetic levitation configurations are displacing bearing-dependent designs at major transplant centers in Boston and New York.
- BiVentricular Assist:Synchronized dual-pump systems address biventricular failure patterns. Complex cannulation requirements limit deployment to surgical teams with advanced perfusionist support.
- Heart-Lung Machines:Cardiopulmonary bypass platforms enable open-chest procedures.
- Retrograde Perfusion:Selective coronary delivery systems protect myocardium during high-risk interventions.
Mechanical Circulatory Support anchors procurement volumes; BiVentricular Assist climbs fastest as cardiogenic shock protocols intensify.
End User:
Care setting determines device portability, monitoring infrastructure, and reimbursement coding.
- Emergency Medical Services:Pre-hospital deployment of mechanical circulatory support compresses time-to-implant for cardiogenic shock. Northeastern United States ambulance systems are equipping mobile intensive care units with portable pumps.
- Cardiac Centers:Transplant-capable institutions manage longitudinal destination therapy populations. CMS national coverage determinations concentrate implant authority at centers meeting volume thresholds.
- Hospitals:Community facilities stabilize patients for transfer to specialized centers.
- Home Care:Discharge protocols for stable VAD patients extend therapy beyond institutional settings.
Cardiac Centers dominate implant volumes; Emergency Medical Services shows steepest expansion trajectory.
Application:
Clinical indication shapes device selection, implant urgency, and expected support duration.
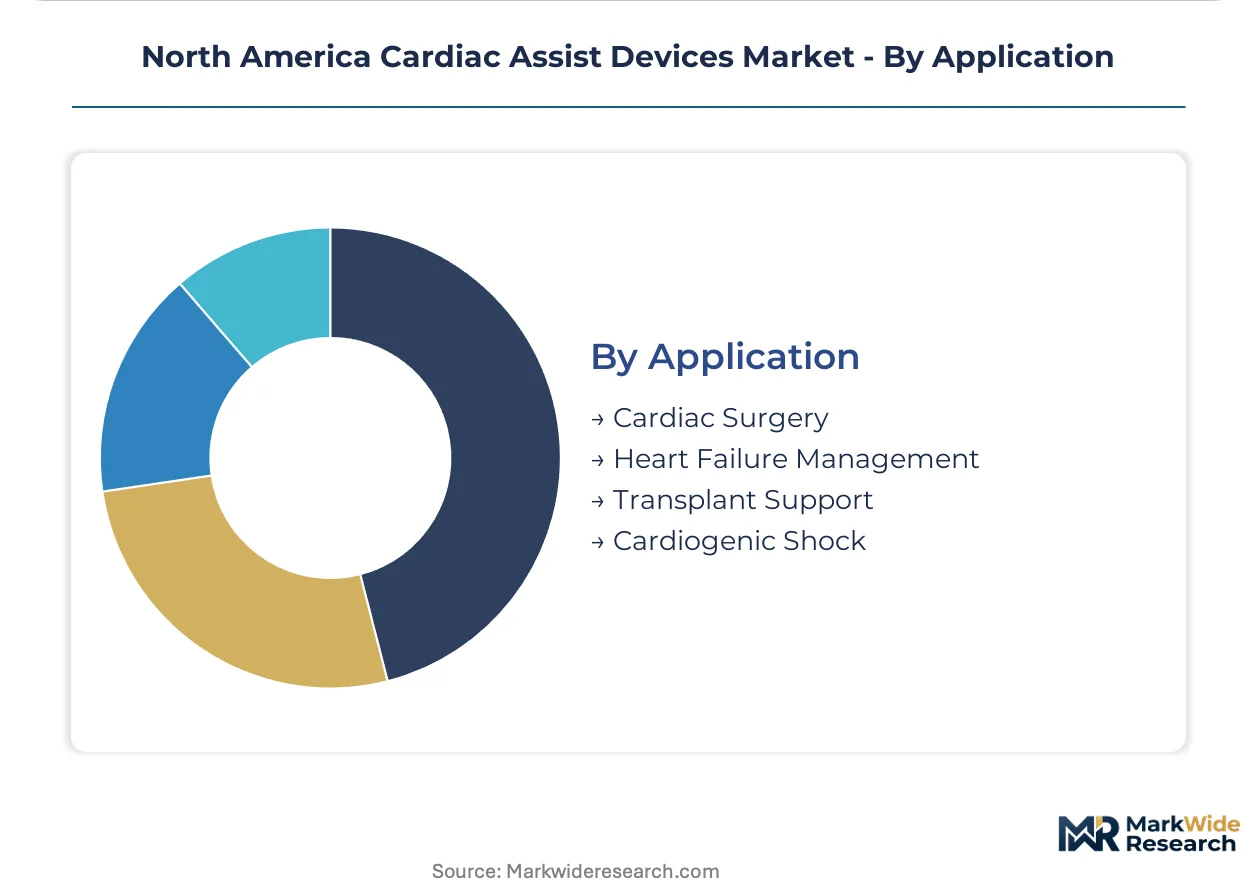
- Heart Failure Management:Chronic mechanical circulatory support extends survival for transplant-ineligible patients. Destination therapy reimbursement from CMS has expanded patient pools beyond traditional bridge protocols.
- Cardiogenic Shock:Acute circulatory collapse requires rapid mechanical support deployment. Pre-hospital protocols in the northeastern United States are accelerating pump initiation before hospital arrival.
- Cardiac Surgery:Intraoperative support enables complex revascularization and valve procedures.
- Transplant Support:Bridge-to-transplant indications maintain priority at specialized cardiac centers.
Heart Failure Management leads on patient volume; Cardiogenic Shock protocols are expanding fastest across care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The northeastern United States academic medical corridor generates the highest ventricular assist device implant volumes, with Boston and New York transplant centers setting clinical protocols that diffuse across regional markets. FDA breakthrough device designation pathways and CMS national coverage determinations create regulatory gravity that shapes procurement patterns from major metropolitan clusters through secondary care networks.
United States
Destination therapy reimbursement expansion and pre-hospital cardiogenic shock protocols drive demand concentration in the Northeast, with Massachusetts General Hospital and NewYork-Presbyterian maintaining the highest implant volumes. FDA premarket approval requirements under the breakthrough devices program govern commercialization timelines for magnetic levitation technologies. The southeastern United States, particularly Florida and Texas transplant centers, shows accelerating program expansion with lower current implant density than northeastern academic clusters.
Canada
Cross-border commercialization through Health Canada's medical device licensing framework allows United States manufacturers to access Canadian transplant centers with minimal regulatory duplication. The country's national pharmaceutical regulator maintains alignment with FDA durability testing standards for mechanical circulatory support devices. Toronto General Hospital and Vancouver Coastal Health anchor implant volumes, with Ontario and British Columbia provinces concentrating specialized cardiac surgery capacity.
Mexico
Emerging transplant infrastructure in Mexico City and Monterrey creates demand for bridge-to-therapy devices as cardiac surgery programs expand at Instituto Nacional de Cardiología and Hospital Universitario. The country's national health regulator oversees medical device import licensing for advanced mechanical circulatory support systems. Northern border states show accelerating patient transfer protocols to United States transplant centers for destination therapy candidacy.
North America Cardiac Assist Devices Market Competitive Landscape
Global majors compete with regional champions across technology platforms and distribution reach, with magnetic levitation innovations compressing incumbent positioning around established reimbursement codes. The market structure shows tiered consolidation: diversified cardiovascular conglomerates anchor North American distribution through cardiac surgery sales channels, while specialized mechanical circulatory support firms compete on perfusion technology adjacencies and transplant center relationships. Strategic moves concentrate on catheter-based delivery integration and value-analysis committee bundling across cardiovascular service lines.
Within the diversified medical technology tier, Abbott Laboratories and Medtronic exemplify scale-driven positioning through structural heart portfolio breadth and established cardiac surgery sales infrastructure. Getinge occupies a distinct position anchored in perfusion technology adjacencies that complement heart-lung machine installed bases. Among specialized mechanical circulatory support developers, Berlin Heart and SynCardia Systems represent focused innovators concentrated on total artificial heart and pediatric ventricular assist device applications.
| Leading Market Players |
|---|
| LivaNova |
| Teleflex |
| Abiomed |
| Berlin Heart |
| Getinge |
| Abbott Laboratories |
| SynCardia Systems |
| Jarvik Heart |
| Medtronic |
| Others |
Value Network & Pricing Analysis
Biocompatible polymer coatings and magnetic levitation bearing assemblies flow from specialized chemical suppliers and precision component manufacturers through tiered pricing structures that stratify transplant centers by implant volume and destination therapy program maturity.
Pricing Analysis
Input-cost pass-through from rare-earth magnet suppliers and medical-grade titanium processors anchors device pricing, with magnetic levitation configurations commanding premium positioning over axial-flow alternatives. Price differentiation separates FDA breakthrough-designated systems from PMA-standard devices, while volume scale at northeastern academic medical clusters unlocks contracted pricing unavailable to emerging southeastern programs. Pricing pressure stems from CMS reimbursement rate compression as destination therapy volumes expand, with emergency medical services segments showing highest price sensitivity due to capital budget constraints.
Supply Chain Analysis
Direct-to-transplant-center channels handle high-volume academic medical center demand, while distributor-mediated pathways serve emerging programs in secondary markets. Manufacturing concentration in the United States, Germany, and Japan feeds North American demand, with magnetic levitation subassemblies drawing from precision engineering clusters in Switzerland and the Netherlands. Supply chain risk centers on single-source vulnerability for thromboresistant coating chemistries and specialized pump motor windings. Distribution runs through cardiac surgery sales organizations with perfusion technology adjacencies, bundling ventricular assist devices with heart-lung machine consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America cardiac assist devices market represents a late-cycle quality story where magnetic levitation durability claims and thromboresistant surface engineering are shifting procurement criteria toward premium specifications that reduce long-term anticoagulant management costs.
For Market Incumbents: Acquire specialized perfusionist training capabilities and VAD coordinator workforce development assets to defend program expansion pace against emerging transplant centers. Magnetic levitation entrants threaten axial-flow incumbents through FDA breakthrough pathways, necessitating backward integration into catheter-based delivery platforms and value-analysis committee bundling across cardiovascular service lines. For New Entrants and Emerging Players: Digital health integration routes through remote patient monitoring platforms offer white-space access to home care discharge protocols and longitudinal destination therapy management. The southeastern United States transplant corridor presents the most penetrable geography, with Florida and Texas centers expanding programs at lower current implant density than northeastern clusters. Target emergency medical services pre-hospital deployment through portable pump miniaturization and ambulance-based training partnerships. For Investors and Strategic Acquirers: Consolidation pressure builds where magnetic levitation technology obsoletes bearing-dependent designs and FDA breakthrough pathways compress commercialization timelines. Five-to-ten-year viability favors platforms with integrated structural heart delivery capabilities and established reimbursement strategy infrastructure. The signal to watch is CMS national coverage determination expansion for biventricular support indications and transcutaneous power technologies.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated PMA timelines compress development-to-commercialization cycles for magnetic levitation innovations. |
| Hospital System Partnership | Value-analysis committee bundling across cardiovascular service lines displaces standalone vendor relationships at academic medical centers. |
| Perfusion Technology Integration | Adjacency to heart-lung machine installed bases creates procurement leverage and cross-selling opportunities. |
| Reimbursement Strategy Development | CMS national coverage determination alignment shapes patient access thresholds and hospital procurement decisions. |
| Software Companion Development | Remote monitoring platforms extend therapy management beyond institutional settings into home care discharge protocols. |
Research Methodology
Bottom-up transplant center and emergency medical services deployment modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with VAD program directors, perfusionist supervisors, hospital value-analysis committee members, and GPO contracts managers combined with secondary validation against FDA PMA databases, CMS national coverage determination records, and hospital procurement system data. Triangulation across these sources ensures segmentation integrity across product type, technology platform, and end-user setting dimensions.
Historical trendline analysis of implant volumes at major academic medical centers established baseline growth patterns extended through the projection horizon. The analytical framework models ventricular assist device, total artificial heart, and intra-aortic balloon pump segments across mechanical circulatory support and bi-ventricular assist technologies, with end-user splits between cardiac centers, emergency medical services, hospitals, and home care. CAGRs derive from patient pool epidemiology, destination therapy candidacy expansion, and pre-hospital protocol penetration assumptions.
The model assumes a particular technology adoption path; alternative pathways for fully transcutaneous power and bearing-free magnetic levitation designs would alter the outlook. Forecasts reflect documented assumptions regarding CMS reimbursement stability, FDA durability testing standard finalization, and transplant center program expansion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiac Valve Market
Cardiovascular Devices
Global Vascular Plugs Market
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Global Coil Wound Devices Market
Cardiovascular Devices
UAE Cardiovascular Devices Market
Cardiovascular Devices
Global Coronary Stent Market
Cardiovascular Devices
Stent-Assisted Coiling Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
North America Interventional Cardiology and Peripheral Vascular Devices Market
Cardiovascular Devices
Saudi Arabia Cardiovascular Devices Market
Cardiovascular Devices
Intravascular Ultrasound (IVUS) System Market
Cardiovascular Devices
Heart Valves Market
Cardiovascular Devices
Radiofrequency Balloon Catheter Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market