
 Drug Eluting Balloon Market | 2026-2036
Drug Eluting Balloon Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Eluting Balloon Market Analysis
The capital-intensity divergence between large-scale manufacturers and specialized coating firms is bifurcating the competitive landscape. Boston Scientific Corporation leverages integrated catheter production lines to control cost structures across coronary and peripheral portfolios. Medtronic anchors its position through sustained investment in drug-polymer matrix research, while B. Braun SE competes on manufacturing scale in European hospital supply chains.
A drug eluting balloon is a semi-compliant angioplasty balloon coated with an antiproliferative agent—typically paclitaxel or sirolimus—delivered to the vessel wall during inflation to inhibit neointimal hyperplasia. The coating technology dimension separates leaders from followers, as uniform drug transfer efficiency directly impacts restenosis rates and clinical outcomes. DEB for coronary applications occupies the largest revenue pool, while combination DEB integrating intravascular lithotripsy represents the fastest-growing segment due to expanding indications in calcified lesions. Cardiology centers now drive volume concentration as procedural specialization shifts away from general hospitals.
FDA premarket approval requirements and EU MDR conformity assessments shape product development timelines and market access costs for manufacturers. Japan's PMDA and Germany's national reimbursement authority, the G-BA, influence adoption velocity through evidence-based coverage decisions. Stakeholders must monitor evolving head-to-head trial data comparing DEB against drug-eluting stents in bifurcation lesions to anticipate shifts in interventional guidelines.
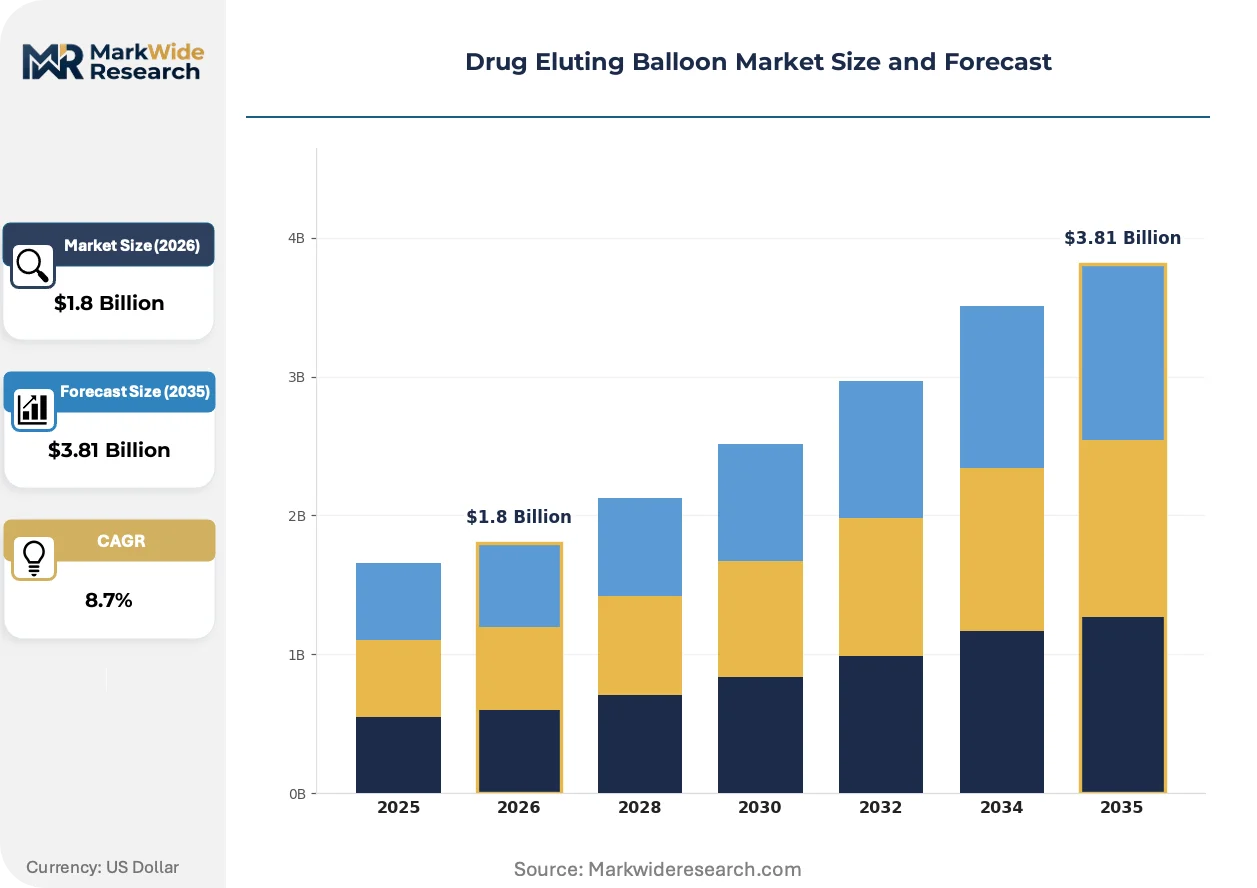
Market Dynamics
Coating technology differentiation is bifurcating the Drug Eluting Balloon competitive landscape into integrated manufacturers with captive polymer science capabilities versus assembly-focused competitors dependent on external coating suppliers.
Growth Catalysts
- EU MDR conformity pathways:Tightened evidence requirements for coated balloon technologies are accelerating consolidation toward manufacturers with robust clinical trial infrastructure and quality management systems.
- Japan's interventional cardiology infrastructure:Aging demographics and PMDA reimbursement alignment favor percutaneous coronary intervention over coronary artery bypass grafting, concentrating procedure volume in specialized cardiology centers.
- Calcified lesion treatment protocols:Combination DEB integrating intravascular lithotripsy is expanding addressable indications beyond standard de novo lesions into heavily calcified vessels previously requiring atherectomy.
Market Restraints
- Active pharmaceutical ingredient concentration:Paclitaxel supply chains concentrate among three specialized chemical manufacturers, exposing DEB producers to input cost volatility and qualification timeline risk.
- FDA premarket approval friction:The agency's heightened scrutiny of coated balloon safety signals following peripheral vascular device evaluations is extending PMA review cycles and inflating clinical evidence costs.
- Drug-eluting stent residual efficacy:Second-generation limus-eluting platforms maintain durable restenosis suppression in straightforward lesions, constraining DEB penetration in low-complexity coronary segments.
Strategic Opportunities
- Bifurcation lesion protocols:Underpenetrated demand exists in side-branch treatment algorithms where DEB avoids dual-stent complexity and strut overlap thrombosis risk.
- Germany's G-BA evidence evaluation:The national reimbursement authority's structured benefit assessment process creates a pathway for premium-coated technologies demonstrating superior cost-effectiveness in complex lesions.
- Peripheral below-the-knee expansion:Critical limb ischemia applications in diabetic populations represent an emerging therapeutic area with limited durable revascularization alternatives.
Industry Challenges
- Coating uniformity expertise:The specialized knowledge base for ultrasonic spray deposition and cryomilling processes remains concentrated among a narrow cohort of polymer scientists, constraining manufacturing scale-up.
- EU MDR technical documentation:The transition from MDD to MDR has compressed notified body capacity, extending conformity assessment timelines and delaying market access for iterative product improvements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Eluting Balloon Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DEB for Coronary, DEB for Peripheral, DEB for Renal, Combination DEB Technology: Balloon Angioplasty, Drug Delivery System, Coating Technology, Bioabsorbable Polymers End User: Hospitals, Outpatient Clinics, Academic Research Institutions, Cardiology Centers Application: Coronary Artery Disease, Peripheral Arterial Disease, Renal Vascular Disease, Vein Conditions |
| Companies Covered | Boston Scientific Corporation, Medtronic, BD, Terumo Corporation, Koninklijke Philips N.V., B. Braun SE, BIOTRONIK, Cook, SurModics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Eluting Balloon Market Emerging Trajectories
Technological convergence between balloon catheter engineering and pharmaceutical formulation science is redefining competitive differentiation in interventional cardiology, with coating transfer efficiency emerging as the decisive performance metric.
Excipient-free coating matrices is bifurcating the technology landscape into two distinct development paths. Hydrophilic carriers without polymer binders facilitate rapid drug release kinetics during brief balloon inflation. Cardiology centers in Germany and Japan are adopting these platforms for bifurcation and small-vessel lesions where stent delivery risks side-branch compromise. The structural consequence is compressing revenue pools for conventional polymer-based coatings while creating premium pricing power for transfer-optimized alternatives.
EU MDR Article 10 post-market surveillance requirements are mandating systematic clinical follow-up registries for all class III devices including DEB. Manufacturers must now maintain active implant tracking and periodic safety update reporting throughout product lifecycles. High-complexity coronary applications face the most stringent scrutiny, with notified bodies demanding real-world evidence complements to premarket trial data.
Hospital procurement committees are consolidating vendor relationships around full interventional cardiology portfolios rather than single-product negotiations. General hospitals lacking specialized catheterization laboratory infrastructure are losing procedure volume to dedicated cardiology centers with 24/7 intervention capability. This concentration is most visible in Japan's metropolitan prefectures and Germany's university hospital networks, where purchasing power has shifted toward integrated device suppliers.
Drug Eluting Balloon Market Segmentation
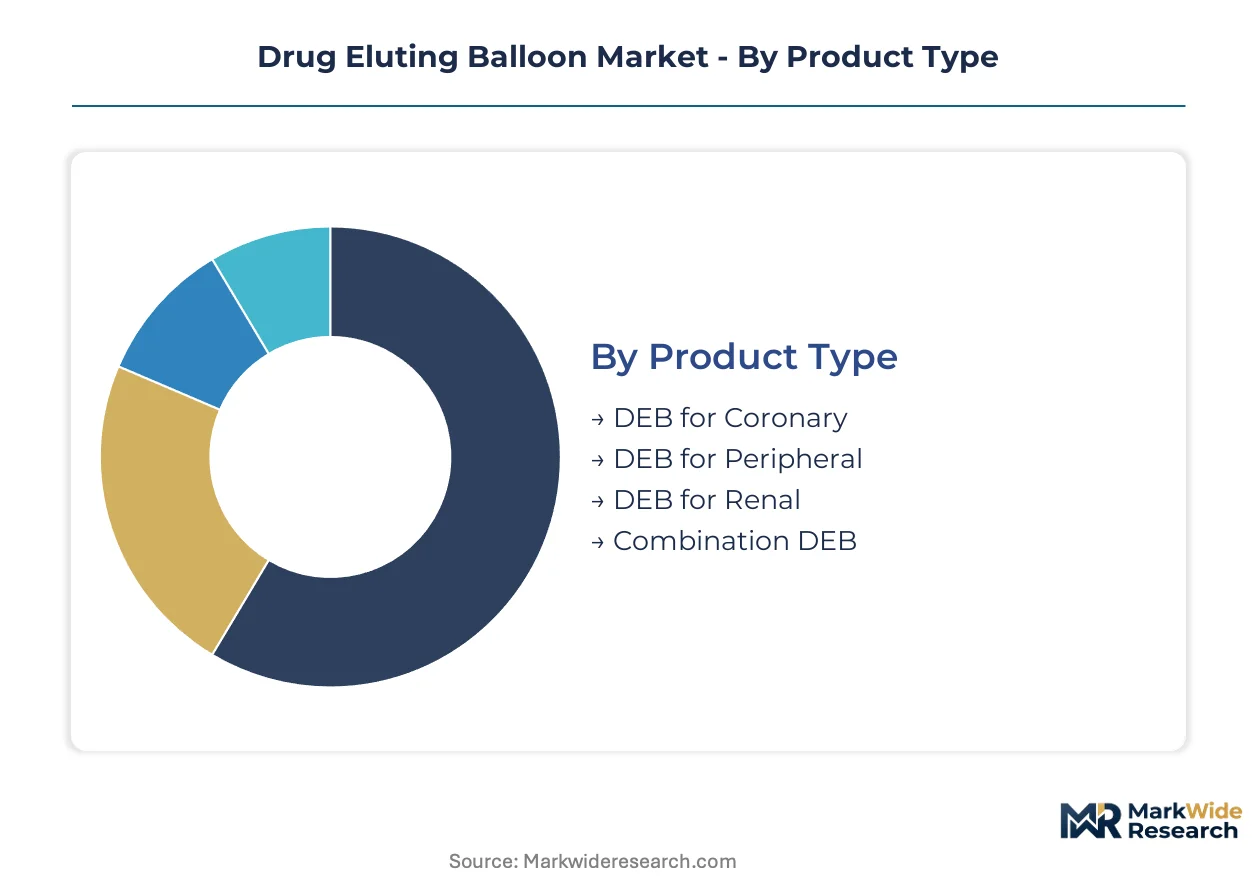
Segmentation in the Drug Eluting Balloon market reveals how coating technology sophistication and procedural site specialization drive purchasing decisions. Manufacturers must align product portfolios across coronary, peripheral, and renal applications while navigating divergent regulatory pathways and reimbursement frameworks.
Product Type:
Substitution pressure from drug-eluting stents and atherectomy systems varies sharply across anatomical targets, with coronary applications facing the most intense competitive threat from limus-eluting platforms.
- DEB for Coronary:Paclitaxel-coated semi-compliant balloons target de novo lesions and in-stent restenosis in native coronary arteries. Cardiology centers in Germany and Japan concentrate demand for bifurcation protocols where dual-stent complexity is avoided.
- DEB for Peripheral:Larger-diameter balloons with modified coating matrices address superficial femoral and popliteal artery disease. Below-the-knee applications in diabetic populations with critical limb ischemia represent the fastest-expanding addressable pool.
- DEB for Renal:Smaller-profile balloons designed for renal artery stenosis carry specialized coating loads calibrated for vessel diameter constraints.
- Combination DEB:Integrated platforms pairing drug delivery with intravascular lithotripsy target calcified lesions previously requiring sequential procedures.
DEB for Coronary anchors the volume base while Combination DEB gains share at the steepest rate.
Technology:
Cost tier stratification separates premium coating platforms with captive polymer science capabilities from assembly-focused competitors dependent on licensed formulations.
- Balloon Angioplasty:Semi-compliant and non-compliant balloon platforms provide the mechanical foundation for lesion preparation and drug transfer.
- Drug Delivery System:Proprietary excipient matrices control release kinetics during brief inflation windows. Excipient-free hydrophilic carriers command premium positioning in Japanese and German procurement channels.
- Coating Technology:Ultrasonic spray deposition and cryomilling processes determine transfer efficiency uniformity. The specialized knowledge base for these techniques concentrates manufacturing scale-up among integrated producers.
- Bioabsorbable Polymers:Degradable carrier systems eliminate permanent polymer residue but face extended EU MDR clinical evidence requirements.
Coating Technology commands the highest margin tier while Bioabsorbable Polymers climb the fastest on expanded regulatory approvals.
End User:
Customer type fragmentation reflects the procedural volume shift from general hospitals toward specialized intervention sites with 24/7 catheterization laboratory capability.
- Hospitals:General acute-care facilities with catheterization laboratories maintain bulk purchasing leverage but lose complex case volume to dedicated centers.
- Outpatient Clinics:Ambulatory surgical centers in Japan's metropolitan prefectures handle straightforward peripheral interventions under PMDA-aligned reimbursement.
- Academic Research Institutions:University hospital networks in Germany conduct head-to-head trials comparing DEB against drug-eluting stents in bifurcation lesions.
- Cardiology Centers:Dedicated intervention facilities concentrate procedure volume and drive vendor consolidation around full interventional cardiology portfolios.
Cardiology Centers anchor the volume base while Academic Research Institutions expand most quickly on clinical trial infrastructure investment.
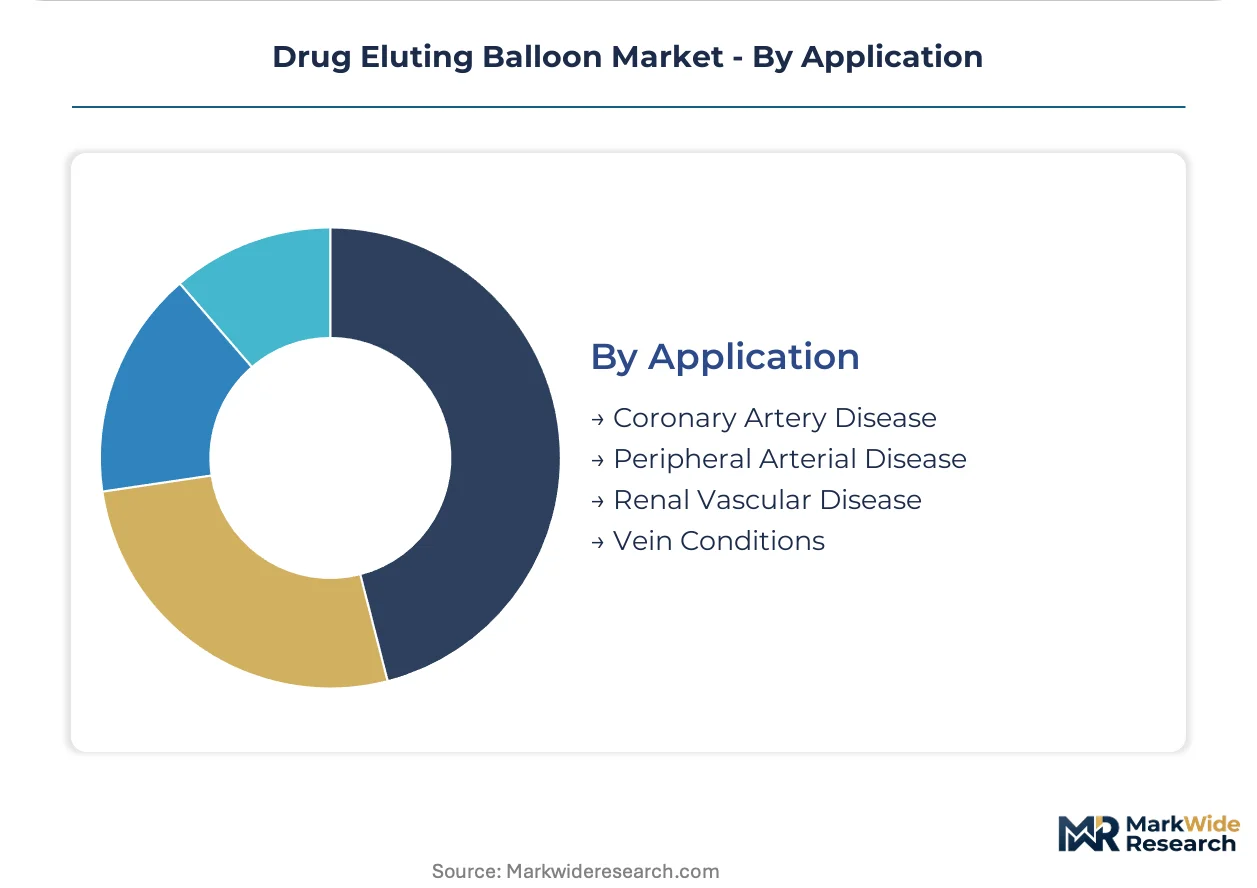
Application:
Maturity differentiation separates established coronary protocols from emerging below-the-knee indications with limited durable revascularization alternatives.
- Coronary Artery Disease:In-stent restenosis and small-vessel de novo lesions constitute the primary approved indications with established reimbursement pathways.
- Peripheral Arterial Disease:Superficial femoral artery interventions face competition from drug-eluting stents, while infrapopliteal segments offer underpenetrated opportunity.
- Renal Vascular Disease:Atherosclerotic renal artery stenosis applications remain constrained by limited randomized trial evidence versus medical management.
- Vein Conditions:Dialysis access and venous stenosis represent niche applications with developing clinical protocols.
Coronary Artery Disease anchors the volume base while Peripheral Arterial Disease climbs fastest on calcified lesion protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Japanese cardiology centers absorb premium pricing for excipient-free coating platforms, while peripheral markets in India and Brazil prioritize cost-competitive alternatives. European procurement committees in Germany and Switzerland negotiate on total procedure value rather than device cost alone.
United States
FDA premarket approval pathways for class III devices shape competitive access, with heightened scrutiny of coated balloon safety signals extending review cycles. The agency's peripheral vascular device evaluations have inflated clinical evidence costs for coronary applications. Boston Scientific Corporation anchors manufacturing presence in Massachusetts, leveraging integrated catheter production lines to control cost structures.
Germany
The G-BA's structured benefit assessment process creates pathways for premium technologies demonstrating superior cost-effectiveness in complex lesions. EU MDR conformity assessments under Article 10 mandate systematic post-market surveillance registries. Cardiology centers in Bavaria and North Rhine-Westphalia concentrate procedure volume and drive vendor consolidation around full interventional portfolios.
Japan
PMDA reimbursement alignment favors percutaneous coronary intervention over coronary artery bypass grafting, concentrating demand in specialized cardiology centers. Aging demographics expand the addressable patient pool for bifurcation and small-vessel protocols. Metropolitan prefectures in Kanto and Kansai regions handle the highest intervention volumes under aligned payment structures.
India
Price sensitivity dominates procurement decisions in general hospitals lacking dedicated catheterization laboratory infrastructure. The country's national pharmaceutical regulator oversees import qualification timelines for coated balloon technologies. Medical device clusters in Maharashtra and Gujarat assemble distribution networks targeting tier-two city cardiology centers.
Switzerland
Swissmedic maintains stringent conformity assessment requirements for drug-device combination products entering the market. Premium pricing tolerance supports adoption of transfer-optimized coating platforms in university hospital networks. The Basel-Zurich corridor concentrates European headquarters functions for multinational manufacturers serving German and Austrian markets.
Drug Eluting Balloon Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated manufacturers commanding polymer science capabilities while assembly-focused competitors compete on manufacturing scale. The market structure consolidates around three strategic tiers: diversified medtech conglomerates with captive R&D infrastructure, specialized interventional firms with coating expertise, and regional suppliers serving price-sensitive procurement channels. Dominant competitive moves include strategic partnerships for coating technology access and geographic expansion through distributor networks in Asia-Pacific markets.
Among diversified medtech conglomerates, Boston Scientific Corporation and Medtronic occupy positions representing integrated manufacturing scale, while B. Braun SE exemplifies European supply chain concentration. These three anchors demonstrate how captive polymer science capabilities separate premium-tier competitors from assembly-dependent alternatives. Terumo Corporation represents Japanese precision manufacturing archetypes, with geographic origin signaling PMDA-aligned regulatory expertise. The competitive dynamic centers on coating transfer efficiency as the decisive performance metric, with player archetypes aligning to either technology leadership or cost leadership vectors.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| BD |
| Terumo Corporation |
| Koninklijke Philips N.V. |
| B. Braun SE |
| BIOTRONIK |
| Cook |
| SurModics Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements for paclitaxel API lock in supply access and price visibility for integrated DEB manufacturers, insulating them from the spot-market volatility that pressures assembly-focused competitors in India and Brazil. These contractual structures concentrate procurement power among firms with captive polymer science capabilities while exposing smaller players to input cost swings.
Pricing Analysis
After-sales revenue from catheter reprocessing contracts and extended technical service agreements drives lifetime value for integrated manufacturers like Boston Scientific and Medtronic. Three-tier pricing structure across premium excipient-free platforms, standard polymer-based coatings, and economy uncoated balloons separates procurement channels. Pricing pressure stems from EU MDR conformity assessment delays that compress commercialization windows. General hospitals in India exhibit highest price sensitivity, while Japanese cardiology centers absorb premium positioning for transfer-optimized technologies.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors determine landed cost competitiveness for European DEB distribution. API production concentrates in China, India, and Switzerland, with coating formulation expertise centering on Germany and Japan. Critical dependencies include paclitaxel raw material, specialized polymer excipients, and semi-compliant balloon substrates. Single-source vulnerability in ultrasonic spray deposition equipment exposes manufacturers to qualification timeline risk. Distribution runs through hospital procurement committees consolidating around full interventional cardiology portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Drug Eluting Balloon market operates as a defensive-moat story where regulatory entrenchment through FDA PMA pathways and EU MDR Article 10 conformity assessments creates structural barriers that protect incumbents with established clinical trial infrastructure.
For Market Incumbents: Consolidate coating technology capabilities through captive polymer science investment or strategic acquisition of specialized deposition firms. Expand manufacturing footprint in Bavaria and North Rhine-Westphalia to capture G-BA reimbursement pathway advantages. Threat: Assembly-focused competitors from Asia-Pacific eroding margin in peripheral segments. Lever: Vertical integration into API qualification to secure paclitaxel supply chains.
For New Entrants and Emerging Players: Differentiate on excipient-free hydrophilic carrier platforms that command premium positioning in Japanese and German procurement channels. Target below-the-knee peripheral applications in diabetic populations where durable revascularization alternatives remain limited. White-space: Academic research institution partnerships for bifurcation lesion trial sponsorship. Go-to-market: Distributor networks in Maharashtra and Gujarat tier-two city cardiology centers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated manufacturers with captive R&D infrastructure over assembly-dependent competitors. Long-term viability hinges on coating transfer efficiency leadership and regulatory approval velocity. Acquisition target: Specialized interventional firms with ultrasonic spray deposition expertise. Signal to watch: Head-to-head trial data comparing DEB against drug-eluting stents in bifurcation lesions as guideline inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Pathway | Article 10 post-market surveillance registries mandate systematic clinical follow-up for class III devices. |
| Hospital System Partnership | Cardiology center alliances in Kanto and Kansai regions concentrate procurement power for integrated portfolios. |
| Coating Technology Licensing | Excipient-free hydrophilic carrier patents differentiate premium positioning in German G-BA evaluations. |
| Reimbursement Strategy | PMDA alignment in Japan favors percutaneous intervention over coronary artery bypass grafting. |
| Manufacturing Scale-Up | Ultrasonic spray deposition capacity expansion addresses coating uniformity expertise scarcity. |
Methodological Framework
A spread of perspectives from interventional cardiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers converged on the working assumptions underlying this analysis. Primary field engagement combined with secondary validation against FDA 510(k) and PMA filings, EU MDR notified body assessment reports, PMDA reimbursement databases, and hospital procurement records. Bottom-up demand modeling across coronary, peripheral, and renal applications triangulated with top-down market sizing from integrated manufacturer revenue disclosures.
Segmentation dimensions modeled include product type, coating technology platform, end-user facility category, and geographic regulatory cluster across the analysis window. CAGRs were derived from procedure volume trajectories, pricing elasticity by procurement channel, and technology substitution curves. Industry-specific inputs incorporated EU MDR transition timelines, PMDA reimbursement alignment decisions, and G-BA structured benefit assessment outcomes.
Forecasts assume regulatory continuity in FDA premarket approval pathways and EU MDR Article 10 requirements; material policy shifts would require re-modeling. Specific risk factors include paclitaxel supply chain disruptions, notified body capacity constraints extending conformity timelines, and head-to-head trial outcomes altering interventional guidelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Transcatheter Heart Valve Market
Cardiovascular Devices
Arterial Cannula Market
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Global Heart Pump Devices Market
Cardiovascular Devices
Vascular Access Systems Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Argentina Cardiovascular Devices Market
Cardiovascular Devices
Patient-Controlled Injectors Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Stent-Assisted Coiling Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Chronic Total Occlusion Catheter Market
Cardiovascular Devices
Neurovascular Coiling Assist Devices Market
Cardiovascular Devices
Implantable Infusion Pumps Market
Cardiovascular Devices
Artificial Blood Vessels Market