
 Canada Magnetic Resonance Imaging (MRI) Market | 2026-2036
Canada Magnetic Resonance Imaging (MRI) Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Magnetic Resonance Imaging (MRI) Market Outlook
Equipment leasing and managed service contracts is rewriting capital deployment patterns for Canadian healthcare providers. Siemens Healthineers leverages its superconducting magnet supply chain to sustain premium system availability across provincial health authorities. GE Healthcare anchors its position through extensive service infrastructure and refurbished equipment channels. Koninklijke Philips differentiates via diagnostic informatics integration with hospital enterprise imaging networks.
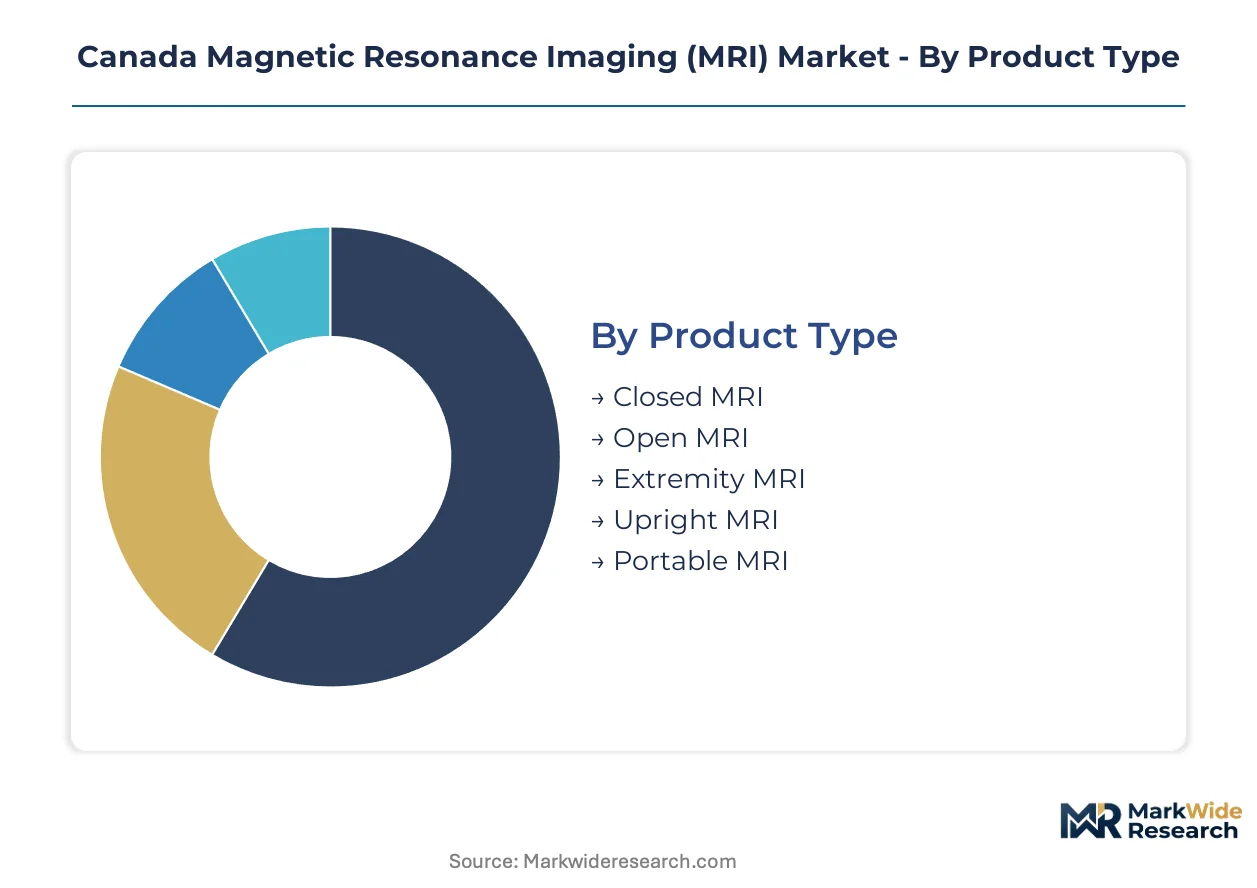
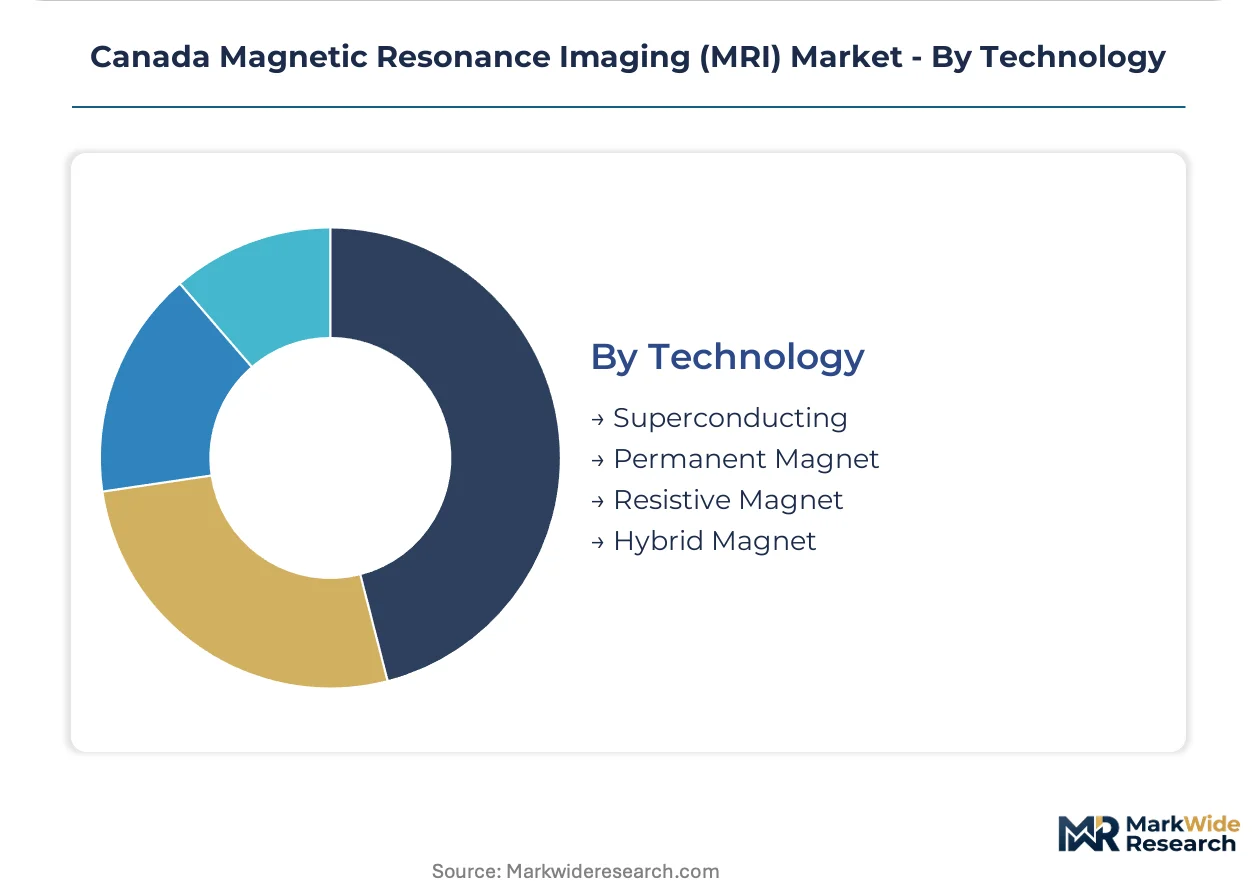
Magnetic Resonance Imaging employs superconducting coils cooled by liquid helium to generate high-resolution tomographic images using magnetic fields between 1.5 and 7 Tesla, primarily serving non-invasive diagnostic visualization of soft tissues, organs, and neural structures. Closed MRI systems dominate installed base volume in Canadian acute care settings due to superior signal-to-noise ratios for neurology and musculoskeletal protocols. Portable MRI technology represents the fastest-expanding product category, addressing rural and remote facility access gaps where permanent infrastructure proves economically unfeasible. Superconducting technology leads the technology segmentation by revenue contribution, though hybrid magnet architectures gain traction for specialized abdominal and cardiovascular applications.
Health Canada's Medical Devices Directorate enforces ISO 13485 quality system compliance and pre-market licensing for MRI systems, while provincial health technology assessment bodies like Ontario Health govern funding allocation and adoption criteria. Health Canada and provincial regulators jointly determine reimbursement eligibility and safety standards that constrain market entry timelines for non-established vendors. Stakeholders must monitor evolving helium supply chain regulations and provincial capital budget cycles to anticipate procurement windows and competitive positioning requirements.
Market Dynamics
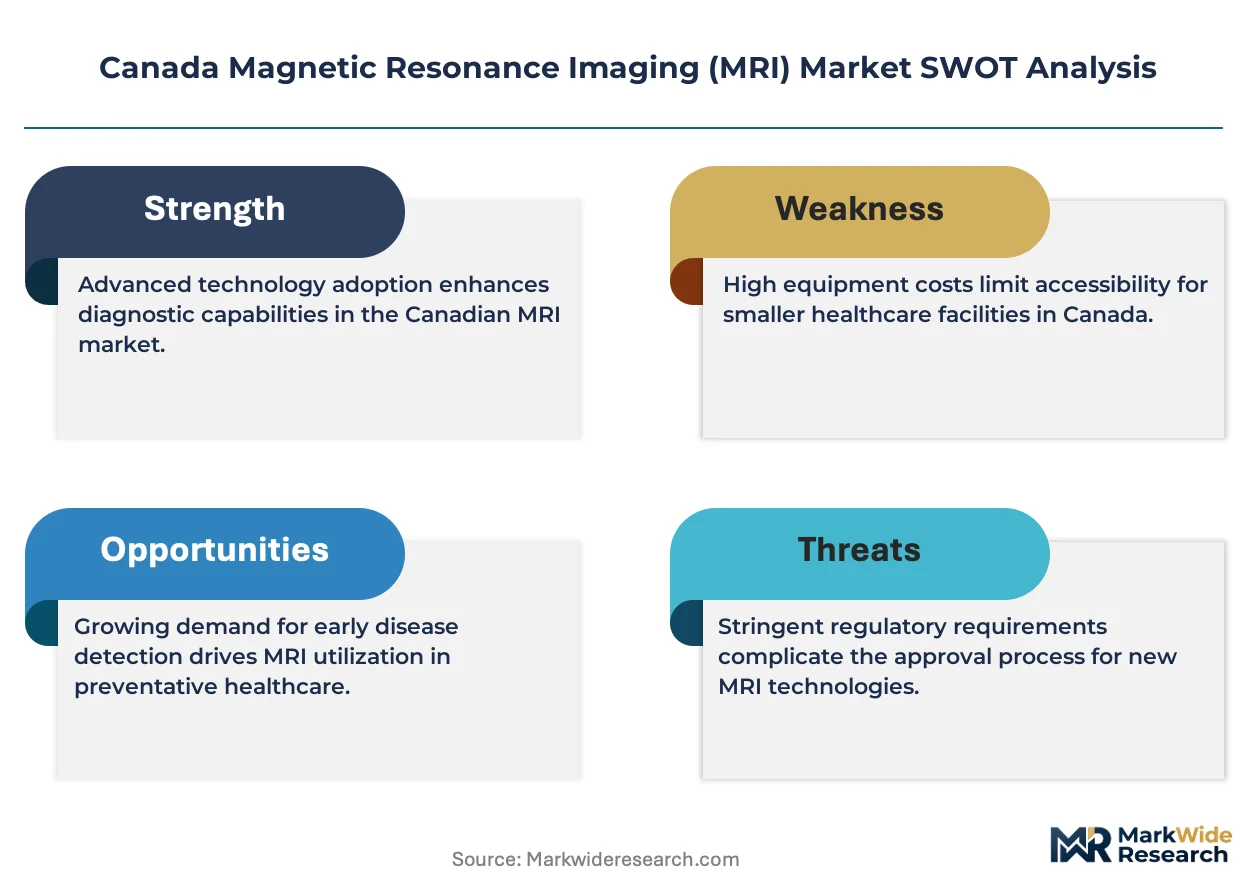
Helium supply chain volatility is compressing procurement timelines for Canadian health authorities, forcing accelerated capital planning cycles and vendor consolidation around domestic service infrastructure.
Growth Catalysts
- Ontario Health Technology Assessment:Streamlined funding pathways for neurology and oncology diagnostics are accelerating MRI deployment across Toronto-area hospital networks.
- Portable magnet architectures:Low-field systems are eliminating cryogen dependency and expanding diagnostic access to remote northern communities beyond permanent infrastructure reach.
- Quebec's provincial capital budgets:Multi-year equipment replacement cycles are creating predictable procurement windows for superconducting system vendors.
Market Restraints
- Liquid helium concentration:North American refining capacity bottlenecks are exposing Canadian purchasers to price volatility and allocation rationing.
- Health Canada Class III licensing:ISO 13485 compliance and pre-market authorization timelines extend vendor qualification periods by 18-24 months.
- Closed-system technical limitations:Conventional bore diameters exclude bariatric and claustrophobic patient populations from standard diagnostic protocols.
Strategic Opportunities
- Alberta and Saskatchewan rural corridors:Mobile MRI service contracts are addressing geographic access gaps without permanent capital deployment.
- Health Canada helium recovery mandates:Closed-loop cryogen recycling requirements are creating aftermarket service revenue streams for magnet maintenance providers.
- Artificial intelligence reconstruction:Deep learning algorithms are enabling diagnostic-quality imaging from lower-field-strength systems, reducing site preparation costs.
Industry Challenges
- Specialized biomedical engineering talent:Superconducting magnet maintenance expertise concentrates in Montreal and Toronto, constraining nationwide service response times.
- Legacy PACS integration complexity:Hospital enterprise imaging networks require costly middleware development to unify MRI data formats across multi-vendor installed bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Magnetic Resonance Imaging (MRI) Market |
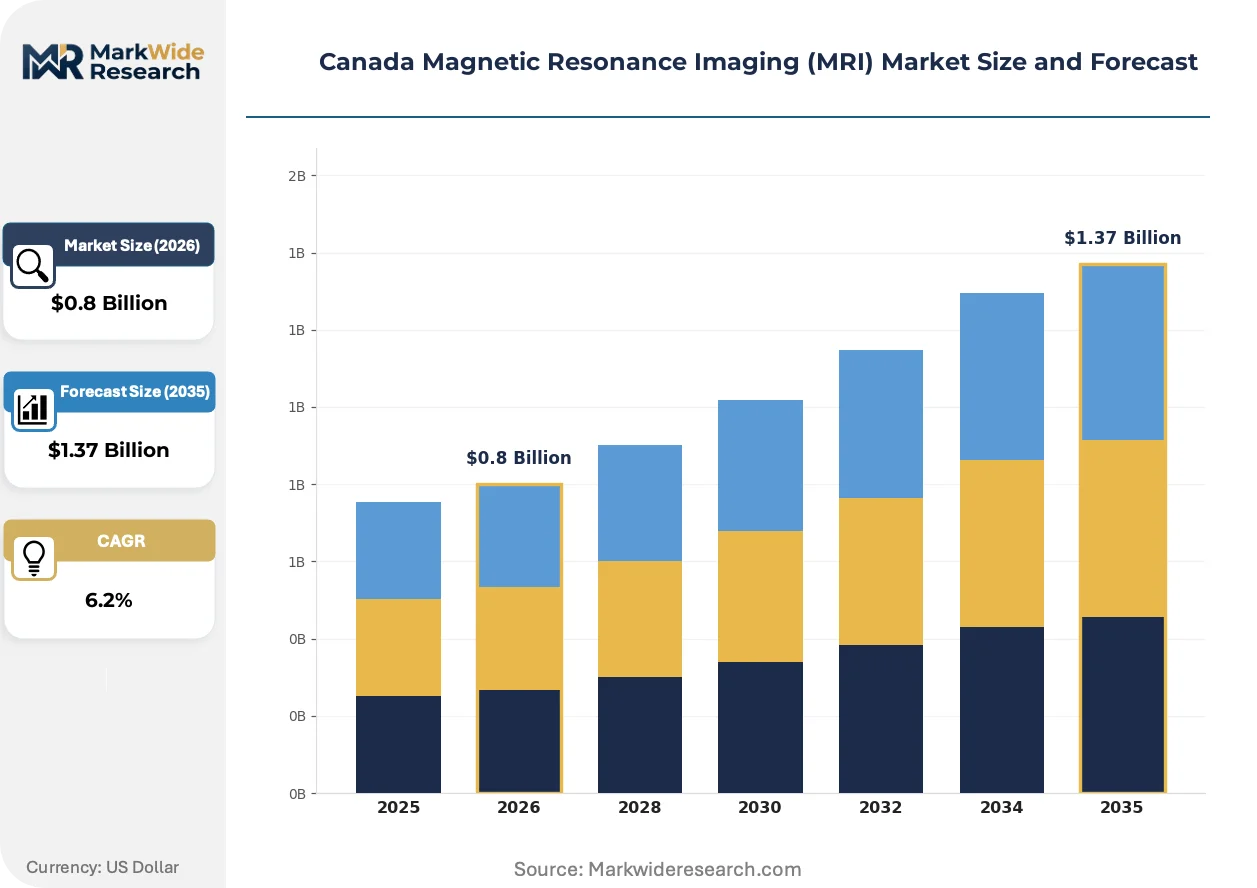
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.37 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Upright MRI, Portable MRI Application: Neurology, Musculoskeletal, Cardiovascular, Oncology, Abdominal Imaging End User: Diagnostic Centers, Research Institutes, Imaging Laboratories, Specialty Clinics Technology: Superconducting, Permanent Magnet, Resistive Magnet, Hybrid Magnet |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems, FUJIFILM Holdings Corporation, United Imaging Healthcare, Hyperfine Inc., Synaptive Medical, Esaote, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Magnetic Resonance Imaging (MRI) Market Strategic Shifts
Canadian MRI procurement is pivoting from capital ownership toward operational expenditure models, while magnetic field generation and image reconstruction undergo simultaneous technological disruption.
Helium-free permanent magnet systems are eliminating cryogenic cooling requirements through advanced rare-earth magnetic arrays. Community hospitals in Manitoba and Atlantic provinces are piloting these systems to bypass helium supply constraints. This architecture is digitizing site selection criteria by removing quench venting infrastructure and specialized foundation requirements from facility planning.
Health Canada's Medical Devices Directorate is tightening post-market surveillance obligations for AI-enabled diagnostic software under evolving Class III device interpretations. Manufacturers must now submit algorithm validation datasets alongside hardware licensing applications. Neurology imaging protocols face the steepest compliance burden as automated lesion detection tools proliferate.
Provincial health authorities are unbundling equipment acquisition from long-term service agreements. British Columbia and Alberta purchasing consortia now separately tender maintenance, upgrade, and replacement components. This disaggregation is compressing vendor lock-in durations and accelerating competitive rebidding cycles for aftermarket revenue streams.
Canada Magnetic Resonance Imaging (MRI) Market Segmentation
Segmentation in the Canadian MRI market reveals how procurement priorities diverge across clinical settings and technological architectures. Understanding these divides helps vendors align product portfolios with provincial funding cycles and Health Canada licensing pathways.
Product Type:
Cost tier differentiation separates high-field hospital systems from accessible alternatives serving constrained budgets and specialized anatomical needs.
- Closed MRI:Superconducting cylindrical bore systems generate magnetic fields between 1.5 and 3 Tesla using liquid helium-cooled niobium-titanium coils. Toronto and Montreal hospital networks concentrate demand here for neurology and oncology protocols requiring superior signal-to-noise ratios.
- Portable MRI:Low-field permanent magnet systems deploy via truck or trailer to northern Manitoba and Saskatchewan communities lacking permanent infrastructure. Federal rural health access programs are accelerating procurement of these helium-free units.
- Open MRI:C-shaped or double-doughnut magnet geometries accommodate claustrophobic and bariatric patients excluded from conventional bore systems. Quebec's patient-centered care mandates drive adoption in community hospital settings.
- Extremity MRI:Dedicated limb-only scanners operate at lower field strengths for hand, wrist, ankle, and foot diagnostics. Sports medicine clinics in Vancouver and Calgary represent concentrated demand pockets.
- Upright MRI:Vertical field configurations permit weight-bearing spine and joint imaging unavailable in supine systems. Workers compensation boards in Ontario fund these for occupational injury assessment.
Closed MRI holds installed capacity. Portable MRI is rotating up the share rankings.
Application:
Clinical workflow priorities determine field strength requirements and pulse sequence investments across diagnostic departments.
- Neurology:Brain and spinal cord imaging demands highest-field systems with advanced diffusion tensor and functional MRI capabilities. Ontario Health Technology Assessment fast-tracks funding for stroke network expansion.
- Oncology:Tumor staging and treatment response monitoring requires multiparametric sequences combining anatomical and functional data. Quebec's cancer agency coordinates provincial standardization of MRI-protocols for prostate and breast screening.
- Musculoskeletal:Joint, ligament, and cartilage assessment dominates outpatient imaging volumes across all field strengths. Private diagnostic chains in Alberta compete aggressively on appointment availability for sports-related referrals.
- Cardiovascular:Cardiac MRI with cine imaging and late gadolinium enhancement addresses coronary artery disease and cardiomyopathy. Academic medical centers in Toronto maintain specialized technologist training programs.
- Abdominal Imaging:Liver, pancreatic, and renal MRI leverages hepatobiliary contrast agents and respiratory gating. British Columbia's hepatitis C elimination program generates sustained demand for non-invasive fibrosis assessment.
Neurology commands premium system allocation. Oncology is climbing the fastest as provincial cancer strategies expand screening access.
End User:
Customer type shapes procurement modality, with capital ownership concentrated in hospital networks and operational expenditure models penetrating outpatient settings.
- Diagnostic Centers:High-volume outpatient facilities balance throughput against equipment utilization rates through extended operating hours. Ontario and Alberta purchasing consortia negotiate multi-site equipment and service bundles.
- Research Institutes:University-affiliated imaging centers operate 7 Tesla and hyperpolarized gas systems for experimental protocols. McGill and University of Toronto maintain Canada's highest-field research magnets.
- Imaging Laboratories:Private reference laboratories serve regional hospital networks with teleradiology integration. Saskatchewan's single health authority contracts these for rural community coverage.
- Specialty Clinics:Orthopedic, sports medicine, and pain management practices deploy extremity-dedicated systems. Vancouver's private surgical clinics lead western Canada in point-of-care MRI investment.
Diagnostic Centers anchor equipment volumes. Specialty Clinics are gaining share fastest as scope-of-practice regulations evolve.
Technology:
Magnet architecture determines helium dependency, site preparation requirements, and clinical performance ceilings.
- Superconducting:Niobium-titanium coils cooled to 4 Kelvin by liquid helium enable highest-field clinical imaging. Health Canada's helium recovery mandates are adding operational complexity to maintenance contracts.
- Permanent Magnet:Rare-earth magnetic arrays eliminate cryogen requirements entirely, reducing siting costs and quench risks. Atlantic Canada community hospitals pilot these for budget-constrained replacement cycles.
- Resistive Magnet:Copper coil systems operate at room temperature with water cooling, limited to low-field applications. Niche educational and veterinary markets sustain minimal Canadian demand.
- Hybrid Magnet:Combined superconducting and permanent magnet configurations optimize field homogeneity for specialized cardiac and abdominal protocols. Toronto General Hospital's cardiovascular institute operates hybrid systems for advanced surgical planning.
Superconducting technology dominates revenue contribution. Permanent Magnet systems are expanding most quickly as helium supply constraints intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's MRI equipment trade flows reflect concentrated import dependency, with domestic production limited to specialized components and service operations. Provincial health authorities source complete systems predominantly from US and European manufacturing bases.
Ontario
Toronto's hospital networks drive demand for 3 Tesla neurology and oncology systems through Ontario Health Technology Assessment fast-track pathways. Health Canada's Medical Devices Directorate licensing requirements shape procurement timelines for Toronto-area academic medical centers. The Greater Toronto Area concentrates Canada's highest-field research installations at University Health Network and Sunnybrook Health Sciences Centre.
Quebec
Montreal's McGill University Health Centre and CHUM superhospital anchor provincial demand for advanced cardiac and functional MRI protocols. Quebec's Ministry of Health and Social Services coordinates multi-year capital replacement cycles through centralized purchasing consortia. The Montreal metropolitan corridor maintains specialized biomedical engineering talent pools for superconducting magnet maintenance.
Alberta
Calgary and Edmonton health zones deploy mobile MRI services to address rural access gaps across the Prairie Provinces. Alberta Health Services tenders separate equipment and service agreements to compress vendor lock-in durations. The Calgary-Edmonton corridor pilots helium-free permanent magnet systems for community hospital budget constraints.
British Columbia
Vancouver Coastal Health and Fraser Health authorities prioritize oncology and hepatobiliary imaging for hepatitis C elimination programs. BC's Provincial Health Services Authority governs funding allocation through health technology assessment processes. The Vancouver metropolitan area concentrates private diagnostic chains and sports medicine MRI investment.
Atlantic Canada
New Brunswick and Nova Scotia health authorities pilot low-field portable systems for rural community access without permanent infrastructure. Federal rural health access programs accelerate procurement of helium-free units for northern and coastal populations. Halifax and Moncton serve as regional hubs for teleradiology integration with provincial networks.
Canada Magnetic Resonance Imaging (MRI) Market Competitive Environment
On the supply side, the industry is consolidated around three dominant system vendors with established Health Canada licensing and nationwide service infrastructure. Siemens Healthineers, GE Healthcare, and Koninklijke Philips anchor the superconducting segment through provincial health authority relationships. Strategic archetypes separate premium-field system manufacturers from portable low-field entrants and specialized extremity vendors. Competitive moves concentrate on service contract unbundling and AI-enabled diagnostic software integration.
Within the established vendor tier, Siemens Healthineers and GE Healthcare exemplify superconducting system manufacturers with extensive Canadian service networks. Koninklijke Philips occupies a position emphasizing diagnostic informatics integration. Among emerging entrants, Hyperfine Inc. represents the portable low-field archetype addressing rural access gaps, while Synaptive Medical anchors specialized surgical navigation and intraoperative imaging applications.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems |
| FUJIFILM Holdings Corporation |
| United Imaging Healthcare |
| Hyperfine Inc. |
| Synaptive Medical |
| Esaote |
| Others |
Value Chain & Pricing Dynamics
The Great Lakes freight corridor channels helium shipments from US Gulf Coast refineries to Toronto and Montreal hospital networks, concentrating procurement cost exposure among Ontario and Quebec health authorities while forcing price differentiation between cryogen-dependent superconducting systems and helium-free permanent magnet alternatives.
Pricing Analysis
Provincial health authority buyers anchor a contract-based pricing structure where three-tier pricing stratifies across premium 3 Tesla neurology systems, standard 1.5 Tesla general-purpose platforms, and economy-grade portable low-field units. Price differentiation rests on Health Canada Class III licensing status and bundled service agreement duration, with ISO 13485-certified vendors commanding substantial premiums. Cost compression in the superconducting tier is intensifying because helium supply rationing extends procurement timelines and forces accelerated capital planning cycles. Community hospitals in Atlantic Canada exhibit highest price sensitivity, while Toronto academic medical centers prioritize field strength and diagnostic capability over unit economics.
Supply Chain Analysis
Contract manufacturing for superconducting niobium-titanium coils concentrates at Siemens Healthineers' Erlangen facilities and GE Healthcare's Florence operations, with final system assembly anchored in Germany and the United States. Raw material dependencies center on liquid helium from US and Qatari refining capacity, rare-earth permanent magnet alloys from Chinese processing operations, and specialized cryogenic steel from Japanese foundries. Single-source vulnerability in helium supply exposes Canadian purchasers to allocation rationing during North American production disruptions. Distribution runs through provincial health authority tendering consortia that unbundle equipment acquisition from long-term service agreements, compressing vendor lock-in durations and accelerating competitive rebidding cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canadian MRI market operates as a substitution defense against portable low-field systems and AI-enabled diagnostic algorithms that threaten to commoditize conventional high-field imaging. Incumbents must navigate helium supply volatility and provincial procurement unbundling that erodes traditional aftermarket revenue streams.
For Market Incumbents: Harden service infrastructure density across Alberta and Saskatchewan rural corridors to defend against mobile MRI service contract competitors. Deepen backward integration into helium recovery and closed-loop cryogen recycling systems to offset Health Canada mandates and capture aftermarket revenue streams that provincial unbundling threatens to displace. Prioritize AI reconstruction algorithm development to maintain diagnostic-quality differentiation against emerging low-field entrants.
For New Entrants and Emerging Players: Establish a beachhead in Atlantic Canada community hospitals where budget constraints and infrastructure limitations favor helium-free permanent magnet systems. Target Manitoba and northern Saskatchewan remote access gaps where federal rural health programs fund portable MRI deployment without permanent capital requirements. Pursue teleradiology integration partnerships with provincial health authorities to bypass established vendor service networks and accelerate clinical validation.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates seeking to divest non-core imaging divisions amid provincial procurement consolidation. Long-term viability hinges on software-enabled diagnostic differentiation rather than hardware field strength competition. Monitor Health Canada post-market surveillance obligations for AI-enabled devices as an inflection indicator for regulatory compliance costs that favor scaled incumbents over emerging entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Helium Recovery Infrastructure Investment | Health Canada mandates create captive aftermarket revenue streams for magnet maintenance providers. |
| AI Reconstruction Algorithm Development | Deep learning validation datasets satisfy evolving Class III device interpretations for diagnostic software. |
| Mobile MRI Service Contract Expansion | Alberta Health Services tenders address geographic access gaps without permanent capital deployment. |
| Provincial Consortium Partnership | Ontario and Alberta purchasing consortia negotiate multi-site equipment and service bundles. |
| Permanent Magnet System Pilot Programs | Atlantic Canada community hospitals bypass helium supply constraints through rare-earth magnetic arrays. |
Study Parameters
The analysis maps closed MRI systems, portable low-field architectures, open bore configurations, and extremity-dedicated scanners, each validated through hospital purchasing committees, biomedical engineering directors, provincial health technology assessment officers, and GPO contracts managers. Primary interviews with Siemens Healthineers and GE Healthcare service operations heads were cross-referenced against secondary sources including Health Canada Medical Devices Directorate licensing records, Ontario Health Technology Assessment funding pathway documentation, and provincial capital budget cycle disclosures. Bottom-up equipment installation tracking and top-down health authority expenditure analysis were triangulated to reconcile volume and value estimates.
Assumptions around helium supply chain stability, Health Canada Class III licensing timeline consistency, and provincial capital budget allocation continuity were held fixed across the projection horizon, while AI-enabled diagnostic software adoption rates and permanent magnet system clinical validation timelines were varied as sensitivity parameters. Segmentation modeling incorporated product type, clinical application, end-user category, and magnet technology architecture. CAGRs were derived from equipment replacement cycle analysis and provincial funding commitment trajectories, with helium price volatility and rural access program expansion serving as key forecast inputs.
Stress conditions across helium allocation rationing severity, Health Canada post-market surveillance obligation tightening, and provincial procurement unbundling acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with helium supply disruption duration and AI diagnostic algorithm regulatory reclassification representing primary revision risks. Cross-checking against provincial health authority published capital plans and GPO contract award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
France Digital Radiology Market
Medical Imaging
Spectroscopy Intravascular Imaging System Market
Medical Imaging
Intravascular Imaging Market
Medical Imaging
Digital Mammography Market
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
Global Single-Photon Emission Computed Tomography (SPECT) Market
Medical Imaging
Industrial Computed Radiography Market
Medical Imaging
Nuclear Medicine Market
Medical Imaging
Imaging Agents Market
Medical Imaging
AI Fetal Ultrasound View Detection Software Market
Medical Imaging
Canada Mammography Market
Medical Imaging
India Mammography Market
Medical Imaging
South Africa Magnetic Resonance Imaging Market
Medical Imaging
India Diagnostic Imaging Equipment Market
Medical Imaging
South Africa Mammography Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market