
 Cerebral Aneurysm Management Market | 2026-2036
Cerebral Aneurysm Management Market Size, Share, and Industry Trends Forecast 2026-2036
Cerebral Aneurysm Management Market Outlook
Minimally invasive endovascular techniques are reshaping cerebral aneurysm treatment paradigms, shifting volume away from open craniotomy toward catheter-based interventions. Medtronic leverages its broad neurovascular portfolio to sustain leadership across coils and flow diversion platforms. Stryker competes through specialized hemorrhagic stroke product lines that anchor its position in emergency interventional settings. Penumbra differentiates via aspiration technology integrated into aneurysm access workflows.
Cerebral aneurysm management encompasses the diagnosis, intervention, and post-treatment monitoring of saccular or fusiform dilations in cerebral arteries, typically addressed through metallic implants such as platinum-titanium alloy coils or nickel-titanium flow diverters that redirect hemodynamic forces away from the aneurysm dome. The primary purpose centers on preventing subarachnoid hemorrhage while preserving parent vessel patency through either surgical or endovascular means. Flow diversion devices command premium positioning due to complex manufacturing requirements and superior durability in large or giant aneurysms, while coils remain the volume backbone in smaller wide-necked lesions where deployment speed matters. Endovascular therapy segments are expanding faster than open surgery as catheter-based platforms reduce ICU stays and enable same-day discharge protocols.
FDA premarket approval pathways and EU MDR technical documentation requirements shape neurovascular device commercialization timelines and clinical evidence standards. The EPA and OSHA additionally influence manufacturing site compliance for nitinol processing facilities and cleanroom operations. Stakeholders must monitor reimbursement parity between clipping and coiling procedures across Medicare and private payers, as payment differentials directly influence hospital capital allocation and physician training investments.
Market Dynamics
Endovascular flow diversion is compressing open surgical volumes while forcing hospital capital allocation toward hybrid angiography suites and specialized neurointerventional training pipelines.
Growth Catalysts
- EU MDR streamlined pathways:CE marking acceleration under the Medical Device Regulation is compressing commercialization timelines for next-generation flow diverters across European stroke centers.
- Aspiration-integrated access platforms:Large-bore aspiration catheters are reducing procedural steps in wide-necked aneurysm cases, cutting fluoroscopy time and contrast load.
- Stroke center certification mandates:United States hospital accreditation requirements are expanding dedicated neurointerventional capacity in tertiary care settings.
Market Restraints
- Platinum-rhodium alloy cost volatility:Coil manufacturing input prices fluctuate with precious metal markets, squeezing gross margins on high-volume detachable coil SKUs.
- Nitinol processing concentration:Shape-memory alloy fabrication for flow diverters clusters in limited cleanroom facilities, creating single-source vulnerability.
- Dual antiplatelet therapy duration requirements:Extended post-procedural medication protocols complicate patient selection and delay same-day discharge protocols.
Strategic Opportunities
- India tertiary hospital expansion:Greenfield neurointerventional suite installations in Mumbai and Delhi private hospital chains are creating first-mover equipment placement windows.
- Bioresorbable flow modulation:Magnesium-based scaffolding that dissolves after aneurysm neck endothelialization is hybridizing permanent implant and temporary support functions.
- Japan PMDA breakthrough designation:Expedited review pathways for hemorrhagic stroke devices are accelerating market entry timelines relative to standard PMA routes.
Industry Challenges
- Neurointerventionalist training throughput:The pipeline of physicians completing endovascular fellowship programs lags procedural volume expansion in high-growth metropolitan markets.
- Legacy clip inventory stranding:Hospital investment in surgical clipping instrumentation faces accelerated obsolescence as referral patterns shift toward catheter-based intervention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cerebral Aneurysm Management Market |
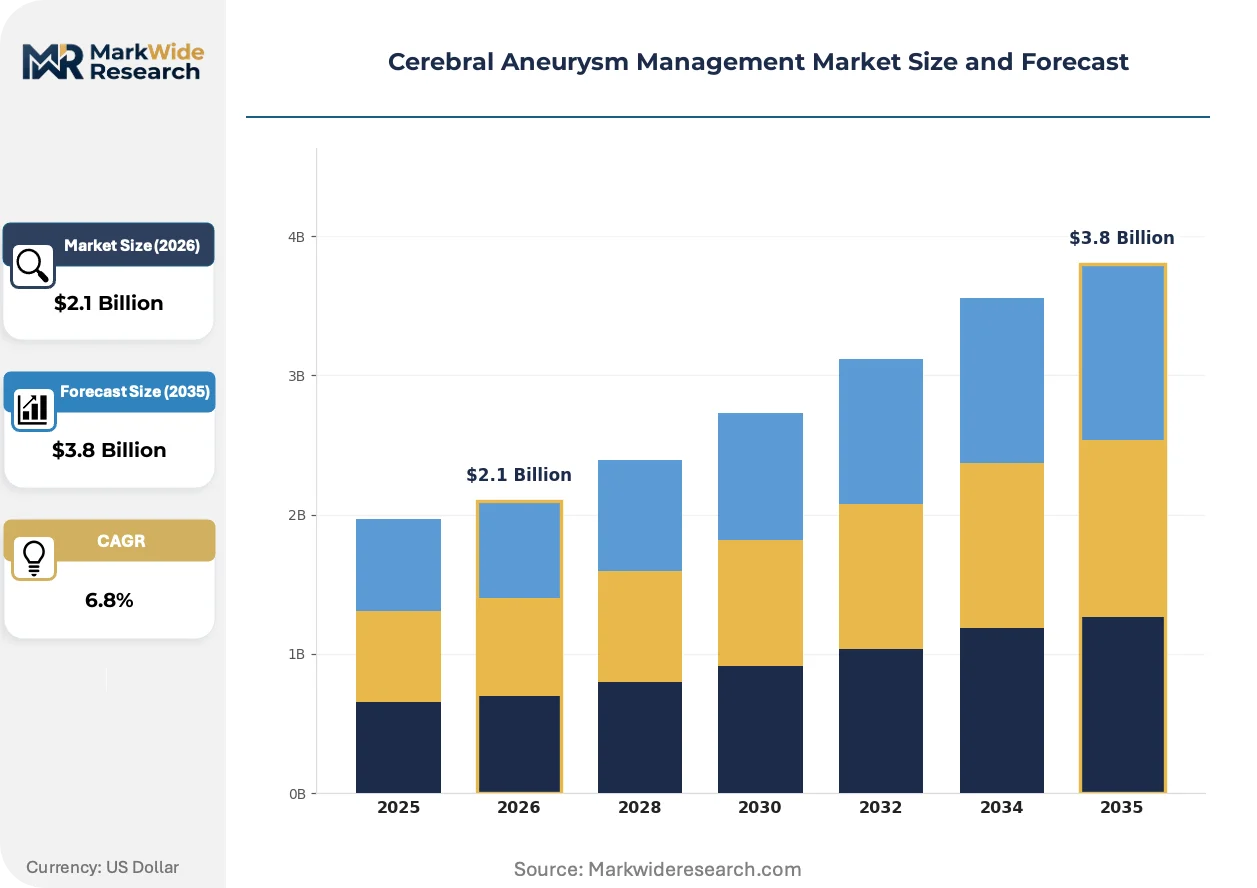
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clips, Coils, Flow Diversion Devices, Stents End User: Hospitals, Specialized Clinics, Imaging Centers, Rehabilitation Centers Therapy Area: Open Surgery, Endovascular Therapy, Surgical Clipping, Embolization Delivery Mode: Invasive, Minimally Invasive, Robotic Surgery, Remote Monitoring |
| Companies Covered | Medtronic, Stryker, Terumo Corporation, B Braun, Integra LifeSciences, Johnson and Johnson MedTech, MicroPort Scientific Corporation, Penumbra, MicroVention, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cerebral Aneurysm Management Market Strategic Shifts
Device-level convergence between flow diversion and intrasaccular occlusion is collapsing the historical segmentation between neck reconstruction and dome filling strategies.
Intrasaccular flow disruptors are hybridizing mechanical scaffolding with hemodynamic damping functions, enabling treatment of bifurcation aneurysms previously excluded from flow diversion candidacy. Academic medical centers in the United States are piloting these platforms in complex posterior circulation cases, compressing the addressable patient pool for traditional coiling.
MDR Article 120 transitional provisions are forcing legacy device recertification, diverting R&D budgets toward clinical evidence generation rather than novel platform development. European manufacturers are responding by consolidating technical documentation and streamlining quality management systems ahead of 2028 deadlines.
Hospital purchasing committees are unbundling device procurement from procedural service contracts, shifting negotiation leverage toward bulk coil and stent purchasing agreements. This pattern concentrates in United States integrated delivery networks where standardized physician preference cards are replacing individual operator-driven selection.
Cerebral Aneurysm Management Market Segmentation
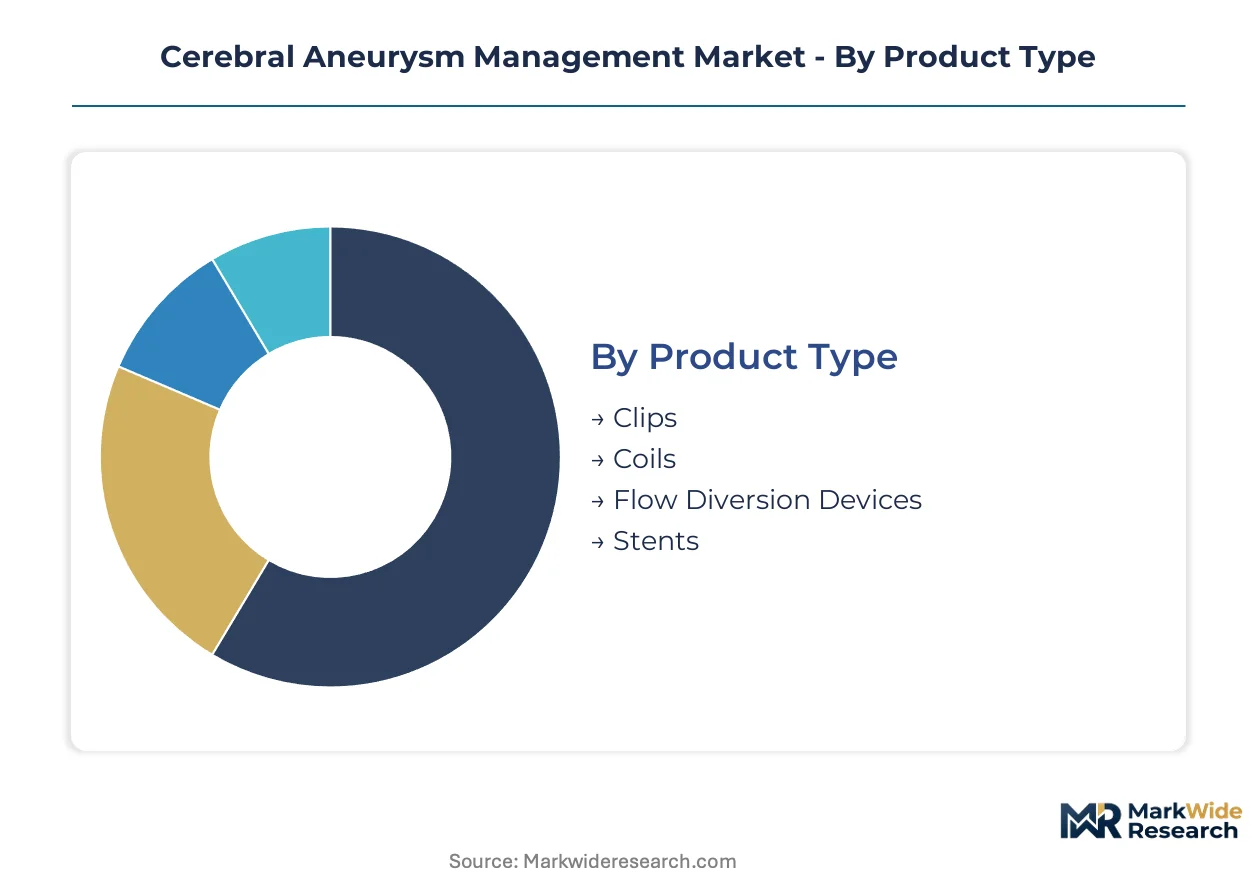
Segmentation in cerebral aneurysm management reveals how technology maturation, reimbursement structures, and procedural site economics allocate demand across implantable devices and delivery settings. Understanding these divides enables targeted portfolio positioning and capital deployment decisions.
Product Type:
Mature metallic implants anchor hospital purchasing budgets while emerging bioresorbable platforms reshape long-term treatment paradigms.
- Clips:Titanium and cobalt-chromium alloy configurations applied during craniotomy for definitive neck closure. Demand concentrates in United States academic medical centers where open surgical fellowship training persists, constrained by referral pattern shifts toward catheter-based alternatives.
- Coils:Platinum-titanium alloy detachable embolics delivered through microcatheters to induce thrombosis within the aneurysm sac. Volume leadership sits with wide-necked saccular lesions under 10mm where deployment speed and device cost efficiency matter most.
- Flow Diversion Devices:Nickel-titanium braided constructs that reconstruct parent vessel hemodynamics. Pipeline embolization devices command premium positioning in large or giant aneurysms at the internal carotid artery.
- Stents:Laser-cut or braided intraluminal scaffolds that maintain parent vessel patency during coil deployment. Neuroform and Enterprise stent families support adjunctive coiling in wide-necked morphologies.
Coils retain volume leadership; flow diversion devices hold the steepest expansion curve.
End User:
Capital intensity and regulatory accreditation requirements stratify procedural sites into distinct procurement and service models.
- Hospitals:Tertiary care centers with dedicated neurointerventional suites and 24/7 stroke team activation. Comprehensive stroke center certification in the United States mandates minimum annual case volumes and specialized imaging infrastructure.
- Specialized Clinics:Ambulatory surgical centers and dedicated neurovascular practices performing elective unruptured aneurysm interventions. Concentrated in metropolitan United States markets where same-day discharge protocols reduce total episode cost.
- Imaging Centers:Diagnostic facilities providing MR angiography and CT angiography for aneurysm detection and surveillance. Serve as referral feeders to intervention-capable hospitals.
- Rehabilitation Centers:Post-acute facilities managing subarachnoid hemorrhage recovery and neurological deficit rehabilitation. Device procurement limited to monitoring and supportive care equipment.
Hospitals command the capital-intensive high-acuity segment; specialized clinics are climbing fastest toward volume parity.
Therapy Area:
Procedural modality selection hinges on aneurysm morphology, rupture status, and operator training pipeline availability.
- Open Surgery:Craniotomy-based clipping with direct visualization of the aneurysm neck. Residual demand centers on complex middle cerebral artery bifurcations where endovascular access geometry proves unfavorable.
- Endovascular Therapy:Catheter-based intervention encompassing coiling, stent-assisted coiling, and flow diversion. Dominates unruptured anterior circulation aneurysms where femoral access permits rapid lesion engagement.
- Surgical Clipping:Microsurgical technique with temporary parent vessel occlusion and definitive clip application. Fellowship training throughput constraints limit expansion in the United States.
- Embolization:Coil or liquid embolic deployment to achieve intra-aneurysmal thrombosis. Liquid embolics address fusiform and dissecting aneurysms excluded from coil candidacy.
Endovascular therapy anchors procedural volume; embolization is gaining share fastest in fusiform morphologies.
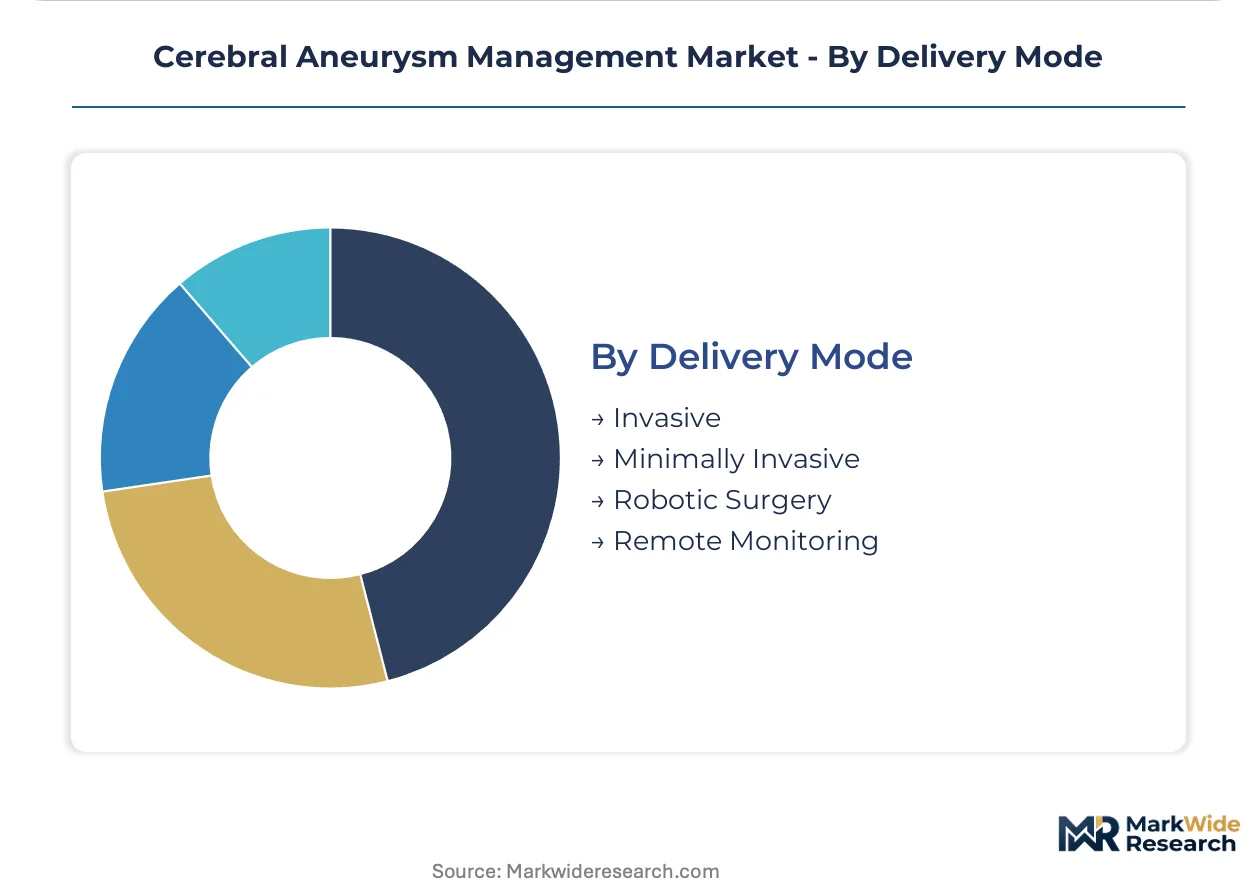
Delivery Mode:
Invasiveness spectrum and automation integration determine recovery timelines, reimbursement tiers, and capital equipment requirements.
- Invasive:Open craniotomy with brain retraction and direct vascular access. ICU occupancy and length-of-stay economics disadvantage this modality against catheter alternatives.
- Minimally Invasive:Transfemoral or transradial catheter navigation without skull breach. Radial access adoption in the United States reduces groin complications and accelerates ambulation.
- Robotic Surgery:Telemanipulation platforms for microsurgical dissection and clip application. Early adoption in selected United States academic centers for tremor filtration and motion scaling.
- Remote Monitoring:Digital surveillance of unruptured aneurysms via serial imaging and patient-reported outcomes. Expands the addressable pool of conservatively managed lesions.
Minimally invasive delivery commands the dominant share; robotic surgery is expanding most quickly in academic training environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of platinum-titanium alloy coils and nickel-titanium flow diverters originate predominantly from United States and German manufacturing clusters, while import demand concentrates in tertiary hospital systems across India and Southeast Asia expanding neurointerventional capacity.
United States
Comprehensive stroke center certification mandates from The Joint Commission drive hospital capital allocation toward hybrid angiography suites. FDA breakthrough device designations compress premarket approval timelines for next-generation flow diverters. The Texas Medical Center in Houston anchors the nation's highest procedural volume for endovascular aneurysm repair.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia maintain Europe's densest concentration of neurointerventional fellowship programs. EU MDR Article 120 transitional provisions force legacy device recertification, diverting manufacturer resources toward clinical evidence generation. The Munich cluster hosts specialized nitinol processing facilities serving flow diverter production.
Japan
Aging demographics and PMDA expedited review pathways for hemorrhagic stroke devices accelerate market entry relative to standard PMA routes. METI funding supports domestic development of robotic microsurgical platforms. The Kanto region around Tokyo concentrates academic medical center pilot programs for intrasaccular flow disruptors.
India
Private hospital chains in Mumbai and Delhi undertake greenfield neurointerventional suite installations, creating equipment placement windows for catheter and coil suppliers. CDSCO medical device rules align with global harmonization initiatives, streamlining import registration. The Delhi-NCR corridor sees fastest growth in elective unruptured aneurysm interventions.
China
NMPA innovation pathway designations accelerate domestic approval of flow diversion technologies previously limited to imported devices. Provincial health commissions in Jiangsu and Guangdong expand stroke center networks beyond tier-one cities. The Yangtze River Delta cluster concentrates contract manufacturing for microcatheter components.
Cerebral Aneurysm Management Market Competitive Environment
On the supply side, the industry is consolidating around diversified medtech conglomerates with dedicated neurovascular divisions, while specialized interventional firms occupy defensible niches in aspiration and access technologies. Two strategic archetypes dominate: integrated hemorrhagic stroke platforms spanning coils through flow diversion, and focused aspiration-integrated workflow specialists. Competitive moves center on portfolio diversification into adjacent hemorrhagic stroke devices and strategic partnerships to secure nitinol supply chain access.
Within the integrated platform tier, Medtronic and Stryker exemplify diversified conglomerate positioning across the full intervention spectrum, while Penumbra occupies a distinct position among workflow-integrated specialists. These three anchors reflect how scale-driven manufacturing and focused technological differentiation coexist as viable competitive postures in catheter-based aneurysm management.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Terumo Corporation |
| B Braun |
| Integra LifeSciences |
| Johnson and Johnson MedTech |
| MicroPort Scientific Corporation |
| Penumbra |
| MicroVention |
| Others |
Value Chain & Pricing Dynamics
German nitinol processing facilities and United States platinum-titanium alloy foundries concentrate upstream supply, anchoring margin pools with flow diverter manufacturers and high-volume coil suppliers who command premium positioning in hospital purchasing negotiations.
Pricing Analysis
Hospital purchasing committees anchor three-tier pricing structure across premium, standard, and economy levels for cerebral aneurysm devices. Price differentiation hinges on FDA breakthrough designation status and procedural volume commitments through GPO contracts. Cost compression in standard-tier detachable coils is intensifying because precious metal input volatility squeezes manufacturer margins. Academic medical centers show least price sensitivity due to training mission requirements, while ambulatory surgical centers negotiate aggressively on same-day discharge protocol bundles.
Supply Chain Analysis
Export control restrictions on nickel-titanium shape-memory alloy processing technology limit flow diverter manufacturing expansion outside established cleanroom clusters. Supply concentrates in Germany, the United States, and Japan for nitinol braiding and laser-cut stent fabrication. Raw material dependencies include platinum-rhodium alloys from South African mining operations and medical-grade nitinol wire from specialized melt facilities. Single-source vulnerability in nitinol processing creates supply chain risk. Distribution runs through hospital GPO contracts and direct manufacturer agreements with comprehensive stroke centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
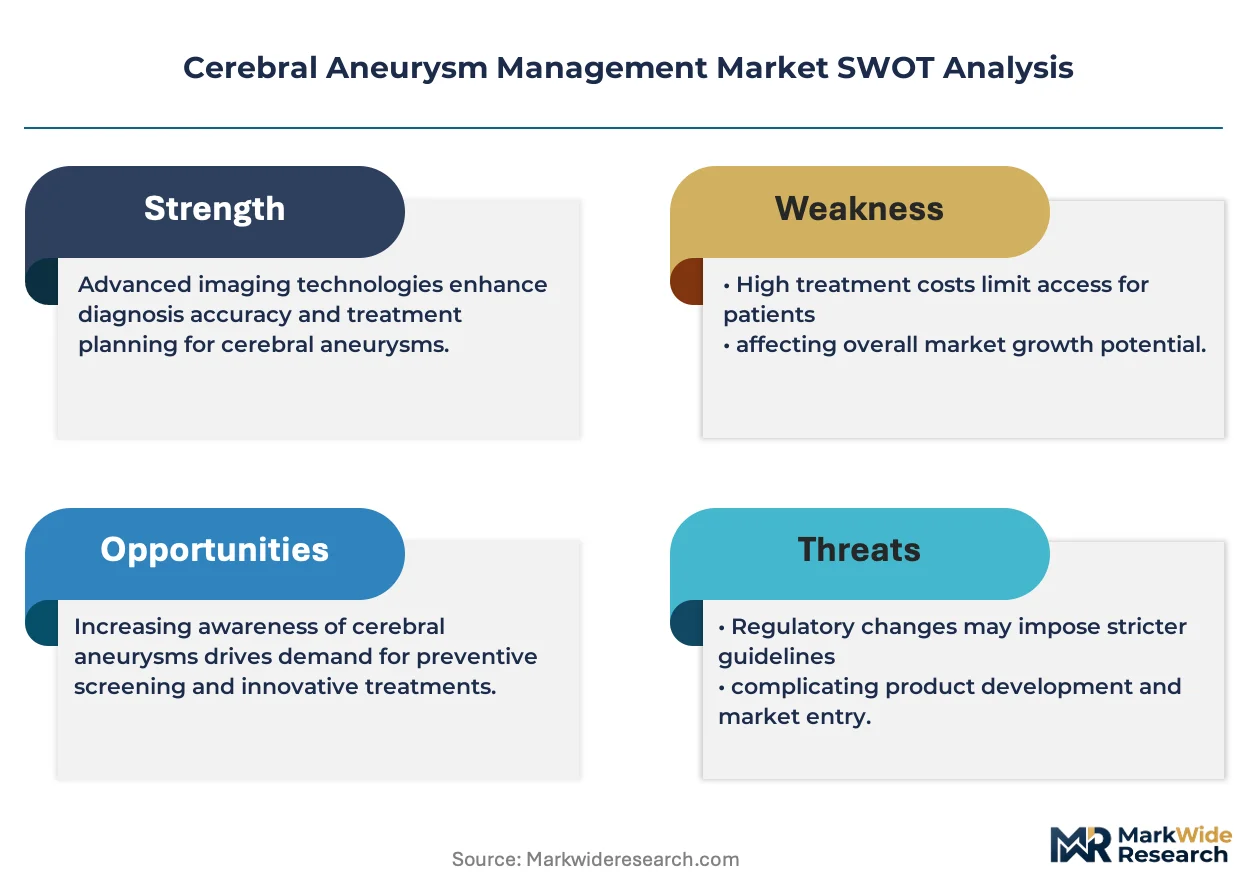
Cerebral aneurysm management operates as a regulatory entrenchment story where FDA premarket approval pathways and EU MDR clinical evidence requirements create switching costs that protect incumbent positions against unproven substitutes.
For Market Incumbents: Harden market position by deepening backward integration into nitinol wire drawing and platinum alloy sourcing to offset precious metal volatility. Secure exclusive supply agreements with comprehensive stroke centers facing certification-mandated case volume requirements. The threat of bioresorbable flow modulation platforms demands accelerated R&D investment in hybrid scaffold technologies before endothelialization data matures. For New Entrants and Emerging Players: Greenfield neurointerventional suites in Mumbai and Delhi private hospital chains represent the most penetrable entry point for catheter and coil suppliers seeking first-mover equipment placement. Japan's PMDA expedited review pathway for hemorrhagic stroke devices offers faster market access than standard PMA routes for novel platforms. A focused go-to-market strategy partnering with regional distributors who hold CDSCO import licenses bypasses direct regulatory navigation costs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed neurovascular device portfolios accumulated during prior consolidation waves. Long-term viability over the five-to-ten year window depends on flow diversion technology expanding into bifurcation aneurysm indications previously excluded from candidacy. The signal to watch is intrasaccular flow disruptor clinical trial readouts from academic medical centers, which would indicate platform substitution risk for traditional coiling volumes.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated premarket approval timelines compress commercialization cycles for flow diversion platforms. |
| EU MDR Technical Documentation Consolidation | Streamlined quality management systems ahead of Article 120 deadlines preserve European market access. |
| Comprehensive Stroke Center Partnership | Exclusive supply agreements with Joint Commission-certified hospitals lock in procedural volume commitments. |
| Nitinol Supply Chain Security | Captive wire drawing and braiding capabilities insulate margins against shape-memory alloy price volatility. |
| Bioresorbable Scaffold Development | Magnesium-based flow modulation hybridizes permanent implant durability with temporary support functions. |
Study Parameters
Two parallel data streams informed the analysis: structured conversations with neurointerventionalists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) and PMA filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement records. Bottom-up procedural volume estimates triangulated against top-down device shipment data from nitinol processing and platinum alloy suppliers.
Forecast inputs include modeling across product type segmentation, end-user site economics, procedural modality selection, and geographic regulatory cluster variations. CAGRs were derived from procedural volume trajectories, device ASP trends, and penetration rate assumptions for emerging platforms. Industry-specific forecast inputs encompass stroke center certification mandates, neurointerventionalist fellowship training throughput, and reimbursement parity dynamics between clipping and coiling procedures.
Practitioners should monitor PMDA breakthrough designation grants, EU MDR recertification completion rates, and intrasaccular flow disruptor pivotal trial outcomes for early signals of competitive inflection. Material shifts in dual antiplatelet therapy protocol duration or nitinol export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Neurology Digital Therapeutics Market
Neurology
Ulnar Nerve Treatment Market
Neurology
Neurocutaneous Disorders Market
Neurology
Canada Neurology Devices Market
Neurology
Moyamoya Disease Market
Neurology
North America Neurology Monitoring Market
Neurology
United Kingdom Neurology Devices Market
Neurology
Global Neuromarketing Market
Neurology
Cluster Headache Syndrome Market
Neurology
Mild Cognitive Impairment Market
Neurology
Brain Tumor Diagnosis and Treatments Market
Neurology
Hydrocephalus Market
Neurology
Pediatric Neurology Device Market
Neurology
Global Neuroblastoma Market
Neurology
3D Neuroscience Market
Neurology
Cervical Dystonia Treatment Market