
 Peripherally Inserted Central Catheters Market | 2026-2036
Peripherally Inserted Central Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Peripherally Inserted Central Catheters Market Outlook
Hospital procurement consortia is reconfiguring how peripherally inserted central catheters reach end users, with group purchasing organizations consolidating vendor panels and squeezing list prices. Becton, Dickinson and Company leverages its broad vascular access portfolio to secure multi-year supply agreements with integrated delivery networks. Teleflex Incorporated anchors its position through dedicated PICC sales specialists embedded in catheterization labs. AngioDynamics competes by specializing in antimicrobial-coated lines that command preference in infection-control committees.
Peripherally inserted central catheters are thin, flexible vascular access devices inserted through peripheral veins and advanced until the catheter tip terminates in the superior vena cava or cavoatrial junction, typically constructed from silicone or polyurethane in French sizes ranging from 3 to 6 Fr and designed for intermediate to long-term infusion therapy. Multi-lumen configurations now dominate new installations as clinicians prioritize simultaneous incompatible infusions, while silicone material formulations sustain premium positioning in neonatal and long-term care settings where biocompatibility demands are most stringent. The chemotherapy application segment leads absolute volume, yet home care end users represent the fastest-growing placement setting as payors push infusion services beyond hospital walls.
FDA 510(k) premarket notification requirements and ISO 10555 intravascular catheter standards jointly shape product design specifications, materials testing protocols, and clinical validation burdens for manufacturers seeking US market access. The Centers for Medicare & Medicaid Services reimbursement coding for PICC insertion and maintenance directly influences hospital purchasing frequency and device selection criteria. Stakeholders must monitor evolving antimicrobial resistance data and corresponding FDA guidance updates to align coating investments with clinical evidence thresholds.
Market Dynamics
Hospital procurement consortia are consolidating vendor panels and squeezing list prices, forcing manufacturers to defend margin position through multi-year supply agreements and embedded specialist teams rather than transactional sales.
Growth Catalysts
- Outpatient infusion protocols:United States payors are pushing chemotherapy and antibiotic administration beyond hospital walls, expanding home care placement volumes for extended therapy regimens.
- Antimicrobial coating technology:Chlorhexidine-silver formulations are commanding preference in infection-control committees, driving replacement cycles in high-acuity settings.
- FDA 510(k) streamlining:Updated clearance pathways for vascular access devices are compressing time-to-market for next-generation catheter designs.
Market Restraints
- Polyurethane raw material concentration:Supply of medical-grade elastomers concentrates among a limited supplier base, exposing manufacturers to input cost volatility.
- Catheter-related bloodstream infection liability:Malpractice exposure from CLABSI events creates defensive prescribing patterns and extended documentation burdens.
- Peripheral IV catheter substitution:Midline alternatives are capturing shorter-duration infusion cases, compressing addressable volume for traditional PICC lines.
Strategic Opportunities
- Neonatal biocompatibility positioning:Silicone material formulations command premium placement in pediatric intensive care units where vessel fragility demands specialized construction.
- Integrated delivery network capture:Multi-hospital systems in Texas and Florida are consolidating vascular access purchasing, creating vendor consolidation windows.
- Remote monitoring convergence:RFID-embedded catheters combined with wireless bedside sensors are enabling real-time tip position verification without fluoroscopy.
Industry Challenges
- Interventional radiology staffing scarcity:Placement volume growth outpaces trained operator supply, creating scheduling bottlenecks and delayed therapy initiation.
- Antimicrobial resistance surveillance alignment:Manufacturers must continuously recalibrate coating investments against evolving FDA guidance and CDC resistance data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peripherally Inserted Central Catheters Market |
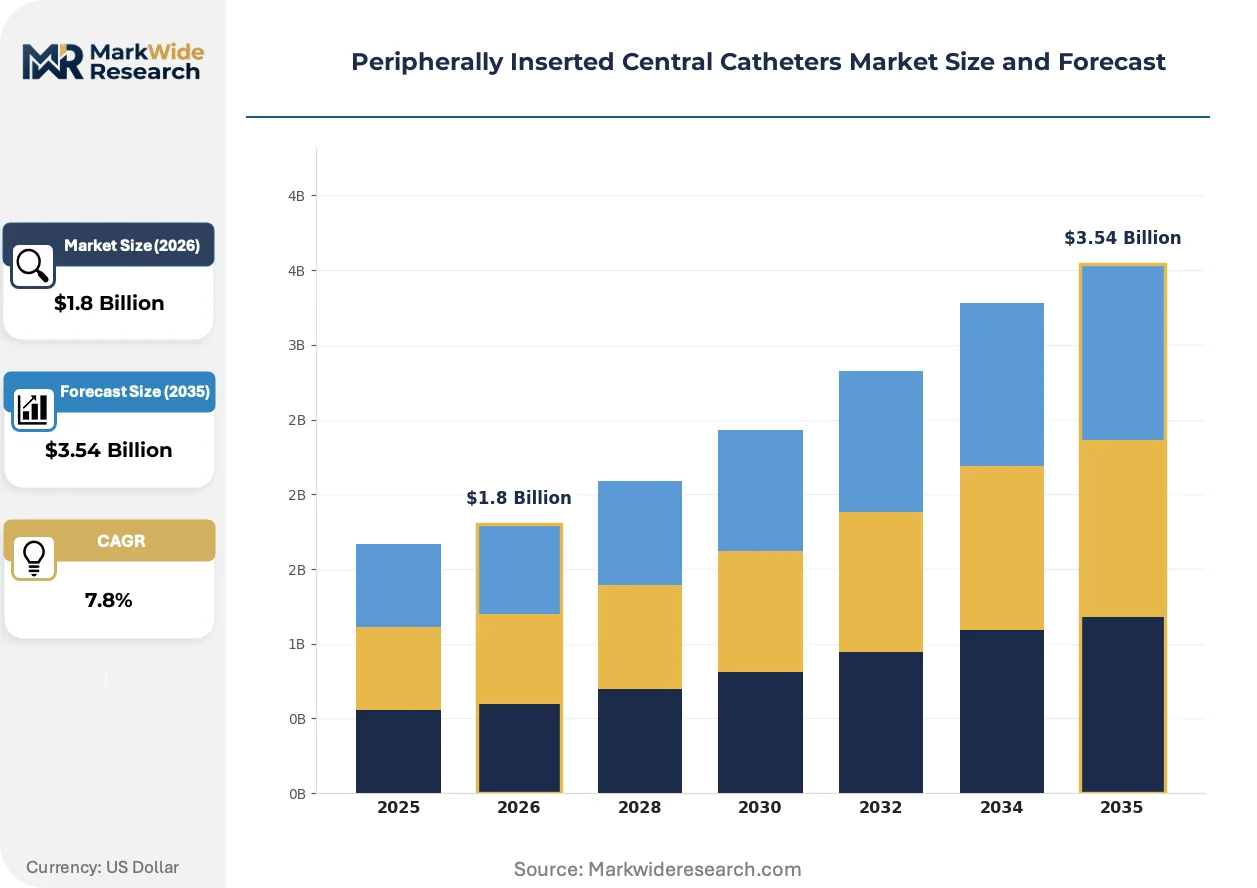
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
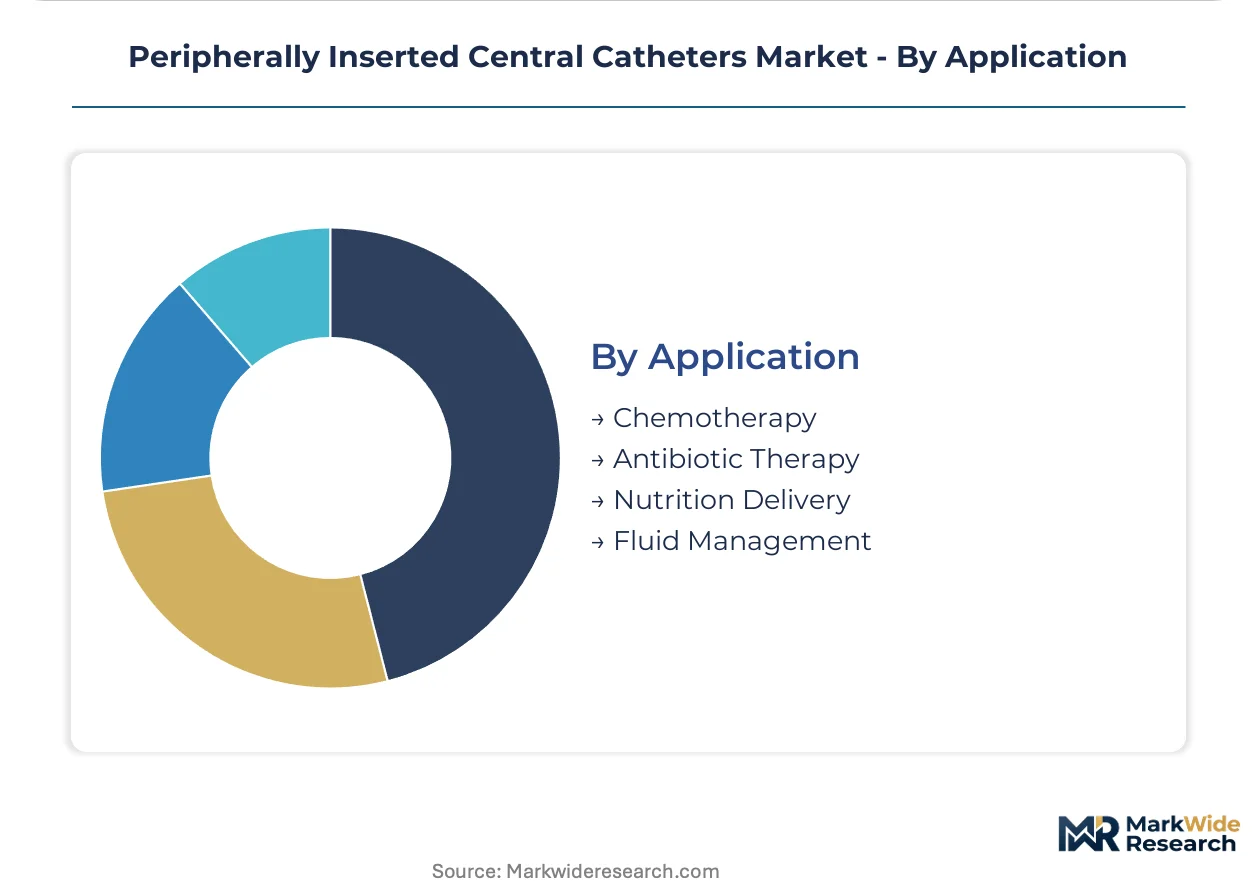
| Segmentation | Product Type: Single-Lumen, Double-Lumen, Triple-Lumen, Multi-Lumen Material: Silicone, Polyurethane, PVC, PET End User: Hospitals, Clinics, Home Care, Long-Term Care Facilities Application: Chemotherapy, Antibiotic Therapy, Nutrition Delivery, Fluid Management |
| Companies Covered | Becton, Dickinson and Company, Teleflex Incorporated, AngioDynamics, B. Braun Melsungen AG, ICU Medical, Cook Medical, Cardinal Health, Argon Medical Devices, Access Vascular, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peripherally Inserted Central Catheters Market Strategic Shifts
Catheter construction and placement protocols are undergoing material-driven transformation, with polyurethane formulations and integrated visualization technologies displacing legacy silicone-only designs in high-volume settings.
Power-injectable polyurethane catheters rated for CT contrast delivery are rendering obsolete single-purpose silicone lines that cannot withstand high-pressure injection protocols. Interventional radiology departments in tertiary hospitals are adopting these dual-purpose devices at accelerating rates. The technology is compressing capital equipment requirements by eliminating dedicated CT port investments.
FDA guidance on antimicrobial device coatings is tightening evidentiary standards for claims substantiation, requiring manufacturers to generate prospective clinical data rather than laboratory susceptibility studies alone. The agency's 2023 safety communication on chlorhexidine allergies is forcing reformulation strategies. High-acuity hospitals in California and New York are already demanding alternative coating chemistries.
Site-of-care economics are driving catheter selection criteria, with hospital-at-home programs prioritizing devices that minimize maintenance complexity and reduce nursing visit frequency. Medicare's expanded hospital-at-home waivers are accelerating this behavioral shift. Home infusion providers in the Midwest are consolidating purchasing around simplified insertion kits with integrated securement.
Peripherally Inserted Central Catheters Market Segmentation
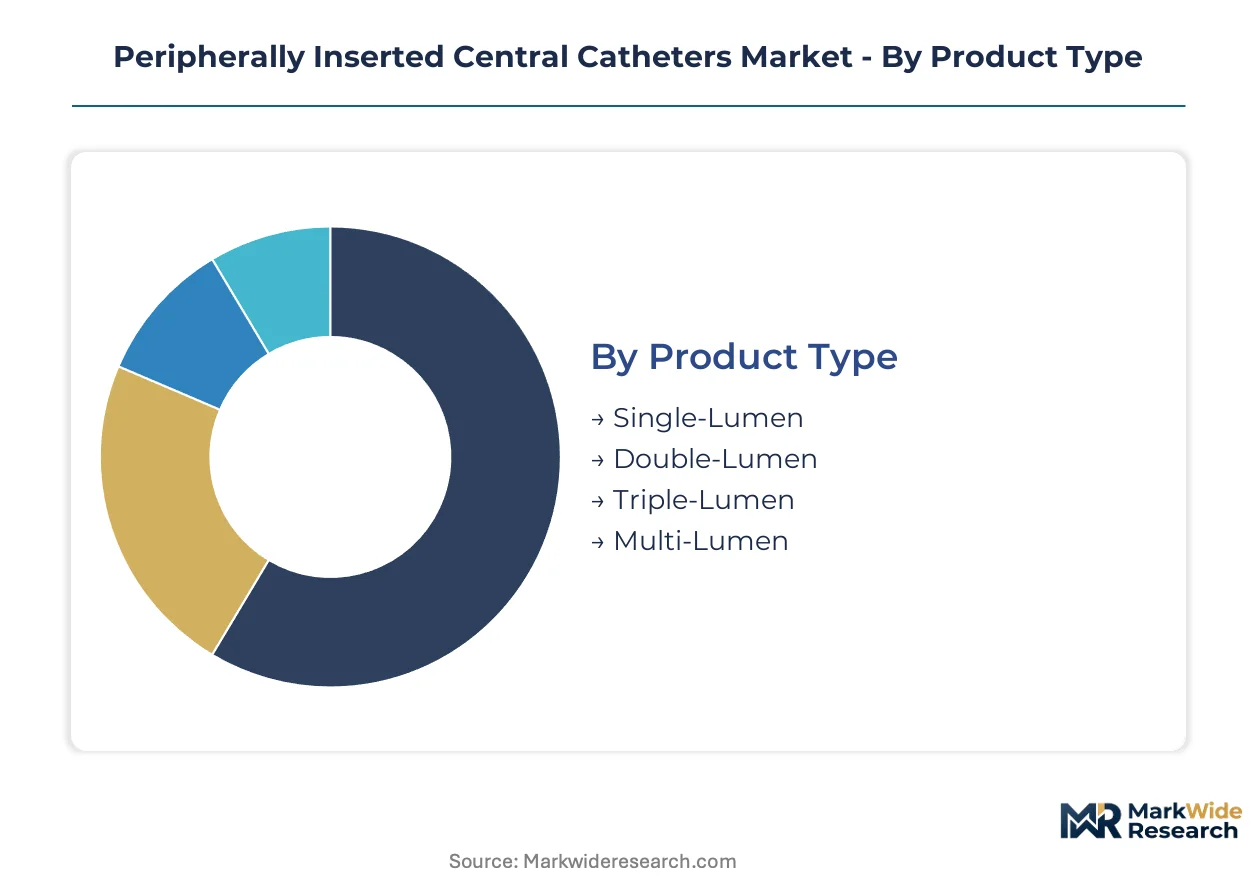
Catheter configuration and material selection directly determine reimbursement eligibility, placement setting suitability, and infection risk profiles across patient populations. Manufacturers align R&D pipelines with the specific technical demands of high-volume therapy categories rather than pursuing one-size-fits-all platforms.
Product Type:
Cost tier differentiation separates basic vascular access from premium multi-channel configurations capable of simultaneous incompatible infusions.
- Single-Lumen:Constructed as a single-channel catheter for dedicated infusion lines, this configuration minimizes vessel trauma in peripheral vein insertion. Demand concentrates in short-term antibiotic therapy within community hospitals where cost containment dominates procurement criteria.
- Double-Lumen:Dual independent channels enable concurrent medication delivery and blood sampling without line crossover. Oncology departments in the United States specify this configuration for intermediate chemotherapy regimens requiring simultaneous hydration and drug infusion.
- Triple-Lumen:Three separate lumens support complex polypharmacy in intensive care settings.
- Multi-Lumen:Four or more channels address the most demanding infusion protocols in tertiary academic medical centers.
Double-Lumen commands the established base. The steepest expansion runs through Multi-Lumen configurations as ICU complexity intensifies.
Material:
Application requirements dictate material selection, with biocompatibility thresholds varying sharply between neonatal intensive care and adult high-pressure injection scenarios.
- Silicone:This elastomer offers superior biocompatibility and reduced thrombogenicity through its soft, pliable structure that conforms to vessel walls. Neonatal intensive care units in California and New York specify silicone formulations exclusively for premature infants where vessel fragility demands minimal mechanical irritation.
- Polyurethane:Higher tensile strength enables thinner wall construction and larger internal diameters at equivalent French sizes. Interventional radiology departments favor this material for power-injectable lines that must withstand CT contrast delivery pressures.
- PVC:Lower-cost thermoplastic serves limited-duration applications in cost-constrained settings.
- PET:Polyester-based formulations address specialized securement and reinforcement applications.
Silicone retains entrenched positioning in pediatric segments. Polyurethane is gaining share fastest as power-injection compatibility becomes standard.
End User:
Customer type determines purchasing authority, with procurement centralization varying across integrated delivery networks versus independent facilities.
- Hospitals:Acute care facilities generate the dominant placement volume through emergency departments, oncology units, and intensive care settings. Hospital-based interventional radiology departments in Texas and Florida anchor utilization as these states expand integrated delivery network consolidation.
- Home Care:Skilled nursing services and home infusion providers manage catheter maintenance for extended therapy regimens. Medicare hospital-at-home waivers in the United States are accelerating placement volume as payors push services beyond traditional facility walls.
- Clinics:Outpatient settings handle initial placement for planned therapy initiation.
- Long-Term Care Facilities:Extended care environments manage chronic vascular access for residents requiring ongoing infusion.
Hospitals retain the volume base. Home Care demonstrates the steepest upward trajectory as site-of-care economics shift.
Application:
Therapy duration and agent toxicity dictate catheter specification, with cytotoxic chemotherapy demanding the most rigorous material and placement standards.
- Chemotherapy:Cytotoxic drug delivery requires catheters capable of withstanding vesicant agents and frequent blood sampling without degradation. Hospital-based oncology departments in the United States specify PICC lines for extended regimens exceeding peripheral IV tolerance, with multi-lumen configurations enabling simultaneous pre-medication and drug infusion.
- Antibiotic Therapy:Extended antimicrobial courses for osteomyelitis or endocarditis require durable access for weeks to months. Home infusion providers concentrate demand here as payors mandate outpatient completion of therapy courses.
- Nutrition Delivery:Parenteral nutrition support in malabsorption or intestinal failure cases.
- Fluid Management:Large-volume resuscitation and electrolyte correction in critical care.
Chemotherapy anchors the installed base. Antibiotic Therapy climbs fastest as outpatient parenteral antimicrobial protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare hospital-at-home waivers and outpatient infusion reimbursement reforms are redistributing catheter placement volumes across national healthcare systems. Regulatory pathways for antimicrobial device coatings vary sharply between jurisdictions, creating divergent compliance burdens for multinational manufacturers.
United States
FDA 510(k) clearance pathways for vascular access devices compress time-to-market for next-generation catheter designs. The Centers for Medicare & Medicaid Services reimbursement coding for PICC insertion directly influences hospital purchasing frequency and device selection criteria. Texas and Florida anchor utilization growth as these states expand integrated delivery network consolidation and interventional radiology capacity.
Germany
EMA medical device regulations and the EU Medical Device Regulation (MDR) implementation impose stringent clinical validation requirements on antimicrobial coating claims. The country's statutory health insurance system maintains rigorous cost-effectiveness assessments for vascular access devices. Bavaria and Baden-Württemberg concentrate catheter manufacturing and hospital procurement decision-making.
Japan
PMDA marketing authorization requirements for intravascular catheters demand extensive biocompatibility testing protocols. METI industrial policy supports domestic production of high-performance medical elastomers to reduce import dependency. The Kanto region around Tokyo dominates hospital procurement volumes and specialist interventional radiology training programs.
China
NMPA registration requirements for imported vascular access devices create extended approval timelines for foreign manufacturers. The country's dual carbon goals are pressuring medical device producers toward sustainable material sourcing and manufacturing processes. The Yangtze River Delta and Pearl River Delta clusters concentrate domestic catheter production and tertiary hospital infrastructure.
United Kingdom
NICE technology appraisals for vascular access devices influence NHS procurement frameworks and clinical guideline development. The Medicines and Healthcare products Regulatory Agency (MHRA) post-Brexit regulatory pathway diverges from EU MDR implementation timelines. London and the Southeast concentrate specialist oncology centers driving multi-lumen catheter demand.
Peripherally Inserted Central Catheters Market Competitive Environment
On the supply side, the industry is consolidating around integrated vascular access portfolios and embedded specialist sales forces rather than transactional distribution. Tiered competitive positioning separates full-line manufacturers with broad hospital contracting leverage from mid-scale specialists commanding premium positioning through antimicrobial differentiation. Strategic archetypes include diversified medical technology conglomerates, dedicated vascular access specialists, and emerging technology-focused entrants. Dominant competitive moves encompass multi-year supply agreements with integrated delivery networks and dedicated specialist teams embedded in catheterization labs.
Among established diversified manufacturers, Becton, Dickinson and Company and Teleflex Incorporated exemplify the full-line archetype with broad vascular access portfolios securing hospital system-level contracts. AngioDynamics occupies a specialist position representing the antimicrobial-coated segment that commands preference in infection-control committees. These three entities anchor the competitive structure through contrasting approaches to hospital procurement engagement.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Teleflex Incorporated |
| AngioDynamics |
| B. Braun Melsungen AG |
| ICU Medical |
| Cook Medical |
| Cardinal Health |
| Argon Medical Devices |
| Access Vascular |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta's polyurethane elastomer production capacity directly constrains downstream catheter pricing power, with medical-grade polymer supply tightness translating into input cost pass-through pressure for finished device manufacturers serving United States hospital systems.
Pricing Analysis
Certification level creates the primary spread across catheter price tiers, with FDA 510(k) clearance and ISO 10555 compliance anchoring premium positioning against CE-marked alternatives. Three-tier pricing structure across premium antimicrobial-coated, standard multi-lumen, and economy single-lumen configurations reflects clinical validation depth. Price erosion runs through standard polyurethane segments as group purchasing organizations consolidate vendor panels and compress list prices. Community hospital procurement committees exhibit highest price sensitivity, while pediatric intensive care units maintain lowest sensitivity due to biocompatibility mandates.
Supply Chain Analysis
Extended payment terms from United States integrated delivery networks now stretch to 90-120 days, forcing catheter manufacturers to deploy supply-chain finance facilities to bridge working capital gaps. Raw material sourcing draws from Germany for medical-grade polyurethane, China for silicone formulations, and the United States for antimicrobial coating chemistries. Single-source vulnerability concentrates in chlorhexidine-silver coating precursors following FDA safety communications on allergy risks. Distribution runs through group purchasing organization contracts directly into hospital materials management systems, bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation through integrated delivery networks in Texas and Florida has shifted bargaining power decisively toward buyers, compressing manufacturer margins and demanding multi-year contractual commitments as table stakes for market access.
For Market Incumbents: Build switching-cost moats through embedded PICC specialist teams stationed in catheterization labs, creating procedural dependency that transcends price competition. Deepen backward integration into medical-grade polyurethane compounding to defend against raw material volatility from limited German and Chinese supplier bases. Secure multi-year supply agreements with expanding integrated delivery networks before procurement windows close.
For New Entrants and Emerging Players: Build out antimicrobial coating alternative portfolios addressing chlorhexidine allergy concerns flagged in FDA 2023 safety communications, capturing replacement demand from California and New York infection-control committees. Target neonatal silicone segments where biocompatibility premiums sustain margin shelter from GPO price compression. Lead with simplified insertion kits designed for hospital-at-home nursing workflows.
For Investors and Strategic Acquirers: Long-term, this sits as a site-of-care migration play because Medicare hospital-at-home waivers are redistributing catheter placement volumes toward home infusion providers with distinct purchasing patterns. Acquisition targets should display antimicrobial coating differentiation or pediatric specialization. Monitor FDA guidance updates on coating evidentiary standards as inflection signals for R&D recalibration requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Reformulation | Addresses FDA 2023 chlorhexidine allergy safety communication and captures California hospital demand. |
| Hospital System Partnership | Secures multi-year supply agreements with Texas and Florida integrated delivery network consolidations. |
| Neonatal Silicone Specialization | Commands premium positioning in pediatric intensive care units with stringent biocompatibility requirements. |
| Home Care Insertion Kit Simplification | Aligns with Medicare hospital-at-home waivers pushing infusion services beyond traditional facility walls. |
| Power-Injectable Polyurethane Development | Displaces legacy silicone lines in interventional radiology departments adopting CT contrast compatibility. |
Study Parameters
Operator-level perspectives from interventional radiologists, hospital purchasing committee members, GPO contracts managers, and home infusion nursing directors anchored the qualitative base. Primary fieldwork combined with secondary validation from FDA 510(k) filings, CMS reimbursement coding databases, hospital procurement records, and antimicrobial resistance surveillance data. Bottom-up catheter placement volume estimates triangulated against top-down market sizing from manufacturer revenue disclosures.
Scenario-bracketing framed the analytical approach, with baseline, optimistic, and conservative trajectories modeled across the projection horizon. Segmentation dimensions included lumen configuration, material formulation, end-user setting, and application therapy type. CAGRs derived from regression analysis against demographic drivers, reimbursement policy shifts, and interventional radiology capacity expansion. Forecast inputs incorporated outpatient infusion protocol adoption rates and FDA antimicrobial coating guidance evolution.
Stress conditions across polyurethane raw material supply disruption, CLABSI liability litigation frequency, and midline catheter substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway stability and reimbursement continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Cardiac Arrest Treatment Market
Cardiovascular Devices
Fibromuscular Dysplasia Treatment Market
Cardiovascular Devices
Centrifugal Blood Pumps Market
Cardiovascular Devices
Global Percutaneous Coronary Intervention (PCI) Devices Market
Cardiovascular Devices
Perfusion Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Cardiovascular Needle Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
Cardiovascular Diagnostic and Monitoring Devices Market
Cardiovascular Devices
Global Intravascular Temperature Management Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Global Heart Valve Repair and Replacement Market
Cardiovascular Devices
Endovascular Aneurysm Repair Market