
 Shock Wave Therapy Devices Market | 2026-2036
Shock Wave Therapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Shock Wave Therapy Devices Market Intelligence
Expanded manufacturing capacity in Europe, particularly within Germany and Switzerland, is narrowing the technology gap between established and emerging device manufacturers. Storz Medical AG leverages its deep expertise in focused and radial shock wave systems. BTL Industries competes on a broad portfolio that includes physiotherapy and aesthetic applications. Zimmer MedizinSysteme sustains its market position through strong distribution networks in clinical settings.
Shock wave therapy devices generate acoustic waves to stimulate healing in targeted tissues, using principles like piezoelectric or electromagnetic energy to create high-pressure pulses. Their primary purpose is to treat musculoskeletal conditions and manage chronic pain. Radial devices hold a significant market share for general physiotherapy applications. However, focused devices, offering greater precision, are seeing accelerated adoption in hospitals and specialized orthopedic clinics.
Market access hinges on regulatory clearances such as the FDA's 510(k) pathway in the United States and the CE marking under the Medical Device Regulation (MDR) in Europe. These frameworks mandate stringent clinical data requirements for safety and efficacy, particularly for new therapeutic indications. Consequently, a key strategic decision for manufacturers involves balancing investment in costly clinical trials against the pursuit of approvals for established, lower-risk applications.
Market Dynamics
The primary tension shaping the market is the regulatory demand for rigorous clinical evidence, particularly under the EU's MDR, against the commercial push to expand shock wave therapy into novel, unproven therapeutic areas like cardiology and dermatology.
Growth Catalysts
- Expanding Orthopedic Use:Growing clinical acceptance for treating chronic tendinopathies and plantar fasciitis drives adoption in sports medicine and rehabilitation centers.
- Aging Demographics:An increasing prevalence of musculoskeletal disorders in aging populations, especially in developed countries like Germany and Japan, sustains demand for non-invasive pain management solutions.
- Piezoelectric Technology:The development of more compact and precise focused shock wave devices using piezoelectric crystals enhances treatment efficacy and enables portability, opening new clinical settings.
Market Restraints
- High Capital Cost:The significant initial investment for focused shock wave systems limits adoption to well-funded hospitals and specialized clinics, excluding smaller physiotherapy practices.
- Reimbursement Inconsistency:Patchy and variable reimbursement policies from public and private payers across the United States and Europe create financial uncertainty for providers.
- Technical Limitations:Radial shock wave devices, while more affordable, offer limited penetration depth, making them less effective for treating deeper tissue pathologies compared to focused systems.
Strategic Opportunities
- Emerging Therapeutic Fields:Untapped applications in urology for erectile dysfunction and in dermatology for wound healing and cellulite reduction present significant growth avenues.
- Veterinary Medicine:The adaptation of shock wave devices for equine and companion animal orthopedics is an underpenetrated market with strong potential.
- Asia-Pacific Expansion:Rising healthcare expenditure and an increasing number of private clinics in countries like South Korea and Australia offer new geographic markets for device manufacturers.
Industry Challenges
- Specialized Operator Training:Effective and safe device operation requires extensive training and a deep understanding of anatomy, creating a skills gap among clinicians.
- Lack of Protocol Standardization:A variance in treatment protocols for specific conditions leads to inconsistent clinical outcomes and complicates comparative efficacy studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shock Wave Therapy Devices Market |
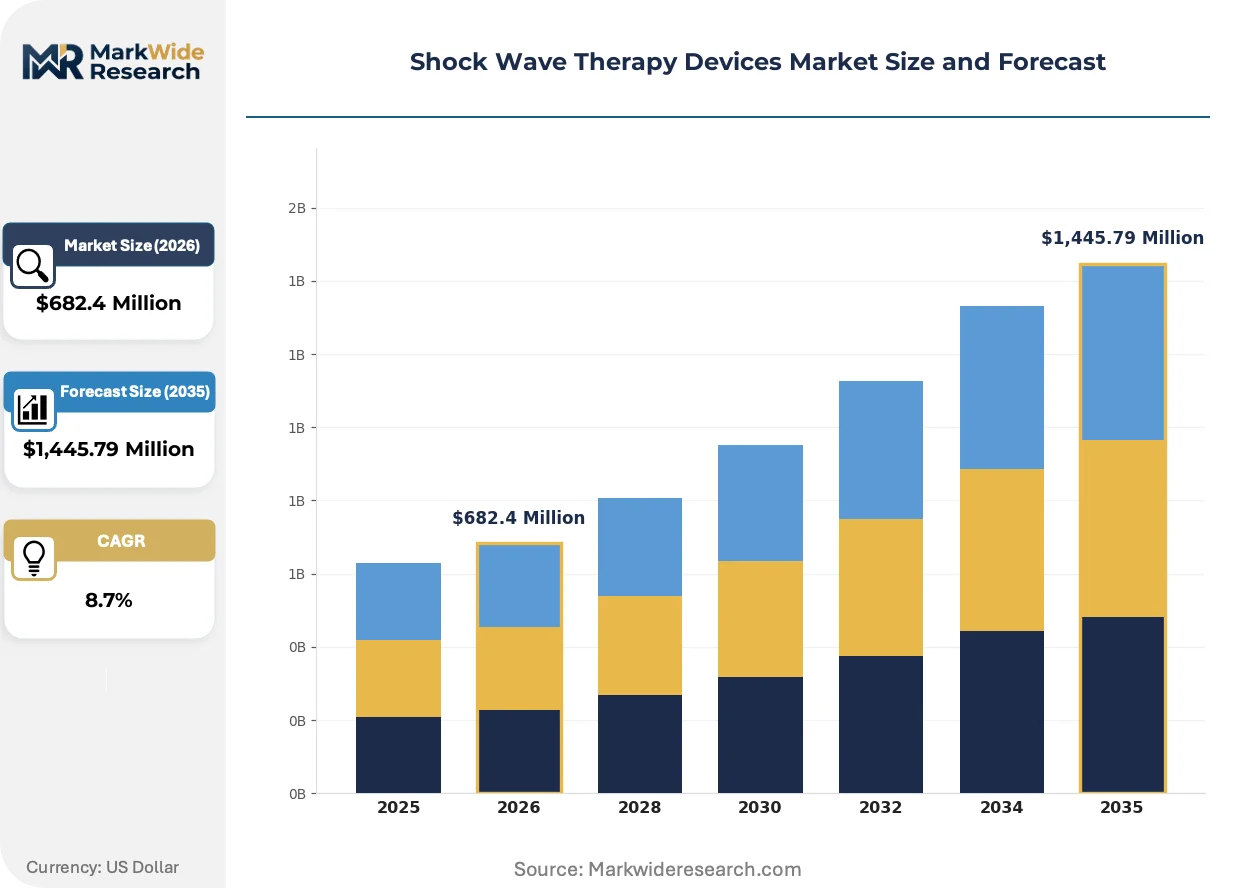
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,445.79 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Devices, Focused Devices, Accessories, Systems End User: Clinics, Rehabilitation Centers, Hospitals, Sports Facilities Technology: Electromagnetic, Pneumatic, Piezoelectric, Ultrasound Application: Orthopedic, Physiotherapy, Aesthetic, Podiatry |
| Companies Covered | Boston Scientific Corporation, BTL Industries, Dornier MedTech, EMS, Olympus Corporation, EDAP TMS, Storz Medical AG, Zimmer MedizinSysteme, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shock Wave Therapy Devices Market Strategic Shifts & Innovations
Application-specific device engineering and improved user ergonomics represent a significant market shift. This evolution prioritizes clinical precision and workflow efficiency over raw power, moving the technology into a wider range of healthcare environments.
Dual-modality systems now combine focused and radial shock wave applicators into a single console. Specialized orthopedic and sports medicine clinics are the primary adopters of this integrated approach. This technology is hybridizing treatment capabilities, allowing practitioners to address both superficial fascia and deep-seated trigger points with one device, thereby maximizing asset utilization and clinical versatility.
Europe’s Medical Device Regulation (MDR) imposes more stringent requirements for clinical evidence and post-market surveillance. The regulation forces manufacturers to generate robust data to substantiate therapeutic claims, increasing the cost and time of market access. This shift particularly impacts companies launching devices for new indications, compelling a more cautious, evidence-based expansion strategy.
A clear preference for portable, smaller-footprint devices is altering purchasing patterns among private practitioners. This trend disrupts the dominance of large, stationary systems traditionally sold to major hospitals. This demand is most visible in North American and European outpatient settings, where physiotherapy and chiropractic clinics value mobility and space efficiency.
Shock Wave Therapy Devices Market Segmentation
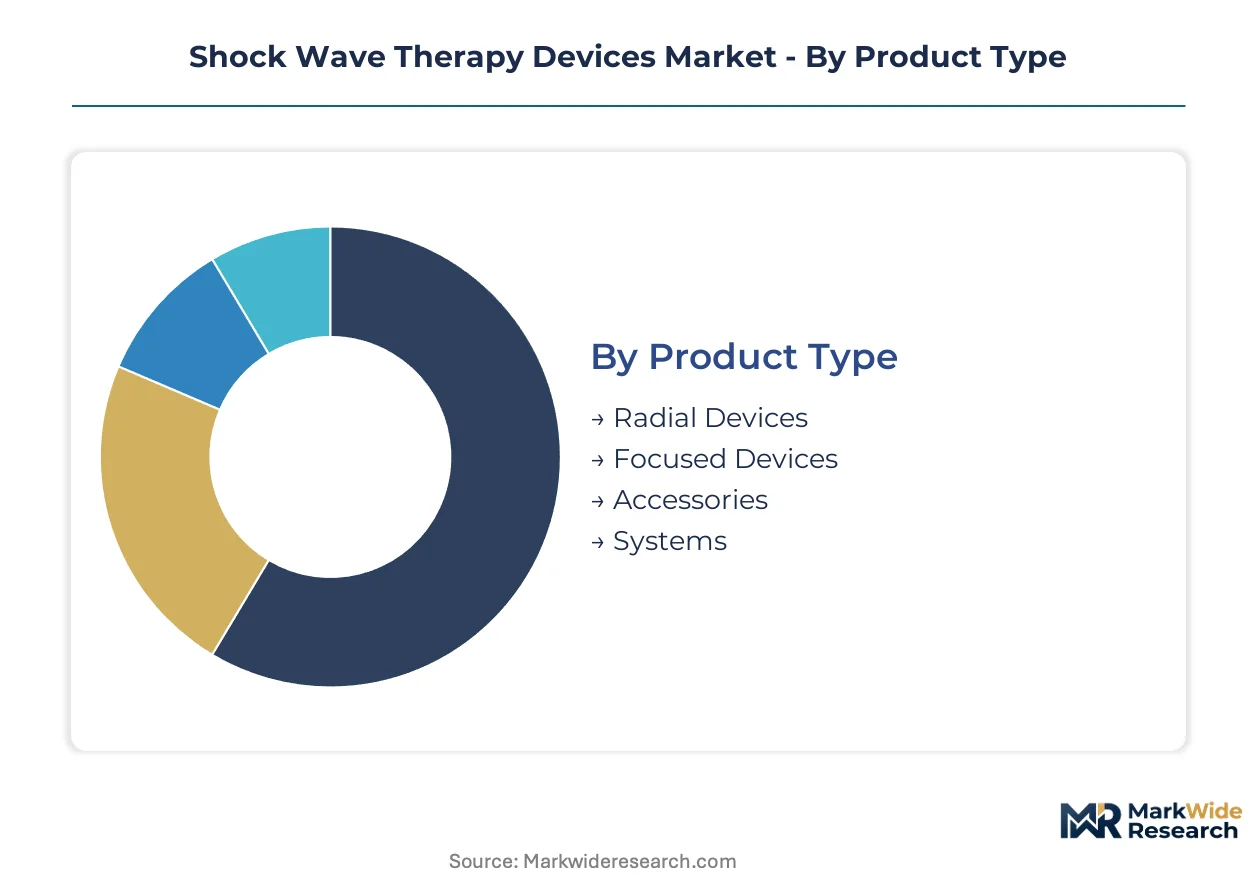
The shock wave therapy devices market segments by technology and clinical use. Understanding these categories helps manufacturers tailor product development and market penetration strategies. Device capabilities vary, impacting cost and accessibility for healthcare providers.
Product Type:
Product type segmentation reflects the diverse use-case spectrum, from general physiotherapy to precise orthopedic interventions. Each device type offers specific advantages in energy delivery and therapeutic reach.
- Focused Devices:These systems generate high-energy acoustic waves that converge at a specific depth, enabling precise treatment of deep tissue pathologies. Demand concentrates in specialized orthopedic clinics and hospitals across Germany and the United States, driven by their enhanced treatment efficacy for chronic tendinopathies.
- Radial Devices:Radial shock wave devices deliver lower energy, diverging waves over a broader surface area, making them suitable for superficial musculoskeletal conditions. Their market presence is strong in general physiotherapy practices and rehabilitation centers, favored for broad pain management applications.
- Accessories:This segment includes applicators, handpieces, gels, and disposable components essential for the operation and maintenance of shock wave therapy systems.
- Systems:Complete shock wave therapy systems integrate consoles, applicators, and software, often combining focused and radial modalities for versatile treatment.
The dominant share belongs to Radial Devices, while Focused Devices are closing the gap fastest.
End User:
End-user segmentation highlights how different customer types prioritize device features and investment. Healthcare facilities vary significantly in capital expenditure capacity and patient throughput.
- Hospitals:Large medical institutions with significant capital budgets acquire advanced focused shock wave systems for treating complex orthopedic and urological conditions. Demand is concentrated in major urban centers within Europe and North America, supporting diverse patient populations.
- Clinics:This category includes private physiotherapy, chiropractic, and pain management clinics, which often prefer portable and versatile shock wave devices. Investment here is driven by the need for cost-effective, non-invasive treatment options for common musculoskeletal complaints.
- Rehabilitation Centers:Rehabilitation centers utilize shock wave therapy for post-injury recovery and chronic pain management, integrating it into broader physical therapy programs.
- Sports Facilities:Professional sports organizations and training centers deploy shock wave devices for athlete recovery, injury prevention, and performance enhancement.
Hospitals represent the largest segment by revenue, with Clinics demonstrating the steepest expansion trajectory.
Technology:
This segmentation reveals how distinct technological principles generate acoustic waves, influencing device precision, power, and cost. Each method offers unique advantages for specific therapeutic outcomes.
- Piezoelectric:Piezoelectric shock wave devices utilize rapidly expanding and contracting ceramic crystals to generate focused acoustic pulses with high precision and compact design. The development of portable piezoelectric systems enhances treatment efficacy in outpatient settings across the United States.
- Electromagnetic:Electromagnetic shock wave generators employ a coil and a membrane to produce high-energy, focused acoustic waves, widely used in urology and orthopedics. This technology is a staple in many European hospitals due to its robust performance and established clinical history.
- Pneumatic:Pneumatic devices use compressed air to accelerate a projectile, generating radial shock waves suitable for superficial treatments.
- Ultrasound:Some advanced systems integrate therapeutic ultrasound capabilities with shock wave therapy, offering combined benefits for tissue healing and pain relief.
Electromagnetic technology maintains substantial market presence, while Piezoelectric technology is gaining share fastest.
Application:
The application segment outlines diverse therapeutic areas where shock wave devices are deployed, from musculoskeletal pain to dermatological conditions. This breadth reflects the technology's versatile biological effects.
- Orthopedic:This primary application addresses conditions like tendinopathies, non-union fractures, and plantar fasciitis, driving significant device adoption in sports medicine. Expanding clinical acceptance for orthopedic use, particularly in Germany and Japan, sustains demand for non-invasive solutions.
- Physiotherapy:Shock wave therapy is integrated into physiotherapy practices for pain management, muscle relaxation, and accelerating rehabilitation from various musculoskeletal injuries. General physiotherapy clinics in the United States and Australia increasingly adopt these devices for broader patient care.
- Aesthetic:Aesthetic medicine uses devices for cellulite reduction, skin tightening, and body contouring, representing an expanding niche market segment.
- Podiatry:Podiatrists utilize shock wave therapy to treat foot and ankle conditions such as heel spurs, Achilles tendinopathy, and other chronic pain issues.
Orthopedic applications hold the largest market share, with Aesthetic applications showing the most rapid growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Established healthcare infrastructure and robust regulatory frameworks underwrite the significant role of developed nations in the shock wave therapy devices market. These regions exhibit high adoption rates driven by advanced medical facilities and a willingness to invest in innovative treatment modalities. Demand for precise, non-invasive solutions for musculoskeletal conditions remains consistently strong across these geographies.
United States
An aging demographic and substantial investment in sports medicine clinics drive demand for shock wave therapy devices in the United States. The FDA's 510(k) pathway guides market access for new devices, ensuring safety and efficacy. Major medical device manufacturing clusters in states like California and Massachusetts lead research and development for advanced piezoelectric systems.
Germany
Germany's well-developed healthcare system and high prevalence of chronic musculoskeletal conditions sustain a strong market for shock wave devices. The CE marking under the Medical Device Regulation (MDR) regulates device sales across Europe, requiring stringent clinical data. Specialized rehabilitation centers in cities such as Munich and Berlin actively integrate shock wave therapy into patient care protocols.
Japan
Expanding orthopedic use and a rapidly aging population contribute to the growing market for shock wave therapy in Japan. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees device approvals, emphasizing clinical outcomes. Leading medical technology firms in Tokyo and Osaka focus on developing compact, high-precision focused shock wave systems for diverse clinical settings.
South Korea
Rising healthcare expenditure and increasing adoption in private clinics fuel the shock wave therapy market in South Korea. The Ministry of Food and Drug Safety (MFDS) regulates medical devices, focusing on both safety and technological innovation. Advanced medical centers in Seoul and Busan are early adopters of dual-modality shock wave systems, enhancing treatment versatility.
Australia
Growing clinical acceptance for treating tendinopathies and a strong sports medicine sector support demand for shock wave devices across Australia. The Therapeutic Goods Administration (TGA) ensures medical device compliance and quality standards. Physiotherapy practices in major urban centers like Sydney and Melbourne increasingly utilize radial shock wave devices for broad pain management.
Shock Wave Therapy Devices Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing essential modules for device assembly. The shock wave therapy devices market exhibits a tiered structure, with established medical technology giants alongside specialized manufacturers. Strategic archetypes include diversified medical device conglomerates and niche shock wave therapy solution providers. Market players primarily engage in portfolio diversification and geographic expansion to solidify their positions.
Within the specialized shock wave therapy segment, Storz Medical AG and BTL Industries exemplify companies with deep expertise in both focused and radial systems. Zimmer MedizinSysteme occupies a position as a provider with strong distribution networks in clinical settings, particularly in Europe. These firms anchor innovation in device precision and user ergonomics, catering to specialized orthopedic clinics and physiotherapy practices.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| BTL Industries |
| Dornier MedTech |
| EMS |
| Olympus Corporation |
| EDAP TMS |
| Storz Medical AG |
| Zimmer MedizinSysteme |
| BD |
| Others |
Cost & Logistics Intelligence
Expanded manufacturing capacity in Europe, particularly Germany and Switzerland, influences the pricing posture of device manufacturers as they seek to optimize production volumes. This utilization pressure shapes both supplier behavior and market entry strategies for new device types.
Pricing Analysis
Volume-based pricing structures characterize the shock wave therapy device market, with significant discounts offered for bulk purchases by large hospital networks. Price differentiation stems from device precision, regulatory clearances like CE marking, and included after-sales service packages. Pricing softness stems from variable reimbursement policies across different geographies, forcing manufacturers to offer flexible terms. Smaller physiotherapy practices exhibit higher price sensitivity compared to major hospitals seeking advanced, high-precision focused systems.
Supply Chain Analysis
Export control regimes targeting advanced medical device components could restrict the flow of specialized piezoelectric crystals. Manufacturing concentrates in Germany, Switzerland, and the United States, drawing from specialized components like piezoelectric ceramics and electromagnetic coils. A structural risk involves single-source vulnerability for these high-precision components, given their specialized production. Distribution runs through established networks targeting hospitals, specialized clinics, and rehabilitation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shock wave therapy devices market is entering a cyclical recovery phase, driven by increasing post-pandemic demand for non-invasive musculoskeletal treatments. Healthcare systems are reinvesting in elective procedures and rehabilitation services, boosting device procurement.
For Market Incumbents:Build a regulatory moat through continuous investment in clinical trials to meet stringent EU MDR requirements. Diversify product portfolios to include dual-modality systems, mitigating the threat from specialized niche players. Leverage existing strong distribution networks in major hospitals to maintain market share against emerging portable device manufacturers. Invest in R&D for next-generation piezoelectric technology, enhancing treatment precision and user ergonomics.
For New Entrants and Emerging Players:Establish a beachhead in the rapidly expanding aesthetic applications segment, leveraging novel device designs for cellulite reduction. Target the underpenetrated veterinary medicine market for equine and companion animal orthopedics. The most penetrable segment lies within private physiotherapy and chiropractic clinics seeking portable, cost-effective radial devices. A direct-to-clinic sales model, emphasizing ease of use and return on investment, offers a strong go-to-market angle.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among companies offering integrated system solutions with consumable accessories and service contracts. Long-term viability hinges on companies with robust clinical evidence supporting new therapeutic indications beyond orthopedics. Target acquisition archetypes include specialized manufacturers with strong intellectual property in piezoelectric technology or niche application expertise. Watch for accelerating regulatory approvals for novel indications as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Dual-Modality R&D | Combines focused and radial capabilities, maximizing asset utilization for specialized orthopedic clinics. |
| Pursue FDA 510(k) and CE Markings | Secures market access in the United States and Europe, substantiating safety and efficacy claims. |
| Develop Portable Piezoelectric Systems | Addresses demand from outpatient settings and private practitioners for mobility and space efficiency. |
| Expand into Veterinary Orthopedics | Taps into an underpenetrated market with strong growth potential for animal health applications. |
| Form Strategic Distribution Partnerships | Strengthens market reach in emerging Asia-Pacific economies like South Korea and Australia. |
Research Approach
Desk research of scientific journals, regulatory filings, and company annual reports preceded structured interviews with orthopedic surgeons, physiotherapists, and medical device procurement managers. This approach combined primary insights from clinicians and industry executives with secondary validation from institutional databases. Bottom-up data aggregation and top-down market sizing ensured comprehensive triangulation across diverse data points.
Assumptions regarding stable regulatory environments and consistent healthcare expenditure were held fixed; technological advancements and therapeutic adoption rates varied across the analysis window. The model segmented demand by product type, end-user, technology, and application, including regional adoption patterns. Compound annual growth rates derived from historical trends and projected clinical acceptance. Forecast inputs included procedure volumes for tendinopathies and device approval timelines.
Sensitivities concentrate around unforeseen regulatory changes and significant shifts in reimbursement policies. Forecasts reflect underlying assumptions about technological evolution and market acceptance. Material shifts in clinical evidence or healthcare funding would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Intravascular Ultrasound Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market
Cardiovascular Devices
Global Peripheral Stent Market
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
Arrhythmogenic Right Ventricular Dysplasia Treatment Market
Cardiovascular Devices
Cardiovascular Stents Market
Cardiovascular Devices
Fibromuscular Dysplasia Treatment Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Arteriovenous (Av) Fistula Needle Market
Cardiovascular Devices
Interventional Cardiology Market
Cardiovascular Devices
Global Cardiac Resynchronization Therapy Market
Cardiovascular Devices
Global Sclerotherapy Market
Cardiovascular Devices
Global Vascular Graft Market
Cardiovascular Devices
Global Vascular Stents Market
Cardiovascular Devices
Percutaneous Coronary Intervention Guidance Devices Market