
 Cerebral Palsy Market | 2026-2036
Cerebral Palsy Market Size, Share, and Industry Trends Forecast 2026-2036
Cerebral Palsy Market Intelligence
Revenue from targeted botulinum toxin therapies is rewriting the profitability landscape previously dominated by generalized anticonvulsant and muscle relaxant sales. AbbVie Inc. leverages its established Botox brand, while Ipsen Biopharmaceuticals Inc. competes directly with its neurotoxin portfolio for spasticity applications. Medtronic extends its influence through implantable drug delivery systems for baclofen, offering a non-biologic alternative for severe cases.
The cerebral palsy market encompasses therapeutic interventions and assistive devices designed to manage a group of non-progressive motor conditions. These interventions aim to improve function and quality of life, ranging from pharmacotherapies that modulate neuromuscular junctions to advanced orthotics. Spasticity management constitutes the largest therapy area by expenditure due to the high cost of biologic treatments. The assistive technologies product segment, including communication aids, is expanding rapidly as digital solutions become more accessible.
Market access is governed by stringent regulatory approvals for both drugs and devices. The U.S. FDA, Europe's EMA, and China's NMPA mandate extensive clinical trials demonstrating safety and efficacy, particularly for pediatric populations. Future competitive advantage will depend on integrating pharmacological treatments with digital health platforms and assistive technologies into a cohesive care continuum.
Market Dynamics
The integration of pharmacological treatments with assistive technologies defines the market's current trajectory. Regulatory bodies like the FDA and EMA increasingly favor solutions that demonstrate improved quality of life, pushing a shift toward a cohesive care continuum that combines drugs, devices, and rehabilitation services.
Growth Catalysts
- EU Medical Device Regulation:The MDR harmonizes safety and performance rules for assistive devices, streamlining market access across the European Union for compliant manufacturers.
- Specialized Care Centers:Growth of pediatric rehabilitation networks in countries like Germany and Canada concentrates demand for advanced therapies and assistive technologies.
- Neurotoxin Efficacy:Improved formulations of botulinum toxin for spasticity management enhance therapeutic outcomes, driving adoption over generalized oral muscle relaxants.
Market Restraints
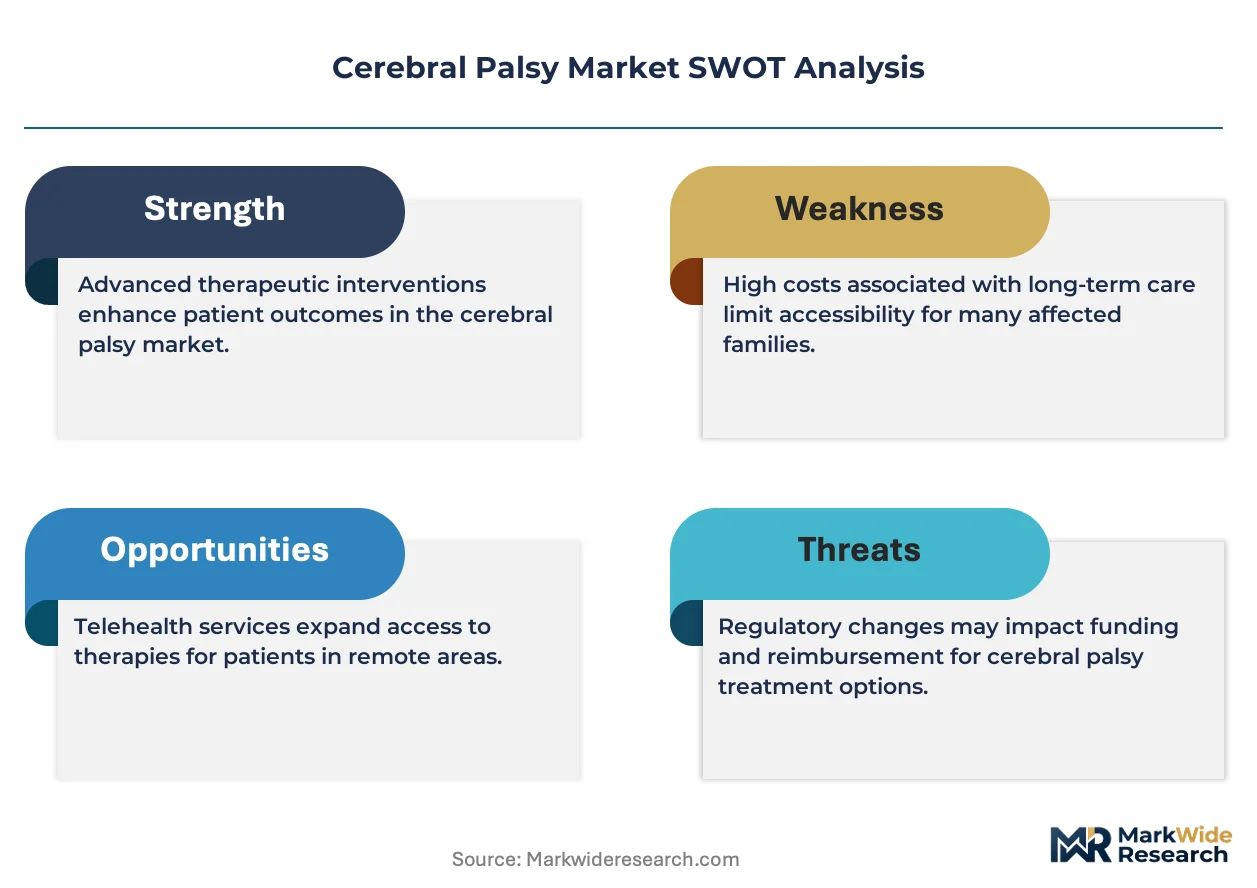
- Biologic Treatment Costs:The high price of botulinum toxin and implantable drug pumps creates significant reimbursement barriers, limiting patient access in many health systems.
- Chronic Condition Burden:The lifelong nature of cerebral palsy management imposes a substantial cumulative cost on families and payers, influencing treatment decisions and adherence.
- Pediatric Trial Complexity:Strict mandates from the FDA and EMA for pediatric clinical trials increase development time and cost, delaying availability of new interventions.
Strategic Opportunities
- Asia-Pacific Expansion:Rising healthcare spending in countries like China and India is creating new demand for advanced cerebral palsy therapies and assistive technologies.
- Integrated Digital Health:Combining drug therapies with digital platforms for remote monitoring offers a pathway to create comprehensive, value-based care solutions for providers.
- AI in Assistive Devices:There is a clear market opening for developing AI-enhanced communication aids that improve functional outcomes for non-verbal patients.
Industry Challenges
- Fragmented Care Pathways:The operational challenge of coordinating care between disparate specialists, such as neurologists and physical therapists, and settings like hospitals and home care, impedes holistic patient management.
- Clinician and Data Scarcity:A shortage of trained therapists limits service delivery, while a lack of standardized long-term outcome data complicates value demonstration for new technologies to payers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cerebral Palsy Market |
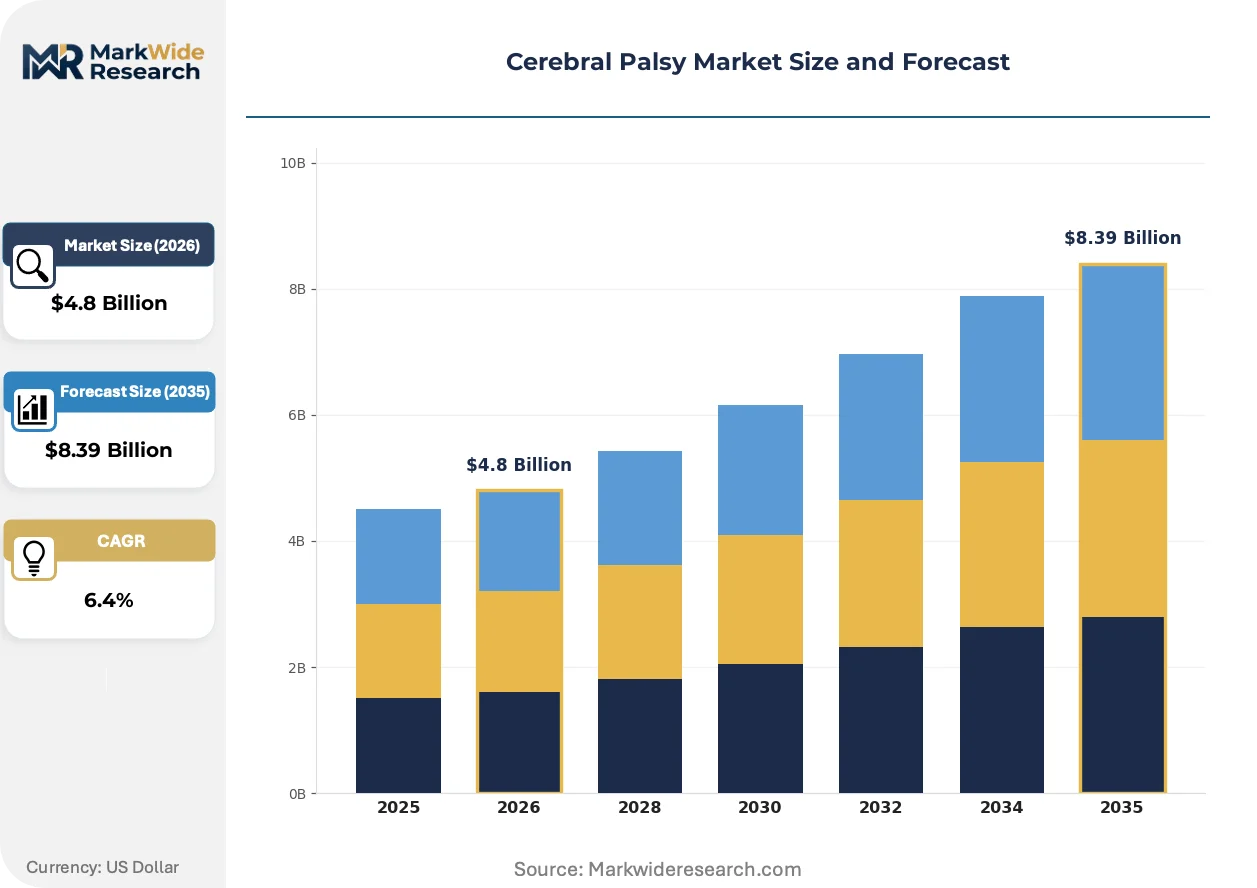
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Physical Therapy Devices, Assistive Technologies, Orthotic Braces, Communication Aids, Adaptive Equipment Therapy Area: Spasticity Management, Motor Function Improvement, Cognitive Support, Speech Therapy, Pain Relief End User: Rehabilitation Centers, Pediatric Clinics, Specialty Hospitals, Home Care Providers, Educational Institutions Delivery Mode: Inpatient Programs, Outpatient Services, Teletherapy, Mobile Health Applications, Community-Based Care |
| Companies Covered | Teva Pharmaceutical Industries Ltd., Revance Therapeutics, AbbVie Inc., Medtronic, Pfizer Inc., Ipsen Biopharmaceuticals Inc., Neurocrine Biosciences Inc., Zimmer Biomet, Merz Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cerebral Palsy Market Strategic Shifts & Innovations
A fundamental shift from managing isolated symptoms toward providing integrated ecosystems of care is redefining the market. This evolution prioritizes the combination of therapeutic interventions, assistive technologies, and digital health services to improve overall quality of life.
Wearable sensors embedded in orthotics and clothing provide continuous, real-world data on patient motor patterns and muscle activity. Rehabilitation centers are increasingly adopting these tools to objectively measure therapeutic progress and tailor interventions. This technology is digitizing the process of functional assessment, replacing periodic clinical observations with a stream of objective data.
Regulatory guidance from the U.S. FDA, particularly its Patient-Focused Drug Development initiative, is altering clinical trial requirements. This policy encourages developers to integrate patient-reported outcomes and real-world evidence to demonstrate a therapy's value beyond traditional clinical endpoints. As a result, new treatments for spasticity and associated conditions are increasingly assessed on their ability to improve daily function and quality of life.
Family-centered care models are gaining prominence, shifting decision-making power from a purely clinician-led approach to a collaborative one involving caregivers. This change is disrupting traditional prescription patterns, as informed parents and guardians actively research and advocate for specific devices and therapies. This trend is most pronounced within specialized pediatric networks in the United States and the United Kingdom.
Cerebral Palsy Market Segmentation
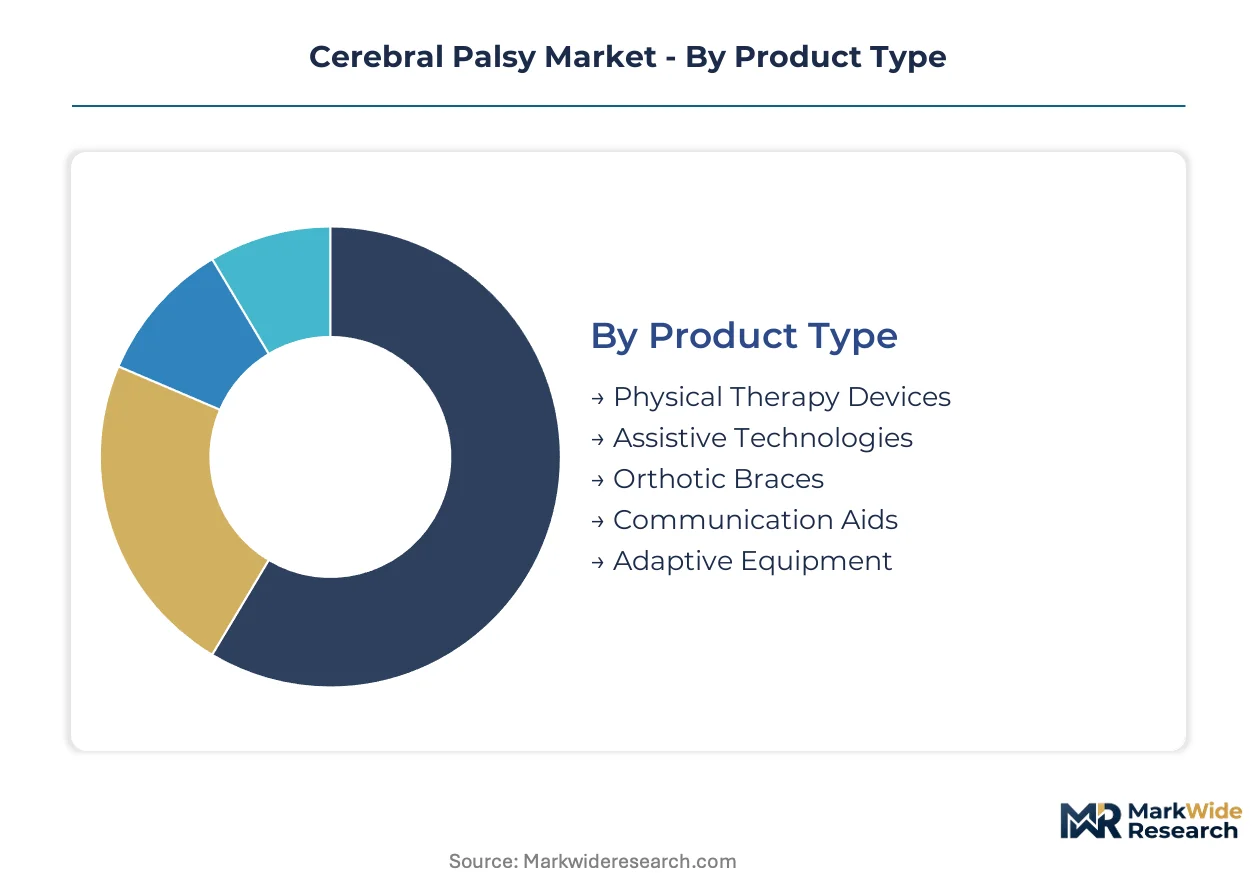
The Cerebral Palsy market segments across diverse product types, therapy areas, end-user categories, and delivery modes. Understanding these distinctions clarifies how interventions are delivered and which innovations gain traction among patient populations. Each segment reflects unique demand drivers and regulatory considerations shaping its growth trajectory.
Product Type:
The product type segment spans both mature and emerging solutions for managing cerebral palsy symptoms and improving daily function.
- Physical Therapy Devices:These include equipment like exercise machines, balance trainers, and gait analysis systems used in clinical and home settings. Demand for these devices is concentrated in rehabilitation centers seeking objective measurement tools.
- Assistive Technologies:This category encompasses a broad range of tools designed to enhance independence, from mobility aids to environmental control systems. Europe, driven by the EU Medical Device Regulation, sees significant demand for compliant, high-performance assistive technologies.
- Orthotic Braces:Custom-fitted or off-the-shelf devices provide support, correct alignment, and prevent deformities in limbs and joints. These braces are essential for maintaining posture and facilitating mobility, particularly in pediatric populations.
- Communication Aids:Devices like speech-generating devices and augmentative and alternative communication (AAC) systems facilitate expression for non-verbal individuals. The United States and the United Kingdom exhibit strong demand for AI-enhanced communication aids in specialized pediatric networks.
- Adaptive Equipment:This segment includes specialized seating, feeding aids, and modified household items that help individuals perform daily activities. Demand for adaptive equipment is consistent across all end-user environments.
Assistive Technologies handles the majority of throughput; Communication Aids is the fastest mover on share.
Therapy Area:
Therapy areas define the specific clinical needs addressed by interventions, with a primary focus on improving motor control and functional independence.
- Spasticity Management:This area addresses muscle stiffness and involuntary contractions, often through pharmaceutical interventions like botulinum toxin and baclofen. The high cost of biologic treatments makes spasticity management the largest therapy area by expenditure, particularly in developed economies.
- Motor Function Improvement:Interventions here aim to enhance movement, coordination, and balance through physical therapy, occupational therapy, and specialized devices. Wearable sensors are increasingly integrated into motor function improvement programs within rehabilitation centers to provide objective data.
- Cognitive Support:This segment focuses on therapies and tools designed to address learning difficulties, attention deficits, and memory issues. Educational institutions and specialized clinics increasingly seek solutions for cognitive support.
- Speech Therapy:This area provides interventions for communication difficulties, including articulation, fluency, and voice disorders. Demand for speech therapy services is concentrated in pediatric clinics and educational settings.
- Pain Relief:Managing chronic pain associated with cerebral palsy involves pharmacological and non-pharmacological approaches. Pain relief interventions are critical for improving patient quality of life across all age groups.
Spasticity Management represents the largest revenue concentration; Motor Function Improvement shows significant expansion due to technological advancements.
End User:
The end-user segment highlights the primary settings where cerebral palsy interventions are delivered, reflecting varied care models and service integration.
- Rehabilitation Centers:These facilities offer comprehensive, multidisciplinary care, integrating physical, occupational, and speech therapies with advanced assistive technologies. Growth of pediatric rehabilitation networks in countries like Germany and Canada drives demand for advanced therapies within these centers.
- Pediatric Clinics:Specialized clinics provide early diagnosis, intervention, and ongoing management for children with cerebral palsy. These clinics are critical hubs for family-centered care models, particularly in the United States.
- Specialty Hospitals:Hospitals with specialized neurological or pediatric departments offer advanced medical and surgical interventions for complex cases. These institutions often serve as referral centers for severe cerebral palsy conditions.
- Home Care Providers:Services delivered in the home environment support ongoing therapy and daily living assistance, promoting independence. Home care providers are increasingly adopting digital health platforms for remote monitoring and teletherapy.
- Educational Institutions:Schools and specialized educational facilities provide support and adaptive tools to ensure inclusive learning environments. These institutions focus on integrating assistive technologies and communication aids for students with cerebral palsy.
Rehabilitation Centers command the largest share of service provision; Home Care Providers exhibit a climbing demand curve for integrated solutions.
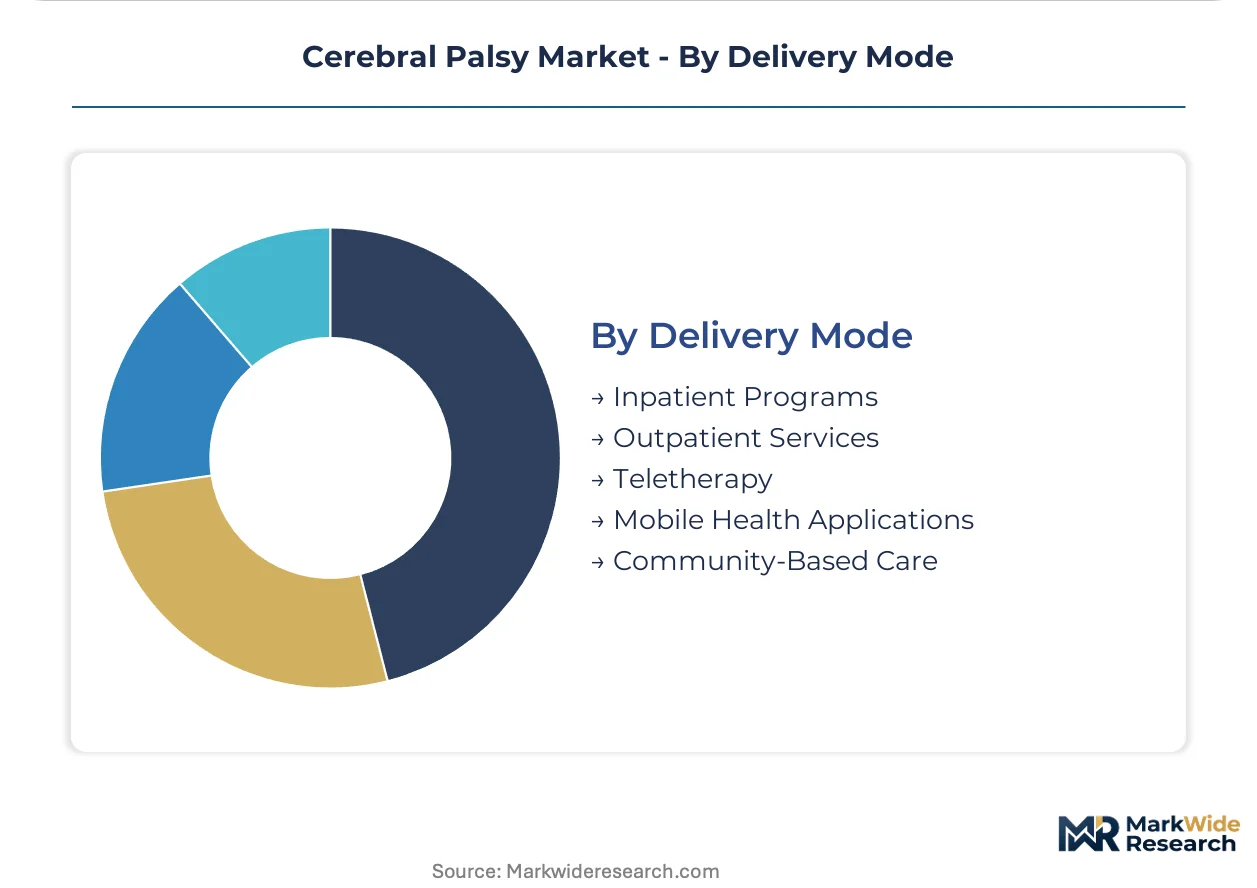
Delivery Mode:
Delivery modes illustrate how services and treatments reach patients, reflecting evolving healthcare models and technological integration.
- Inpatient Programs:These intensive, facility-based programs offer round-the-clock care and therapy for individuals requiring comprehensive rehabilitation. Inpatient programs are typically utilized for initial diagnosis or severe cases requiring constant medical supervision.
- Outpatient Services:Patients receive scheduled therapy sessions and medical consultations while living at home, offering flexibility and continuity of care. The integration of pharmacological treatments with assistive technologies is a hallmark of modern outpatient services.
- Teletherapy:Remote delivery of therapeutic services via digital platforms, including physical therapy, occupational therapy, and speech therapy. Teletherapy provides a pathway for comprehensive, value-based care solutions, especially in geographically dispersed areas.
- Mobile Health Applications:Software applications on smartphones or tablets support exercise routines, track progress, and provide educational resources. These applications offer convenient tools for patient engagement and data collection in real-world settings.
- Community-Based Care:Services delivered within local communities, such as support groups, recreational programs, and accessible facilities. Community-based care enhances social integration and quality of life for individuals with cerebral palsy.
Outpatient Services dominate patient engagement; Teletherapy is rapidly expanding its reach and influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cerebral Palsy market exhibits a landscape where innovation and specialized care provision are concentrating in developed economies. These regions drive demand for advanced therapies and assistive technologies due to established healthcare infrastructure and robust research ecosystems. Regulatory frameworks significantly influence market access and product development across these key geographies.
United States
Demand for integrated digital health platforms and advanced communication aids is strong in the United States. The U.S. FDA's Patient-Focused Drug Development initiative encourages patient-reported outcomes in clinical trials. Specialized pediatric networks in major metropolitan areas like Boston and New York City lead in adopting family-centered care models.
Germany
Germany shows high demand for compliant assistive technologies and advanced rehabilitation services. The EU Medical Device Regulation harmonizes safety standards, streamlining market entry for manufacturers. Pediatric rehabilitation networks in regions like Bavaria and North Rhine-Westphalia are expanding their technological capabilities.
China
Rising healthcare spending in China creates new demand for advanced cerebral palsy therapies. The NMPA mandates extensive clinical trials, particularly for pediatric populations, influencing market entry strategies. Major urban centers such as Shanghai and Beijing are developing specialized clinics and rehabilitation facilities.
United Kingdom
The United Kingdom demonstrates significant demand for AI-enhanced communication aids and family-centered care. Regulatory guidance from the Medicines and Healthcare products Regulatory Agency (MHRA) supports innovation in medical devices. Specialized pediatric networks in London and the Southeast actively research and advocate for specific devices.
Canada
Canada's public health coverage drives demand for specialized pediatric rehabilitation networks and advanced therapies. Health Canada's regulations ensure safety and efficacy for both drugs and medical devices. Cities like Toronto and Vancouver are hubs for integrating pharmacological treatments with digital health platforms.
Cerebral Palsy Market Key Industry Players
Innovator pharmaceutical companies and specialized medical device manufacturers split the Cerebral Palsy market, creating a dynamic competitive environment. This structure combines highly consolidated segments for biologic therapies, where a few large players dominate, with more fragmented areas for assistive technologies and digital health solutions. Large incumbents prioritize portfolio diversification and geographic expansion, seeking to integrate various treatment modalities into comprehensive care solutions. Smaller specialized firms often focus on technology licensing and strategic partnerships to access broader markets and enhance product development, particularly in niche areas.
Global pharmaceutical giants, such as AbbVie Inc., anchor the market for targeted botulinum toxin therapies, leveraging established brand presence and extensive distribution networks. Ipsen Biopharmaceuticals Inc. represents another key player, offering a competitive neurotoxin portfolio specifically designed for spasticity applications, challenging existing market leaders. Medtronic occupies a distinct position through its implantable drug delivery systems for baclofen, exemplifying a non-biologic alternative that addresses severe and refractory cases. These firms collectively represent the blend of advanced pharmacological and device-based interventions shaping the treatment landscape and exemplify distinct approaches to patient care.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd. |
| Revance Therapeutics |
| AbbVie Inc. |
| Medtronic |
| Pfizer Inc. |
| Ipsen Biopharmaceuticals Inc. |
| Neurocrine Biosciences Inc. |
| Zimmer Biomet |
| Merz Pharma |
| Others |
Cost & Logistics Intelligence
Specialized biologics manufacturing for botulinum toxin therapies concentrates margin pools within a few pharmaceutical giants. This supply concentration underpins the premium pricing of advanced spasticity management solutions.
Pricing Analysis
U.S. FDA mandates dictate the pricing tier structure for novel cerebral palsy interventions, emphasizing value-based pricing for advanced therapies. This market primarily uses a hybrid model, combining value-based pricing for biologics and contract-based pricing for assistive devices. Price differentiation stems from demonstrated clinical efficacy and established brand premium. Pricing softness originates from significant reimbursement barriers and the cumulative cost burden of chronic care. Health systems and public payers exhibit high price sensitivity, while specialized pediatric networks with robust funding are less constrained.
Supply Chain Analysis
Export controls on certain advanced medical device components limit the free flow of specialized manufacturing capabilities across borders. The supply chain for cerebral palsy therapies and devices concentrates in the United States for biologics and advanced electronics, with Germany specializing in rehabilitation technology. Critical dependencies include highly purified biologic precursors and specialized microprocessors. Single-source vulnerability for these high-tech components represents a significant structural risk. Distribution runs through a network of specialized medical distributors and direct sales to rehabilitation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cerebral Palsy market faces a capability scarcity in integrating diverse therapeutic interventions and digital health platforms. This gap creates fragmented patient journeys and limits holistic care delivery.
For Market Incumbents: Harden existing market positions by deepening integration between pharmacological treatments and digital health platforms. Companies should prioritize strategic acquisitions of specialized assistive technology firms to counter fragmentation. The threat of integrated digital health solutions displacing standalone offerings is real. Investing in R&D for AI-enhanced communication aids and remote monitoring tools acts as a crucial lever for long-term relevance.
For New Entrants and Emerging Players: Build out comprehensive digital health ecosystems that seamlessly combine drug therapies with remote monitoring. White-space targets include developing AI-enhanced communication aids and integrated platforms for continuous spasticity management. The home care provider segment is most penetrable due to its demand for integrated solutions. A strategic go-to-market angle involves forming value-based care partnerships with rehabilitation networks.
For Investors and Strategic Acquirers: Capital is best deployed toward companies demonstrating robust capabilities in integrating pharmacological treatments with advanced assistive technologies and digital health platforms. Long-term viability hinges on solutions proving improved quality of life and generating patient-reported outcomes. Target acquisition archetypes include specialized digital health platforms or innovative AI-enhanced communication aid developers. The signal to watch is the expansion of value-based reimbursement models.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Demonstrating superior efficacy and safety for pediatric populations drives market adoption for new therapies. |
| Platform Integration | Combining drug therapies with digital health platforms creates comprehensive, value-based care solutions for providers. |
| Acquisition of Specialist Firm | Securing niche expertise in AI-enhanced communication aids or wearable sensor technology strengthens competitive positioning. |
| Reimbursement Strategy | Navigating complex payer landscapes is crucial for ensuring patient access to high-cost biologic treatments. |
| Software Companion Development | Enhancing assistive devices with digital interfaces and remote monitoring capabilities improves functional outcomes. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to inform market dynamics and future projections. This involved primary interviews with neurologists, physical therapists, rehabilitation center directors, and medical device engineers. Secondary validation drew from U.S. FDA filings, EMA submissions, clinical trial registries, and national healthcare expenditure reports. A robust bottom-up and top-down triangulation approach ensured data accuracy.
The calibration of market forecasts integrated both historical trends and forward-looking indicators across the analysis window. Market segmentation dimensions modeled included product type, therapy area, end-user, delivery mode, and regional regulatory frameworks. Compound Annual Growth Rates (CAGRs) were derived from multi-factor regression analysis. Key forecast inputs included cerebral palsy prevalence rates and novel neurotoxin adoption.
Stress conditions across reimbursement policy changes and clinical trial success rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding market access and technological innovation. Material shifts in major regulatory frameworks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Gastrointestinal Stromal Tumors Market
Specialty Medicine
Global Axial Spondyloarthritis (Axspa) Market
Specialty Medicine
Medical Foods for Orphan Diseases Market
Specialty Medicine
Triple X Syndrome Management Market
Specialty Medicine
Anophthalmia and Microphthalmia Market
Specialty Medicine
Oral Cancer Treatment Market
Specialty Medicine
Global Appendiceal Cancer Treatment Market
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
Acute Myeloid Leukemia Therapeutics Market
Specialty Medicine
Optic Atrophy Management Market
Specialty Medicine
SPINA Bifida and Hydrocephalus Market
Specialty Medicine
Global Major Depressive Disorder (MDD) Market
Specialty Medicine
Enzyme Replacement Therapy Market
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market