
 Idiopathic Pulmonary Fibrosis (IPF) Market | 2026-2036
Idiopathic Pulmonary Fibrosis (IPF) Market Size, Share, and Industry Trends Forecast 2026-2036
Idiopathic Pulmonary Fibrosis (IPF) Market Intelligence
Market Context
Specialty clinics is decoupling from hospital-based infusion centers as the preferred site for antifibrotic therapy administration. Boehringer Ingelheim International GmbH leverages its established pulmonology sales infrastructure to sustain physician access across outpatient networks. F. Hoffmann-La Roche Ltd anchors its position through biomarker-linked diagnostic ecosystems that identify eligible patients earlier in disease progression.
Technical Definition and Segment Structure
Idiopathic Pulmonary Fibrosis represents a chronic, progressive interstitial lung disease characterized by irreversible scarring of pulmonary parenchyma, with a median survival of three to five years from diagnosis absent therapeutic intervention; antifibrotic agents function by inhibiting tyrosine kinase pathways or modulating TGF-beta signaling to slow forced vital capacity decline. Oral delivery mode dominates prescription volume due to patient preference for home-based administration, though intravenous formulations capture higher per-dose margins in hospital settings. Antifibrotic therapy leads the therapy area mix, while supportive care segments expand fastest as payers emphasize quality-of-life endpoints alongside survival metrics.
Regulatory Framework
The FDA's Breakthrough Therapy and orphan drug programs compress development timelines for IPF candidates, while EMA's PRIME designation creates parallel European acceleration pathways that shape multinational trial design. Post-market surveillance requirements from both agencies intensify pharmacovigilance investment, particularly for agents targeting novel mechanisms like autotaxin inhibition or integrin modulation. Stakeholders must monitor evolving payer evidence frameworks that increasingly demand patient-reported outcome data alongside traditional pulmonary function endpoints.
Market Dynamics
Antifibrotic therapy administration is migrating from hospital infusion suites to specialty pulmonology clinics, compressing site-of-care economics while expanding patient access to oral nintedanib and pirfenidone regimens.
Growth Catalysts
- Orphan drug acceleration:The FDA's orphan drug designation pathway compresses clinical trial timelines and extends market exclusivity for novel IPF mechanisms, incentivizing biotech investment in autotaxin and integrin targets.
- Medicare reimbursement stability:United States federal coverage for antifibrotic agents eliminates prior authorization friction for eligible patients, sustaining prescription volume in the largest national market.
- Biomarker-linked screening:High-resolution CT protocols and forced vital capacity monitoring in pulmonology practices identify progressive fibrosis earlier, expanding the addressable patient pool for disease-modifying therapy.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthetic routes for nintedanib intermediates rely on a limited base of contract manufacturers in India and China, exposing supply continuity to single-source vulnerabilities.
- Diagnostic latency:Median time from symptom onset to definitive IPF diagnosis exceeds two years in most healthcare systems, delaying antifibrotic initiation and compressing effective treatment windows.
- Generic substitution pressure:Patent cliffs for first-generation antifibrotics will expose originator pricing to compulsory licensing frameworks in emerging markets.
Strategic Opportunities
- Home-based monitoring integration:Connected spirometry devices and patient-reported outcome platforms enable decentralized trial endpoints, reducing site burden for Phase III fibrosis studies.
- Japan's PRIME-adjacent pathway:PMDA's Sakigake designation offers priority review for IPF candidates with Japanese patient data, creating a faster regulatory track for novel mechanisms.
- Supportive care bundling:Supplemental oxygen, pulmonary rehabilitation, and palliative services represent underpenetrated revenue streams as payers migrate toward episode-based reimbursement for interstitial lung disease.
Industry Challenges
- Interstitial lung disease specialist scarcity:Fellowship-trained pulmonologists capable of distinguishing IPF from hypersensitivity pneumonitis and connective tissue-associated fibrosis remain concentrated in academic medical centers, limiting community diagnostic capacity.
- Pharmacovigilance infrastructure:Post-market surveillance requirements for hepatotoxicity and gastrointestinal adverse events demand dedicated safety databases that strain emerging biotech resource allocation.
Report Scope
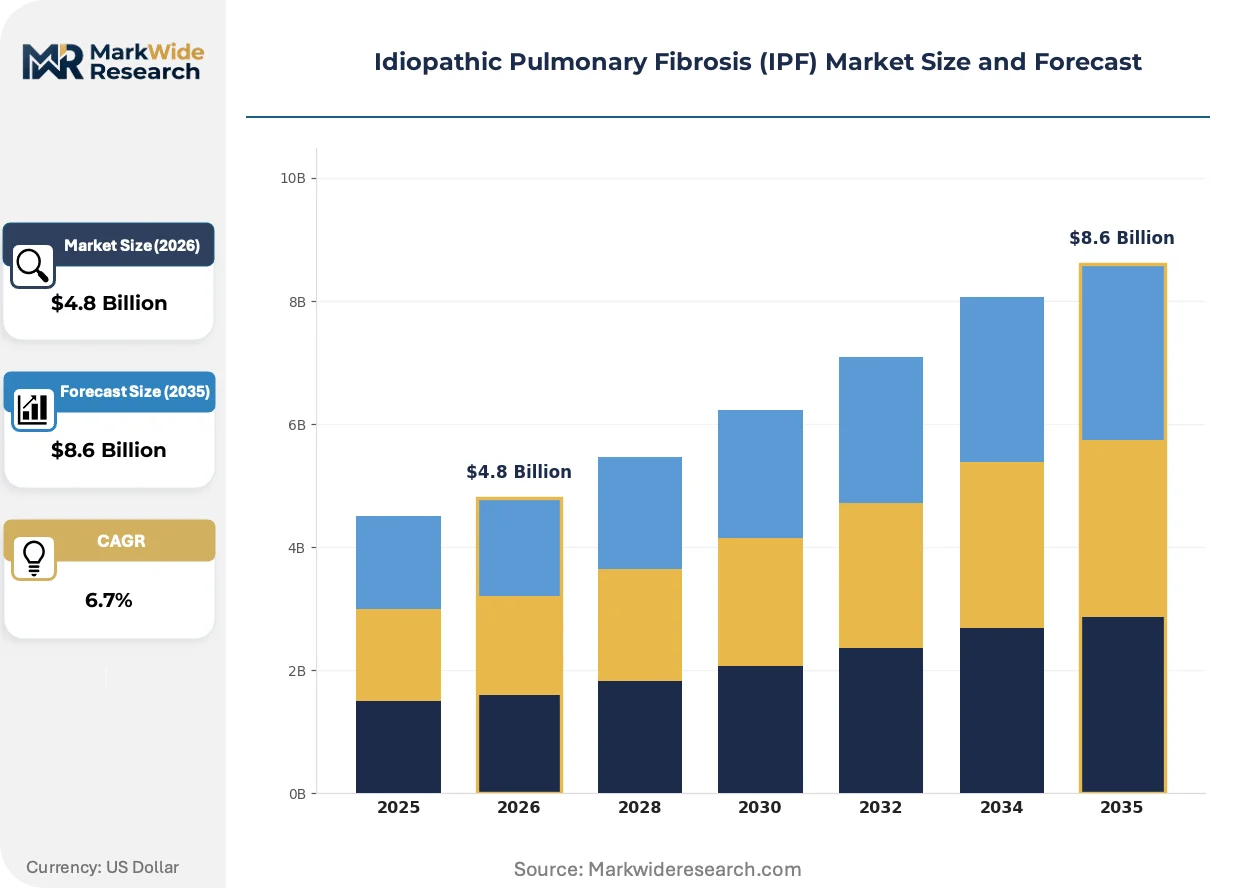
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Idiopathic Pulmonary Fibrosis (IPF) Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Antifibrotic Therapy, Immunosuppressants, Corticosteroids, Supportive Care Delivery Mode: Intravenous, Oral, Subcutaneous, Inhalation End User: Hospitals, Specialty Clinics, Home Care, Research Laboratories Application: Clinical Trials, Diagnostic Procedures, Risk Assessment, Patient Management |
| Companies Covered | Boehringer Ingelheim International GmbH, F. Hoffmann-La Roche Ltd, FibroGen Inc., Horizon Therapeutics plc, United Therapeutics Corporation, Galapagos NV, Bristol-Myers Squibb, Pliant Therapeutics Inc., Vicore Pharma AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Idiopathic Pulmonary Fibrosis (IPF) Market Strategic Shifts & Innovations
Digital biomarker platforms and decentralized trial infrastructure are compressing traditional development timelines while regulatory agencies accelerate novel mechanism review through orphan and breakthrough designations.
Machine learning algorithms applied to quantitative CT fibrosis scoring are unifying radiologic interpretation standards across multicenter trials, reducing inter-reader variability that has historically confounded progression endpoints. Academic research networks in the United States and Germany are deploying these tools for screening enrichment, enabling smaller sample sizes with higher event rates. This convergence of imaging informatics and clinical trial design is compressing Phase II readout timelines.
The FDA's Breakthrough Therapy designation for IPF candidates with novel mechanisms creates parallel development tracks with rolling review, compressing the traditional NDA submission window. EMA's PRIME designation offers similar acceleration for European market access, shaping multinational trial protocols to satisfy both agencies simultaneously. Sponsors are responding by embedding patient-reported outcome instruments earlier in development to meet evolving payer evidence requirements.
Specialty pharmacy distribution is displacing traditional wholesale channels for oral antifibrotics, with hub services managing adherence monitoring and prior authorization support. This channel shift concentrates volume with a limited set of accredited specialty pharmacies capable of handling REMS requirements and patient assistance program coordination. The United States exhibits the most pronounced channel migration, though European markets are following with centralized dispensing models in Germany and the Netherlands.
Idiopathic Pulmonary Fibrosis (IPF) Market Segmentation
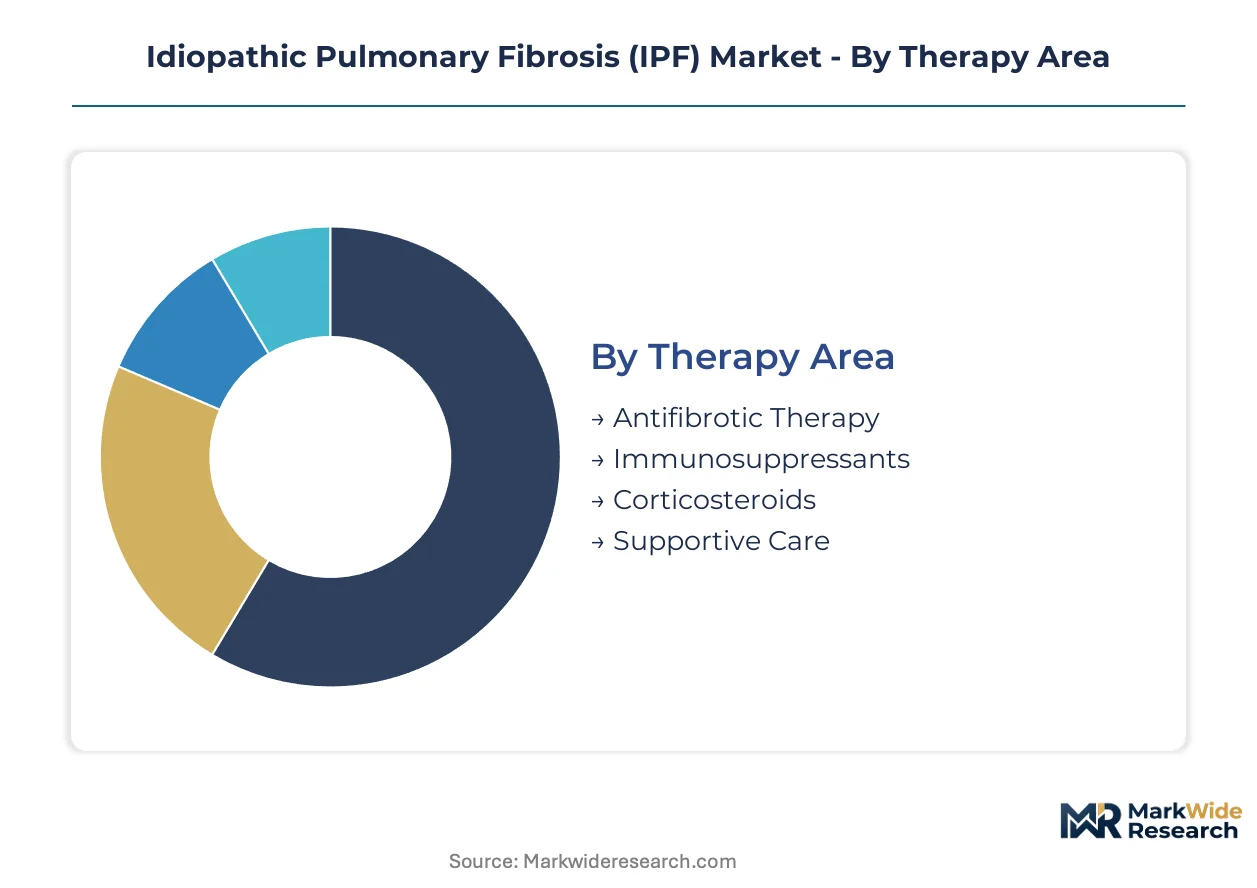
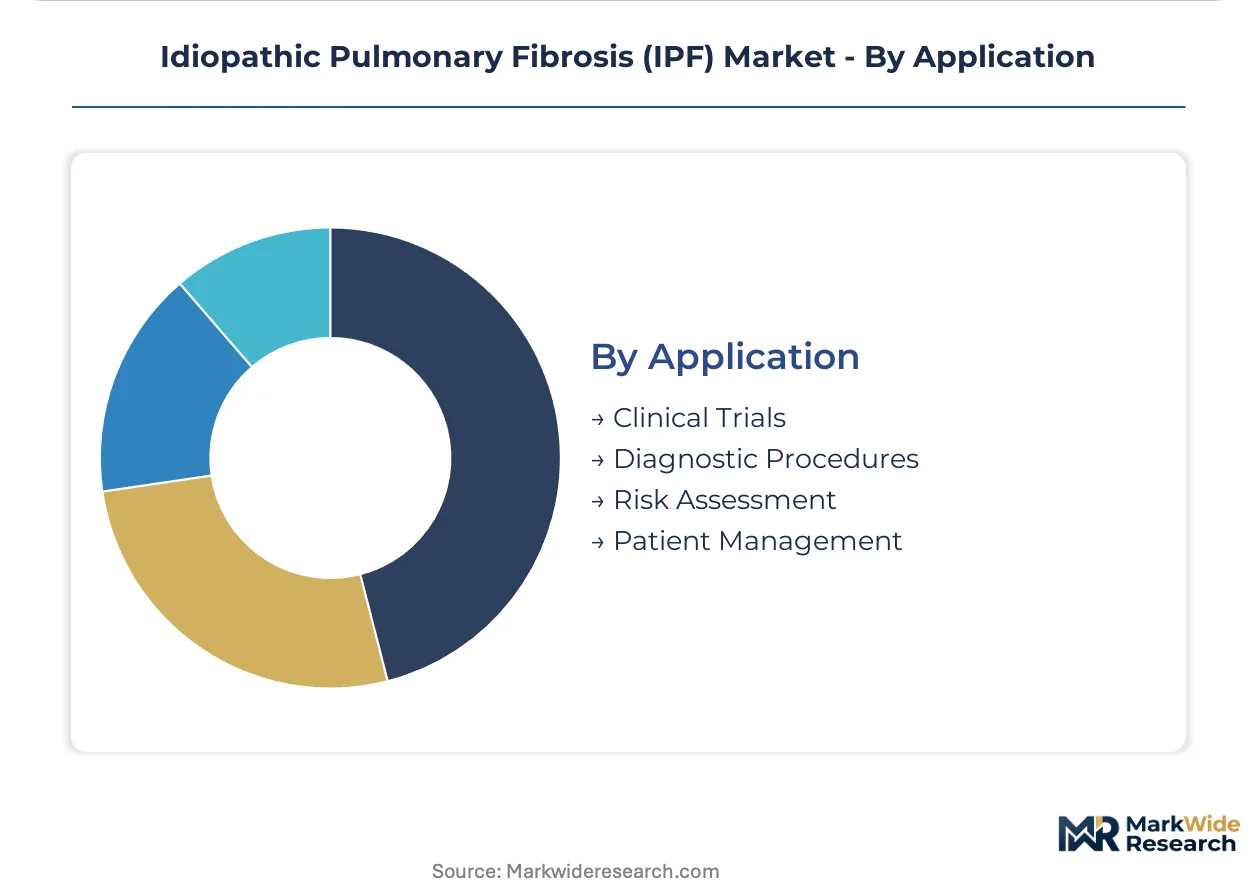
IPF market segmentation reflects the tension between disease-modifying efficacy and patient-centered administration preferences. Each axis shapes reimbursement pathways, site-of-care economics, and competitive positioning for incumbent and emerging therapies.
Therapy Area:
Mechanism of action determines regulatory pathway speed, pricing power, and prescriber adoption curves across the therapeutic spectrum.
- Antifibrotic Therapy:Tyrosine kinase inhibition and TGF-beta modulation constitute the clinical standard of care, with oral nintedanib and pirfenidone commanding preferred formulary placement in Medicare Part D and commercial plans. United States pulmonology practices concentrate prescription volume where prior authorization infrastructure minimizes access friction.
- Supportive Care:Supplemental oxygen, pulmonary rehabilitation, and palliative services address quality-of-life endpoints that payers increasingly bundle under episode-based reimbursement. Germany's Diagnosis-Related Group refinements for interstitial lung disease accelerate hospital adoption of integrated care pathways.
- Immunosuppressants:Azathioprine and mycophenolate mofetil retain niche use in connective tissue-associated fibrosis with overlapping pathology.
- Corticosteroids:Prednisone-equivalent regimens persist in acute exacerbation management despite absent disease-modifying evidence.
Antifibrotic Therapy leads on scale; Supportive Care leads on momentum.
Delivery Mode:
Route of administration directly shapes site-of-care economics, patient adherence profiles, and manufacturing complexity for formulation development.
- Oral:Capsule and tablet formulations dominate prescription volume through home-based administration that eliminates infusion center dependency. Boehringer Ingelheim and Roche have built specialty pharmacy distribution networks around oral antifibrotic convenience.
- Intravenous:Hospital-based infusion captures higher per-dose margins and enables therapeutic drug monitoring for investigational candidates, though site capacity constraints limit scalability.
- Subcutaneous:Prefilled syringe and autoinjector formats under development for next-generation biologics targeting autotaxin and integrin pathways.
- Inhalation:Nebulized formulations remain experimental, with deposition efficiency challenges in fibrotic parenchyma constraining clinical translation.
Oral formulations anchor volume concentration; subcutaneous delivery is climbing the fastest as pipeline candidates advance.
End User:
Care setting selection reflects diagnostic capability, reimbursement mechanics, and patient acuity stratification across the disease course.
- Specialty Clinics:Fellowship-trained interstitial lung disease programs in academic medical centers and community pulmonology practices drive antifibrotic initiation through high-resolution CT interpretation and forced vital capacity monitoring infrastructure.
- Hospitals:Inpatient admission for acute exacerbation, transplant evaluation, and clinical trial enrollment maintains concentrated procedural revenue despite declining chronic administration share.
- Home Care:Remote patient monitoring platforms and visiting nurse services expand fastest where supplemental oxygen and rehabilitation protocols integrate with telehealth follow-up.
- Research Laboratories:Biomarker discovery and companion diagnostic development concentrate in United States and German academic consortia with longitudinal patient registries.
Specialty Clinics dominate antifibrotic prescribing; Home Care is gaining share fastest as site-of-care migration accelerates.
Application:
Functional use case segmentation separates revenue-generating clinical administration from diagnostic and research-adjacent activities that shape market expansion.
- Patient Management:Chronic antifibrotic prescribing, adverse event monitoring, and disease progression tracking constitute the core revenue base with established reimbursement codes.
- Clinical Trials:Phase II and Phase III enrollment for novel mechanisms generates site fees and per-patient revenue that subsidizes specialized ILD center infrastructure.
- Diagnostic Procedures:Surgical lung biopsy, bronchoalveolar lavage, and genomic profiling support definitive IPF classification versus hypersensitivity pneumonitis mimics.
- Risk Assessment:Quantitative CT fibrosis scoring and composite physiologic index calculation inform prognosis counseling and transplant referral timing.
Patient Management leads on revenue scale; Clinical Trials lead on investment intensity as pipeline candidates multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics pull antifibrotic manufacturing toward jurisdictions with streamlined orphan drug pathways and favorable reimbursement mechanics, while diagnostic capacity concentrates where pulmonology specialist density supports earlier disease identification.
United States
Medicare Part D coverage eliminates prior authorization barriers for nintedanib and pirfenidone, sustaining prescription volume in the largest national market. The FDA's Breakthrough Therapy and orphan drug programs compress development timelines for novel mechanisms. The Boston-Cambridge corridor anchors biomarker-linked diagnostic ecosystems that identify eligible patients earlier in disease progression.
Germany
Diagnosis-Related Group refinements for interstitial lung disease accelerate hospital adoption of integrated care pathways that bundle antifibrotic therapy with pulmonary rehabilitation. EMA's PRIME designation creates parallel European acceleration pathways that shape multinational trial design. The Heidelberg-Mannheim region concentrates academic research networks deploying quantitative CT fibrosis scoring for screening enrichment.
Japan
PMDA's Sakigake designation offers priority review for IPF candidates with Japanese patient data, creating a faster regulatory track for novel mechanisms targeting autotaxin and integrin pathways. The national health insurance system provides predictable reimbursement for approved antifibrotics. The Tokyo-Osaka corridor hosts the densest concentration of interstitial lung disease specialists capable of distinguishing IPF from hypersensitivity pneumonitis mimics.
United Kingdom
NICE technology appraisals determine formulary access for antifibrotic agents within the National Health Service, creating transparent pricing negotiations that reference clinical value frameworks. The Medicines and Healthcare products Regulatory Agency aligns post-market surveillance requirements with EMA standards. The Manchester-Liverpool cluster concentrates Phase II and Phase III enrollment infrastructure that subsidizes specialized ILD center operations.
India
Contract manufacturing concentration for nintedanib intermediates exposes supply continuity to single-source vulnerabilities despite lower production costs. CDSCO's accelerated approval pathway for orphan indications remains underutilized relative to FDA and EMA equivalents. The Hyderabad-Bangalore corridor hosts active pharmaceutical ingredient facilities that serve global generic substitution demand as first-generation antifibrotic patents expire.
Idiopathic Pulmonary Fibrosis (IPF) Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with originator firms commanding premium pricing in Medicare-reimbursed markets while generic producers prepare for post-patent cliff volume capture. The vendor base organizes around three strategic archetypes: multinational pharmaceutical conglomerates with established pulmonology sales infrastructure, mid-cap biotechs advancing novel mechanisms through accelerated regulatory pathways, and contract development and manufacturing organizations securing API supply continuity. Dominant competitive moves include strategic partnerships to embed biomarker-linked diagnostics and geographic expansion into Japan's Sakigake-designated approval track.
Among Germany-based pharmaceutical conglomerates, Boehringer Ingelheim International GmbH anchors the established pulmonology sales infrastructure archetype, while Switzerland-based F. Hoffmann-La Roche Ltd exemplifies the biomarker-integrated diagnostic ecosystem model. Mid-cap biotechs advancing novel mechanisms include California-based Pliant Therapeutics Inc., which occupies a position within the autotaxin and integrin target development tier.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| F. Hoffmann-La Roche Ltd |
| FibroGen Inc. |
| Horizon Therapeutics plc |
| United Therapeutics Corporation |
| Galapagos NV |
| Bristol-Myers Squibb |
| Pliant Therapeutics Inc. |
| Vicore Pharma AB |
| Others |
Cost & Logistics Intelligence
Fellowship-trained interstitial lung disease specialists concentrated in the Boston-Cambridge and Heidelberg-Mannheim corridors command compensation premiums that widen spreads between academic medical center pricing and community pulmonology clinic reimbursement tiers.
Pricing Analysis
Specialty pharmacy distributor margins anchor the channel economics for oral antifibrotics, with hub services layering adherence monitoring and prior authorization support fees atop drug acquisition costs. Pricing stratifies across originator-branded, authorized generic, and compulsory-licensed economy tiers based on patent status and regulatory exclusivity. Cost compression in the emerging-market tier intensifies as Indian and Chinese contract manufacturers scale nintedanib intermediate production. Medicare Part D beneficiaries exhibit lowest price sensitivity; cash-pay patients in markets without national health insurance coverage face highest out-of-pocket exposure.
Supply Chain Analysis
Workforce availability constraints in synthetic organic chemistry limit active pharmaceutical ingredient production to concentrated facilities in Hyderabad, Bangalore, and select Zhejiang province manufacturing zones. Nintedanib intermediates draw from specialized pyridine derivative and malonate ester feedstocks sourced through Indian and Chinese chemical suppliers. Single-source vulnerability in contract manufacturing organization capacity exposes continuity to regulatory inspection disruptions or export restriction events. Distribution runs through accredited specialty pharmacy networks in the United States and centralized dispensing models in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IPF market represents a late-cycle quality story where antifibrotic therapy demand shifts toward premium formulations with integrated biomarker-linked diagnostic ecosystems and patient-reported outcome platforms.
For Market Incumbents: Deepen vertical integration into companion diagnostic development to lock in prescriber workflow dependency before patent cliffs expose originator pricing to generic substitution. Expand manufacturing capacity in FDA-inspected facilities to defend against single-source API vulnerabilities from Indian contract manufacturers. Prioritize formulary defense investments in Medicare Part D plans where prior authorization infrastructure creates switching costs. For New Entrants and Emerging Players: The premium-to-economy price-point gap in supportive care bundling offers white-space entry for integrated pulmonary rehabilitation and supplemental oxygen service platforms. Target home care monitoring segments where telehealth reimbursement codes remain underpenetrated relative to specialty clinic prescribing volume. Pursue strategic partnerships with quantitative CT fibrosis scoring developers to embed diagnostic-enabled therapy selection into pulmonology practice workflows. For Investors and Strategic Acquirers: Mid-cap biotechs with PMDA Sakigake-designated IPF candidates are the most active acquisition targets for multinational pharmaceutical conglomerates seeking Japanese market access acceleration. The five-to-ten year viability window favors platforms with novel autotaxin or integrin mechanisms that can demonstrate forced vital capacity preservation against nintedanib and pirfenidone comparators. Watch FDA Breakthrough Therapy designation announcements as inflection indicators for pipeline asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Linked Diagnostic Ecosystem Development | Roche's quantitative CT scoring partnerships with academic ILD centers accelerate patient identification earlier in fibrosis progression. |
| PMDA Sakigake Designation Pursuit | Japanese priority review compresses regulatory timelines for novel mechanisms with domestic patient enrollment data. |
| Specialty Pharmacy Hub Services Expansion | Boehringer Ingelheim's adherence monitoring infrastructure reduces prescription abandonment through prior authorization support. |
| Home-Based Monitoring Platform Integration | Connected spirometry devices enable decentralized trial endpoints that reduce Phase III site burden and patient travel requirements. |
| Supportive Care Bundling Infrastructure | Germany's Diagnosis-Related Group refinements create episode-based reimbursement opportunities for integrated pulmonary rehabilitation services. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at national payers, and hospital procurement managers with secondary validation through FDA orphan drug designations, EMA PRIME submissions, ClinicalTrials.gov protocol records, and Medicare Part D formulary databases. Bottom-up patient population estimates and top-down antifibrotic prescription volume reconstructions were triangulated against manufacturer-reported sales disclosures.
Segment-weighting approaches distributed value across therapy area, delivery mode, end user, and application dimensions, with regional regulatory clusters and site-of-care migration patterns modeled as cross-cutting variables. CAGRs were derived from fitted growth curves anchored to diagnosed prevalence projections and treatment penetration assumptions. Forecast inputs incorporated pulmonology specialist density by metropolitan area, Medicare reimbursement rate stability, and patent expiration timelines for first-generation antifibrotics.
Caveats apply where diagnostic latency reduction, generic substitution acceleration, or API supply disruptions could materially shift the outlook. Forecasts reflect assumptions about orphan drug exclusivity duration and specialty pharmacy channel concentration that warrant monitoring against regulatory and competitive developments. Material deviation in FDA breakthrough designation timelines or EMA pharmacovigilance requirement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Pseudomonas Aeruginosa Treatment Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Primary Ciliary Dyskinesia Market
Specialty Medicine
Global Specialty Injectable Generics Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Post-Traumatic Stress Disorder Treatment Market
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Global Lupus Market
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Non-Alcoholic Steatohepatitis Treatment Market
Specialty Medicine
Global Childhood Absence Epilepsy Treatment Market
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
Global Gastroesophageal Reflux Disease Market
Specialty Medicine
Solid Tumor Therapeutics Market