
 Global Breast Cancer Therapeutics Market | 2026-2036
Global Breast Cancer Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Breast Cancer Therapeutics Market Foresight
EMA's Good Manufacturing Practice certification for antibody-drug conjugates is bifurcating the competitive field into qualified biologics manufacturers and legacy small-molecule suppliers. Roche Holding AG leverages its vertically integrated diagnostics-therapeutics platform to sustain leadership in HER2-directed therapy. Pfizer Inc. anchors its position through manufacturing scale across North American and European production networks. Novartis AG differentiates via radiopharmaceutical capabilities that occupy a narrow but high-barrier niche.
Breast cancer therapeutics comprise pharmaceutical agents and biologics designed to interrupt oncogenic signaling, induce apoptosis, or mobilize immune responses against malignant breast tissue, with antibody-drug conjugates requiring precise drug-to-antibody ratios between 3.5 and 4.0 for optimal efficacy-toxicity profiles. These treatments serve the primary commercial purpose of extending progression-free survival in metastatic settings and reducing recurrence risk in adjuvant protocols. Targeted therapy commands the largest current revenue pool given established HER2 and CDK4/6 franchises, while immunotherapy represents the fastest-expanding category as checkpoint inhibitors penetrate triple-negative disease. The therapy area dimension shows HER2-positive segments maintaining mature profitability, whereas triple-negative breast cancer attracts disproportionate R&D investment due to unmet medical need.
FDA accelerated approval pathways, EMA conditional marketing authorization, and Japan's PMDA sakigake designation collectively compress development timelines while intensifying post-market evidence requirements. These regulatory frameworks shape demand by rewarding therapies demonstrating overall survival benefit in confirmatory trials with preferential formulary placement. Stakeholders must monitor evolving biomarker definitions and companion diagnostic requirements that determine patient eligibility and reimbursement access across jurisdictions.
Market Dynamics
FDA's accelerated approval pathway for breakthrough therapies compresses commercialization timelines from 10 years to 6-7 years, intensifying post-market evidence collection and reshaping how manufacturers allocate clinical trial resources across confirmatory studies.
Growth Catalysts
- EMA Conditional Marketing Authorization:European regulators permit early patient access while confirmatory trials continue, accelerating revenue recognition for antibody-drug conjugates before full approval.
- Oncology Clinic Consolidation:Large cancer centers in the United States negotiate formulary placement directly with manufacturers, bypassing traditional pharmacy benefit managers for infused biologics.
- Companion Diagnostic Mandates:Biomarker testing requirements for HER2, PD-L1, and BRCA status expand addressable patient pools by precisely identifying therapy-eligible populations.
Market Restraints
- Plasma-Derived Raw Material Concentration:Over 70% of high-grade fetal bovine serum supply originates from controlled herds in Australia and New Zealand, creating single-source vulnerability for cell culture media production.
- Complex Manufacturing Yields:Antibody-drug conjugate production achieves 40-60% yield rates versus 85-95% for monoclonal antibodies, constraining supply elasticity during demand surges.
- Reimbursement Compression:Germany's G-BA early benefit assessment frequently assigns non-quantifiable added benefit ratings to novel agents, triggering mandatory price negotiations below launch thresholds.
Strategic Opportunities
- Japan's PMDA Sakigake Designation:Priority review status for innovative oncology products reduces regulatory review timelines, enabling first-mover advantage in Asia-Pacific's second-largest pharmaceutical market.
- Radiopharmaceutical Theranostics Convergence:Paired diagnostic imaging and therapeutic isotope delivery creates new reimbursement categories for lutetium-based agents in bone metastasis.
- Direct-to-Patient Specialty Pharmacy:Oral targeted therapies bypass infusion center dependency, opening rural and community access points previously unreachable by hospital-based administration.
Industry Challenges
- ADC Payload-Conjugate Chemistry Talent Scarcity:Drug-to-antibody ratio optimization and linker stability engineering require rare cross-disciplinary expertise spanning synthetic chemistry and protein engineering.
- Multi-Jurisdictional Evidence Generation:Divergent biomarker acceptance criteria between FDA, EMA, and PMDA force parallel clinical program designs, inflating trial costs without proportional patient recruitment efficiency.
- Cold Chain Integrity for Biologics:Temperature excursions during distribution destroy potency of temperature-sensitive monoclonal antibodies, requiring redundant monitoring infrastructure across last-mile logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Breast Cancer Therapeutics Market |
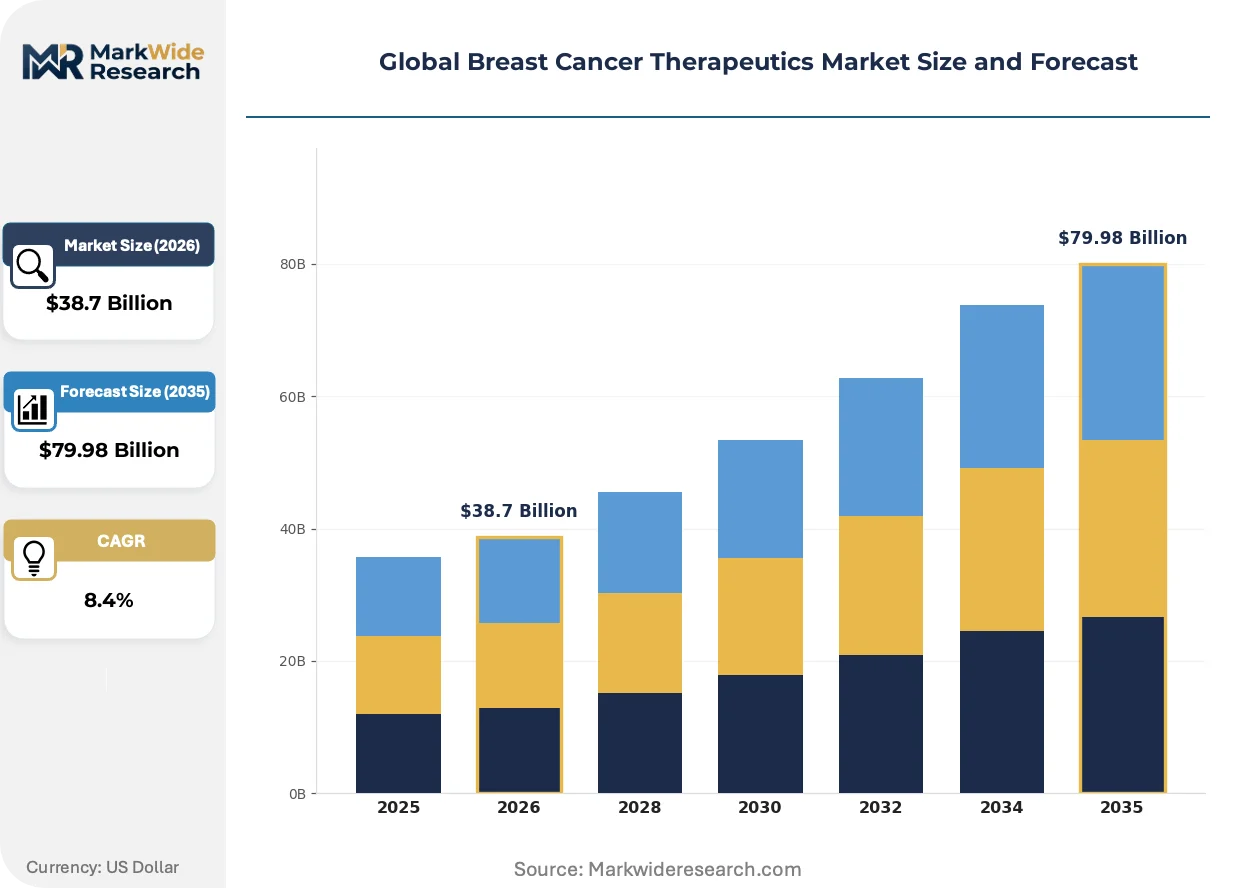
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormone Therapy, Targeted Therapy, Chemotherapy, Immunotherapy, Radiopharmaceuticals Therapy Area: HER2-Positive, Triple Negative, ER-Positive, Inflammatory, Ductal Carcinoma End User: Oncology Clinics, Cancer Centers, Research Institutes, Specialty Hospitals, Diagnostic Labs Delivery Mode: Oral, Intravenous, Subcutaneous, Intramuscular, Implantable Devices |
| Companies Covered | Roche Holding AG, Pfizer Inc., Novartis AG, AstraZeneca, Eli Lilly and Company, Merck & Co., Inc., Bristol-Myers Squibb Company, Eisai Co., Ltd., AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Breast Cancer Therapeutics Market Shifts & Advancements
Precision medicine architectures are fragmenting traditional oncology treatment paradigms, replacing empirical chemotherapy selection with biomarker-driven therapy assignment that demands simultaneous evolution in diagnostic infrastructure and clinical workflow redesign.
Antibody-drug conjugate engineering is fragmenting the cytotoxic payload landscape as manufacturers move beyond auristatin and maytansinoid warheads toward novel topoisomerase inhibitors and DNA alkylating agents. Community oncology practices in the United States adopt these agents faster than academic centers due to streamlined prior authorization pathways for infused therapies. The resulting therapeutic pluralism is fragmenting market share concentration among HER2-directed franchises.
REACH regulation amendments governing pharmaceutical manufacturing effluent standards are forcing European production facilities to install advanced oxidation processes for cytotoxic compound destruction. This environmental compliance layer adds 8-12% to manufacturing overhead for batch production. Contract manufacturing organizations in Germany and Switzerland are responding by consolidating production into purpose-built greenfield sites with integrated waste treatment.
Hospital procurement committees increasingly require real-world evidence dashboards demonstrating progression-free survival in their specific patient populations before granting formulary access to premium immuno-oncology agents. Traditional reliance on randomized controlled trial data is yielding to institution-specific outcomes contracts that tie reimbursement to measured clinical benefit. This behavioral shift is most pronounced in integrated delivery networks across California and Texas where pharmacy spend exceeds 25% of oncology service line revenue.
Global Breast Cancer Therapeutics Market Segmentation
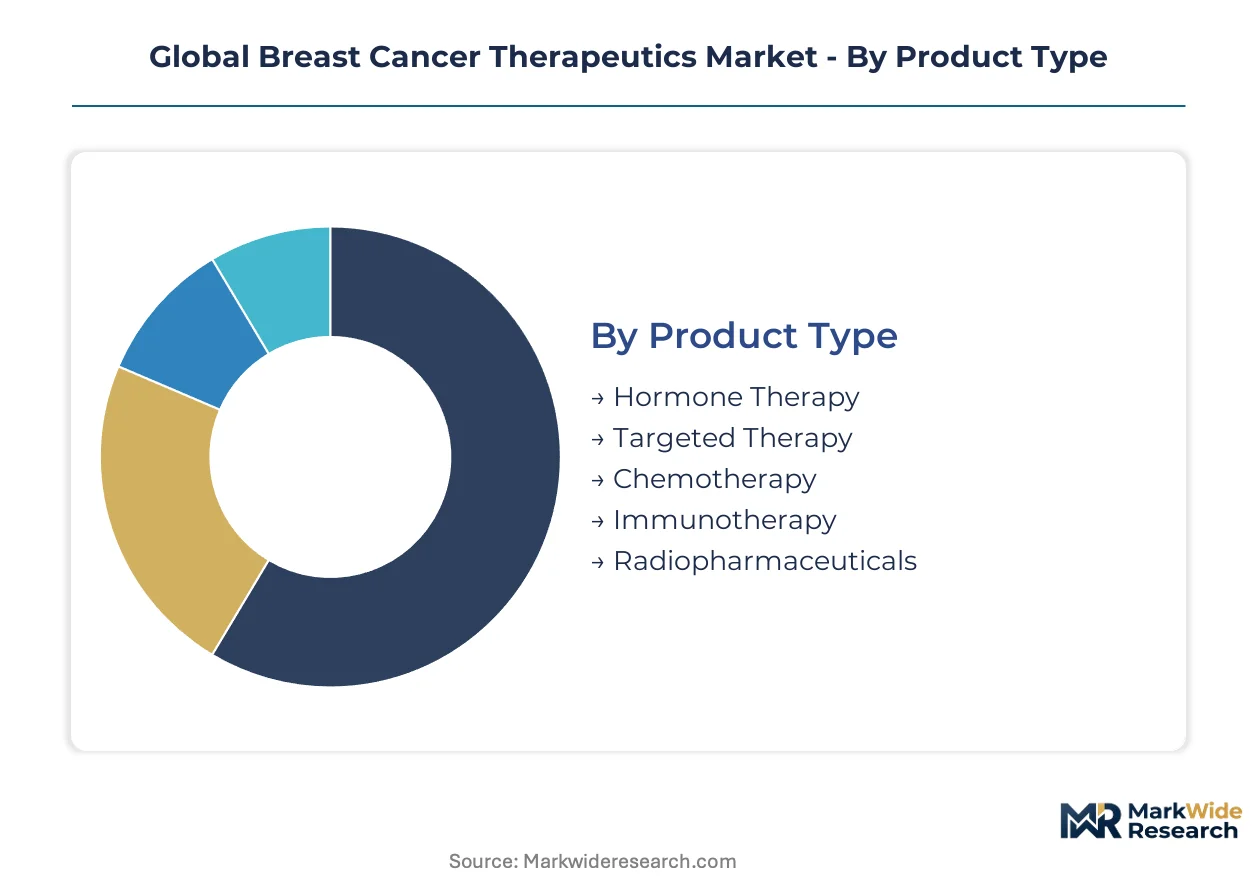
Channel configuration in breast cancer therapeutics determines which segments reach patients through hospital infusion centers versus retail pharmacy networks. Understanding these pathways illuminates where manufacturers must build distribution partnerships and where formulary negotiations concentrate.
Product Type:
Infused biologics flow through oncology clinic purchasing committees, while oral agents route through specialty pharmacy benefit managers with distinct prior authorization protocols.
- Targeted Therapy:HER2-directed monoclonal antibodies and CDK4/6 inhibitors constitute the revenue core, with trastuzumab biosimilars now penetrating through integrated delivery networks in Texas and California. Hospital procurement committees demand real-world progression-free survival dashboards before granting formulary access.
- Immunotherapy:Checkpoint inhibitors for triple-negative disease require PD-L1 companion diagnostic testing, creating parallel demand for laboratory infrastructure. Community oncology practices adopt these agents faster than academic centers due to streamlined prior authorization pathways.
- Hormone Therapy:Oral aromatase inhibitors and selective estrogen receptor modulators distribute through retail pharmacy channels with established generic substitution patterns.
- Chemotherapy:Cytotoxic agents remain embedded in neoadjuvant protocols, with taxane and anthracycline combinations purchased through group purchasing organizations.
- Radiopharmaceuticals:Lutetium-based bone-seeking agents require nuclear medicine infrastructure and specialized handling licenses, limiting deployment to major cancer centers.
Targeted therapy dominates installed base. Immunotherapy is where expansion concentrates.
Therapy Area:
Biomarker-defined segments command premium pricing tiers commensurate with diagnostic confirmation requirements and eligible population precision.
- HER2-Positive:Established diagnostic infrastructure and decades of clinical data support mature profitability, though biosimilar entry compresses margins in European markets where EMA has approved multiple trastuzumab alternatives.
- Triple Negative:Absence of hormone receptor and HER2 expression creates urgent unmet need, attracting disproportionate R&D investment into antibody-drug conjugates and immunotherapy combinations. Japan's PMDA has granted sakigake priority review to multiple investigational agents in this category.
- ER-Positive:CDK4/6 inhibitor combinations with endocrine therapy define current standard of care, with resistance mechanisms now driving next-generation PI3K inhibitor development.
- Inflammatory:Aggressive presentation requires multimodal neoadjuvant approaches, concentrating demand at academic medical centers with surgical oncology expertise.
- Ductal Carcinoma:Early-stage disease management emphasizes recurrence risk reduction through adjuvant endocrine and targeted protocols.
HER2-positive segments anchor current revenue. Triple negative attracts the steepest expansion trajectory.
End User:
Site-of-care economics reshape procurement authority, with hospital-owned clinics consolidating purchasing power previously fragmented across independent practices.
- Oncology Clinics:Physician-owned and hospital-affiliated infusion centers negotiate directly with manufacturers for biologic purchasing, bypassing traditional pharmacy benefit managers.
- Cancer Centers:National Cancer Institute-designated comprehensive centers command preferred pricing through volume commitments and clinical trial participation.
- Specialty Hospitals:Women's health-focused institutions concentrate demand for breast-specific surgical and medical oncology services.
- Research Institutes:Early-phase clinical trial sites generate demand for investigational agents before commercial launch.
- Diagnostic Labs:Companion diagnostic testing facilities create parallel revenue streams tied to therapy eligibility determination.
Cancer centers dominate clinical trial volume. Oncology clinics concentrate commercial dispensing expansion.
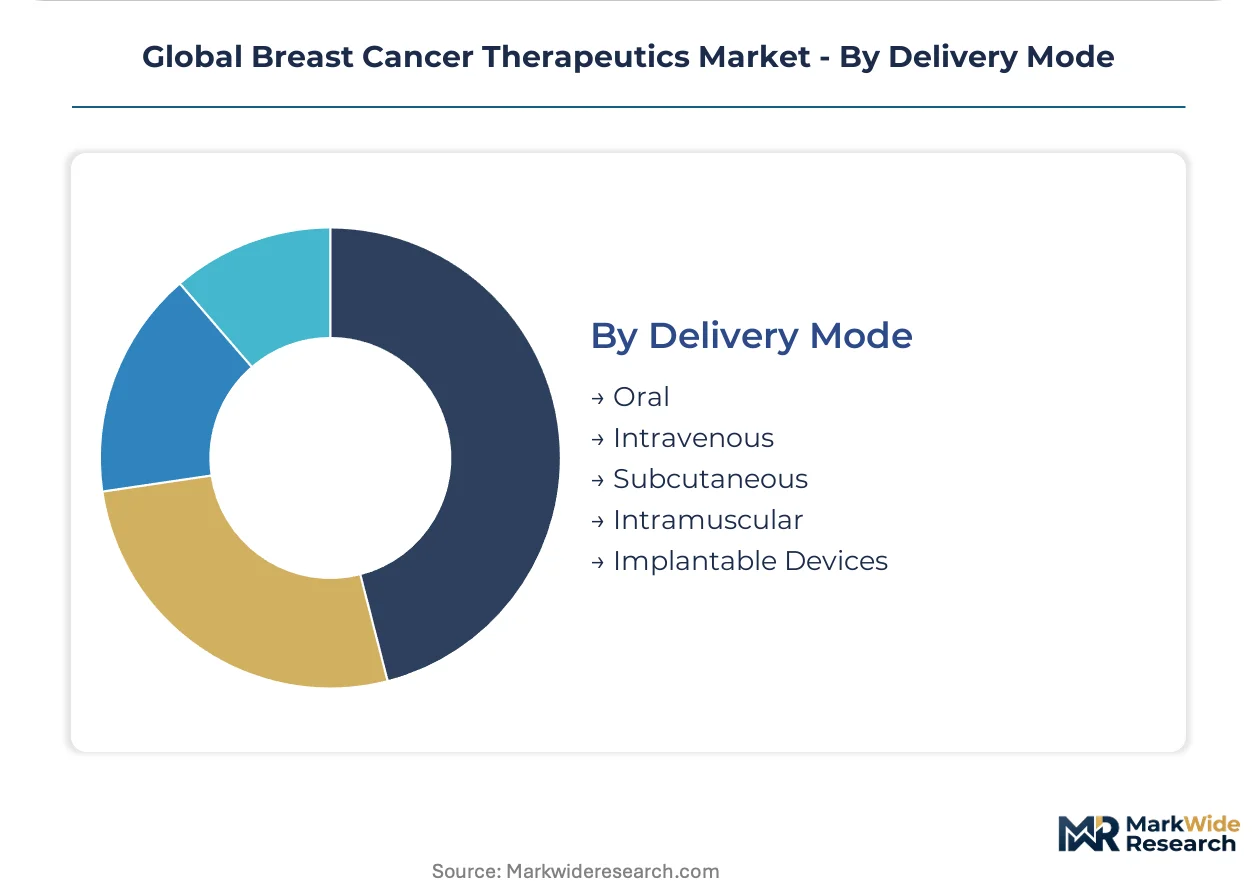
Delivery Mode:
Administration route determines site-of-care requirements, reimbursement coding, and patient convenience trade-offs that shape competitive positioning.
- Intravenous:Infusion center dependency creates capacity constraints and scheduling friction, though biosimilar substitution has reduced per-dose costs in German and US markets.
- Oral:Subcutaneous trastuzumab formulations and small molecule kinase inhibitors enable home administration, expanding rural access points unreachable by hospital-based care.
- Subcutaneous:Fixed-dose formulations reduce pharmacy preparation time and enable patient self-administration training.
- Intramuscular:Luteinizing hormone-releasing hormone agonists for ovarian suppression in premenopausal patients.
- Implantable Devices:Experimental localized drug delivery systems in development for sustained release applications.
Intravenous maintains protocol dominance. Oral administration is gaining share fastest among patient convenience segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology clinics in the United States, Germany, and Japan command the steepest premium pricing for immuno-oncology agents, while reimbursement frameworks in these markets increasingly tie formulary placement to real-world survival data. Hospital procurement committees in these geographies negotiate directly with manufacturers for infused biologics, bypassing traditional pharmacy benefit managers.
United States
National Cancer Institute-designated comprehensive cancer centers in Houston and Boston anchor clinical trial volume for antibody-drug conjugates. FDA's accelerated approval pathway compresses commercialization timelines, enabling earlier revenue recognition for breakthrough therapies. The MD Anderson Cancer Center and Dana-Farber Cancer Institute concentrate demand for investigational HER2-directed agents.
Germany
G-BA early benefit assessments frequently assign non-quantifiable added benefit ratings to novel agents, triggering mandatory price negotiations below launch thresholds. EMA's Good Manufacturing Practice certification for antibody-drug conjugates bifurcates qualified biologics manufacturers from legacy small-molecule suppliers. Production facilities in Baden-Württemberg and Bavaria are installing advanced oxidation processes for cytotoxic compound destruction under REACH amendments.
Japan
PMDA's sakigake designation grants priority review status to innovative oncology products, reducing regulatory timelines for triple-negative breast cancer agents. The Tokyo and Osaka metropolitan areas concentrate diagnostic laboratory infrastructure for PD-L1 companion testing. Japan's reimbursement framework favors premium immuno-oncology agents with demonstrated overall survival benefit.
Switzerland
Swissmedic maintains stringent batch release requirements for biologics that align with EMA standards while preserving national autonomy. Basel and Zurich host vertically integrated diagnostics-therapeutics platforms serving cross-border European demand. Contract manufacturing organizations are consolidating production into purpose-built greenfield sites with integrated waste treatment.
United Kingdom
NICE technology appraisals increasingly require cost-effectiveness thresholds below £30,000 per quality-adjusted life year for routine formulary access. London and Cambridge concentrate early-phase clinical trial sites generating demand for investigational agents. The Cancer Drugs Fund provides managed access pathways for promising therapies pending confirmatory trial data.
Global Breast Cancer Therapeutics Market Competitive Landscape
Player mix skews toward vertically integrated pharmaceutical conglomerates with diagnostics capabilities and specialized biologics manufacturers with antibody-drug conjugate expertise. Market structure concentrates around three to five dominant conglomerates controlling HER2-directed and CDK4/6 inhibitor franchises, while mid-tier specialists compete on radiopharmaceutical and biosimilar vectors. Strategic archetypes include diagnostics-therapeutics integrators, manufacturing-scale anchors, and narrow-niche radiopharmaceutical specialists. Competitive moves center on companion diagnostic co-development partnerships and manufacturing capacity expansion for antibody-drug conjugates.
Within the diagnostics-therapeutics integrator tier, Roche Holding AG occupies a position exemplifying vertical control over biomarker testing and therapy delivery. Pfizer Inc. and Novartis AG represent manufacturing-scale anchors with differentiated production network configurations across North American and European facilities. These three conglomerates anchor the competitive structure, with Roche exemplifying platform integration, Pfizer representing manufacturing scale, and Novartis occupying the radiopharmaceutical niche.
| Leading Market Players |
|---|
| Roche Holding AG |
| Pfizer Inc. |
| Novartis AG |
| AstraZeneca |
| Eli Lilly and Company |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Eisai Co., Ltd. |
| AbbVie Inc. |
| Others |
Supply & Pricing Matrix
EMA Good Manufacturing Practice certification for antibody-drug conjugates gates both supply qualification and price differentiation simultaneously, creating bifurcated access between certified biologics manufacturers and legacy small-molecule suppliers unable to meet the stringent drug-to-antibody ratio specifications.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate long-term supply agreements for monoclonal antibodies, though biosimilar entry has compressed margins in European markets where EMA-approved trastuzumab alternatives now compete on price. Price differentiation rests on GMP certification tier and manufacturing scale, with hospital procurement committees in the United States and Germany demanding real-world survival dashboards before granting formulary access to premium agents. Cost compression in the HER2-directed segment intensifies as biosimilars penetrate integrated delivery networks. Community oncology practices exhibit highest price sensitivity due to streamlined prior authorization pathways, while National Cancer Institute-designated centers command preferred pricing through volume commitments.
Supply Chain Analysis
Australia and New Zealand anchor high-grade fetal bovine serum production for cell culture media, with over seventy percent of controlled-herd supply originating from these jurisdictions. Antibody-drug conjugate manufacturing draws from synthetic chemistry expertise in Switzerland and Germany, while fill-finish operations concentrate in North American and European facilities. Single-source vulnerability in plasma-derived raw materials creates supply risk during demand surges for breakthrough therapies. Distribution runs through oncology clinic purchasing committees for infused biologics and specialty pharmacy benefit managers for oral agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The breast cancer therapeutics market sits in early-cycle expansion, with FDA accelerated approval pathways compressing commercialization timelines and enabling earlier revenue recognition for antibody-drug conjugates and checkpoint inhibitors.
For Market Incumbents: Consolidate manufacturing capacity in EMA-certified facilities to defend against biosimilar erosion in the HER2-directed segment. Deepen backward integration into diagnostic infrastructure to capture companion diagnostic revenue streams tied to PD-L1 and BRCA testing requirements. Lock in long-term fetal bovine serum supply contracts with Australian and New Zealand producers to mitigate single-source raw material vulnerability.
For New Entrants and Emerging Players: Japan's PMDA sakigake designation offers priority review fast-track for innovative triple-negative breast cancer agents, creating first-mover advantage in Asia-Pacific's second-largest pharmaceutical market. Target radiopharmaceutical theranostics as the most penetrable niche, where lutetium-based bone-seeking agents require specialized handling licenses that limit competition. Pursue direct-to-patient specialty pharmacy partnerships for oral targeted therapies to bypass hospital infusion center dependency.
For Investors and Strategic Acquirers: FDA confirmatory trial requirements reshape the acquisition landscape by rewarding therapies with demonstrated overall survival benefit in post-market studies. The five-to-ten year viability window favors vertically integrated diagnostics-therapeutics platforms over standalone manufacturing assets. Watch for EMA conditional marketing authorization decisions as inflection indicators for early revenue recognition potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | PD-L1 and BRCA testing mandates lock in therapy-eligible patient identification. |
| Antibody-Drug Conjugate Manufacturing Scale-Up | EMA GMP certification requirements limit qualified production capacity expansion. |
| Radiopharmaceutical Theranostics Platform | Paired diagnostic imaging and therapeutic isotope delivery creates new reimbursement categories. |
| Direct-to-Patient Specialty Pharmacy Network | Oral targeted therapies expand rural access points beyond hospital-based administration. |
| Real-World Evidence Dashboard Development | Hospital procurement committees in California and Texas demand institution-specific outcomes contracts. |
Research Methodology
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Primary fieldwork across oncology clinics, cancer centers, and diagnostic laboratories in the United States, Germany, and Japan informed demand-side validation. Secondary sources included SEC 10-K disclosures, GPO contract databases, and CMS Medicare reimbursement data. Bottom-up patient-flow modeling and top-down market sizing triangulated volume estimates.
Variance decomposition across therapy area, product type, delivery mode, and regional regulatory cluster informed the analytical framework. Segmentation dimensions modeled included treatment line, administration route, and biomarker-defined patient population. CAGRs were derived from patient incidence projections, therapy penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated companion diagnostic adoption rates, biosimilar entry timelines, and accelerated approval pathway utilization.
Decision-makers should treat outputs as directional under assumptions of stable regulatory frameworks and continued reimbursement favorability for immuno-oncology agents; material deviation in G-BA benefit assessments or FDA confirmatory trial outcomes would warrant model refresh. Recalibration cycles align with material shifts in biomarker definitions, companion diagnostic requirements, and post-market evidence generation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Vitiligo Treatment Market
Specialty Medicine
Interstitial Lung Disease Treatment Market
Specialty Medicine
Global Gastrointestinal Stromal Tumors Market
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market
Specialty Medicine
TIL Therapy Market
Specialty Medicine
Global Gastroesophageal Reflux Disease Market
Specialty Medicine
Europe Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Americas Gerd and Nerd Treatment Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
Global Major Depressive Disorder (MDD) Market
Specialty Medicine
Pseudobulbar Treatment Market
Specialty Medicine
Borderline Personality Disorder Market
Specialty Medicine
Osteomyelitis Market
Specialty Medicine
Barlow's Syndrome Market