
 Medical Foods for Orphan Diseases Market | 2026-2036
Medical Foods for Orphan Diseases Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Foods for Orphan Diseases Market Intelligence
FDA orphan drug incentives are broadening the cost-of-entry calculus for developers of disease-specific nutritional therapies. Abbott Laboratories leverages its pediatric metabolic portfolio to anchor distribution across North American hospital networks. Danone Nutricia specializes in inherited metabolic disorder formulations, while Cambrooke Therapeutics competes through precision amino acid profiles for phenylketonuria and related conditions.
Medical foods for orphan diseases constitute formulated nutritional products designed to meet distinctive dietary requirements of rare disease patients, typically manufactured under cGMP standards with precise macronutrient and micronutrient ratios tailored to genetic metabolic defects. These products serve the primary commercial purpose of preventing disease progression, managing symptoms, and reducing hospitalization frequency in populations where standard nutrition proves metabolically toxic. Liquid formulas dominate current revenue pools due to their suitability for enteral feeding in pediatric and dysphagic patients, while powdered supplements represent the fastest-expanding category as home-care protocols gain traction among caregivers seeking portability and dosing flexibility. Inherited metabolic disorders anchor therapy area demand, with neuromuscular disorders emerging as a concentrated margin pool where reimbursement codes remain underdeveloped.
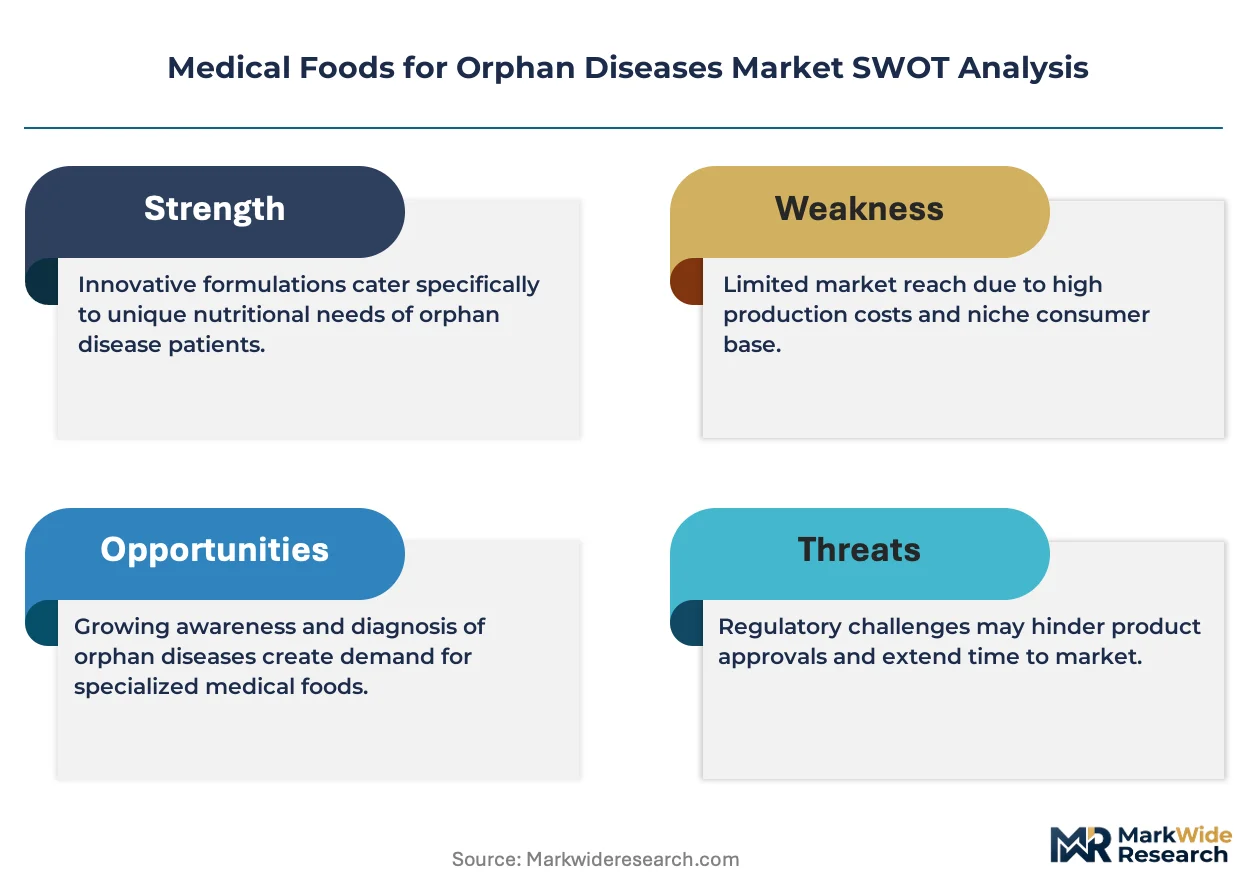
FDA medical food regulations, EFSA health claims protocols, and state-level Medicaid rare disease carve-outs collectively shape product standards, labeling requirements, and market access pathways across jurisdictions. The FDA distinguishes medical foods from drugs through its 21 CFR 101.9(j) framework, yet orphan disease overlap creates compliance ambiguity that manufacturers must navigate. Stakeholders should monitor evolving FDA guidance on medical food versus drug classification, as reclassification risk threatens existing product portfolios and reimbursement structures.
Market Dynamics
Pediatric metabolic clinics are consolidating their purchasing power through group procurement organizations, compressing price points for condition-specific nutritional formulations while demanding tighter cGMP documentation from suppliers.
Growth Catalysts
- FDA orphan drug framework:The FDA's expanded reimbursement pathways for medical foods under rare disease designations reduce cost-of-entry barriers for developers of amino acid-modified formulas.
- Home-care protocols:Caregivers managing phenylketonuria and maple syrup urine disease are adopting powdered supplement formats that enable precise dosing outside clinical settings.
- Medicaid rare disease carve-outs:State-level coverage expansions in the United States eliminate prior authorization delays for inherited metabolic disorder patients requiring lifelong nutritional therapy.
Market Restraints
- Specialized raw material concentration:Pharmaceutical-grade amino acid suppliers cluster in Switzerland and Germany, creating single-source vulnerability for precision-formulation manufacturers.
- Regulatory classification ambiguity:FDA 21 CFR 101.9(j) creates compliance friction when medical food claims overlap with drug-like therapeutic effects, triggering re-examination risk.
- Substitute enteral nutrition:Standard medical foods for general dysphagia management capture budget share from condition-specific orphan formulations in cost-constrained hospital settings.
Strategic Opportunities
- Neuromuscular disorder expansion:Spinal muscular atrophy and Duchenne muscular dystrophy patient populations lack dedicated medical food protocols, representing formulation white space.
- EFSA health claims harmonization:European Food Safety Authority convergence on inherited metabolic disorder labeling creates pathway for US-manufactured products to access EU reimbursement.
- Direct-to-patient distribution:Specialty pharmacy channels bypass hospital formulary committees, capturing margin previously allocated to institutional procurement.
Industry Challenges
- Metabolic dietitian scarcity:Board-certified specialists in inherited metabolic disorders number fewer than 400 across US pediatric centers, constraining patient onboarding capacity.
- cGMP facility certification timelines:FDA pre-approval inspections for medical food manufacturing sites average 18-24 months, delaying product launches for reformulated amino acid profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Foods for Orphan Diseases Market |
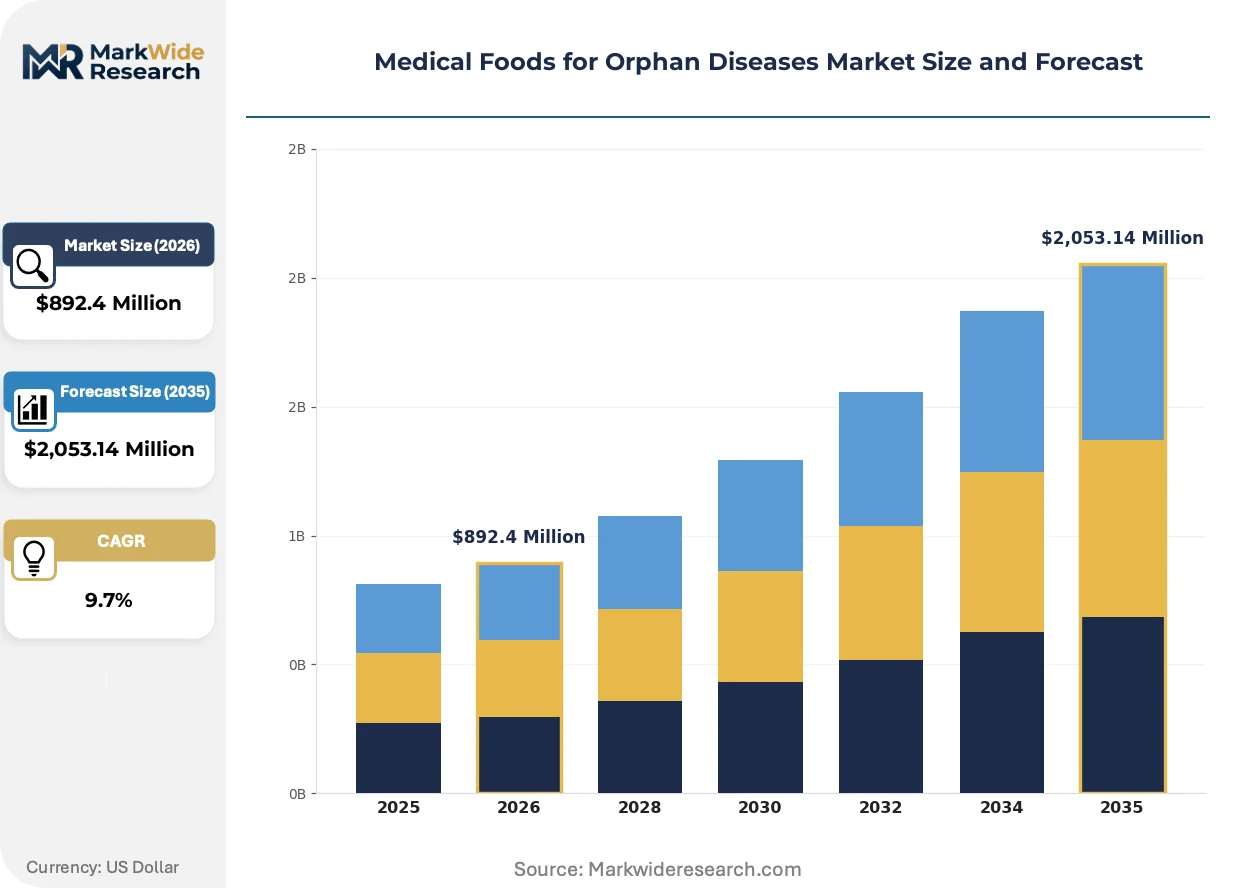
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $2,053.14 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Formulas, Powdered Supplements, Nutritional Bars, Ready-to-Use Foods Delivery Mode: Enteral Feeding, Oral Supplementation, Tube Feeding, Parenteral Nutrition Therapy Area: Inherited Metabolic Disorders, Rare Gastrointestinal Diseases, Neuromuscular Disorders, Specific Nutrient Deficiencies End User: Home Care, Hospitals, Specialized Clinics, Long-term Care Facilities |
| Companies Covered | Nestlé Health Science, Abbott Laboratories, Danone Nutricia, Cambrooke Therapeutics, Vitaflo International Ltd, BioMarin Pharmaceutical Inc., Mead Johnson Nutrition, MedDay Pharmaceuticals, Relmada Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Foods for Orphan Diseases Market Strategic Shifts & Innovations
Precision nutrition platforms are converging with metabolic phenotyping data, enabling real-time formula adjustments that respond to individual enzyme activity levels rather than static diagnosis categories.
Microencapsulation technology for branched-chain amino acids is absorbing volatility in patient plasma level management. Pediatric metabolic programs at Boston Children's Hospital and Children's Hospital of Philadelphia are deploying these stabilized formulations for maple syrup urine disease. The technology is absorbing demand previously served by frequent blood monitoring and emergency hospitalization protocols.
EFSA's 2023 guidance on disease-specific medical food labeling is compressing formulation standardization timelines across EU member states. Manufacturers must now submit amino acid ratio stability data spanning 24-month shelf-life periods. Powdered supplement categories face the steepest compliance burden as member state regulators implement divergent translation requirements for patient instruction leaflets.
Caregiver purchasing committees within rare disease advocacy organizations are consolidating formulary influence previously held by individual prescribers. The National PKU Alliance and similar bodies now negotiate directly with manufacturers for volume-based pricing on phenylalanine-free formulas. This concentration is most visible in the United States, where state Medicaid programs reference these negotiated benchmarks for their own reimbursement schedules.
Medical Foods for Orphan Diseases Market Segmentation
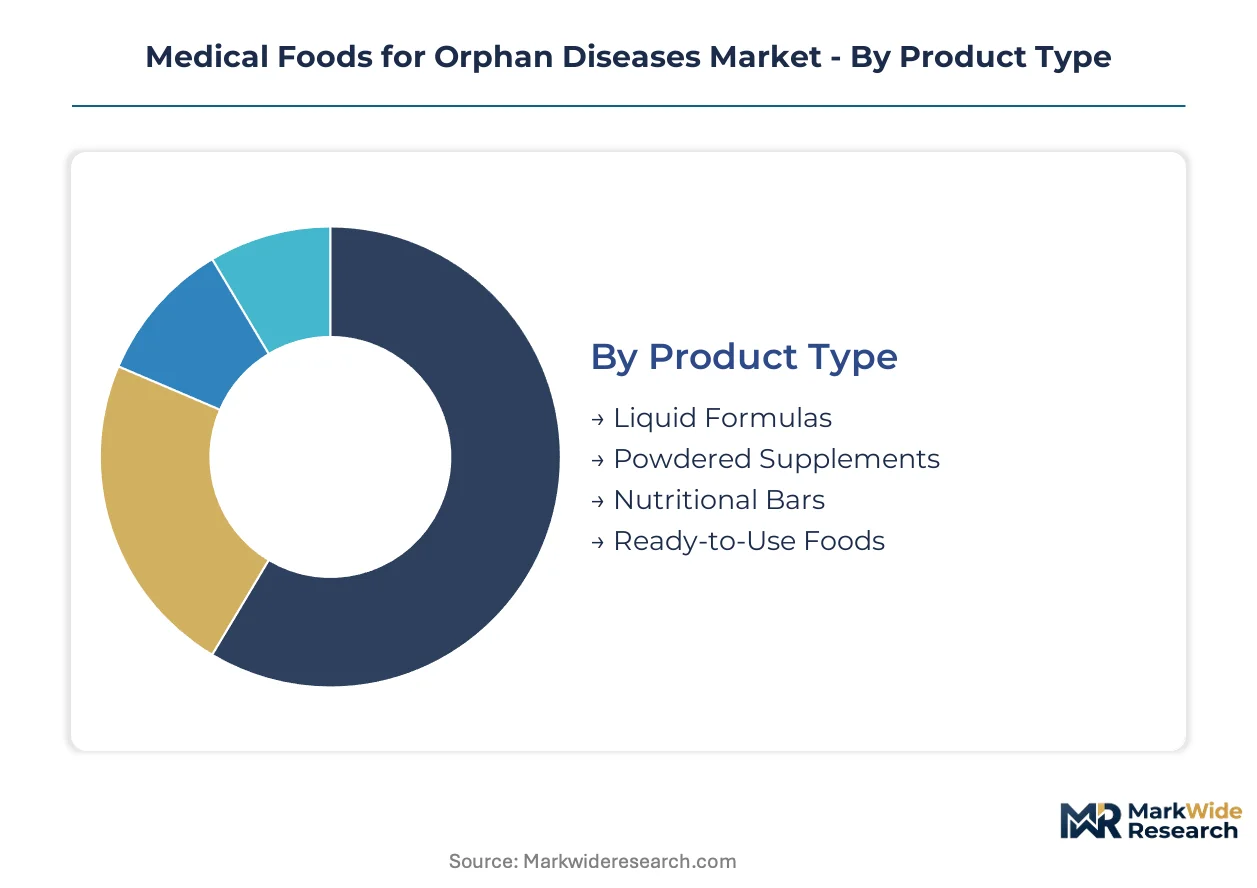
Medical foods for orphan diseases demand precise segmentation because metabolic defects vary by enzyme pathway, age of onset, and feeding capability. Manufacturers must align formulation formats with clinical infrastructure constraints and caregiver mobility needs across distinct therapy areas.
Product Type:
Replacement cycles differ sharply across formats, with liquid formulas requiring refrigerated supply chains that limit shelf life and reorder frequency compared to ambient-stable alternatives.
- Liquid Formulas:Ready-to-feed emulsions with precise amino acid ratios and lipid profiles designed for enteral administration. Demand concentrates in US pediatric metabolic centers where Boston Children's Hospital and Children's Hospital of Philadelphia protocols mandate liquid formats for maple syrup urine disease patients requiring strict plasma level control.
- Powdered Supplements:Dried amino acid blends and micronutrient premixes enabling custom reconstitution. Home-care adoption is accelerating fastest among phenylketonuria caregivers seeking portable dosing flexibility for school-age children managing protein restrictions outside clinical settings.
- Nutritional Bars:Solid matrix products incorporating protein substitutes and vitamin fortification for ambulatory patients with chewing capability.
- Ready-to-Use Foods:Pre-portioned shelf-stable meals requiring no preparation, targeting travel and emergency backup scenarios.
Volume placements concentrate in Liquid Formulas; the faster expansion belongs to Powdered Supplements.
Delivery Mode:
Cost tiers separate institutional from home-based administration, with enteral systems carrying pump and supply overhead that oral formats avoid entirely.
- Enteral Feeding:Gastrostomy or nasogastric tube delivery of complete nutritional formulas. US Medicaid rare disease carve-outs increasingly cover pump equipment and disposable sets, reducing out-of-pocket burden for inherited metabolic disorder families managing long-term feeding dependency.
- Oral Supplementation:Self-administered liquids, powders, or solids consumed by mouth. Neuromuscular disorder patients with preserved swallowing function represent the concentrated margin pool here, as Duchenne muscular dystrophy protocols emphasize caloric density without tube placement.
- Tube Feeding:Bolus or continuous administration via established access devices, distinct from initial enteral placement procedures.
- Parenteral Nutrition:Intravenous amino acid and lipid emulsion delivery for patients with non-functional gastrointestinal tracts, requiring compounding pharmacy infrastructure.
Institutional procurement favors Enteral Feeding; Oral Supplementation is climbing the fastest as home-care protocols expand.
Therapy Area:
Application maturity varies by diagnostic prevalence and reimbursement code development, with well-characterized metabolic defects commanding established protocols versus emerging indications lacking standardized nutritional guidelines.
- Inherited Metabolic Disorders:Phenylketonuria, maple syrup urine disease, and homocystinuria protocols requiring lifelong amino acid-modified nutrition. US state Medicaid programs anchor volume through newborn screening mandates that identify patients requiring immediate dietary intervention.
- Neuromuscular Disorders:Spinal muscular atrophy and Duchenne muscular dystrophy nutritional management addressing hypermetabolism and swallowing dysfunction. Formulation white space persists as no dedicated medical food protocols exist, though specialized clinics at Cincinnati Children's Hospital are piloting branched-chain amino acid supplementation.
- Rare Gastrointestinal Diseases:Short bowel syndrome and intestinal failure formulations emphasizing macronutrient absorption optimization.
- Specific Nutrient Deficiencies:Isolated vitamin or mineral disorders requiring targeted supplementation rather than complete formula replacement.
Revenue concentration sits with Inherited Metabolic Disorders; Neuromuscular Disorders show the steepest expansion trajectory as protocols develop.
End User:
Customer type dictates packaging scale and support intensity, with hospitals purchasing bulk institutional formats while home caregivers need individual-unit convenience and instructional materials.
- Home Care:Family-managed administration of prescribed nutritional therapies outside clinical facilities. Caregiver purchasing committees at the National PKU Alliance and similar advocacy bodies now negotiate volume pricing directly with manufacturers, consolidating influence previously dispersed across individual prescribers.
- Hospitals:Inpatient metabolic crisis management and perioperative nutritional support. Pediatric metabolic clinics at major US academic centers are consolidating purchasing power through group procurement organizations, compressing price points while demanding tighter cGMP documentation.
- Specialized Clinics:Outpatient inherited metabolic disorder programs providing ongoing monitoring and formula adjustment.
- Long-term Care Facilities:Residential settings managing adult patients with chronic nutritional dependencies.
Procurement volume concentrates in Home Care; Specialized Clinics are gaining share fastest as metabolic dietitian capacity constraints shift stable patients from hospital oversight.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orphan disease medical food production clusters in jurisdictions offering rare disease tax credits and specialized manufacturing incentives. FDA orphan drug incentives in the United States and EFSA harmonization efforts in Europe anchor regulatory concentration. Switzerland and Germany supply pharmaceutical-grade amino acids that feed formulation networks across North America and Asia-Pacific.
United States
State Medicaid rare disease carve-outs eliminate prior authorization delays for phenylketonuria and maple syrup urine disease patients. FDA 21 CFR 101.9(j) provides the primary medical food classification framework, though orphan disease overlap creates compliance ambiguity. Boston Children's Hospital and Children's Hospital of Philadelphia anchor pediatric metabolic clinic networks that consolidate purchasing through group procurement organizations.
Germany
Pharmaceutical-grade amino acid suppliers cluster in Baden-Württemberg and North Rhine-Westphalia, creating upstream concentration for European formulators. EFSA health claims protocols on inherited metabolic disorder labeling shape product standardization timelines. Heidelberg University Hospital operates one of Europe's largest inherited metabolic disorder centers, driving protocol development for maple syrup urine disease nutritional management.
Switzerland
Specialized raw material production concentrates around Basel and Zurich, with Swissmedic oversight of medical food manufacturing standards. The country's pharmaceutical heritage supports cGMP facility certification for precision amino acid profiling. University Hospital Zurich maintains reference laboratory status for plasma amino acid monitoring used across German-speaking European metabolic clinics.
United Kingdom
NHS England's highly specialized services commissioning framework funds inherited metabolic disorder nutritional therapies through designated centers. MHRA medical food guidance aligns with EFSA trajectory while maintaining national flexibility on phenylalanine-free formula reimbursement. Manchester University NHS Foundation Trust and Great Ormond Street Hospital coordinate the UK's primary pediatric metabolic networks.
Japan
MHLW rare disease designation programs expand reimbursement for amino acid-modified formulas through specified disease treatment research programs. PMDA consultation pathways for medical food classification remain less developed than FDA or EFSA equivalents. National Center for Child Health and Development in Tokyo anchors metabolic dietitian training capacity that constrains patient onboarding nationwide.
Medical Foods for Orphan Diseases Market Key Industry Players
North American producers anchor one tier; European specialists hold formulation expertise in inherited metabolic disorders. Market structure concentrates around multinational nutrition conglomerates with pediatric metabolic portfolios, mid-cap precision amino acid formulators, and emerging neuromuscular disorder entrants. Tiering separates hospital-contracted institutional suppliers from direct-to-patient specialty pharmacy channels. Competitive moves center on cGMP facility certification timelines and metabolic dietitian training partnerships that accelerate patient onboarding.
Within the multinational nutrition tier, Nestlé Health Science, Abbott Laboratories, and Danone Nutricia exemplify divergent geographic anchoring and portfolio breadth. Nestlé's Swiss-originated structure represents European formulation heritage applied to global metabolic disorder protocols. Abbott's US-based position exemplifies hospital network contracting dominance through pediatric metabolic clinic relationships. Danone Nutricia's Dutch-French origins exemplify EFSA-harmonized labeling expertise applied to inherited metabolic disorder specialization. Cambrooke Therapeutics occupies a distinct position as a precision amino acid specialist focused on phenylketonuria and related conditions.
| Leading Market Players |
|---|
| Nestlé Health Science |
| Abbott Laboratories |
| Danone Nutricia |
| Cambrooke Therapeutics |
| Vitaflo International Ltd |
| BioMarin Pharmaceutical Inc. |
| Mead Johnson Nutrition |
| MedDay Pharmaceuticals |
| Relmada Therapeutics |
| Others |
Cost & Logistics Intelligence
Pharmaceutical-grade amino acid price indices cascade through formulation networks into three-tier pricing structures across premium, standard, and economy levels. Swiss and German raw material benchmarks transmit volatility downstream to US pediatric metabolic clinics negotiating volume contracts through group procurement organizations.
Pricing Analysis
Short lead-time premiums apply to cGMP-certified liquid formulas stocked for metabolic crisis management, while powdered supplements trade at spot discounts when inventory clears ahead of EFSA-mandated shelf-life stability deadlines. Price differentiation rests on FDA 21 CFR 101.9(j) compliance tier and amino acid purity grade. Cost compression in institutional procurement channels intensifies because pediatric metabolic clinics consolidate purchasing power through GPOs. Home-care caregivers show highest price sensitivity due to out-of-pocket burden before Medicaid carve-out reimbursement, while hospital emergency stockpiles demonstrate lowest sensitivity.
Supply Chain Analysis
FDA pre-approval inspections and EFSA health claims protocols gate facility qualification, extending cGMP certification timelines to 18-24 months for new manufacturing sites. Pharmaceutical-grade amino acid production concentrates in Switzerland, Germany, and the Netherlands. Formulation networks draw from branched-chain amino acid precursors, micronutrient premixes, and lipid emulsion bases. Single-source vulnerability persists around Swiss crystalline amino acid suppliers. Distribution runs through specialty pharmacy channels bypassing hospital formulary committees for direct-to-patient delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microencapsulation technology for branched-chain amino acids is displacing legacy plasma monitoring protocols in maple syrup urine disease management. This transition compresses hospitalization frequency and enables home-care dosing precision previously requiring clinical oversight.
For Market Incumbents: Extend metabolic dietitian training partnerships with Boston Children's Hospital and Children's Hospital of Philadelphia to accelerate patient onboarding capacity constrained by board-certified specialist scarcity. Deepen backward integration into pharmaceutical-grade amino acid supply through Swiss and German supplier alliances, mitigating single-source vulnerability threatening formulation continuity. For New Entrants and Emerging Players: Capture neuromuscular disorder formulation white space in spinal muscular atrophy and Duchenne muscular dystrophy protocols where no dedicated medical foods exist. Target caregiver purchasing committees at the National PKU Alliance for direct volume negotiations, bypassing institutional procurement channels that favor established hospital-contracted suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision amino acid specialists with cGMP-certified facilities in North America over capital-intensive greenfield manufacturing plays. Long-term viability across the 5-10 year window hinges on EFSA-US regulatory harmonization progress. Watch for FDA guidance reclassification risk on medical food versus drug designation as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Metabolic Dietitian Training Partnership | Boston Children's Hospital partnerships expand patient onboarding capacity constrained by specialist scarcity. |
| cGMP Facility Certification Investment | FDA pre-approval inspection readiness compresses 18-24 month timelines for amino acid profile launches. |
| Direct-to-Patient Specialty Pharmacy Channel | National PKU Alliance caregiver committees capture margin previously allocated to hospital procurement. |
| Microencapsulation Technology Licensing | Children's Hospital of Philadelphia protocols validate stabilized branched-chain amino acid formulations. |
| EFSA Health Claims Harmonization Pathway | European labeling convergence enables US-manufactured products to access EU reimbursement codes. |
Research Approach
Document review covered FDA 21 CFR guidance documents, EFSA health claims protocols, and state Medicaid rare disease carve-out policies, complemented by interviews with metabolic dietitians, pediatric metabolic clinic directors, GPO procurement managers, and specialty pharmacy channel operators. Secondary validation drew from FDA orphan drug designations, newborn screening mandate databases, and hospital formulary records. Bottom-up patient population estimates triangulated against top-down reimbursement expenditure data across the analysis window.
Cross-referencing historical amino acid price volatility patterns against expert panel inputs on regulatory timeline expectations shaped the projection framework. Segmentation modeling incorporated product format, therapy area, delivery mode, and end-user channel dimensions. CAGRs derived from volume placement trajectories in liquid formulas versus powdered supplement adoption curves, calibrated against metabolic dietitian capacity constraints and cGMP facility certification pipelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA reclassification guidance and EFSA labeling harmonization implementation. Forecasts reflect documented assumptions on Medicaid carve-out expansion rates and newborn screening mandate coverage. A model refresh is warranted upon material change in FDA medical food versus drug classification precedent.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Glucagon Therapy Market
Specialty Medicine
Intussusception Market
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
Pharyngitis Treatment Market
Specialty Medicine
Facial Paralysis Market
Specialty Medicine
Veno-Occlusive Hepatic Disease Therapeutics Market
Specialty Medicine
Europe Precision Medicine Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Post-Traumatic Stress Disorder Treatment Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Global Neurotrophic Keratitis Treatment Market
Specialty Medicine
Meningitis Treatment Market
Specialty Medicine
Premature Ejaculation Treatment Market
Specialty Medicine
Cystinuria Treatment Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Cholangitis Market