
 Oral Cancer Treatment Market | 2026-2036
Oral Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Cancer Treatment Market Analysis
Specialized biologics manufacturing clusters in Switzerland and Ireland are repositioning global supply chains for monoclonal antibodies used in oral oncology. Pfizer Inc. leverages its integrated small-molecule and biologics platforms to sustain manufacturing flexibility across therapy classes. F. Hoffmann-La Roche Ltd. anchors its competitive stance through deep specialization in companion diagnostics linked to targeted therapy selection. Bristol-Myers Squibb Company differentiates via checkpoint inhibitor portfolios that dominate immuno-oncology protocols for recurrent oral malignancies.
Oral cancer treatment encompasses therapeutic interventions targeting malignant neoplasms of the lip, tongue, buccal mucosa, and oropharynx, utilizing cytotoxic agents, ionizing radiation, immune-modulating biologics, and receptor-targeted small molecules administered through systemic or localized delivery routes to achieve tumor regression, organ preservation, or palliative symptom control. Chemotherapy retains the largest patient-volume footprint but faces margin compression from biosimilar competition, while immunotherapy captures the fastest expansion trajectory as PD-1 and CTLA-4 inhibitors secure expanded indications in recurrent and metastatic disease settings. Targeted therapy concentrates value in biomarker-selected patient subsets where EGFR and angiogenesis inhibitors command premium positioning, and radiotherapy maintains structural importance in definitive and adjuvant protocols despite capital-intensive delivery infrastructure.
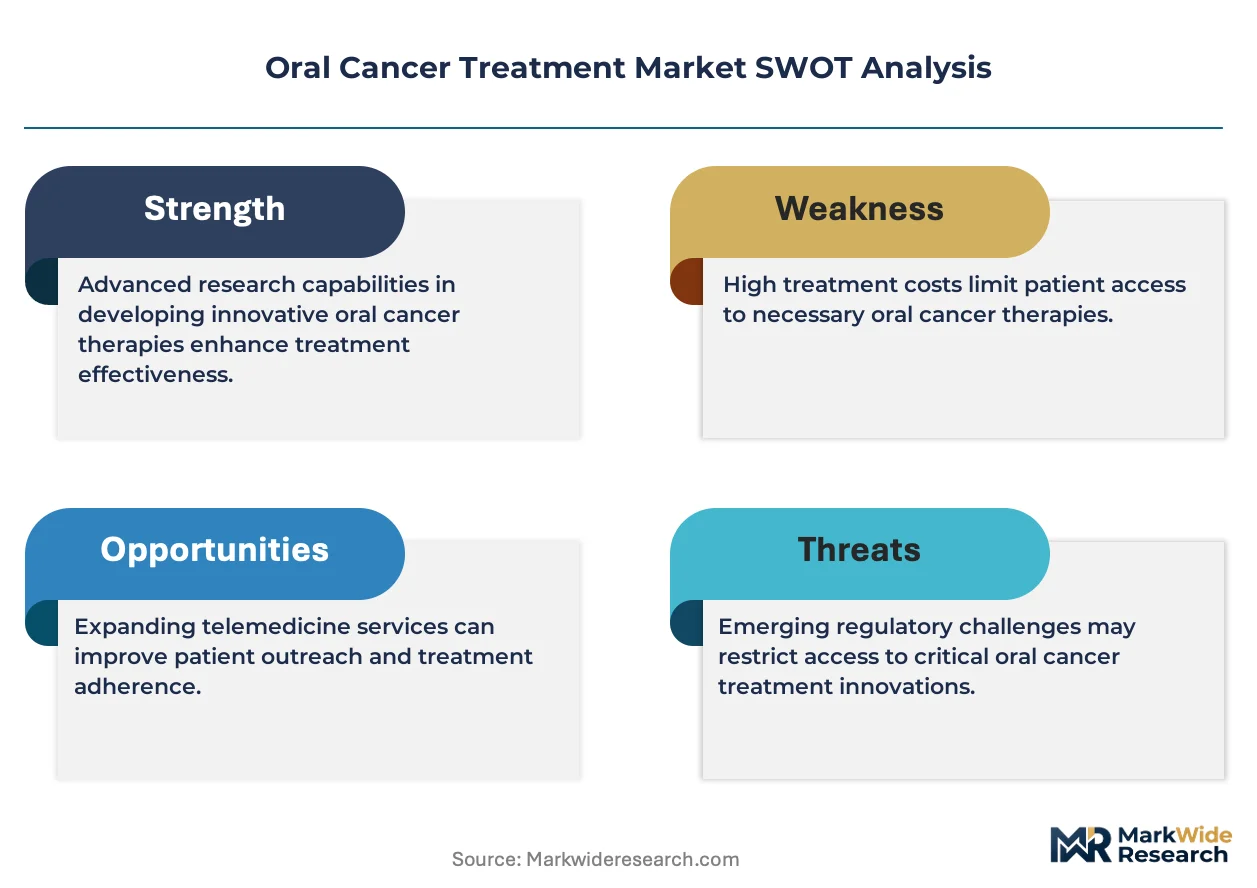
The FDA's Breakthrough Therapy designation and Orphan Drug programs shape clinical trial investment and commercial prioritization for oral oncology developers, while EMA's centralized marketing authorization procedures govern pan-European access and reimbursement negotiations. India's CDSCO alignment with ICH-GCP standards and domestic price control mechanisms under the National Pharmaceutical Pricing Authority create a dual-track environment of innovation incentives and access mandates. Stakeholders must monitor evolving biomarker coverage policies by public and private payers, as molecular testing reimbursement increasingly determines which targeted and immunotherapy segments achieve scalable adoption.
Market Dynamics
FDA's Breakthrough Therapy designation compresses commercialization timelines for immuno-oncology assets, while India's CDSCO alignment with ICH-GCP standards accelerates patient access to novel biologics. This dual-track regulatory environment concentrates investment in checkpoint inhibitor development and companion diagnostic co-development.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's breakthrough therapy and orphan drug programs compress Phase II-to-commercialization timelines, incentivizing developers to prioritize oral oncology indications with unmet need.
- Biomarker-Enabled Patient Selection:Companion diagnostics linked to PD-L1, EGFR, and HPV status are expanding addressable populations for targeted therapy and immunotherapy protocols.
- Government Screening Mandates:India's National Programme for Prevention and Control of Cancer expands tertiary care referrals, concentrating demand in Mumbai, Chennai, and Delhi oncology centers.
Market Restraints
- Biosimilar Margin Compression:Cytotoxic chemotherapy portfolios face pricing pressure as trastuzumab and rituximab biosimilars erode originator margins in India and Europe.
- Radiotherapy Capital Intensity:Linear accelerator and proton therapy infrastructure requires $15-50 million per installation, limiting geographic penetration outside major metropolitan clusters.
- Reimbursement Fragmentation:Molecular testing coverage policies vary across US commercial payers and Medicare Advantage plans, creating adoption friction for biomarker-directed therapy selection.
Strategic Opportunities
- Rural Tertiary Care Expansion:India's district hospital upgrade programs under Ayushman Bharat create white space for mobile chemotherapy units and tele-radiology partnerships.
- Neoadjuvant Immunotherapy Protocols:Checkpoint inhibitor administration prior to surgical resection is expanding organ-preservation indications beyond traditional chemoradiation boundaries.
- Real-World Evidence Pathways:FDA's Project Orbis and EMA's adaptive licensing frameworks enable accelerated post-approval data collection for combination therapy sequencing.
Industry Challenges
- Manufacturing Talent Scarcity:Switzerland and Ireland biologics clusters face acute shortages of cell culture specialists and aseptic fill-finish technicians.
- Cold Chain Integrity:Temperature excursions during monoclonal antibody distribution to Indian tier-2 cities compromise product stability and patient safety.
- Interoperable Data Standards:Electronic health record fragmentation across US oncology networks impedes multi-site trial enrollment and post-market surveillance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Cancer Treatment Market |
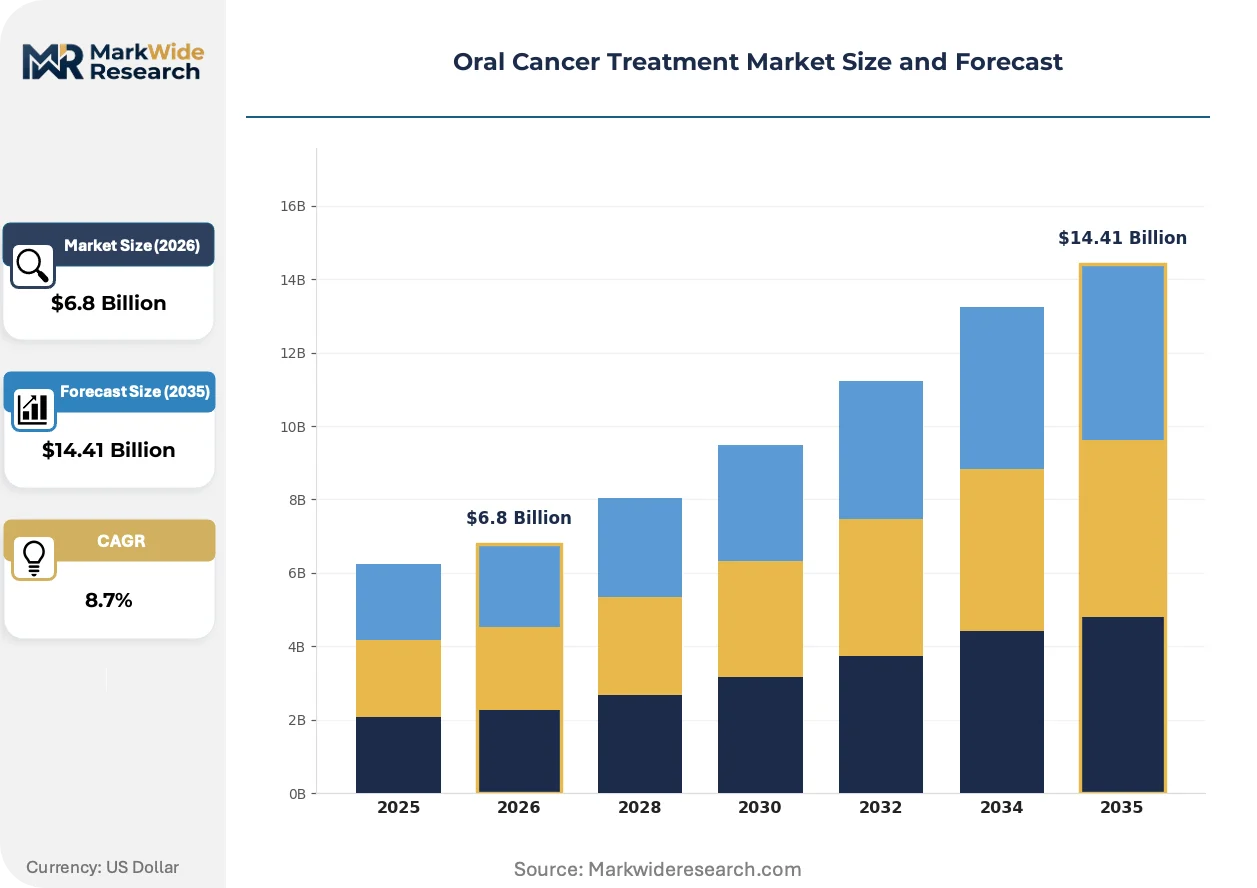
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiotherapy, Immunotherapy, Targeted Therapy Delivery Mode: Oral, Injectable, Intravenous, Topical End User: Hospitals, Oncology Clinics, Homecare, Research Laboratories Treatment Stage: Early Stage, Advanced Stage, Relapse, Palliative Care |
| Companies Covered | Pfizer Inc., F. Hoffmann-La Roche Ltd., Merck & Co., AbbVie Inc., Novartis AG, Bristol-Myers Squibb Company, Eli Lilly and Company, Teva Pharmaceutical Industries Ltd., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Cancer Treatment Market Emerging Trajectories
Artificial intelligence and liquid biopsy technologies are converging to reshape early detection and treatment monitoring protocols. These advances compress diagnostic timelines while enabling longitudinal tumor surveillance without invasive tissue sampling.
Neoadjuvant immunotherapy is modularizing surgical oncology workflows. Academic medical centers in the US and Germany are adopting preoperative checkpoint inhibitor administration as standard protocol for locally advanced oropharyngeal malignancies. This sequencing is enabling organ-preservation outcomes that previously required radical resection, compressing the addressable market for reconstructive surgery while expanding adjuvant therapy duration.
EMA's centralized marketing authorization procedures are harmonizing pan-European access pathways for combination oncology therapies. The regulator's parallel scientific advice program with FDA accelerates transatlantic trial design alignment. Biotechnology developers are responding by prioritizing EU-enriched enrollment strategies for oropharyngeal cancer indications, anticipating faster pricing and reimbursement negotiations in Germany and France.
Hospital procurement committees are consolidating vendor relationships for oncology biologics around integrated service agreements. US health systems including Mayo Clinic and MD Anderson are unbundling drug distribution from clinical pharmacy services, selecting distributors with captive cold chain capabilities. This concentration is most visible in the Southwest and Southeast regions, where temperature-controlled logistics infrastructure determines contract awards.
Oral Cancer Treatment Market Segmentation
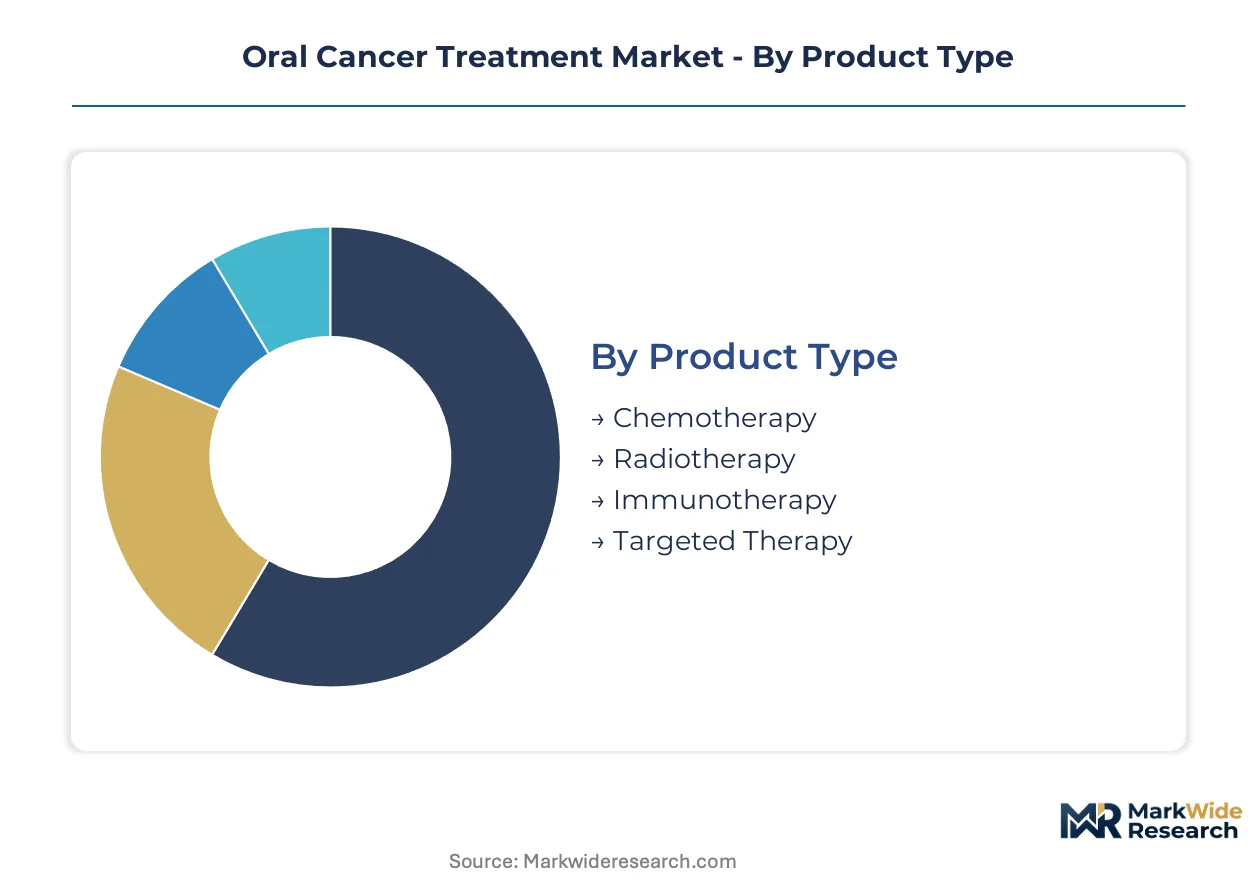
Oral cancer treatment modalities fragment across therapeutic mechanism, administration route, care setting, and disease progression stage. Each segmentation axis reveals distinct procurement patterns, reimbursement pathways, and technology substitution dynamics that reshape competitive positioning.
Product Type:
Upgrade cycles accelerate where biomarker testing infrastructure enables precision therapy selection, compressing legacy protocol durations.
- Immunotherapy:Checkpoint inhibitors targeting PD-1 and CTLA-4 pathways modulate T-cell mediated tumor recognition. Demand concentrates in US academic medical centers with integrated companion diagnostic laboratories, driven by expanded FDA indications for recurrent and metastatic oropharyngeal malignancies.
- Targeted Therapy:EGFR inhibitors and angiogenesis blockers interrupt signal transduction in molecularly selected patient subsets. Oncology clinics in Germany and France prioritize these agents where EMA centralized authorization has streamlined reimbursement.
- Chemotherapy:Platinum-based cytotoxic regimens retain foundational positioning in neoadjuvant and concurrent protocols.
- Radiotherapy:External beam and brachytherapy modalities require capital-intensive linear accelerator infrastructure.
Volume placements concentrate in chemotherapy; the faster expansion belongs to immunotherapy.
Delivery Mode:
Cost tier differentiation separates hospital-administered infusions from self-administered oral formulations, reshaping site-of-care economics.
- Intravenous:Monoclonal antibodies and cytotoxic agents requiring controlled infusion rates dominate hospital outpatient revenue. US oncology clinics are expanding dedicated infusion centers to capture 340B drug pricing advantages.
- Oral:Small-molecule kinase inhibitors enable decentralized administration with remote monitoring protocols. Homecare adoption in India accelerates where Ayushman Bharat reimbursement covers oral oncology agents.
- Injectable:Subcutaneous checkpoint inhibitor formulations reduce infusion chair time.
- Topical:Localized agents address premalignant lesions and palliative mucositis.
Patient preference is shifting toward oral; intravenous retains the revenue concentration.
End User:
Customer type fragmentation reflects divergent procurement authority, with health systems consolidating vendor relationships around integrated service agreements.
- Oncology Clinics:Specialized ambulatory centers concentrate infusion capacity and biomarker testing in metropolitan corridors. US community oncology networks are affiliating with hospital systems to secure 340B pricing on biologics.
- Hospitals:Tertiary academic centers anchor clinical trial enrollment and complex case referral patterns. India's government-funded cancer centers in Mumbai, Chennai, and Delhi drive volume through screening program referrals.
- Homecare:Nursing services support oral therapy adherence and symptom management.
- Research Laboratories:Contract research organizations manage investigational agent handling.
Treatment episodes concentrate in oncology clinics; homecare is climbing the fastest.
Treatment Stage:
Application timing determines therapy intensity, with neoadjuvant protocols expanding organ-preservation indications.
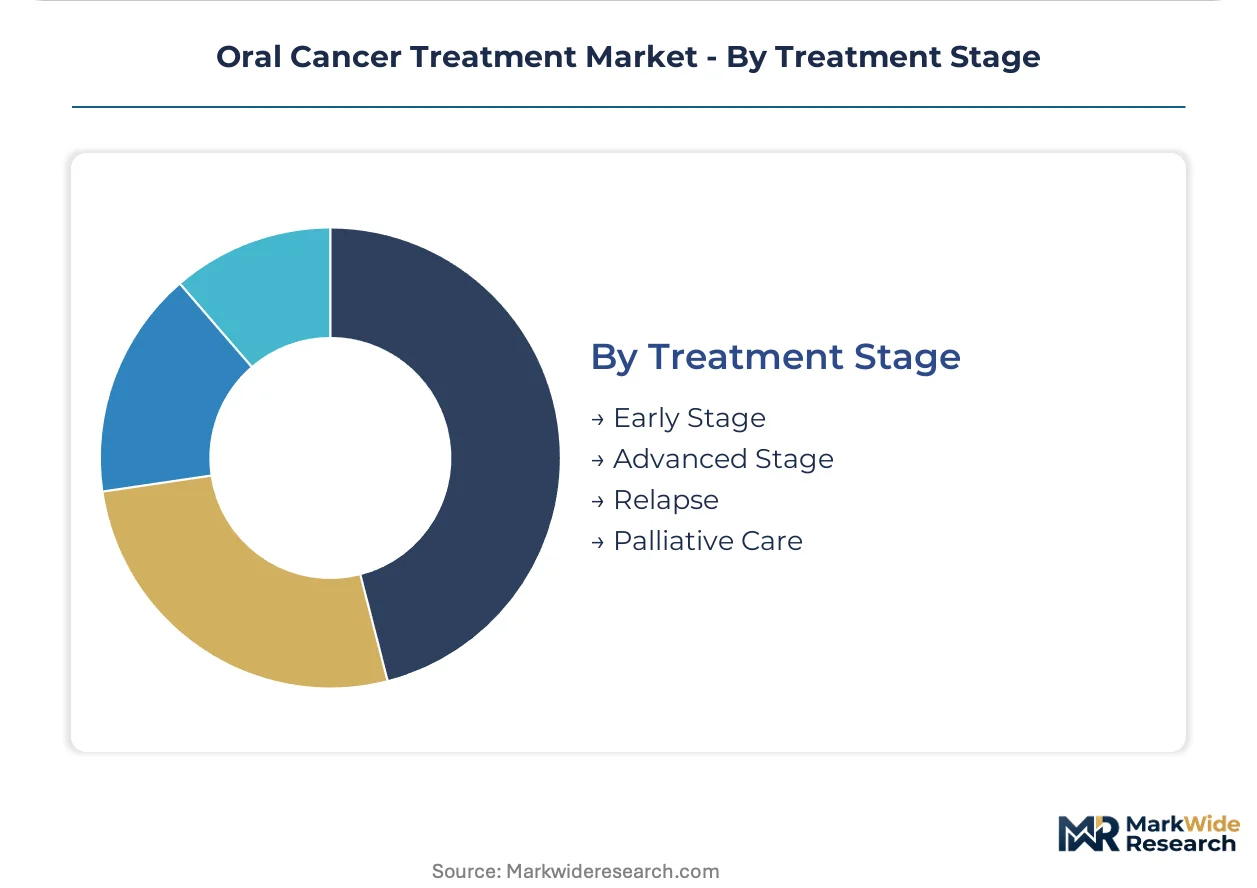
- Advanced Stage:Combination immunotherapy and chemoradiation protocols address unresectable or metastatic disease. Mayo Clinic and MD Anderson are standardizing checkpoint inhibitor sequencing prior to surgical intervention.
- Early Stage:Definitive surgical resection with adjuvant radiation maintains curative intent. German head-and-neck oncology centers emphasize transoral robotic surgery to minimize functional impairment.
- Relapse:Salvage protocols deploy alternative mechanisms after first-line failure.
- Palliative Care:Symptom-directed interventions prioritize quality-of-life endpoints.
Patient volume concentrates in advanced stage; neoadjuvant expansion is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturing clusters in Switzerland and Ireland anchor supply-side positioning for monoclonal antibodies. Patient demand concentrates in oncology corridors where screening programs and tertiary infrastructure intersect.
United States
Academic medical centers in Houston and Boston drive checkpoint inhibitor adoption through integrated companion diagnostic laboratories. FDA breakthrough therapy designations compress Phase II-to-commercialization timelines for recurrent oropharyngeal indications. The Southwest and Southeast regions concentrate infusion capacity around 340B-eligible hospital systems.
India
Government-funded screening programs under the National Programme for Prevention and Control of Cancer expand tertiary care referrals in Mumbai, Chennai, and Delhi. CDSCO alignment with ICH-GCP standards accelerates patient access to novel biologics. District hospital upgrades under Ayushman Bharat create white space for mobile chemotherapy units.
Germany
Head-and-neck oncology centers emphasize transoral robotic surgery to minimize functional impairment in early-stage protocols. EMA centralized authorization streamlines reimbursement for EGFR inhibitors and angiogenesis blockers. The Munich and Heidelberg clusters anchor immuno-oncology trial enrollment.
Switzerland
Specialized biologics manufacturing infrastructure supports monoclonal antibody production for export markets. Swissmedic regulatory frameworks align with EMA procedures while maintaining distinct pricing autonomy. Basel and Zürich concentrate cell culture specialist talent pools.
Japan
PMDA accelerated approval pathways for orphan oncology indications incentivize development investment. METI industrial policy supports domestic biologics manufacturing capacity expansion. Tokyo and Osaka metropolitan areas concentrate proton therapy infrastructure investment.
Oral Cancer Treatment Market Vendor Landscape
Global majors compete with regional champions across manufacturing scale and biomarker-linked service integration. The vendor base organizes into three tiers: integrated pharmaceutical conglomerates with dual small-molecule and biologics platforms, specialized immuno-oncology developers with checkpoint inhibitor depth, and emerging biosimilar manufacturers pressuring chemotherapy margins. Consolidation dynamics favor M&A activity around companion diagnostic capabilities and strategic partnerships for cold chain distribution in emerging markets.
Within the integrated pharmaceutical tier, Pfizer Inc. and F. Hoffmann-La Roche Ltd. occupy anchor positions. Pfizer leverages manufacturing flexibility across therapy classes, while Roche exemplifies deep specialization in companion diagnostics linked to targeted therapy selection. Bristol-Myers Squibb Company represents the immuno-oncology specialist archetype, with checkpoint inhibitor portfolios dominating recurrent oral malignancy protocols.
| Leading Market Players |
|---|
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd. |
| Merck & Co. |
| AbbVie Inc. |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Eli Lilly and Company |
| Teva Pharmaceutical Industries Ltd. |
| Bayer AG |
| Others |
Supply Flow & Price Mechanics
Cell culture specialist concentrations in Switzerland and Ireland create labor-cost differentials that widen pricing spreads between premium biologics and commoditized chemotherapy agents. Contract manufacturers in Basel and Dublin command wage premiums that flow through to checkpoint inhibitor pricing, while Indian API producers compress margins on cytotoxic portfolios through lower technical labor costs.
Pricing Analysis
Warranty and service bundling separates originator biologics from unbundled biosimilar offerings, with Pfizer and Roche packaging cold chain guarantees and patient support programs into premium positioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by companion diagnostic integration and infusion service inclusion. Price differentiation hinges on biomarker testing bundling and 340B eligibility access for US hospital systems. Cost compression in chemotherapy runs through trastuzumab and rituximab biosimilar penetration, with Indian government tenders showing highest price sensitivity and US academic medical centers demonstrating lowest sensitivity for immuno-oncology assets.
Supply Chain Analysis
Reverse logistics for temperature-compromised monoclonal antibodies remains underdeveloped, with most distributors lacking standardized refurbishment protocols for cold chain excursions. Active pharmaceutical ingredient production concentrates in India and China, while fill-finish capacity clusters in Switzerland, Ireland, and the United States. Supply chains draw from recombinant protein cell lines, sterile filtration components, and single-use bioreactor systems. Single-source vulnerability in aseptic fill-finish talent pools threatens continuity. Distribution runs through specialized oncology distributors with captive cold chain capabilities, with hospital procurement committees consolidating around integrated service agreements in the US Southwest and Southeast.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into companion diagnostic development and biologics manufacturing capacity represents the dominant competitive race, with players securing upstream control over biomarker-linked patient selection and downstream capture of infusion service revenue.
For Market Incumbents: Acquire companion diagnostic laboratories to lock in biomarker-driven prescribing pathways and defend against biosimilar erosion in chemotherapy portfolios. Bristol-Myers Squibb and Roche exemplify this defensive consolidation through integrated PD-L1 testing networks. Capacity addition in Indian district hospital corridors under Ayushman Bharat secures volume anchoring against emerging local manufacturers.
For New Entrants and Emerging Players: FDA's Breakthrough Therapy designation in the United States opens a window for checkpoint inhibitor developers to compress trial timelines and secure accelerated commercial access. India's CDSCO alignment with ICH-GCP standards creates regulatory tailwind for novel biologic entry. Target mobile chemotherapy unit partnerships in Indian tier-2 cities as the most penetrable white space, with tele-radiology integration as the go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap immuno-oncology developers given checkpoint inhibitor expansion into neoadjuvant oropharyngeal protocols. Long-term viability over a five-to-ten year window favors developers with parallel FDA and EMA submission strategies and companion diagnostic co-development partnerships. Acquisition target archetype: specialized biologics manufacturers with Swiss or Irish fill-finish assets and Indian API sourcing relationships. Monitor EMA centralized authorization timelines for oropharyngeal cancer indications as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Biomarker-linked patient selection secures premium positioning for PD-1 inhibitors in recurrent disease. |
| Manufacturing Scale-Up in Biologics Clusters | Basel and Dublin capacity expansion addresses acute cell culture specialist shortages for monoclonal antibody supply. |
| Regulatory Approval Pathway Optimization | FDA Breakthrough Therapy and EMA parallel scientific advice compress Phase II-to-commercialization timelines. |
| Mobile Chemotherapy Unit Deployment | Ayushman Bharat district hospital upgrades in India create white space for decentralized infusion access. |
| Cold Chain Distribution Partnership | Integrated service agreements with 340B-eligible US hospital systems consolidate vendor relationships in the Southwest. |
Methodological Framework
Multi-period observation of FDA approval timelines, EMA centralized authorization patterns, and Indian screening program referral volumes anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Primary fieldwork combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up patient volume modeling and top-down revenue triangulation cross-checked segment-level projections.
Input-output matrices mapped therapeutic modality demand against manufacturing capacity constraints, administration route preferences, and regional regulatory clusters across the projection horizon. Segmentation dimensions included treatment stage, delivery mode, end-user setting, and biomarker-directed therapy eligibility. CAGRs derived from fitted growth curves applied to baseline epidemiology and penetration assumptions. Forecast inputs incorporated checkpoint inhibitor expansion trajectories and radiotherapy infrastructure investment cycles.
The model assumes a particular technology adoption path for neoadjuvant immunotherapy protocols; alternative pathways for transoral robotic surgery expansion would alter the outlook for organ-preservation therapy sequencing. Forecasts reflect assumptions regarding biomarker testing reimbursement stability and cold chain distribution integrity. Practitioners should monitor CDSCO inspection readiness timelines and US Medicare Advantage molecular coverage policies for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Anal Fistula Treatment Market
Specialty Medicine
Brugada Syndrome Market
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
Global Spinal Muscular Atrophy Treatment Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Coagulation Disorders Market
Specialty Medicine
Tardive Dyskinesia (TD) Treatment Market
Specialty Medicine
Lipoprotein Metabolism Disorders Treatment Market
Specialty Medicine
Gallbladder Cancer Therapeutics Market
Specialty Medicine
Myasthenia Gravis Market
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
Chordoma Disease Therapeutics Market
Specialty Medicine
Primary Biliary Cholangitis (PBC) Treatment Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Generalized Anxiety Disorder (GAD) Market
Specialty Medicine
Cytomegalovirus Retinitis Market