
 Acute Myeloid Leukemia Therapeutics Market | 2026-2036
Acute Myeloid Leukemia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Myeloid Leukemia Therapeutics Market Intelligence
Companion diagnostic revenue is rewriting how oncology franchises capture value upstream of drug sales. Novartis AG leverages its FLT3 inhibitor portfolio to anchor high-margin testing-to-treatment workflows. Pfizer Inc. competes through broad hospital formulary access rather than biomarker-restricted positioning. Bristol-Myers Squibb sustains its presence in the CD47 pathway with R&D intensity that matches its myeloid-focused clinical investments.
Acute Myeloid Leukemia therapeutics comprise systemic agents designed to eliminate leukemic blast cells through cytotoxic, targeted, or immune-mediated mechanisms, with treatment selection governed by cytogenetic profiling and measurable residual disease monitoring. These therapies serve the primary purpose of inducing remission, preventing relapse, and extending survival in a disease where median untreated survival spans weeks to months. Targeted therapies command the deepest margin pools where FLT3, IDH1/2, and BCL-2 inhibitors command premium pricing against well-defined biomarker populations. Immunotherapies represent the fastest-expanding segment as bispecific antibodies and CAR-T platforms advance through registrational trials. Chemotherapies remain the volume backbone in induction regimens despite eroding price per course.
FDA accelerated approval, EMA conditional marketing authorization, and Japan PMDA sakigake designation collectively compress development timelines while demanding confirmatory evidence that shapes post-market investment. These frameworks reward sponsors who integrate biomarker strategies early, penalizing programs that treat AML as a homogeneous indication. Stakeholders must monitor how regulators reconcile benefit-risk for single-arm trials against rising expectations for overall survival data.
Market Dynamics
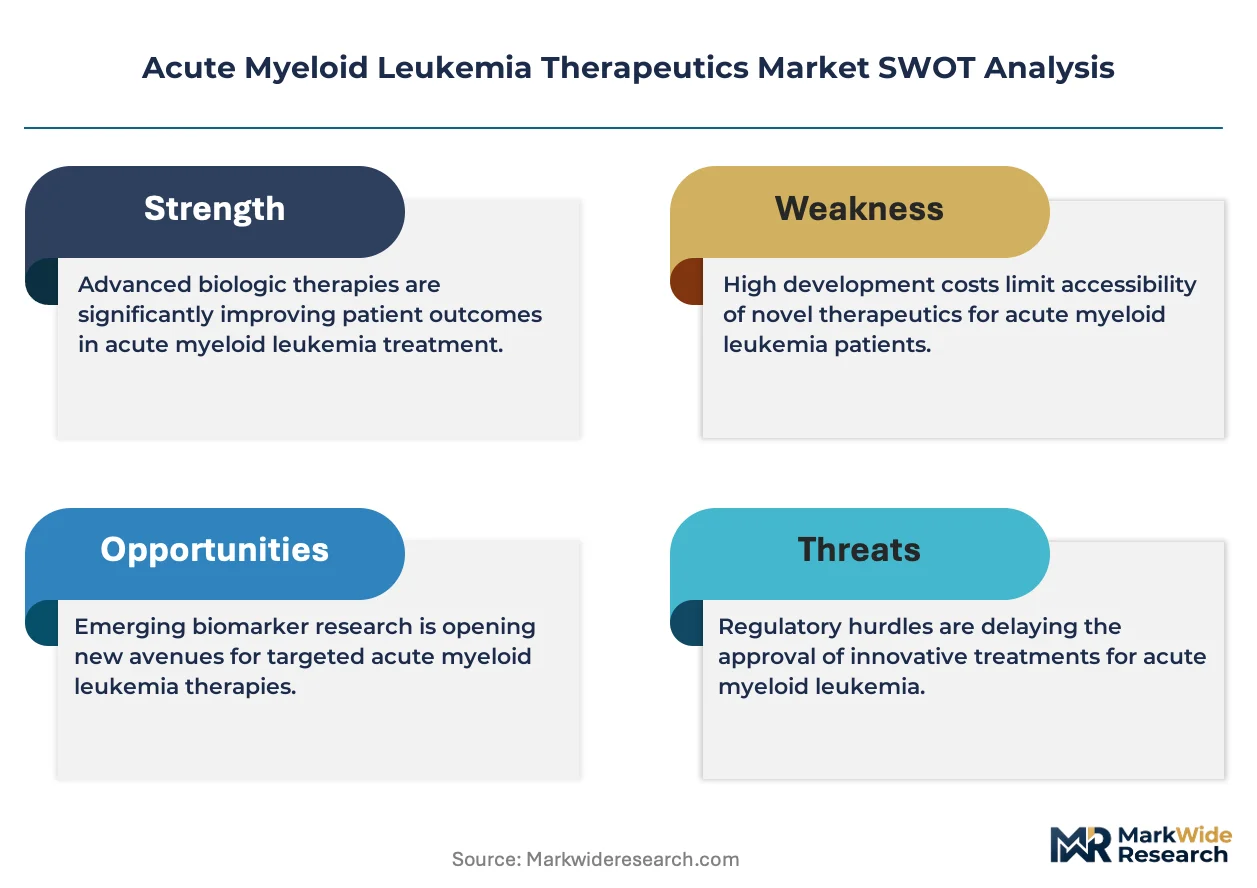
The convergence of biomarker-driven stratification and accelerated regulatory pathways is fragmenting AML into addressable subpopulations, forcing sponsors to abandon broad-label development in favor of cytogenetically defined niches with premium pricing power.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses Phase II-to-market timelines for FLT3 and IDH inhibitors, rewarding sponsors who integrate companion diagnostics early in clinical design.
- Measurable Residual Disease Monitoring:Next-generation sequencing-based MRD detection is expanding addressable patient pools by identifying molecular relapse before hematologic progression.
- Japan PMDA Sakigake:Priority review designation for hematologic malignancies is drawing Japanese investment into global registrational trials, accelerating Eastern patient access to novel mechanisms.
Market Restraints
- Plasmid Manufacturing Bottleneck:Viral vector and CAR-T construct production remains concentrated among three CDMOs in the United States and Europe, creating 18-24 month queue times for clinical supply.
- Confirmatory Trial Failure Risk:FDA's requirement for overall survival verification in accelerated approvals creates post-market investment exposure that deters mid-cap sponsors from pursuing conditional pathways.
- Allogeneic Transplant Substitution:Curative-intent stem cell transplantation in fit patients limits the addressable duration of targeted therapy exposure in first-line settings.
Strategic Opportunities
- Germany's Diagnosis-Related Group Reform:The 2024 G-DRG update introduced separate reimbursement codes for molecularly stratified AML induction, creating precedent for biomarker-linked payment in Europe's largest market.
- Bispecific Antibody Outpatient Administration:Subcutaneous dosing formats are enabling community oncology clinic adoption outside academic transplant centers, displacing hospital-centric infusion models.
- Real-World Evidence Generation:FDA's guidance on external control arms permits synthetic comparator construction from EHR networks, reducing placebo-controlled trial requirements in rare molecular subsets.
Industry Challenges
- Hematopathologist Workforce Constraints:Cytogenetic interpretation and flow cytometry MRD analysis require specialized training that academic medical centers struggle to staff at scale.
- Multi-Omics Data Integration:Harmonizing genomic, transcriptomic, and proteomic inputs into actionable treatment algorithms exceeds the informatics capabilities of most community oncology practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Myeloid Leukemia Therapeutics Market |
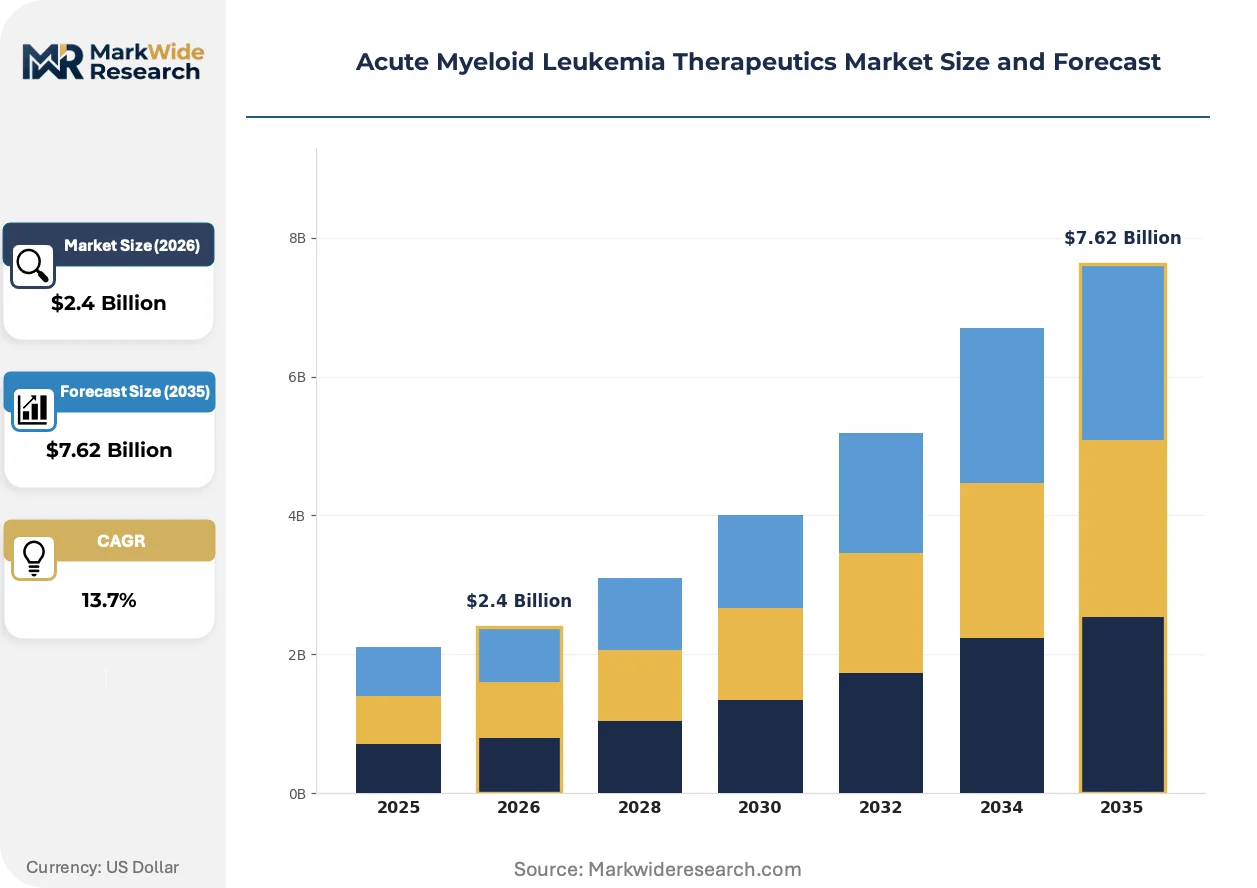
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapies, Targeted Therapies, Immunotherapies, Combination Therapies Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular End User: Hospitals, Clinics, Home Healthcare, Specialty Pharmacies Stage of Disease: Acute, Remission, Relapse, Maintenance |
| Companies Covered | Novartis AG, Pfizer Inc., Bristol-Myers Squibb, AbbVie Inc., Astellas Pharma Inc., Roche Holding AG, Daiichi Sankyo Company, Limited, Gilead Sciences Inc., Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Myeloid Leukemia Therapeutics Market Strategic Shifts & Innovations
Artificial intelligence is penetrating biomarker discovery and clinical trial design, compressing the traditional decade-long development cycle while regulators scramble to validate algorithmic endpoints.
Computational pathology platforms are digitizing bone marrow aspirate morphology review, enabling quantitative blast enumeration that reduces inter-reader variability. Academic medical centers in the United States and Germany are piloting these systems for MRD assessment, with deployment timelines accelerating as laboratory information management systems integrate cloud-based image analysis modules. The technology is digitizing diagnostic workflows that previously required specialized hematopathologist availability.
EMA's revised guideline on clinical investigation of medicinal products in acute myeloid leukemia now mandates measurable residual disease as a secondary endpoint in registrational trials, elevating molecular response criteria alongside traditional survival metrics. This regulatory shift is forcing sponsors to pre-specify MRD assay methodologies and analytical validation packages before Phase III initiation. European trial designs are responding by embedding central laboratory partnerships earlier in protocol development.
Specialty pharmacies are capturing patient access functions previously managed through hospital outpatient departments, particularly for oral targeted agents requiring risk evaluation and mitigation strategy compliance. This channel migration is concentrating distribution volume among three national pharmacy networks in the United States, with similar consolidation emerging in Germany's Apotheken landscape. The shift is most pronounced in maintenance therapy settings where oral azacitidine and venetoclax combinations dominate prescribing.
Acute Myeloid Leukemia Therapeutics Market Segmentation
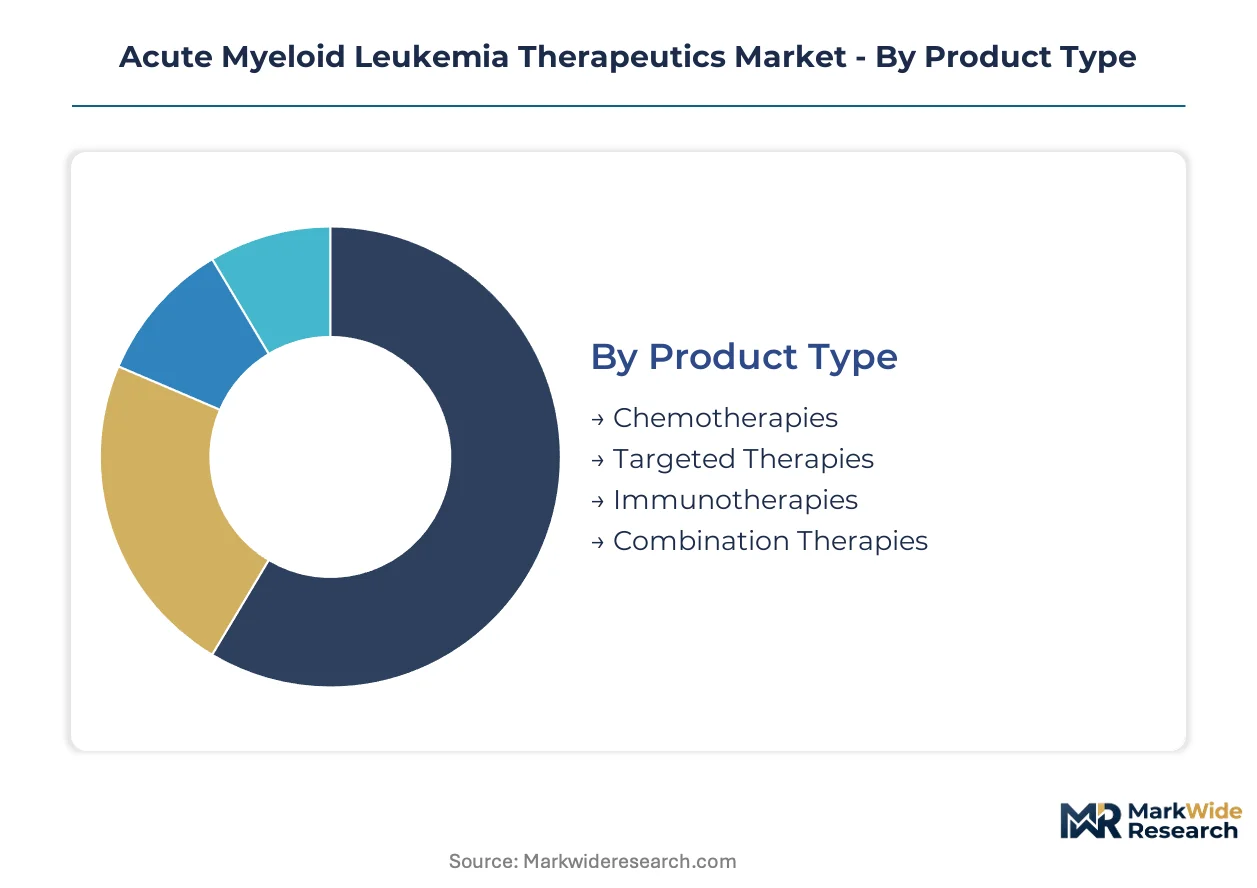
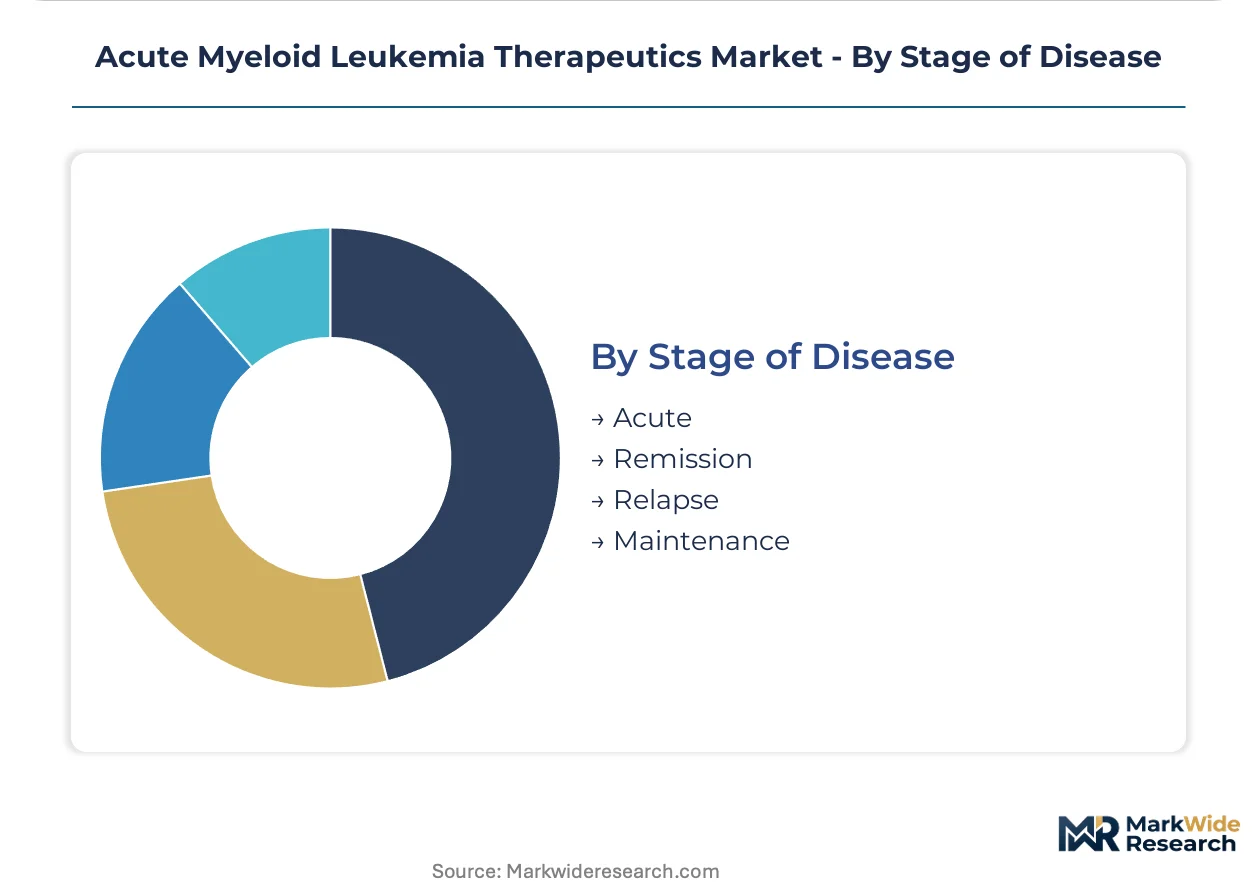
AML therapeutics fragment across four dimensions that determine pricing power, distribution strategy, and clinical positioning. Product type governs margin structure. Administration route dictates site-of-care economics. End user concentration shapes channel control. Disease stage defines treatment duration and reimbursement intensity.
Product Type:
Cost tier stratification separates commoditized induction regimens from precision mechanisms commanding premium positioning.
- Targeted Therapies:FLT3, IDH1/2, and BCL-2 inhibitors deliver mechanism-specific cytotoxicity against cytogenetically defined blast populations. Demand concentrates in academic medical centers across the United States and Germany where companion diagnostic infrastructure supports biomarker-directed prescribing and payers reimburse molecularly stratified protocols.
- Immunotherapies:Bispecific antibodies and CAR-T platforms recruit T-cell or NK-cell effector functions against leukemic blasts through CD33, CD123, or CD47 targeting. Clinical trial density in Japan and the United States is accelerating regulatory submissions as PMDA sakigake and FDA breakthrough designations compress development timelines for novel mechanisms.
- Chemotherapies:Cytarabine-anthracycline combinations remain the volume backbone for induction despite eroding price per course.
- Combination Therapies:Venetoclax-hypomethylating agent regimens dominate frontline therapy for unfit patients.
Chemotherapies command the established base. The steepest expansion runs through immunotherapies.
Administration Route:
Application format determines whether therapy anchors in hospital infusion centers or migrates toward community and home settings.
- Oral:Azacitidine tablets and targeted small molecules enable outpatient maintenance without infusion infrastructure. Germany's G-DRG reform created separate reimbursement codes for oral protocols, shifting prescribing toward community oncology practices outside transplant centers.
- Intravenous:Cytotoxic induction and antibody-based therapies require hospital-based administration with pharmacy oversight.
- Subcutaneous:Bispecific antibody formats are displacing hospital-centric infusion models through community clinic adoption.
- Intramuscular:Limited application for supportive care agents in neutropenic patients.
Intravenous administration anchors the established base. Oral and subcutaneous formats are gaining share fastest.
End User:
Customer type concentration is reshaping channel economics and patient access control points across the treatment journey.
- Specialty Pharmacies:Risk evaluation and mitigation strategy compliance for oral targeted agents has concentrated distribution among three national networks in the United States, with Germany's Apotheken landscape showing similar consolidation. These entities capture REMS administration, adherence monitoring, and prior authorization management previously handled by hospital outpatient departments.
- Hospitals:Academic medical centers retain control of induction therapy, transplant evaluation, and clinical trial enrollment.
- Clinics:Community oncology practices are expanding into maintenance therapy as oral regimens reduce infusion dependency.
- Home Healthcare:Limited to post-transplant supportive care and oral medication administration.
Hospitals command the established base. Specialty pharmacies represent the fastest-expanding control point.
Stage of Disease:
Maturity of disease state governs treatment intensity, duration of exposure, and curative versus palliative intent.
- Acute:Induction therapy demands immediate cytoreduction through intensive chemotherapy or venetoclax-based combinations in unfit populations.
- Remission:Measurable residual disease monitoring is expanding addressable pools by identifying molecular relapse before hematologic progression.
- Relapse:Salvage regimens and clinical trial enrollment concentrate in specialized centers with CAR-T and bispecific access.
- Maintenance:Oral azacitidine and venetoclax combinations dominate extended therapy with specialty pharmacy channel concentration.
Acute stage therapy commands the established base. Maintenance and relapse segments are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement elasticity varies sharply across markets. The United States and Germany absorb premium pricing for biomarker-directed therapies, while Japan and the United Kingdom demand cost-effectiveness thresholds that compress margins for novel mechanisms.
United States
Academic medical centers in Boston, Houston, and New York City drive demand for FLT3 and IDH inhibitor protocols. FDA accelerated approval pathways compress development timelines, rewarding sponsors who integrate companion diagnostics early. The National Cancer Institute's clinical trial networks concentrate patient access in major metropolitan hospital systems.
Germany
The 2024 G-DRG reform introduced separate reimbursement codes for molecularly stratified AML induction, creating precedent for biomarker-linked payment. Heidelberg and Berlin anchor hematologic oncology excellence clusters where measurable residual disease monitoring expands addressable patient pools. EMA conditional marketing authorizations align with Germany's early-access frameworks.
Japan
PMDA sakigake designation for hematologic malignancies draws domestic investment into global registrational trials. Tokyo and Osaka academic centers concentrate bispecific antibody and CAR-T clinical development. The national health insurance system applies stringent cost-effectiveness reviews that delay reimbursement for premium mechanisms.
United Kingdom
NICE technology appraisals impose cost-per-QALY thresholds that restrict access to targeted therapies outside clinical trials. London and Manchester hematology networks prioritize venetoclax-hypomethylating combinations in unfit populations. The NHS Cancer Drugs Fund provides temporary reimbursement pending real-world evidence generation.
France
ANSM early-access programs permit compassionate use of investigational AML therapies outside clinical trials. Paris and Lyon academic hospitals lead European adoption of computational pathology platforms for MRD assessment. HAS transparency committee evaluations determine reimbursement levels for novel agents in maintenance settings.
Acute Myeloid Leukemia Therapeutics Market Key Industry Players
Integrated pharmaceutical conglomerates and targeted-therapy specialists split the market into distinct capability tiers. Consolidation around FLT3, IDH1/2, and BCL-2 inhibitor portfolios has created concentrated competition in biomarker-defined segments. Three archetypes dominate: multinational oncology franchises with companion diagnostic capabilities, mid-cap biotechs with single-asset precision mechanisms, and generic manufacturers supplying chemotherapy backbones. Portfolio diversification through M&A and strategic partnerships for diagnostic co-development represent the dominant competitive moves.
Within the multinational oncology tier, Novartis AG and Pfizer Inc. exemplify divergent positioning strategies. Novartis anchors high-margin testing-to-treatment workflows through its FLT3 inhibitor portfolio and companion diagnostic integration. Pfizer competes through broad hospital formulary access rather than biomarker-restricted positioning. Bristol-Myers Squibb occupies a position in the CD47 pathway with R&D intensity matching its myeloid-focused clinical investments.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Bristol-Myers Squibb |
| AbbVie Inc. |
| Astellas Pharma Inc. |
| Roche Holding AG |
| Daiichi Sankyo Company, Limited |
| Gilead Sciences Inc. |
| Amgen Inc. |
| Others |
Cost & Logistics Intelligence
Plasmid manufacturing bottlenecks concentrated among three CDMOs in the United States and Europe compress pricing power for CAR-T developers while inflating cost spreads between viral vector-dependent immunotherapies and small-molecule targeted agents. This single-source dependency forces sponsors to absorb 18-24 month queue premiums or abandon accelerated approval timelines entirely.
Pricing Analysis
Companion diagnostic bundling drives lifetime value for FLT3 and IDH inhibitor portfolios, with testing-to-treatment workflows capturing margin upstream of drug dispensing. Three-tier pricing structure across premium biomarker-directed therapies, standard hypomethylating combinations, and economy chemotherapy backbones stratifies the market by cytogenetic complexity. Pricing pressure stems from confirmatory trial failure risk that deters mid-cap sponsors from conditional approval pathways. Community oncology practices exhibit highest price sensitivity due to limited prior authorization infrastructure, while academic medical centers absorb premium positioning for novel mechanisms.
Supply Chain Analysis
Tariff exposure between the United States and China dominates raw material sourcing for small-molecule API production, forcing sponsors to qualify secondary suppliers in India and Switzerland. Viral vector production draws from plasmid DNA, cell culture media, and specialized resin inputs concentrated in North American and European manufacturing networks. Single-source vulnerability persists for GMP-grade cytokines and critical reagents used in CAR-T expansion protocols. Distribution runs through specialty pharmacy networks for oral maintenance agents, while hospital-based infusion centers control access to intravenous induction regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Curative-intent allogeneic stem cell transplantation threatens extended duration of targeted therapy exposure, forcing incumbents to defend addressable patient pools through biomarker-driven positioning that transplant-eligible populations cannot access.
For Market Incumbents: Insulate market position by deepening companion diagnostic integration to anchor high-margin testing-to-treatment workflows before transplant evaluation redirects fit patients. Pursue backward integration into GMP plasmid manufacturing to reduce CDMO queue dependency and compress clinical supply timelines. Prioritize MRD assay co-development partnerships that expand maintenance therapy eligibility beyond current hematologic remission criteria. For New Entrants and Emerging Players: Bispecific antibody outpatient administration in community oncology clinics represents the most penetrable entry point, displacing hospital-centric infusion models through subcutaneous dosing formats. Japan's PMDA sakigake pathway offers accelerated regulatory access for hematologic malignancy specialists with domestic clinical development partnerships. Target Germany's G-DRG reform-created reimbursement codes for molecularly stratified induction as the initial European market entry mechanism. For Investors and Strategic Acquirers: The market sits at a biomarker fragmentation phase that favors precision-therapy specialists with integrated diagnostic capabilities over broad-formulary competitors. Acquisition targets should demonstrate validated companion diagnostic partnerships and registrational trial exposure in FLT3, IDH1/2, or CD47 pathways. Watch FDA confirmatory trial readouts as the critical inflection signal for portfolio revaluation across accelerated approval assets.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Testing-to-treatment workflows anchor premium pricing for Novartis AG's FLT3 portfolio. |
| Subcutaneous Formulation Development | Outpatient bispecific dosing displaces hospital infusion dependency for community clinic adoption. |
| Real-World Evidence Infrastructure | FDA external control arm guidance permits synthetic comparator construction from EHR networks. |
| CDMO Partnership Diversification | Secondary viral vector suppliers in Switzerland reduce queue risk for CAR-T clinical supply. |
| MRD Assay Centralization | EMA-mandated molecular endpoints force pre-specified laboratory partnerships before Phase III initiation. |
Research Approach
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient flow modeling and top-down revenue reconciliation triangulated market size estimates across the analysis window.
Demand-supply-balance framing anchored the analytical approach, with segmentation dimensions spanning treatment line, administration route, disease stage, and regional regulatory cluster. CAGRs were derived from epidemiological incidence projections, therapy penetration curves, and pricing elasticity assumptions. Forecast inputs incorporated measurable residual disease monitoring expansion rates and accelerated approval pathway success probabilities.
Stress conditions across confirmatory trial failure rates, plasmid manufacturing capacity constraints, and transplant substitution thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory guidance shifts or manufacturing technology disruptions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Complex Regional Pain Syndrome (CRPS) Market
Specialty Medicine
Bipolar Disorder (BPD) Market
Specialty Medicine
Vasomotor Symptoms Market
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Central Pontine Myelinolysis Market
Specialty Medicine
Global Actinic Keratosis Treatment Market
Specialty Medicine
Nephrogenic Systemic Fibrosis (NSF) Treatment Market
Specialty Medicine
Folliculotropic Mycosis Fungoides Treatment Market
Specialty Medicine
Peripheral Neuropathy Market
Specialty Medicine
Rheumatoid Arthritis Treatment Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Peptide-Based Metabolic Disorders Therapeutics Market
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Piriformis Syndrome Treatment Market
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market