
 Global Axial Spondyloarthritis (Axspa) Market | 2026-2036
Global Axial Spondyloarthritis (Axspa) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Axial Spondyloarthritis (Axspa) Market Foresight
Injectable-to-oral modality bundling is shifting how payers and physicians evaluate treatment sequences for axial spondyloarthritis patients. AbbVie leverages its immunology infrastructure to sustain biologic dominance across multiple autoimmune indications. Eli Lilly and Company differentiates through Janus kinase inhibitor development, while Novartis Pharmaceuticals Corporation anchors its position with interleukin-17 pathway specialization. UCB competes on sustained-release formulation technology for its established monoclonal antibody platform.
Axial spondyloarthritis comprises a spectrum of chronic inflammatory diseases primarily affecting the sacroiliac joints and spine, characterized by human leukocyte antigen-B27 association and enthesitis as core pathological features. Tumor necrosis factor inhibitors retain the largest revenue share but face margin compression as interleukin inhibitors capture treatment-naïve patient flows, while Janus kinase inhibitors represent the fastest-expanding category driven by oral convenience advantages. Injectable therapy dominates delivery mode value due to biologic administration requirements, though oral medication segments are expanding fastest as small-molecule inhibitors gain formulary inclusion.
The FDA maintains stringent immunogenicity surveillance requirements for biologic AxSpA therapies, while the EMA's evolving biosimilar interchangeability guidelines shape European competitive dynamics. Japan's PMDA imposes distinct post-market safety monitoring protocols that influence regional product launch sequencing. Stakeholders must monitor regulatory divergence across major markets to optimize clinical trial placement and reimbursement negotiation timing.
Market Dynamics
The axial spondyloarthritis market is restructuring around oral small-molecule displacement of injectable biologics in first-line therapy, forcing incumbents to defend formulary position through outcome-based contracting and sustained-release formulation investments.
Growth Catalysts
- Japan's PMDA post-market surveillance protocols:These stringent safety monitoring requirements accelerate physician confidence in novel immunomodulators, expanding eligible patient pools for advanced therapies.
- Rheumatology clinic consolidation:Large specialty practice networks standardize biologic protocols across multiple sites, creating concentrated demand channels for established manufacturers.
- Interleukin-17 pathway inhibitors:This mechanism demonstrates superior radiographic progression control versus tumor necrosis factor blockers in head-to-head trials, redirecting treatment-naïve patient flows.
Market Restraints
- Biosimilar price compression:The FDA's abbreviated approval pathways for adalimumab and etanercept biosimilars erode originator margins across the United States, forcing portfolio diversification.
- Cold chain distribution requirements:Biologic therapies demand specialized logistics infrastructure, limiting pharmacy participation and concentrating dispensing through hospital outpatient departments.
- Human leukocyte antigen-B27 testing gaps:Diagnostic delays in primary care settings postpone specialist referrals, compressing the addressable window for early intervention therapies.
Strategic Opportunities
- Germany's Diagnosis-Related Group reimbursement reform:New bundled payment structures for inflammatory spine conditions create incentives for oral therapy adoption, reducing infusion center dependency.
- Telemedicine-enabled remote monitoring:Digital biomarker tracking through patient-reported outcome platforms expands rural access to specialist-managed care, unlocking underpenetrated United States markets.
- Janus kinase inhibitor and interleukin-17 antagonist combination protocols:Converging small-molecule and biologic mechanisms in sequential therapy designs offer differentiated positioning against single-agent competitors.
Industry Challenges
- Rheumatology fellowship training bottlenecks:The United States faces persistent specialist shortages, constraining patient throughput for complex biologic initiation and monitoring protocols.
- Immunogenicity assay standardization:Variable anti-drug antibody testing methodologies across reference laboratories complicate therapeutic drug monitoring and dose optimization decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Axial Spondyloarthritis (Axspa) Market |
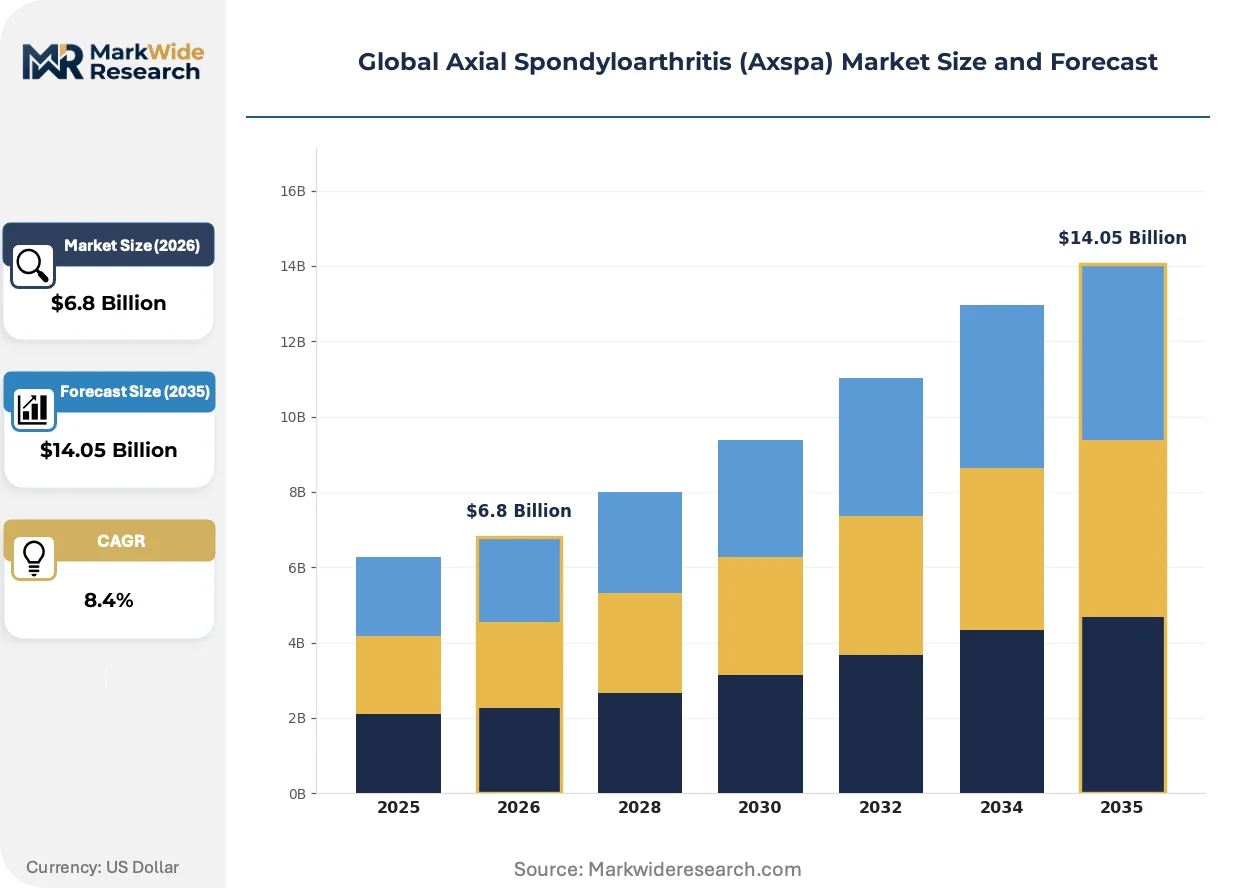
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nonsteroidal Anti-inflammatory Drugs, Tumor Necrosis Factor Inhibitors, Interleukin Inhibitors, Janus Kinase Inhibitors, Corticosteroids Therapy Area: Inflammation Control, Pain Management, Immune Regulation, Physical Rehabilitation, Disease Modification End User: Rheumatology Clinics, Specialty Hospitals, Outpatient Care Centers, Diagnostic Laboratories Delivery Mode: Oral Medication, Injectable Therapy, Infusion, Topical Application |
| Companies Covered | AbbVie, Novartis Pharmaceuticals Corporation, UCB, Eli Lilly and Company, Amgen, Johnson & Johnson, Pfizer, Janssen Biotech, Kyowa Kirin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Axial Spondyloarthritis (Axspa) Market Shifts & Advancements
Oral therapy convenience is compressing the traditional injectable-first treatment paradigm, while regulatory convergence around biosimilar interchangeability and real-world evidence requirements reshapes competitive entry strategies.
Sustained-release subcutaneous formulations are modularizing administration frequency for established monoclonal antibodies. Rheumatology practices in Germany and Japan adopt quarterly injection schedules to reduce nursing burden and patient travel requirements. This formulation innovation compresses site-of-care costs while extending effective patent protection through delivery technology differentiation.
The EMA's evolving biosimilar interchangeability guidelines create pathway uncertainty for automatic substitution across European Union member states. Manufacturers must navigate divergent national pharmacy substitution rules, complicating pan-European launch sequencing. France and Germany deploy distinct risk-sharing arrangements that condition reimbursement on real-world effectiveness data collection.
Patient-reported outcome integration into reimbursement negotiations disrupts traditional physician-centric purchasing. United States payers now condition preferred formulary tier placement on demonstrated improvements in Bath Ankylosing Spondylitis Disease Activity Index scores. This behavioral shift concentrates contract value with manufacturers possessing robust post-market evidence generation infrastructure.
Global Axial Spondyloarthritis (Axspa) Market Segmentation
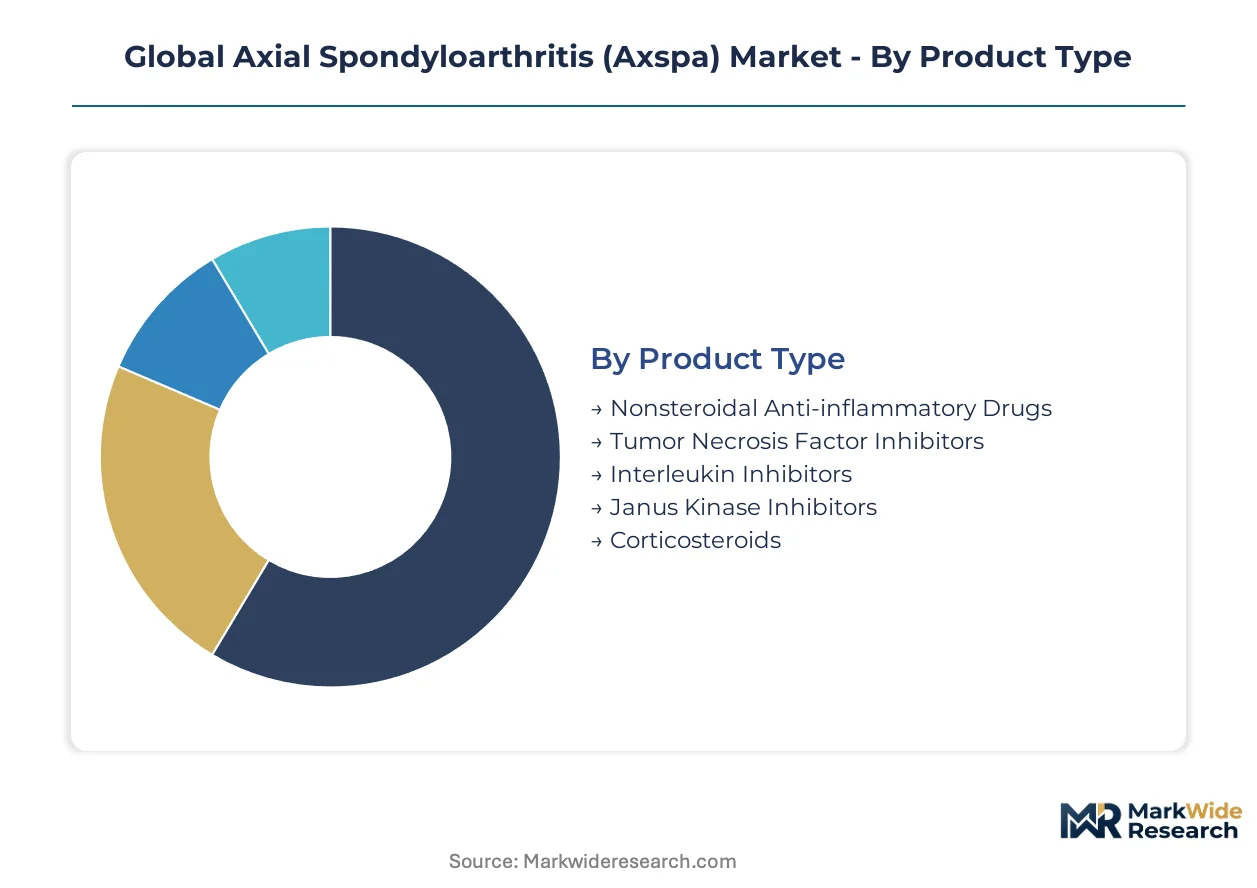
Axial spondyloarthritis treatment pathways diverge sharply across patient phenotypes and disease progression stages, requiring manufacturers to align pipeline investments with distinct regulatory approval burdens and reimbursement thresholds. Segmentation reveals where FDA, EMA, and PMDA certification requirements concentrate commercial risk and which delivery technologies command premium positioning.
Product Type:
FDA's immunogenicity surveillance requirements and EMA's evolving biosimilar interchangeability guidelines impose divergent certification burdens across molecular classes, with biologics facing extended approval timelines versus small molecules.
- Tumor Necrosis Factor Inhibitors:Established monoclonal antibodies and fusion proteins targeting TNF-alpha cytokine signaling. Demand concentrates in Germany and Japan where rheumatology clinic networks standardize first-line biologic protocols, though biosimilar price compression erodes originator margins across United States hospital outpatient departments.
- Interleukin Inhibitors:Monoclonal antibodies blocking IL-17A, IL-17F, or IL-23 pathways demonstrate superior radiographic progression control in head-to-head trials. United States payers increasingly prioritize these agents for treatment-naïve patients based on Bath Ankylosing Spondylitis Disease Activity Index outcomes, redirecting patient flows from TNF inhibitors.
- Janus Kinase Inhibitors:Oral small-molecule agents targeting JAK1, JAK2, or JAK3 enzymes enable home administration without cold chain logistics. Eli Lilly and other developers leverage oral convenience to penetrate rural United States markets underserved by infusion centers.
- Nonsteroidal Anti-inflammatory Drugs:First-line symptomatic therapy with cyclooxygenase inhibition remains the entry point for undiagnosed patients in primary care settings across all major markets.
- Corticosteroids:Systemic and localized anti-inflammatory agents provide bridging therapy during biologic initiation or flare management in specialist-managed care.
Leading the category by volume: Tumor Necrosis Factor Inhibitors. Growing fastest: Janus Kinase Inhibitors.
Therapy Area:
Cost tier stratification separates premium disease-modifying biologics from commoditized symptomatic management, with reimbursement frameworks in Germany and Japan creating distinct access thresholds.
- Disease Modification:Biologic and targeted synthetic agents halting structural progression through immune pathway blockade. United States payers condition preferred formulary tier placement on demonstrated inhibition of radiographic spinal fusion.
- Immune Regulation:Precision immunomodulation restoring T-cell and cytokine homeostasis in HLA-B27-associated pathogenesis. Germany's Diagnosis-Related Group reimbursement reform creates bundled payment incentives for therapies reducing long-term disability costs.
- Inflammation Control:Acute and chronic suppression of sacroiliac and spinal entheseal inflammation.
- Pain Management:Analgesic protocols addressing mechanical and inflammatory pain components.
- Physical Rehabilitation:Non-pharmacological mobility preservation and posture correction interventions.
Premium pricing concentrates in Disease Modification. Fastest formulary expansion: Immune Regulation.
End User:
Customer type determines site-of-care economics and nursing burden, with rheumatology clinic consolidation in the United States and Germany concentrating purchasing power.
- Rheumatology Clinics:Specialist practices managing biologic initiation, therapeutic drug monitoring, and dose optimization. Large United States networks standardize protocols across multiple sites, creating concentrated demand channels for established manufacturers with sustained-release formulations.
- Specialty Hospitals:Academic medical centers handling complex cases with extra-articular manifestations or treatment-refractory disease. Japan's PMDA post-market surveillance protocols accelerate physician confidence in novel immunomodulators within these settings.
- Outpatient Care Centers:Community-based infusion and injection facilities.
- Diagnostic Laboratories:HLA-B27 testing and disease activity biomarker analysis providers.
Highest biologic throughput: Rheumatology Clinics. Fastest digital integration: Specialty Hospitals.
Delivery Mode:
Supply concentration favors manufacturers with cold chain infrastructure for biologics, while oral medication segments expand through retail pharmacy penetration.
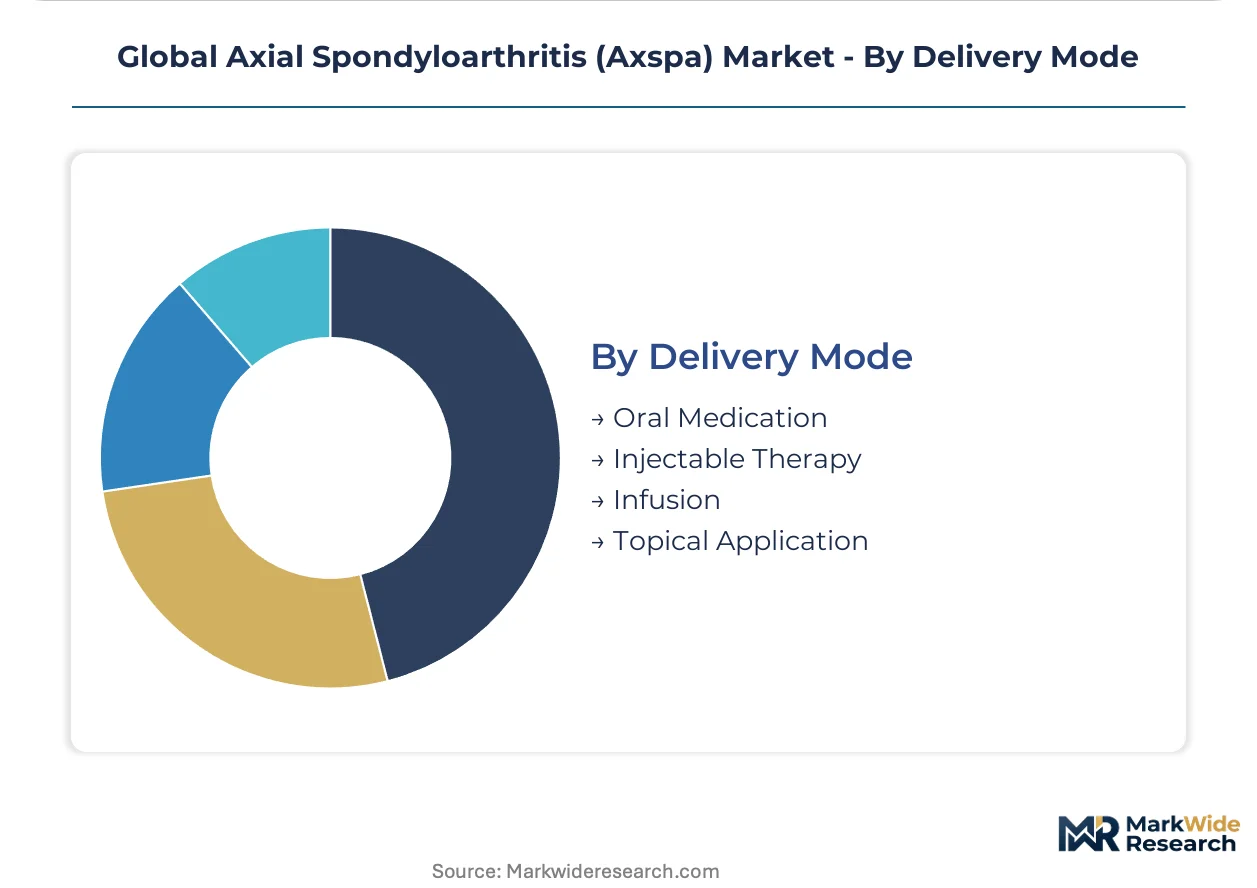
- Injectable Therapy:Subcutaneous and intramuscular administration of monoclonal antibodies and fusion proteins. Sustained-release formulations enabling quarterly injection schedules reduce nursing burden in Germany and Japan while extending effective patent protection.
- Oral Medication:Small-molecule tablets and capsules eliminating infusion center dependency. United States rural access expansion through telemedicine-enabled remote monitoring unlocks underpenetrated markets for JAK inhibitors.
- Infusion:Intravenous biologic administration requiring hospital outpatient department infrastructure.
- Topical Application:Localized corticosteroid or NSAID delivery for peripheral enthesitis.
Dominant value share: Injectable Therapy. Steepest expansion trajectory: Oral Medication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of biologic therapies concentrates in Switzerland, Germany, and the United States, while patient consumption clusters in markets with mature reimbursement frameworks. Cold chain distribution networks favor proximity to major airport hubs and specialized logistics corridors.
United States
Rheumatology clinic consolidation across large specialty networks standardizes biologic protocols and creates concentrated demand channels. The FDA's evolving biosimilar approval pathways reshape competitive entry for adalimumab and etanercept alternatives. Boston and New York Metro anchor clinical trial placement and specialist training infrastructure.
Germany
Diagnosis-Related Group reimbursement reform creates bundled payment incentives for oral therapy adoption over infusion-dependent biologics. The EMA's evolving biosimilar interchangeability guidelines shape pharmacy substitution rules across federal states. North Rhine-Westphalia and Bavaria concentrate rheumatology research centers and post-market surveillance data collection.
Japan
PMDA post-market surveillance protocols accelerate physician confidence in novel immunomodulators and expand eligible patient pools. Distinct safety monitoring requirements influence regional product launch sequencing versus Western markets. Tokyo and Osaka metropolitan areas host the majority of specialist-managed care and biologic initiation protocols.
Switzerland
Swissmedic maintains stringent immunogenicity surveillance requirements that align with EMA frameworks while preserving national regulatory autonomy. Basel and Zurich anchor biologic manufacturing clusters with integrated cold chain export infrastructure. The country's pricing negotiation mechanisms reference German and French reimbursement outcomes.
United Kingdom
NICE technology appraisals condition National Health Service access to interleukin-17 and Janus kinase inhibitors based on cost-effectiveness thresholds. London and the Southeast concentrate academic medical centers handling complex treatment-refractory cases. Post-Brexit regulatory divergence from EMA guidelines creates pathway uncertainty for biosimilar interchangeability.
Global Axial Spondyloarthritis (Axspa) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across molecular platform categories. The market structure consolidates around three tiers: established biologic incumbents defending formulary position, oral small-molecule challengers capturing convenience premiums, and biosimilar manufacturers eroding originator margins. Strategic archetypes include immunology infrastructure deployers, pathway specialization pure-plays, and sustained-release formulation technologists. Dominant competitive moves encompass outcome-based contracting for payers and sustained-release patent extension investments.
Within the immunology infrastructure tier, AbbVie leverages cross-indication platform deployment, while Eli Lilly and Company anchors oral small-molecule positioning through Janus kinase inhibitor development. Novartis Pharmaceuticals Corporation exemplifies pathway specialization with interleukin-17 antagonist focus, and UCB occupies sustained-release formulation differentiation for monoclonal antibody delivery.
| Leading Market Players |
|---|
| AbbVie |
| Novartis Pharmaceuticals Corporation |
| UCB |
| Eli Lilly and Company |
| Amgen |
| Johnson & Johnson |
| Pfizer |
| Janssen Biotech |
| Kyowa Kirin |
| Others |
Supply & Pricing Matrix
Biologics manufacturing specialists concentrated in Basel and Boston anchor production economics, with labor-cost differentials between Swiss precision-craft clusters and US contract manufacturing organizations driving three-tier spreads across originator, biosimilar, and oral-small-molecule tiers.
Pricing Analysis
Margin tightening in TNF inhibitor originators reflects FDA biosimilar pathway acceleration for adalimumab and etanercept alternatives. Three-tier pricing structure across premium interleukin-17 inhibitors, standard TNF biosimilars, and economy oral JAK agents stratifies by radiographic progression control demonstrated in head-to-head trials. United States payers condition preferred formulary tier placement on Bath Ankylosing Spondylitis Disease Activity Index outcomes, compressing price realization for manufacturers lacking post-market evidence infrastructure. Rheumatology clinic networks in Germany and Japan exhibit lowest price sensitivity due to bundled reimbursement structures, while United States hospital outpatient departments face highest cost-down pressure from 340B program constraints.
Supply Chain Analysis
Return flows of temperature-compromised biologics from rural United States infusion centers feed into specialized reverse-logistics networks for controlled destruction or redistribution. Active pharmaceutical ingredient production concentrates in Switzerland, Germany, and the United States, with mammalian cell culture capacity anchored in Basel and Boston biotech clusters. Cold chain distribution draws from specialized logistics corridors connecting Zurich and Frankfurt airport hubs to regional hospital outpatient departments. Single-source vulnerability in fill-finish capacity for sustained-release monoclonal antibodies creates concentration risk, while distribution runs through hospital-owned specialty pharmacies and rheumatology clinic consignment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
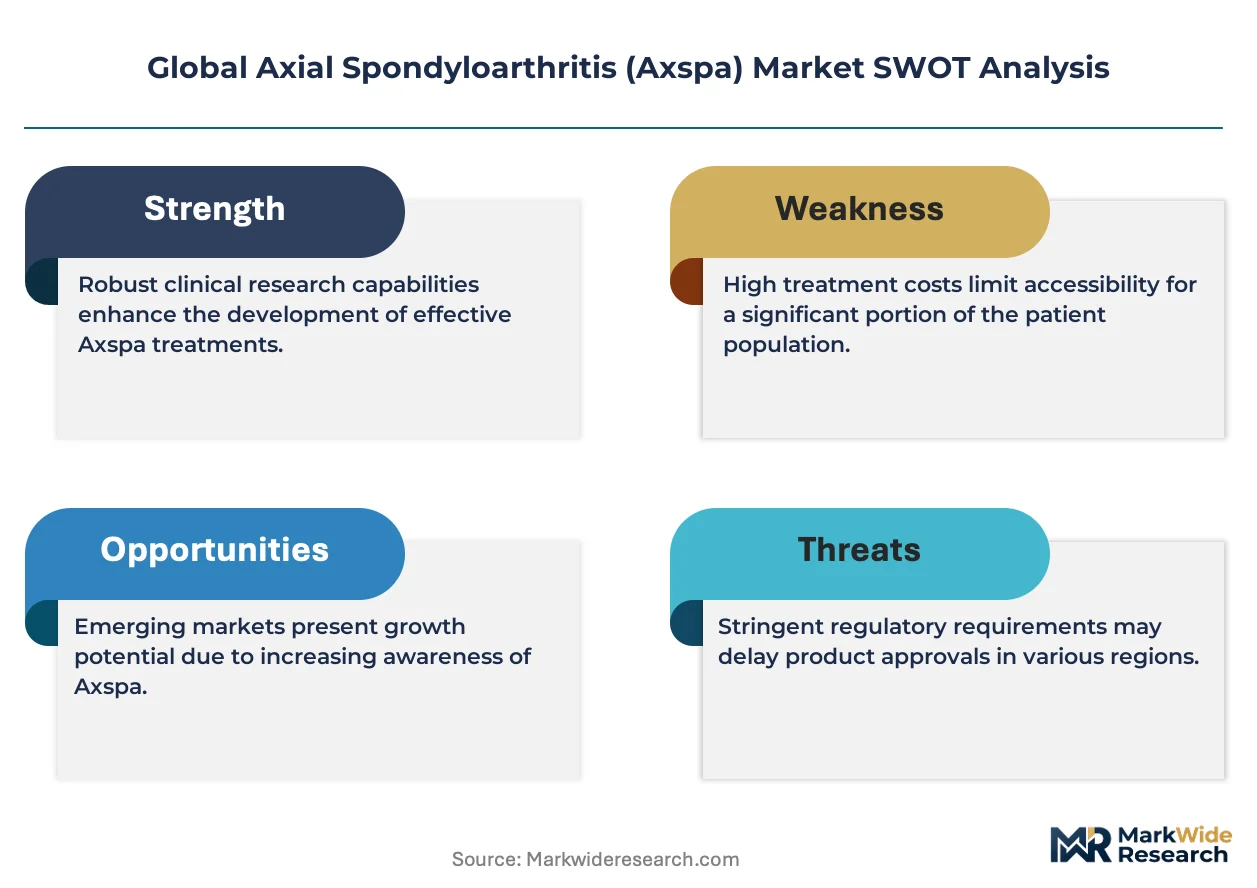
Biosimilar price compression is forcing portfolio consolidation among TNF inhibitor originators, eliminating sub-scale players lacking interleukin-17 or JAK inhibitor pipeline diversification.
For Market Incumbents: Deploy outcome-based contracting with United States payers to defend formulary position against interleukin-17 pathway competitors. Invest in sustained-release formulation technology to extend effective patent protection and reduce site-of-care nursing burden. Biologic manufacturing scale-up in Switzerland and Germany anchors supply security against single-source fill-finish vulnerabilities. For New Entrants and Emerging Players: Telemedicine-enabled remote monitoring platforms unlock rural United States markets underserved by infusion center infrastructure. Target JAK inhibitor penetration in primary care settings where HLA-B27 diagnostic gaps delay specialist referral. Partner with rheumatology clinic networks for digital biomarker integration into standard-of-care protocols. For Investors and Strategic Acquirers: Re-rating potential sits with oral-small-molecule specialists given Germany's Diagnosis-Related Group reimbursement reform accelerating oral therapy adoption. Long-term viability over the next decade favors developers with dual JAK inhibitor and interleukin-17 antagonist combination protocols. Monitor FDA biosimilar interchangeability guideline finalization as inflection indicator for originator margin compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Head-to-head trials against TNF inhibitors establish radiographic progression superiority for formulary tier placement. |
| Regulatory Approval Pathway | FDA immunogenicity surveillance requirements shape biologic development timelines and post-market commitment structures. |
| Manufacturing Scale-Up | Sustained-release formulation capacity in Basel and Boston extends effective patent protection through delivery differentiation. |
| Pipeline Diversification | JAK inhibitor and interleukin-17 antagonist combinations create sequential therapy positioning against single-agent competitors. |
| Reimbursement Strategy | Patient-reported outcome integration into United States payer negotiations conditions preferred formulary access. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with formulary directors, regulatory affairs leads, hospital procurement managers, and payer access specialists. FDA 510(k) submissions, EMA marketing authorization applications, ClinicalTrials.gov protocols, and Japanese PMDA consultation minutes provided secondary validation. Bottom-up patient flow modeling and top-down pharmaceutical spending analysis enabled cross-verification across the analysis window.
Granularity-level modeling operated at treatment line, molecular class, administration route, and regional regulatory cluster dimensions. CAGRs derived from patient population epidemiology, treatment penetration curves, and pricing trajectory assumptions across the projection horizon. Biosimilar entry velocity, oral therapy substitution elasticities, and rheumatology clinic consolidation rates served as industry-specific forecast inputs.
The model holds under stable reimbursement frameworks in United States, Germany, and Japan; deviation in FDA biosimilar interchangeability finalization or EMA post-market surveillance requirement changes would shift competitive entry timing assumptions. Practitioners should monitor PMDA safety protocol harmonization discussions and United States 340B program litigation outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Non Small Cell Lung Cancer (NSCLC) Therapeutics Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market
Specialty Medicine
Microcephaly Market
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
Global Endometriosis Treatment Market
Specialty Medicine
Open Angle Glaucoma Market
Specialty Medicine
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market
Specialty Medicine
Head and Neck Cancer Therapeutics Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market
Specialty Medicine
Acute Lymphoblastic Leukemia Therapeutics Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market
Specialty Medicine
Nerve Entrapment Syndrome Therapeutics Market
Specialty Medicine
Thyroid Cancer Therapeutics Market
Specialty Medicine
Primary Immunodeficiency Market
Specialty Medicine
Glaucoma Market