
 SPINA Bifida and Hydrocephalus Market | 2026-2036
SPINA Bifida and Hydrocephalus Market Size, Share, and Industry Trends Forecast 2026-2036
SPINA Bifida and Hydrocephalus Market Analysis
Silicone is decoupling from premium shunt systems as manufacturers adopt advanced biocompatible polymers with lower protein-adhesion profiles. Medtronic leverages its integrated neurosurgical portfolio to sustain leadership in programmable valve technology. Integra LifeSciences anchors its position through specialized dural repair and CSF management product lines.
Spina bifida and hydrocephalus constitute congenital neural tube defects and cerebrospinal fluid dysregulation conditions requiring surgical intervention, shunt-dependent drainage systems, and lifelong monitoring; hydrocephalus shunts typically operate at pressure thresholds of 5–20 cmH₂O with programmable magnetic adjustment mechanisms. Surgery and therapeutic devices command the deepest margin pools where programmable shunt technology and minimally invasive endoscopic third ventriculostomy tools concentrate value. Pediatric care applications within the end-user segment are expanding fastest as neonatal screening protocols widen detection windows and shift intervention earlier in patient pathways.
FDA premarket notification pathways and EU MDR Class III device requirements shape neurosurgical product commercialization timelines and clinical evidence burdens for manufacturers seeking market access. B. Braun SE and Sophysa navigate these frameworks through dedicated regulatory affairs infrastructure and notified body relationships across multiple jurisdictions. Stakeholders must monitor how evolving FDA guidance on CSF diversion devices and emerging EU MDR clinical evaluation requirements will reshape competitive positioning for new market entrants.
Market Dynamics
Programmable shunt valve miniaturization is compressing revision surgery rates while forcing manufacturers to rebuild regulatory dossiers around biocompatibility testing protocols that now exceed legacy silicone benchmarks.
Growth Catalysts
- Neonatal screening mandates:Expanded newborn neural tube defect protocols in Germany and Japan are detecting hydrocephalus earlier, extending shunt-dependent patient lifecycles and recurring device revenue streams.
- EU MDR Class III pathway clarity:The 2021 Medical Device Regulation transition has stabilized clinical evidence requirements for cerebrospinal fluid diversion devices, reducing premarket uncertainty for notified body submissions.
- Magnetic resonance-conditional materials:Titanium-nitride valve coatings are eliminating MRI compatibility barriers that previously forced shunt replacement before imaging procedures.
Market Restraints
- Platinum-cured silicone supply concentration:Three specialty chemical suppliers in Germany and Switzerland control medical-grade elastomer feedstocks, exposing valve manufacturers to polymer allocation delays.
- FDA 510(k) substantial equivalence tightening:The 2023 guidance on CSF shunt predicates requires new clinical data for programmable pressure mechanisms, extending clearance timelines by 8-14 months.
- Endoscopic third ventriculostomy substitution:Neurosurgical training programs in Japan and the United States are prioritizing ETV over shunt placement for selected aqueductal stenosis cases.
Strategic Opportunities
- Remote pressure monitoring integration:Telemetric shunt sensors that transmit intracranial pressure data to cloud platforms are opening subscription revenue models alongside hardware sales.
- Pediatric-specific valve miniaturization:Neonatal anatomical constraints below 2.5 kg body weight remain underserved by standard pediatric shunt dimensions, creating white space for dedicated product lines.
- Japanese super-aging corridor:Normal pressure hydrocephalus diagnosis rates in adults over 75 are rising faster than pediatric incidence, shifting volume toward adult-programmable systems.
Industry Challenges
- Pediatric neurosurgical workforce density:Fellowship-trained specialists concentrate in 12 metropolitan surgical centers across the United States, creating access bottlenecks for rural shunt placement.
- Biocompatibility testing cascade costs:ISO 10993 cytotoxicity, sensitization, and implantation studies for novel polymers now exceed $400,000 per material qualification, compressing R&D budgets at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SPINA Bifida and Hydrocephalus Market |
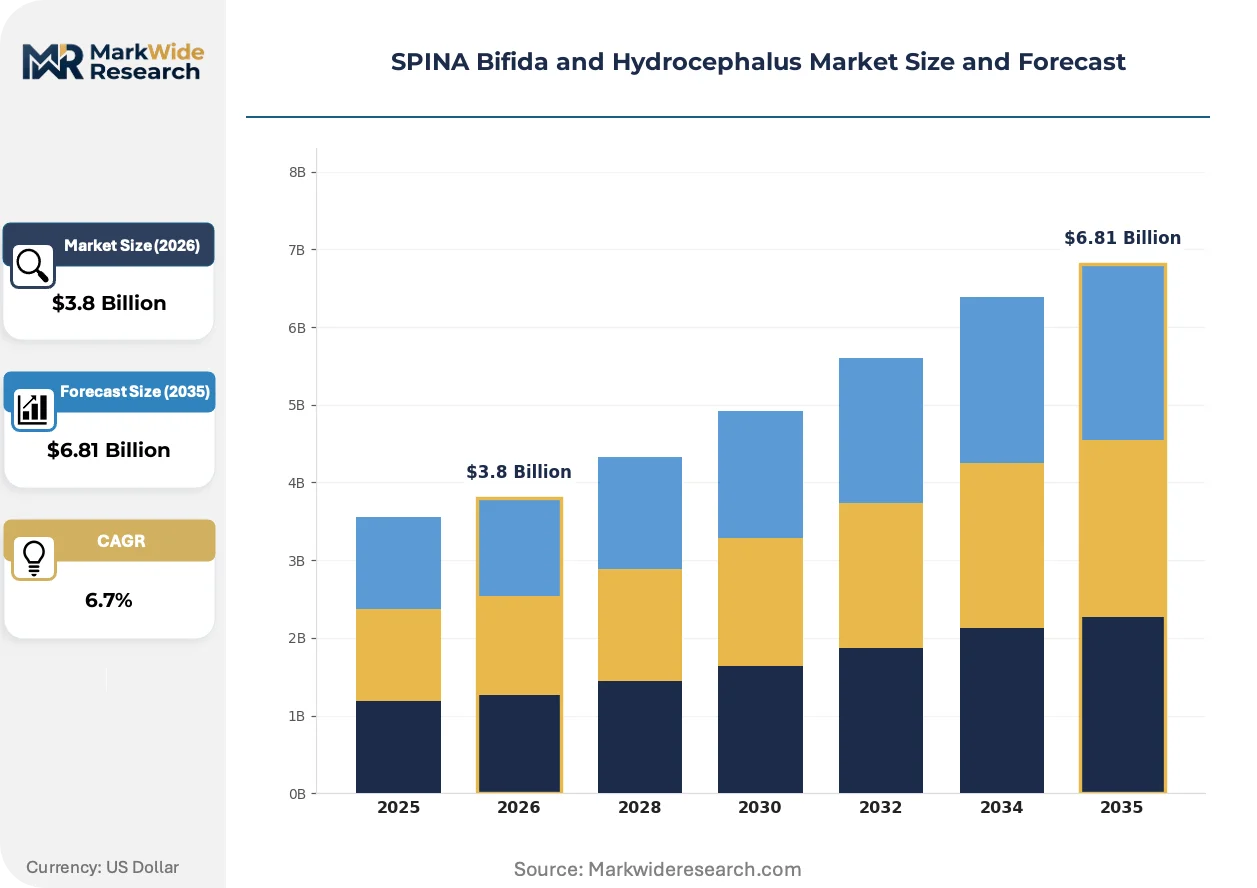
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostics, Surgery, Rehabilitation, Medication Application: Pediatric Care, Neurosurgery, Physical Therapy, Neurology End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Technology: Imaging Techniques, Surgical Tools, Therapeutic Devices, Monitoring Systems |
| Companies Covered | Medtronic, Integra LifeSciences Corporation, B. Braun SE, Sophysa, Spiegelberg GmbH & Co. KG, Aesculap, Cook Medical, Hollister Incorporated, CHRISTOPH MIETHKE GMBH & CO. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SPINA Bifida and Hydrocephalus Market Emerging Trajectories
Magnetic adjustment mechanisms and wireless telemetry are converging to create shunt systems that no longer require physical palpation for pressure verification, fundamentally altering the clinical workflow between neurosurgeons and follow-up care teams.
Smart valve platforms incorporating MEMS pressure transducers and Bluetooth Low Energy transmission are modularizing the traditional shunt into separable sensing, processing, and actuation subsystems. Pediatric hospitals in Boston and Tokyo are piloting these architectures for remote intracranial pressure trending. This modularization is enabling third-party software developers to build patient-monitoring applications that sit outside manufacturer-controlled ecosystems.
EMA's 2024 guidance on active implantable medical devices is requiring cybersecurity documentation for any shunt system with wireless connectivity, adding technical file burdens that delay CE marking by four to six months. Manufacturers must now submit penetration testing reports and software bill of materials alongside traditional biocompatibility data. The programmable valve segment is absorbing these costs through dedicated regulatory affairs teams that maintain parallel FDA and notified body relationships.
Hospital procurement departments are consolidating shunt purchasing through value-analysis committees that bundle valves, catheters, and external drainage systems under single-source contracts. Academic medical centers in Germany and the United States are leading this consolidation, displacing the previous surgeon-driven preference model. This shift is most visible in high-volume pediatric neurosurgical programs where standardization reduces operating room inventory complexity.
SPINA Bifida and Hydrocephalus Market Segmentation
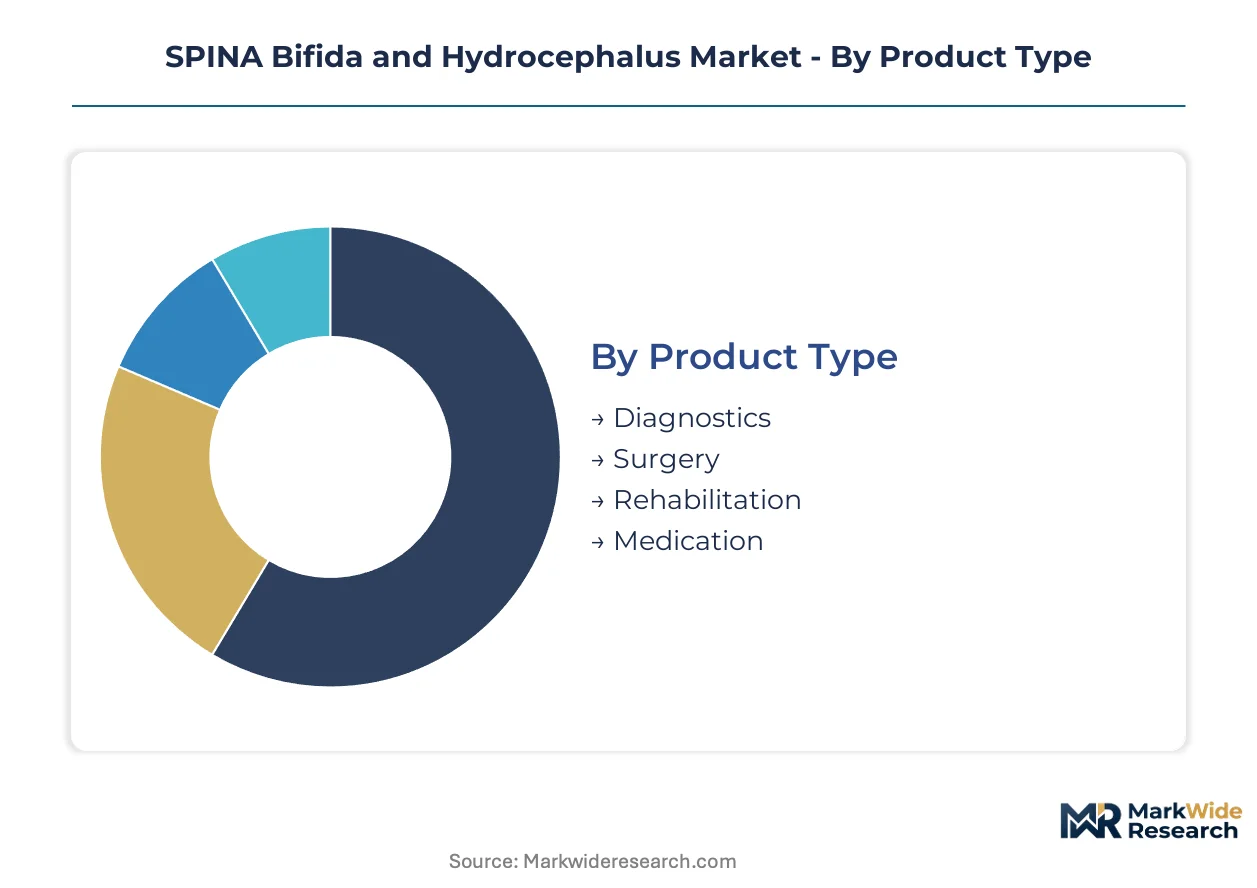
Spina bifida and hydrocephalus treatment pathways demand precise segmentation mapping because patient age, anatomical severity, and comorbidity profiles dictate entirely different product specifications and regulatory pathways. Manufacturers must align R&D portfolios with how hospitals actually procure—whether through bundled neurosurgical contracts or standalone pediatric device tenders.
Product Type:
FDA Class III and EU MDR Class III pathways impose divergent clinical evidence burdens across these four product categories, with active implantables facing the steepest premarket validation requirements.
- Surgery:Programmable shunt valves, endoscopic third ventriculostomy tools, and dural repair matrices constitute the revenue core. Demand clusters in metropolitan pediatric neurosurgical centers in the United States, Germany, and Japan where fellowship-trained specialists concentrate caseloads and drive preference for magnetic-adjustment mechanisms.
- Therapeutic Devices:CSF diversion systems, external ventricular drains, and lumbar-peritoneal shunts operate at pressure thresholds of 5–20 cmH₂O. German and Japanese hospitals are prioritizing MRI-conditional titanium-nitride coatings that eliminate replacement requirements before imaging procedures.
- Diagnostics:Prenatal ultrasound, fetal MRI, and biomarker assays enable neural tube defect detection. Maternal-fetal medicine programs in academic medical centers drive adoption of high-resolution imaging protocols.
- Rehabilitation:Orthotic bracing, urological management systems, and mobility aids address spina bifida sequelae. Home care reimbursement frameworks in the United States determine patient access to powered wheelchair and continence device prescriptions.
Leading the category by volume: Surgery. Growing fastest: Therapeutic Devices.
Application:
Cost tiers separate emergency neurosurgical intervention from chronic management, with pediatric pathways commanding premium pricing due to miniaturization requirements and extended monitoring obligations.
- Pediatric Care:Neonatal shunt placement for hydrocephalus associated with myelomeningocele requires specialized valve dimensions below 2.5 kg body weight. Expanded newborn screening mandates in Germany and Japan are detecting cases earlier and extending shunt-dependent patient lifecycles.
- Neurosurgery:Craniotomy, shunt revision, and endoscopic procedures generate the deepest margin pools. Academic medical centers in Boston and Tokyo are piloting smart valve platforms with MEMS pressure transducers and Bluetooth Low Energy transmission for remote intracranial pressure trending.
- Neurology:Adult normal pressure hydrocephalus diagnosis and management is climbing the fastest in Japan's super-aging corridor where patients over 75 now exceed pediatric incidence rates.
- Physical Therapy:Gait training, spasticity management, and functional mobility restoration support spina bifida patients post-surgery. Rehabilitation centers coordinate with orthopedic and urological services for comprehensive care pathways.
Pediatric Care commands the highest revenue per patient. Neurosurgery shows the steepest expansion trajectory in procedure volumes.
End User:
Procurement authority concentrates differently across these settings—surgeon preference dominates academic hospitals while value-analysis committees control purchasing in consolidated health systems.
- Hospitals:Tertiary pediatric neurosurgical centers perform the majority of primary shunt placements and revisions. Hospital procurement departments in Germany and the United States are consolidating valve, catheter, and external drainage purchases under single-source contracts.
- Home Care:Shunt malfunction monitoring, urological catheter management, and family caregiver training extend institutional protocols into residential settings. Telemetric shunt sensors transmitting intracranial pressure data to cloud platforms are opening subscription revenue models alongside hardware sales.
- Clinics:Outpatient neurology and maternal-fetal medicine practices handle diagnosis, prenatal counseling, and longitudinal shunt surveillance. MRI compatibility requirements shape referral patterns to imaging-capable facilities.
- Rehabilitation Centers:Post-surgical functional recovery and adaptive equipment fitting serve spina bifida patients with lower extremity paralysis. Orthotic and wheelchair prescription authority varies by national reimbursement frameworks.
Hospitals lead by volume. Home Care is gaining share fastest as remote monitoring platforms mature.
Technology:
Maturity gradients separate established imaging modalities from emerging wireless telemetry systems still navigating EMA cybersecurity documentation requirements.
- Surgical Tools:Programmable valves, neuroendoscopes, and ultrasonic aspirators enable minimally invasive intervention. Miniaturization is compressing revision surgery rates while forcing manufacturers to rebuild regulatory dossiers around biocompatibility testing protocols.
- Monitoring Systems:Telemetric pressure sensors, cloud-based trending platforms, and patient-facing mobile applications modularize traditional shunts into separable subsystems. EMA's guidance on active implantable medical devices now requires penetration testing reports and software bills of materials.
- Imaging Techniques:Fetal MRI, high-resolution ultrasound, and rapid-sequence CT support diagnosis and shunt surveillance. Magnetic resonance-conditional materials are eliminating compatibility barriers that previously forced device replacement.
- Therapeutic Devices:Programmable shunts, external drainage systems, and lumbar-peritoneal configurations manage cerebrospinal fluid dynamics. FDA guidance on CSF shunt predicates now requires new clinical data for programmable pressure mechanisms.
Surgical Tools dominate current revenue. Monitoring Systems show the most rapid technology substitution as wireless telemetry platforms achieve regulatory clearance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates where specialized pediatric neurosurgical infrastructure intersects with regulatory clarity for Class III implantables. The United States, Germany, and Japan absorb the majority of programmable shunt placements due to fellowship-trained specialist density and reimbursement frameworks that cover magnetic-adjustment mechanisms.
United States
Pediatric neurosurgical centers in Boston and Philadelphia drive preference for telemetric pressure monitoring platforms. FDA 510(k) pathways for CSF diversion devices now require new clinical data for programmable mechanisms, extending clearance timelines. Academic medical centers consolidate valve, catheter, and drainage purchases under value-analysis committees rather than surgeon-driven selection.
Germany
Expanded newborn neural tube defect screening protocols detect hydrocephalus earlier, extending shunt-dependent patient lifecycles. EU MDR Class III requirements for cerebrospinal fluid devices stabilized after the 2021 transition, reducing premarket uncertainty. Specialty chemical suppliers in Baden-Württemberg control platinum-cured silicone feedstocks for medical-grade elastomers.
Japan
Normal pressure hydrocephalus diagnosis in adults over 75 now exceeds pediatric incidence, shifting volume toward adult-programmable systems. PMDA reviews active implantable medical devices with heightened scrutiny for wireless connectivity features. Tokyo hospitals pilot MEMS pressure transducer platforms with Bluetooth Low Energy transmission for remote intracranial pressure trending.
Switzerland
Swissmedic oversees notified body relationships for manufacturers seeking CE marking under EU MDR frameworks. Precision polymer suppliers in the Basel region provide advanced biocompatible materials with lower protein-adhesion profiles than legacy silicone. The country's regulatory infrastructure supports parallel FDA and European submissions for neurosurgical device developers.
United Kingdom
NHS procurement frameworks bundle shunt systems under centralized tenders that favor standardization over brand preference. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulations with EU MDR technical standards. London pediatric neurosurgical units concentrate revision surgery caseloads for complex shunt-dependent patients.
SPINA Bifida and Hydrocephalus Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers extend from hardware into subscription-based remote monitoring services. The vendor base organizes around three tiers: integrated neurosurgical conglomerates with full CSF management portfolios, specialized valve and catheter developers, and regional contract manufacturers supplying private-label components. Strategic archetypes include technology licensors monetizing magnetic-adjustment patents, vertically integrated polymer processors controlling material feedstocks, and software platforms modularizing traditional shunt architectures. M&A activity and regulatory dossier rebuilding around biocompatibility protocols represent the dominant competitive moves.
Among integrated-device conglomerates, Medtronic and Integra LifeSciences occupy positions exemplifying the full-portfolio archetype spanning programmable valves through dural repair matrices. B. Braun SE represents the European regulatory-specialist archetype, maintaining dedicated notified body relationships across multiple jurisdictions. These three entities anchor the premium tier where magnetic-adjustment mechanisms and MRI-conditional coatings concentrate value, while mid-tier manufacturers navigate ISO 10993 testing cascades that now exceed $400,000 per novel polymer qualification.
| Leading Market Players |
|---|
| Medtronic |
| Integra LifeSciences Corporation |
| B. Braun SE |
| Sophysa |
| Spiegelberg GmbH & Co. KG |
| Aesculap |
| Cook Medical |
| Hollister Incorporated |
| CHRISTOPH MIETHKE GMBH & CO. KG |
| Others |
Supply Flow & Price Mechanics
Pediatric neurosurgical specialist concentration in 12 United States metropolitan centers creates acute labor-cost differentials between academic medical centers and community hospitals, compressing pricing-tier spreads for programmable shunt systems as manufacturers absorb premium workforce premiums into standard tier offerings.
Pricing Analysis
High-volume shunt valve placements in pediatric centers generate thin margins while low-volume revision surgeries in specialized units capture premium returns. Three-tier pricing structure across premium magnetic-adjustment, standard fixed-pressure, and economy external drainage levels separates MRI-conditional titanium-nitride coatings from legacy silicone. Cost compression in standard pediatric valves is intensifying because German and Japanese procurement committees consolidate purchases under single-source contracts. Academic medical centers show lowest price sensitivity due to bundled reimbursement frameworks, while rural hospitals face acute budget constraints driving economy-tier preference.
Supply Chain Analysis
Domestic-content mandates in Japan's PMDA framework and EU MDR technical documentation requirements are reshaping sourcing patterns for active implantable components. Platinum-cured silicone feedstocks concentrate in Germany and Switzerland, with titanium-nitride coating services anchored in Japanese precision-metalworking clusters. Raw material dependencies span medical-grade elastomers, rare-earth magnetic alloys, and biocompatible polymer substrates. Single-source vulnerability in German specialty chemical suppliers exposes valve manufacturers to polymer allocation delays. Distribution runs through hospital value-analysis committees in consolidated health systems, displacing surgeon-driven procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fellowship-trained pediatric neurosurgical workforce scarcity props pricing power for implantable shunt systems, as capacity constraints limit procedure volume expansion regardless of device availability.
For Market Incumbents: Deepen backward integration into platinum-cured silicone feedstocks to insulate against German and Swiss supplier allocation disruptions. Fortify regulatory dossiers for EU MDR Class III cybersecurity documentation requirements ahead of EMA's active implantable guidance enforcement. Control channel position by embedding telemetry subscription services into long-term hospital contracts, locking out competitors from remote monitoring revenue streams. For New Entrants and Emerging Players: EU MDR Class III pathway clarity in cerebrospinal fluid devices opens a window for specialized valve miniaturization below 2.5 kg neonatal thresholds, an underserved white space dominated by legacy dimensions. Target Japanese normal pressure hydrocephalus diagnosis growth in adults over 75, where volume now exceeds pediatric incidence. Pursue software companion development partnerships with Boston and Tokyo academic centers piloting MEMS pressure transducer platforms, bypassing hardware manufacturing barriers. For Investors and Strategic Acquirers: The window for entry favors mid-tier manufacturers with completed ISO 10993 biocompatibility testing cascades for novel polymers, as qualification costs exceeding $400,000 create defensive moats. Long-term viability hinges on telemetric shunt sensor platforms transitioning from pilot to reimbursable standard-of-care. Watch FDA guidance evolution on CSF shunt predicates as the inflection signal—tightened substantial equivalence requirements will accelerate consolidation toward dossier-complete incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class III technical documentation for wireless telemetry systems delays market entry by four to six months. |
| Hospital System Partnership | Bundled valve-catheter-drainage contracts with German academic centers displace surgeon preference models. |
| Software Companion Development | Bluetooth Low Energy patient-monitoring applications modularize traditional shunt architectures beyond manufacturer control. |
| Reimbursement Strategy | Remote intracranial pressure trending subscription models in United States pediatric centers create recurring revenue alongside hardware. |
| FDA Submission | Premarket notification pathways for programmable pressure mechanisms now require new clinical data, extending timelines. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews conducted with pediatric neurosurgeons, hospital purchasing committee members, biomedical engineers specializing in implantable devices, and GPO contracts managers. FDA 510(k) clearance databases, EMA medical device registration records, PMDA approval documents, and hospital procurement transaction logs supplied quantitative validation. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Data-stream reconciliation between shunt placement procedure counts and valve unit shipments calibrated the analytical framework across product type, application, end user, and technology dimensions. CAGRs derived from weighted regression across neonatal screening expansion rates, specialist workforce density projections, and reimbursement policy trajectories. Forecast inputs incorporated EU MDR transition completion timelines, Japanese super-aging corridor diagnosis patterns, and magnetic resonance-conditional material adoption curves.
The model assumes a particular technology adoption path; alternative pathways for wireless telemetry integration would alter the outlook if cybersecurity documentation requirements accelerate or telemetric sensor reliability fails clinical validation. Forecasts reflect assumptions around stable platinum-cured silicone supply and sustained specialist concentration in metropolitan surgical centers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Complex Regional Pain Syndrome (CRPS) Market
Specialty Medicine
Cytomegalovirus Retinitis Market
Specialty Medicine
Global Hormone Replacement Therapy Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Peripheral Neuropathy Market
Specialty Medicine
Chimeric Antigen Receptor (CAR) T-Cell Therapy Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Treatment Market
Specialty Medicine
Moderate-To-Severe Acne Therapeutics Market
Specialty Medicine
Abetalipoproteinemia Management Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market
Specialty Medicine
Cirrhosis Management Market
Specialty Medicine
Anaplastic Astrocytoma Market
Specialty Medicine
Toxoplasmosis Treatment Market
Specialty Medicine
Cholangiocarcinoma Market
Specialty Medicine
Global Pemphigus Vulgaris Market