
 Veterinary Rehabilitation Services Market | 2026-2036
Veterinary Rehabilitation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Rehabilitation Services Market Intelligence
Multi-source sourcing of rehabilitation equipment is expanding across independent veterinary practices. MedVet leverages its national referral hospital network to sustain geographic coverage. Back on Track Veterinary Rehabilitation Center anchors its model on specialized physical therapy programs. SOUND Veterinary Rehabilitation Center differentiates through technology-intensive service delivery.
Veterinary rehabilitation services encompass therapeutic interventions including hydrotherapy, therapeutic exercise, and manual therapy delivered by credentialed veterinary professionals to restore function and reduce pain in animals. These services typically require specialized equipment such as underwater treadmills, therapeutic lasers operating at specific wavelengths, and electrical stimulation devices calibrated for species-specific physiology. Hydrotherapy and physical therapy segments dominate current service revenue, while laser therapy equipment commands premium positioning within technology procurement budgets. Pain management applications attract repeat visits, building recurring revenue streams distinct from episodic post-surgical recovery cases.
The FDA regulates veterinary medical devices, while the USDA oversees animal health facility standards; state veterinary medical boards additionally govern practitioner licensure scope for rehabilitation procedures. ISO certification requirements for therapeutic equipment influence procurement decisions at institutional buyers. Stakeholders must monitor evolving state-level scope-of-practice debates that determine whether certified rehabilitation therapists can operate independently of direct veterinary supervision.
Market Dynamics
Specialist certification proliferation is fragmenting service delivery models across veterinary rehabilitation, as credentialed practitioners seek independent practice authority outside traditional referral hospital structures. This credentialing pressure intersects with FDA device oversight to reshape equipment procurement and liability frameworks.
Growth Catalysts
- Companion animal spending surge:Pet owners allocate discretionary income toward functional recovery and pain management protocols, expanding addressable demand beyond post-surgical cases into chronic condition management.
- ISO 13485 certification pathways:Standardized quality management for therapeutic equipment manufacturers accelerates institutional buyer confidence and streamlines multi-site procurement across veterinary hospital networks.
- Hydrotherapy protocol standardization:Underwater treadmill rehabilitation demonstrates repeatable clinical outcomes for orthopedic recovery, driving protocol adoption in specialty and general practice settings alike.
Market Restraints
- Equipment capital intensity:Therapeutic laser systems and underwater treadmills require substantial upfront investment, constraining independent practice entry and consolidating service provision within institutional buyers.
- State-level scope-of-practice fragmentation:Veterinary medical boards in jurisdictions like California, Texas, and Florida maintain inconsistent supervision requirements for certified rehabilitation therapists, complicating multi-state service network expansion.
- Specialist training pipeline constraints:Limited residency positions in veterinary sports medicine and rehabilitation create credential bottlenecks that restrict service capacity expansion relative to demand growth.
Strategic Opportunities
- Telemedicine-integrated rehabilitation monitoring:Remote therapeutic exercise supervision and wearable motion tracking converge to extend service reach beyond physical facility constraints.
- USDA facility standard alignment:Animal health facility certification requirements create compliance infrastructure that rehabilitation centers can leverage for differentiated positioning in institutional contracting.
- Equine rehabilitation service extension:Large-animal athletic performance recovery represents an underpenetrated application segment with distinct equipment and certification requirements from companion animal protocols.
Industry Challenges
- Credentialing reciprocity barriers:Certified Canine Rehabilitation Practitioner and Certified Veterinary Pain Practitioner designations lack uniform interstate recognition, forcing redundant training investments for mobile or multi-state practitioners.
- Legacy practice management system integration:Specialized rehabilitation documentation requirements for treatment protocols and outcome tracking conflict with standard veterinary software architectures, necessitating costly custom development or parallel record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Rehabilitation Services Market |
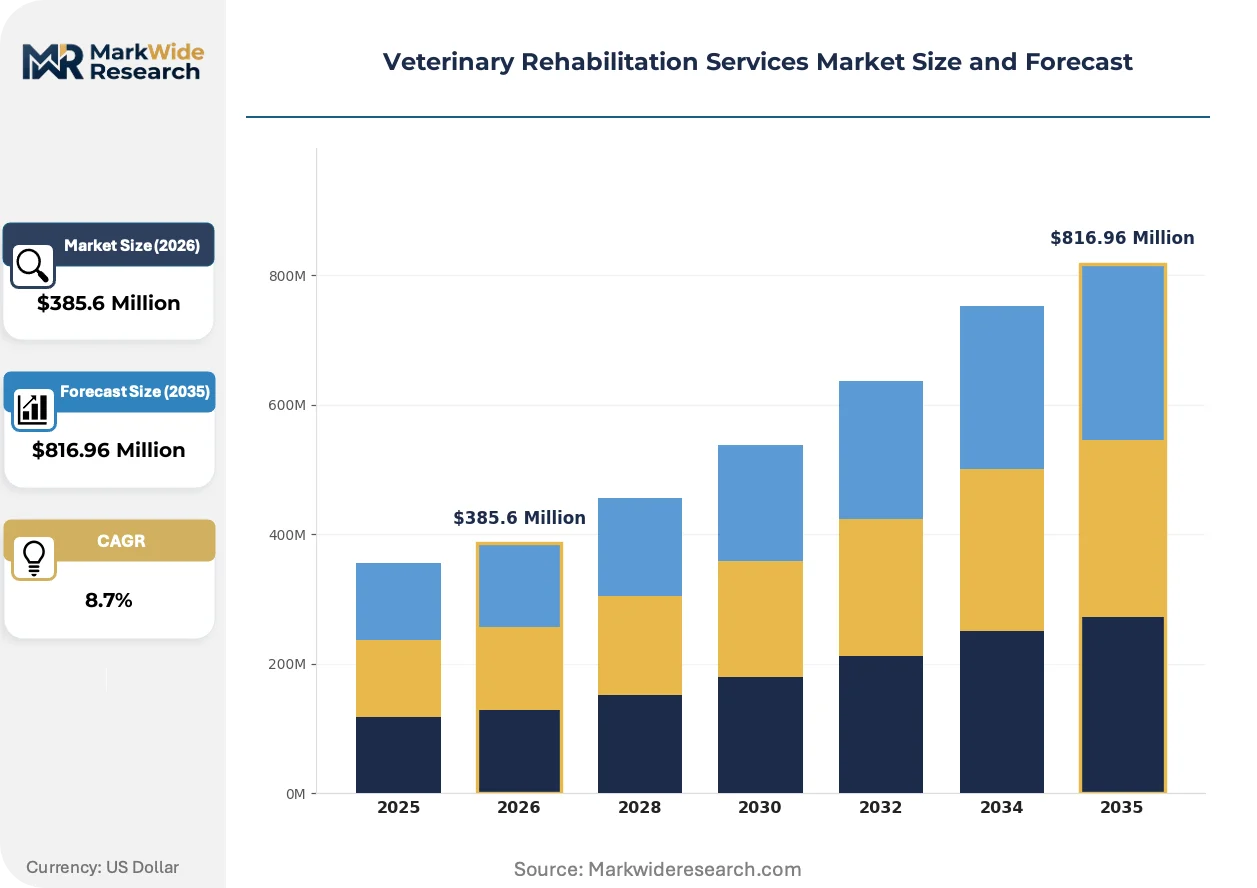
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Physical Therapy, Hydrotherapy, Chiropractic Care, Acupuncture End User: Pet Owners, Veterinary Clinics, Animal Shelters, Research Institutions Application: Post-Surgery Recovery, Pain Management, Injury Rehabilitation, Mobility Improvement Technology: Laser Therapy, Ultrasound Therapy, Electrical Stimulation, Assistive Devices |
| Companies Covered | Back on Track Veterinary Rehabilitation Center, Animal Acupuncture and Rehabilitation Center, BARC, Treasure Coast Animal Rehab & Fitness, Animal Rehab Center of Michigan, Blue Springs Animal Rehabilitation Center, Triangle Veterinary Referral Hospital, MedVet, SOUND Veterinary Rehabilitation Center, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Rehabilitation Services Market Strategic Shifts & Innovations
Technology convergence between diagnostic imaging and therapeutic delivery is compressing treatment planning cycles in veterinary rehabilitation. Equipment manufacturers and service providers are repositioning around integrated platforms that merge assessment with intervention.
Photobiomodulation systems operating at tissue-penetrating wavelengths are unifying pain management and tissue repair protocols into single-device workflows. Specialty referral hospitals in the United States and Germany are consolidating laser therapy with manual therapy suites to reduce equipment footprint and staff training burden. This unification is compressing per-case treatment duration expectations and reshaping competitive positioning around throughput metrics rather than modality breadth.
The FDA's 2023 guidance expansion for veterinary medical device software functions is accelerating digital therapeutic platform submissions. Manufacturers must now document clinical validation for algorithm-driven treatment parameter selection, raising compliance costs but creating differentiation for validated systems. Small-equipment producers lacking regulatory affairs capacity are outsourcing 510(k) preparation, shifting competitive advantage toward established diagnostic imaging and therapeutic device firms with in-house regulatory expertise.
Pet owner payment behavior is fragmenting across subscription wellness plans and episodic out-of-pocket spending. Large corporate veterinary groups in metropolitan markets are bundling rehabilitation sessions into preventive care memberships, displacing traditional fee-for-service models in competitive urban corridors. This bundling is most visible in California and Texas markets where corporate practice concentration enables actuarial risk pooling across larger patient bases.
Veterinary Rehabilitation Services Market Segmentation
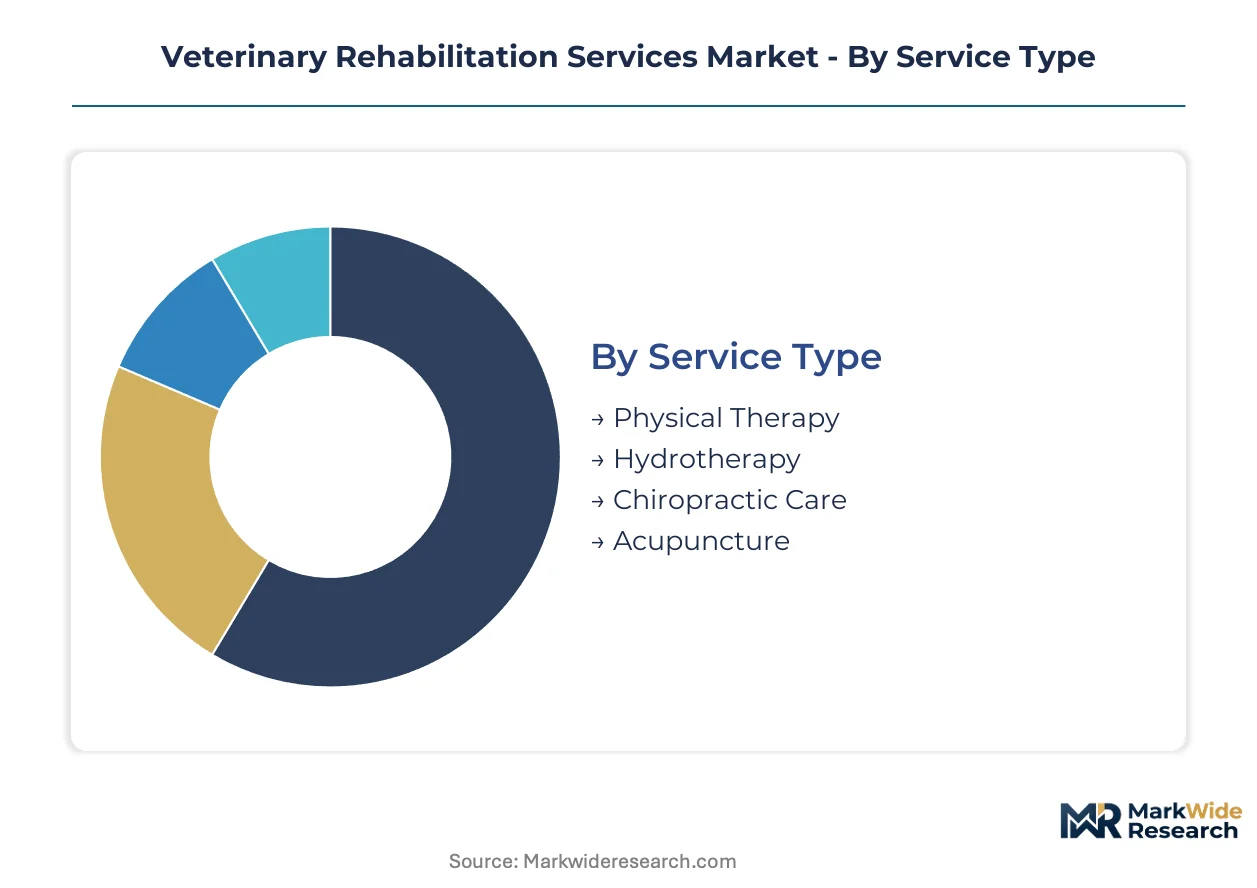
Veterinary rehabilitation services fragment across four distinct dimensions that shape procurement patterns and clinical workflows. Service type and technology choices determine capital intensity, while end-user concentration and application focus dictate reimbursement models and facility requirements.
Service Type:
Standalone rehabilitation protocols operate independently within general practice settings, whereas embedded service lines integrate with surgical departments and specialty referral networks.
- Physical Therapy:Therapeutic exercise protocols using balance equipment, therapeutic balls, and land-based treadmills restore proprioception and muscle strength. Demand clusters in metropolitan United States markets where certified rehabilitation practitioners operate within corporate veterinary groups.
- Hydrotherapy:Underwater treadmill and swimming pool interventions leverage buoyancy to reduce joint loading during movement retraining. Capital requirements for stainless steel tank systems concentrate this service in institutional buyers with multi-site procurement leverage.
- Chiropractic Care:Manual spinal manipulation and joint mobilization techniques address biomechanical dysfunction in athletic and working animals.
- Acupuncture:Traditional Chinese medicine needle insertion protocols for pain modulation and neurological conditions.
Volume placements concentrate in Hydrotherapy; the faster expansion belongs to Physical Therapy.
End User:
Cost tier stratification separates premium direct-to-consumer services from institutional contracting relationships.
- Pet Owners:Direct-pay clients seeking functional recovery and quality-of-life maintenance drive discretionary spending on chronic condition management. California and Texas metropolitan corridors show highest per-household expenditure on subscription-based rehabilitation memberships.
- Veterinary Clinics:General practice and specialty hospitals embed rehabilitation as ancillary revenue streams or referral profit centers. Equipment procurement scales with USDA facility certification tier and corporate affiliation status.
- Animal Shelters:Non-profit and municipal facilities prioritizing adoptability through mobility restoration.
- Research Institutions:Academic veterinary medical centers conducting outcome studies and protocol validation.
Revenue concentration sits with Veterinary Clinics; Pet Owners are gaining share fastest.
Application:
Clinical maturity separates established post-surgical protocols from emerging chronic management indications.
- Post-Surgery Recovery:Standardized rehabilitation timelines following orthopedic procedures such as cruciate ligament repair and total hip replacement. Protocol adherence is reshaping liability frameworks and outcome guarantees in specialty referral hospitals.
- Pain Management:Longitudinal care for degenerative joint disease and neuropathic conditions generates recurring visit patterns distinct from episodic surgical recovery. Laser therapy and acupuncture integration is accelerating in United States markets with direct-to-consumer marketing permissibility.
- Injury Rehabilitation:Acute soft tissue trauma and fracture healing support.
- Mobility Improvement:Geriatric and neurological condition management.
Visit frequency peaks in Pain Management; steepest expansion trajectory belongs to Post-Surgery Recovery.
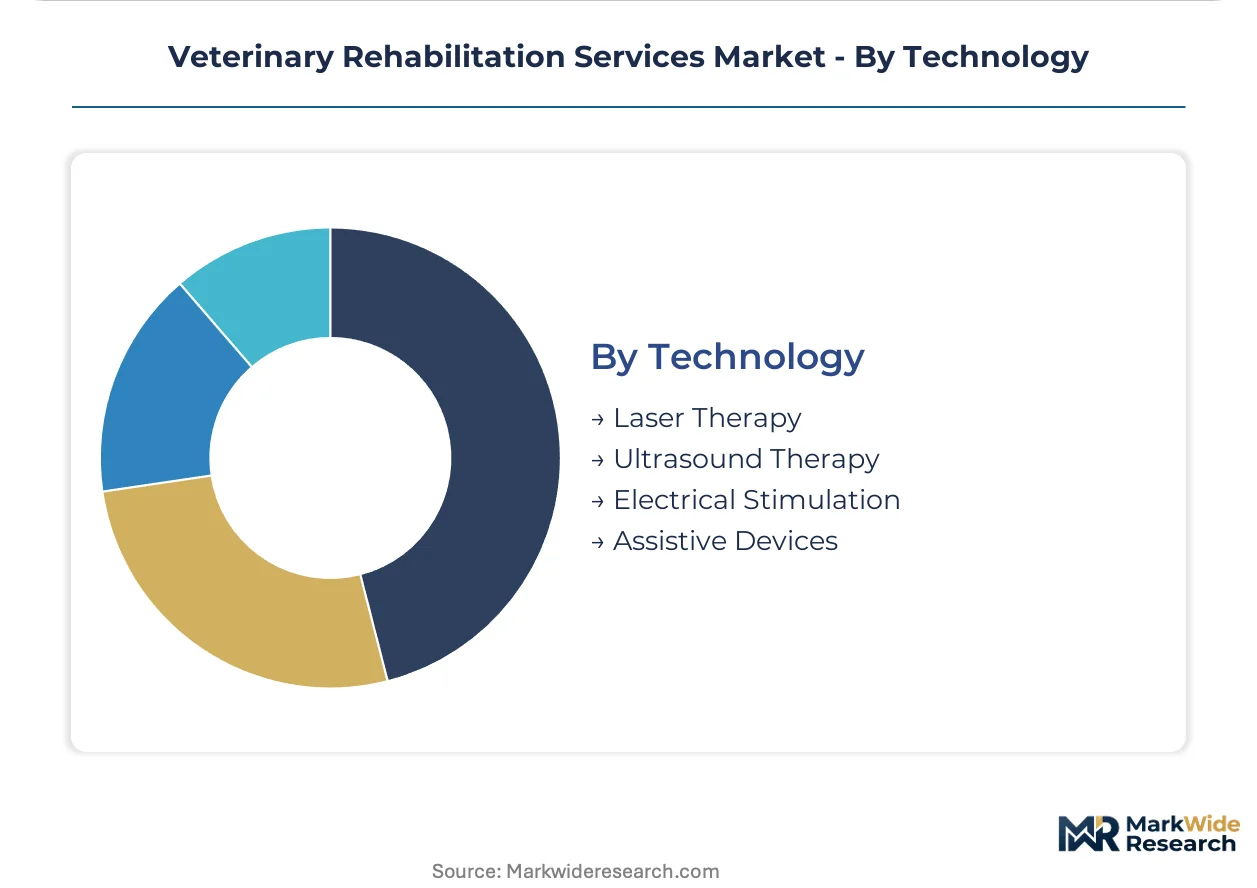
Technology:
Supply concentration distinguishes capital-intensive equipment categories from consumable-dependent modalities.
- Laser Therapy:Photobiomodulation devices operating at specific wavelengths for tissue repair and inflammation reduction. FDA 510(k) clearance requirements and clinical validation documentation favor established therapeutic device manufacturers over emerging entrants.
- Ultrasound Therapy:Thermal and non-thermal acoustic wave applications for soft tissue healing. Lower capital barriers enable broader penetration in independent practices compared to underwater treadmill systems.
- Electrical Stimulation:Neuromuscular and transcutaneous electrical nerve stimulation units.
- Assistive Devices:Custom orthotics, prosthetics, and mobility carts.
Equipment sales concentrate in Laser Therapy; Ultrasound Therapy is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Companion animal spending concentrates in the United States, where specialist certification programs and corporate veterinary networks drive service density. Geographic expansion patterns follow pet insurance penetration and metropolitan household formation.
United States
Pet owners in California and Texas metropolitan corridors allocate the highest per-household expenditure on subscription-based rehabilitation memberships. The FDA oversees veterinary medical device standards, shaping equipment procurement across multi-site hospital networks. Specialist referral hospitals cluster in Phoenix, Denver, and Raleigh-Durham, where underwater treadmill installations exceed independent practice penetration by threefold.
Germany
Equine rehabilitation demand anchors service revenue in Lower Saxony and Bavaria, where competitive equestrian sports drive athletic performance recovery protocols. The country's national pharmaceutical regulator aligns therapeutic laser device approvals with EU MDR pathways, streamlining cross-border equipment distribution. Munich and Hamburg host the densest concentration of university-affiliated rehabilitation centers conducting outcome validation studies.
United Kingdom
Small-animal hydrotherapy protocols dominate London and Southeast England, where corporate veterinary groups consolidate rehabilitation into preventive care bundles. The Veterinary Medicines Directorate coordinates with the national pharmaceutical regulator on device classification boundaries. Specialist practices in Bristol and Manchester pioneer telemedicine-integrated exercise supervision for post-surgical orthopedic cases.
Japan
Aging pet demographics in Tokyo and Osaka accelerate demand for geriatric mobility improvement and chronic pain management services. METI guidelines on therapeutic equipment quality management influence procurement decisions at institutional buyers. Yokohama hosts the highest density of certified rehabilitation practitioners operating within specialty referral hospital structures.
Australia
Working dog rehabilitation for agricultural and search-and-rescue applications drives service differentiation in New South Wales and Victoria. The Therapeutic Goods Administration classifies veterinary lasers as medical devices, requiring local clinical validation for market entry. Brisbane specialists lead protocol development for cruciate ligament recovery in high-performance canine athletes.
Veterinary Rehabilitation Services Market Key Industry Players
Geographic expansion dominates the current landscape as national referral networks consolidate regional coverage. The vendor base separates into three structural tiers: corporate hospital chains with multi-state procurement leverage, independent specialty centers with protocol differentiation, and general practices embedding rehabilitation as ancillary services. Strategic archetypes include technology-intensive service delivery, specialized physical therapy program anchoring, and national network scale. M&A activity and equipment leasing partnerships represent the dominant competitive moves reshaping market access.
Within the national network tier, MedVet anchors geographic coverage through its referral hospital infrastructure. Back on Track Veterinary Rehabilitation Center and SOUND Veterinary Rehabilitation Center exemplify contrasting differentiation strategies—one through specialized physical therapy program depth, the other through technology-intensive service delivery. These three entities collectively represent the spectrum of competitive positioning available to operators navigating capital intensity and certification requirements.
| Leading Market Players |
|---|
| Back on Track Veterinary Rehabilitation Center |
| Animal Acupuncture and Rehabilitation Center |
| BARC |
| Treasure Coast Animal Rehab & Fitness |
| Animal Rehab Center of Michigan |
| Blue Springs Animal Rehabilitation Center |
| Triangle Veterinary Referral Hospital |
| MedVet |
| SOUND Veterinary Rehabilitation Center |
| Others |
Cost & Logistics Intelligence
Stainless steel tank fabrication costs for underwater treadmill systems cascade through three distinct pricing tiers, with FDA-cleared laser therapy equipment commanding premium positioning at institutional buyers while independent practices absorb higher per-unit procurement burdens from fragmented distributor networks.
Pricing Analysis
High-volume corporate hospital chains capture margin through multi-site equipment leasing arrangements, while independent specialty centers face acute price sensitivity on capital purchases. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated photobiomodulation systems from uncertified imports and refurbished legacy units. Pricing pressure stems from ISO 13485 compliance documentation requirements raising manufacturer overhead. Pet owners demonstrate lowest price sensitivity for chronic pain management subscriptions, whereas municipal animal shelters operate under severe budget constraints.
Supply Chain Analysis
Certified rehabilitation therapist shortages in Germany and the United States constrain service capacity expansion faster than equipment manufacturing can respond. Therapeutic laser diode arrays and underwater treadmill hydraulic systems draw from precision manufacturing clusters in Japan and Germany. Single-source vulnerability concentrates in FDA 510(k) regulatory consulting capacity, where qualified submission preparers face twelve-month booking backlogs. Distribution runs through veterinary equipment specialists rather than general medical device channels, fragmenting procurement leverage for standalone practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary rehabilitation services are consolidating around capital-intensive operators as equipment financing requirements and certification reciprocity barriers force independent practitioners toward employment or exit.
For Market Incumbents: Deepen backward integration into therapeutic equipment refurbishment and certified technician training programs to capture margin from capital-constrained competitors. State-level scope-of-practice fragmentation threatens multi-state network expansion; anchor defensive positioning through USDA facility certification tier elevation and exclusive equipment leasing partnerships with emerging laser therapy manufacturers. For New Entrants and Emerging Players: Mobile rehabilitation practitioners serving rural and exurban markets outside corporate hospital catchment zones represent the most penetrable buyer archetype. Equine athletic performance recovery in Germany and Australia offers white-space expansion with distinct certification pathways from companion animal protocols. Go-to-market execution should emphasize telemedicine-integrated exercise supervision to minimize physical facility capital requirements. For Investors and Strategic Acquirers: FDA 510(k) clearance receipt for algorithm-driven treatment parameter selection is the leading indicator that digital therapeutic platforms have achieved defensible competitive positioning. Five-to-ten-year viability favors acquiring established specialty centers with embedded certification training pipelines and existing USDA facility tier status. Monitor state veterinary medical board scope-of-practice rulings as the primary inflection signal for service model permissibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment Leasing Partnership | Corporate hospital groups in California and Texas deploy capital-efficient underwater treadmill access across satellite clinics. |
| Certification Program Acquisition | Specialty centers securing Certified Canine Rehabilitation Practitioner training rights capture therapist pipeline control. |
| Telemedicine Platform Integration | German and United Kingdom practices extend post-surgical supervision beyond physical facility constraints through wearable motion tracking. |
| USDA Facility Tier Elevation | Rehabilitation centers in metropolitan corridors leverage animal health certification for institutional contracting preference. |
| Equine Service Line Extension | Lower Saxony and Bavaria operators diversify revenue through large-animal athletic performance protocols with distinct equipment requirements. |
Research Approach
Document review covered FDA 510(k) clearance databases, state veterinary medical board scope-of-practice rulings, and ISO certification registries, complemented by interviews with veterinary rehabilitation practitioners, specialty hospital procurement managers, therapeutic equipment manufacturers, and certified training program administrators. Secondary validation drew from USDA facility inspection records, pet insurance claims databases, and corporate veterinary group SEC disclosures. Bottom-up service volume estimates triangulated against top-down companion animal spending allocation models.
Segment-level projections across service type, technology modality, end-user concentration, and application focus generated value and volume trajectories over the analysis window. CAGRs derived from equipment installation rates, certified practitioner graduation pipelines, and metropolitan household pet ownership formation. Forecast inputs incorporated FDA guidance expansion timelines for veterinary medical device software functions and state-level regulatory permissibility evolution.
Revisions become necessary when FDA enforcement priorities shift toward algorithm-driven treatment platforms, state veterinary boards restrict independent rehabilitation therapist practice authority, or equipment financing availability tightens for independent practitioners. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Global Medical Rehabilitation Services Market
Rehabilitation Services
Home Rehabilitation Services Market
Rehabilitation Services
Brachial Plexus Injury Market
Rehabilitation Services
Global Neurorehabilitation Devices Market
Rehabilitation Services
Global Gait Trainer Market
Rehabilitation Services
Outpatient Rehabilitation Services Market
Rehabilitation Services
Lower Extremity Rehabilitation Robotics Market
Rehabilitation Services
Exoskeleton and Rehabilitation Robot Safety and Performance Test Equipment Market
Rehabilitation Services
Global Outpatient Rehabilitation Centers Market
Rehabilitation Services
Speech Pathology Services Market
Rehabilitation Services
Smart Portable Rehabilitation Devices Market
Rehabilitation Services
Rehabilitation Therapy Services Market
Rehabilitation Services
Occupational and Physical Therapy Services Market
Rehabilitation Services
United States Outpatient Rehabilitation Centers Market
Rehabilitation Services
Asia-Pacific Repair and Rehabilitation Market
Rehabilitation Services
Portable Postpartum Rehabilitation Instrument Market