
 US Speech Therapy Market | 2026-2036
US Speech Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
US Speech Therapy Market Intelligence
Aftermarket service revenue from post-acute rehabilitation contracts is narrowing as payers shift toward bundled episode payments. Genesis Rehab Services dominates skilled nursing facility placements across the Sun Belt. Kindred Healthcare anchors its position through hospital-based acute rehab partnerships. Select Medical competes on scale with its national network of outpatient therapy centers.
Speech therapy encompasses diagnostic assessment and therapeutic intervention for speech, language, voice, fluency, and swallowing disorders, typically delivered through structured sessions using standardized tools such as the Western Aphasia Battery or Modified Barium Swallow studies to measure functional outcomes. Its primary commercial purpose is restoring or compensating for communication and oral-motor deficits across neurological, developmental, and structural etiologies. Language intervention services for pediatric autism spectrum clients represent the fastest-expanding segment as school districts expand mandated early intervention staffing ratios. Telepractice delivery models are capturing margin pools previously held by clinical facility operators, particularly in rural counties with provider shortages. Voice therapy for aging professionals remains a mature, high-retention segment with limited price elasticity.
The Centers for Medicare and Medicaid Services shapes demand through prospective payment system updates for outpatient therapy, while state Medicaid agencies determine prior authorization requirements for speech-language pathology services. HIPAA privacy rules constrain telepractice platform selection and data storage architectures for multi-state providers. The Individuals with Disabilities Education Act mandates school-based service delivery, creating a stable institutional funding floor. Stakeholders must monitor state telehealth parity law evolution and Medicaid managed care penetration to anticipate reimbursement rate trajectories and site-of-service restrictions.
Market Dynamics
Telehealth parity legislation at the state level is fragmenting reimbursement pathways, forcing providers to maintain dual operational models for in-person and virtual delivery while CMS recalibrates its outpatient therapy payment schedules.
Growth Catalysts
- IDEA Mandates:The Individuals with Disabilities Education Act requires school districts to staff speech-language pathologists at mandated ratios, creating institutional demand floors for pediatric autism services.
- Telehealth Expansion:State-level parity laws in Texas and Florida now reimburse telepractice at parity with in-person sessions, opening rural counties with provider shortages.
- Aging Demographics:California's Medicare population growth is accelerating demand for dysphagia and aphasia intervention in post-acute settings.
Market Restraints
- Reimbursement Compression:CMS prospective payment system updates for outpatient therapy are narrowing per-session margins below cost-recovery thresholds for independent practices.
- Credentialing Bottlenecks:State licensing boards impose asynchronous telehealth restrictions that prevent multi-state providers from achieving operational scale.
- Workforce Supply Constraints:ASHA-accredited graduate programs produce fewer certified clinicians than district hiring mandates require, particularly in high-cost metropolitan areas.
Strategic Opportunities
- Rural Penetration:Federally Qualified Health Centers in Appalachian counties and the Texas Panhandle remain underserved for swallowing disorder assessment.
- Voice Therapy for Professionals:Broadcasters, attorneys, and executives in New York and Los Angeles represent a cash-pay segment with minimal payer interference.
- AI-Assisted Documentation:Natural language processing tools are reducing clinician administrative burden, freeing capacity for billable session volume expansion.
Industry Challenges
- Platform Interoperability:HIPAA-compliant telepractice systems require costly integration with electronic health record architectures already deployed by hospital systems.
- Outcome Measurement Standardization:Payers demand functional improvement metrics, yet the Western Aphasia Battery and Modified Barium Swallow studies lack universal adoption for episode-based contracting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Speech Therapy Market |
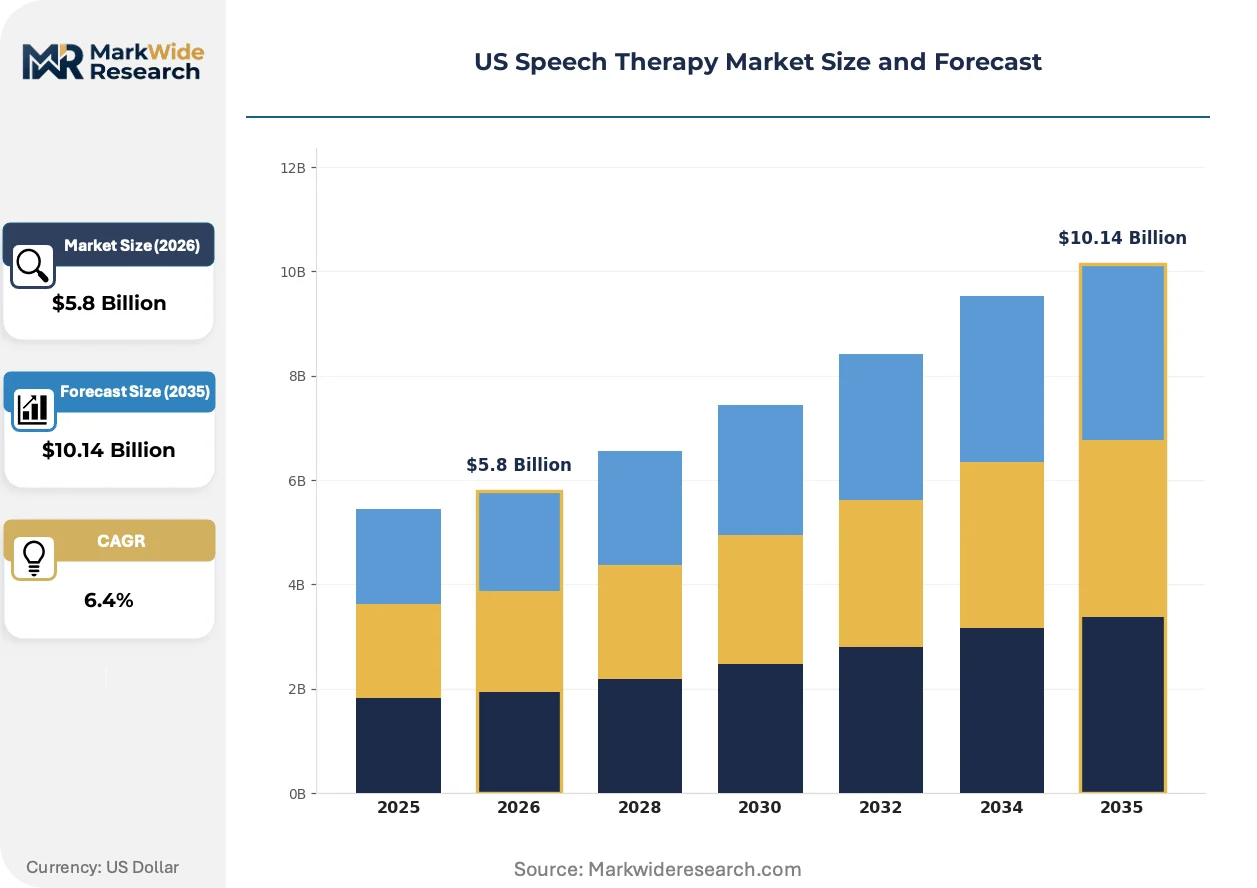
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Articulation Therapy, Language Intervention, Cognitive-Communication Therapy, Fluency Therapy, Voice Therapy Client Type: Children, Adults, Geriatric Patients, Individuals with Autism Spectrum, Stroke Survivors, Traumatic Brain Injury Patients Delivery Model: In-Person Therapy, Telepractice, Group Sessions, Home-Based Therapy, School-Based Therapy, Clinical Facility End User Industry: Educational Institutions, Rehabilitation Centers, Pediatric Clinics, Elder Care Facilities, Mental Health Centers |
| Companies Covered | Genesis Rehab Services, Kindred Healthcare, HCR ManorCare, Select Medical, Fox Rehabilitation, Smart Speech Therapy, Therapy Solutions Inc., Reliant Rehabilitation, Humanus Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Speech Therapy Market Strategic Shifts & Innovations
Automation of diagnostic screening and documentation workflows is compressing the labor intensity of service delivery, while regulatory pressure on site-of-service restrictions forces platform investments that smaller practices struggle to fund.
Artificial intelligence-powered speech analysis tools are automating articulation and fluency screening for pediatric clients. School districts in Florida and Texas are piloting these platforms to triage evaluation backlogs. The technology is rendering obsolete the traditional 90-minute initial assessment model that consumed scarce clinician hours.
CMS is tightening prior authorization requirements for repetitive outpatient therapy services through its Medicare Administrative Contractors. This policy shift is redirecting volume toward skilled nursing facility-based provision where bundled payments apply. Post-acute operators in the Sun Belt are restructuring staffing ratios to capture this redirected demand.
Employer-sponsored health plans are carving out speech therapy benefits to specialized managed care vendors with narrow networks. Large self-insured employers in California are consolidating purchasing through third-party administrators that credential only telepractice-enabled providers. This channel consolidation favors platforms with multi-state licensing infrastructure over single-site clinics.
US Speech Therapy Market Segmentation
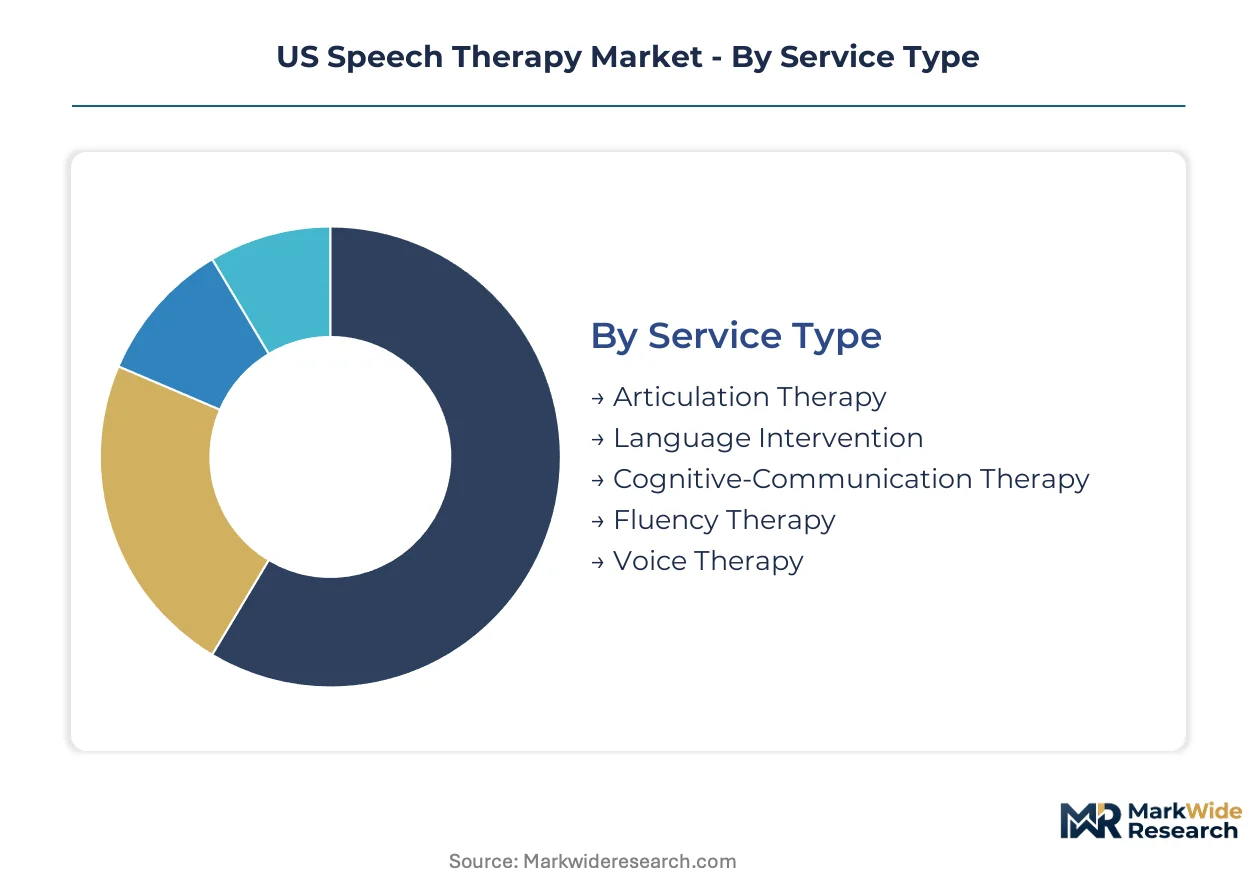
Speech therapy service delivery fragments across multiple axes that determine reimbursement pathways, operational cost structures, and regulatory compliance burdens. Understanding how these dimensions intersect reveals where margin pools concentrate and which provider configurations capture sustainable economics under evolving payer policies.
Service Type:
Cost tier stratification across service types reflects labor intensity, equipment requirements, and payer reimbursement differentials that shape provider portfolio decisions.
- Articulation Therapy:Targets speech sound production disorders through structured drill-based exercises and auditory discrimination training. Demand concentrates in school-based settings across Texas and Florida where IDEA mandates drive caseload volumes, though reimbursement rates lag clinical facility benchmarks.
- Language Intervention:Addresses receptive and expressive language deficits through narrative-based and social communication protocols. Pediatric autism services in California school districts represent the steepest expansion trajectory as mandated staffing ratios outpace ASHA-accredited graduate program output.
- Cognitive-Communication Therapy:Restores executive function, memory, and problem-solving capacities following neurological events.
- Fluency Therapy:Modifies stuttering patterns through behavioral techniques and assistive technology integration.
- Voice Therapy:Treats vocal fold pathology and professional voice optimization; aging broadcasters and attorneys in New York and Los Angeles sustain cash-pay demand with minimal prior authorization friction.
Voice therapy holds installed capacity. Language intervention is rotating up the share rankings.
Client Type:
Application focus across client populations determines session frequency, treatment duration, and the mix of institutional versus commercial payer sources.
- Children:Early intervention recipients aged 0-5 years receiving services through state Part C programs and school district preschool special education. California, Texas, and Florida account for disproportionate volume given birth cohort size and Medicaid early intervention penetration.
- Individuals with Autism Spectrum:Fastest-climbing segment driven by diagnostic expansion and school district hiring mandates that exceed ASHA-certified clinician supply in high-cost metropolitan markets.
- Adults:Working-age clients accessing employer-sponsored benefits or private insurance for acquired communication disorders.
- Geriatric Patients:Medicare beneficiaries requiring dysphagia and aphasia intervention in post-acute settings; CMS prospective payment system updates are narrowing per-session margins below independent practice thresholds.
- Stroke Survivors:Post-acute rehabilitation recipients whose care trajectories are reshaping under bundled episode payment models.
- Traumatic Brain Injury Patients:Complex cases requiring extended interdisciplinary coordination.
Children command the largest addressable population base. Individuals with autism spectrum are gaining share fastest.
Delivery Model:
Volume distribution across delivery modalities reflects site-of-service restrictions, telehealth parity law evolution, and capital requirements for platform infrastructure.
- Telepractice:Virtual delivery through HIPAA-compliant platforms capturing margin pools previously held by clinical facility operators, particularly in rural Appalachian counties and the Texas Panhandle with provider shortages. Texas and Florida parity laws now reimburse at in-person rates.
- In-Person Therapy:Traditional clinical delivery retaining dominance for swallowing disorder assessment requiring Modified Barium Swallow studies and hands-on oral-motor intervention.
- School-Based Therapy:IDEA-mandated services creating institutional demand floors with stable funding but compressed hourly rates.
- Home-Based Therapy:Early intervention and geriatric services delivered in residential settings.
- Group Sessions:Cost-efficient social pragmatics and fluency treatment formats.
- Clinical Facility:Hospital outpatient departments and independent practices with full diagnostic capabilities.
In-person therapy retains the deepest installed base. Telepractice is climbing the fastest.
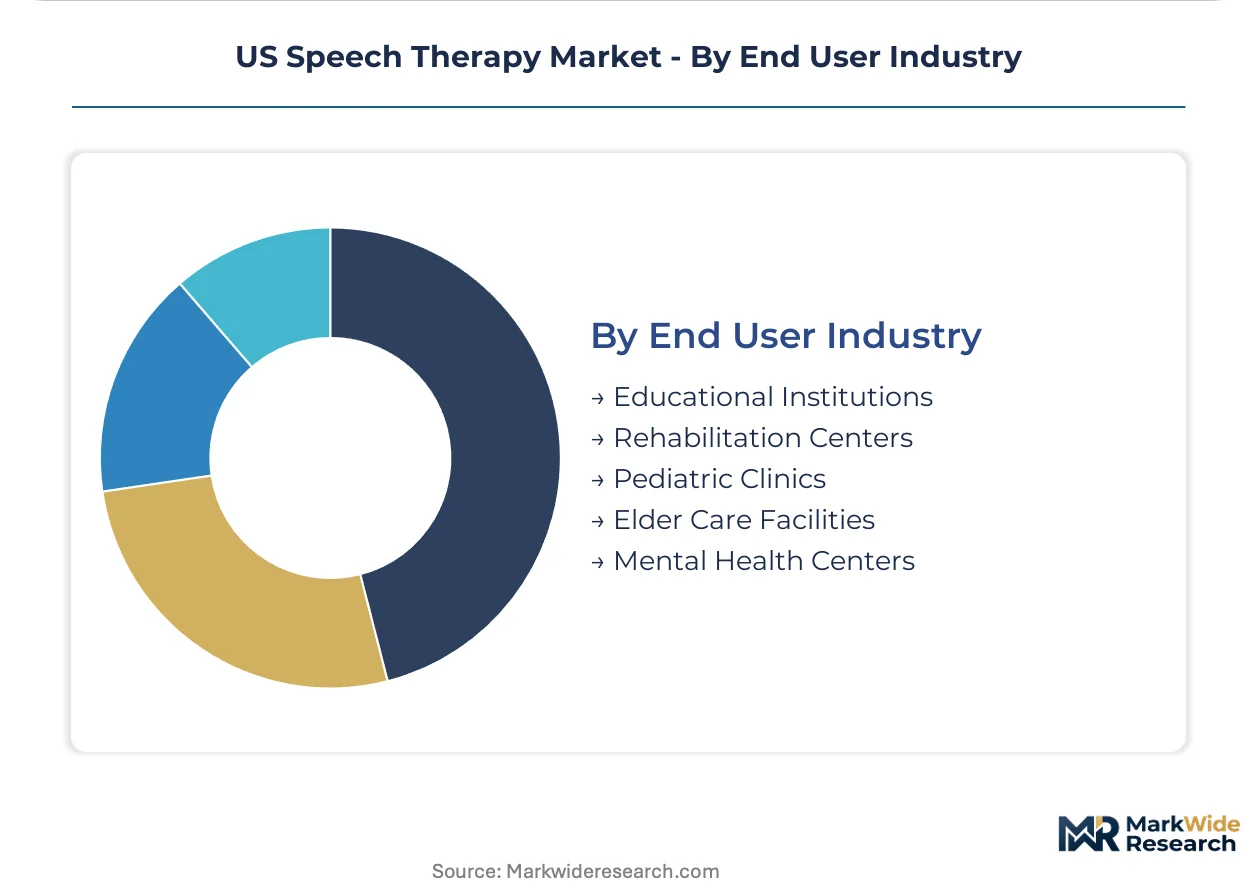
End User Industry:
Customer type concentration determines contract structure, credentialing requirements, and exposure to policy shifts in Medicare reimbursement and Medicaid managed care penetration.
- Educational Institutions:K-12 school districts and early intervention programs representing the largest institutional purchaser category. IDEA mandates create inelastic demand, though staffing ratio requirements in California, Texas, and Florida outpace ASHA-accredited program completion rates.
- Pediatric Clinics:Specialized outpatient facilities expanding autism spectrum service lines; Florida and Texas operators are piloting AI-assisted articulation screening to triage evaluation backlogs.
- Rehabilitation Centers:Post-acute facilities capturing redirected volume as CMS tightens prior authorization for repetitive outpatient services.
- Elder Care Facilities:Skilled nursing and assisted living settings with bundled payment exposure.
- Mental Health Centers:Integrated care sites addressing co-occurring communication and behavioral health conditions.
Educational institutions anchor procurement volume. Pediatric clinics are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across US sub-regions: Medicare-dependent rural markets compress margins relentlessly, while cash-pay professional voice therapy in major metros sustains premium pricing with minimal payer friction.
California
School districts in Los Angeles and San Diego counties face acute staffing shortfalls as IDEA-mandated autism service ratios outpace ASHA-accredited graduate program output. Medi-Cal managed care expansion is tightening prior authorization requirements for outpatient speech-language pathology. The San Francisco Bay Area anchors telepractice platform development, with startups piloting AI-assisted articulation screening for district evaluation backlogs.
Texas
State telehealth parity laws now reimburse telepractice at in-person rates, opening rural Panhandle counties and West Texas to virtual providers. Early intervention programs in Harris and Dallas counties absorb disproportionate pediatric caseloads given birth cohort scale. Federally Qualified Health Centers in Appalachian-adjacent East Texas remain underserved for dysphagia assessment.
Florida
Miami-Dade and Broward school districts rank among the nation's largest employers of speech-language pathologists, driven by diagnostic expansion in autism spectrum services. State Medicaid agency prior authorization requirements for repetitive therapy sessions are redirecting volume toward skilled nursing facilities with bundled payment contracts. Tampa Bay pediatric clinics are piloting automated fluency screening platforms.
New York Metro
Manhattan and Brooklyn sustain mature cash-pay markets for professional voice optimization serving broadcasters, attorneys, and executives. Commercial payer carve-outs to narrow-network managed care vendors are consolidating purchasing power among third-party administrators. Academic medical centers in the Bronx anchor NIH-funded aphasia research with limited commercial scale.
Pacific Northwest
Washington and Oregon school districts operate under state-level staffing mandates less stringent than California's, producing more elastic demand patterns. Medicare Advantage penetration in Seattle and Portland metro areas is accelerating site-of-service restrictions for outpatient therapy. Rural Cascade counties with provider shortages represent untapped telepractice addressable markets.
US Speech Therapy Market Key Industry Players
Capability concentration sits with post-acute specialists commanding bundled episode expertise; scale advantage sits with national outpatient networks achieving density economics. The market structures around three tiers: hospital-anchored acute rehab operators, skilled nursing facility placement specialists, and telepractice-enabled platform players. Consolidation pressure favors operators with multi-state licensing infrastructure and EHR integration capabilities. M&A activity targets regional pediatric clinic chains; strategic partnerships with school district purchasing cooperatives are emerging as defensive positioning moves.
Within the post-acute tier, Genesis Rehab Services, Kindred Healthcare, and Select Medical occupy positions reflecting distinct site-of-service strategies. Genesis Rehab Services exemplifies the skilled nursing facility placement model dominating Sun Belt bundled payment capture. Kindred Healthcare represents hospital-based acute rehab partnership structures with embedded speech-language pathology staffing. Select Medical sits within the outpatient network archetype, competing on session volume density across geographically dispersed centers. These three operators collectively illustrate how reimbursement pathway fragmentation rewards divergent operational configurations rather than unified market leadership.
| Leading Market Players |
|---|
| Genesis Rehab Services |
| Kindred Healthcare |
| HCR ManorCare |
| Select Medical |
| Fox Rehabilitation |
| Smart Speech Therapy |
| Therapy Solutions Inc. |
| Reliant Rehabilitation |
| Humanus Corporation |
| Others |
Cost & Logistics Intelligence
I-35 freight corridors linking Texas pediatric clinics to California technology vendors concentrate logistics costs that amplify price spreads between metropolitan and rural service delivery. These transportation economics reinforce supply concentration among multi-state telepractice platforms while squeezing independent practitioners in Appalachian and Panhandle counties.
Pricing Analysis
Aftermarket service revenue from extended post-acute rehabilitation contracts drives lifetime value for skilled nursing facility operators. Three-tier pricing structure across premium cash-pay voice therapy, standard commercial insurance sessions, and compressed Medicaid school-based rates reflects payer mix differentials. Pricing pressure stems from CMS prospective payment system updates narrowing per-session margins below cost-recovery thresholds for independent practices. School districts exhibit highest price sensitivity due to IDEA-mandated staffing ratios with fixed budget allocations, while Manhattan broadcasters sustain lowest sensitivity with direct-pay professional voice optimization.
Supply Chain Analysis
Contract-manufacturing concentration for HIPAA-compliant telepractice platforms sits with specialized health IT developers in California's Bay Area and Austin's technology corridor. Clinical equipment supply draws from German diagnostic imaging manufacturers and domestic medical device distributors for Modified Barium Swallow systems. Supply chain risk centers on single-source vulnerability for ASHA-accredited graduate program output failing to match district hiring mandates. Distribution runs through hospital system purchasing cooperatives, school district centralized procurement offices, and direct-to-practice platform subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US speech therapy market exhibits cyclical recovery characteristics as Medicare reimbursement recalibrations and state telehealth parity law waves create successive expansion windows. IDEA mandate cycles and CMS payment system updates provide predictable demand pulses.
For Market Incumbents: Build regulatory compliance moats through multi-state licensing infrastructure and EHR integration capabilities. Consolidate regional pediatric clinic chains before telepractice platforms capture rural margin pools. Defend against AI-assisted screening substitution by embedding clinicians into school district evaluation workflows as irreplaceable decision-makers. Prioritize backward integration into ASHA-accredited graduate program partnerships to secure workforce pipeline control. For New Entrants and Emerging Players: Rural Appalachian counties and the Texas Panhandle represent underpenetrated addressable markets where provider shortages exceed telehealth parity law expansion. Target Federally Qualified Health Centers lacking dysphagia assessment capacity through mobile Modified Barium Swallow partnerships. Penetrate Florida school districts piloting AI triage platforms by offering hybrid human-AI service bundles that satisfy mandated staffing ratios. For Investors and Strategic Acquirers: Carve-out targets emerge from hospital system outpatient therapy divisions facing CMS prior authorization compression. Long-term viability favors operators with bundled episode payment expertise in post-acute settings over pure-play telepractice vendors vulnerable to platform commoditization. Monitor state Medicaid managed care penetration rates as inflection signals for reimbursement rate trajectory shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-State Licensing Infrastructure | Texas and Florida parity laws reward operators with pre-built regulatory compliance across jurisdictions. |
| AI-Assisted Documentation Integration | Natural language processing tools reduce clinician administrative burden and expand billable session capacity. |
| School District Purchasing Cooperative Partnerships | California and Florida IDEA mandates create institutional demand floors with stable multi-year contract visibility. |
| Post-Acute Bundled Payment Capability | CMS prior authorization tightening redirects volume toward skilled nursing facilities with episode-based expertise. |
| ASHA-Accredited Workforce Pipeline Investment | Graduate program output constraints in high-cost metropolitan areas threaten service delivery scalability. |
Research Approach
The analysis maps telepractice platforms, post-acute rehabilitation operators, school-based service providers, and pediatric specialty clinics, each validated through speech-language pathologists, district special education directors, hospital procurement managers, and CMS policy specialists. Primary interviews combined with secondary validation from CMS Medicare data, state Medicaid agency prior authorization filings, ASHA workforce supply statistics, and IDEA implementation reports. Bottom-up session volume modeling triangulated against top-down reimbursement flow analysis.
Assumptions held fixed include current IDEA mandate staffing ratios and existing state telehealth parity law coverage; variables included CMS prospective payment system update timing and Medicaid managed care penetration trajectories. Segmentation dimensions modeled encompass service type, client population, delivery modality, and end-user industry across the projection horizon. CAGRs derived from reimbursement rate trend extrapolation, workforce supply-demand gap analysis, and technology adoption curve integration for AI-assisted screening platforms.
Practitioners should monitor CMS Medicare Administrative Contractor prior authorization guidance releases and state telehealth parity law amendment cycles for early signals of reimbursement pathway shifts. Quarterly review of ASHA-accredited graduate program completion rates and district hiring mandate expansion timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Speech Pathology Services Market
Rehabilitation Services
United States Outpatient Rehabilitation Centers Market
Rehabilitation Services
Rehabilitation Therapy Services Market
Rehabilitation Services
Global Women Health Rehabilitation Products Market
Rehabilitation Services
Wearable Neurorehabilitation Devices Market
Rehabilitation Services
VR Stroke Rehabilitation Market
Rehabilitation Services
Physiotherapy Services Market
Rehabilitation Services
Massage Therapy Services Market
Rehabilitation Services
United States Behavioral Rehabilitation Market
Rehabilitation Services
Neurorehabilitation Gaming Systems Market
Rehabilitation Services
US Assisted Living Facility and Neurorehabilitation Market
Rehabilitation Services
Occupational and Physical Therapy Services Market
Rehabilitation Services
Lower Extremity Rehabilitation Robotics Market
Rehabilitation Services
Veterinary Rehabilitation Services Market
Rehabilitation Services
Brachial Plexus Injury Market
Rehabilitation Services
Global Outpatient Rehabilitation Centers Market