
 Optic Atrophy Management Market | 2026-2036
Optic Atrophy Management Market Size, Share, and Industry Trends Forecast 2026-2036
Optic Atrophy Management Market Analytics
Gene therapy vector refinement is narrowing the gap between preclinical promise and reimbursable clinical outcomes for optic atrophy indications. F. Hoffmann-La Roche AG leverages its deep ophthalmology franchise to sustain neuroprotective drug development pipelines. GenSight Biologics anchors its competitive position through mitochondrial-targeted gene therapy platforms. Novartis AG competes via established rare disease infrastructure that extends into ocular gene therapy recruitment networks.
Optic atrophy management encompasses diagnostic, pharmacological, surgical, and rehabilitative interventions aimed at preserving residual visual function and slowing progression of retinal ganglion cell loss in conditions such as Leber hereditary optic neuropathy, glaucoma-related damage, and compressive lesions. The field relies heavily on optical coherence tomography retinal nerve fiber layer thickness measurement as a functional endpoint, alongside electrophysiological assessment and genetic confirmation for hereditary variants. Neuroprotective agents command the deepest existing revenue pool given chronic administration profiles, while gene therapy segments attract the fastest capital allocation as registrational trials advance toward commercialization. Diagnostic imaging sustains the broadest installed base across hospital systems, though wearable devices for home-based visual field monitoring represent the fastest-growing technology adoption curve among ambulatory settings.
The FDA's orphan drug designation program and breakthrough therapy pathway shape trial design incentives and expedited review timelines for novel optic atrophy therapeutics, while the EMA's PRIME eligibility criteria parallel European development strategy. ISO 14155 governs clinical investigation standards that determine multinational trial acceptability, directly affecting regulatory submission efficiency across jurisdictions. Stakeholders must weigh manufacturing scale-up timelines against evolving payer evidence requirements for one-time gene therapies versus chronic pharmacological management.
Market Dynamics
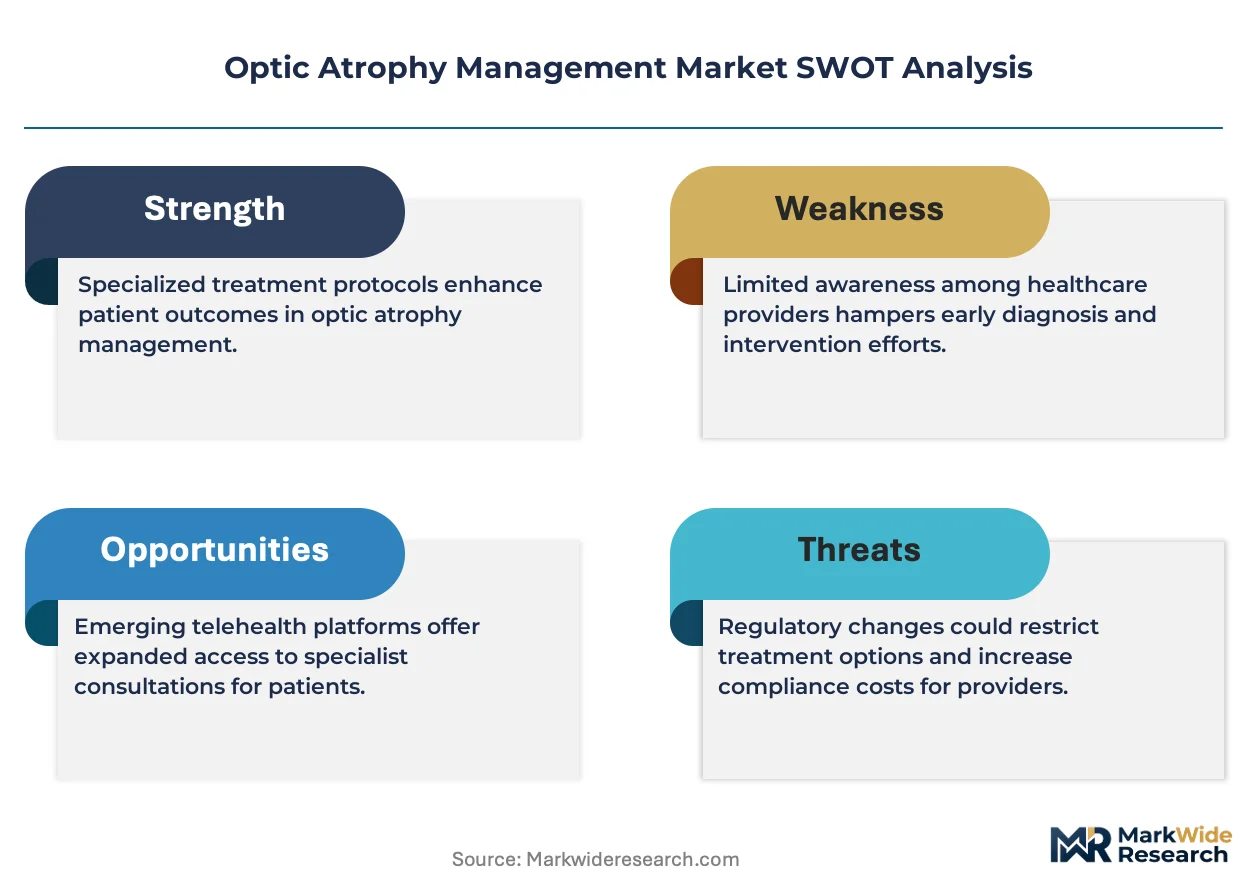
The FDA's orphan drug incentives and EMA's PRIME eligibility are compressing clinical trial timelines for rare optic neuropathies, accelerating capital flows toward gene therapy platforms while hospital neuro-ophthalmology departments consolidate diagnostic-treatment protocols under single-roof specialty centers.
Growth Catalysts
- Orphan drug designation:The FDA's accelerated approval pathway and tax credits for rare disease trials reduce regulatory friction for mitochondrial-targeted therapies in Leber hereditary optic neuropathy.
- Optical coherence tomography:Retinal nerve fiber layer thickness measurement standardization enables objective functional endpoints that satisfy payer evidence requirements for neuroprotective agents.
- Academic medical center networks:United States referral consolidation into specialized institutions concentrates patient access for inherited optic neuropathy screening and enrollment.
Market Restraints
- AAV vector manufacturing scale-up:Viral vector production bottlenecks limit batch yields for adeno-associated virus-based gene therapies, constraining supply of one-time treatments.
- Reimbursement uncertainty:Payer hesitation over single-administration gene therapy pricing versus chronic pharmacological management creates access friction for novel modalities.
- Diagnostic confirmation delays:Genetic testing turnaround times and electrophysiological assessment complexity prolong time-to-treatment initiation for hereditary variants.
Strategic Opportunities
- Home-based visual field monitoring:Wearable device adoption in ambulatory settings extends care beyond hospital-based neuro-ophthalmology departments.
- ISO 14155 harmonization:Multinational clinical investigation standards enable streamlined regulatory submissions across FDA and EMA jurisdictions simultaneously.
- Mitochondrial-targeted platform expansion:Gene therapy vector refinement opens adjacent indications beyond Leber hereditary optic neuropathy into other retinal ganglion cell loss conditions.
Industry Challenges
- Neuro-ophthalmology specialist scarcity:Fellowship-trained clinician availability limits patient throughput at academic medical centers anchoring referral networks.
- Gene therapy manufacturing capex:Commercial-scale viral vector facilities require substantial capital deployment before revenue realization from registrational trial outcomes.
- Retinal nerve fiber layer endpoint validation:Optical coherence tomography measurement standardization across multicenter trials demands rigorous protocol alignment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optic Atrophy Management Market |
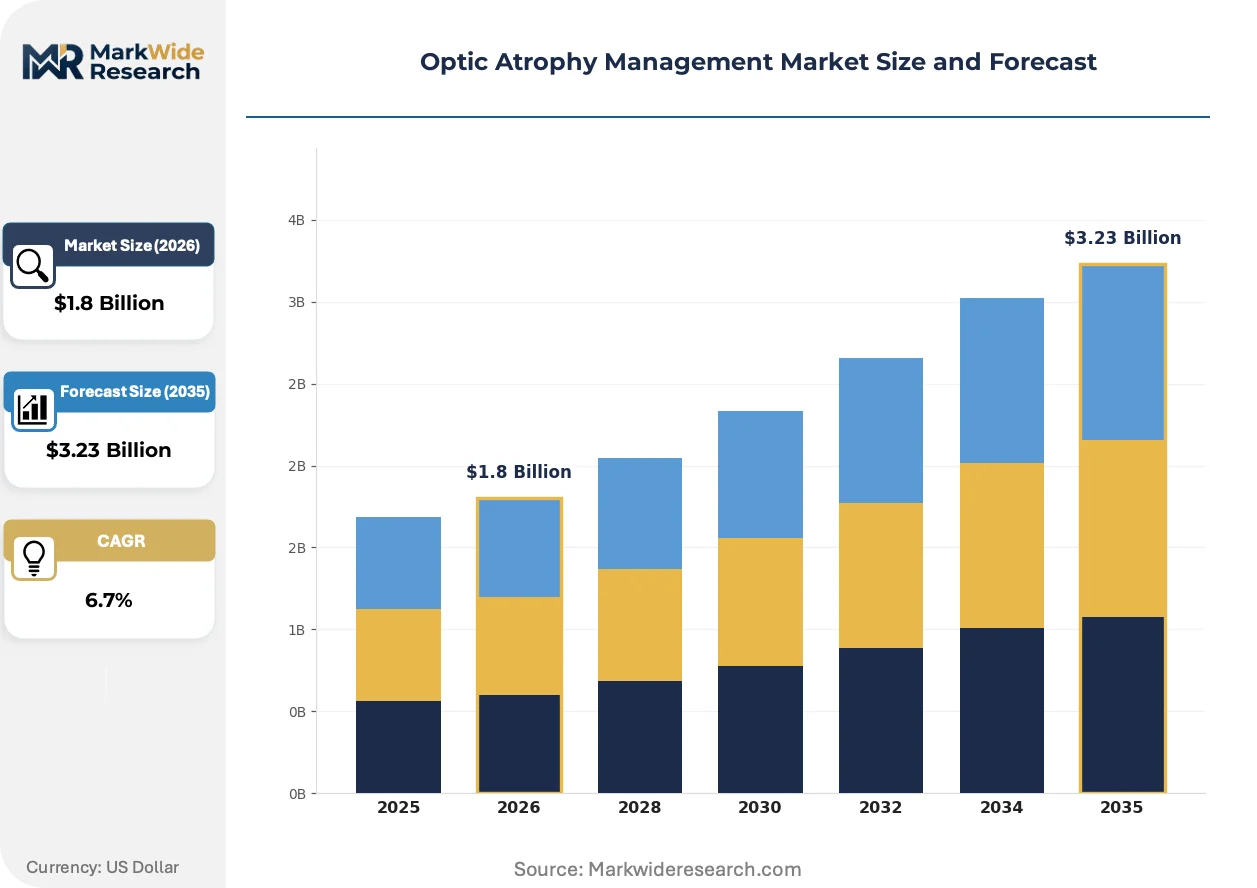
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vision Therapy, Neuroprotective Agents, Surgical Intervention, Genetic Testing End User: Clinics, Hospitals, Rehabilitation Centers, Research Institutions Technology: Telemedicine, Drug Delivery Systems, Diagnostic Imaging, Wearable Devices Delivery Mode: In-person, Online, Home Care, Community Outreach |
| Companies Covered | Pfizer Inc., Novartis AG, AbbVie Inc., F. Hoffmann-La Roche AG, Bausch + Lomb, Santen Pharmaceutical Co., Ltd., Teva Pharmaceutical Industries Ltd., GenSight Biologics, Santhera Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optic Atrophy Management Market Evolving Landscape
Gene therapy delivery mechanisms and diagnostic endpoint technologies are converging to redefine how optic atrophy progression is measured, treated, and reimbursed across hospital and home settings.
Adeno-associated virus vector engineering is virtualizing the therapeutic landscape for inherited optic neuropathies. Roche and GenSight Biologics anchor development pipelines around mitochondrial-targeted delivery systems. Hospital-based neuro-ophthalmology departments are virtualizing patient selection criteria through enhanced genetic screening protocols.
EMA's PRIME eligibility criteria parallel FDA breakthrough therapy pathways, compressing European development timelines for rare retinal disease therapeutics. Manufacturers now design registrational trials to satisfy simultaneous submission requirements across both jurisdictions. Gene therapy segments face the steepest compliance burden as ISO 14155 clinical investigation standards govern multinational acceptability.
Specialty pharmacy distribution is displacing traditional hospital outpatient dispensing for chronic neuroprotective agents. Payer preference for site-of-care optimization drives volume toward ambulatory infusion centers in the United States. Academic medical centers retain gene therapy administration exclusivity due to complex vector handling requirements.
Optic Atrophy Management Market Segmentation
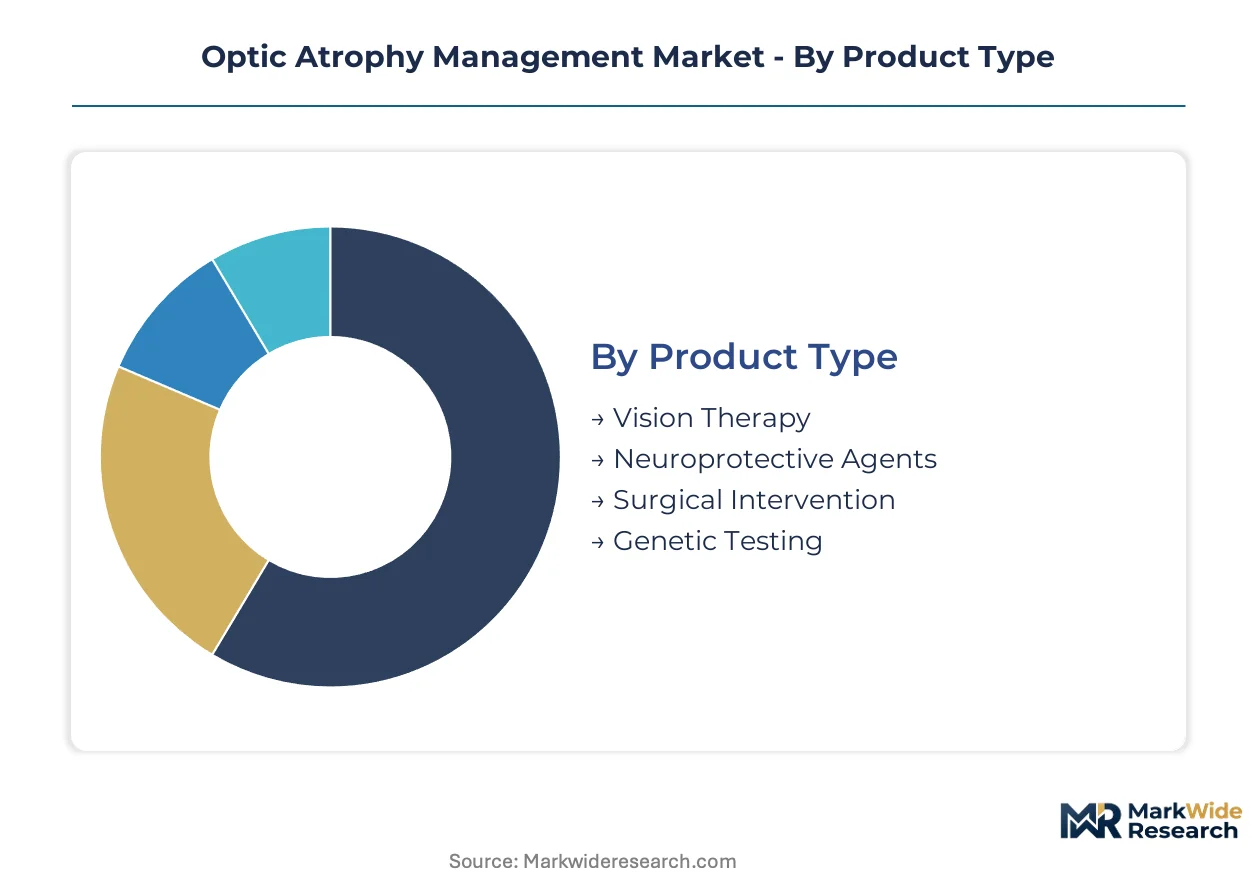
Optic atrophy management spans acute intervention modalities and chronic monitoring platforms with divergent replacement cycles. Segmentation reveals which revenue streams sustain recurring revenue versus one-time therapeutic events.
Product Type:
Cycle times vary dramatically across this category, with chronic administration therapies turning over monthly while surgical interventions operate on multi-year replacement horizons.
- Neuroprotective Agents:Pharmacological compounds administered chronically to slow retinal ganglion cell apoptosis. Demand concentrates in United States academic medical centers where payer coverage for chronic administration remains most favorable. Monthly prescription refills generate predictable recurring revenue streams that attract sustained pharmaceutical investment.
- Genetic Testing:Molecular diagnostic protocols confirming hereditary optic neuropathy variants including LHON mutations. Adoption accelerates in specialized neuro-ophthalmology departments seeking to stratify patients for gene therapy eligibility. Rapid test turnaround requirements compress operational cycles toward same-day result delivery.
- Vision Therapy:Structured rehabilitative programs targeting residual visual function preservation.
- Surgical Intervention:Decompressive and optic nerve sheath fenestration procedures for compressive etiologies.
Neuroprotective agents anchor the volume base while genetic testing gains share at the steepest rate.
End User:
Patient acuity and reimbursement sophistication determine facility-level purchasing authority across this category.
- Hospitals:Tertiary care institutions housing integrated neuro-ophthalmology departments with surgical capabilities and gene therapy administration infrastructure. United States academic medical centers concentrate inherited optic neuropathy referral networks and clinical trial enrollment. Complex vector handling requirements and infusion monitoring sustain hospital exclusivity for advanced therapeutics.
- Clinics:Outpatient facilities delivering diagnostic workup and chronic disease management. Community-based ophthalmology practices in suburban United States markets handle stable patient monitoring and medication management. Lower capital requirements enable geographic expansion into underserved regions.
- Rehabilitation Centers:Post-acute facilities specializing in adaptive training for vision loss.
- Research Institutions:Academic centers conducting registrational trials and biomarker development.
Hospitals capture the highest revenue per patient encounter while clinics expand most quickly into ambulatory market penetration.
Technology:
Capital intensity and regulatory burden separate installed-base technologies from emerging adoption curves in this category.
- Diagnostic Imaging:Optical coherence tomography systems measuring retinal nerve fiber layer thickness as a functional endpoint. Hospital neuro-ophthalmology departments in the United States, Germany, and Japan maintain the densest installed base. Standardization across multicenter trials drives equipment procurement decisions.
- Wearable Devices:Home-based visual field monitoring systems extending care beyond clinical settings. Ambulatory adoption concentrates in United States markets with favorable remote monitoring reimbursement. Patient preference for reduced visit frequency accelerates penetration.
- Telemedicine:Virtual consultation platforms connecting specialists with geographically dispersed patients.
- Drug Delivery Systems:Sustained-release implants and intravitreal injection platforms.
Diagnostic imaging sustains the broadest installed base while wearable devices climb the fastest toward commercial scale.
Delivery Mode:
Site-of-care economics and vector handling requirements partition patient touchpoints across this category.
- In-person:Traditional clinical encounters encompassing examination, procedure, and infusion administration. Academic medical centers in the United States retain exclusivity for gene therapy delivery due to complex cold-chain and biosafety requirements. Reimbursement rates favor hospital-based administration for high-acuity interventions.
- Home Care:Domestic administration of chronic therapies and monitoring protocols. United States specialty pharmacy networks disperse neuroprotective agents directly to patients. Payer site-of-care optimization initiatives redirect volume from hospital outpatient departments.
- Online:Digital platforms for consultation, education, and remote monitoring.
- Community Outreach:Screening programs targeting hereditary optic neuropathy detection in underserved populations.
In-person delivery commands premium reimbursement while home care expands most rapidly through specialty pharmacy channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German gene therapy exports flow into United States academic medical centers, anchoring transatlantic supply corridors for mitochondrial-targeted interventions. Japan and Switzerland concentrate precision diagnostic manufacturing, feeding hospital neuro-ophthalmology departments worldwide.
United States
Academic medical centers in Boston, Baltimore, and San Francisco anchor inherited optic neuropathy referral networks. FDA orphan drug designation and breakthrough therapy pathways compress trial timelines for Leber hereditary optic neuropathy candidates. Massachusetts General Hospital and Johns Hopkins scale integrated diagnostic-treatment protocols under single-roof specialty centers.
Germany
University hospitals in Munich and Heidelberg drive adoption of optical coherence tomography standardization for multicenter trials. EMA PRIME eligibility parallels FDA pathways, accelerating European development timelines. The Heidelberg University Eye Hospital concentrates electrophysiological assessment expertise for hereditary variant confirmation.
Switzerland
Roche's Basel headquarters sustains neuroprotective drug development pipelines targeting retinal ganglion cell preservation. Swissmedic harmonizes with EMA standards, streamlining regulatory submissions for rare disease therapeutics. The Basel-Zurich corridor anchors ophthalmology franchise manufacturing and clinical trial coordination.
Japan
PMDA sakigake designation accelerates regenerative medicine approvals for optic nerve interventions. METI funding targets mitochondrial disease research clusters in Kansai and Kanto regions. Osaka University Hospital leads electrophysiological biomarker development for Asian patient populations.
United Kingdom
Moorfields Eye Hospital in London anchors NHS specialized commissioning for rare optic neuropathies. MHRA alignment with FDA-EMA trial standards enables simultaneous submission strategies. The London-Oxford-Cambridge triangle concentrates genetic testing capacity and gene therapy patient recruitment.
Optic Atrophy Management Market Competitive Landscape
Channel-controlling players compete with product-specialist players across gene therapy, neuroprotective agents, and diagnostic platforms. The market structure consolidates around multinational pharmaceutical conglomerates with rare disease infrastructure, while biotechnology specialists occupy vector engineering and mitochondrial-targeted delivery niches. Three archetypes dominate: diversified pharma giants with ophthalmology franchises, gene therapy platform companies, and diagnostic imaging equipment manufacturers. Competitive moves center on strategic partnerships for AAV manufacturing scale-up and portfolio diversification into home-based monitoring technologies.
Among Swiss-based diversified pharmaceutical conglomerates, F. Hoffmann-La Roche AG exemplifies the integrated ophthalmology franchise archetype. French gene therapy specialists occupy the mitochondrial-targeted platform tier, with GenSight Biologics representing vector refinement capabilities. Novartis AG anchors the rare disease infrastructure archetype, leveraging established recruitment networks into ocular gene therapy development. These three entities collectively illustrate how geographic clustering around Basel and Paris shapes competitive positioning in registrational trial advancement.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| AbbVie Inc. |
| F. Hoffmann-La Roche AG |
| Bausch + Lomb |
| Santen Pharmaceutical Co., Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| GenSight Biologics |
| Santhera Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
The Basel-Zurich corridor's viral vector manufacturing capacity constrains batch yields for adeno-associated virus-based gene therapies, concentrating pricing power among facilities capable of commercial-scale production while forcing chronic neuroprotective agents toward commodity-like margins through specialty pharmacy channel displacement.
Pricing Analysis
Next-generation mitochondrial-targeted gene therapies command substantial premiums over first-generation neuroprotective agents and diagnostic imaging platforms. Pricing stratifies across premium, standard, and economy tiers based on therapeutic modality complexity and FDA orphan drug exclusivity status. Cost compression in chronic pharmacological management intensifies as United States specialty pharmacy networks displace hospital outpatient dispensing. Academic medical centers exhibit lowest price sensitivity due to complex vector handling requirements and infusion monitoring protocols, while community ophthalmology clinics face highest sensitivity to reimbursement rate fluctuations.
Supply Chain Analysis
Tariff exposure between Switzerland and the United States dominates supply chain risk planning for gene therapy vector shipments requiring cold-chain integrity. Manufacturing concentrates in Switzerland, Germany, and the United States for AAV production, while Japan and South Korea anchor precision diagnostic component fabrication. Raw material dependencies center on plasmid DNA, cell culture media, and specialized resins for chromatography purification. Single-source vulnerability persists for high-titer viral vector production lines. Distribution runs through hospital-based specialty pharmacy channels for gene therapies and ambulatory infusion networks for chronic agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment, where FDA orphan drug designation and EMA PRIME eligibility create multi-year exclusivity windows that compound switching costs for treating physicians and hospital systems.
For Market Incumbents: Harden manufacturing scale-up commitments in Basel and Boston corridors to preempt AAV vector batch yield constraints that threaten supply security. Deepen backward integration into plasmid DNA production to reduce dependency on third-party suppliers facing capacity bottlenecks. Fortify hospital system partnerships through integrated diagnostic-treatment protocol co-development that embeds optical coherence tomography standardization into clinical workflow.
For New Entrants and Emerging Players: Pursue home-based visual field monitoring as the most penetrable white-space segment, where wearable device reimbursement codes remain underdeveloped and patient preference for reduced visit frequency creates adoption tailwinds. Target community ophthalmology clinics in suburban United States markets underserved by academic medical center referral networks. Lead with telemedicine-enabled remote monitoring platforms that extend specialist reach without requiring physical infrastructure investment.
For Investors and Strategic Acquirers: Long-term, this sits as a platform-extension play because mitochondrial-targeted delivery systems validated in Leber hereditary optic neuropathy open adjacent retinal ganglion cell loss indications with minimal incremental R&D. Acquisition candidates should demonstrate registrational trial enrollment velocity and established relationships with United States academic medical centers. The signal to watch is FDA breakthrough therapy designation frequency for novel vector serotypes, indicating regulatory pathway de-risking.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | AAV vector batch yield expansion in Basel-Zurich corridor secures supply for registrational trials. |
| Regulatory Approval Pathway | FDA orphan drug designation compresses timelines for mitochondrial-targeted therapies in LHON. |
| Hospital System Partnership | Academic medical center alliances concentrate patient access for inherited optic neuropathy screening. |
| Pipeline Diversification | Mitochondrial platform extension into glaucoma-related retinal ganglion cell loss broadens addressable population. |
| Reimbursement Strategy | Optical coherence tomography endpoint standardization satisfies payer evidence requirements for neuroprotective agents. |
Research Methodology
Desk research of FDA orphan drug designation filings, EMA PRIME eligibility decisions, ClinicalTrials.gov registrational protocols, and hospital procurement databases preceded structured interviews with neuro-ophthalmology department heads, gene therapy manufacturing executives, payer formulary directors, and specialty pharmacy distribution managers. Secondary validation drew from ISO 14155 clinical investigation standards documentation, SEC pharmaceutical segment disclosures, and academic medical center annual reports. Bottom-up patient volume modeling and top-down therapeutic category sizing were triangulated against manufacturer capacity announcements.
Assumptions held fixed include current FDA and EMA regulatory pathway structures, existing reimbursement codes for optical coherence tomography procedures, and United States academic medical center referral network configurations. Variables modeled across the analysis window encompass gene therapy manufacturing scale-up timelines, payer acceptance curves for single-administration versus chronic pricing models, and wearable device penetration rates in ambulatory settings. Segmentation dimensions included therapeutic modality, end-user facility type, technology platform, and delivery mode. CAGRs were derived from patient population epidemiology, treatment penetration curves, and pricing trajectory assumptions for novel modalities.
Sensitivities concentrate around AAV vector manufacturing yield improvements, FDA accelerated approval pathway modifications for rare retinal diseases, and Medicare reimbursement rate determinations for home-based monitoring technologies. Forecasts reflect assumptions about regulatory incentive continuity and payer evidence requirement evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market
Specialty Medicine
Lipoprotein Metabolism Disorders Treatment Market
Specialty Medicine
Global Fuchs Endothelial Corneal Dystrophy (FECD) Market
Specialty Medicine
Middle East and Africa Primary Angle-Closure Glaucoma Market
Specialty Medicine
Coagulation Disorders Market
Specialty Medicine
Ankylosing Spondylitis Market
Specialty Medicine
Vitiligo Treatment Market
Specialty Medicine
Polyarticular Juvenile Idiopathic Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
Global Retinal Biologics Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Transthyretin (TTR) Amyloidosis Market
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
Gouty Arthritis Market