
 Brazil Medical Devices Market | 2026-2036
Brazil Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Medical Devices Market Analysis
Polymer-based biocompatible materials is decoupling device economics from traditional stainless-steel dependency across Brazil's implantable and surgical portfolio. Medtronic leverages its vertically integrated polymer compounding capabilities to sustain margin structures on cardiac rhythm devices. Siemens Healthineers AG anchors its installed base through localized imaging service contracts that compete on uptime guarantees rather than hardware pricing alone.
Brazil medical devices encompass instruments, apparatus, and software intended for diagnosis, prevention, monitoring, or treatment of disease, typically requiring ISO 13485-certified quality management systems and biocompatibility testing under ISO 10993 protocols to ensure patient safety. Diagnostic Equipment leads product-type revenue pools due to chronic disease screening mandates, while Wearable Devices within the technology dimension captures the fastest structural expansion as remote patient monitoring penetrates homecare settings. Orthopedic Devices maintains mature, replacement-driven demand tied to Brazil's aging demographic profile and sports medicine volume.
ANVISA governs pre-market registration, post-market surveillance, and Good Manufacturing Practice certification, effectively filtering market access for imported and domestically produced devices. The Brazilian Health Regulatory Agency's alignment with Mercosur harmonization standards, supplemented by INMETRO metrology requirements for active devices, shapes product development timelines and localization strategies. Stakeholders must monitor pending ANVISA administrative simplification measures and their interaction with local content incentives under the PLI scheme analog to determine manufacturing footprint decisions.
Market Dynamics
ANVISA's updated Good Manufacturing Practice requirements are forcing domestic manufacturers to accelerate compliance investments while imported devices face extended registration timelines, reshaping competitive positioning between local production and foreign supply.
Growth Catalysts
- Chronic disease screening mandates:Diagnostic equipment procurement expands as public health programs prioritize early detection of cardiovascular and metabolic conditions. Municipal hospital networks in São Paulo state drive volume concentration.
- ISO 13485 certification expansion:Quality management standardization enables domestic manufacturers to access Mercosur harmonization pathways. Certification reduces technical barriers for cross-border trade within the trading bloc.
- Polymer compounding capabilities:Advanced biocompatible materials reduce device weight and improve patient tolerance. Cardiac rhythm and orthopedic implant segments capture material science benefits.
Market Restraints
- INMETRO metrology requirements:Active medical devices face mandatory calibration and testing protocols that extend product development timelines. Certification costs disproportionately burden small and mid-sized domestic manufacturers.
- Import dependency for imaging components:Detector arrays and high-voltage power supplies concentrate among German and Japanese suppliers. Currency volatility amplifies landed cost unpredictability.
- Biocompatibility testing capacity:ISO 10993 protocol execution requires specialized laboratory infrastructure concentrated in São Paulo and Rio de Janeiro. Regional manufacturers face sample logistics bottlenecks.
Strategic Opportunities
- Remote patient monitoring penetration:Wearable devices capture structural expansion as homecare settings absorb post-acute monitoring functions. Private insurance reimbursement frameworks are adapting to ambulatory data collection.
- PLI scheme analog localization:Production-linked incentive structures under consideration would reward domestic manufacturing with tax and credit benefits. Multinational strategists are evaluating greenfield versus partnership models.
- Sports medicine volume growth:Orthopedic device demand accelerates in southeastern metropolitan corridors where recreational athletic participation expands. Arthroscopic and reconstructive procedures drive replacement cycle compression.
Industry Challenges
- Biomedical engineering talent scarcity:Regulatory affairs and clinical evaluation specialists concentrate in São Paulo state. Interior manufacturing zones face recruitment friction for ISO 13485 implementation roles.
- Legacy imaging system integration:Public hospital infrastructure modernization requires interoperability with decade-old hardware. Procurement specifications struggle to balance backward compatibility against performance thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Medical Devices Market |
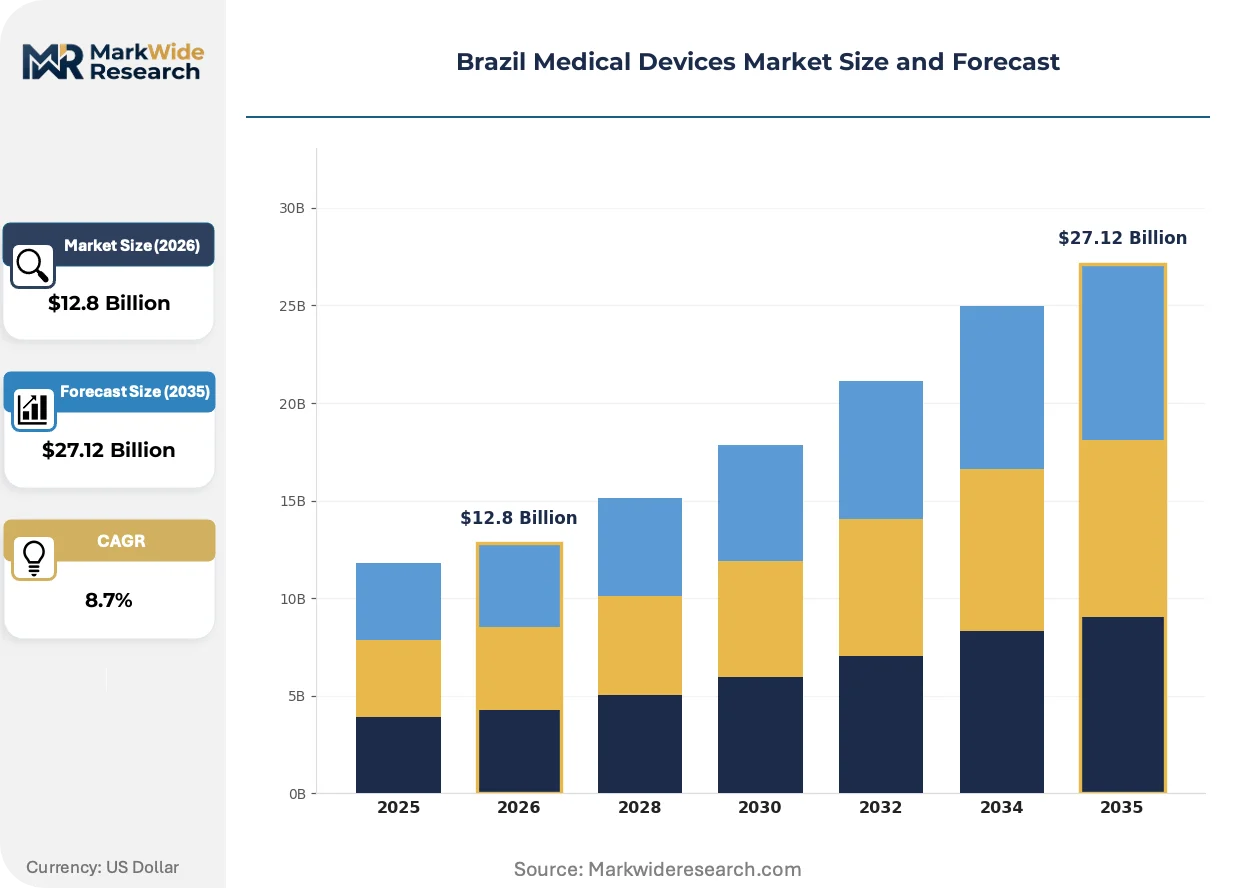
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Equipment, Surgical Instruments, Patient Monitoring Devices, Orthopedic Devices End User: Hospitals, Clinics, Laboratories, Homecare Technology: Wearable Devices, Imaging Systems, Electrosurgical Equipment, In-vitro Diagnostics Application: Cardiology, Orthopedics, Neurology, Respiratory Care |
| Companies Covered | Cardinal Health, Koninklijke Philips N.V., Medtronic, BD, Siemens Healthineers AG, Johnson & Johnson Services, Inc., Abbott, Boston Scientific Corporation, GE Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Medical Devices Market Emerging Trajectories
Digital health infrastructure and materials science are converging to reshape device economics, with regulatory harmonization and procurement model evolution determining competitive access across Brazil's fragmented healthcare delivery landscape.
Artificial intelligence-enabled diagnostic algorithms are integrating into imaging workflows to compress radiologist review timelines and standardize anomaly detection. Private hospital chains in São Paulo's metropolitan corridor deploy these tools fastest, prioritizing throughput in high-volume screening programs. The technology is integrating clinical decision support into hardware procurement specifications, shifting vendor selection criteria from resolution metrics to algorithmic accuracy benchmarks.
ANVISA's administrative simplification measures under consultation aim to streamline pre-market registration for devices with prior FDA or EMA approval. The regulatory convergence reduces redundant clinical evidence requirements for multinational manufacturers. Diagnostic equipment and implantable device categories stand to benefit most, with domestic distributors accelerating parallel filing strategies to capture first-mover positioning.
Service unbundling from hardware sales is restructuring imaging system commercial relationships. Municipal procurement offices increasingly separate equipment acquisition from multi-year maintenance contracts, enabling third-party technical service competition. This shift concentrates in southeastern state hospital networks where budget autonomy allows contract fragmentation, pressuring original equipment manufacturers to defend recurring revenue through uptime guarantee differentiation rather than captive service lock-in.
Brazil Medical Devices Market Segmentation
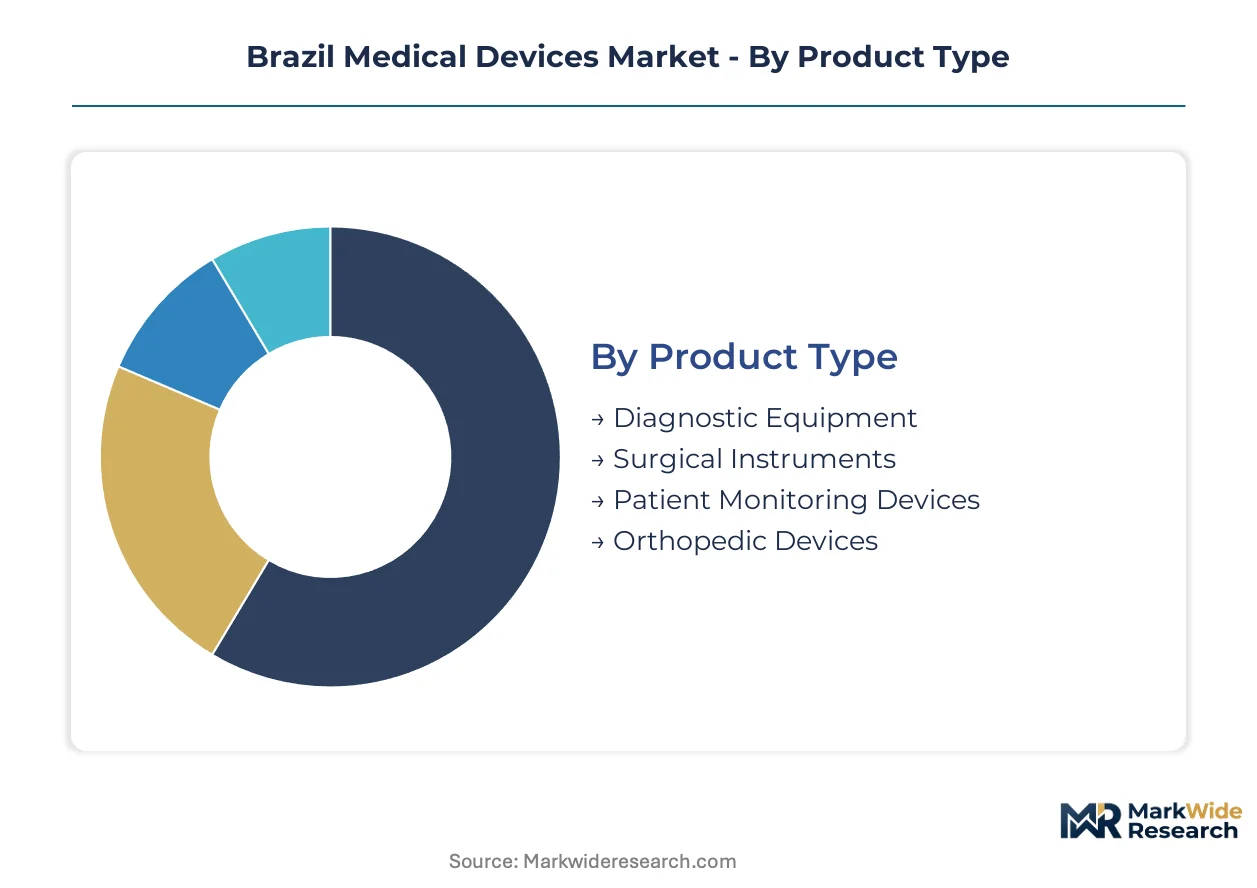
Segmentation in Brazil's medical devices market reveals how capital deployment, regulatory pathways, and procurement concentration diverge across product categories. Understanding these fault lines enables manufacturers to align certification investments with addressable revenue pools.
Product Type:
Capital intensity varies sharply across this dimension, with imaging modalities requiring manufacturing infrastructure that domestic players struggle to replicate.
- Diagnostic Equipment:Modalities span MRI, CT, ultrasound, and molecular diagnostics platforms. São Paulo's metropolitan hospital networks concentrate procurement volume as municipalities execute chronic disease screening mandates. ANVISA registration timelines for imported systems extend lead times, favoring established vendors with regulatory affairs capacity.
- Surgical Instruments:Reusable and single-use instrumentation spans open and minimally invasive procedures. Domestic manufacturers in Minas Gerais and São Paulo states capture mid-tier demand through ISO 13485-certified production, though high-precision laparoscopic tools remain import-dependent.
- Patient Monitoring Devices:Bedside and transportable systems track vital signs in acute care settings. Private hospital chains in southeastern Brazil drive replacement cycles.
- Orthopedic Devices:Joint reconstruction, trauma fixation, and spine systems address Brazil's aging demographic profile. Sports medicine volume accelerates in metropolitan corridors.
Diagnostic Equipment absorbs the bulk of installed capacity; Orthopedic Devices is expanding most quickly.
End User:
Procurement authority and reimbursement frameworks segment this category, with public tender processes diverging sharply from private purchasing autonomy.
- Hospitals:Tertiary and secondary facilities command the largest device procurement budgets. Public hospital networks in São Paulo, Rio de Janeiro, and Minas Gerais states modernize imaging infrastructure through municipal financing mechanisms. Private chains negotiate directly with multinational vendors, bypassing tender complexity.
- Clinics:Ambulatory surgical and specialty diagnostic centers concentrate in southeastern metropolitan areas. Outpatient procedure volume growth drives demand for compact, mobile-capable equipment.
- Laboratories:Clinical pathology and reference labs require high-throughput in-vitro diagnostic platforms. Centralized testing networks in state capitals concentrate purchasing power.
- Homecare:Post-acute and chronic disease management settings absorb wearable and portable monitoring devices. Private insurance reimbursement for remote patient monitoring is adapting to ambulatory data collection models.
Hospitals command the dominant share of capital equipment deployment; Homecare is gaining share fastest as care settings fragment.
Technology:
Intellectual property intensity and software integration requirements differentiate competitive positioning across this dimension.
- Wearable Devices:Continuous glucose monitors, cardiac event recorders, and pulse oximetry systems enable remote patient monitoring. Homecare penetration in São Paulo's private insurance corridors drives structural expansion as reimbursement frameworks adapt.
- Imaging Systems:Radiography, fluoroscopy, CT, MRI, and ultrasound platforms anchor diagnostic workflows. Service unbundling from hardware sales is restructuring municipal procurement in southeastern state networks.
- Electrosurgical Equipment:Radiofrequency and ultrasonic cutting and coagulation systems support minimally invasive procedures. Adoption tracks surgical volume in metropolitan private hospitals.
- In-vitro Diagnostics:Immunoassay, molecular, and clinical chemistry platforms serve laboratory and point-of-care settings. Reagent rental business models dominate high-throughput installations.
Imaging Systems retain the largest installed base; Wearable Devices shows the steepest expansion trajectory.
Application:
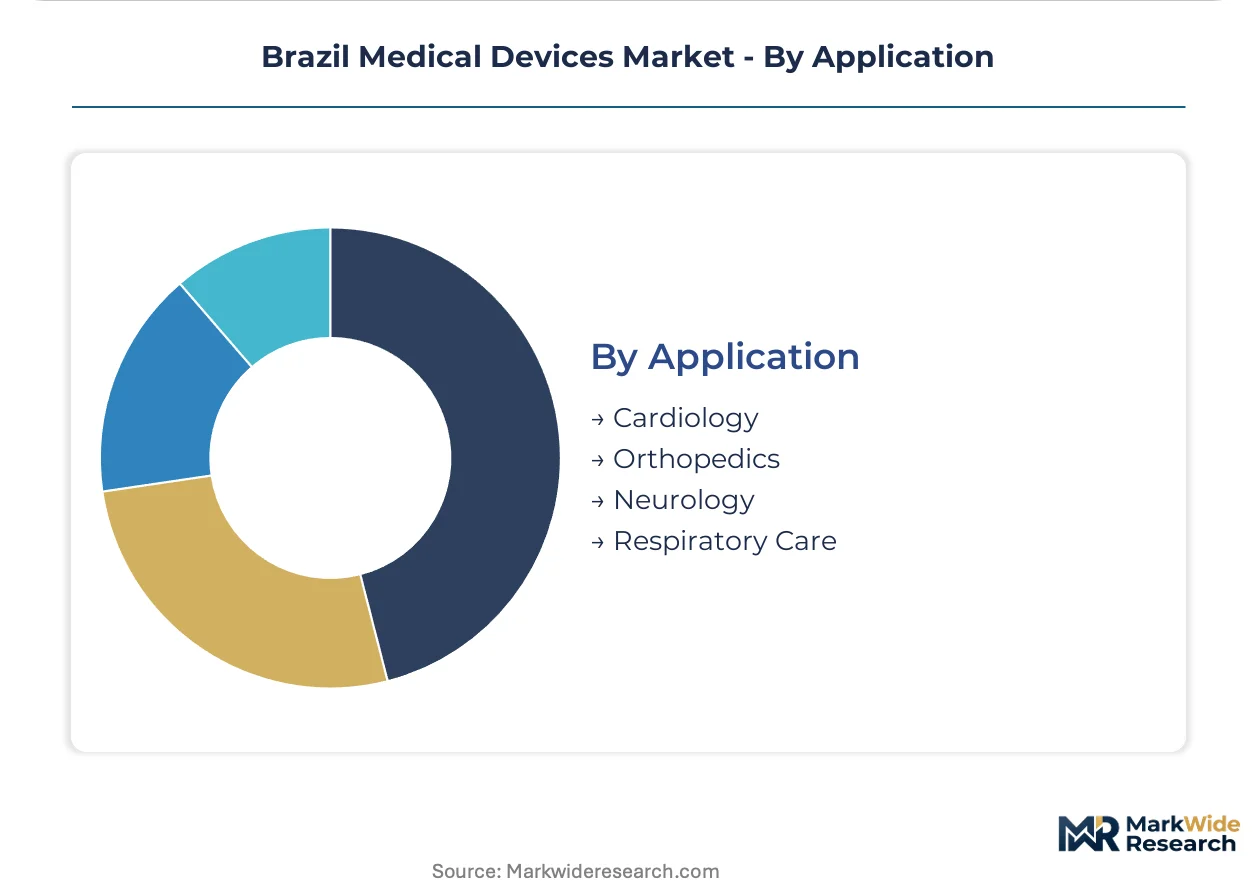
Disease burden demographics and procedure reimbursement rates determine addressable market size across clinical specialties.
- Cardiology:Interventional cardiology, electrophysiology, and cardiac rhythm management devices address Brazil's cardiovascular disease prevalence. Medtronic's vertically integrated polymer compounding supports margin structures on implantable pulse generators.
- Orthopedics:Joint replacement, trauma, and sports medicine procedures concentrate in southeastern metropolitan corridors. Arthroscopic technique diffusion compresses replacement cycles.
- Neurology:Neurostimulation, cerebrospinal fluid management, and neurosurgical navigation systems serve specialized centers. Concentrated demand in São Paulo and Rio de Janeiro academic medical centers.
- Respiratory Care:Ventilation, oxygen therapy, and sleep apnea devices address chronic obstructive pulmonary disease and post-acute needs. Homecare penetration accelerated following pandemic-era infrastructure investment.
Cardiology captures the greatest share of high-value implantable device revenue; Orthopedics is climbing the fastest on sports medicine and aging demographic tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's medical device demand concentrates in southeastern metropolitan corridors, where chronic disease screening mandates and private hospital chain expansion drive procurement volume. State-level health infrastructure investments and ANVISA regulatory harmonization shape regional competitive access.
São Paulo
São Paulo state's metropolitan corridor anchors diagnostic equipment procurement as municipalities modernize public hospital imaging infrastructure. ANVISA's administrative simplification measures for prior FDA-approved devices accelerate registration timelines for multinational vendors. The São Paulo city cluster concentrates biomedical engineering talent and ISO 10993 testing capacity, supporting domestic manufacturer compliance investments.
Minas Gerais
Minas Gerais hosts surgical instrument manufacturing clusters where ISO 13485-certified domestic producers capture mid-tier hospital demand. State industrial policy supports medical device production localization through tax incentive frameworks. Belo Horizonte's academic medical centers drive orthopedic and cardiovascular device evaluation protocols.
Rio de Janeiro
Rio de Janeiro's research institutions and private hospital networks concentrate neurostimulation and specialized diagnostic demand. Post-market surveillance infrastructure under ANVISA jurisdiction supports clinical evaluation specialist recruitment. The metropolitan area faces biomedical engineering talent scarcity relative to procurement growth rates.
Rio Grande do Sul
Rio Grande do Sul's manufacturing base supplies electrosurgical and patient monitoring components to southeastern distribution networks. State-level health secretariats execute chronic disease screening programs that expand diagnostic equipment deployment. Porto Alegre's private insurance corridors pilot remote patient monitoring reimbursement frameworks.
Paraná
Paraná's industrial parks attract polymer compounding investments for implantable device material sourcing. State hospital networks participate in federal chronic disease prevention programs that standardize diagnostic procurement specifications. Curitiba's medical technology distributors serve as logistics hubs for Mercosur cross-border trade.
Brazil Medical Devices Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational OEMs dominating imaging and implantable categories while domestic fabricators capture surgical instrument mid-tiers. Market structure reflects ANVISA registration capacity advantages for established foreign suppliers against local producers' cost positioning. Three archetypes prevail: vertically integrated polymer specialists, imaging service-anchored system vendors, and ISO-certified domestic instrument manufacturers. Competitive dynamics center on regulatory affairs scale and multi-year maintenance contract capture.
Among North American-domiciled healthcare conglomerates, Medtronic and Boston Scientific Corporation exemplify polymer-integrated cardiac and orthopedic implant positioning. Siemens Healthineers AG anchors the European imaging vendor archetype through localized service contract structures. These three entities occupy positions that reflect divergent responses to ANVISA compliance timelines and municipal procurement fragmentation.
| Leading Market Players |
|---|
| Cardinal Health |
| Koninklijke Philips N.V. |
| Medtronic |
| BD |
| Siemens Healthineers AG |
| Johnson & Johnson Services, Inc. |
| Abbott |
| Boston Scientific Corporation |
| GE Healthcare |
| Others |
Supply Flow & Price Mechanics
ISO 13485 certification bifurcation splits Brazil's medical devices landscape into premium-import and economy-domestic tiers, with ANVISA registration timelines and INMETRO metrology requirements amplifying price spreads while concentrating supply chain control among established multinational vendors.
Pricing Analysis
Volume-margins diverge sharply across Brazil's medical devices tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ANVISA registration status and ISO 10993 biocompatibility testing completion. Pricing pressure stems from municipal procurement offices unbundling service contracts from hardware sales, forcing original equipment manufacturers to compete on uptime guarantees rather than captive maintenance lock-in. Public hospital networks exhibit acute price sensitivity, while private hospital chains in São Paulo's metropolitan corridor prioritize algorithmic accuracy benchmarks over unit cost.
Supply Chain Analysis
Pending PLI scheme analog localization requirements are reshaping sourcing strategies for active device components. Detector arrays and high-voltage power supplies draw from Germany and Japan, while polymer compounding feedstocks rest on specialized suppliers in the United States and Europe. Single-source vulnerability concentrates in imaging system electronics, where currency volatility amplifies landed cost unpredictability. Distribution runs through São Paulo-based medical technology distributors serving as logistics hubs for Mercosur cross-border trade.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's updated Good Manufacturing Practice certification functions as a cost-of-compliance moat, filtering market access and rewarding players with regulatory affairs scale while domestic manufacturers face extended timelines and disproportionate certification burdens.
For Market Incumbents: Deploy multi-year maintenance contract capture as the anchor lever. Siemens Healthineers AG and comparable imaging vendors should deepen service unbundling defenses through uptime guarantee differentiation. Biomedical engineering talent scarcity in interior manufacturing zones threatens ISO 13485 implementation capacity; incumbents should secure São Paulo-based regulatory specialists through retention premiums and clinical evaluation specialist pipelines. For New Entrants and Emerging Players: Distributors with established ANVISA registration pathways offer the fastest market access channel. Homecare wearable devices present the most penetrable white-space target, as private insurance reimbursement frameworks adapt to ambulatory data collection models. Sports medicine volume in southeastern metropolitan corridors provides a secondary entry vector, with arthroscopic and reconstructive procedure growth compressing replacement cycles. Partner with São Paulo state GPO contracts managers to bypass tender complexity. For Investors and Strategic Acquirers: Re-rating potential sits with ISO 13485-certified domestic surgical instrument manufacturers given Mercosur harmonization pathway expansion. Long-term viability frames around production-linked incentive structures under legislative consideration, which would reward domestic manufacturing with tax and credit benefits. Watch ANVISA administrative simplification measures for prior FDA-approved devices as the inflection signal—their implementation would accelerate registration timelines and compress first-mover windows.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Pathway Optimization | Parallel filing strategies for prior FDA-approved devices capture first-mover positioning in diagnostic equipment categories. |
| Hospital System Partnership | Direct negotiations with São Paulo private chains bypass municipal tender complexity and secure multi-year equipment deployment. |
| Software Companion Development | AI-enabled diagnostic algorithms shift vendor selection criteria from resolution metrics to algorithmic accuracy benchmarks. |
| Reimbursement Strategy | Private insurance framework adaptation for remote patient monitoring enables wearable device structural expansion in homecare settings. |
| CE Marking Pathway | Mercosur harmonization standards reduce technical barriers for cross-border trade within the trading bloc. |
Methodological Framework
ANVISA regulatory filings, hospital procurement databases, and GPO contracts formed the secondary backbone of this analysis. Primary interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and regulatory affairs specialists validated demand assumptions and procurement timeline estimates. Bottom-up segmentation modeling across product type, end user, technology, and application dimensions was cross-checked against top-down market sizing from trade flow analysis and installed base estimates.
Historical trendline analysis of diagnostic equipment deployment and orthopedic procedure volumes anchored the forecast framework. Segmentation dimensions modeled include capital intensity tiers, procurement authority structures, intellectual property intensity levels, and disease burden demographics. CAGRs were derived from regression analysis of equipment replacement cycles and reimbursement framework evolution across the projection horizon. Chronic disease screening mandate execution rates and sports medicine participation growth served as industry-specific demand inputs.
Caveats apply where ANVISA administrative simplification implementation delays, PLI scheme analog legislative outcomes, or currency volatility shocks could materially shift the outlook. Forecasts reflect documented assumptions about municipal infrastructure financing availability and private insurance reimbursement adaptation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Female Pelvic Implants Market
Medical Devices
Medical Device Cros Market
Medical Devices
Electroencephalography (EEG) Systems Market
Medical Devices
Neuro Ablation Devices Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
Global Extracorporeal CO2 Removal Devices Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
Support Surfaces Market
Medical Devices
Supraglottic Airway Devices Market
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Neurostimulation Devices Market
Medical Devices
Global Angioplasty Balloons Market
Medical Devices
Embolic Protection Systems Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Artificial Cartilage Implant Market