
 Global Gastrointestinal Stromal Tumors Market | 2026-2036
Global Gastrointestinal Stromal Tumors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gastrointestinal Stromal Tumors Market Foresight
The gastrointestinal stromal tumors landscape is restructuring around a sharp split between premium kinase inhibitor therapies and commoditized generic imatinib formulations. Novartis AG anchors the premium segment through sustained R&D investment in next-generation KIT inhibitors. Sun Pharmaceutical Industries Limited competes aggressively on cost-optimized manufacturing of generic alternatives. Pfizer Inc. leverages its oncology infrastructure to control distribution across specialized cancer centers.
Gastrointestinal stromal tumors are mesenchymal neoplasms arising from interstitial cells of Cajal, characterized by KIT or PDGFRA mutations detectable via immunohistochemistry and molecular sequencing. These tumors require precision therapeutic intervention due to variable mutational profiles driving differential drug sensitivity. The targeted therapy segment leads clinical value creation through mutation-specific inhibitor development, while the diagnostic kits category registers fastest expansion as companion testing becomes standard of care. Immunotherapy occupies an emerging position with ongoing trials in PD-1 refractory populations. Surgical instruments represent a mature revenue pool with stable replacement cycles in oncology clinics.
The FDA, EMA, and Japan's PMDA enforce divergent evidentiary standards for breakthrough oncology designations, directly shaping trial investment locations and launch sequencing. China's NMPA accelerates local approval timelines for innovative kinase inhibitors, altering manufacturer geographic prioritization. Stakeholders must monitor evolving reimbursement criteria for companion diagnostics across these regulators.
Market Dynamics
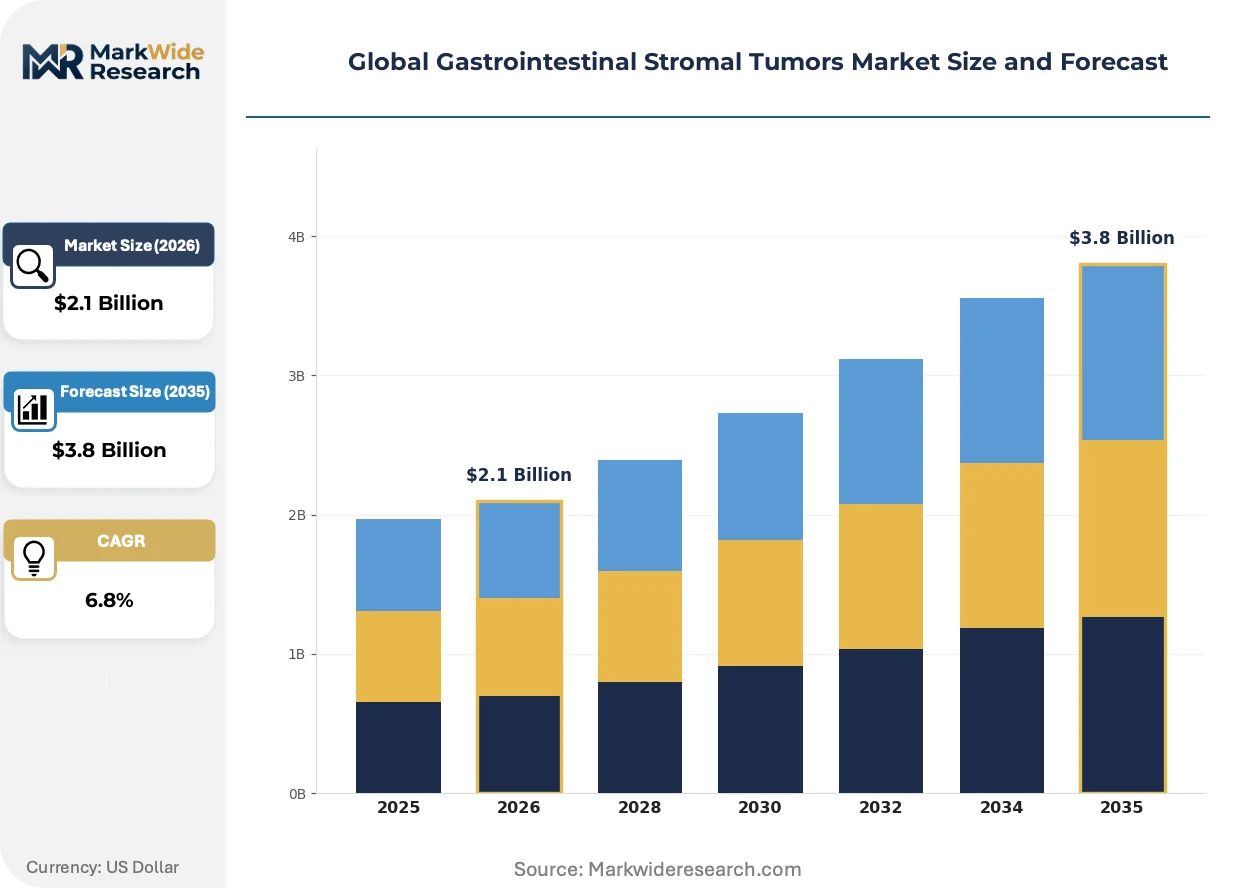
The gastrointestinal stromal tumors market is fragmenting along precision-medicine fault lines, with molecular diagnostic stratification now determining therapy selection before first-line treatment begins. This diagnostic-treatment coupling is compressing traditional sales cycles and elevating companion test manufacturers to gatekeeper status.
Growth Catalysts
- Accelerated Approval Frameworks:The FDA's breakthrough therapy designation and EMA's PRIME scheme compress development timelines for KIT/PDGFRA inhibitors. Oncology developers prioritize these pathways for mutation-specific agents.
- Companion Diagnostic Mandates:Payers in Germany and Japan now require documented PDGFRA exon 18 mutation status prior to reimbursing avapritinib-class therapies. Testing laboratories expand sequencing capacity accordingly.
- Academic-Industry Consortia:Multi-center tumor boards in the United States integrate real-world genomic data into treatment algorithms. These networks accelerate off-label evidence generation for resistant mutation subsets.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for imatinib mesylate concentrates in Indian and Chinese chemical parks. Geopolitical friction or environmental enforcement actions disrupt generic supply continuity.
- Reimbursement Compression:Germany's G-BA applies incremental cost-effectiveness thresholds that depress pricing for second-line sunitinib. Manufacturers face indication-specific reference pricing.
- Biomarker Test Fragmentation:Discordant KIT mutation reporting between immunohistochemistry and next-generation sequencing platforms creates therapeutic ambiguity. Community oncology practices lack standardized protocols.
Strategic Opportunities
- China's Innovation Reimbursement:The NMPA's conditional approval pathway and NRDL negotiation mechanisms reward domestic development of novel KIT exon 17 inhibitors. Multinationals partner with local biotechs for market access.
- Liquid Biopsy Integration:Circulating tumor DNA monitoring for resistance mutation emergence enables therapy switching before radiographic progression. Specialized reference laboratories in Japan pioneer clinical validation.
- Immunotherapy Combinations:PD-1 inhibitor trials in SDH-deficient GIST subpopulations address unmet need in wild-type disease. Academic medical centers in the United States sponsor investigator-initiated studies.
Industry Challenges
- Molecular Pathology Workforce Gap:Interpretation of complex KIT/PDGFRA co-mutation patterns requires specialized training. Community hospitals in the United States struggle to recruit board-certified molecular pathologists.
- Clinical Trial Enrollment Friction:Rare disease prevalence and stringent biomarker eligibility criteria prolong recruitment for targeted agent studies. Sites compete for limited patient pools across overlapping kinase inhibitor protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gastrointestinal Stromal Tumors Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
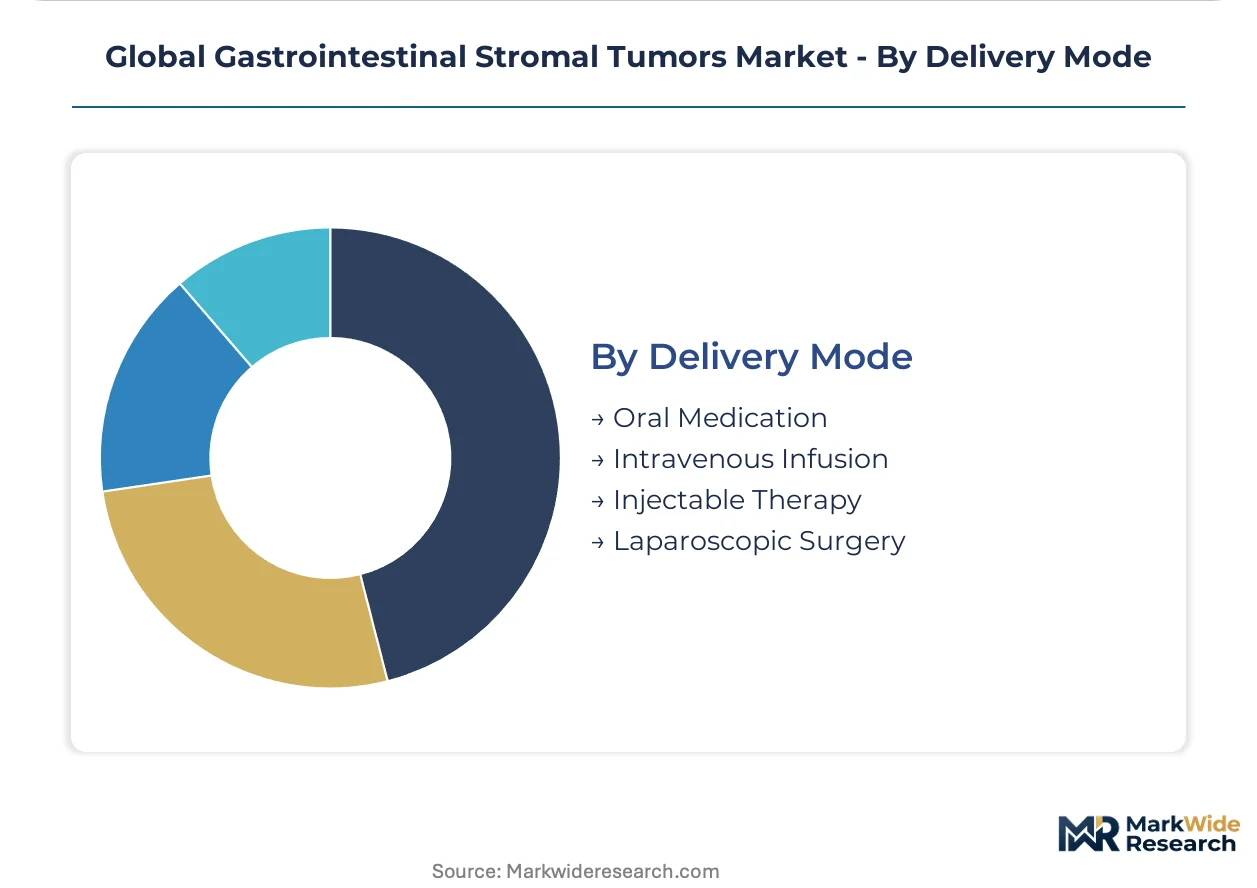
| Segmentation | Product Type: Targeted Therapy, Immunotherapy, Chemotherapy, Surgical Instruments, Diagnostic Kits Therapy Area: Primary Tumors, Recurrent Tumors, Metastatic Tumors, Resistant Tumors End User: Oncology Clinics, Specialized Cancer Centers, Research Laboratories, Diagnostic Centers Delivery Mode: Oral Medication, Intravenous Infusion, Injectable Therapy, Laparoscopic Surgery |
| Companies Covered | Deciphera Pharmaceuticals, NATCO Pharma Limited, Novartis AG, Blueprint Medicines Corporation, F. Hoffmann-La Roche Ltd., Pfizer Inc., Sun Pharmaceutical Industries Limited, Merck & Co. Inc., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gastrointestinal Stromal Tumors Market Shifts & Advancements
Artificial intelligence is penetrating mutation interpretation workflows, compressing turnaround times for complex KIT variant classification. These computational advances are redistributing diagnostic value from hardware platforms to algorithmic expertise.
Next-generation sequencing panels are absorbing the functional role of single-gene immunohistochemistry in upfront GIST diagnosis. Major cancer centers in the United States deploy comprehensive solid tumor profiling within 72-hour windows. This technology shift is compressing revenue for standalone IVD manufacturers while elevating integrated platform vendors.
The FDA's tumor-agnostic approval paradigm for NTRK fusion inhibitors is reshaping GIST trial design, with sponsors now enrolling histology-agnostic cohorts. EMA's parallel scientific advice process accelerates European alignment on biomarker strategies. Smaller biotechnology firms leverage this regulatory convergence to pursue simultaneous US-EU filings for rare mutation targets.
Consolidated purchasing by integrated delivery networks in the United States is displacing traditional distributor relationships for oral oncology agents. These systems negotiate direct contracts with manufacturers, capturing specialty pharmacy margins internally. The behavioral shift is most pronounced in California and Texas, where large IDNs control majority market share in their catchment areas.
Global Gastrointestinal Stromal Tumors Market Segmentation
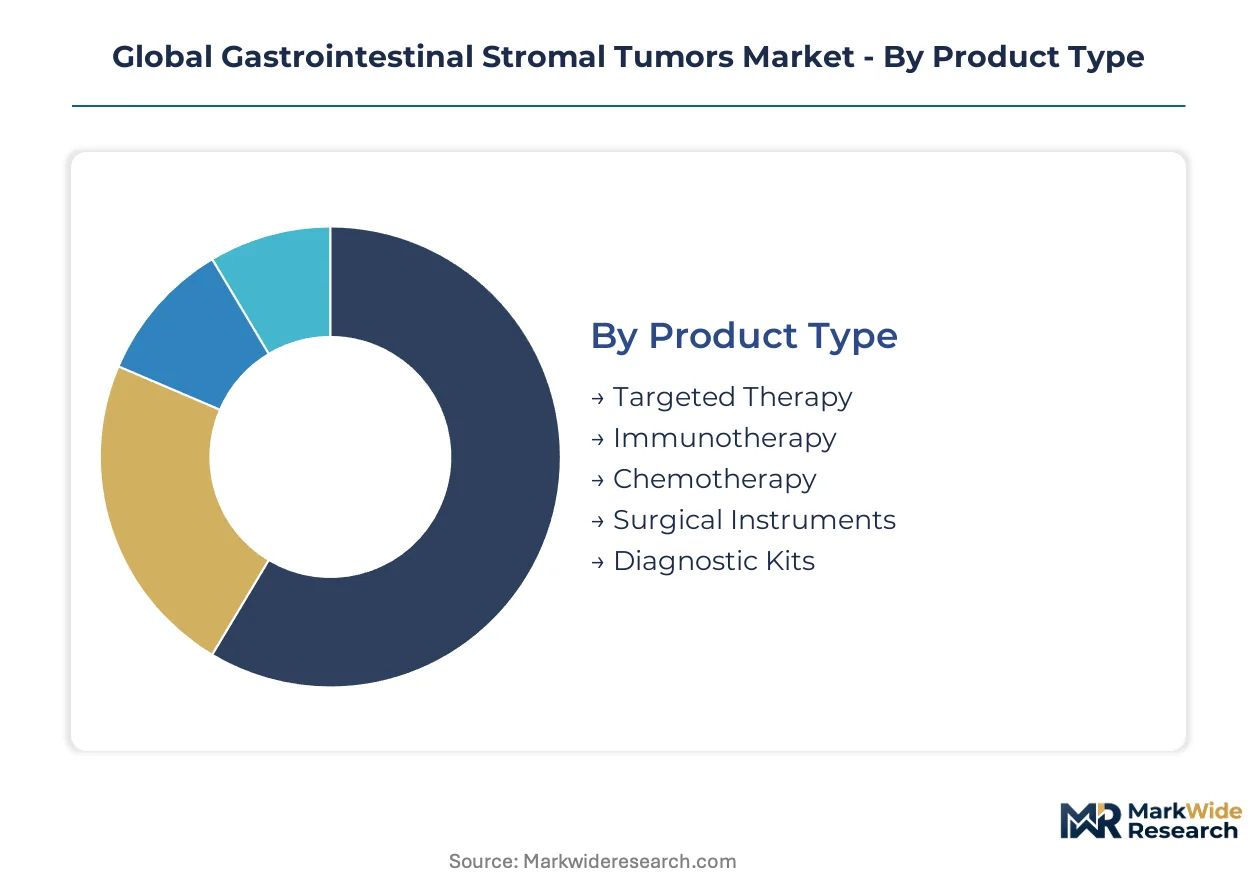
GIST treatment pathways now branch at the molecular diagnostic node, with mutation status determining product selection before therapy initiation. Segmentation logic follows this diagnostic-treatment coupling, tracking how companion testing reshapes demand across delivery modes and care settings.
Product Type:
Supply concentration for active pharmaceutical ingredients skews manufacturing economics toward kinase inhibitor developers with captive synthesis capabilities.
- Targeted Therapy:Small-molecule KIT and PDGFRA inhibitors dominate clinical protocols through mutation-specific binding affinity. United States oncology clinics concentrate demand for next-generation agents as first-line standards displace older tyrosine kinase inhibitors.
- Diagnostic Kits:Companion immunohistochemistry and next-generation sequencing platforms gate reimbursement for premium therapies. German and Japanese laboratories are expanding sequencing capacity to meet payer documentation requirements.
- Immunotherapy:Checkpoint inhibitors target SDH-deficient wild-type subpopulations with limited kinase inhibitor sensitivity.
- Chemotherapy:Cytotoxic regimens retain niche utility in multi-resistant cases where targeted options exhaust.
- Surgical Instruments:Laparoscopic resection kits follow stable replacement cycles in high-volume cancer centers.
Targeted therapy absorbs the bulk of installed capacity; diagnostic kits are expanding most quickly.
Therapy Area:
Patient stratification by disease stage determines pricing tier and treatment duration, with metastatic cases generating sustained pharmaceutical demand.
- Primary Tumors:Neoadjuvant imatinib followed by surgical resection represents the curative-intent standard in localized disease. United States academic medical centers drive adoption of extended adjuvant protocols.
- Resistant Tumors:Secondary KIT mutations necessitate sequential inhibitor switching, creating recurring revenue for developers of exon 17-targeted agents. Japanese referral networks specialize in resistance profiling.
- Recurrent Tumors:Local relapse after complete resection triggers re-challenge with previously effective agents.
- Metastatic Tumors:Systemic disease requires chronic kinase inhibitor administration with dose escalation protocols.
Primary tumors command the largest addressable population; resistant tumors generate the steepest expansion trajectory for novel agent developers.
End User:
Procurement authority is consolidating within integrated delivery networks that internalize specialty pharmacy functions.
- Oncology Clinics:Community-based practices handle stable first-line cases with standardized protocols. Texas and California IDNs are capturing majority market share through direct manufacturer contracting.
- Specialized Cancer Centers:NCI-designated comprehensive centers manage complex mutation profiles and clinical trial enrollment. These sites concentrate access to avapritinib-class agents for PDGFRA exon 18 mutations.
- Research Laboratories:Academic pathology departments validate liquid biopsy assays for resistance monitoring.
- Diagnostic Centers:Independent reference laboratories compete on turnaround time for NGS-based profiling.
Specialized cancer centers anchor premium therapy volume; oncology clinics are gaining share fastest through IDN consolidation.
Delivery Mode:
Oral bioavailability of kinase inhibitors displaces infusion-dependent regimens across outpatient settings.
- Oral Medication:Tyrosine kinase inhibitors enable home administration with monthly pharmacy dispensing. Patient adherence programs in Germany support continuous therapy maintenance.
- Laparoscopic Surgery:Minimally invasive resection reduces recovery time for localized gastric and small intestinal primaries. Japanese surgical societies lead technical training standardization.
- Intravenous Infusion:Limited to investigational immunotherapy combinations in academic settings.
- Injectable Therapy:Subcutaneous formulations under development for selected kinase inhibitors.
Oral medication captures dominant patient-days; laparoscopic surgery maintains stable procedural volume with incremental technique refinements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors clinical trial density for kinase inhibitor development, with Massachusetts General Hospital and Dana-Farber Cancer Institute enrolling the majority of North American GIST patients into mutation-specific protocols.
United States
FDA's breakthrough therapy designation compresses approval timelines for KIT exon 17 inhibitors. Medicare reimbursement policies now mandate companion diagnostic documentation before covering avapritinib-class therapies. Texas Medical Center in Houston concentrates resistance profiling capacity for second-line treatment decisions.
Germany
G-BA applies incremental cost-effectiveness thresholds that depress pricing for second-line sunitinib. Heidelberg University Hospital leads European molecular pathology training for KIT/PDGFRA co-mutation interpretation. Bavarian reference laboratories expand next-generation sequencing capacity to meet payer documentation requirements.
Japan
PMDA accelerates approval timelines for novel kinase inhibitors through the sakigake designation system. National Cancer Center Hospital in Tokyo specializes in liquid biopsy validation for circulating tumor DNA monitoring. Osaka-based surgical societies drive technical standardization for laparoscopic resection protocols.
China
NMPA's conditional approval pathway rewards domestic development of KIT exon 17 inhibitors through priority review vouchers. Shanghai Zhangjiang Hi-Tech Park concentrates biotech partnerships between multinationals and local developers. Beijing's cancer hospitals pioneer real-world evidence collection for resistance mutation registries.
Switzerland
Swissmedic maintains alignment with EMA scientific advice processes for simultaneous European filings. Basel anchors pharmaceutical R&D infrastructure for next-generation inhibitor chemistry. Zurich University Hospital integrates artificial intelligence into mutation interpretation workflows for community pathology networks.
Global Gastrointestinal Stromal Tumors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the diagnostic-treatment coupling dimension. Novartis AG and Blueprint Medicines Corporation command pricing power through mutation-specific patent protection, while Sun Pharmaceutical Industries Limited and NATCO Pharma Limited compete on manufacturing scale for generic imatinib formulations. Three archetypes dominate: integrated pharmaceutical conglomerates with captive oncology infrastructure, precision medicine biotechs with single-asset dependency, and cost-optimized generic manufacturers with API backward integration. Competitive moves concentrate on strategic partnerships for companion diagnostic co-development and geographic licensing for China market access.
Within the integrated pharmaceutical tier, Novartis AG and Pfizer Inc. occupy positions defined by distribution control across specialized cancer centers. Deciphera Pharmaceuticals and Blueprint Medicines Corporation exemplify the precision medicine archetype through kinase inhibitor specialization. Sun Pharmaceutical Industries Limited anchors the cost-optimized manufacturing segment with Indian production base.
| Leading Market Players |
|---|
| Deciphera Pharmaceuticals |
| NATCO Pharma Limited |
| Novartis AG |
| Blueprint Medicines Corporation |
| F. Hoffmann-La Roche Ltd. |
| Pfizer Inc. |
| Sun Pharmaceutical Industries Limited |
| Merck & Co. Inc. |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Imatinib mesylate API spot prices in Indian chemical parks anchor cost baselines for generic manufacturers, cascading through formulation economics into three distinct pricing tiers: premium mutation-specific inhibitors, branded generics, and commoditized imatinib tablets.
Pricing Analysis
Value-based pricing anchors avapritinib-class therapies to PDGFRA exon 18 mutation documentation, with reimbursement contingent on companion diagnostic confirmation. Three-tier pricing structure across premium kinase inhibitors, standard second-line agents, and economy generic imatinib reflects patent status and manufacturing scale. Cost compression in the generic tier intensifies as Indian API producers expand capacity. Community oncology clinics exhibit highest price sensitivity; NCI-designated centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements from German and Japanese payers mandate qualified secondary suppliers for critical KIT inhibitor APIs, forcing manufacturers to maintain redundant manufacturing relationships. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland. Supply chains draw from specialized chemical intermediates, high-purity solvents, and chromatography resins. Single-source vulnerability persists for KIT exon 17-targeting chemistry platforms. Distribution runs through integrated delivery networks in Texas and California that internalize specialty pharmacy functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with control over companion diagnostic development and API synthesis determining margin capture across the diagnostic-treatment coupling.
For Market Incumbents: Deepen captive manufacturing of next-generation KIT inhibitor chemistry to offset API supply disruption risks from Indian and Chinese chemical parks. Expand molecular pathology training partnerships with community hospitals to address workforce gaps that threaten test adoption. Secure exclusive distribution arrangements with Texas and California integrated delivery networks before competitor contracting solidifies. For New Entrants and Emerging Players: The mid-tier pricing gap between premium avapritinib-class agents and economy generic imatinib offers entry space for differentiated second-line inhibitors. Target Japanese referral networks specializing in resistance profiling, where clinical validation partnerships accelerate regulatory pathways. Pursue licensing arrangements with Shanghai-based biotechs to access NMPA conditional approval mechanisms. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision medicine biotechs with single-asset dependency in Switzerland and Massachusetts, where regulatory convergence enables simultaneous FDA-EMA filings. Long-term viability hinges on pipeline diversification beyond kinase inhibitor modalities. Watch for inflection signals in liquid biopsy reimbursement decisions by Medicare and Germany's G-BA.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA's breakthrough therapy designation requires documented biomarker testing, elevating diagnostic gatekeeper status. |
| API Backward Integration | Captive synthesis capabilities insulate Novartis and Blueprint from Indian chemical park disruption risks. |
| China Market Access Partnership | NMPA's priority review vouchers reward local development alliances for KIT exon 17 inhibitors. |
| Liquid Biopsy Clinical Validation | Japanese reference laboratories pioneer circulating tumor DNA monitoring for resistance mutation detection. |
| IDN Direct Contracting | Texas Medical Center and California systems capture specialty pharmacy margins through manufacturer direct agreements. |
Research Methodology
Document review covered FDA breakthrough therapy designations, EMA PRIME scheme approvals, and Japan PMDA sakigake registrations, complemented by interviews with oncology drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from ClinicalTrials.gov entries, CMS Medicare reimbursement databases, and German G-BA benefit assessment documents. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Historical approval timelines and investigator panel input cross-referenced to project therapy adoption curves across the projection horizon. Segmentation dimensions modeled included treatment line, mutation subtype, administration route, and regional regulatory cluster. CAGRs derived from patent expiry schedules, generic entry assumptions, and companion diagnostic penetration curves. Resistance mutation prevalence and liquid biopsy adoption rates served as industry-specific forecast inputs.
Inputs from FDA, EMA, and PMDA regulatory databases were available through the study window; gaps in real-world sequencing volume data introduce uncertainty bands around diagnostic kit forecasts. Deviation in China's NRDL negotiation outcomes or German G-BA cost-effectiveness thresholds would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Ulcerative Colitis Market
Specialty Medicine
Complex Regional Pain Syndrome (CRPS) Market
Specialty Medicine
Hemorrhagic Stroke Treatment Market
Specialty Medicine
Atrophic Vaginitis Treatment Market
Specialty Medicine
Cryoglobulinemia Treatment Market
Specialty Medicine
Tardive Dyskinesia (TD) Treatment Market
Specialty Medicine
Global Parkinsons Disease Treatment Market
Specialty Medicine
Immunology Market
Specialty Medicine
Tinea Corporis Market
Specialty Medicine
Amyotrophic Lateral Sclerosis (ALS) Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Peptide Receptor Radionuclide Therapy (PRRT) Market
Specialty Medicine
Global Pigmentation Disorders Treatment Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Treatment Market