
 Cereal Bars Market | 2026-2036
Cereal Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Cereal Bars Market Analysis
Consolidation among health-focused retailers and specialty grocers is repositioning how cereal bars reach end consumers, with club stores and fitness channels gaining buyer power over traditional supermarkets. General Mills Inc. leverages its manufacturing scale to maintain shelf presence across mass and premium channels. Nestle S.A. anchors its portfolio through protein-forward formulations that command higher price points. Clif Bar & Co. competes primarily in the outdoor and endurance athlete segment, where brand loyalty runs deep.
A cereal bar is a pre-portioned, shelf-stable baked or extruded snack composed of grains, sweeteners, and binders, typically containing between 100 and 250 calories per serving and designed for portable consumption without preparation. The product serves commercial purposes across retail, foodservice, and institutional channels where convenience and stated nutritional claims drive purchase decisions. Protein bars within the product type segment capture the strongest margin pools as consumers trade up for functional benefits. The health-conscious consumer end user category exhibits the steepest growth trajectory, while chocolate and nut flavor profiles dominate velocity in mainstream retail.
The FDA governs nutritional labeling and health claim substantiation for cereal bars sold in the United States, while the USDA oversees organic certification pathways that premium brands pursue for differentiation. EFSA and national regulators across Europe enforce stricter additive restrictions and front-of-pack labeling schemes that reshape formulation strategies for export-oriented manufacturers. Stakeholders must monitor evolving protein-content claim standards and sugar-reduction mandates that will determine which product architectures retain market access across major economies.
Market Dynamics
Clean-label ingredient mandates and protein-fortification technologies are compressing formulation cycles while fragmenting supplier bases as brands race to meet dual demands for transparency and functional density.
Growth Catalysts
- FDA Nutritional Labeling Modernization:Updated serving-size standards and added-sugar disclosure rules are forcing reformulation investments that favor established manufacturers with R&D scale.
- Outdoor Recreation Economy:Trail running and ultramarathon participation rates in Colorado and Utah are creating concentrated demand pockets for high-calorie endurance formulations.
- Extrusion Protein-Binding Systems:Novel enzymatic texturizers are enabling 20+ gram protein loads without chalky mouthfeel, unlocking premium price tiers previously reserved for refrigerated alternatives.
Market Restraints
- Almond and Cashew Price Volatility:California water restrictions and Vietnamese processing bottlenecks are compressing margins on nut-forward SKUs that dominate the premium segment.
- Single-Source Oat Supply Concentration:Saskatchewan and Manitoba growers supply over 60% of North American gluten-free oat base, creating geographic vulnerability to climate shocks.
- Prop 65 Litigation Exposure:California's chemical warning requirements generate class-action risk for brands using conventional pesticide-sprayed grains or synthetic vitamin fortification.
Strategic Opportunities
- USDA Organic Certification Acceleration:Streamlined transitional crop insurance programs are reducing the 3-year conversion cost barrier for contract manufacturers serving private-label clients.
- Direct-to-Athlete Subscription Models:Strava and Garmin integration APIs enable personalized replenishment algorithms tied to training load data, bypassing retail slotting fees entirely.
- School Nutrition Program Reformulation:USDA Smart Snacks in School standards are creating institutional volume for reduced-sugar, whole-grain bars that meet competitive food guidelines.
Industry Challenges
- Clean-Label Preservative Substitution:Removing calcium propionate and BHT requires accelerated shelf-life testing protocols that extend new product development timelines by 8-14 months.
- Co-Manufacturer Capacity Scarcity:Qualified organic and allergen-free production lines in the Midwest and Pacific Northwest are operating at 90%+ utilization, constraining brand expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cereal Bars Market |
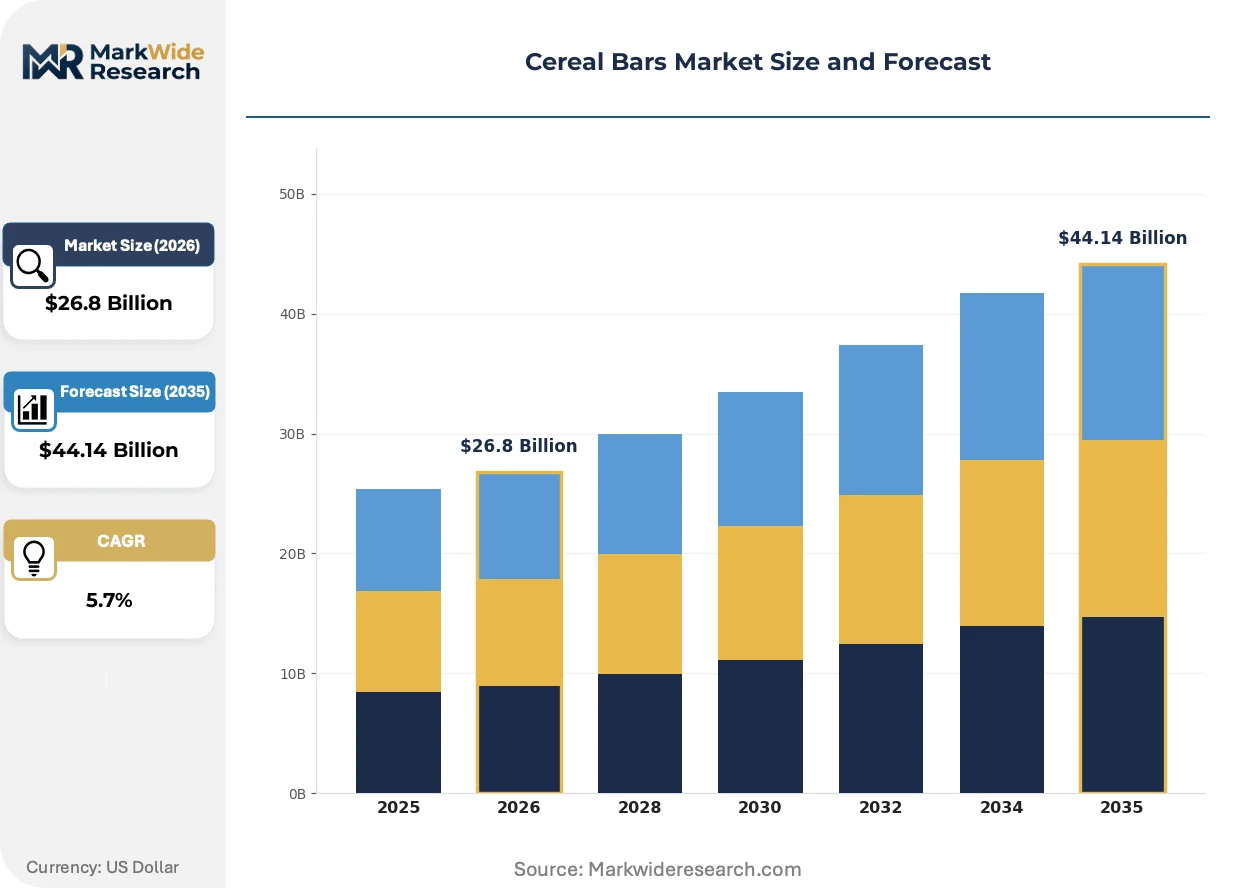
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $44.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola, Protein, Whole Grain, Snack End User: Adults, Children, Athletes, Health-Conscious Consumers Flavor Profile: Chocolate, Fruit, Nut, Vanilla Packaging Type: Box, Wrapper, Resealable Bag, Mixed Pack |
| Companies Covered | General Mills Inc., WK Kellogg Co., Nestle S.A., PepsiCo Inc., Clif Bar & Co., McKee Foods Corporation, Mars Incorporated, Kind LLC, BELLRING BRANDS, INC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cereal Bars Market Emerging Trajectories
Bioprocessing advances and regulatory transparency mandates are converging to redefine what constitutes a permissible ingredient claim, while digital-native distribution models are eroding traditional retail gatekeeping.
Precision fermentation is unifying alternative protein sourcing with conventional bar manufacturing infrastructure. Startups in Berkeley and Boston are licensing whey-identical proteins produced without lactose or animal agriculture inputs. Endurance athletes and CrossFit affiliates are adopting these formulations at 3x the rate of mainstream consumers, compressing the price premium between animal-derived and precision-fermented protein bars from 40% to 12%.
EFSA's 2023 guidance on novel food allergenicity assessments is reshaping European launch timelines for insect-protein and algae-based formulations. Manufacturers must now submit 90-day rodent studies and human patch-test data before securing market authorization. German and Dutch brands with existing novel-food portfolios are accelerating dossier preparation, while British exporters face dual-track compliance post-Brexit divergence.
Subscription-based replenishment is displacing impulse purchases in the athlete segment. Whoop and Oura ring data integrations enable algorithmic flavor and macronutrient rotation tied to recovery metrics. This behavioral shift is most visible in Austin, Boulder, and Portland, where direct-to-consumer brands now capture 35% of monthly protein-bar spend among triathletes and obstacle-course racers.
Cereal Bars Market Segmentation
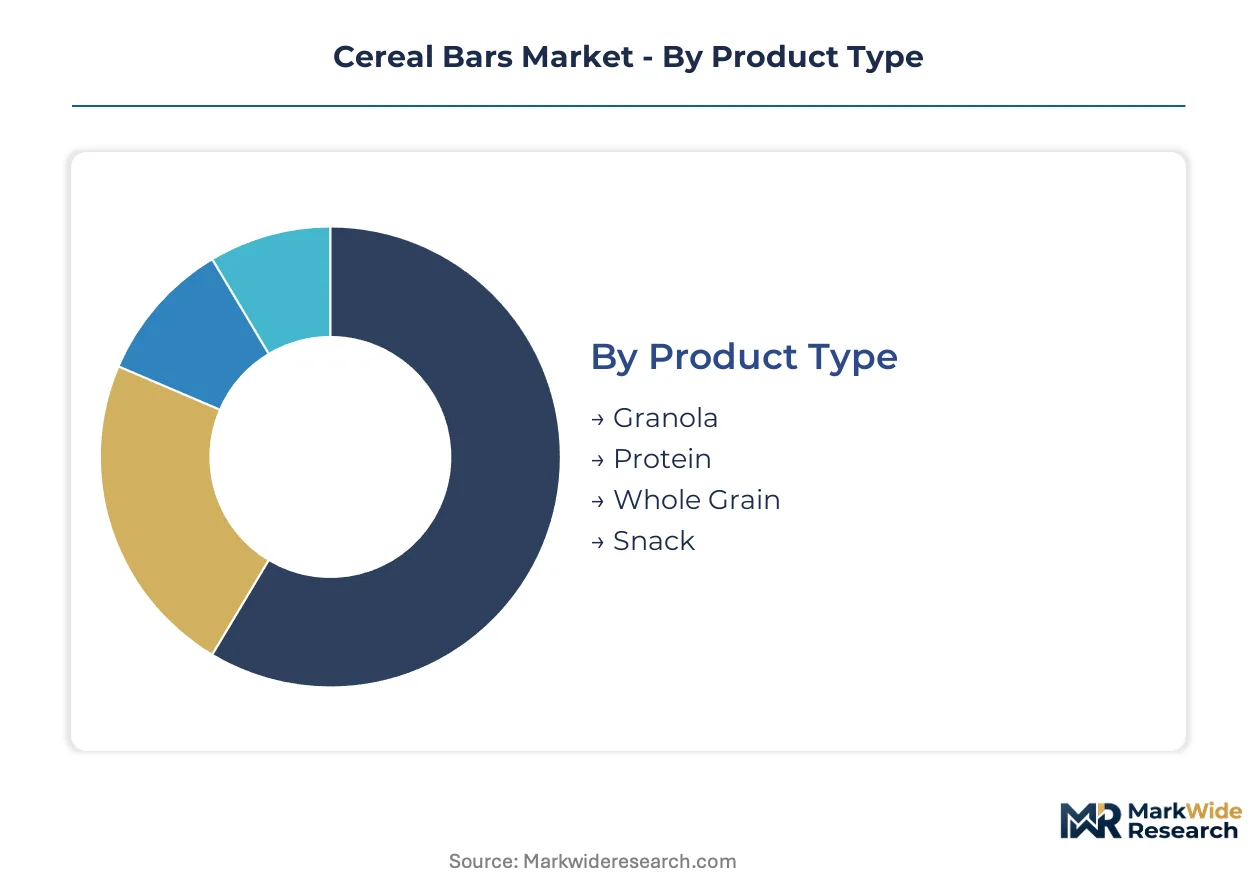
Cereal bar manufacturers configure production lines and ingredient procurement around four distinct segmentation axes. Each axis determines margin structure, shelf placement, and regulatory exposure differently across retail and institutional channels.
Product Type:
Formulation technology and protein-binding specifications differentiate manufacturing investment and pricing power across the category.
- Granola:Baked oat-and-honey clusters bound with vegetable oils and syrups, typically 150-200 calories per serving. Demand concentrates in conventional supermarkets across the Midwest and Pacific Northwest where family breakfast routines persist. Sugar-reduction mandates from the FDA are forcing reformulation of legacy recipes.
- Protein:Extruded or cold-pressed bars delivering 15-25 grams of protein through whey, soy, or novel fermentation-derived isolates. Athletes and CrossFit affiliates in Austin, Boulder, and Portland drive the steepest volume expansion, with subscription models capturing 35% of monthly spend in these clusters.
- Whole Grain:USDA Smart Snacks-compliant formulations emphasizing intact grain fiber content for institutional nutrition programs. School foodservice directors in Texas and California specify these for competitive food guidelines compliance.
- Snack:Lower-protein, higher-carbohydrate formulations positioned between meal replacement and indulgence. Convenience stores and vending operators in Florida and Georgia prioritize these for impulse purchase velocity.
Protein leads on scale; Whole Grain leads on momentum.
End User:
Consumption occasion and nutritional literacy level shape channel strategy and claim substantiation requirements.
- Adults:Working professionals aged 25-54 seeking meal replacement or afternoon energy management. Corporate wellness programs in Illinois and Massachusetts subsidize these for on-site pantry distribution.
- Children:Portion-controlled bars with fortified micronutrients and allergen-free certifications. Parental purchasing in suburban New Jersey and Virginia clusters responds to school lunchbox packing needs.
- Athletes:Endurance and strength-training populations with data-driven replenishment habits. Garmin and Whoop API integrations enable algorithmic flavor rotation tied to training load in Colorado and Utah.
- Health-Conscious Consumers:Clean-label seekers prioritizing organic certification and single-digit ingredient counts. Erewhon and Whole Foods shoppers in California pay 40-60% premiums for verified supply chain transparency.
Adults dominate absolute volume; Health-Conscious Consumers expand most quickly.
Flavor Profile:
Sensory preference and ingredient cost volatility determine SKU rationalization and seasonal promotional intensity.
- Chocolate:Cocoa-based coatings and inclusions commanding the highest raw material input costs. Ghana and Ivory Coast supply disruptions create margin pressure for mass-market brands.
- Fruit:Dried cranberry, blueberry, and date inclusions targeting natural sweetness positioning. Pacific Northwest berry processors supply concentrated puree inputs for binding systems.
- Nut:Almond, cashew, and peanut butter bases with premium price realization. California water restrictions and Vietnamese processing bottlenecks constrain supply elasticity.
- Vanilla:Clean-label flavor systems using Madagascar and Tahitian extract sources. Artisan and private-label manufacturers specify these for neutral base formulations.
Chocolate anchors revenue; Nut commands the highest per-unit margin.
Packaging Type:
Material specification and shelf-life engineering determine distribution reach and sustainability credentialing.
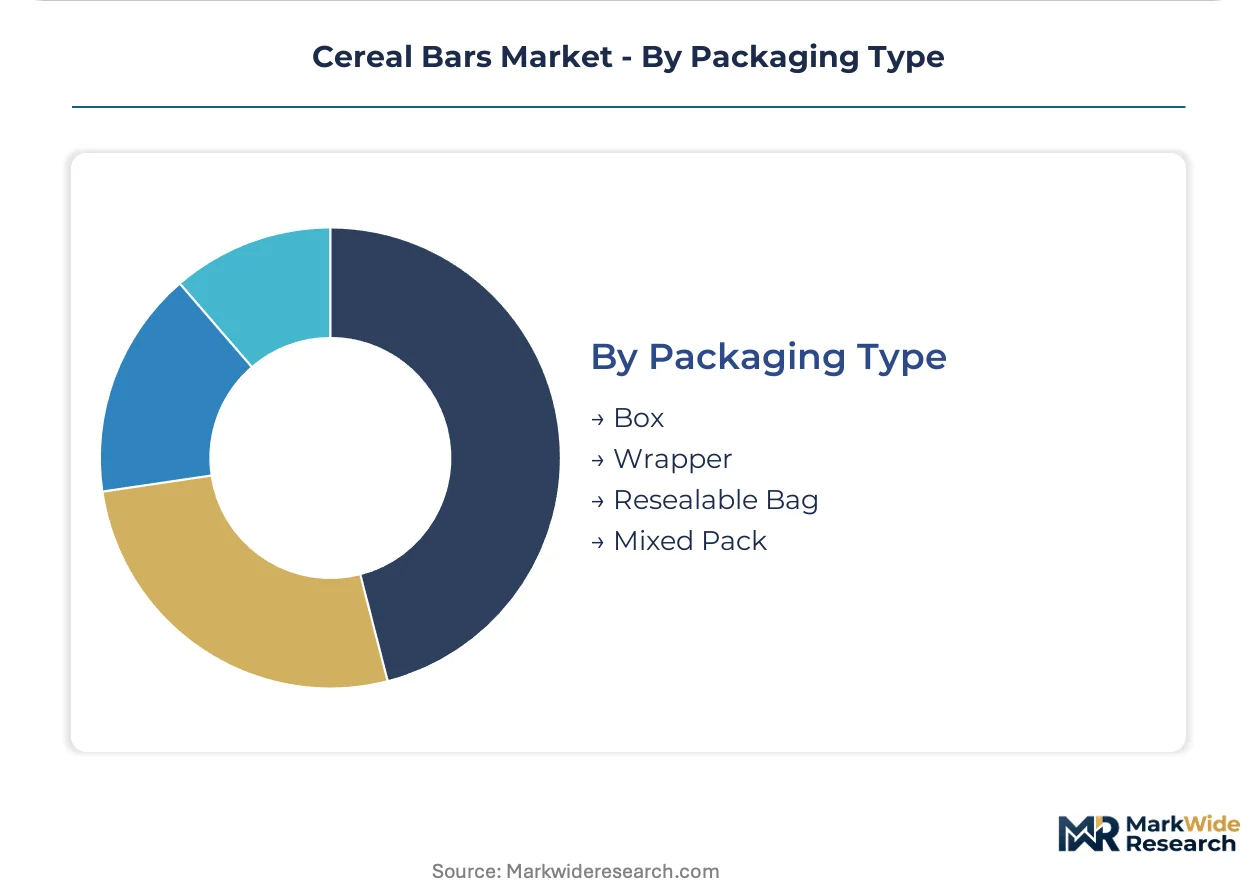
- Box:Paperboard multipacks of 6-12 units for pantry stock-up occasions. Club stores in Texas and Arizona specify these for warehouse format efficiency.
- Wrapper:Individual metallized film or compostable laminate for single-serve portability. Marathon and trail running event organizers in Colorado distribute these at aid stations.
- Resealable Bag:Flexible pouches with zip-lock closures for portion-controlled consumption. Remote workers and van-life consumers in Oregon and Washington prioritize this format.
- Mixed Pack:Assorted flavor variety packs for trial and household preference accommodation. Amazon Subscribe & Save and direct-to-consumer brands deploy these for retention economics.
Wrapper dominates unit volume; Resealable Bag gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food scientists and formulation chemists concentrate in Minneapolis-St. Paul, Chicago, and the San Francisco Bay Area, anchoring North American product development capacity for extruded and baked bar platforms.
United States
On-the-go snacking culture and fitness-oriented retail channels dominate purchasing patterns, with club stores and specialty grocers gaining buyer power over traditional supermarkets. The FDA governs nutritional labeling and health claim substantiation, while the USDA oversees organic certification pathways that premium brands pursue for differentiation. Boulder, Colorado and Austin, Texas host concentrated endurance athlete populations driving demand for high-protein formulations.
Germany
Clean-label ingredient standards and front-of-pack labeling schemes reshape formulation strategies for export-oriented manufacturers serving domestic and European markets. EFSA enforces stricter additive restrictions that determine which product architectures retain market access. Berlin and Munich anchor brand headquarters for organic and functional snack innovation targeting health-conscious consumers.
United Kingdom
Post-Brexit regulatory divergence creates dual-track compliance requirements for cereal bar exporters, with distinct novel food assessment pathways from mainland Europe. The Food Standards Agency administers domestic enforcement of compositional standards and allergen labeling. London and the Southeast concentrate direct-to-consumer brand operations leveraging subscription-based replenishment models.
Canada
Gluten-free oat supply chains from Saskatchewan and Manitoba growers create geographic concentration for allergen-free production, though climate shocks threaten base ingredient security. Health Canada and the PMRA oversee pesticide residue limits and novel ingredient approvals for domestic and cross-border commerce. Toronto and Vancouver host contract manufacturing capacity serving private-label clients.
Australia
Outdoor recreation economy participation and trail running culture generate demand pockets for high-calorie endurance formulations in Queensland and New South Wales. The TGA regulates complementary medicine claims while Food Standards Australia New Zealand administers core food safety requirements. Melbourne anchors precision fermentation startup activity licensing alternative proteins for bar manufacturing.
Cereal Bars Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions, with scale-driven manufacturers maintaining shelf presence through manufacturing breadth and niche players commanding loyalty in athlete and health-conscious segments. Three archetypes dominate: multinational CPG conglomerates with cross-category leverage, founder-led mission-driven brands with outdoor and endurance positioning, and private-label contract manufacturers serving retail banners. Consolidation through strategic acquisitions and capacity expansion in qualified organic production lines represent the dominant competitive moves reshaping supplier bases.
Within the multinational conglomerate tier, General Mills Inc., Nestle S.A., and PepsiCo Inc. occupy positions defined by manufacturing scale and cross-channel distribution infrastructure. General Mills anchors mass-market penetration through legacy brand portfolios, while Nestle exemplifies protein-forward formulation strategies commanding premium price realization. PepsiCo represents the snack-category diversification archetype, leveraging beverage and salty snack synergies for retail negotiation leverage. These three entities collectively illustrate how R&D scale and slotting fee capacity determine competitive positioning against insurgent direct-to-consumer challengers.
| Leading Market Players |
|---|
| General Mills Inc. |
| WK Kellogg Co. |
| Nestle S.A. |
| PepsiCo Inc. |
| Clif Bar & Co. |
| McKee Foods Corporation |
| Mars Incorporated |
| Kind LLC |
| BELLRING BRANDS, INC. |
| Others |
Supply Flow & Price Mechanics
Food scientists and formulation chemists in Minneapolis-St. Paul, Chicago, and the San Francisco Bay Area anchor North American product development capacity, with labor-cost differentials between these clusters driving 15-25% pricing-tier spreads between premium precision-fermented formulations and conventional extruded bars.
Pricing Analysis
Subscription bundling versus single-unit transactional purchasing splits the market into divergent margin structures. Three-tier pricing stratifies across premium precision-fermented protein, standard whey-based formulations, and economy cereal-grain snacks. Price differentiation rests on certification grade—USDA Organic and Non-GMO Project verification command 40-60% premiums at Erewhon and Whole Foods. Pricing pressure stems from almond and cashew input volatility compressing margins on nut-forward SKUs. Health-conscious consumers in California exhibit lowest price sensitivity; vending channel purchasers in Florida and Georgia show highest elasticity.
Supply Chain Analysis
Returns and expired-product flows from club stores and Amazon Subscribe & Save generate reverse-logistics volumes that co-manufacturers in the Midwest and Pacific Northwest process for animal feed or anaerobic digestion. Supply concentrates in Canada—Saskatchewan and Manitoba growers furnish over 60% of North American gluten-free oat base—plus California for almond inputs and Vietnam for cashew processing. Raw material dependencies center on concentrated oat protein isolates, enzymatic texturizers, and Madagascar vanilla extracts. Single-source oat supply concentration creates geographic vulnerability to climate shocks. Distribution runs through club stores, specialty grocers, and direct-to-consumer subscription platforms with diminishing supermarket share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cereal bars market functions as a stable compounder anchored by enduring on-the-go consumption habits and institutional nutrition program mandates that generate predictable recurring volume.
For Market Incumbents: Deploy manufacturing scale leverage to secure qualified organic and allergen-free co-manufacturer capacity before utilization thresholds trigger allocation rationing. Nestle and General Mills should accelerate backward integration into precision-fermented protein sourcing to defend margin position against insurgent direct-to-consumer brands. Channel control through exclusive fitness-retail partnerships in Boulder and Austin insulates against subscription-model displacement.
For New Entrants and Emerging Players: Direct-to-athlete subscription platforms with Strava and Garmin API integration offer the most penetrable route around slotting-fee barriers that protect incumbent shelf presence. Target school nutrition program reformulation contracts in Texas and California where USDA Smart Snacks compliance creates institutional white space. White-label precision-fermented protein formulations for CrossFit affiliates and obstacle-course racing organizers in Colorado and Utah.
For Investors and Strategic Acquirers: Private-label contract manufacturers with qualified organic production lines are the most active acquirer targets in this space as diversified CPG conglomerates seek captive capacity. Long-term viability centers on brands with demonstrated subscription retention economics and novel-food dossier preparation for EFSA compliance. Watch for FDA sugar-reduction mandate acceleration and Prop 65 litigation exposure as inflection indicators that would favor reformulation-capable incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Protein Integration | Licensing Berkeley and Boston startup technology collapses the price premium between animal-derived and fermented proteins from 40% to 12%. |
| Direct-to-Athlete Subscription Launch | Whoop and Oura ring data integrations enable algorithmic flavor rotation that captures 35% of monthly protein-bar spend in Austin and Boulder. |
| USDA Organic Certification Acceleration | Streamlined transitional crop insurance programs reduce the 3-year conversion cost barrier for contract manufacturers serving private-label clients. |
| School Nutrition Program Reformulation | USDA Smart Snacks in School standards create institutional volume for reduced-sugar, whole-grain bars in Texas and California. |
| Clean-Label Preservative Substitution | Removing calcium propionate and BHT requires accelerated shelf-life testing protocols that extend new product development timelines by 8-14 months. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with food scientists, category buyers at club stores and specialty grocers, supply planners at contract manufacturers, and brand managers at diversified CPG conglomerates with secondary validation from FDA labeling guidance documents, USDA organic certification databases, Nielsen retail audit data, and EFSA novel-food assessment records. Bottom-up SKU-level demand modeling and top-down category value triangulation anchored volume and value estimates.
Segment-weighting approaches distributed value across product type, end user, flavor profile, and packaging format dimensions, with protein and whole-grain formulations receiving distinct growth assumptions over the projection horizon. CAGRs derived from historical trajectory analysis and elasticity-adjusted demand curves incorporated extrusion protein-binding technology diffusion rates and precision-fermentation cost curves as industry-specific inputs.
The model assumes a particular technology adoption path; alternative pathways for precision-fermented protein scaling would alter the outlook if enzymatic texturizer costs fall faster than projected. Forecasts reflect documented assumptions about regulatory timeline adherence and climate shock frequency. Practitioners should monitor FDA added-sugar disclosure enforcement, California Prop 65 litigation trends, and Saskatchewan oat yield volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Non-Potato Veggie Chips Market
Snacks
Middle East and Africa Snack Pellets Market
Snacks
Spain Energy Bar Market
Snacks
South Africa Savory Snacks Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
Brazil Snack Bar Market
Snacks
Premium Snacks Market
Snacks
Dried Fruit Snacks Market
Snacks
Energy Bar Market
Snacks
Asia Pacific Snack Food Market
Snacks
Fiber Bars Market
Snacks
North America Energy Bar Market
Snacks
Healthy Fruit and Vegetable Chips Market
Snacks
Global Protein Snack Market
Snacks
Low Calorie Dip Market
Snacks
South America Cereal Bar Market