
 Low Calorie Dip Market | 2026-2036
Low Calorie Dip Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Dip Market Analysis
Single-serve packaging is restructuring how households and foodservice operators stock low calorie dips, shifting volume from bulk tubs toward portion-controlled formats that reduce spoilage and support on-the-go consumption. Sabra Dipping Company leverages its refrigerated supply chain dominance to anchor retail shelf presence across conventional and natural channels. PepsiCo sustains broad brand recognition through cross-category snack bundling that pairs dips with complementary items. General Mills competes via R&D intensity in dairy-alternative formulations that broaden addressable dietary segments.
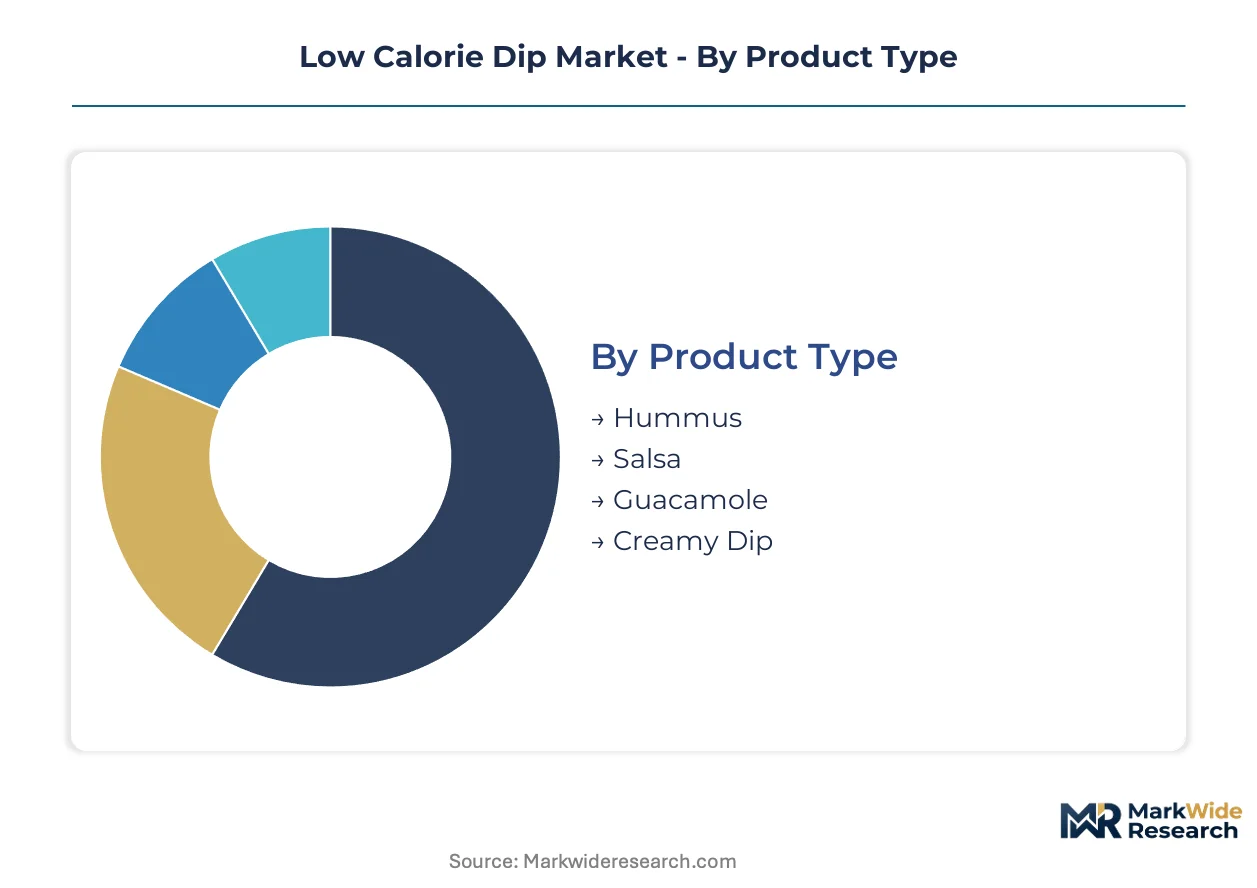
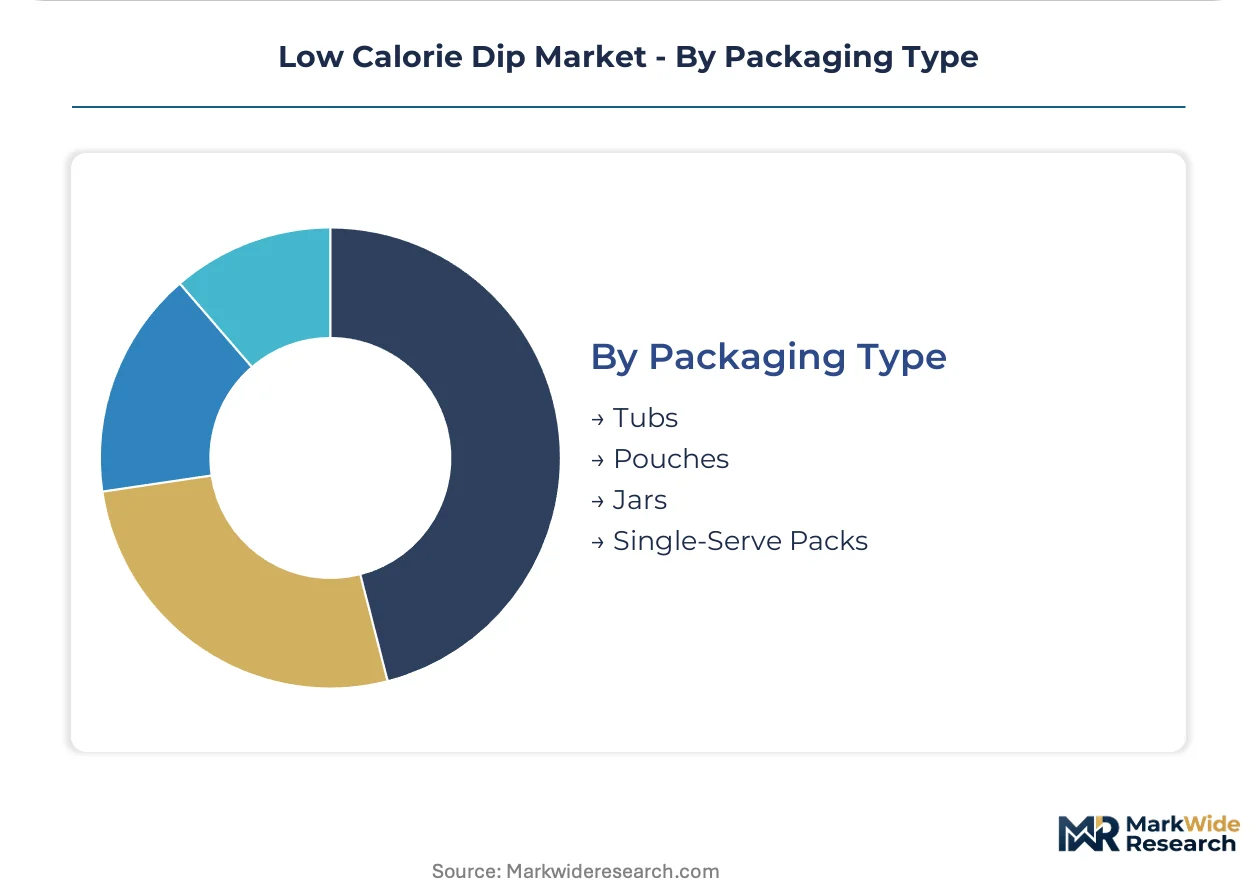
Low calorie dip denotes a reduced-fat or reduced-calorie condiment typically formulated with modified starch, yogurt, legume, or vegetable bases and containing fewer kilocalories per serving than conventional equivalents, designed for direct consumption with vegetables, chips, or crackers. Manufacturing employs cold-fill processing for fresh varieties and aseptic systems for shelf-stable lines to preserve texture and microbial safety. Hummus commands the largest volume share among product types due to its protein positioning and established Mediterranean culinary acceptance. Single-serve packs represent the fastest-expanding packaging type as convenience retailers and school lunch programs prioritize portion compliance. Creamy dip variants retain margin concentration in premium private-label contracts where ingredient differentiation justifies elevated price points.
The FDA governs nutrition labeling and health claim substantiation for low calorie dips sold in the United States, while the USDA oversees school nutrition standards that influence institutional procurement specifications. EFSA evaluates novel ingredient approvals and clean-label claims for products distributed across European Union member states, creating compliance complexity for exporters. Stakeholders must monitor evolving front-of-package labeling mandates and sugar-reduction targets as these regulatory instruments reshape formulation roadmaps and geographic prioritization.
Market Dynamics
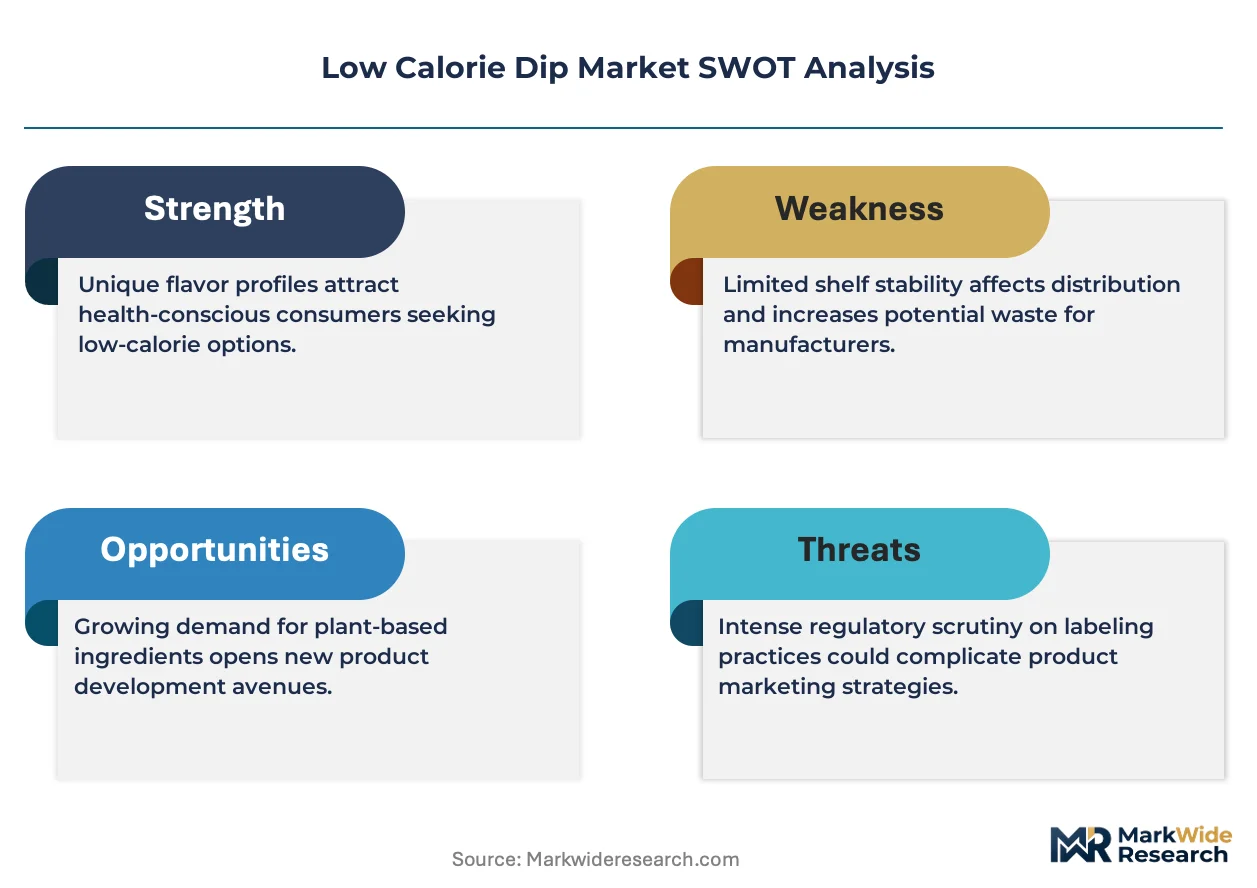
Clean-label reformulation pressure is fragmenting manufacturing footprints as brands rebuild supply chains around plant-based bases and cold-fill infrastructure to meet retailer sustainability mandates.
Growth Catalysts
- USDA school nutrition standards:K-12 procurement specifications now prioritize reduced-fat condiments, institutionalizing volume commitments for compliant low calorie dip suppliers.
- Cold-fill processing technology:Extended shelf-life without chemical preservatives enables national distribution of fresh hummus and yogurt-based varieties.
- United States snacking frequency:Per-capita consumption occasions now average three daily, expanding addressable occasions for portion-controlled dip formats.
Market Restraints
- Chickpea supply concentration:North American hummus production depends on drought-vulnerable Montana and North Dakota growing regions.
- FDA health claim substantiation:Pre-market notification requirements delay launch timelines for novel functional ingredient positioning.
- Refrigerated freight cost volatility:Diesel price fluctuations and driver shortages compress margins on temperature-controlled last-mile delivery.
Strategic Opportunities
- European clean-label tailwinds:EFSA novel ingredient approvals create first-mover advantage for fermented plant-protein bases in EU retail channels.
- Direct-to-institution channels:Corporate campus foodservice contracts bypass traditional retail slotting fees and build recurring revenue.
- High-pressure processing convergence:HPP technology paired with recyclable mono-material packaging satisfies both food safety and circular economy mandates.
Industry Challenges
- Food science talent scarcity:Formulation chemists with expertise in fat-mimetic starches and protein stabilization command premium compensation.
- Co-manufacturer certification timelines:BRC and SQF audits require six-to-nine month qualification periods, constraining capacity scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Dip Market |
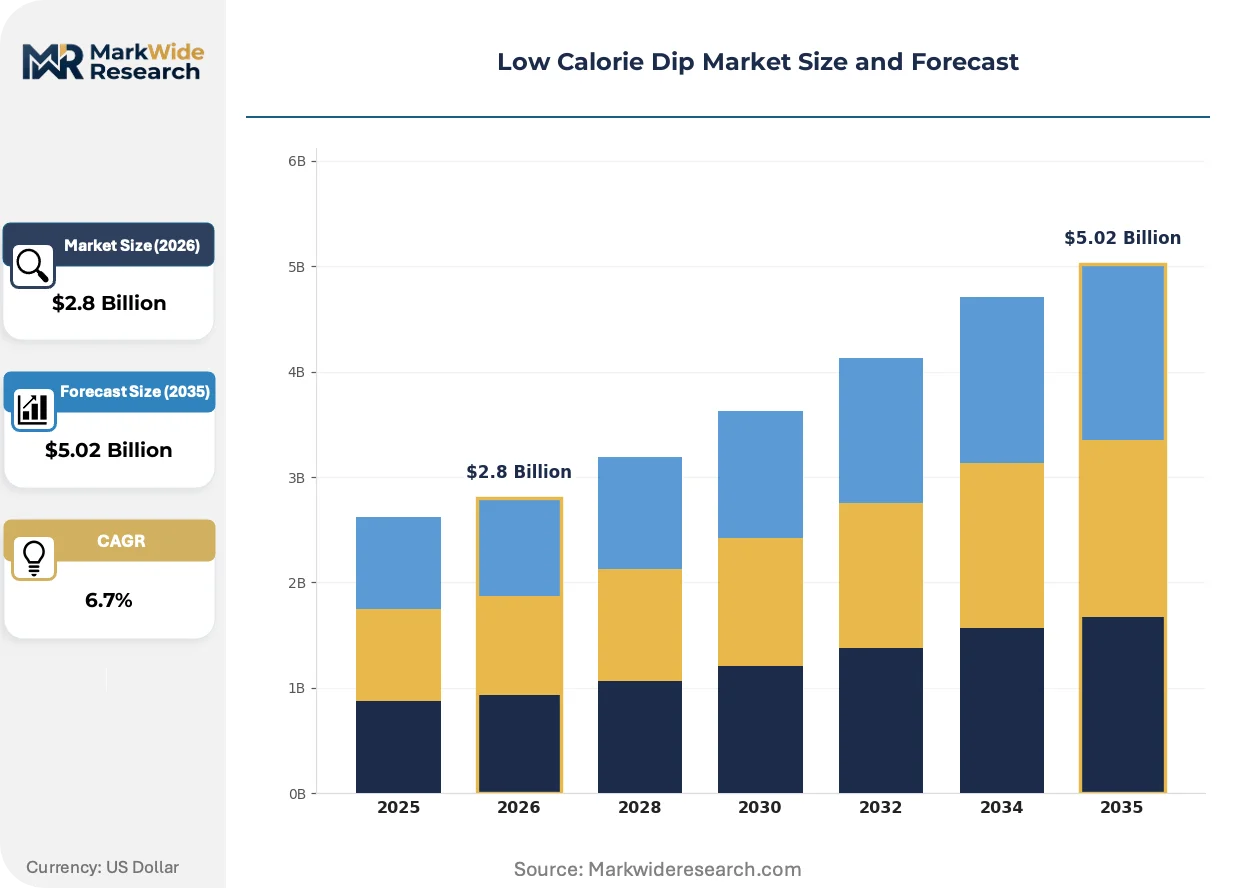
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hummus, Salsa, Guacamole, Creamy Dip Flavor Profile: Spicy, Sweet, Savory, Herb Target Consumer: Health-Conscious, Diabetics, Athletes, Families Packaging Type: Tubs, Pouches, Jars, Single-Serve Packs |
| Companies Covered | The J.M. Smucker Company, Sabra Dipping Company, Nestle, GreenSpace Brands, WayFare Health Foods, PepsiCo, General Mills, Good Karma Foods, Kite Hill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Dip Market Emerging Trajectories
Reformulation science and packaging engineering are converging to redefine freshness signaling, with brands competing on ingredient transparency rather than calorie reduction alone.
High-pressure processing is modularizing production economics for regional manufacturers. This non-thermal pasteurization method preserves texture and nutrient density in hummus and yogurt-based dips. Mid-sized co-manufacturers in Texas and California are adopting HPP lines to serve private-label clients without centralized national infrastructure. The technology is modularizing competitive entry by reducing minimum efficient scale requirements.
EFSA front-of-package nutrient profiling proposals are reshaping permissible marketing claims across EU member states. Draft regulations would restrict "low calorie" descriptors on products exceeding sodium thresholds, forcing sodium reduction parallel to fat reformulation. Mediterranean exporters to Germany and France are accelerating potassium chloride substitution trials to maintain label eligibility.
Subscription-based replenishment is displacing traditional grocery replenishment among urban households. Direct-to-consumer platforms bundle rotating dip varieties with produce boxes, capturing pantry share from conventional retail. This model concentrates in United States coastal metros where delivery density supports cold-chain unit economics.
Low Calorie Dip Market Segmentation
Low calorie dip manufacturers configure production lines around distinct formulation bases and consumption occasions. Segment-specific packaging investments and cold-chain requirements reshape margin structures across each category.
Product Type:
Formulation chemistry and shelf-life engineering separate winners from commodity players in this axis.
- Hummus:Chickpea-tahini emulsions stabilized with citric acid and cold-fill processing dominate refrigerated sets. United States retail chains anchor volume through Mediterranean salad bar placements and grab-and-go snack bundles.
- Salsa:Tomato-pepper blends with modified starch thickeners achieve ambient distribution via hot-fill acidification. Mexican and Southwest United States regional preferences concentrate demand for fire-roasted and verde variants.
- Guacamole:High-pressure processing preserves avocado texture without thermal degradation. California and Florida growing regions supply Hass cultivars to fresh-format retailers.
- Creamy Dip:Yogurt or legume bases replace sour cream in reduced-fat formulations. Institutional foodservice contracts in the United States Midwest drive bulk tub procurement for K-12 and healthcare channels.
Hummus leads on scale; single-serve guacamole gains share fastest through convenience retail expansion.
Flavor Profile:
Palate segmentation tracks regional heat tolerance and meal-occasion pairing patterns.
- Spicy:Capsicum extracts and fermented pepper bases target younger demographics in Texas, Arizona, and New Mexico retail environments. Scoville-rated labeling builds transparency trust.
- Sweet:Fruit-puree blends with alternative sweeteners serve dessert-snack crossover occasions. Northeast United States urban markets show concentration for cinnamon and vanilla profiles.
- Savory:Umami-forward formulations using yeast extracts and mushroom powders appeal to savory-snack substitutors. Pacific Northwest natural channel retailers prioritize clean-label savory options.
- Herb:Fresh-dried herb combinations signal premium positioning through visible particulate. Mediterranean herb blends concentrate in Florida and California coastal markets with established hummus consumption.
Savory commands the broadest household penetration; spicy climbs fastest through social media recipe amplification.
Target Consumer:
Health claim substantiation requirements and channel placement fees vary sharply by dietary specification.
- Health-Conscious:Clean-label seekers prioritize ingredient lists under seven items with recognizable vegetable bases. Natural channel slotting fees in the United States reflect this segment's margin contribution.
- Diabetics:Glycemic-index positioning requires clinical substantiation for glucose-response claims. FDA notification timelines extend launch cycles for this segment.
- Athletes:Protein-fortified formulations using pea or soy isolates target post-workout recovery occasions. United States gym and fitness center foodservice channels concentrate demand.
- Families:Value-format multipacks with mild flavor profiles dominate club store rotations. USDA school nutrition compliance opens institutional volume for this segment.
Health-conscious consumers drive premium pricing; athletes represent the steepest expansion trajectory through sports nutrition channel development.
Packaging Type:
Unit economics and spoilage risk allocate manufacturing capacity across format types.
- Tubs:Injection-molded polypropylene containers with tamper-evident lidding serve family-size and foodservice volumes. Reclosing functionality supports multi-occasion consumption.
- Pouches:Flexible film structures with fitment closures reduce shipping cube and material cost. Stand-up pouch adoption accelerates in club store private-label programs.
- Jars:Glass or PET barrier containers enable hot-fill shelf-stable distribution. Ambient logistics cost advantages support rural United States market penetration.
- Single-Serve Packs:Portion-controlled cups and squeeze formats minimize food waste and support on-the-go consumption. Convenience store and school lunch program specifications institutionalize demand.
Tubs retain volume leadership; single-serve packs expand most quickly through grab-and-go retail format proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Low calorie dip manufacturing originated in Mediterranean culinary traditions before scaling through United States refrigerated distribution networks. Cold-chain infrastructure investments during the 1990s transformed regional specialties into nationally distributed categories. Today production clusters concentrate where chickpea cultivation intersects with dairy-alternative innovation ecosystems.
United States
Three daily snacking occasions per capita sustain demand for portion-controlled formats across convenience retail and school nutrition channels. USDA K-12 procurement standards institutionalize reduced-fat condiment specifications, locking in volume commitments for compliant suppliers. California's Central Valley and Texas dairy corridors host co-manufacturing clusters serving private-label and branded programs.
Germany
EFSA front-of-package nutrient profiling proposals drive sodium reduction reformulation among Mediterranean exporters targeting German retail. Clean-label fermentation expertise in Bavaria supports plant-protein base development for hummus alternatives. Berlin-Brandenburg logistics hubs enable cold-chain distribution across Northern European markets.
France
Mediterranean culinary acceptance positions hummus and herb-forward varieties in Parisian natural channel retail. ANSM labeling oversight intersects with EFSA claim substantiation requirements for functional positioning. Provence-Alpes-Côte d'Azur foodservice clusters concentrate demand for premium single-serve formats in hospitality channels.
Canada
Health Canada nutrition labeling harmonization with FDA standards simplifies cross-border product development for North American portfolios. Cold-fill processing adoption in Ontario and Quebec supports fresh-format distribution without chemical preservatives. Greater Toronto Area retail density enables subscription-based replenishment model pilot programs.
United Kingdom
Meal-deal culture in London/Southeast convenience retail accelerates grab-and-go dip format penetration. FSA front-of-package labeling schemes pressure simultaneous fat and sodium reduction in creamy dip formulations. Midlands manufacturing corridors host co-packing capacity for European brand exporters.
Low Calorie Dip Market Vendor Landscape
Premium-margin players sit above commodity-margin players across cold-chain infrastructure ownership and clean-label certification depth. Refrigerated supply chain dominance separates national distributors from regional specialists dependent on third-party logistics. Three archetypes populate the competitive set: diversified snack conglomerates with cross-category bundling capability, refrigerated supply chain specialists with retail shelf anchoring strength, and plant-based formulation innovators targeting dietary restriction segments. Consolidation activity concentrates on co-manufacturer acquisition to secure BRC-certified capacity, while portfolio diversification into fermented bases addresses European clean-label tailwinds.
Within the diversified snack tier, PepsiCo and General Mills exemplify cross-category leverage strategies that pair dip portfolios with complementary cracker and chip assortments. Sabra Dipping Company occupies a position as the refrigerated supply chain anchor, representing the specialist archetype that built national distribution through Mediterranean product authenticity. Nestle sits within the nutrition-science tier, applying dairy-alternative R&D infrastructure from adjacent categories to low calorie dip formulation.
| Leading Market Players |
|---|
| The J.M. Smucker Company |
| Sabra Dipping Company |
| Nestle |
| GreenSpace Brands |
| WayFare Health Foods |
| PepsiCo |
| General Mills |
| Good Karma Foods |
| Kite Hill |
| Others |
Supply Flow & Price Mechanics
Retailer sustainability mandates for recyclable mono-material packaging now gate access to premium shelf placement and margin-accretive price tiers across United States and European grocery channels. Cold-fill infrastructure ownership separates suppliers who command branded price premiums from co-manufacturers locked into private-label rate cards.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by certification depth and cold-chain control. Premium tiers capture branded positioning through BRC-certified production and HPP-enabled clean-label claims, while economy tiers compete on volume scale in club store private-label programs. Pricing pressure stems from refrigerated freight cost volatility compressing last-mile margins. Institutional foodservice buyers exhibit highest price sensitivity due to USDA procurement compliance requirements, whereas natural channel retailers absorb premiums for seven-item ingredient lists.
Supply Chain Analysis
Single-source vulnerability sits with Montana and North Dakota chickpea cultivation, where drought exposure threatens hummus production economics. Raw material flows draw from California avocado groves, Texas dairy corridors for yogurt bases, and Mediterranean tahini suppliers. Tariff exposure on imported olive oil and sesame paste feeds into formulation cost instability. Distribution runs through refrigerated regional distribution centers serving conventional and natural retail channels, with direct-to-institution bypass emerging for corporate campus contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low calorie dip market functions as a stable compounder, with USDA school nutrition standards institutionalizing recurring volume commitments that smooth demand cyclicality.
For Market Incumbents: To counter cold-fill co-manufacturer capacity constraints, Sabra Dipping Company and PepsiCo should deepen backward integration into HPP-equipped production facilities in California and Texas dairy corridors. BRC certification depth anchors retail shelf permanence against private-label encroachment. For New Entrants and Emerging Players: Begin with subscription-based replenishment pilots in Greater Toronto Area and United States coastal metros, where delivery density supports cold-chain unit economics. Direct-to-institution corporate campus contracts bypass slotting fee barriers and build recurring revenue streams absent in conventional retail. For Investors and Strategic Acquirers: Roll-up economics work for regional co-manufacturers with SQF-certified capacity because six-to-nine month qualification timelines create scarcity value for acquirers with integration bandwidth. Five-to-ten year viability hinges on fermented plant-protein base capabilities for European clean-label tailwinds. Monitor EFSA novel ingredient approval velocity as inflection signal for first-mover positioning in EU retail channels.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Fill Infrastructure Expansion | HPP adoption in Texas and California reduces minimum efficient scale for regional manufacturers serving private-label clients. |
| Backward Integration into Chickpea Sourcing | Montana and North Dakota growing region exposure necessitates captive supply or diversified origination strategies. |
| EFSA Novel Ingredient Submissions | Fermented plant-protein base approvals unlock premium positioning in German and French clean-label retail channels. |
| Direct-to-Institution Channel Development | Corporate campus foodservice contracts bypass traditional retail slotting fees and build recurring revenue visibility. |
| Mono-Material Packaging Transition | Retailer sustainability mandates gate premium shelf placement and margin-accretive price tier access. |
Methodological Framework
Bottom-up snacking occasion modeling reconciled against top-down refrigerated distribution capacity tracking forms the analytical core. Primary interviews with category buyers at conventional and natural retailers, cold-chain logistics planners, co-manufacturer operations directors, and K-12 foodservice procurement officers combined with secondary validation from FDA nutrition labeling guidance, USDA school nutrition standards documentation, Nielsen retail audit data, and EFSA novel ingredient approval registers. Triangulation across stakeholder inputs and regulatory filings grounds volume and value estimates.
Input-output matrices map chickpea supply availability, HPP equipment installation rates, and cold-fill processing capacity against snacking frequency trends and institutional procurement specifications across the projection horizon. Segmentation dimensions span product type, packaging format, flavor profile, and target consumer dietary specification, with CAGRs derived from regression analysis of historical refrigerated category growth rates and forward-looking clean-label adoption curves. Forecast inputs incorporate EFSA front-of-package nutrient profiling proposal timelines and diesel price volatility assumptions for refrigerated freight.
Several conditions sit outside the modeled scope, including extreme weather events affecting Montana and North Dakota chickpea yields, abrupt FDA health claim substantiation requirement changes, and trade policy shifts impacting tahini and olive oil import costs. Forecasts reflect documented assumptions about snacking frequency stability and school nutrition program funding continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
North America Snack Pellets Market
Snacks
Low Calorie Crackers Market
Snacks
South America Protein Bar Market
Snacks
Kale Chips Market
Snacks
Baked Chips Market
Snacks
US Potato Chips Market
Snacks
Crackers Market
Snacks
Super Low Calorie Snacks Market
Snacks
Gluten Free Snacks Market
Snacks
Healthy Fruit and Vegetable Chips Market
Snacks
Qatar Potato Chips Market
Snacks
Snack Products Market
Snacks
Italy Snack Bar Market
Snacks
Saudi Arabia Snacks Industry Market
Snacks
Fat Free Snacks Market
Snacks
Superfoods-Based Packaged Snacks Market