
 Asia Pacific Snack Food Market | 2026-2036
Asia Pacific Snack Food Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Snack Food Market Outlook
Asset-light contract manufacturing and third-party co-packing arrangements is narrowing the capital barrier for regional challengers in the Asia Pacific Snack Food Market. PepsiCo leverages its integrated potato procurement networks across India and Thailand to sustain cost leadership in savory chips. Haldiram anchors its competitive position through deep distribution into Indian railway stations, highway stops, and neighborhood kirana stores. Calbee specializes in extruded and cereal-based formats that dominate Japanese convenience retail and extend into Southeast Asian airports.
Asia Pacific snack food comprises processed, ready-to-eat consumables manufactured through frying, baking, extrusion, or air-popping, with shelf stability achieved via moisture control, lipid oxidation inhibitors, and modified atmosphere packaging. These products serve immediate consumption occasions ranging from transit breaks to workplace replenishment across dense urban populations. Chips and extruded snacks occupy the largest volume share due to their compatibility with local grain supplies and established production infrastructure. Flexible packs lead packaging demand as brands chase portion-control formats and reduced material cost per unit in price-sensitive markets.
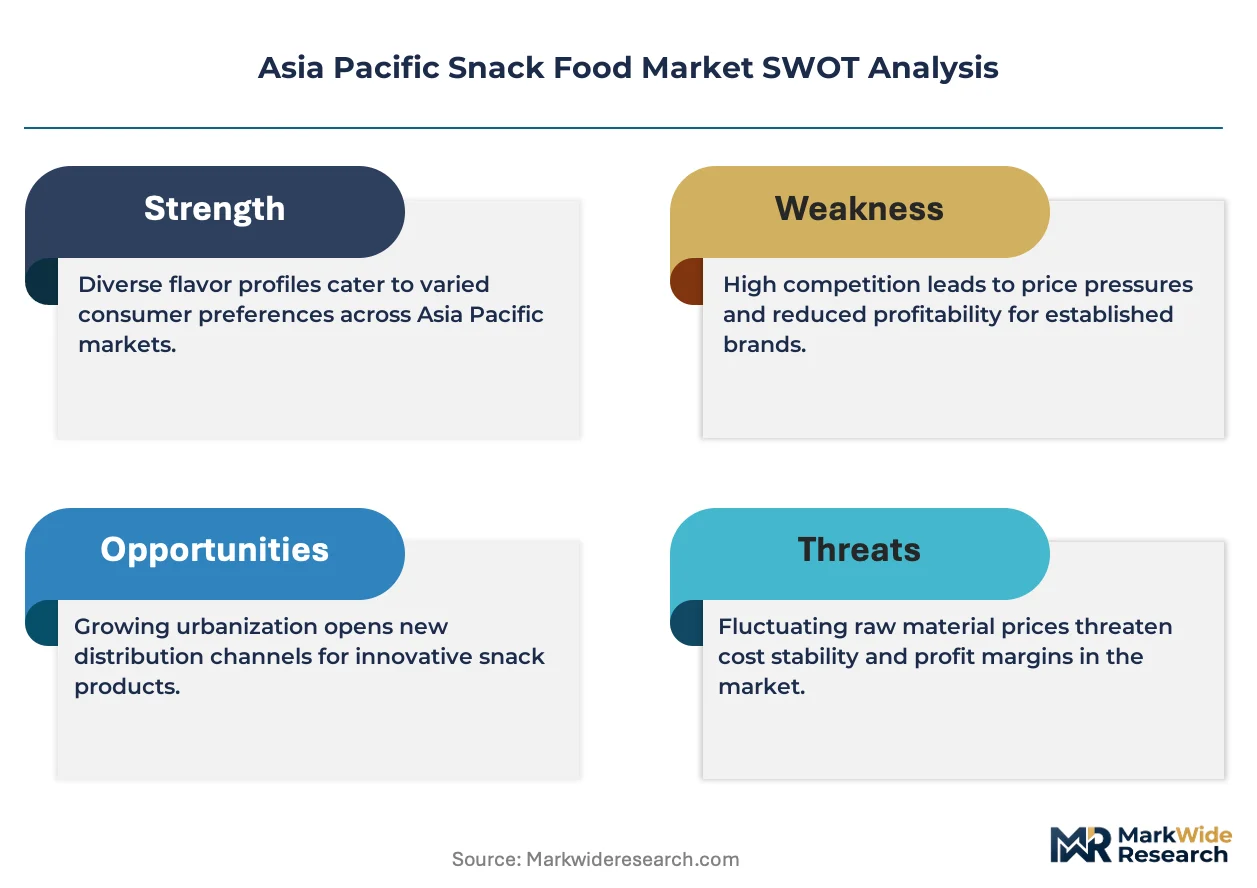
FSSAI in India enforces progressively stricter limits on trans fat content and front-of-pack labeling, while China's SAMR coordinates GB standard updates for additive usage in fried and baked categories. Both frameworks elevate compliance costs for informal producers and redirect volume toward organized manufacturers with in-house testing laboratories. Stakeholders must monitor how evolving extended producer responsibility rules across Indonesia, Thailand, and Vietnam reshape packaging material selection and reverse logistics obligations.
Market Dynamics
Urbanization across metropolitan India and China's Yangtze River Delta is compressing traditional meal occasions into portable, shelf-stable formats. FSSAI trans fat limits and China's GB additive standards are simultaneously elevating compliance thresholds while redirecting volume toward organized manufacturers with captive laboratory infrastructure.
Growth Catalysts
- Railway and transit retail penetration:Indian railway stations and highway corridors generate captive consumption windows where packaged snacks disperse through kirana networks and automated vending. This channel captures impulse purchases during commute breaks.
- FSSAI front-of-pack labeling mandates:India's progressive disclosure requirements for sodium, sugar, and saturated fat content are accelerating reformulation investments by organized manufacturers. Compliance capability now functions as a competitive moat against informal producers.
- Extrusion technology adoption:Air-popping and twin-screw extrusion systems enable local grain diversification beyond potato into rice, tapioca, and millet bases. Equipment suppliers report accelerating inquiries from Southeast Asian contract manufacturers.
Market Restraints
- Palm oil price volatility:Fried snack categories remain exposed to Malaysian and Indonesian palm oil futures swings. Margin compression during supply shocks disproportionately affects mid-tier brands lacking forward contracting discipline.
- Flexible film supply concentration:Biaxially oriented polypropylene substrate production clusters in China's Zhejiang and Guangdong provinces. Regional challengers face extended lead times and minimum order quantity constraints.
- Moisture barrier technical limits:Current metallized film structures struggle to maintain crispness beyond 180 days in tropical humidity conditions. Product returns in monsoon-affected distribution corridors erode brand equity.
Strategic Opportunities
- Vietnam central highlands penetration:Da Nang and Ho Chi Minh City convenience retail remains underdeveloped relative to Bangkok or Jakarta. Early movers can establish shelf space before modern trade consolidation accelerates.
- Extended producer responsibility tailwinds:Indonesia's packaging waste regulations and Thailand's reverse logistics mandates are creating first-mover advantages for brands with mono-material flexible film and deposit-return infrastructure.
- E-commerce quick commerce convergence:Swiggy Instamart and Zepto in India, alongside Meituan in China, are collapsing traditional distributor layers. Direct-to-dark-store fulfillment enables dynamic pricing and real-time inventory optimization.
Industry Challenges
- Food safety auditor scarcity:FSSAI-recognized third-party laboratories face capacity constraints. Certification backlogs delay product launches by 8-14 weeks for challengers without in-house testing.
- Legacy distributor integration friction:Modern trade and quick commerce platforms demand real-time inventory visibility. Traditional kirana-facing distributors lack ERP infrastructure for data exchange.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Snack Food Market |
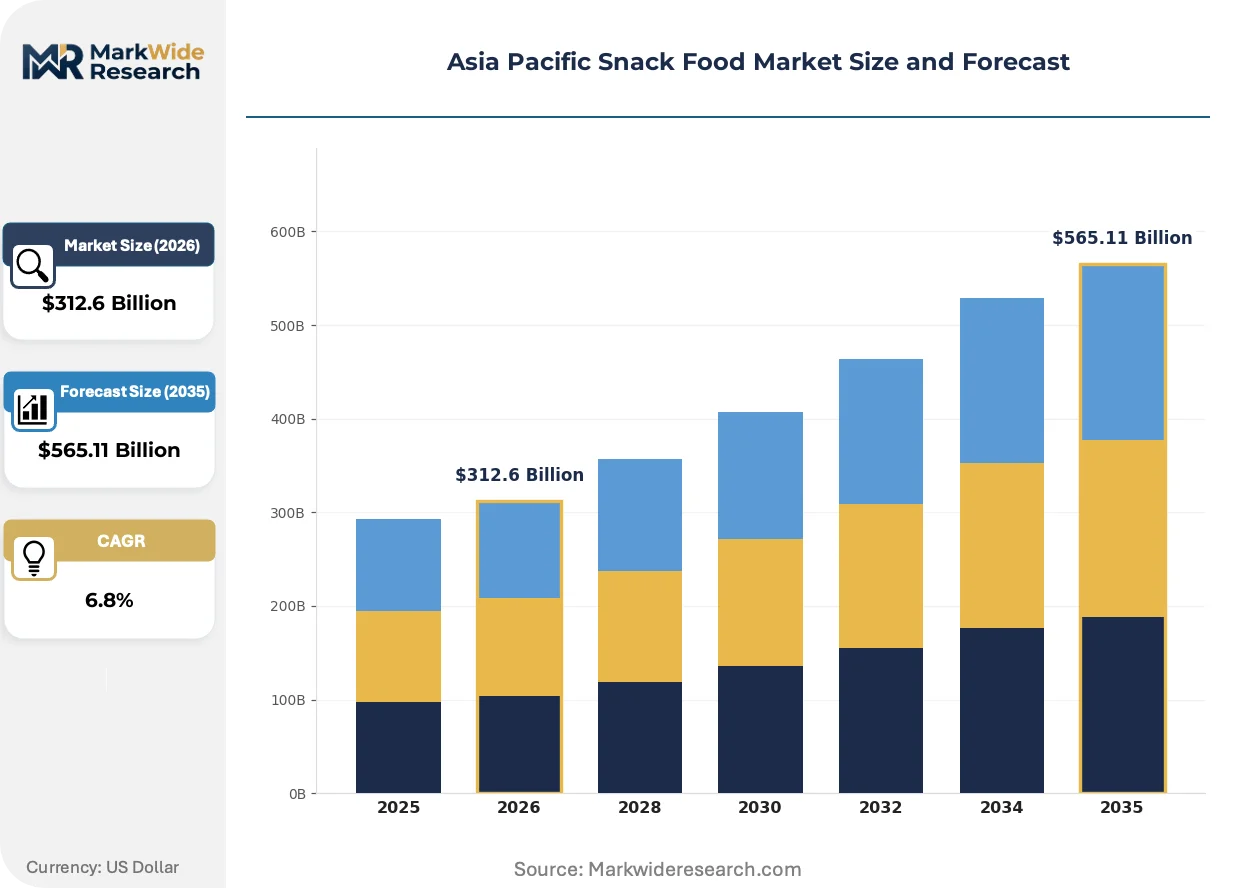
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Nuts, Popcorn, Extruded Snacks Flavor Profile: Savory, Sweet, Spicy, Tangy Packaging Type: Flexible Packs, Rigid Containers, Bags, Cans Sales Channel: Supermarkets, Online Retail, Convenience Stores, Snack Shops |
| Companies Covered | Mondelēz International, General Mills, PepsiCo, ITC Limited, Haldiram, Nestlé, Kellogg, Calbee, Unilever, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Snack Food Market Strategic Shifts
Reformulation chemistry and packaging material science are converging to extend shelf stability while satisfying tightening trans fat and additive regulations across India and China.
High-pressure processing applied to wet snacks and alternative protein bases is collapsing the traditional trade-off between extended shelf life and clean label positioning. Japanese convenience retail chains and Southeast Asian airport concessionaires are piloting HPP-treated chickpea and lentil formats. This technology is collapsing the premium price gap between preservative-laden mass market SKUs and refrigerated fresh alternatives.
China's SAMR coordination of GB 2760 additive standard revisions is restricting benzoate and sorbate usage in baked and fried categories. Domestic manufacturers are accelerating natural antioxidant sourcing from rosemary extract and green tea polyphenols. Fried potato and extruded rice segments in China's eastern provinces are absorbing the steepest compliance costs through supply chain restructuring.
Quick commerce platforms are fragmenting bulk purchasing into single-serve and twin-pack formats. Dark-store operators in Bangalore, Mumbai, and Jakarta are demanding 100-gram and 150-gram SKUs optimized for motorcycle delivery thermal bags. This pattern is most visible in Indian metropolitan zones where 10-minute delivery promises have compressed traditional weekly stock-up behavior into spontaneous replenishment cycles.
Asia Pacific Snack Food Market Segmentation
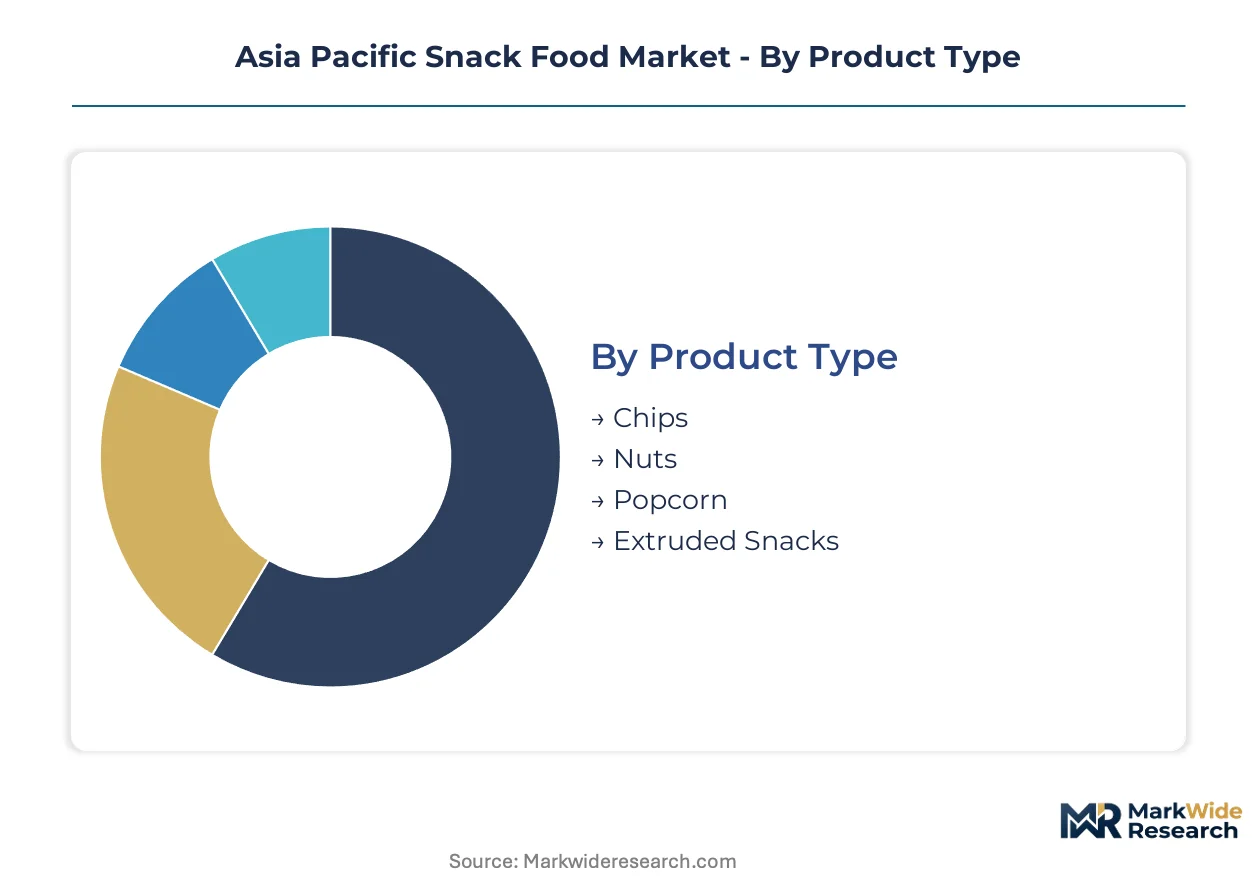
Segmentation in Asia Pacific snack food reveals how consumption occasions, regulatory exposure, and channel economics fragment addressable demand. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning across metropolitan India and Southeast Asian corridors.
Product Type:
Product format determines capital intensity, raw material sourcing radius, and shelf stability engineering requirements across the region.
- Chips:Thin-sliced potato or root vegetable formats fried or baked to sub-2% moisture content. Demand concentrates in India's tier-one cities and Thailand's Bangkok metro corridor where modern trade penetration supports premium price points and controlled atmosphere distribution.
- Extruded Snacks:Twin-screw processed puffs and rings from rice, tapioca, or millet bases with uniform cell structure. Japanese convenience retail chains and Southeast Asian airport concessionaires drive specifications for extended shelf stability in tropical humidity conditions.
- Nuts:Roasted, seasoned, or coated tree nuts and legumes requiring aflatoxin monitoring and moisture-controlled packaging.
- Popcorn:Air-popped or oil-popped formats with high expansion ratio sensitivity to kernel quality and storage conditions.
Chips holds installed capacity. Extruded Snacks is rotating up the share rankings.
Flavor Profile:
Flavor architecture reflects regional palate segmentation and reformulation complexity under tightening FSSAI and GB additive standards.
- Savory:Salt-forward profiles with umami enhancement from hydrolyzed proteins or yeast extracts. India's railway station kiranas and highway stops generate concentrated demand for single-serve savory formats during transit breaks.
- Spicy:Capsicum-derived heat levels calibrated to Scoville tolerance variations across Southeast Asian markets. Vietnam's Da Nang and Ho Chi Minh City convenience retail shows fastest adoption of extreme-heat variants among young urban professionals.
- Sweet:Sugar or alternative sweetener-based profiles requiring distinct moisture management and Maillard reaction control.
- Tangy:Acidulated citric or tamarind-based sour profiles with pH-dependent shelf stability constraints.
Savory dominates volume throughput. Spicy is climbing the fastest among flavor investments.
Packaging Type:
Packaging economics hinge on material science capabilities, extended producer responsibility compliance, and quick commerce thermal bag compatibility.
- Flexible Packs:Metallized or clear biaxially oriented polypropylene with moisture and oxygen barrier layers. Dark-store operators in Bangalore, Mumbai, and Jakarta specify 100-gram and 150-gram flexible formats optimized for motorcycle delivery and spontaneous replenishment cycles.
- Bags:Multi-layer structures with reseal features for portion control in household consumption occasions.
- Rigid Containers:Injection-molded or thermoformed plastics with structural protection for fragile formats.
- Cans:Metal or composite cylinders for premium gifting segments and extended ambient stability requirements.
Flexible Packs commands production line investment. Bags is gaining share fastest through quick commerce fragmentation.
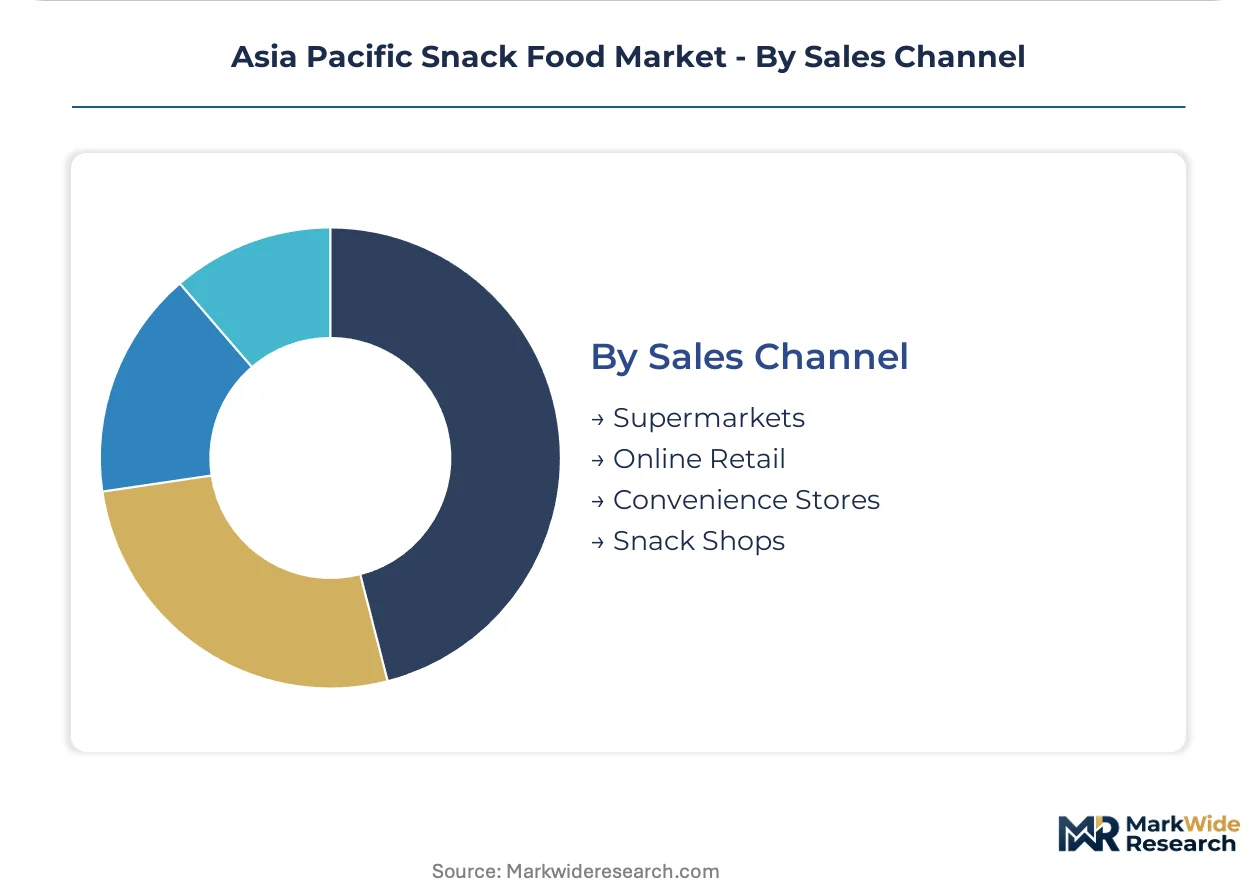
Sales Channel:
Channel selection determines distributor capability requirements, inventory visibility standards, and pricing architecture flexibility.
- Convenience Stores:24-hour urban formats with limited SKU count and high turnover velocity. China's Yangtze River Delta manufacturing corridor and Indonesia's Jakarta satellite cities show dense convenience store penetration capturing workplace replenishment occasions.
- Supermarkets:Large-format modern trade with category management discipline and promotional calendar dependency.
- Online Retail:E-commerce platforms with warehousing economics and last-mile delivery cost structures.
- Snack Shops:Traditional specialized outlets with local brand concentration and limited cold chain integration.
Convenience Stores anchors shelf space negotiations. Online Retail is expanding most quickly through quick commerce convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young urban professionals in metropolitan India and China's Yangtze River Delta corridor concentrate snack food purchasing power. Transit-oriented consumption and workplace replenishment occasions compress traditional meal patterns into portable formats. Regulatory tightening across FSSAI and GB standards elevates compliance costs that favor organized manufacturers with captive laboratory infrastructure.
India
Tier-one cities generate concentrated demand for convenient packaged formats among commuting professionals. FSSAI mandates progressively stricter trans fat limits and front-of-pack labeling disclosures for sodium and sugar content. Mumbai and Delhi-NCR manufacturing corridors absorb the steepest reformulation investments as organized players build in-house testing capacity.
China
The Yangtze River Delta manufacturing corridor anchors savory chip and extruded snack production capacity. SAMR coordinates GB standard updates that restrict benzoate and sorbate usage in fried and baked categories. Shanghai and Jiangsu province facilities accelerate natural antioxidant sourcing from rosemary extract and green tea polyphenols.
Japan
Convenience retail chains and airport concessionaires drive specifications for extended shelf stability in tropical humidity conditions. METI oversees food contact material standards and extended producer responsibility frameworks. Tokyo-Osaka metropolitan zones pilot high-pressure processing for chickpea and lentil alternative protein formats.
Vietnam
Da Nang and Ho Chi Minh City convenience retail remains underdeveloped relative to Bangkok or Jakarta, creating shelf space opportunities. The country's national food safety authority enforces progressive packaging waste regulations and reverse logistics mandates. Central highlands distribution corridors show fastest adoption of extreme-heat spicy variants among young urban professionals.
Indonesia
Jakarta satellite cities demonstrate dense convenience store penetration capturing workplace replenishment occasions. Extended producer responsibility rules reshape packaging material selection toward mono-material flexible films. Java-based manufacturing clusters face minimum order quantity constraints from biaxially oriented polypropylene suppliers in China's Zhejiang province.
Asia Pacific Snack Food Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tier structures. The market organizes around three archetypes: integrated procurement networks with captive raw material sourcing, deep distribution penetrators into transit and neighborhood retail, and extrusion technology specialists dominating convenience formats. Dominant competitive moves include strategic partnerships with quick commerce platforms and portfolio diversification into alternative protein bases.
Within the integrated procurement tier, PepsiCo anchors cost leadership through potato sourcing networks across India and Thailand. Haldiram occupies a position exemplifying deep distribution penetration into railway stations, highway stops, and kirana stores. Calbee represents the extrusion technology specialist archetype with cereal-based formats dominating Japanese convenience retail and Southeast Asian airport channels.
| Leading Market Players |
|---|
| Mondelēz International |
| General Mills |
| PepsiCo |
| ITC Limited |
| Haldiram |
| Nestlé |
| Kellogg |
| Calbee |
| Unilever |
| Others |
Value Chain & Pricing Dynamics
Zhejiang and Guangdong provinces concentrate biaxially oriented polypropylene substrate production, granting incumbent packaging suppliers outsized leverage over regional snack brands negotiating flexible film contracts. This upstream concentration cascades into downstream pricing power asymmetries that favor organized manufacturers with forward contracting discipline and captive laboratory infrastructure for FSSAI and GB compliance testing.
Pricing Analysis
Cost-plus contracts indexed to Malaysian and Indonesian palm oil futures dominate fried snack procurement agreements between mid-tier brands and contract manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates organized players with in-house testing from informal producers and from modern trade private labels. Pricing pressure stems from palm oil volatility that compresses margins for brands lacking forward hedging programs. Kirana-facing distributors in India's tier-two corridors exhibit highest price sensitivity, while Japanese convenience retail chains absorb premium positioning for extended shelf stability formats.
Supply Chain Analysis
Upstream feedstock flows center on potato sourcing networks across India and Thailand, rice and tapioca bases from Southeast Asian contract manufacturers, and natural antioxidant extracts from rosemary and green tea polyphenol suppliers in China's eastern provinces. Raw material dependencies include palm oil from Malaysia and Indonesia, metallized film substrates from China's Zhejiang cluster, and millet bases from India's central highlands. Single-source vulnerability concentrates in biaxially oriented polypropylene supply from China's coastal provinces. Distribution runs through kirana networks and railway station concessionaires in India, convenience retail chains in Japan, and quick commerce dark stores in metropolitan Southeast Asian corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward quick commerce platforms and modern trade consolidators, fragmenting traditional distributor influence while concentrating volume among data-capable purchasing entities. This consolidation among downstream buyers demands defensive repositioning from incumbents and targeted white-space entry from challengers.
For Market Incumbents: Pre-empt quick commerce platform disintermediation by building direct dark-store fulfillment capabilities in Bangalore, Mumbai, and Jakarta. Secure backward integration into natural antioxidant sourcing from rosemary extract and green tea polyphenol suppliers before GB standard revisions tighten additive restrictions. Channel control through captive kirana network data exchange infrastructure functions as the priority defensive lever against platform consolidation. For New Entrants and Emerging Players: Vietnam's central highlands convenience retail corridors offer shelf space availability before modern trade consolidation accelerates in Da Nang and Ho Chi Minh City. Contract manufacturing partnerships with twin-screw extrusion equipment owners in Thailand and Indonesia bypass capital-intensive production investment. Go-to-market through railway station and highway stop kiranas in India's tier-one corridors captures impulse transit consumption with lower modern trade slotting fee exposure. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-arbitrage play because FSSAI and GB standard tightening systematically displaces informal producers toward organized manufacturers with captive laboratory infrastructure. Acquisition targets should display in-house testing capability, mono-material flexible film packaging readiness for extended producer responsibility rules, and established quick commerce platform relationships. Monitor FSSAI certification backlog durations as an early signal of competitive moat widening or narrowing.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Flexible Film Transition | Indonesia's packaging waste regulations and Thailand's reverse logistics mandates reward early compliance with deposit-return infrastructure. |
| Quick Commerce Platform Partnership | Swiggy Instamart and Zepto in India collapse distributor layers and enable real-time inventory optimization for dark-store fulfillment. |
| Natural Antioxidant Supply Integration | China's SAMR benzoate and sorbate restrictions in GB 2760 accelerate sourcing from rosemary extract and green tea polyphenol suppliers. |
| High-Pressure Processing Pilot Expansion | Japanese convenience retail chains and Southeast Asian airport concessionaires pilot HPP-treated chickpea formats collapsing premium-fresh price gaps. |
| Central Highlands Distribution Buildout | Vietnam's Da Nang and Ho Chi Minh City convenience retail underpenetration creates first-mover shelf space before modern trade consolidation. |
Study Parameters
Operator-level perspectives from brand managers at organized manufacturers, category buyers at quick commerce platforms, FSSAI-recognized laboratory directors, and procurement leads at flexible film suppliers anchored the qualitative base. Secondary validation drew from FSSAI regulatory filings, SAMR GB standard documentation, Nielsen retail audit data for Indian metropolitan corridors, and customs records for palm oil and polypropylene substrate trade flows. Bottom-up SKU-level volume modeling triangulated against top-down category expenditure estimates across the analysis window.
Scenario-bracketing around palm oil price volatility bands, regulatory compliance cost trajectories, and quick commerce penetration rates structured the analytical framework. Segmentation dimensions modeled include product format, flavor profile, packaging type, and sales channel across metropolitan India, China's Yangtze River Delta, and Southeast Asian convenience retail corridors. CAGRs were derived from installed capacity utilization rates, per-capita consumption trend extrapolation, and channel shift elasticity parameters. Forecast inputs incorporated FSSAI trans fat limit phase-in schedules and extended producer responsibility rule implementation timelines.
Practitioners should monitor palm oil futures volatility, FSSAI certification backlog durations, and quick commerce dark-store expansion cadence for early signals of forecast revision necessity. Forecasts reflect assumptions regarding regulatory implementation timelines, commodity price stabilization patterns, and platform consolidation trajectories. Quarterly review of FSSAI laboratory capacity utilization, Malaysian palm oil inventory reports, and quick commerce SKU proliferation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Poland Snack Bar Market
Snacks
North America Fruit Snacks Market
Snacks
Better for You Snacks Market
Snacks
Global Vegetable Chips Market
Snacks
Thailand Snack Bar Market
Snacks
Low Calorie Snacks Market
Snacks
Europe Snack Pellets Market
Snacks
Superfoods-Based Packaged Snacks Market
Snacks
Meat Protein Chips Market
Snacks
Fruit Jerky Market
Snacks
Extruded Snacks Market
Snacks
No-Fat Peanut Butter Market
Snacks
Potato Chips Market
Snacks
Low Calorie Crackers Market
Snacks
Veggie Chips Market
Snacks
Brazil Snack Bar Market