
 Sodium Propionate Market | 2026-2036
Sodium Propionate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Propionate Market Outlook
Ingredient-as-a-service contracting is restructuring how sodium propionate suppliers monetize their output, shifting from bulk chemical sales toward integrated preservation solutions bundled with technical support. Niacet Corporation leverages its North American manufacturing footprint to sustain long-term supply agreements with industrial bakeries. Corbion differentiates through fermentation-derived propionate technology that reduces synthetic additive labeling in European applications. Shandong Tongtai Weirun Chemical Co., Ltd. dominates cost-sensitive Asian markets through integrated acetic acid-to-propionate production.
Sodium propionate is the sodium salt of propionic acid, manufactured primarily through neutralization of propionic acid with sodium hydroxide to yield a white crystalline powder with minimum assay specifications typically exceeding 99 percent. The compound functions as a mold inhibitor and preservative, extending shelf life in baked goods and preventing spoilage in processed animal feed. Food Grade material anchors the value pool due to stringent purity requirements and higher pricing relative to feed and industrial grades, while Pharmaceutical Grade represents the fastest-expanding segment driven by excipient demand in tablet formulations. Application concentration in baking reflects the segment's volume scale, though animal feed preservation is gaining structural importance as livestock operations consolidate procurement.
EFSA maintains maximum permitted levels for propionates in bread and fine bakery wares under EU food additive regulations, while the FDA governs GRAS status and labeling requirements in United States commerce. China's SAMR enforces GB standards for food-grade preservatives that govern import access for foreign suppliers. Stakeholders must monitor regulatory divergence between jurisdictions on clean-label thresholds and synthetic preservative restrictions to align product positioning with evolving compliance frameworks.
Market Dynamics
European EFSA purity mandates are compressing supplier margins while simultaneously rewarding fermentation-derived propionate producers with clean-label positioning advantages over synthetic counterparts.
Growth Catalysts
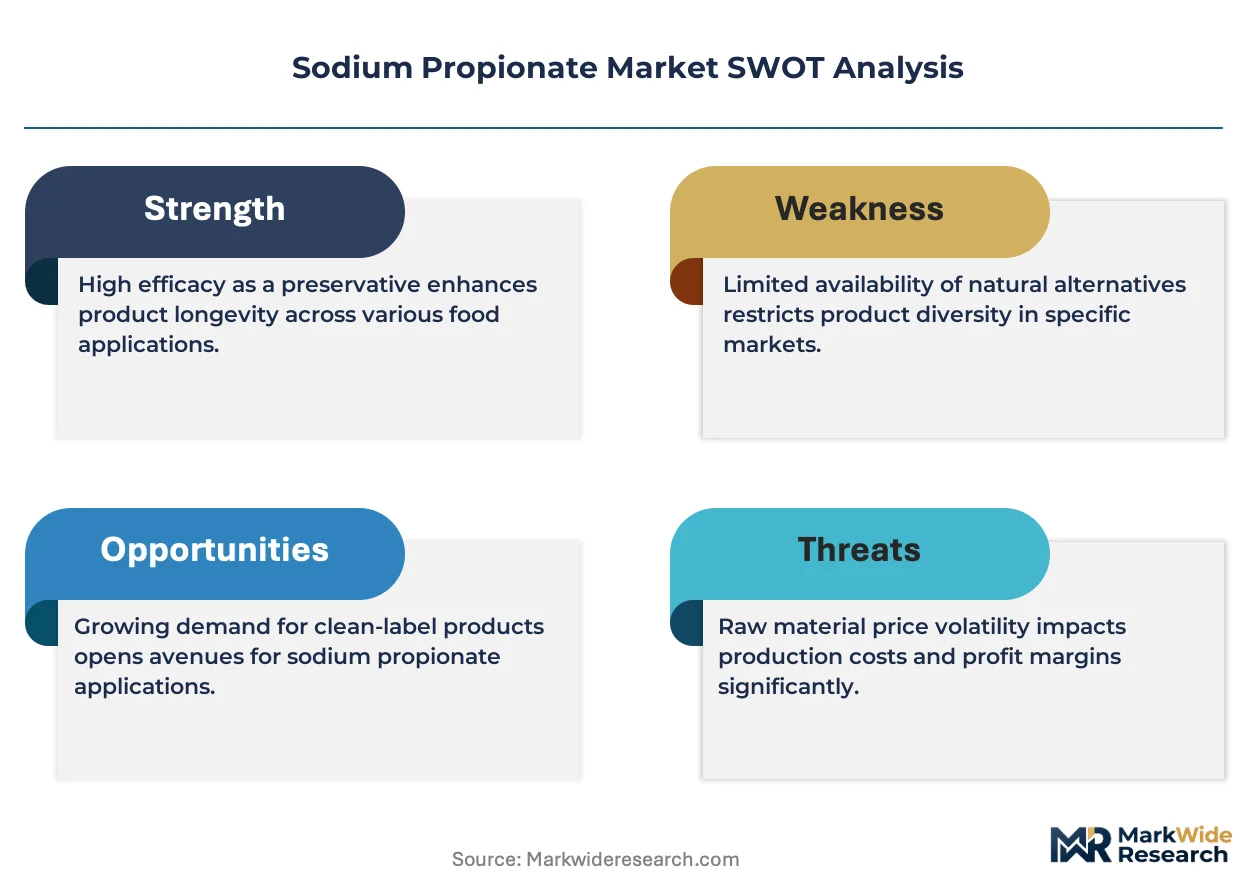
- EFSA Regulatory Stringency:Tighter food additive purity specifications under EU Regulation 1333/2008 are disqualifying marginal producers and consolidating volume among certified suppliers capable of meeting updated assay thresholds.
- Industrial Baking Concentration:Germany's Ruhr-Rhine bakery corridor is expanding sodium propionate offtake as automated production lines require standardized preservation inputs at industrial scale.
- Feed Sector Consolidation:Large livestock operations are centralizing procurement of mold inhibitors for compound feed, creating dedicated demand channels distinct from fragmented food-grade distribution.
Market Restraints
- Propionic Acid Feedstock Volatility:Petroleum-derived propionic acid prices fluctuate with naphtha cracking economics, compressing margin predictability for neutralization-based sodium propionate manufacturers.
- Clean-Label Substitution Pressure:Fermentation-based cultured wheat and vinegar blends are capturing shelf-life extension share in premium bakery segments sensitive to E-number disclosure.
- Chinese Supply Concentration:Shandong Province hosts disproportionate acetic acid-to-propionate integrated capacity, creating geographic single-point vulnerability for cost-sensitive Asian buyers.
Strategic Opportunities
- Pharmaceutical Excipient Expansion:Tablet formulation manufacturers are qualifying sodium propionate as a disintegrant and pH buffer, opening higher-margin channels outside commodity food preservation.
- India FSSAI Alignment:India's food safety regulator is harmonizing preservative standards with Codex Alimentarius, enabling import substitution opportunities for compliant foreign suppliers.
- Bioprocess Technology Convergence:Fermentation-derived propionate production is integrating with carbon capture feedstock streams, offering synthetic-free labeling compatible with EU Green Deal circular economy frameworks.
Industry Challenges
- Pharmaceutical Grade Certification Timelines:USP-NF and EP monograph compliance requires 18-24 month validation cycles that delay excipient market entry and tie up analytical chemistry resources.
- Legacy Equipment Retrofit Costs:Synthetic propionate plants face capital-intensive upgrades to segregate fermentation-derived product streams for clean-label certification without cross-contamination risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Propionate Market |
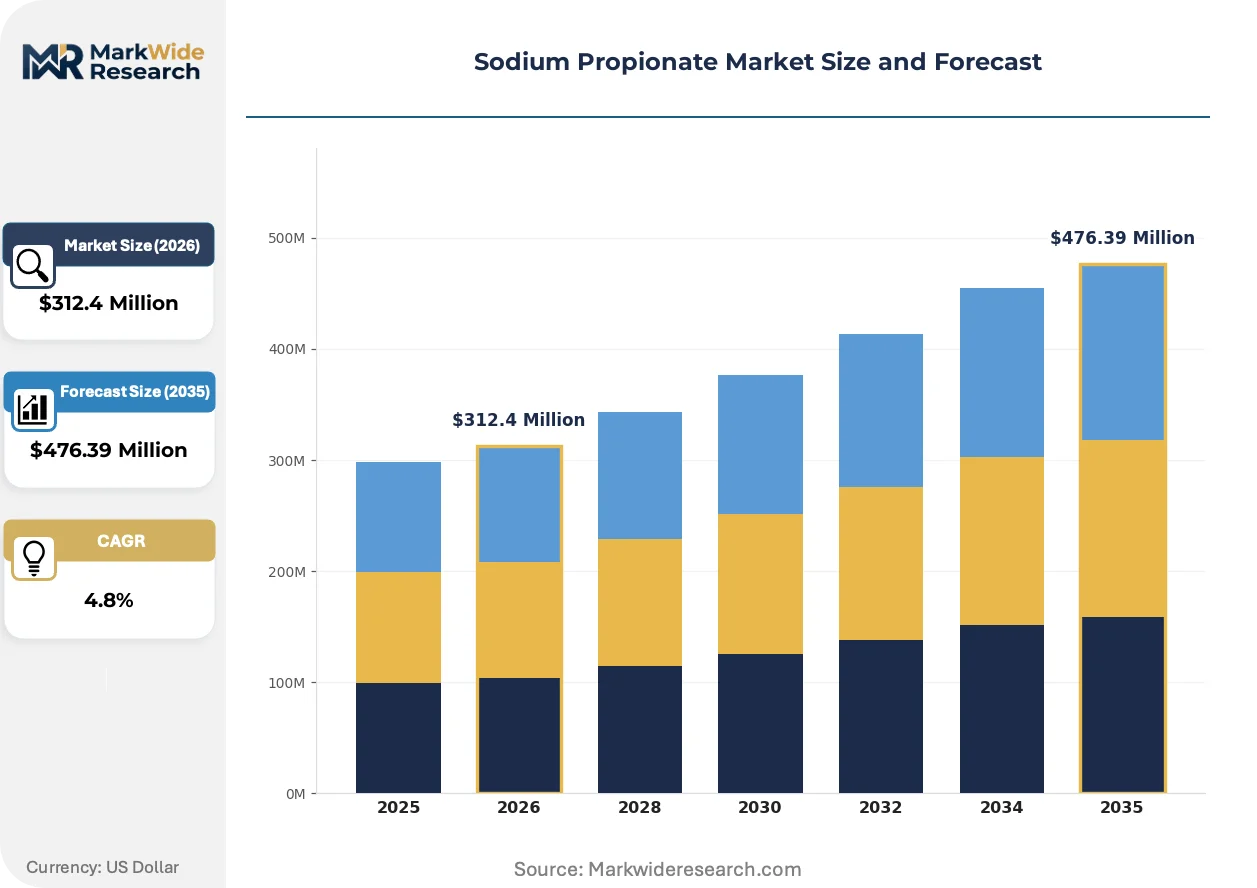
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Feed Grade, Pharmaceutical Grade, Industrial Grade Application: Baking, Preservation, Animal Feed, Pharmaceuticals End User: Food Manufacturers, Animal Feed Producers, Pharmaceutical Companies, Chemical Manufacturers Distribution Channel: Online Retailers, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Niacet Corporation, Prathista Industries Ltd, Macco Organiques Inc., Fine Organic Industries Ltd, Dr. Paul Lohmann GmbH KG, Foodchem International Corporation, Shandong Tongtai Weirun Chemical Co., Ltd., Corbion, Bailin Group Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Propionate Market Strategic Shifts
Preservation chemistry is bifurcating between synthetic efficiency and biological provenance, with supplier business models adapting to capture value from technical service bundling rather than commodity volume alone.
Fermentation-derived propionate technology is integrating synthetic biology platforms with traditional dairy propionibacteria cultures to achieve commercial yields competitive with petrochemical routes. European industrial bakeries are adopting this material fastest, pressured by retailer clean-label mandates that disadvantage E281 synthetic designation. The structural consequence is compressing price premiums between fermentation and synthetic grades as scale economies emerge.
EU Regulation 2023/915 on contaminants in food is tightening maximum residue limits for processing aids used in preservative manufacture. This regulatory friction is forcing sodium propionate suppliers to requalify upstream chemical inputs and document supply chain purity at intermediate manufacturing stages. Fine bakery wares with extended shelf-life claims face the most intensive audit scrutiny, driving consolidation toward integrated producers with captive analytical capabilities.
Ingredient-as-a-service contracting is displacing spot bulk purchasing among multinational bakery groups seeking guaranteed preservation performance rather than commodity chemical inputs. Technical support teams now embed within customer R&D facilities to customize propionate blends for specific water activity and pH parameters. This behavioral shift is most pronounced in Germany and the Netherlands, where industrial baking R&D concentration supports dedicated supplier personnel deployment.
Sodium Propionate Market Segmentation
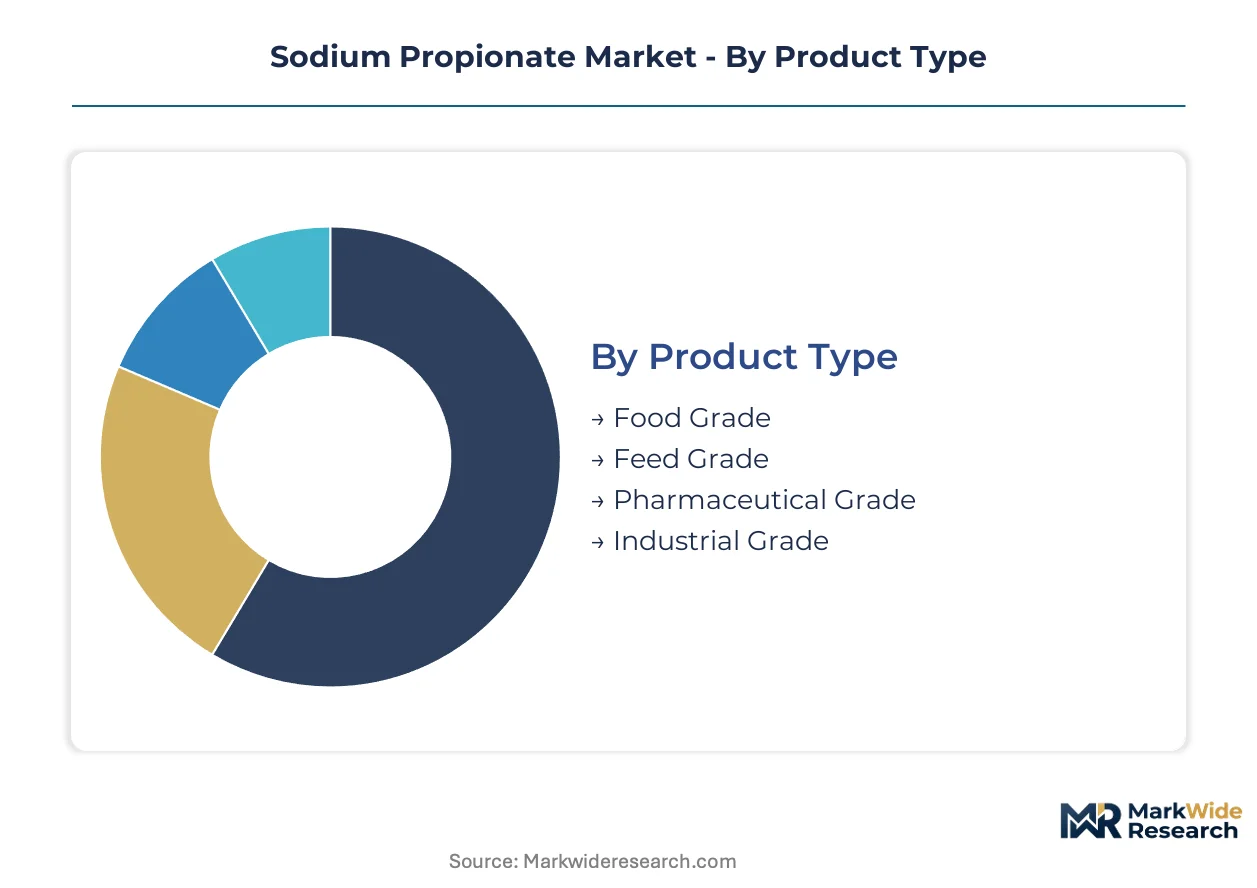
Sodium propionate suppliers face divergent capital requirements across grade certifications, with pharmaceutical validation demanding analytical infrastructure that food-grade neutralization plants cannot readily replicate. Segmentation discipline separates commodity volume plays from margin-protected specialty positions.
Product Type:
Capital intensity escalates sharply from industrial neutralization through pharmaceutical-grade validation cycles, with certification timelines and analytical equipment requirements defining competitive moats.
- Food Grade:Neutralization reactors and crystallization systems constitute baseline manufacturing infrastructure. Germany's industrial baking corridor concentrates offtake as EFSA purity mandates under EU Regulation 1333/2008 compress margins for uncertified suppliers.
- Pharmaceutical Grade:USP-NF and EP monograph compliance demands 18-24 month validation cycles with dedicated QC laboratories and segregated production streams. Tablet formulation manufacturers in North America and Europe are qualifying sodium propionate as a disintegrant and pH buffer, opening excipient channels outside commodity food preservation.
- Feed Grade:Compound feed preservation tolerates broader assay tolerances than food applications, with procurement centralizing among large livestock operations in the US Midwest and Brazilian feedlot belts.
- Industrial Grade:Chemical synthesis and leather tanning applications accept technical-grade specifications with minimal regulatory burden, sourcing predominantly from Shandong Province integrated acetic acid-to-propionate producers.
Most installed capacity flows through Food Grade. Expansion is steepest in Pharmaceutical Grade.
Application:
Application segmentation tracks moisture sensitivity and pH parameters, with water activity thresholds determining propionate dosage precision and technical service intensity.
- Baking:Automated production lines in Germany's Ruhr-Rhine corridor require standardized preservation inputs calibrated to specific dough chemistries. Ingredient-as-a-service contracting is displacing spot bulk purchasing among multinational bakery groups seeking guaranteed shelf-life performance.
- Preservation:Processed meat and dairy applications face accelerating clean-label substitution pressure from fermentation-based cultured wheat and vinegar blends in premium European retail channels.
- Animal Feed:Mold inhibition in compound feed concentrates procurement among consolidated livestock operations, creating dedicated demand channels distinct from fragmented food-grade distribution networks.
- Pharmaceuticals:Excipient demand is climbing fastest as tablet manufacturers seek pH buffering and disintegrant functionality, though qualification timelines delay volume conversion.
Volume concentration remains in Baking. Steepest expansion trajectory belongs to Pharmaceuticals.
End User:
End-user segmentation reflects procurement sophistication, with technical integration requirements separating formulation partners from commodity buyers.
- Food Manufacturers:Industrial bakeries embed supplier technical teams within R&D facilities to customize propionate blends for specific water activity parameters, concentrating this behavior in Germany and the Netherlands.
- Animal Feed Producers:Large integrated livestock operations centralize mold inhibitor procurement, negotiating long-term supply agreements that bypass traditional distributor markups.
- Pharmaceutical Companies:Qualification protocols and monograph compliance requirements extend sales cycles but lock in multi-year excipient supply positions with limited supplier switching.
- Chemical Manufacturers:Industrial synthesis applications prioritize feedstock cost and logistics reliability over technical service, sourcing through spot markets and bulk terminal arrangements.
Procurement scale concentrates among Food Manufacturers. Technical integration intensity is climbing fastest with Pharmaceutical Companies.
Distribution Channel:
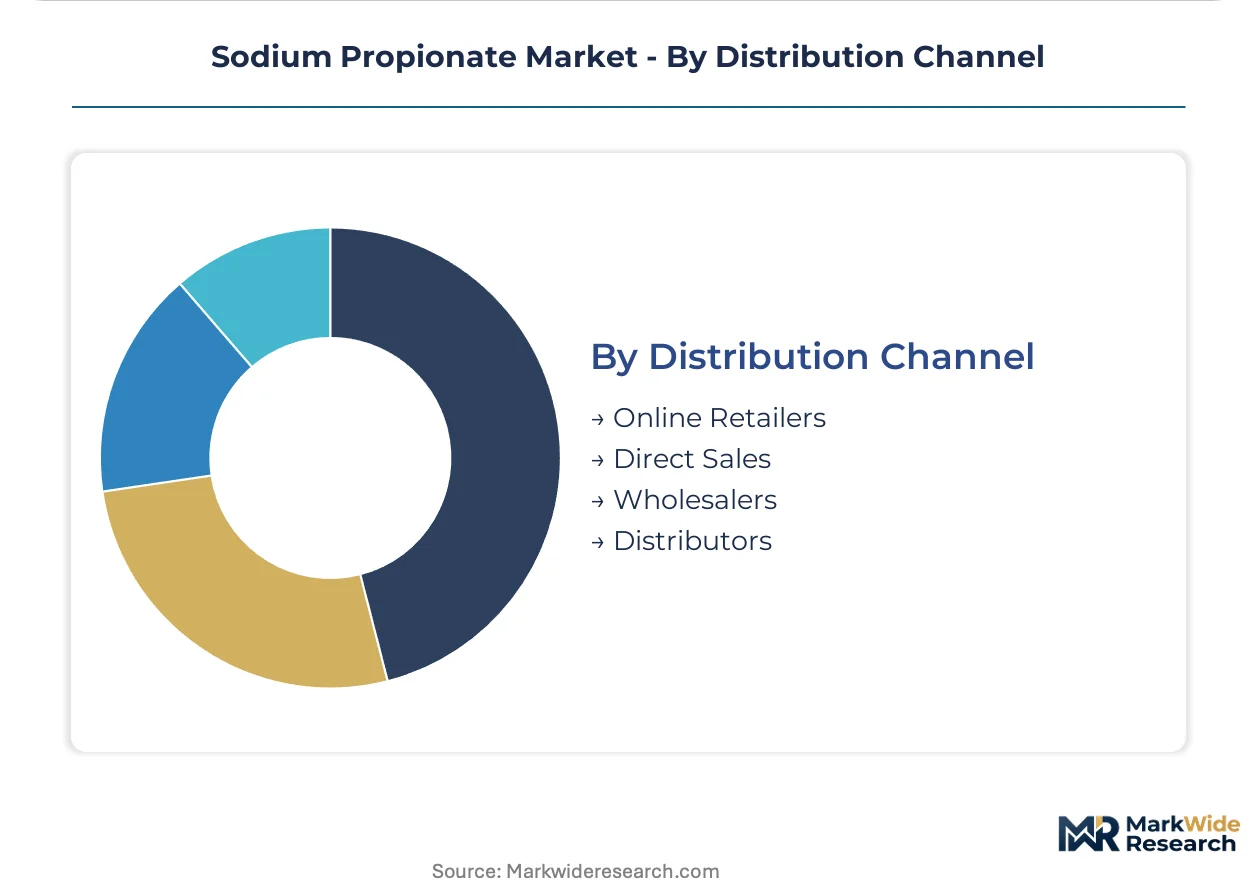
Channel segmentation tracks customer scale and technical support requirements, with direct relationships commanding premium positioning.
- Direct Sales:Multinational bakery groups and pharmaceutical formulators negotiate long-term agreements with dedicated technical support, bypassing distributor margins.
- Distributors:Regional chemical distributors serve mid-scale food manufacturers requiring smaller lot sizes and local inventory positioning.
- Wholesalers:Feed-grade volume moves through agricultural supply cooperatives in livestock-producing regions, consolidating fragmented farm-level demand.
- Online Retailers:Laboratory and small-scale industrial buyers source pharmaceutical and industrial grades through specialized chemical marketplaces with documented certificates of analysis.
Volume flows predominantly through Direct Sales. Digital channel penetration is expanding most quickly in laboratory and specialty chemical procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing sodium propionate production capacity toward jurisdictions with lower cost-of-compliance structures, even as EFSA purity mandates in Europe compress margins for uncertified suppliers.
United States
Industrial bakeries in the Midwest and Southeast are consolidating procurement of mold inhibitors through long-term supply agreements. FDA GRAS status governs preservative labeling requirements for interstate commerce. Chicago's automated baking corridor anchors domestic demand as multinational groups embed supplier technical teams within R&D facilities.
Germany
EFSA's updated food additive regulations under EU Regulation 1333/2008 are disqualifying marginal producers from the Ruhr-Rhine bakery corridor. The country's national food safety regulator enforces assay thresholds that reward fermentation-derived propionate with clean-label positioning. Stuttgart's industrial baking R&D concentration supports dedicated supplier personnel deployment for customized preservation blends.
China
Shandong Province's integrated acetic acid-to-propionate producers dominate cost-sensitive Asian markets through captive feedstock supply. SAMR enforces GB standards for food-grade preservatives that govern import access for foreign suppliers. Qingdao's chemical manufacturing cluster concentrates neutralization-based capacity serving domestic feed and industrial applications.
India
FSSAI harmonization with Codex Alimentarius standards is enabling import substitution opportunities for compliant foreign suppliers in processed food preservation. The country's national food safety regulator is tightening maximum residue limits for processing aids. Maharashtra's industrial bakery belt is expanding automated production lines requiring standardized preservation inputs.
Brazil
Large livestock operations in the feedlot belts of São Paulo and Minas Gerais are centralizing mold inhibitor procurement for compound feed. ANVISA governs preservative approvals for food and pharmaceutical applications. Campinas' agricultural supply cooperatives consolidate fragmented farm-level demand through wholesale distribution channels.
Sodium Propionate Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with fermentation-derived producers capturing premium positioning in European clean-label channels while synthetic neutralization specialists defend volume in cost-sensitive Asian markets. The vendor base organizes around three archetypes: integrated petrochemical producers with captive propionic acid supply, fermentation technology specialists leveraging biological provenance for regulatory advantage, and regional neutralization plants serving feed-grade commodity demand. Dominant competitive moves include backward integration into propionic acid feedstock and technology licensing partnerships to access fermentation-derived production platforms without capital-intensive plant retrofits.
Among North American preservation specialists, Niacet Corporation occupies a position within the integrated manufacturing tier, while Netherlands-based Corbion exemplifies the fermentation-technology archetype through its biological propionate platforms. Chinese producers Shandong Tongtai Weirun Chemical Co., Ltd. and Bailin Group Co., Ltd. anchor the cost-optimized neutralization segment. Fine Organic Industries Ltd represents India's emerging position in food-grade preservative supply. Dr. Paul Lohmann GmbH KG sits within the pharmaceutical-grade validation tier where USP-NF and EP monograph compliance creates extended qualification barriers.
| Leading Market Players |
|---|
| Niacet Corporation |
| Prathista Industries Ltd |
| Macco Organiques Inc. |
| Fine Organic Industries Ltd |
| Dr. Paul Lohmann GmbH KG |
| Foodchem International Corporation |
| Shandong Tongtai Weirun Chemical Co., Ltd. |
| Corbion |
| Bailin Group Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
EFSA's updated purity mandates under EU Regulation 1333/2008 are forcing industrial bakeries to requalify suppliers against stricter assay thresholds, compressing acceptable sourcing pools and amplifying pricing power for certified fermentation-derived producers capable of clean-label positioning.
Pricing Analysis
Distributor margins in regional chemical supply chains are compressing as multinational bakery groups negotiate direct long-term agreements that bundle technical support with volume commitments. Three-tier pricing structure across pharmaceutical, food, and feed grades reflects certification burden and analytical infrastructure requirements. Pricing pressure stems from petroleum-derived propionic acid feedstock volatility tied to naphtha cracking economics. Feed-grade buyers exhibit highest price sensitivity, while pharmaceutical formulators prioritize monograph compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Shandong Province's integrated acetic acid-to-propionate producers, which anchor cost-sensitive Asian supply. Manufacturing concentrates in China, Germany, and the Netherlands, with fermentation-derived capacity clustering around European dairy propionibacteria feedstock streams. Raw material dependencies include propionic acid, sodium hydroxide, and dairy culture media. Tariff exposure on Chinese chemical imports threatens margin stability for Western neutralization plants. Distribution runs through direct technical partnerships for multinational food manufacturers and agricultural cooperatives for fragmented feed-grade demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation technology scale economies and pharmaceutical-grade certification premiums are expanding margin capture opportunities for suppliers capable of escaping commodity food-grade pricing dynamics.
For Market Incumbents: To counter clean-label substitution pressure from cultured wheat and vinegar blends, synthetic propionate producers should retrofit legacy neutralization plants for segregated fermentation-derived streams while deepening captive propionic acid supply through backward integration into petrochemical or bioprocess feedstock sources. For New Entrants and Emerging Players: Capture pharmaceutical excipient qualification pipelines in North America and Europe, where USP-NF and EP monograph compliance creates extended barriers that lock out commodity producers and enable premium positioning through dedicated analytical chemistry capabilities and regulatory affairs specialization. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation-technology specialists possessing validated biological propionate platforms and established clean-label supply relationships with European industrial bakeries, as regulatory stringency amplifies their structural advantage over synthetic incumbents facing capital-intensive retrofit cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Platform Scale-Up | Bioprocess capacity expansion enables synthetic-free labeling aligned with EU Green Deal circular economy frameworks. |
| Pharmaceutical Grade Certification | USP-NF and EP monograph compliance opens excipient channels with multi-year supply lock-ins and limited switching. |
| Backward Integration into Propionic Acid | Captive feedstock supply insulates margin stability from petroleum-derived input volatility and naphtha cracking economics. |
| Ingredient-as-a-Service Contracting | Technical team embedding within customer R&D facilities displaces spot bulk purchasing with performance-guaranteed partnerships. |
| Geographic Capacity Expansion | India FSSAI alignment with Codex Alimentarius enables import substitution positioning in Maharashtra's industrial bakery belt. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at propionate neutralization facilities, procurement leads at industrial bakeries and pharmaceutical formulators, distribution channel partners in regional chemical supply networks, and technical R&D directors at fermentation technology specialists with secondary validation against customs and trade data, Cefic chemical industry reports, SEC 10-K filings from listed suppliers, and EFSA regulatory guidance documents. Bottom-up capacity assessments and top-down demand modeling were triangulated to anchor volume estimates.
Segment-weighting approaches applied differential growth assumptions across pharmaceutical grade, food grade, feed grade, and industrial grade tiers, with application splits modeled for baking, preservation, animal feed, and pharmaceuticals end-uses. CAGRs were derived from regression analysis of historical price-volume relationships and forward projection of regulatory-driven substitution effects. Forecast inputs included EFSA purity mandate implementation timelines, pharmaceutical excipient qualification pipeline visibility, and livestock operation consolidation patterns in compound feed procurement.
Propionic acid feedstock cost volatility, regulatory divergence on clean-label thresholds between jurisdictions, and fermentation technology yield improvements are the dominant revision risks that could shift trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
France Food Enzymes Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Synthetic Food Preservatives Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Food Grade Glue Market
Food Additives and Ingredients
Carob Gum Market
Food Additives and Ingredients
Film Forming Starches Market
Food Additives and Ingredients
Carrageenan Market
Food Additives and Ingredients
Dairy Stabilizer Market
Food Additives and Ingredients
Russia Food Enzymes Market
Food Additives and Ingredients
United Kingdom Food Additives Market
Food Additives and Ingredients
Egypt Food Enzymes Market
Food Additives and Ingredients
North America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Italy Food Enzymes Market
Food Additives and Ingredients
Middle East and Africa Food Anti Caking Agents Market
Food Additives and Ingredients
France Feed Additives Market