
 Fiber Bars Market | 2026-2036
Fiber Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Bars Market Analysis
Sports nutrition departments is realigning fiber bar procurement toward higher-protein formulations. Pultron Composites leverages its materials science heritage to anchor composite reinforcement applications adjacent to food-grade fiber technologies. SGL Carbon SE sustains specialized carbon fiber operations that inform broader fiber bar structural engineering. Röchling Group dominates industrial polymer processing with capabilities that extend into high-performance fiber composite manufacturing.
Fiber bars are extruded or molded food products containing soluble and insoluble dietary fibers at concentrations typically exceeding three grams per serving, designed to deliver satiety, digestive health benefits, and macronutrient supplementation in portable formats. Protein fiber bars occupy the premium tier with higher margin pools and dedicated shelf space at health food stores, while snack fiber bars compete on velocity through convenience store channels with faster inventory turns. Single-serve packs lead packaging type demand in on-the-go consumption contexts, though multi-pack boxes generate stronger unit economics through club and online retail formats.
The FDA governs nutrition labeling and health claims under the Federal Food, Drug, and Cosmetic Act, while EFSA evaluates novel fiber ingredients and substantiation requirements in Europe, with both frameworks elevating barrier costs for new entrants. The USDA organic certification and Non-GMO Project verification create parallel compliance tracks that influence ingredient sourcing decisions and supplier qualification timelines. Stakeholders must monitor evolving fiber intake guidance from WHO and national health agencies to anticipate reformulation cycles and positioning shifts ahead of regulatory revisions.
Market Dynamics
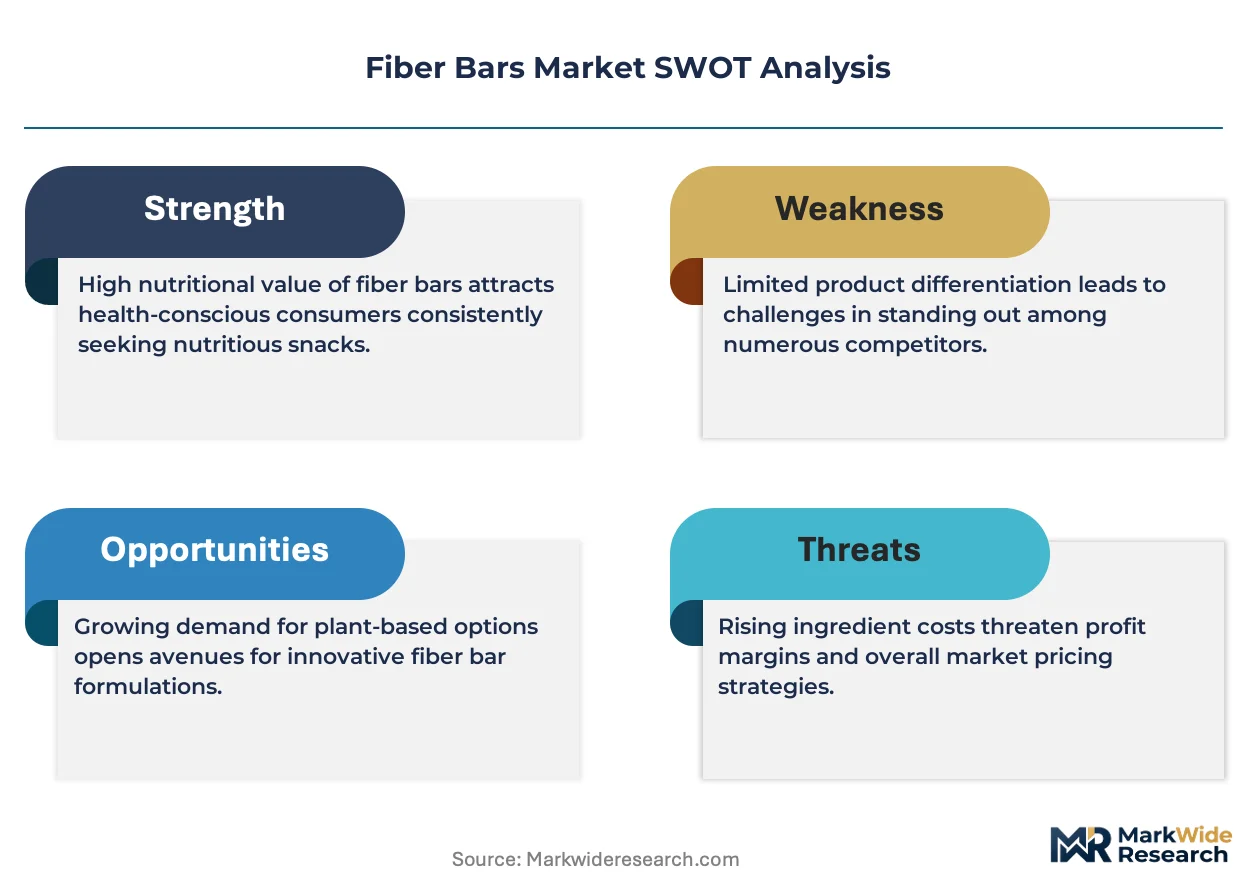
The FDA and EFSA clean-label mandates are forcing simultaneous reformulation of fiber bar ingredient decks and packaging claims, compressing product development cycles while elevating compliance costs for manufacturers across all tiers.
Growth Catalysts
- Collegiate Sports Nutrition Expansion:Athletic departments at major universities are expanding dedicated procurement budgets for protein-fiber bars, creating institutional demand anchors with multi-year supply agreements.
- REACH-Compliant Fiber Innovation:EFSA novel fiber ingredient approvals are unlocking new soluble fiber sources that deliver enhanced digestive health claims with substantiated clinical backing.
- China Functional Food Policy:SAMR regulations permitting dietary fiber health claims are accelerating domestic production capacity and import substitution for premium fiber bar formats.
Market Restraints
- Prebiotic Fiber Input Volatility:Inulin and resistant starch supply chains concentrate in Belgian and Chilean processing facilities, exposing manufacturers to weather-driven crop yield fluctuations and ocean freight rate spikes.
- USDA Organic Certification Bottlenecks:Three-year transition requirements for organic ingredient sourcing extend supplier qualification timelines, freezing out mid-tier brands from premium shelf positioning.
- Plant Protein Digestibility Limits:Pea and rice protein blends in high-fiber matrices create texture and palatability ceilings that constrain protein loading beyond twenty grams per serving without sensory degradation.
Strategic Opportunities
- Germany Precision Fermentation:Novel microbial fiber production methods are reducing land-use intensity and enabling customized fiber chain-length profiles for targeted gut microbiome applications.
- Direct-to-Consumer Subscription Models:Personalized nutrition platforms are bypassing traditional retail slotting fees, capturing recurring revenue with algorithm-driven flavor and fiber-type customization.
- India Functional Snack White Space:FSSAI regulatory clarity on dietary fiber fortification is opening packaged food channels previously dominated by unorganized street snack vendors.
Industry Challenges
- Clean-Label R&D Talent Scarcity:Formulation chemists with dual expertise in sensory science and regulatory compliance command premium compensation, stretching mid-cap R&D budgets.
- Non-GMO Project Verification Backlogs:Six-to-nine-month audit queues are delaying product launches and freezing marketing commitments for brands dependent on third-party certification credibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Bars Market |
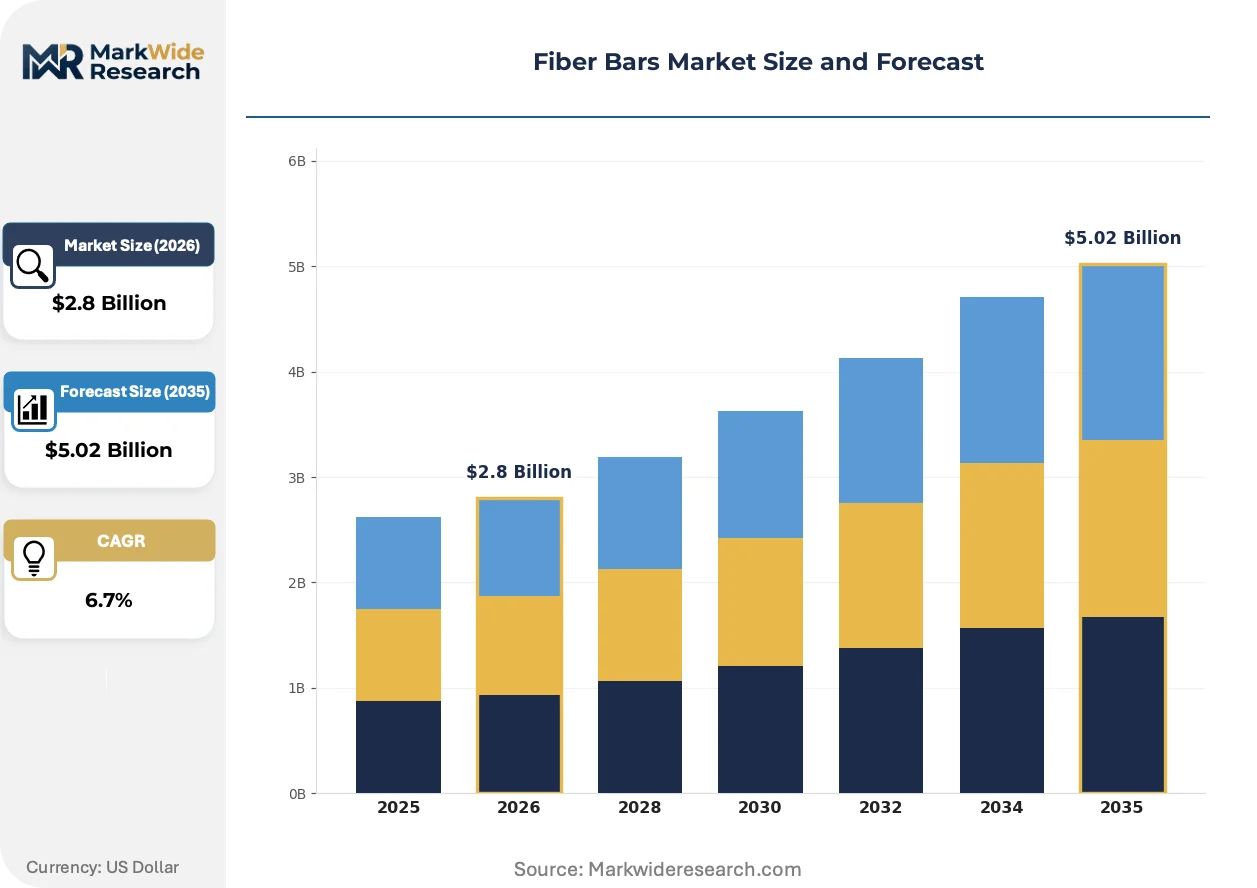
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Fiber Bars, Meal Replacement Bars, Snack Fiber Bars, Dietary Fiber Bars Ingredient Type: Whey Protein, Pea Protein, Oats, Nuts Packaging Type: Single-Serve Packs, Multi-Pack Boxes, Resealable Bags, Bulk Packaging Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Convenience Stores |
| Companies Covered | Schöck Bauteile GmbH, Neuvokas Corporation, Dextra Group, SGL Carbon SE, Armastek, Pultron Composites, Kodiak Fiberglass Rebar, Röchling Group, Pultrall Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Bars Market Emerging Trajectories
Reformulation chemistry and packaging engineering are converging to address the tension between shelf-stable convenience and clean-label ingredient transparency that dominates consumer purchase decisions.
Precision fermentation-derived dietary fibers are integrating into mainstream fiber bar production, enabling customized molecular structures that deliver targeted fermentation rates in the gut microbiome. Sports nutrition brands are adopting these ingredients at accelerated pace to differentiate premium protein-fiber lines. This technology is integrating functional customization capabilities that compress the gap between pharmaceutical-grade precision and mass-market snack accessibility.
EFSA's updated guidance on substantiation of digestive health claims is tightening evidentiary requirements for prebiotic fiber marketing across European markets. Manufacturers must now commission human intervention studies rather than relying on in vitro fermentation data, elevating R&D spend thresholds. Protein-fiber bars positioned with gut health claims face the steepest compliance burden, driving consolidation among brands with insufficient clinical trial budgets.
Health food retailers are unbundling bulk multi-pack formats into single-serve trial sizes at checkout counters, compressing consumer experimentation cycles and accelerating flavor preference data collection. This channel innovation displaces traditional velocity-based shelf allocation with algorithmic replenishment tied to real-time consumption analytics. Germany and the United States show the most advanced deployment of this demand-sensing infrastructure.
Fiber Bars Market Segmentation
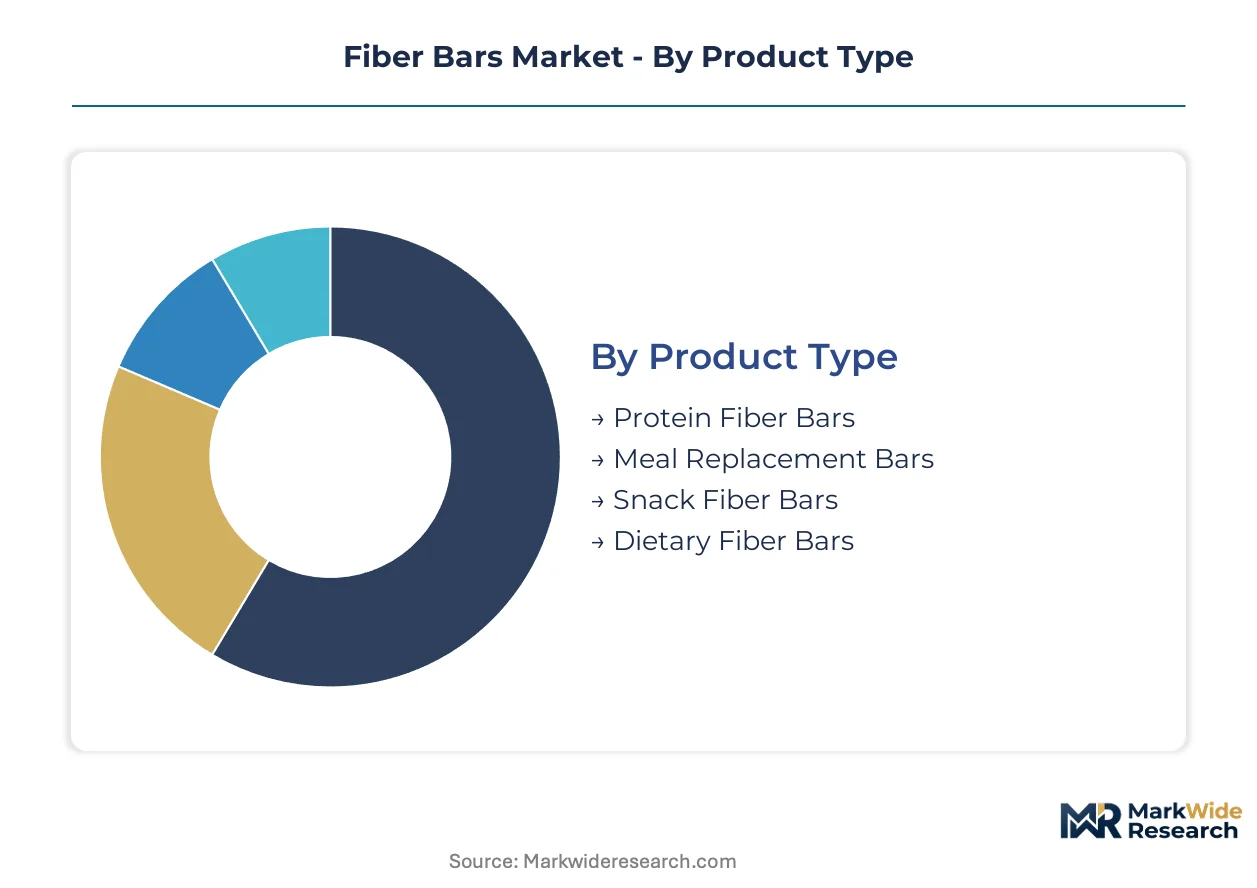
Fiber bar manufacturers configure production lines around distinct nutritional positioning and consumption occasions. Segmentation discipline separates premium protein formulations from velocity-driven snack formats, each demanding different ingredient sourcing, packaging capital, and channel economics.
Product Type:
Capital intensity peaks with protein fiber bars requiring specialized extrusion and cold-forming equipment, while snack formats run on lower-cost conventional bar lines.
- Protein Fiber Bars:Cold-pressed or extruded matrices combining soluble fiber with 15-25g protein per serving. Collegiate athletic departments in the United States anchor procurement with multi-year supply agreements, though pea protein digestibility limits constrain formulation flexibility above 20g protein loads.
- Meal Replacement Bars:Higher caloric density with balanced macronutrient profiles and micronutrient fortification. Germany's precision fermentation sector supplies novel fiber inputs for these premium formulations, enabling customized gut microbiome targeting that commands shelf space at health food retailers.
- Snack Fiber Bars:Lower protein, higher velocity formats optimized for convenience store distribution. Single-serve packs dominate impulse purchase occasions.
- Dietary Fiber Bars:Clinical positioning around digestive health with substantiated prebiotic claims. EFSA evidentiary requirements elevate R&D spend thresholds for European market entry.
Most installed capacity flows through Snack Fiber Bars. Expansion is steepest in Protein Fiber Bars.
Ingredient Type:
Raw material qualification timelines stretch longest for organic-certified inputs, freezing mid-tier brands out of premium positioning.
- Whey Protein:Dairy-derived complete amino acid profiles with superior bioavailability. Supply chains concentrate in Wisconsin and New Zealand processing facilities, exposing manufacturers to dairy commodity cycles and sustainability scrutiny.
- Pea Protein:Plant-based alternative with lower allergenicity but textural limitations in high-fiber matrices. Chinese domestic production capacity is expanding under SAMR functional food regulations, reducing import dependence for Asia-Pacific brands.
- Oats:Beta-glucan soluble fiber source with established cholesterol health claims. USDA organic certification bottlenecks extend supplier qualification to three-year transition cycles.
- Nuts:Almond and cashew inclusions deliver crunch texture and unsaturated fat content. California water stress and Chilean freight volatility squeeze margin stability.
Ingredient sourcing concentrates in Whey Protein for margin capture. Pea Protein is climbing the fastest as plant-based positioning gains shelf allocation.
Packaging Type:
Packaging capital allocation reflects channel strategy divergence between trial-driven single-serve and loyalty-driven multi-unit formats.
- Single-Serve Packs:Individual flow-wrapped units for on-the-go consumption. Checkout counter placement at health food retailers in Germany and the United States accelerates flavor experimentation cycles through algorithmic replenishment.
- Multi-Pack Boxes:Club retail and online subscription formats with stronger unit economics. Amazon and Costco procurement specifications drive corrugated and board material compliance costs.
- Resealable Bags:Flexible pouches for portion-controlled consumption. Barrier film specifications balance shelf stability against clean-label transparency demands.
- Bulk Packaging:Foodservice and institutional formats for collegiate athletic programs. Palletization and case-count optimization reduce per-unit logistics burden.
Production volume concentrates in Single-Serve Packs. Subscription-driven Multi-Pack Boxes are expanding most quickly.
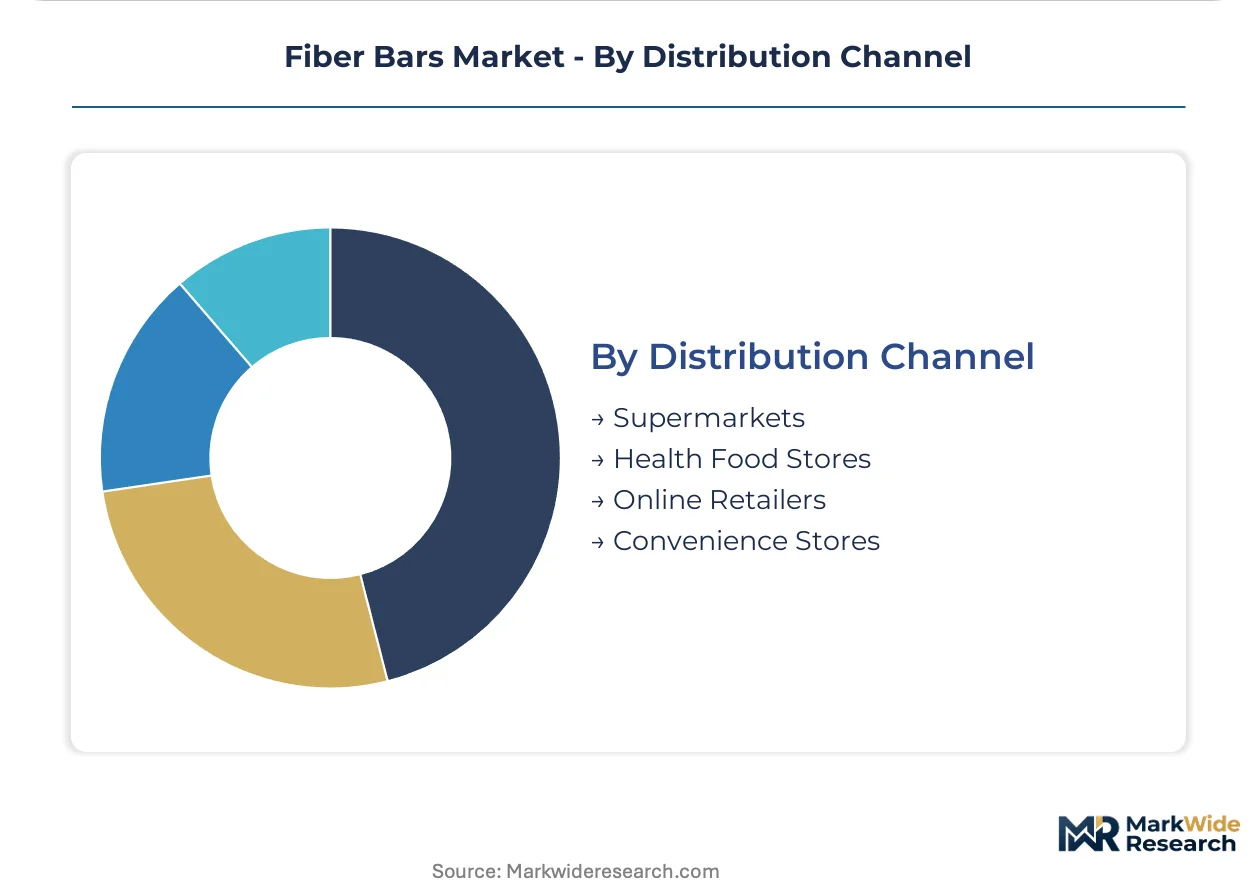
Distribution Channel:
Channel selection determines slotting fee exposure, margin structure, and consumer data access for personalization algorithms.
- Supermarkets:Mass-market reach with high slotting fee barriers and velocity-based shelf allocation. Clean-label R&D talent scarcity stretches mid-cap brand budgets for retailer-specific compliance.
- Health Food Stores:Premium positioning with educated consumers and tolerance for higher price points. Germany and United States retailers deploy demand-sensing infrastructure for real-time replenishment.
- Online Retailers:Direct-to-consumer subscription models bypass traditional slotting fees. Algorithm-driven flavor customization captures recurring revenue with reduced customer acquisition costs.
- Convenience Stores:Impulse-driven velocity with rapid inventory turns. Snack fiber bars compete here on price-per-ounce against conventional candy and chip alternatives.
Revenue concentration sits with Supermarkets. Online Retailers are gaining share fastest as subscription infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting fiber bar production toward jurisdictions with streamlined novel ingredient approval pathways. Manufacturers are relocating R&D and pilot-scale operations to exploit gaps between FDA substantiation timelines and EFSA fast-track mechanisms for precision-fermentation fibers.
United States
Collegiate athletic departments in Texas and California are expanding dedicated procurement budgets for protein-fiber bars with multi-year supply agreements. The FDA governs nutrition labeling under the Federal Food, Drug, and Cosmetic Act, elevating barrier costs for new entrants. Wisconsin anchors whey protein processing infrastructure, while Greater Boston clusters precision-fermentation startups developing customized fiber chain-length profiles.
Germany
Health food retailers in Berlin and Munich deploy demand-sensing infrastructure for real-time replenishment of premium fiber bar formats. EFSA evaluates novel fiber ingredients under tightened evidentiary requirements for digestive health claims. The precision fermentation sector in Baden-Württemberg supplies microbial fiber inputs that enable targeted gut microbiome applications for meal replacement bars.
China
SAMR regulations permitting dietary fiber health claims are accelerating domestic production capacity in the Yangtze River Delta. Pea protein processing clusters in Shandong Peninsula are expanding under functional food policy support to reduce import dependence. Shanghai-based brands are capturing premium positioning through direct-to-consumer subscription models with algorithm-driven customization.
India
FSSAI regulatory clarity on dietary fiber fortification is opening packaged food channels in Maharashtra and Karnataka previously dominated by unorganized street snack vendors. The PLI scheme for food processing incentivizes capacity expansion in Gujarat. Mumbai and Bangalore anchor emerging demand for snack fiber bars through modern retail and quick-commerce platforms.
Brazil
São Paulo and Minas Gerais concentrate ingredient sourcing for inulin and resistant starch derivatives from regional chicory and cassava processing. ANVISA governs novel food ingredient approvals with timelines that attract South American headquarters functions. The Southeast region clusters contract manufacturing capacity serving export markets with USDA organic-certified production lines.
Fiber Bars Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium protein-fiber lines consolidating around clinical substantiation capabilities while snack formats fragment across regional co-packers. Three structural tiers have emerged: multinational ingredient suppliers with captive bar production, mid-cap brands with dedicated R&D facilities, and private-label specialists serving retail banners. M&A activity concentrates on precision-fermentation fiber startups and organic-certified ingredient processors. Geographic expansion into India and Brazil dominates strategic planning.
Among Germany-based industrial specialists, Schöck Bauteile GmbH and Röchling Group exemplify the materials science heritage that informs adjacent fiber composite capabilities. SGL Carbon SE anchors specialized carbon fiber operations with structural engineering expertise transferable to high-performance applications. Pultron Composites occupies a position within precision manufacturing archetypes that bridge industrial polymer processing and food-grade fiber technology development.
| Leading Market Players |
|---|
| Schöck Bauteile GmbH |
| Neuvokas Corporation |
| Dextra Group |
| SGL Carbon SE |
| Armastek |
| Pultron Composites |
| Kodiak Fiberglass Rebar |
| Röchling Group |
| Pultrall Inc. |
| Others |
Supply Flow & Price Mechanics
Captive sourcing of organic-certified ingredients anchors both supply security and premium pricing power for fiber bar manufacturers navigating USDA three-year transition requirements. This vertical integration into ingredient production insulates premium tier brands from commodity volatility while compressing procurement timelines for clean-label formulations.
Pricing Analysis
Retailer markup layers stratify across premium, standard, and economy tiers, with health food stores extracting higher margins on protein-fiber bars positioned with clinical substantiation. Price differentiation hinges on certification grade — USDA organic and Non-GMO Project verification command shelf space premiums — and volume scale, where club retail multi-packs dilute per-unit economics. Cost compression in snack fiber bars is intensifying because convenience store channels prioritize velocity over margin, squeezing mid-tier brands without captive production. Collegiate athletic procurement shows lowest price sensitivity due to multi-year supply agreement structures.
Supply Chain Analysis
Ocean freight rate volatility from Belgian inulin processors and Chilean resistant starch facilities transmits directly into landed cost structures for North American manufacturers. Geographic supply concentration centers on Belgium for chicory-derived prebiotic fibers, China for pea protein expansion under SAMR functional food policy, and Wisconsin for whey protein processing infrastructure. Raw material dependencies include inulin, pea protein isolates, and beta-glucan oat extracts. Single-source vulnerability in Belgian chicory processing creates bottleneck exposure. Distribution runs through health food retailers with demand-sensing replenishment, club retail for multi-pack formats, and direct-to-consumer subscription platforms bypassing traditional slotting fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fiber bar demand is shifting toward precision-fermentation ingredients with customized gut microbiome targeting, elevating quality specifications as the defining competitive axis. This premium specification migration favors manufacturers with clinical substantiation capabilities and captive fermentation capacity.
For Market Incumbents: Lock in multi-year supply agreements with collegiate athletic departments before precision-fermentation startups scale alternative protein-fiber formulations. Deepen backward integration into organic-certified ingredient sourcing to circumvent USDA three-year transition bottlenecks freezing out mid-tier competitors. Prioritize EFSA-compliant clinical trial investment for digestive health claims, as tightened evidentiary requirements will consolidate European market share around substantiated brands.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms represent the most penetrable channel architecture, bypassing supermarket slotting fees that consume thirty to forty percent of wholesale revenue for conventional entrants. Target algorithm-driven flavor customization as the go-to-market angle, capturing recurring revenue through personalized nutrition platforms with lower customer acquisition costs than retail velocity plays.
For Investors and Strategic Acquirers: Roll-up economics work for precision-fermentation fiber startups because EFSA and FDA regulatory barriers prevent rapid replication of clinical substantiation assets, creating durable moats around approved novel ingredients. Long-term viability centers on platform consolidation of microbial fiber production capabilities with established bar manufacturing infrastructure. Watch FDA novel fiber ingredient approval timelines as the inflection signal — acceleration would unlock premium positioning for early-mover fermentation platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Baden-Württemberg microbial fiber production enables customized chain-length profiles for targeted gut health applications. |
| Direct-to-Consumer Subscription Launch | Algorithm-driven flavor customization captures recurring revenue while bypassing health food retailer slotting fee structures. |
| USDA Organic Certification Investment | Three-year transition timeline completion secures premium shelf positioning inaccessible to non-certified competitors. |
| Collegiate Athletic Supply Agreement | Texas and California university procurement anchors institutional demand with multi-year volume commitments. |
| EFSA Clinical Trial Commissioning | Human intervention study investment satisfies tightened digestive health claim substantiation requirements ahead of competitor compliance. |
Methodological Framework
Coverage spans the United States, Germany, China, and India, with primary inputs from each market cluster combined with secondary validation. Interviews engaged fiber bar brand managers, health food retailer category buyers, collegiate athletic nutrition directors, precision-fermentation R&D leads, and organic ingredient procurement specialists. Secondary sources included FDA nutrition labeling guidance documents, EFSA novel food approval registers, SAMR functional food regulations, FSSAI fortification standards, and USDA organic certification databases. Bottom-up demand modeling triangulated against top-down market sizing from trade flow analysis.
Rate-of-change decomposition separated volume expansion from value premium capture across the projection horizon. Segmentation dimensions modeled include product type tier, ingredient certification grade, packaging format, and distribution channel economics. CAGRs derived from regression analysis of historical procurement patterns, collegiate athletic program budget disclosures, and regulatory approval velocity. Industry-specific inputs incorporated precision-fermentation scale-up curves and EFSA evidentiary requirement compliance timelines.
Underlying measurement precision varies by segment; protein fiber bars with established collegiate procurement contracts carry tighter precision than emerging precision-fermentation ingredient categories. Forecasts reflect assumptions around regulatory approval velocity, organic certification transition completion rates, and ocean freight cost normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Global Snack Food Market
Snacks
Organic Snack Food Market
Snacks
United Kingdom Energy Bar Market
Snacks
Better for You Snacks Market
Snacks
US Potato Chips Market
Snacks
Dried Fruit Snacks Market
Snacks
Europe Snack Pellets Market
Snacks
South America Cereal Bar Market
Snacks
UAE Snack Bar Market
Snacks
North America Fruit Snacks Market
Snacks
Baked Chips Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Fat Free Snacks Market
Snacks
North America Cereal Bar Market
Snacks
Saudi Arabia Snacks Industry Market
Snacks
Low Fat Protein Snacks Market