
 Global Protein Snack Market | 2026-2036
Global Protein Snack Market Size, Share, and Industry Trends Forecast 2026-2036
Global Protein Snack Market Outlook
Market Context
North American dairy processing capacity is restructuring as whey protein isolate output expands to serve bar and chip manufacturers. Nestlé S.A. leverages its pharmaceutical-grade filtration infrastructure to supply high-purity protein isolates for co-manufacturing partnerships. PepsiCo Inc. sustains shelf dominance through direct-store-delivery networks that control convenience channel placement. Tyson Foods Inc. anchors its position in jerky through captive livestock supply chains and smokehouse automation.
Technical Definition and Segment Structure
Global protein snacks comprise shelf-stable, ready-to-eat foods delivering 10–20 grams of protein per serving through extruded, baked, or dried matrices designed for satiety and muscle recovery. Manufacturing employs high-moisture extrusion for plant crisps, low-temperature dehydration for jerky, and cold-pressed bar forming to preserve amino acid bioavailability. Bars occupy the largest revenue pool due to format familiarity and premium price positioning, while pea protein formulations within the ingredient type dimension represent the fastest structural expansion as allergen-free positioning opens retail access. Online retail as a distribution channel captures disproportionate growth velocity as subscription models reduce customer acquisition costs for direct-to-consumer specialists.
Regulatory Framework and Outlook
FDA nutrition labeling rules and EFSA health claim assessments shape permissible protein content declarations and marketing language across the United States and European Union. China's SAMR enforces GB standards for imported protein products, creating compliance thresholds that filter market entrants. India's FSSAI mandates protein percentage disclosure on front-of-pack labels, tightening formulation transparency. Stakeholders must monitor evolving plant protein novel food approvals as regulatory divergence between jurisdictions threatens unified product portfolios.
Market Dynamics
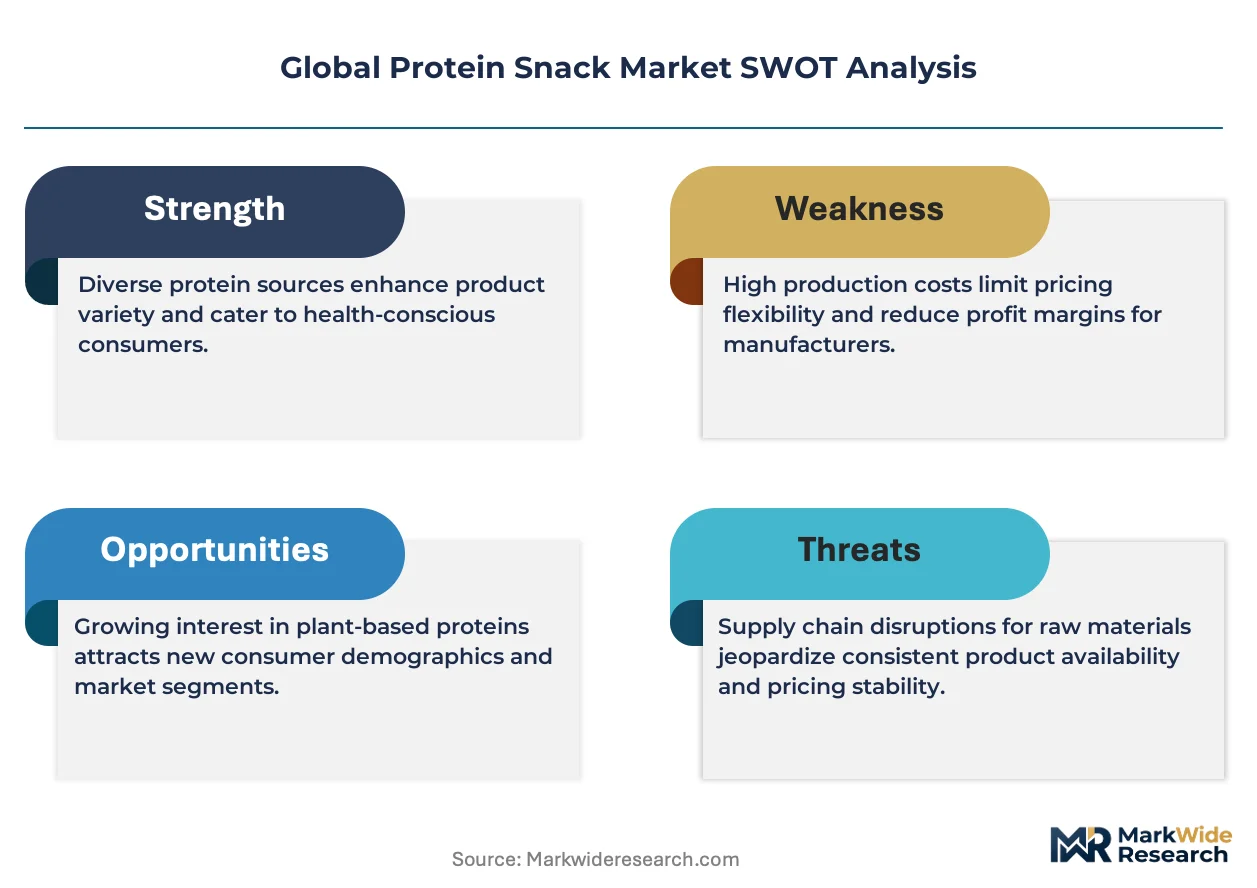
Clean-label reformulation pressure under FDA and EFSA guidelines is compressing legacy whey-dominant portfolios while accelerating plant-protein extrusion capacity buildouts across three continents.
Growth Catalysts
- Fitness Enthusiast Routine Formation:Post-workout consumption habits among gym-goers and amateur athletes are creating predictable demand pulses that stabilize production planning for bar and chip manufacturers.
- EFSA Health Claim Pathways:Approved protein content declarations in the European Union are enabling premium positioning for isolate-heavy formulations that command shelf-space allocation.
- Pea Protein Extrusion Maturation:High-moisture extrusion technology for allergen-free crisps is opening retail access previously blocked by soy and dairy labeling concerns.
Market Restraints
- Input Cost Volatility:Yellow pea isolate prices fluctuate with Canadian and Ukrainian harvest cycles, squeezing margin structures for mid-tier bar producers.
- Supply Concentration Risk:Pharmaceutical-grade filtration infrastructure for whey isolate clusters in the Upper Midwest United States, creating single-point vulnerability for co-manufacturing networks.
- Regulatory Friction:China's SAMR GB standards for imported protein products impose testing timelines that filter smaller brand entrants from cross-border e-commerce channels.
Strategic Opportunities
- German Functional Snacking Infrastructure:Specialized retail shelf-space expansion for sports nutrition in drugstore and convenience channels offers first-mover positioning for clean-label entrants.
- Subscription Model Convergence:Direct-to-consumer specialists combining personalized nutrition algorithms with auto-replenishment are compressing customer acquisition costs versus traditional retail slotting.
- India FSSAI Transparency Mandate:Front-of-pack protein percentage disclosure requirements are rewarding formulation precision with trust premiums among urban health-conscious consumers.
Industry Challenges
- Extrusion Engineering Talent Scarcity:High-moisture plant protein processing requires hybrid food science and mechanical engineering skills concentrated in European technical universities.
- Dual Certification Timelines:Simultaneous FDA nutrition label compliance and EFSA novel food approval for emerging protein sources extends product launch windows by eighteen to twenty-four months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Protein Snack Market |
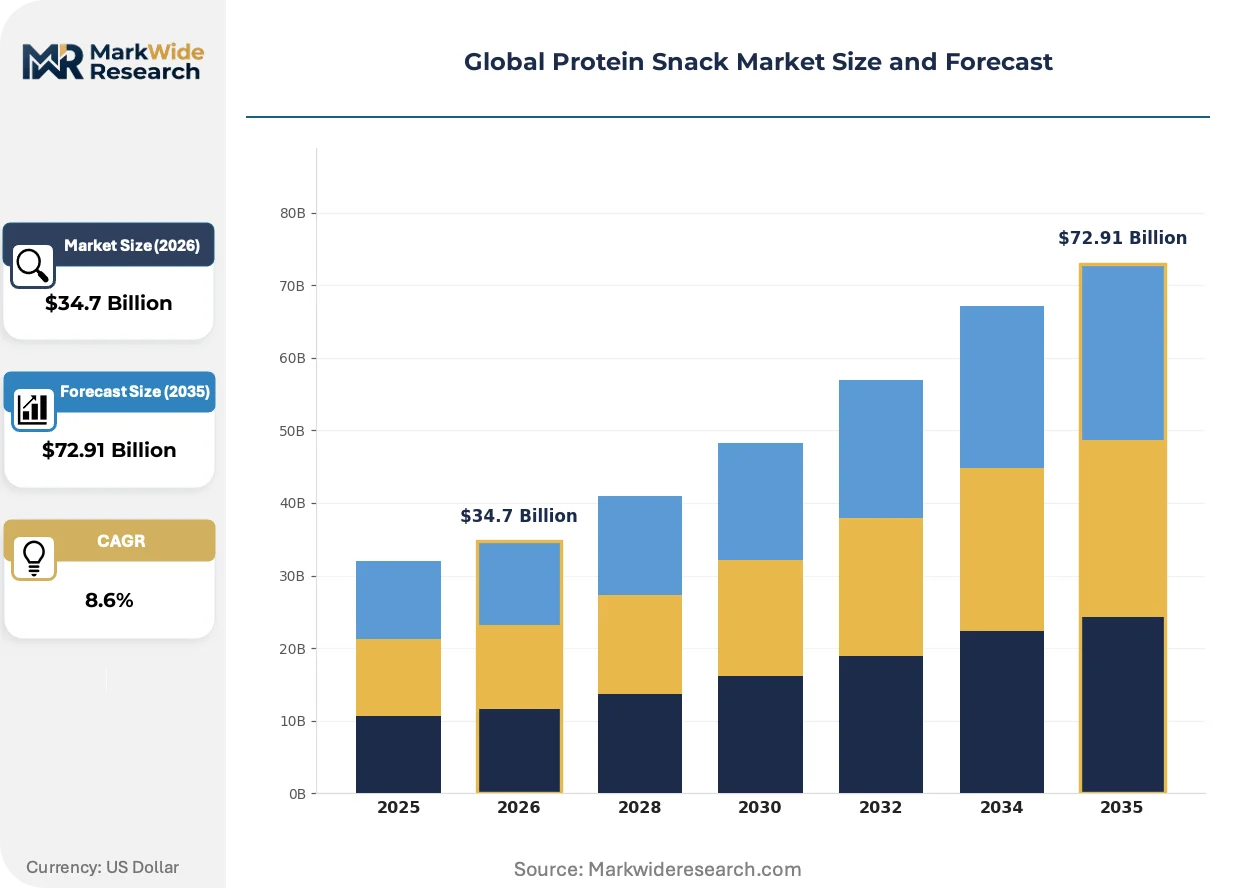
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Chips, Jerky, Crisps Ingredient Type: Whey Protein, Pea Protein, Soy Protein, Casein Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores End User: Athletes, Fitness Enthusiasts, Busy Professionals, Students |
| Companies Covered | Nestlé S.A., PepsiCo Inc., Mondelez International Inc., Mars Inc., General Mills Inc., Tyson Foods Inc., Kellanova, The Simply Good Foods Company, Quest Nutrition LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Protein Snack Market Strategic Shifts
Formulation science and distribution architecture are diverging sharply as plant-protein processing matures and direct channels capture preference data that reshapes N pipelines.
Precision fermentation-derived dairy proteins are overtaking conventional whey isolates in premium bar applications. Sports nutrition brands targeting collegiate athletes and boutique fitness studios are adopting these ingredients at pace. This biotechnology is compressing the carbon footprint gap between animal and plant sourcing while maintaining amino acid completeness.
REACH chemical safety registrations for novel protein extraction solvents are tightening purity thresholds across European Union manufacturing. Industrial consequence includes accelerated capital deployment toward aqueous extraction methods that bypass solvent-based purification. Bar manufacturers serving German and Benelux markets are reformulating around these constraints ahead of enforcement timelines.
After-workout consumption occasions are fragmenting into micro-moment targeting by direct-to-consumer brands. Convenience channel placement is losing share to subscription lockers in apartment complexes and office buildings where replenishment triggers proximity. This behavioral shift concentrates in United States coastal metros and Chinese Tier-1 cities where delivery density supports unit economics.
Global Protein Snack Market Segmentation
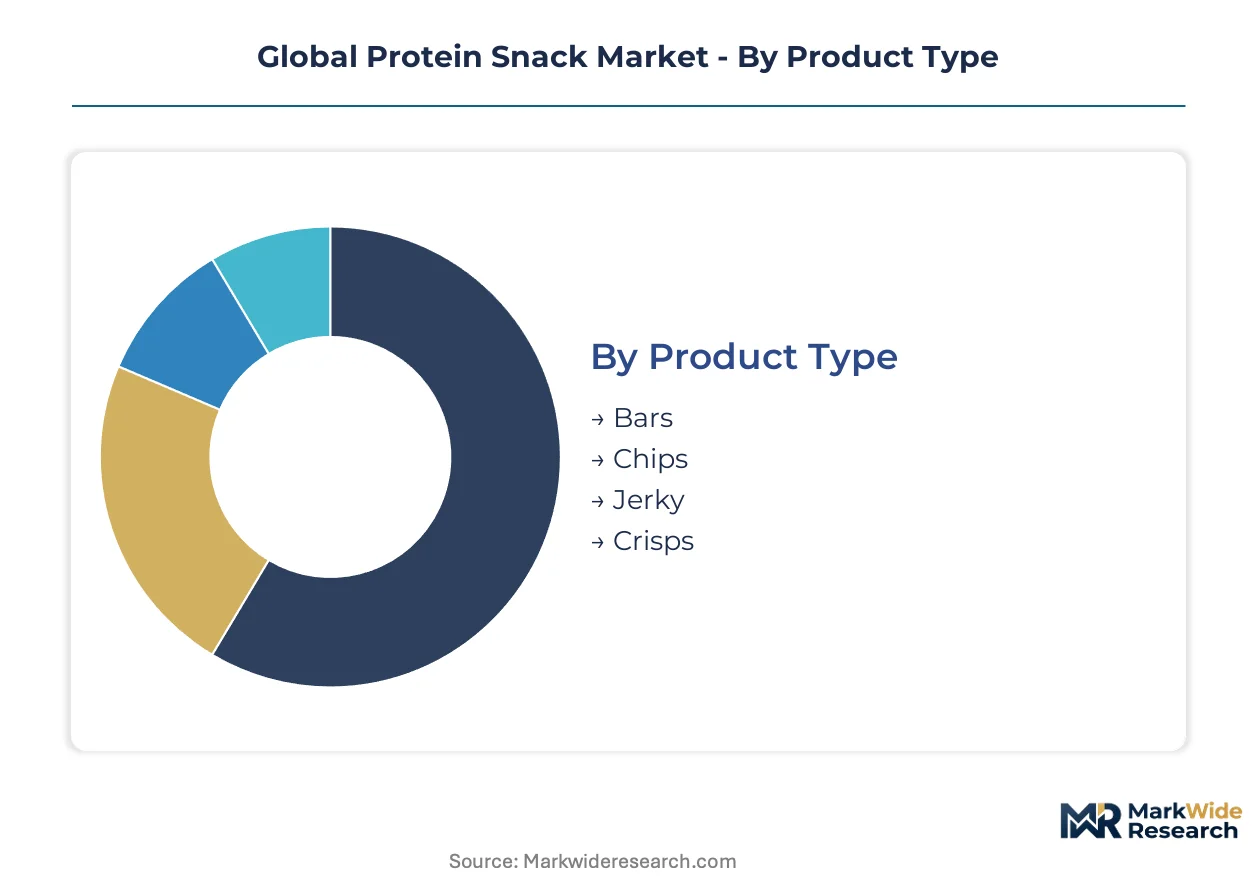
Protein snack manufacturers configure product portfolios across four intersecting dimensions where format innovation, protein sourcing, channel access, and occasion-based targeting determine margin capture. Category boundaries blur as bar producers launch chip lines and direct-to-consumer specialists build retail presence.
Product Type:
Upgrade cycles accelerate as consumers rotate between formats based on consumption occasion and portability requirements.
- Bars:Cold-pressed and extruded formats deliver 10–20 grams protein through nut butter, crisp rice, or isolate matrices. Demand concentrates among fitness enthusiasts seeking post-workout recovery solutions where convenience and amino acid completeness outweigh price sensitivity.
- Chips:High-moisture extrusion creates puffed or flat structures from pea, lentil, or fava protein isolates. German drugstore chains and US coastal convenience channels are expanding shelf space for these alternatives as allergen-free positioning opens retail access previously blocked by soy labeling concerns.
- Jerky:Low-temperature dehydration of whole-muscle or restructured meat delivers dense protein with extended shelf stability. Tyson Foods and Jack Link's dominate through captive smokehouse automation and livestock supply chain control.
- Crisps:Thin-sheet extrusion or baking of plant protein isolates creates brittle textures mimicking traditional potato chips. Chinese Tier-1 city consumers drive trial through cross-border e-commerce channels.
Bars sit at the top of the volume ranking, with chips climbing the fastest as extrusion technology matures and retail buyers seek format diversification.
Ingredient Type:
Cost tier differentiation separates premium isolate formulations from commodity concentrate blends as input price volatility reshapes procurement strategies.
- Whey Protein:Isolate and concentrate forms derived from dairy processing deliver complete amino acid profiles with rapid absorption kinetics. US Upper Midwest filtration infrastructure clusters create supply concentration risk for co-manufacturing networks dependent on pharmaceutical-grade purity.
- Pea Protein:Yellow pea isolate extracted via aqueous or dry fractionation offers allergen-free positioning with neutral flavor profiles improving through enzymatic treatment. Canadian and Ukrainian harvest cycles drive price volatility that squeezes mid-tier bar producer margins.
- Soy Protein:Isolate and concentrate from defatted soy flakes retain cost advantages but face clean-label headwinds in North American and European markets. Chinese domestic consumption absorbs most regional supply.
- Casein:Micellar casein from milk provides slow-release amino acid delivery suited to overnight recovery positioning. Premium pricing limits penetration to specialized sports nutrition channels.
Whey protein commands the volume lead, though pea protein gains share fastest as EFSA and FDA clean-label pressures displace legacy formulations.
Distribution Channel:
Customer acquisition economics diverge sharply between high-frequency retail replenishment and subscription-driven direct relationships.
- Supermarkets:Mass merchandisers and grocery chains allocate end-cap and checkout placement based on velocity metrics and slotting fee commitments. PepsiCo's direct-store-delivery networks control convenience-adjacent positioning in US channels.
- Online Retail:Direct-to-consumer specialists and marketplace aggregators capture disproportionate growth velocity through subscription auto-replenishment models. Personalized nutrition algorithms reduce customer acquisition costs versus traditional retail slotting.
- Convenience Stores:Impulse-driven single-serve purchases concentrate in travel and workplace proximity locations. After-workout micro-moment targeting is fragmenting this channel's share to subscription lockers in apartment complexes.
- Health Food Stores:Specialized retailers curate premium and novel formulations for early-adopter consumers. German drugstore channel expansion is absorbing traditional health food store positioning.
Supermarkets retain volume dominance, yet online retail expands most quickly as delivery density improves unit economics in coastal metros.
End User:
Application occasion maturity separates established athletic consumption from emerging professional and student segments where habit formation remains incomplete.
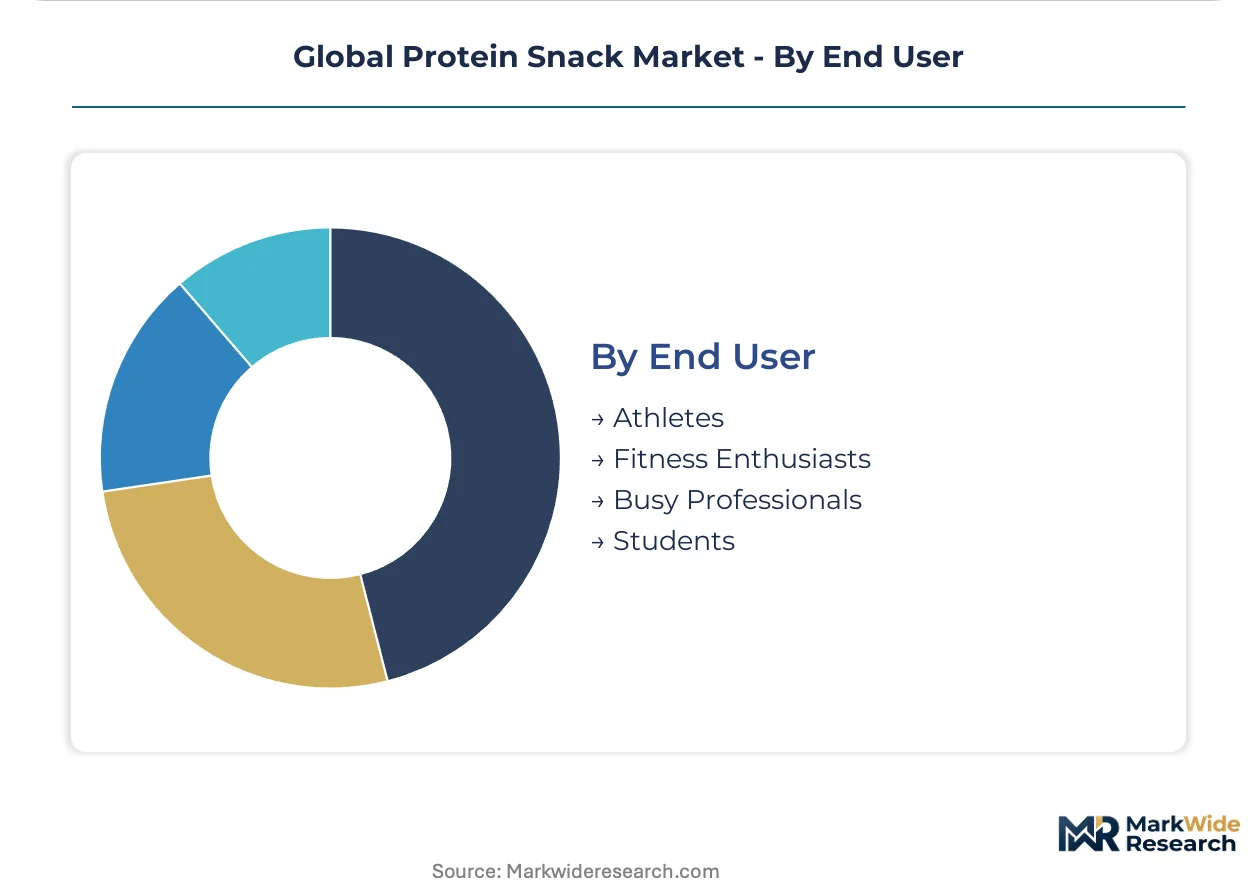
- Athletes:Collegiate, amateur, and professional competitors prioritize amino acid completeness and batch-tested certification. Precision fermentation-derived proteins are overtaking conventional whey in premium applications targeting this cohort.
- Fitness Enthusiasts:Gym-goers and boutique studio attendees drive routine post-workout consumption that stabilizes manufacturer production planning. This segment's predictable demand pulses create inventory efficiency for bar and chip producers.
- Busy Professionals:Meal replacement and desk-side snacking occasions favor shelf-stable formats with minimal preparation. Office building subscription locker deployments concentrate in US and Chinese Tier-1 cities.
- Students:Price-sensitive trial behavior and campus proximity vending drive lower-margin volume. India's urban university corridors represent emerging demand concentration as FSSAI transparency mandates build trust.
Fitness enthusiasts anchor current volume, with busy professionals gaining share fastest as workplace consumption rituals solidify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting protein snack manufacturing toward jurisdictions where EFSA novel food pathways and FDA nutrition label compliance create divergent cost-of-market-entry profiles. Production investment clusters where filtration infrastructure and extrusion engineering talent concentrate.
United States
Fitness enthusiasts in coastal metros drive subscription locker deployments for post-workout consumption. FDA nutrition labeling rules govern protein content declarations and marketing claims. The Upper Midwest hosts pharmaceutical-grade whey isolate filtration infrastructure serving co-manufacturing networks.
Germany
Drugstore chains expand specialized retail shelf space for sports nutrition and clean-label entrants. EFSA health claim assessments shape permissible protein content declarations and isolate-heavy formulation positioning. The Benelux-adjacent Rhine-Ruhr corridor concentrates aqueous extraction method deployment ahead of REACH enforcement timelines.
China
Tier-1 city consumers trial extruded plant protein crisps through cross-border e-commerce channels. SAMR GB standards for imported protein products impose testing timelines that filter smaller brand entrants. Yangtze River Delta manufacturing hubs scale high-moisture extrusion capacity for allergen-free chip exports.
India
Urban university corridors generate emerging demand from price-sensitive student segments. FSSAI mandates front-of-pack protein percentage disclosure, tightening formulation transparency. Maharashtra and Karnataka host pilot production lines for pea protein bar manufacturing targeting domestic health-conscious consumers.
Canada
Yellow pea isolate supply chains anchor procurement strategies for North American bar producers. Canadian harvest cycles drive input price volatility that squeezes mid-tier manufacturer margins. Prairie Provinces concentrate dry fractionation infrastructure serving plant-protein extrusion facilities.
Global Protein Snack Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and direct-to-consumer subscription models. The market structures around three maturity tiers: multinational CPG conglomerates with captive distribution, mid-tier specialists with co-manufacturing dependence, and venture-backed DTC brands with algorithm-driven personalization. Dominant competitive moves include portfolio diversification into adjacent formats and backward integration into protein isolate supply.
Among Swiss and American conglomerates, Nestlé S.A. and PepsiCo Inc. exemplify scale-driven archetypes with infrastructure leverage, while Tyson Foods Inc. represents livestock-integrated vertical positioning. These entities anchor the competitive set through contrasting supply chain configurations rather than overlapping strategic postures.
| Leading Market Players |
|---|
| Nestlé S.A. |
| PepsiCo Inc. |
| Mondelez International Inc. |
| Mars Inc. |
| General Mills Inc. |
| Tyson Foods Inc. |
| Kellanova |
| The Simply Good Foods Company |
| Quest Nutrition LLC |
| Others |
Value Chain & Pricing Dynamics
Yellow pea isolate costs cascade from Canadian Prairie harvests through three pricing tiers as bar manufacturers absorb volatility or push it downstream. Input price swings squeeze mid-tier producers lacking long-term offtake contracts, while premium brands with captive sourcing maintain margin stability.
Pricing Analysis
Distributor margins compress as direct-to-consumer subscription models bypass traditional retail slotting fees. Three-tier pricing structure across premium, standard, and economy levels separates precision-fermentation isolate formulations from commodity whey concentrates and private-label alternatives. Pricing pressure stems from EFSA clean-label compliance costs that reformulation absorbs rather than passes through. Students and price-sensitive trial consumers in Indian urban corridors exhibit highest elasticity, while collegiate athletes and boutique fitness studios accept premium positioning for batch-tested certification.
Supply Chain Analysis
Extrusion engineering talent scarcity in European technical universities constrains high-moisture plant protein capacity expansion. Supply concentrates in the United States Upper Midwest for pharmaceutical-grade whey filtration, China's Yangtze River Delta for allergen-free chip exports, and Germany's Rhine-Ruhr corridor for aqueous extraction methods. Raw material dependencies include yellow pea isolate, precision-fermentation dairy proteins, and micellar casein. Single-source vulnerability clusters around Upper Midwest filtration infrastructure serving co-manufacturing networks. Distribution runs through direct-store-delivery networks controlling convenience channel placement, subscription auto-replenishment compressing customer acquisition costs, and cross-border e-commerce penetrating Chinese Tier-1 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Protein snack manufacturing arbitrages regulatory divergence between FDA nutrition label compliance costs and EFSA novel food approval timelines, with eighteen-to-twenty-four-month dual certification windows favoring jurisdiction-selective launch sequencing.
For Market Incumbents: Deploy captive supply chain control as the defensive anchor. Nestlé S.A.'s pharmaceutical-grade filtration infrastructure and Tyson Foods' smokehouse automation demonstrate how backward integration into protein isolate production insulates against input volatility. PepsiCo's direct-store-delivery networks defend shelf position against subscription-model erosion. Precision fermentation entrants threaten whey-dominant portfolios; isolate-heavy reformulation toward plant proteins preserves retail access under tightening EFSA and FDA clean-label guidelines. For New Entrants and Emerging Players: Begin with German drugstore channel specialization where sports nutrition shelf-space expansion rewards first-mover clean-label positioning. India's FSSAI transparency mandate creates white-space for formulation-precision brands targeting urban university corridors with front-of-pack protein percentage disclosure as trust signal. Subscription locker deployment in US coastal metros and Chinese Tier-1 cities captures after-workout micro-moments fragmented from convenience channels. Personalized nutrition algorithms paired with auto-replenishment compress customer acquisition costs versus traditional retail slotting. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier bar producers face margin compression from yellow pea isolate volatility without long-term offtake contracts. Five-to-ten-year viability favors specialists with hybrid food science and mechanical engineering capabilities concentrated in European technical universities, or those with precision fermentation partnerships overtaking conventional whey. Acquisition target archetype: direct-to-consumer brands with algorithm-driven personalization and proven subscription unit economics. Signal to watch: REACH enforcement timelines accelerating aqueous extraction method deployment ahead of solvent-based purification restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isolate Supply | Tyson Foods' captive livestock chains and Nestlé's filtration infrastructure insulate margin structures from input volatility. |
| Precision Fermentation Partnership | Biotechnology-derived dairy proteins compress carbon footprint gaps while maintaining amino acid completeness for collegiate athlete targeting. |
| Direct-to-Consumer Subscription Launch | Auto-replenishment algorithms reduce customer acquisition costs versus PepsiCo's traditional retail slotting fee structures. |
| German Drugstore Channel Expansion | Specialized sports nutrition shelf-space allocation rewards EFSA-compliant clean-label entrants with premium positioning. |
| Aqueous Extraction Method Deployment | Benelux-adjacent manufacturing reformulates ahead of REACH solvent-purity enforcement timelines. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged protein snack brand managers, category buyers at German drugstore chains and US mass merchandisers, extrusion engineering leads at European technical universities, and regulatory affairs specialists navigating FDA and EFSA compliance pathways. Secondary validation drew from FDA nutrition labeling filings, EFSA novel food approval registers, SAMR GB standards documentation, FSSAI front-of-pack mandate circulars, Nielsen retail audit data, and customs records tracking yellow pea isolate trade flows. Bottom-up demand modeling triangulated against top-down macroeconomic anchors.
Segment-weighting distributed value and volume across product type, ingredient source, distribution channel, and end-user occasion dimensions. Bars, chips, jerky, and crisps carried distinct growth assumptions reflecting format maturity and extrusion technology diffusion. Whey, pea, soy, and casein protein tiers incorporated EFSA and FDA clean-label displacement trajectories. Online retail, supermarket, convenience, and health food channel weights reflected subscription model velocity and direct-store-delivery network control. Fitness enthusiasts, athletes, busy professionals, and students carried differential price elasticity and occasion-based consumption frequency. CAGRs derived from trend extrapolation, technology S-curve positioning, and regulatory enforcement timeline alignment.
Several conditions sit outside the modeled scope, including sudden tariff disruptions on Canadian yellow pea imports, precision fermentation regulatory reclassification, and pandemic-scale logistics chokepoints. Forecasts embed assumptions about EFSA novel food approval velocity, REACH solvent restriction enforcement, and SAMR GB standards stability. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low Calorie Cookies Market
Snacks
Trail Mix Market
Snacks
South Africa Snack Bar Market
Snacks
Europe Energy Bar Market
Snacks
Global Vegetable Chips Market
Snacks
Europe Extruded Snack Food Market
Snacks
United Kingdom Energy Bar Market
Snacks
North America Snack Food Market
Snacks
South Korea Snack Bar Market
Snacks
Asia-Pacific Snack Bar Market
Snacks
Allergy-Free Snacks Market
Snacks
Low Sodium Snacks Market
Snacks
Superfoods-Based Packaged Snacks Market
Snacks
Organic Snack Food Market
Snacks
Instant Meat Marinated Snacks Market
Snacks
Nutritional Bar Market