
 Middle East and Africa Snack Pellets Market | 2026-2036
Middle East and Africa Snack Pellets Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Snack Pellets Market Foresight
The price-performance boundary between premium and commodity snack pellet tiers is hardening in the Middle East and Africa. Quality Pellets AS leverages its Nordic extrusion technology to command premium positioning among Gulf foodservice operators. Bach Snacks SAL anchors Levantine supply chains through integrated potato sourcing and regional distribution hubs. Crunchy Food FZE competes on volume scale from its UAE base, serving private-label contracts across Arabian Peninsula retail banners.
Snack pellets are intermediate semi-finished products manufactured through extrusion, frying, baking, or dehydration of starch-based doughs formulated from potato, corn, rice, or tapioca, designed for final expansion and flavoring by downstream processors. Extruded pellets retain dominant volume share due to their versatility across both foodservice frying operations and retail-ready baked formats. The material mix is shifting toward tapioca and rice variants as Gulf-based snack manufacturers seek differentiation from commodity potato lines and respond to dietary preference evolution in urban centers.
Saudi Arabia's SFDA enforces escalating food safety protocols for processed ingredient imports, while Egypt's national food control authority administers parallel inspection regimes that shape cross-border trade flows. The UAE's municipal food control departments in Dubai and Abu Dhabi impose additional halal certification and labeling requirements that filter market access for non-compliant suppliers. Stakeholders must monitor regulatory divergence between Gulf standardization initiatives and North African national food codes when configuring regional manufacturing and distribution footprints.
Market Dynamics
Gulf foodservice chains are accelerating pellet procurement for fried snack menus while Saudi SFDA tightening on ingredient disclosure forces reformulation investments across regional supply chains.
Growth Catalysts
- Quick-service restaurant expansion:Gulf Cooperation Council chains are scaling pellet volumes for standardized fried and baked product lines across their franchised networks.
- SFDA labeling mandates:Saudi Arabia's escalating disclosure requirements for processed intermediates are pushing domestic manufacturers toward cleaner-label formulations that command shelf preference.
- Tapioca diversification:Starch blend innovation is electrifying product differentiation as Egyptian and Emirati producers develop non-potato variants for urban dietary shifts.
Market Restraints
- Potato input volatility:Starch raw material costs fluctuate with Levantine and North African harvest cycles, compressing margin predictability for extrusion-dependent operators.
- Supply concentration risk:Egyptian production corridors dominate regional pellet export capacity, creating single-geography vulnerability for North African buyers.
- Halal certification friction:UAE municipal food control departments in Dubai and Abu Dhabi impose divergent halal verification protocols that fragment cross-emirate distribution.
Strategic Opportunities
- North African export channels:Egypt's food manufacturing corridor offers underexploited gateway positioning for pellet supply into Maghreb retail banners seeking private-label sourcing.
- Baked format migration:Health-positioned retail SKUs are displacing oil-fried alternatives, opening equipment upgrade cycles for extrusion lines configured to dual-process formats.
- Gulf standardization initiatives:GCC regulatory harmonization efforts are creating certification economies of scale for compliant suppliers operating across Saudi, UAE, and Kuwait markets.
Industry Challenges
- Extrusion engineering talent scarcity:Specialized process optimization expertise for starch-based dough rheology remains concentrated among Nordic and European equipment vendors, complicating local technical staffing.
- Multi-jurisdiction compliance timelines:Parallel inspection regimes between Saudi SFDA and Egypt's national food control authority create divergent product registration cycles that delay regional rollout synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Snack Pellets Market |
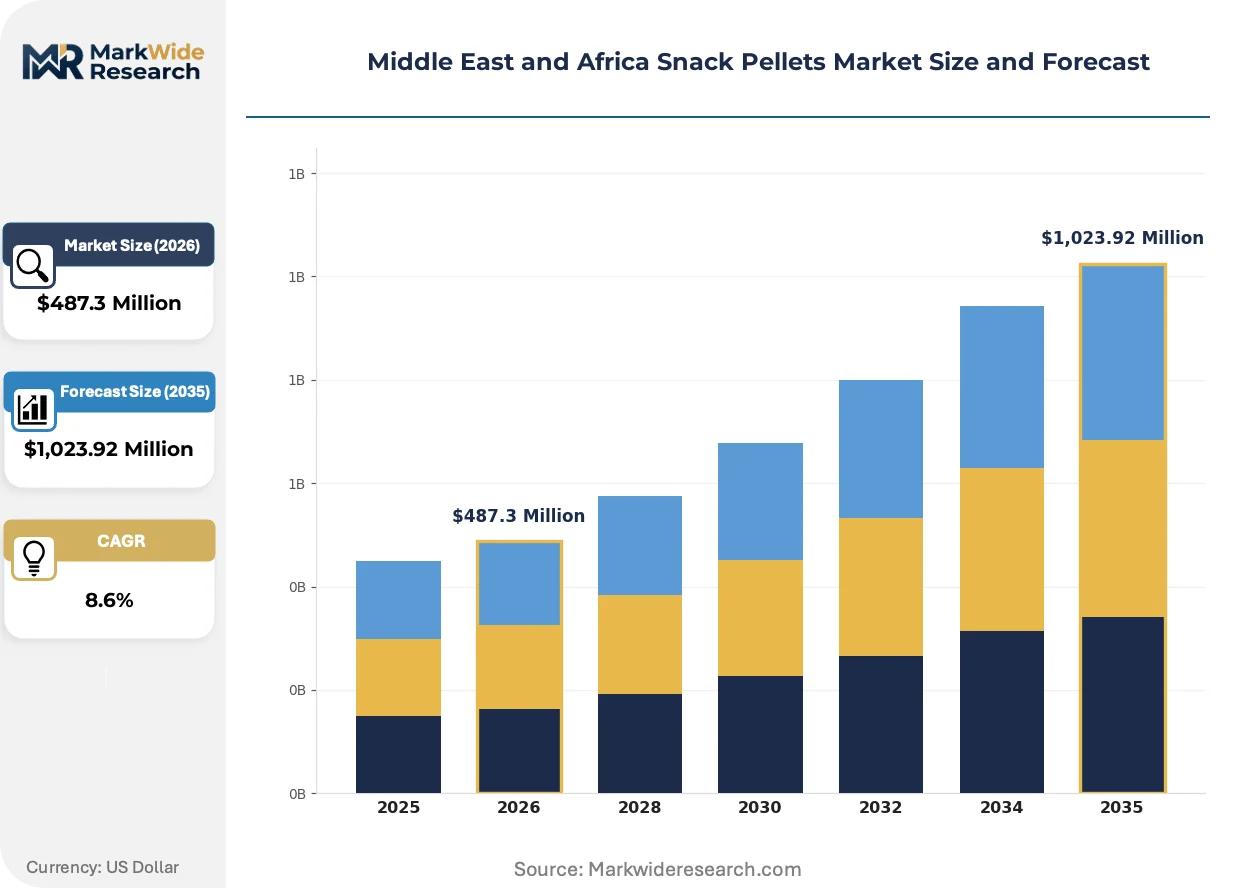
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruded, Fried, Baked, Dehydrated Material: Potato, Corn, Rice, Tapioca Distribution Channel: Online, Supermarkets, Hypermarkets, Convenience Stores End User: Retail, Foodservice, Catering, Snack Manufacturers |
| Companies Covered | Quality Pellets AS, GHANEM ALMOUNAJED MD, Bach Snacks SAL, Akkel Group, SOLINO Ltd Corp SaRL, Societe Cooperative Agricole Limagrain, Mafin SRL, Liven S.A., Crunchy Food FZE, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Snack Pellets Market Shifts & Advancements
Extrusion technology advances and regulatory disclosure mandates are compressing product development cycles while reshaping procurement relationships between pellet manufacturers and downstream snack finishers.
Low-shear extrusion systems are electrifying texture control capabilities for multigrain and legume-based pellet formulations. Gulf-based contract manufacturers are adopting these systems to serve health-positioned retail brands seeking differentiated crunch profiles. The technology is electrifying competitive positioning by enabling premium pricing for functional ingredient claims that commodity potato lines cannot replicate.
SFDA enforcement of processed ingredient safety protocols is tightening import inspection regimes for starch-based intermediates entering Saudi Arabia. Industrial consequence includes accelerated local production investments to bypass border documentation complexity. Egyptian and UAE suppliers are responding with dedicated Saudi-market production lines and enhanced batch traceability systems.
Foodservice procurement consolidation is compressing supplier negotiation cycles as Gulf quick-service chains centralize pellet buying through nominated distributors. Longstanding direct mill relationships are giving way to tiered distributor contracts with volume-commitment clauses. This shift is most visible in Dubai and Riyadh, where franchise operators prioritize supply security over price optimization in their sourcing calculus.
Middle East and Africa Snack Pellets Market Segmentation
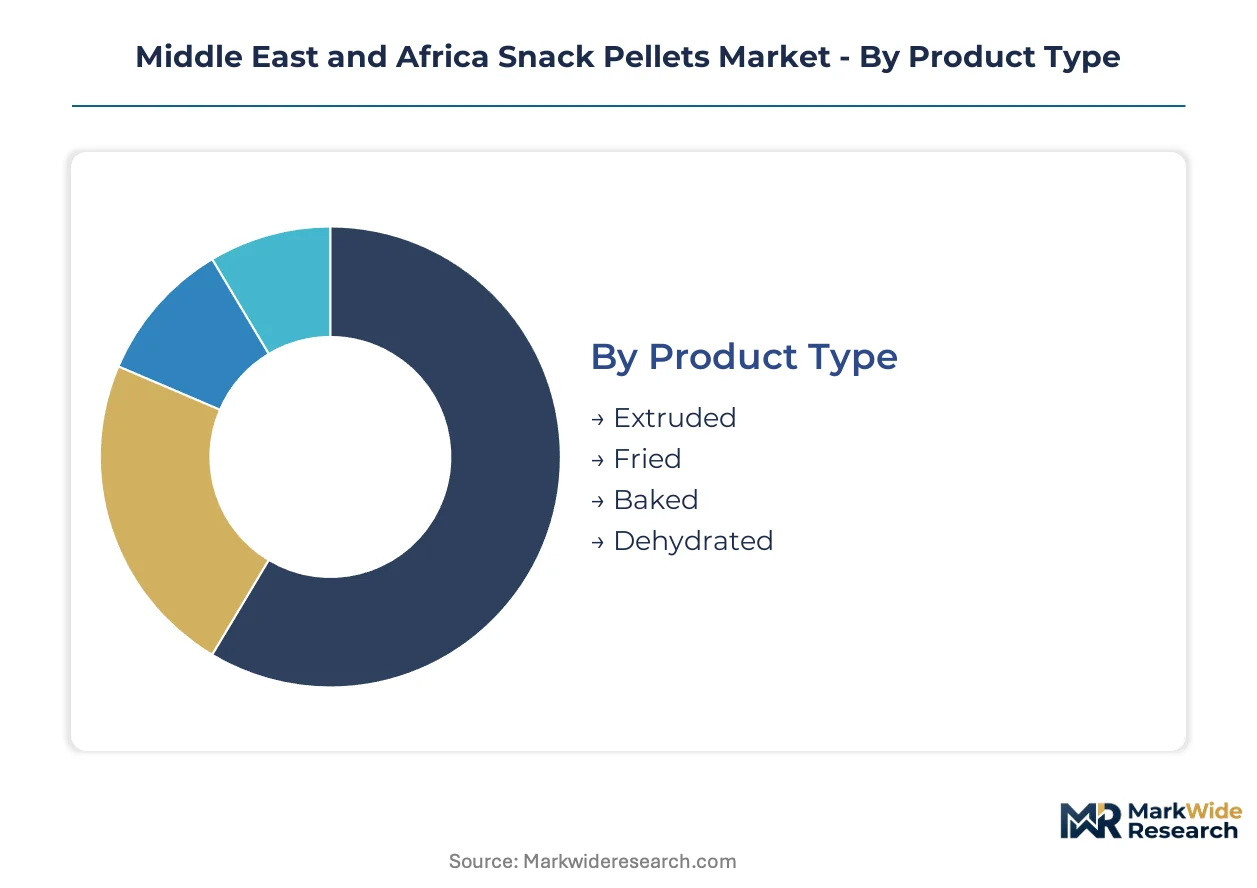
Segmentation in the Middle East and Africa snack pellets market reveals how processing technology, raw material sourcing, and channel configuration determine competitive positioning across Gulf and North African supply chains. Each dimension carries distinct regulatory, cost, and customer-access implications that shape supplier strategy.
Product Type:
Supply concentration in extrusion equipment and frying infrastructure across Egyptian and Emirati production corridors creates divergent cost structures for each processing format.
- Extruded:Starch-based dough forced through dies under heat and pressure creates uniform, shelf-stable intermediates suitable for both frying and baking expansion. Gulf quick-service chains concentrate procurement here for standardized crunch profiles across franchised networks, though extrusion line capital intensity limits new entrant participation.
- Fried:Oil-immersion cooking delivers immediate expansion and intense flavor absorption, dominating foodservice applications where final frying occurs on-site. Egyptian manufacturers supply this segment heavily into North African retail channels seeking authentic taste positioning, yet Saudi SFDA documentation requirements for processed oil-bearing intermediates complicate cross-border shipments.
- Baked:Dry-heat expansion produces lower-fat alternatives aligned with health-positioned retail SKUs in UAE and Saudi urban centers.
- Dehydrated:Moisture reduction through controlled drying yields lightweight, transport-efficient pellets for remote distribution.
Today's leader: Extruded. Tomorrow's challenger: Baked.
Material:
Raw material cost tiers separate commodity potato sourcing from premium tapioca and rice positioning in Gulf formulation strategies.
- Potato:Native and modified potato starches provide familiar taste profiles and reliable expansion characteristics across extrusion and frying processes. Levantine harvest volatility and Egyptian irrigation constraints create input price unpredictability that compresses margin stability for potato-dependent operators.
- Tapioca:Cassava-derived starch enables neutral flavor bases and superior textural crispness that differentiate premium retail lines. Emirati and Saudi manufacturers are climbing the fastest in this segment as urban dietary shifts away from commodity potato positioning accelerate formulation investments.
- Corn:Maize starch offers cost-competitive expansion and golden coloration familiar to North African consumers.
- Rice:Rice flour and starch support gluten-free and clean-label claims in health-focused Gulf retail channels.
Volume dominance sits with potato. Differentiation premiums flow to tapioca.
Distribution Channel:
Channel selection determines customer touchpoint economics and halal certification complexity across Saudi and UAE regulatory environments.
- Supermarkets:Organized retail banners in Saudi Arabia and UAE centralize procurement through nominated distributors, demanding batch traceability systems and SFDA-compliant labeling that favor established suppliers with documentation capabilities.
- Hypermarkets:Large-format operators in Dubai and Riyadh drive volume scale through private-label contracts, prioritizing supply security over price optimization in sourcing calculus.
- Convenience Stores:Small-format urban outlets in Cairo and Jeddah require flexible minimum order quantities and rapid replenishment cycles.
- Online:E-commerce platforms are gaining traction for specialty and imported pellet varieties in Gulf markets.
Procurement gravity centers on supermarkets. Format experimentation concentrates online.
End User:
Customer type dictates formulation specificity, with foodservice demanding frying-optimized pellets and retail seeking bake-ready or finished-product compatibility.
- Foodservice:Quick-service restaurants and institutional kitchens across GCC states require frying-stable pellets with consistent expansion ratios and oil absorption profiles. Centralized procurement through franchise operators compresses supplier negotiation cycles and privileges distributors with multi-emirate halal certification coverage.
- Retail:Packaged snack brands and private-label banners seek bake-compatible or ready-to-eat pellet formats aligned with health-positioned SKU strategies.
- Catering:Event and hospitality sectors in UAE and Qatar demand bulk formats with extended holding stability.
- Snack Manufacturers:Downstream processors in Egypt's food manufacturing corridor source intermediate pellets for flavoring and packaging into finished consumer goods.
Contract security runs through foodservice. Margin expansion targets retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's SFDA mandates are tightening faster than Egypt's export infrastructure can adapt, creating divergent compliance timelines across the two largest production corridors.
Saudi Arabia
Quick-service restaurant chains in Riyadh and Jeddah are scaling pellet procurement for standardized fried menu items across franchised networks. SFDA enforcement of processed ingredient safety protocols is accelerating local production investments to bypass border documentation complexity. The Riyadh-based food manufacturing corridor is attracting Egyptian and UAE suppliers establishing dedicated Saudi-market production lines with enhanced batch traceability systems.
United Arab Emirates
Dubai and Abu Dhabi foodservice operators are centralizing pellet buying through nominated distributors prioritizing supply security over price optimization. Municipal food control departments in both emirates impose divergent halal verification protocols that fragment cross-emirate distribution for non-compliant suppliers. The Jebel Ali industrial zone hosts contract manufacturers adopting low-shear extrusion systems to serve health-positioned retail brands seeking differentiated texture profiles.
Egypt
Local producers in Cairo's food manufacturing corridor supply both domestic retail and North African export channels, creating single-geography vulnerability for regional buyers. The national food control authority administers parallel inspection regimes that shape cross-border trade flows into Libya and Sudan. Alexandria's port infrastructure supports pellet export capacity serving Maghreb retail banners seeking private-label sourcing alternatives to European imports.
South Africa
Urban dietary shifts in Johannesburg and Cape Town are accelerating demand for non-potato starch variants including tapioca and rice-based formulations. The country's national food safety regulator maintains import inspection regimes for processed starch intermediates that filter market access for non-compliant suppliers. The Gauteng industrial corridor hosts extrusion-dependent operators facing margin compression from starch raw material cost volatility tied to regional harvest cycles.
Middle East and Africa Snack Pellets Market Competitive Landscape
Top-tier vendors anchor premium positioning through Nordic extrusion technology, while volume-scale operators compete on private-label contract fulfillment across Arabian Peninsula retail banners. The vendor base stratifies across three tiers: technology licensors commanding equipment premiums, integrated producers controlling regional distribution hubs, and contract manufacturers serving foodservice procurement consolidation. Strategic archetypes include extrusion engineering specialists, backward-integrated starch processors, and distributor-centric supply aggregators. Dominant competitive moves encompass capacity expansion in Saudi Arabia to bypass SFDA import friction and portfolio diversification into baked formats aligned with health-positioned retail SKU strategies.
Within the technology-specialist tier, Quality Pellets AS exemplifies Nordic-origin premium positioning through advanced extrusion capabilities. Bach Snacks SAL occupies a position as a Levantine-integrated operator with regional distribution hub control. Crunchy Food FZE represents the scale-driven archetype competing from its UAE base on volume contract fulfillment. These three anchors illustrate how geographic origin and structural configuration determine competitive positioning across Gulf and North African supply chains.
| Leading Market Players |
|---|
| Quality Pellets AS |
| GHANEM ALMOUNAJED MD |
| Bach Snacks SAL |
| Akkel Group |
| SOLINO Ltd Corp SaRL |
| Societe Cooperative Agricole Limagrain |
| Mafin SRL |
| Liven S.A. |
| Crunchy Food FZE |
| Others |
Supply & Pricing Matrix
Extrusion engineering talent concentration in Nordic equipment corridors widens pricing-tier spreads between premium technology-licensed pellets and commodity-grade regional production. Labor-cost differentials between European specialist vendors and Egyptian volume operators translate into persistent price-performance boundaries across Gulf procurement contracts.
Pricing Analysis
Packaged technical service bundles versus unbundled equipment-only procurement splits the market into divergent contract structures. Three-tier pricing structure across premium, standard, and economy levels separates Nordic-licensed extrusion systems from Levantine-integrated operators and Egyptian volume producers. Price differentiation flows from SFDA certification grade and after-sales technical support depth. Pricing pressure stems from potato starch input volatility compressing margin predictability for commodity-tier suppliers. Quick-service restaurant chains demonstrate lowest price sensitivity due to supply security prioritization, while private-label retail banners exhibit highest sensitivity to per-unit procurement costs.
Supply Chain Analysis
Single-source vulnerability sits with Egyptian production corridors dominating North African export capacity and Gulf import dependency. Geographic supply concentration clusters in Egypt, UAE, and Saudi Arabia for finished pellet manufacturing, with Nordic countries anchoring specialized extrusion equipment sourcing. Raw material dependencies center on Levantine potato harvests, Thai tapioca starch imports, and regional corn processing. Supply chain risk manifests as regulatory restriction friction from divergent halal certification protocols between Dubai and Abu Dhabi municipal departments. Distribution runs through nominated distributor networks consolidating procurement for franchised foodservice operators across GCC states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where Saudi SFDA disclosure mandates accelerate demand for traceable, clean-label pellet formulations that command shelf preference and supply security premiums.
For Market Incumbents: Anchor premium positioning through backward integration into tapioca starch sourcing and dedicated Saudi-market production lines that bypass SFDA import documentation complexity. Defend against Egyptian volume competition by locking multi-year distributor contracts with Gulf quick-service chains prioritizing supply continuity. Invest in low-shear extrusion capability to capture baked-format migration demand from health-positioned retail SKUs. For New Entrants and Emerging Players: Direct-to-specialty-retail e-commerce channels offer underexploited penetration routes for differentiated tapioca and rice-based pellet variants in Gulf urban centers. Target South African metropolitan markets where non-potato starch demand accelerates fastest among health-conscious consumer segments. Pursue white-label contract manufacturing partnerships with Emirati distributors seeking flexible minimum order quantities for convenience store replenishment cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among Egyptian volume producers with underutilized export capacity into Maghreb retail banners. Long-term viability favors integrated operators controlling both starch processing and regional distribution hub positioning. Monitor GCC regulatory harmonization progress as the inflection signal for certification economies of scale that reward compliant multi-market suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tapioca Sourcing | Captures margin from Thai starch imports while enabling premium positioning claims in Gulf retail channels. |
| Low-Shear Extrusion System Deployment | Unlocks texture differentiation for multigrain formulations that command pricing premiums from health-positioned brands. |
| Dedicated Saudi-Market Production Lines | Bypasses SFDA import documentation friction while accelerating batch traceability compliance for quick-service procurement. |
| Multi-Emirate Halal Certification Coverage | Resolves Dubai-Abu Dhabi protocol divergence that fragments distribution for non-compliant regional suppliers. |
| Private-Label Contract Manufacturing Scale-Up | Captures volume commitments from hypermarket banners prioritizing supply security over per-unit price optimization. |
Research Methodology
Coverage spans Middle East and North Africa, with primary inputs from each major production corridor combining executive interviews with extrusion equipment vendors, procurement directors at Gulf quick-service chains, Egyptian food manufacturing plant managers, and UAE distributor operations heads. Secondary validation draws from SFDA regulatory filings, Egyptian national food control authority inspection protocols, GCC customs trade data, and Nielsen retail audit coverage of snack pellet shelf positioning. Bottom-up demand modeling triangulates against top-down supply capacity assessments across Egyptian, Emirati, and Saudi production facilities.
Granularity-level modeling disaggregates volume and value across product type, material composition, distribution channel, and end-user segments with regional regulatory cluster differentiation. CAGRs derive from trend extrapolation of quick-service restaurant expansion rates, SFDA compliance investment cycles, and starch raw material cost trajectories across the projection horizon. Industry-specific forecast inputs include franchise network pellet procurement volumes and halal certification timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for low-shear extrusion diffusion would alter the outlook if equipment cost curves flatten faster than projected. Forecasts reflect assumptions about GCC regulatory harmonization progress and Egyptian export infrastructure development that could revise trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Healthy Fat-Free Snacks Market
Snacks
Asia-Pacific Popcorn Market
Snacks
South America Energy Bar Market
Snacks
Low Calorie Granola Market
Snacks
North America Frozen Snacks Market
Snacks
Europe Energy Bar Market
Snacks
Dried Fruit Snacks Market
Snacks
Low Calorie Snacks Market
Snacks
UK Snack Market
Snacks
Dairy Snacks Market
Snacks
Baked Savoury Snacks Market
Snacks
Global Rice Snacks Market
Snacks
Low Calorie Snack Foods Market
Snacks
Europe Snacks Food Market
Snacks
Saudi Arabia Snacks Industry Market
Snacks
UAE Snack Bar Market