
 Brazil Snack Bar Market | 2026-2036
Brazil Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Snack Bar Market Outlook
Asset-light franchising and third-party co-manufacturing arrangements is reshaping competitive entry in Brazil's snack bar sector. The Kellogg Company leverages its cereal-to-bar ingredient pipeline to control input costs. Nutrimental anchors its position through deep distribution in Brazilian pharmacies and health channels. Mars Incorporated competes via confectionery expertise translated into indulgent bar formats.
Brazil snack bars comprise formulated food products combining cereals, proteins, sweeteners, and binders through extrusion or cold-pressing, typically shelf-stable for six to twelve months and designed for portable between-meal consumption. Savory Snacks and Granola Bars capture divergent margin pools, with savory formats commanding premium positioning in convenience channels while granola bars sustain volume through health food store penetration. Distribution through Supermarkets and Online Retail concentrates reach, though Health Food Stores generate superior per-unit economics for functional and organic-positioned lines.
ANVISA enforces stringent nutrition labeling and health claim verification, while the PLI scheme and Mercosur technical regulations govern cross-border ingredient sourcing and manufacturing standards. These frameworks elevate compliance costs for imported formulations while creating protected terrain for domestically produced bars meeting local fortification protocols. Stakeholders must monitor pending updates to front-of-package warning labels and decide whether to reformulate portfolios proactively or absorb anticipated compliance-driven price adjustments.
Market Dynamics
ANVISA's pending front-of-package warning label mandates are forcing Brazilian snack bar manufacturers to reformulate sugar and sodium profiles ahead of enforcement timelines, compressing product development cycles and elevating R&D expenditure across domestic portfolios.
Growth Catalysts
- ANVISA nutrition labeling mandates:Stricter disclosure requirements for added sugars and saturated fats are accelerating clean-label reformulation investments among domestic manufacturers seeking preemptive compliance positioning.
- São Paulo fitness culture penetration:Dense urban gym networks and cross-training communities in Brazil's Southeast region generate concentrated demand for protein-fortified portable nutrition formats.
- Cold-pressing technology adoption:Low-temperature processing methods preserve heat-sensitive micronutrients in functional bars, enabling premium positioning in Brazilian pharmacy and health food channels.
Market Restraints
- Imported whey protein cost volatility:Brazil's dependence on Argentine and North American dairy concentrate inputs exposes margin structures to currency fluctuation and Mercosur trade friction.
- Southeast distribution concentration:Modern trade penetration clusters disproportionately in São Paulo state, leaving Northern and Center-West regions underserved by temperature-controlled logistics networks.
- ANVISA health claim verification timelines:Extended approval cycles for functional ingredient positioning delay product launches and tie up working capital in regulatory review queues.
Strategic Opportunities
- Minas Gerais dairy corridor proximity:Co-location near Brazil's largest milk-producing state enables captive whey and casein sourcing, reducing import dependency for protein bar manufacturers.
- PLI scheme domestic manufacturing incentives:Brazil's production-linked incentive framework for processed foods offers tax abatements for capital investment in automated extrusion and enrobing lines.
- Pharmacy channel expansion:Nutrimental's demonstrated model of health-positioned bar distribution through Brazilian drugstore chains remains replicable for clinical nutrition and diabetes-management formats.
Industry Challenges
- Food technologist talent scarcity:Brazilian universities produce limited graduates skilled in cereal chemistry and protein stabilization, forcing manufacturers to recruit from confectionery and bakery adjacent sectors.
- Legacy ERP integration with traceability systems:
- ANVISA lot-tracking mandates require real-time ingredient genealogy documentation that conflicts with decade-old manufacturing execution software deployed across mid-tier Brazilian co-packers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Snack Bar Market |
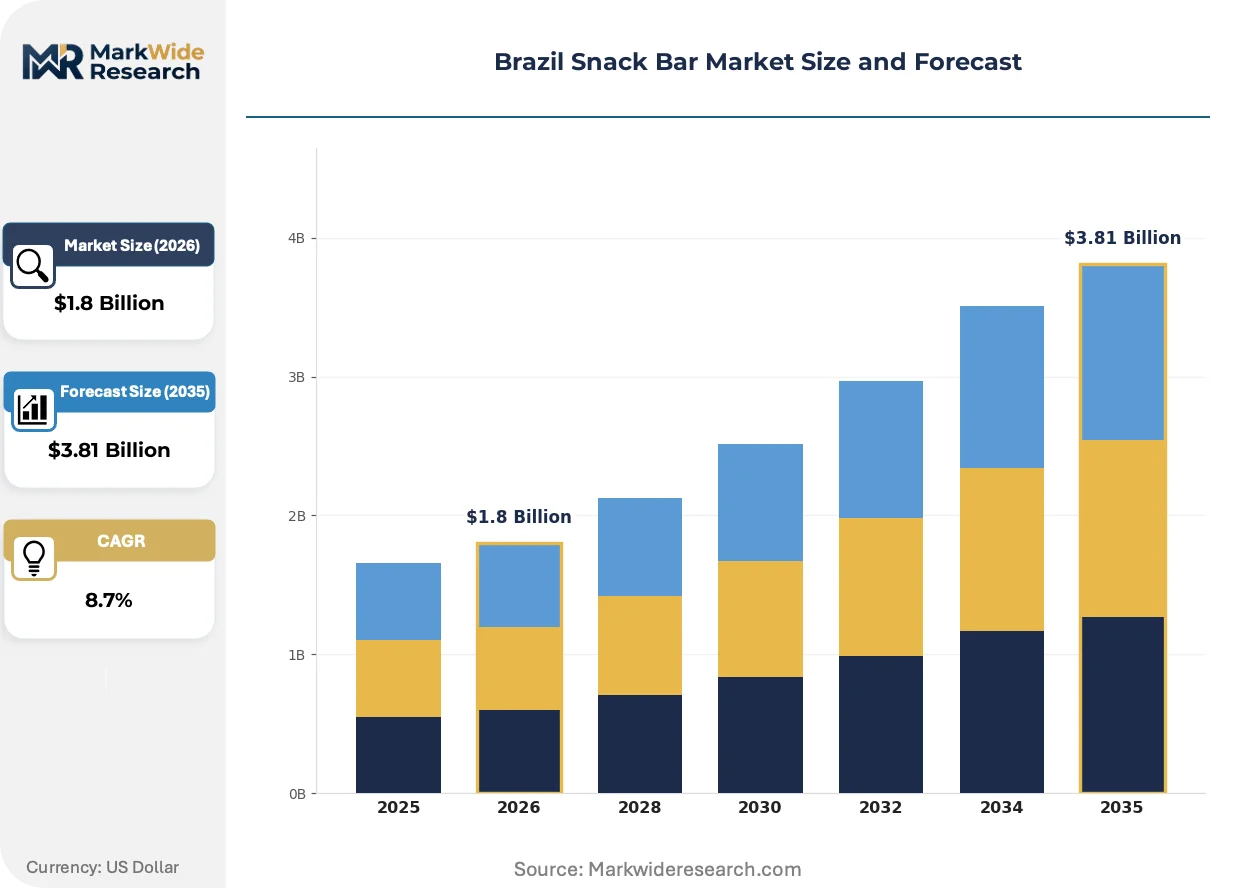
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baked Snacks, Confectionery, Savory Snacks, Granola Bars Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores End User: Adults, Children, Athletes, Health-Conscious Consumers Flavor Profile: Chocolate, Fruit, Spicy, Nutty |
| Companies Covered | The Kellogg Company, Nutrimental, Nestlé, Mars Incorporated, M. Dias Branco, PepsiCo, General Mills, Alfred Ritter, Mondelēz International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Snack Bar Market Strategic Shifts
Cold-pressed protein matrices, regulatory-driven reformulation protocols, and pharmacy-channel premiumization are converging to reshape Brazilian snack bar value capture. These developments favor domestic manufacturers with agile formulation capabilities and established health-channel relationships.
Pea-rice protein blends are hybridizing traditional whey-dominant formulations in Brazil's snack bar segment. Fitness-oriented consumers in Rio de Janeiro and São Paulo metro areas are adopting these plant-based alternatives at accelerating rates. This ingredient shift is hybridizing supply chain configurations, forcing manufacturers to qualify new South American pea protein suppliers alongside established dairy concentrate vendors.
ANVISA's proposed front-of-package octagonal warning labels for high-sugar products are compressing permissible formulation thresholds. Domestic manufacturers are accelerating stealth sugar reduction using allulose and fiber-based bulking agents to avoid triggering warning triggers. Indulgent-positioned bars with confectionery heritage face the steepest reformulation burden, while already-clean functional formats gain relative shelf appeal.
Cross-training enthusiasts and amateur endurance athletes in Brazil's Southeast region are consolidating purchase decisions around subscription-based direct-to-door delivery. This channel shift is disintermediating traditional supermarket impulse-buy placement, forcing brands to invest in digital fulfillment infrastructure and retention analytics. Pharmacy chains and specialized running stores in Belo Horizonte and Curitiba are responding with curated bar assortments and nutritionist-staffed consultation counters.
Brazil Snack Bar Market Segmentation
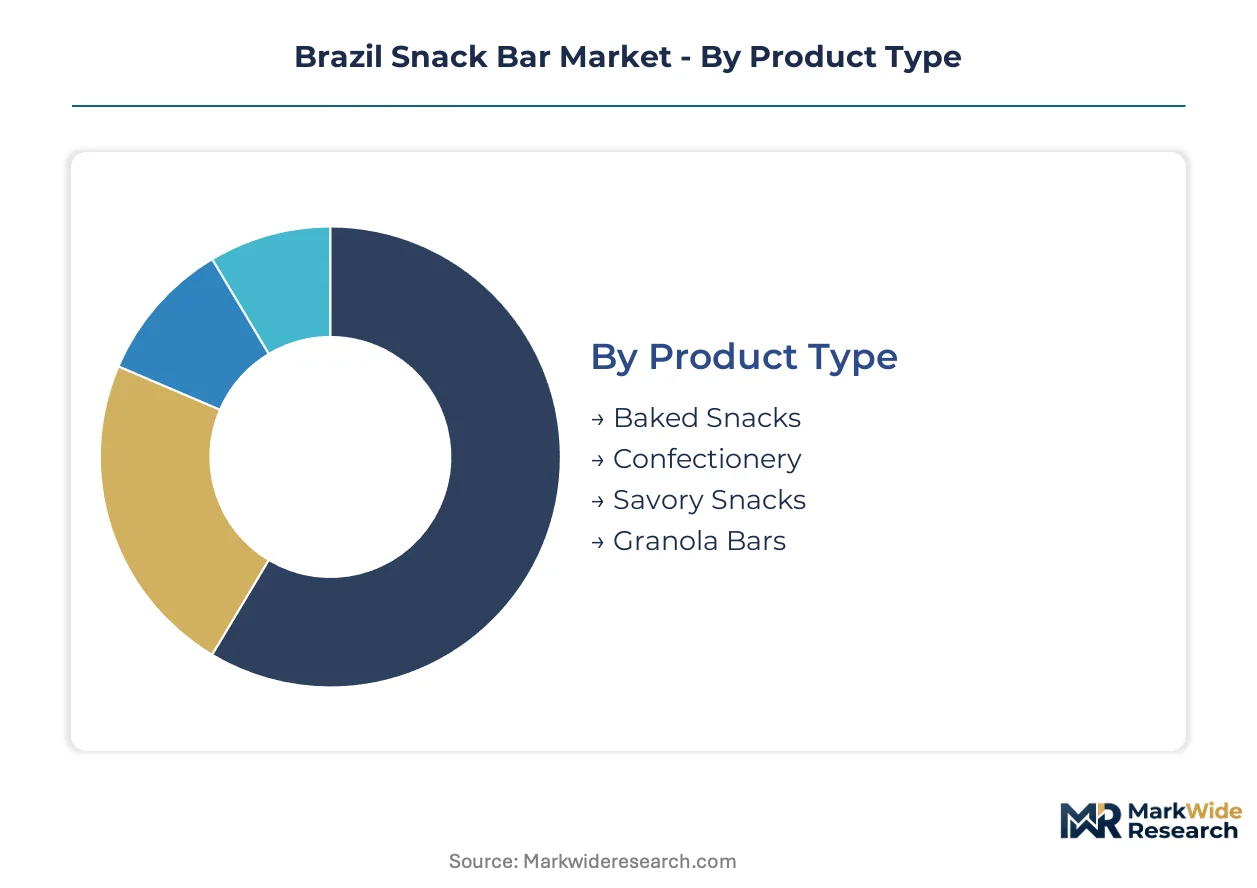
Segmentation in Brazil's snack bar market exposes divergent margin architectures across formulation philosophies and channel economics. Product type and distribution channel stratification reveal where functional premiumization confronts mass-market volume plays.
Product Type:
Mature extrusion-based formats coexist with emerging cold-pressed alternatives as manufacturers navigate ANVISA reformulation mandates.
- Savory Snacks:These bars combine dehydrated vegetables, legume flours, and umami seasoning matrices through low-temperature drying rather than high-heat extrusion. Demand clusters in São Paulo convenience channels where urban professionals seek portable meal replacements outside sweet-dominant formats.
- Granola Bars:Rolled oat and honey-bound clusters remain the technical baseline for Brazilian mass-market penetration. Southeast health food stores and pharmacy chains in Belo Horizonte sustain volume for traditional formulations even as protein-fortified variants capture shelf space.
- Baked Snacks:Cracker-style bars using tapioca and cassava starches target gluten-avoidant consumers through supermarket natural aisles.
- Confectionery:Chocolate-enrobed and caramel-layered bars leverage Mars Incorporated's existing confectionery infrastructure for impulse-channel placement.
Granola bars retain volume leadership; savory snacks hold the steepest expansion curve.
Distribution Channel:
Channel selection dictates margin capture through temperature-control requirements and shelf-position economics.
- Health Food Stores:Specialized retailers in Curitiba and Rio de Janeiro stock refrigerated protein bars with live probiotic cultures and sub-5°C storage protocols. These channels generate superior per-unit economics for functional-positioned lines despite lower absolute throughput.
- Supermarkets:Modern trade penetration concentrates in São Paulo state's hypermarket networks where ambient-stable bars compete for checkout-lane impulse placement. Temperature-controlled logistics constraints limit distribution reach into Northern Brazil.
- Online Retail:Direct-to-consumer subscription models disintermediate traditional wholesale markups for cross-training communities.
- Convenience Stores:Petrobras-branded fuel stations and independent bodegas stock single-serve formats for immediate consumption occasions.
Supermarkets sustain absolute volume; health food stores deliver the highest margin per square meter.
End User:
User segmentation maps onto Brazil's uneven fitness-culture geography and income stratification.
- Athletes:Amateur endurance competitors and cross-training practitioners in Southeast metro areas consolidate purchase decisions around 20-30 gram protein formats with branched-chain amino acid fortification. Subscription-based replenishment models dominate this cohort's procurement patterns.
- Health-Conscious Consumers:Middle-class urban households seeking clean-label alternatives drive demand for organic-certified and non-GMO verified bars through pharmacy and natural-product channels.
- Adults:Working professionals in São Paulo and Rio de Janeiro metro corridors use snack bars for between-meal satiety without meal-replacement positioning.
- Children:School-lunch-compatible formats face stringent ANVISA sodium and sugar thresholds that eliminate most confectionery-positioned entries.
Adults represent the largest addressable base; athletes are climbing the fastest in per-capita expenditure.
Flavor Profile:
Flavor formulation reflects raw material sourcing proximity and regional taste preference divergence.
- Nutty:Brazil nut and cashew-dominant bars leverage Minas Gerais and Ceará agricultural corridors for captive supply of native Amazonian ingredients. These formats command premium positioning in export-oriented and domestic gourmet channels.
- Chocolate:Cocoa-sourced coatings from Bahia plantations anchor mass-market appeal through supermarket placement.
- Fruit:Açaí and cupuaçu pulp infusions target regional preference in Northern Brazil.
- Spicy:Pimenta malagueta and chili-lime variants test limited release in Northeast urban markets.
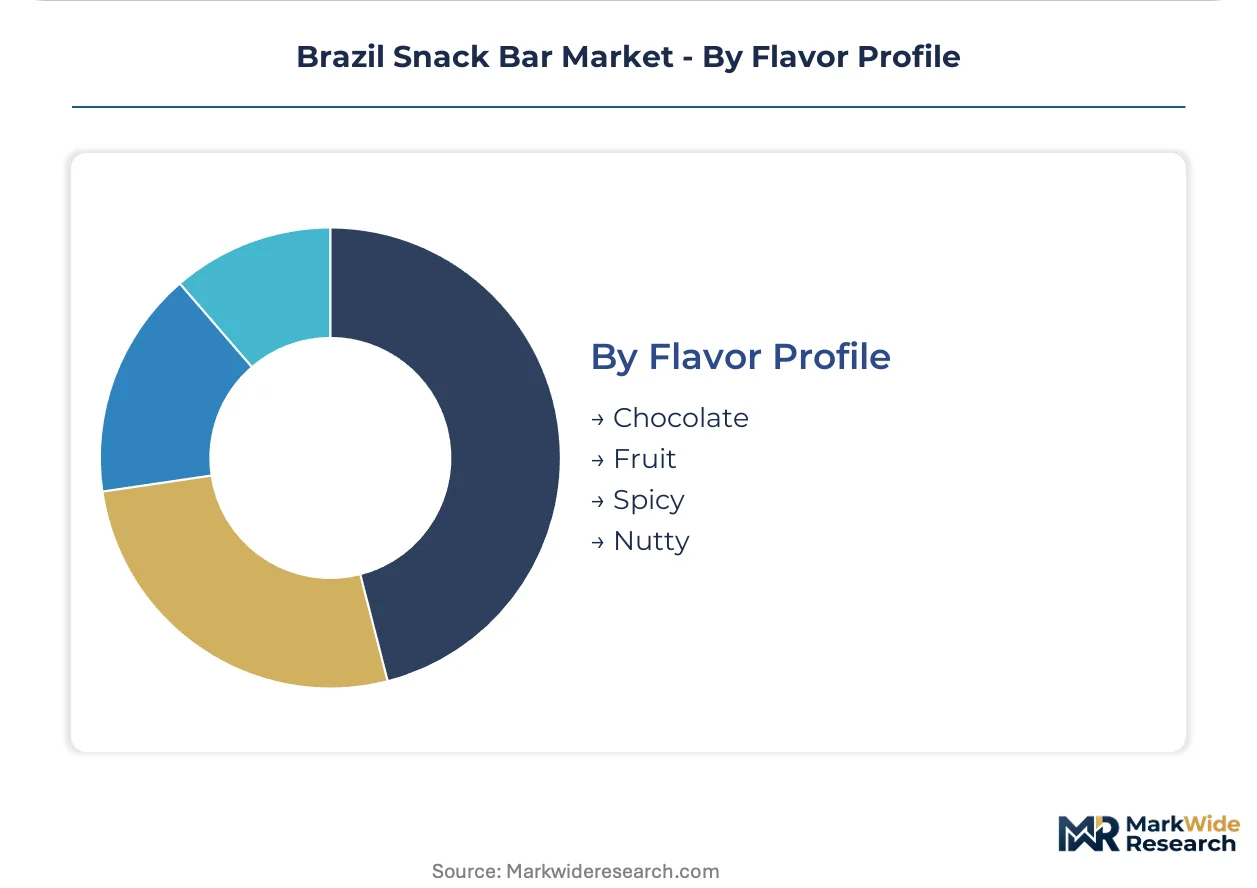
Chocolate maintains universal penetration; nutty profiles gain share fastest in premium tier expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's PLI scheme for processed foods and ANVISA's evolving nutrition labeling mandates are redistributing snack bar manufacturing capacity across sub-regional corridors. State-level incentives and dairy proximity are pulling investment toward Minas Gerais while Southeast logistics networks retain distribution dominance.
São Paulo
São Paulo state's hypermarket density and cross-training gym networks generate concentrated demand for protein-fortified formats. ANVISA's headquarters proximity accelerates regulatory compliance timelines for manufacturers based in the metropolitan corridor. Barueri and Guarulhos industrial zones host automated extrusion facilities serving both domestic supermarket chains and Mercosur export channels.
Minas Gerais
Proximity to Brazil's largest milk-producing state enables captive whey and casein sourcing for protein bar manufacturers. The state's dairy processing corridor reduces import dependency on Argentine dairy concentrates. Uberlândia and Belo Horizonte clusters are attracting PLI-linked capital investment in cold-pressing and enrobing automation.
Rio de Janeiro
Fitness culture penetration in Rio's South Zone and Barra da Tijuca drives demand for subscription-based direct-to-door delivery models. ANVISA's pending front-of-package warning labels are accelerating local reformulation partnerships between manufacturers and university food technology programs. Niterói pharmaceutical distribution hubs support pharmacy-channel expansion for clinical nutrition formats.
Rio Grande do Sul
The state's German-heritage food processing tradition supports technical expertise in cereal chemistry and protein stabilization. Porto Alegre's Mercosur trade infrastructure facilitates cross-border ingredient sourcing from Argentine suppliers. Local universities are expanding food engineering programs to address technologist talent scarcity affecting extrusion and binding formulation.
Bahia
Cocoa plantation proximity anchors chocolate-enrobed bar production for mass-market supermarket placement. ANVISA organic certification requirements are driving smallholder cooperative integration into supply chains for açaí and cupuaçu pulp infusions. Ilhéus and Itabuna processing zones specialize in native Amazonian ingredient sourcing for premium nutty-profile formats.
Brazil Snack Bar Market Competitive Environment
Channel-controlling players compete with product-specialist players across Brazil's snack bar sector. The market structure fragments between multinational packaged food conglomerates with cereal-to-bar ingredient pipelines and domestic health-channel specialists with pharmacy distribution depth. Three archetypes dominate: diversified conglomerates leveraging confectionery infrastructure, health-positioned domestic brands with drugstore penetration, and contract manufacturers serving private-label supermarket lines. Competitive moves center on co-manufacturing partnerships for asset-light expansion and cold-pressing technology licensing for functional premiumization.
Within the diversified conglomerate tier, The Kellogg Company and Mars Incorporated exemplify players translating cereal and confectionery expertise into bar formats. Nestlé occupies a position bridging mass-market volume and emerging functional nutrition positioning. Among domestic specialists, Nutrimental anchors health-channel distribution through pharmacy networks. M. Dias Branco represents the baked-goods-to-bars expansion archetype typical of Brazilian processed food conglomerates. PepsiCo and General Mills exemplify multinational snack portfolio diversification into the category. Mondelēz International and Alfred Ritter illustrate European confectionery heritage adapted to Brazilian taste preferences and regulatory requirements.
| Leading Market Players |
|---|
| The Kellogg Company |
| Nutrimental |
| Nestlé |
| Mars Incorporated |
| M. Dias Branco |
| PepsiCo |
| General Mills |
| Alfred Ritter |
| Mondelēz International |
| Others |
Value Chain & Pricing Dynamics
Barueri's automated extrusion facilities anchor Brazil's snack bar manufacturing capacity, and their proximity to São Paulo's hypermarket networks translates into downstream pricing power for ambient-stable formats. Cold-pressed protein bars from Minas Gerais command premium positioning through pharmacy channels where temperature-controlled logistics create natural margin buffers against mass-market price erosion.
Pricing Analysis
Certification level (ANVISA organic and front-of-package compliance-grade) creates the primary spread between premium functional bars and mass-market extruded formats. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity, with cold-pressed and probiotic-fortified variants at the top and conventional granola bars at the base. Cost compression in the standard tier is intensifying because imported whey protein exposure to currency fluctuation forces manufacturers to absorb margin hits or reformulate toward domestic dairy. Health-conscious consumers in Southeast metro areas show least price sensitivity for pharmacy-channel clinical nutrition formats, while supermarket impulse buyers in Northern Brazil exhibit highest elasticity.
Supply Chain Analysis
Upstream feedstock for Brazil's snack bar sector draws from Argentine dairy concentrates for whey and casein, Minas Gerais milk-processing corridors for domestic protein sourcing, and Bahia cocoa plantations for chocolate-enrobed mass-market lines. Pea-rice protein blends are hybridizing supply configurations as manufacturers qualify new South American legume suppliers alongside established dairy vendors. Single-source vulnerability concentrates in imported whey dependency, with Mercosur trade friction threatening input cost stability. Distribution runs through temperature-controlled logistics networks that cluster in Southeast industrial zones, leaving Northern and Center-West regions underserved by cold-chain infrastructure for refrigerated functional formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's snack bar market reflects concentrated buyer power as supermarket chains and pharmacy networks consolidate assortment decisions around fewer suppliers with proven ANVISA compliance track records. This consolidation elevates barriers for unproven entrants while rewarding incumbents with established health-channel relationships.
For Market Incumbents: Harden formulation agility through preemptive ANVISA warning-label reformulation using allulose and fiber-based bulking agents ahead of enforcement timelines. Deepen captive supply relationships with Minas Gerais dairy processors to reduce Argentine import exposure. Cold-pressing technology licensing represents a critical lever for functional premiumization against mass-market extrusion competitors. For New Entrants and Emerging Players: Northern Brazil's underpenetrated supermarket networks offer white-space expansion for ambient-stable granola formats with simplified logistics requirements. Center-West cross-training communities present subscription-based direct-to-door opportunities disintermediating traditional wholesale markups. Pharmacy channel partnerships with diabetes-management positioning provide the most penetrable go-to-market angle for clinical nutrition credibility. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic manufacturers with agile reformulation capabilities and established ANVISA regulatory navigation expertise. Long-term viability hinges on portfolio exposure to clean-label functional formats rather than confectionery-heritage indulgent lines. Cold-pressing equipment utilization rates signal inflection points for premium tier expansion capacity.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Preemptive Reformulation | Stealth sugar reduction using allulose avoids octagonal warning label triggers ahead of mandates. |
| Minas Gerais Dairy Integration | Captive whey and casein sourcing reduces Argentine import dependency and currency exposure. |
| Pharmacy Channel Expansion | Nutrimental's drugstore distribution model remains replicable for clinical nutrition and diabetes formats. |
| Cold-Pressing Technology Licensing | Low-temperature processing preserves heat-sensitive micronutrients for premium health food positioning. |
| Subscription Direct-to-Door Infrastructure | Digital fulfillment and retention analytics capture cross-training communities disintermediating supermarkets. |
Study Parameters
The analysis maps savory snacks, granola bars, baked formats, and confectionery-positioned lines, each validated through food technology directors, pharmacy category buyers, supermarket procurement managers, and co-manufacturing facility operators. Primary interview intelligence triangulates against ANVISA regulatory filings, Mercosur trade data, Nielsen retail audit records, and Brazilian customs import statistics for dairy concentrates and pea protein. Bottom-up volume builds from state-level production cluster capacity combine with top-down category spend estimates to anchor projection integrity.
Assumption-sets held ANVISA warning-label implementation timelines and PLI scheme incentive continuity fixed across the modeling period, while varying protein input cost scenarios and cold-chain logistics penetration rates. Segmentation dimensions span product type, distribution channel, end-user archetype, and flavor profile, with regional fitness-culture penetration intensity as a Brazil-specific overlay. CAGRs derive from regression-adjusted historical trajectory analysis against per-capita protein bar consumption benchmarks. Forecast inputs include whey protein import volume volatility and pharmacy channel square-meter expansion rates.
Practitioners should monitor ANVISA front-of-package warning label enforcement dates and Mercosur dairy trade policy shifts for early signals requiring forecast revision. Cross-checking against Argentine dairy export statistics and Brazilian supermarket same-store snack bar velocity data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Non-Potato Veggie Chips Market
Snacks
Premium Snacks Market
Snacks
Low Calorie Cookies Market
Snacks
Argentina Snack Bar Market
Snacks
Low Calorie Snacks Market
Snacks
Low-Fat Tortillas Market
Snacks
Healthy Fruit and Vegetable Chips Market
Snacks
Poland Snack Bar Market
Snacks
Low Fat Crackers Market
Snacks
Organic Snack Food Market
Snacks
Salty Puffed Snacks Market
Snacks
Europe Snack Bar Market
Snacks
Europe Extruded Snack Food Market
Snacks
Pretzel Salts Market
Snacks
Extruded Cereals Market
Snacks
Spain Energy Bar Market