
 Protein Bars Market | 2026-2036
Protein Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Bars Market Intelligence
The increasing use of asset-light contract manufacturing is reshaping competitive positioning by lowering barriers to entry for niche brands. This allows smaller companies to compete without massive capital investment in production facilities. Global food giants like Nestlé S.A. leverage extensive distribution channels to maintain market share. General Mills Inc. competes by diversifying its portfolio across different consumer segments, while The Simply Good Foods Company specializes in low-sugar and high-protein product lines.
Protein bars are supplemental food products formulated to deliver a high concentration of protein, typically ranging from 15 to 30 grams per serving. These bars utilize protein sources like whey, casein, soy, or pea protein and serve as convenient options for post-exercise muscle recovery, meal replacement, or as a healthy snack. While athletes remain a core end-user segment, demand from busy professionals is expanding rapidly. Vegan and low-sugar product types are experiencing the fastest category growth, appealing to health-conscious consumers.
Regulatory frameworks established by bodies such as the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern the market. These agencies enforce strict guidelines on nutritional labeling, health claims, and allergen declarations, directly impacting product formulation and packaging. Navigating consumer preferences between traditional protein sources like whey and emerging alternatives such as plant-based proteins remains a central strategic challenge for manufacturers.
Market Dynamics
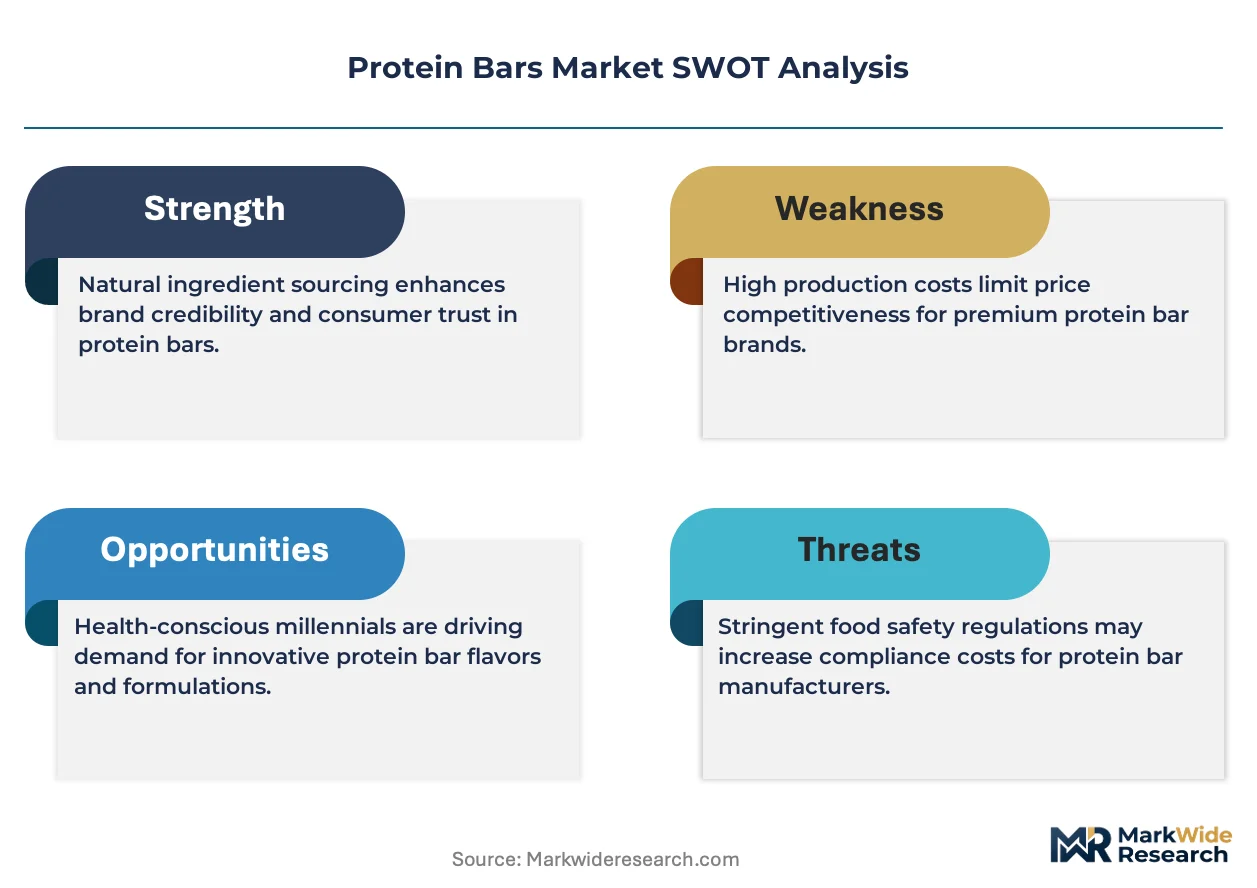
The central structural force shaping the protein bar market is the diversification of its consumer base beyond elite athletes to include lifestyle users and busy professionals. This shift compels manufacturers to innovate on flavor, format, and functional ingredients to meet a wider array of dietary preferences and health goals.
Growth Catalysts
- Mainstream Consumer Adoption:Demand from busy professionals in the United States and Europe for convenient meal replacements or healthy snacks is a primary catalyst, moving protein bars from niche sports nutrition stores to mainstream supermarkets.
- Plant-Based Protein Innovation:The development of higher-quality pea, rice, and soy protein isolates allows brands to cater to the fast-growing vegan and flexitarian consumer segments without compromising on protein content or texture.
- Regulatory Clarity:European Food Safety Authority (EFSA) mandates for transparent nutritional labeling and substantiated health claims build consumer trust and force manufacturers to improve product formulations, legitimizing the category.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of whey protein concentrate, a primary ingredient, directly impact production costs and retail pricing, creating margin pressure for manufacturers.
- Substitution Threat:Protein bars face intense competition from a wide range of convenient health-oriented snacks, including protein shakes, Greek yogurt, fortified beverages, and nut-based snacks.
- Formulation Complexity:Achieving a desirable taste, texture, and extended shelf life in high-protein and low-sugar bars remains a significant technical hurdle, particularly when using plant-based or alternative ingredients.
Strategic Opportunities
- Geographic Expansion:Untapped demand in markets across Latin America and Southeast Asia, where wellness trends and disposable incomes are rising, presents significant growth opportunities for first-movers.
- Functional Ingredients:Incorporating ingredients beyond protein, such as nootropics for cognitive support, prebiotics for gut health, or adaptogens for stress relief, opens new avenues for product differentiation.
- Channel Innovation:Direct-to-consumer (DTC) subscription models enable brands to bypass traditional retail, build direct customer relationships, and leverage data for personalized product development and marketing.
Industry Challenges
- Regulatory Navigation:Adhering to disparate and evolving food labeling and health claim regulations between jurisdictions, such as those governed by the FDA and EFSA, complicates global product launches and marketing strategies.
- Supply Chain Management:Ensuring the integrity of temperature-sensitive ingredients or finished products with natural or preservative-free formulations adds complexity and cost to logistics and distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Bars Market |
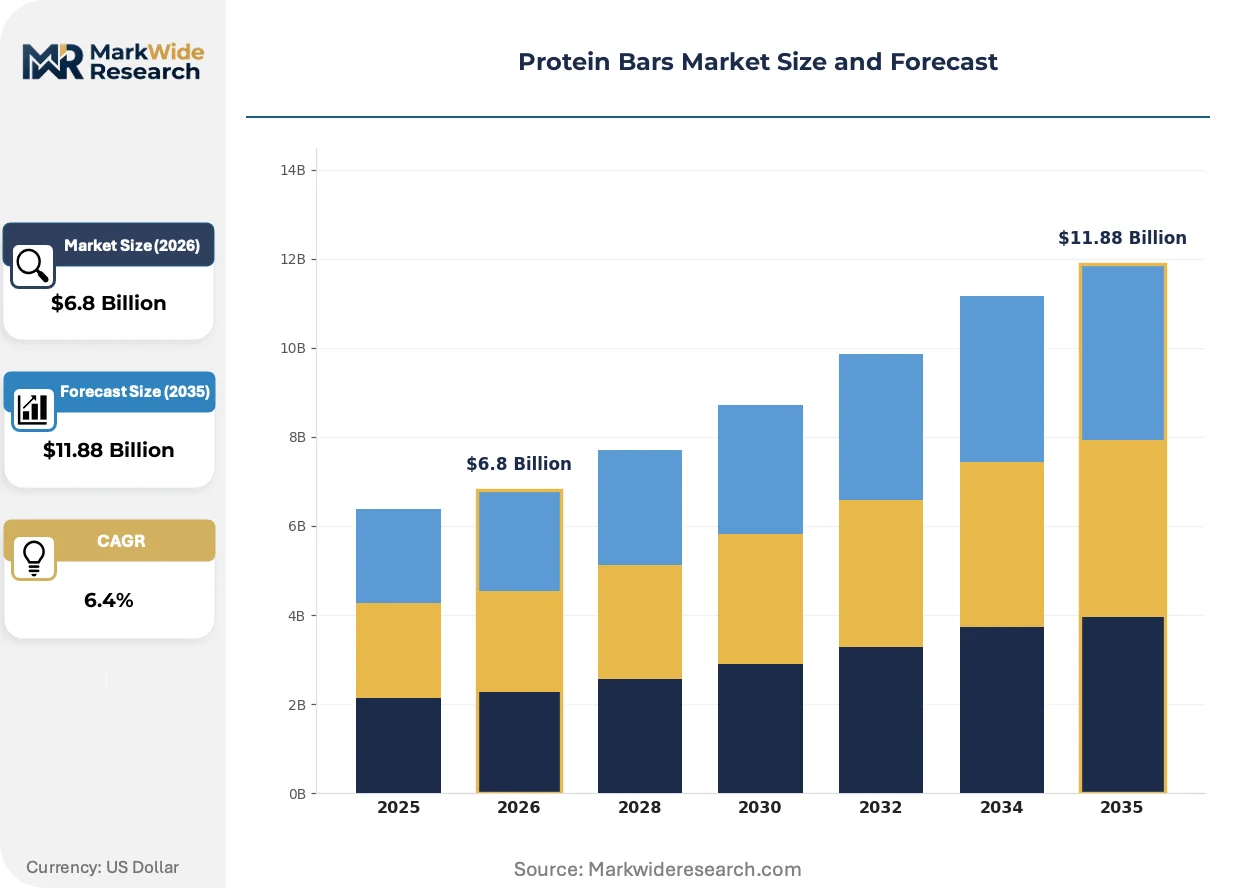
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Sugar, High Protein, Organic, Vegan End User: Fitness Enthusiasts, Weight Watchers, Athletes, Busy Professionals Flavor: Chocolate, Peanut Butter, Vanilla, Berry Packaging Type: Single Serve, Box, Bulk, Resealable Pouch |
| Companies Covered | Nestlé S.A, The Simply Good Foods Company, General Mills Inc, Premier Nutrition Company, NuGo Nutrition, Mars Incorporated, Kellanova, Amway Corp, Mondelez International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Bars Market Strategic Shifts & Innovations
Product formulation is actively reshaping the market as it moves beyond basic protein delivery. Innovations are now focused on creating bars that serve specific functional purposes, cater to precise dietary protocols like ketogenic or paleo, and align with ethical considerations such as sustainability.
Protein source technology is evolving to incorporate novel ingredients like cricket powder and algal proteins, prized for their sustainability credentials and unique nutritional profiles. Environmentally conscious consumers and early adopters, particularly in European markets, are showing initial interest in these alternatives. The market focus is migrating from a singular reliance on traditional whey and soy toward a more diversified and sustainable portfolio of protein ingredients.
The US Food and Drug Administration's updated rule mandating the declaration of "added sugars" on nutritional facts panels has had a significant impact. This regulation pressures manufacturers to reformulate products using alternative sweeteners like monk fruit, stevia, or allulose to appeal to health-conscious buyers. Low-sugar and keto-friendly product lines are most affected, leveraging compliance as a key marketing advantage.
Consumers are increasingly favoring curated, direct-to-consumer (DTC) subscription services over traditional bulk retail purchases. This behavioral shift disrupts established grocery and specialty store channels by offering greater personalization, convenience, and product discovery. The trend is most prominent in urban centers across North America and Western Europe, where digital-native brands utilize online platforms to target niche consumer segments effectively.
Protein Bars Market Segmentation
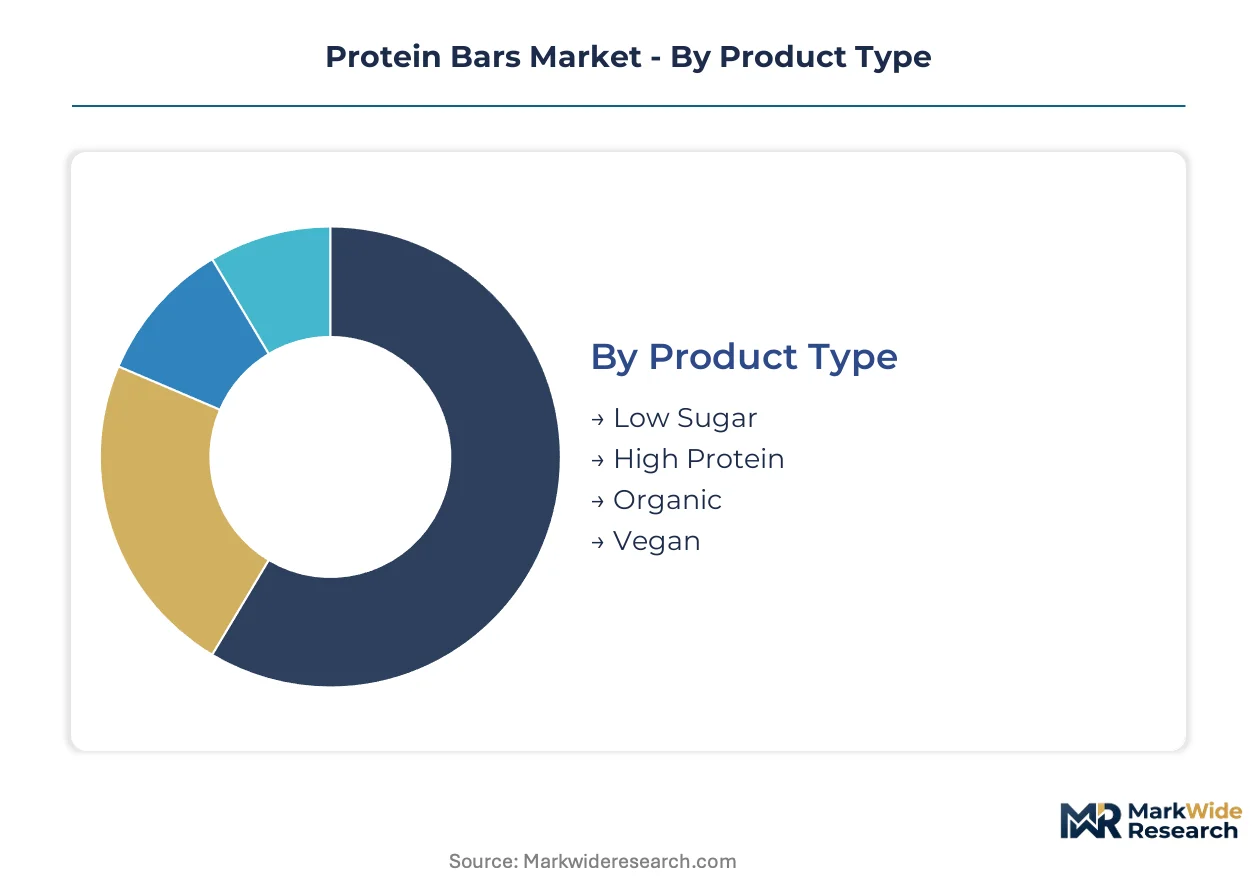
The Protein Bars Market exhibits significant segmentation, reflecting the diverse consumer preferences and functional requirements driving product innovation. Understanding these distinct segments allows manufacturers to tailor offerings and marketing strategies effectively. This granular view highlights areas of concentrated demand and emerging growth opportunities.
Product Type:
Product formulation across the Protein Bars Market primarily differentiates by functional composition and ingredient sourcing, catering to specific dietary goals.
- Low Sugar:These bars are formulated to minimize glycemic impact, often utilizing alternative sweeteners like stevia or monk fruit. Demand concentrates in health-conscious consumer groups in the United States and Germany, driven by concerns over metabolic health and weight management.
- Vegan:These products rely exclusively on plant-based protein sources such as pea, rice, or soy, avoiding all animal-derived ingredients. European markets like the UK and Sweden show strong demand for vegan options, appealing to ethical and environmental consumer preferences.
- High Protein:These bars deliver substantial protein content, typically exceeding 20 grams per serving, supporting muscle repair and satiety.
- Organic:Certified organic bars utilize ingredients grown without synthetic pesticides or fertilizers, appealing to consumers prioritizing natural and sustainable food choices.
High Protein bars hold installed capacity. Vegan options are rotating up the share rankings.
End User:
Consumer demographics significantly shape product development and marketing efforts within the Protein Bars Market, reflecting varied lifestyles and health objectives.
- Busy Professionals:These consumers seek convenient, nutrient-dense meal replacements or snacks to maintain energy levels during demanding schedules. Demand is particularly strong in urban centers across the United States and France, where time constraints necessitate on-the-go solutions.
- Athletes:This segment utilizes protein bars for muscle recovery, performance enhancement, and sustained energy during intense physical activity. Countries with strong sports cultures, such as Australia and Canada, show consistent demand from this core user base.
- Fitness Enthusiasts:These individuals incorporate protein bars into their diets to support general fitness goals, muscle maintenance, and healthy snacking.
- Weight Watchers:Consumers focused on weight management use protein bars as controlled-portion, high-satiety options to curb hunger and manage calorie intake.
Busy Professionals exert a growing influence on product innovation, pushing for enhanced flavor and convenience.
Flavor:
Sensory appeal remains a critical factor, with flavor profiles directly influencing consumer preference and repeat purchases in the Protein Bars Market.
- Chocolate:This classic flavor often incorporates cocoa powder or chocolate chips, providing a widely appealing taste profile. It commands substantial market share across the United States and the United Kingdom, consistently ranking as a top consumer choice.
- Peanut Butter:Offering a rich, nutty taste and often a denser texture, peanut butter flavors are popular for their satisfying qualities. This flavor maintains strong popularity in Canada and Australia, often combined with other ingredients like chocolate for variety.
- Vanilla:A versatile and often subtly sweet flavor, vanilla-based protein bars serve as a foundational option, sometimes paired with other complementary ingredients.
- Berry:These bars incorporate various fruit extracts or dried berries, providing a lighter, often tart or sweet, refreshing taste profile.
While traditional flavors like Chocolate maintain stable demand, Berry profiles are experiencing innovation to capture new consumer segments.
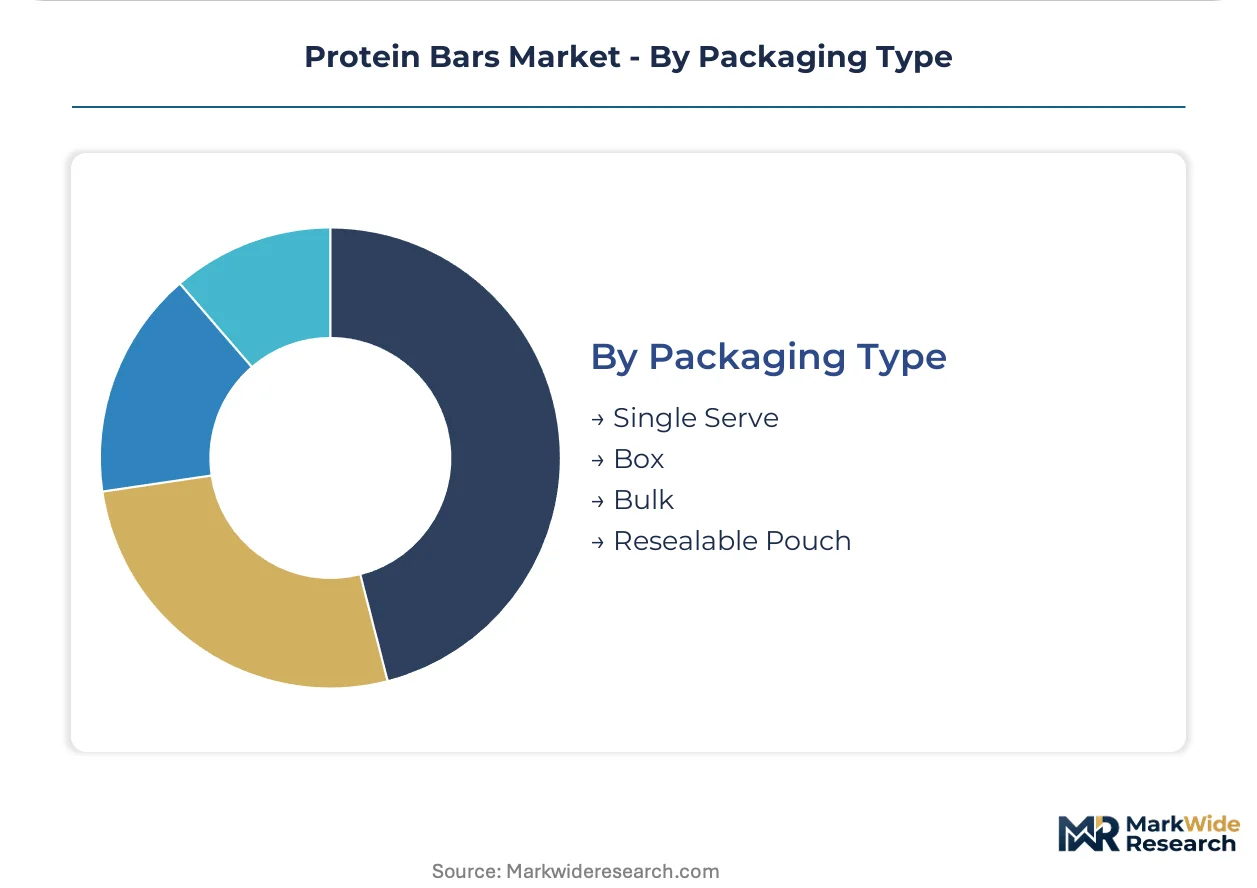
Packaging Type:
Packaging formats address diverse consumption occasions and purchasing habits, influencing convenience and product preservation for protein bars.
- Single Serve:Individually wrapped bars prioritize portability and immediate consumption, catering to on-the-go lifestyles and impulse purchases. This format dominates convenience store sales in Japan and Germany, appealing to consumers seeking quick, healthy snacks.
- Box:Multi-pack boxes typically contain several individually wrapped bars, offering value and convenience for planned consumption at home or work. Supermarkets across the United States and France widely stock this format, targeting regular users.
- Bulk:Larger quantities of unwrapped or minimally packaged bars cater to high-volume consumers or institutional buyers, often found in specialty stores or online.
- Resealable Pouch:This flexible packaging allows for multiple servings and maintains freshness, appealing to consumers who consume portions over time.
Single Serve packaging remains a consumer favorite for convenience, while Resealable Pouch designs are gaining traction due to perceived freshness and reduced waste.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European food safety regulations, particularly EFSA mandates for transparent labeling, significantly influence product formulation across the protein bars market. This regulatory clarity builds consumer trust and legitimizes the category. Demand is especially concentrated in the United States, driven by a strong health and wellness culture and busy professional lifestyles.
United States
United States consumers drive demand for convenient meal replacements and healthy snacks, particularly among busy professionals in urban centers. The US Food and Drug Administration (FDA) mandates clear nutritional labeling, including "added sugars" declarations, which pressures manufacturers to reformulate. Major food manufacturers in cities like Chicago and Los Angeles continuously innovate product offerings to meet evolving dietary preferences.
Germany
German consumers prioritize low-sugar and health-conscious protein bar options, reflecting a broader European trend towards metabolic health. The European Food Safety Authority (EFSA) guidelines on health claims directly impact product development and marketing strategies. Food industry clusters in Bavaria and North Rhine-Westphalia focus on functional ingredients and clean label formulations to appeal to discerning buyers.
United Kingdom
United Kingdom consumers show strong demand for vegan and ethically sourced protein bars, influenced by environmental and animal welfare concerns. The Food Standards Agency (FSA) enforces strict allergen declarations and nutritional information, ensuring product transparency. London and Manchester serve as innovation hubs for plant-based protein bar brands, developing new textures and flavors.
France
French busy professionals seek convenient, nutrient-dense options for on-the-go consumption, integrating protein bars into their daily routines. European Union regulations, including those from EFSA, shape ingredient approval and labeling requirements across the market. Food innovation centers in Paris and Lyon develop novel flavor profiles for sophisticated palates, enhancing sensory appeal.
Canada
Canadian athletes and fitness enthusiasts consistently demand protein bars for muscle recovery and sustained energy during physical activity. Health Canada guidelines govern nutritional content and permissible health claims on food products, ensuring consumer safety. Toronto and Vancouver host a growing number of specialized sports nutrition brands, catering to performance-oriented consumers.
Protein Bars Market Key Industry Players
On the supply side, the industry is characterized by a blend of asset-light niche players and established global food conglomerates. Smaller companies leverage contract manufacturing to enter the market without significant capital investment in production facilities. This structure fosters diverse strategic archetypes, including large-scale brand managers, specialized functional ingredient innovators, and direct-to-consumer disruptors. Dominant competitive moves include extensive distribution network utilization and continuous portfolio diversification across consumer segments.
Global food giants, exemplified by Nestlé S.A. and General Mills Inc., leverage their extensive distribution channels and brand portfolios to maintain market share. These corporations often diversify across various consumer segments, from mainstream snacks to performance nutrition. The Simply Good Foods Company represents a specialized archetype, focusing on low-sugar and high-protein product lines to cater to specific dietary preferences. These entities collectively shape product availability and consumer choices across the market.
| Leading Market Players |
|---|
| Nestlé S.A |
| The Simply Good Foods Company |
| General Mills Inc |
| Premier Nutrition Company |
| NuGo Nutrition |
| Mars Incorporated |
| Kellanova |
| Amway Corp |
| Mondelez International |
| Others |
Cost & Logistics Intelligence
Commodity volatility, particularly in whey protein, determines both pricing tier spreads and supply chain shape for protein bars. This fluctuation directly impacts manufacturing costs, influencing retail pricing strategies across premium and economy segments.
Pricing Analysis
Ingredient quality and certification create the primary pricing spread for protein bars. The market operates on a per-unit transactional model, with some value-based offerings for multi-packs. Brand premium and organic certification drive differentiation, while private labels and substitute snacks exert downward pricing pressure. Athletes exhibit low price sensitivity for performance-oriented bars, unlike weight watchers who prioritize cost-effective options.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support ingredient procurement for protein bar manufacturers. Supply concentration for whey protein centers in regions like the United States and New Zealand, while plant-based proteins source globally. Raw material dependencies include pea protein, soy protein, and alternative sweeteners. Commodity price volatility for these inputs poses a structural risk, impacting downstream multi-channel distribution through supermarkets and specialty stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The protein bars market offers a defensive moat story, driven by regulatory entrenchment around nutritional claims and transparent labeling requirements.
For Market Incumbents:Harden distribution networks against emerging direct-to-consumer brands to maintain market share. Invest in research and development for novel plant-based protein sources, mitigating input cost volatility from traditional whey. Focus on robust regulatory compliance with FDA and EFSA guidelines as a strategic barrier to entry. Diversify product portfolios across different consumer segments.
For New Entrants and Emerging Players:Build out niche product lines targeting specific dietary protocols like ketogenic or paleo diets. Target underpenetrated geographic markets across Latin America and Southeast Asia for first-mover advantage. Leverage direct-to-consumer models for personalized product discovery and direct customer relationships. Focus on ingredient transparency and clean label formulations for market penetration.
For Investors and Strategic Acquirers:EFSA and FDA labeling mandates reshape the acquisition landscape for protein bar manufacturers, favoring transparent and compliant brands. Long-term viability rests on agile players with diversified protein portfolios and strong brand equity. Seek acquisition targets with proven innovation in plant-based ingredients or functional additives. Watch for consolidation among specialized ingredient suppliers as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Brand Extension into Functional Categories | Expands market reach by catering to diverse health and wellness needs beyond basic protein. |
| Direct-to-Consumer (DTC) Channel Development | Builds direct customer relationships and offers valuable data for product personalization. |
| Premium Tier Introduction with Novel Ingredients | Captures higher margins by offering innovative formulations and unique flavor profiles. |
| Distribution Channel Expansion in Emerging Markets | Unlocks new revenue streams by tapping into rising disposable incomes and wellness trends. |
| Sustainability Repositioning for Plant-Based Offerings | Appeals to environmentally conscious consumers and aligns with ethical purchasing preferences. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to gather comprehensive market insights. Primary interviews involved brand managers, R&D specialists, retail buyers, and sports nutritionists. Secondary data sources included food industry reports, regulatory filings from the FDA and EFSA, and consumer dietary surveys. This approach facilitated both bottom-up and top-down triangulation for robust data validation.
Quantitative models were calibrated using historical market performance across the analysis window. Segmentation dimensions modeled included product type, end-user, flavor, packaging type, and regional adoption patterns. Compound annual growth rates were derived from both volume and value projections. Forecast inputs included protein ingredient availability trends and evolving consumer health preferences.
The forecast holds incumbent behavior within observed patterns; aggressive moves by global food giants or niche disruptors would shift outcomes. Projections reflect current market understanding and prevailing consumer preferences. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Extruded Snacks Market
Snacks
Better for You Snacks Market
Snacks
Low Calorie Crackers Market
Snacks
United States Snack Bar Market
Snacks
High Carb Low Fat Snack Market
Snacks
Forti Flakes Market
Snacks
Organic Chips Market
Snacks
Peanut Butter Keto Snacks Market
Snacks
France Energy Bar Market
Snacks
Organic Snacks Market
Snacks
Plant-Based Snacks Market
Snacks
Mediterranean Lentil Crisps and Inclusion Bases Market
Snacks
Global Protein Snack Market
Snacks
Baked Savoury Snacks Market
Snacks
North America Pretzel Market
Snacks
North America Cereal Bar Market