
 Dried Fruit Snacks Market | 2026-2036
Dried Fruit Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Fruit Snacks Market Insights
Capital-intensity divergence between integrated growers and contract-reliant packers is bifurcating competitive returns in dried fruit snacks. Sun-Maid Growers of California leverages captive vineyard and orchard assets to control raw material quality through the drying cycle. Archer Daniels Midland Company anchors its position through bulk ingredient supply contracts with multinational food manufacturers. Meduri Farms differentiates via small-batch artisan drying technology that preserves volatile flavor compounds.
Dried fruit snacks consist of whole, sliced, or diced fruits dehydrated to moisture levels below 20 percent through air drying, freeze drying, or osmotic concentration, yielding shelf-stable products with concentrated sugars, fibers, and micronutrients for direct consumption or food manufacturing inclusion. Resealable bags dominate retail velocity due to portion control and portability, while bulk packaging captures margin pools in foodservice and industrial channels. Dried mangoes and dried cranberries represent the fastest-expanding product types, driven by tropical flavor novelty and functional berry positioning in health-oriented snacking.
FDA food safety rules under the Food Safety Modernization Act impose preventive controls on dried fruit processing facilities, while EFSA maximum residue limits for sulphur dioxide and ochratoxin A shape import acceptance criteria for European-bound shipments. USDA organic certification and EU organic regulation create dual compliance pathways that segment premium pricing tiers. Stakeholders must monitor evolving sulphite labeling thresholds and invest in alternative preservation technologies to maintain cross-border market access.
Market Dynamics
Clean-label procurement mandates from EU snack bar manufacturers are compressing sulphite tolerance thresholds and forcing rapid adoption of alternative preservation technologies across the supply base.
Growth Catalysts
- EFSA contaminant limits:Tightening maximum residue thresholds for ochratoxin A and sulphur dioxide in dried produce imports are accelerating investment in advanced sorting and drying infrastructure among European-bound suppliers.
- Snack bar inclusions:Clean-label dried fruit procurement by bar and cafe chains is expanding volume commitments for minimally processed, low-sulphite ingredient streams.
- Germany organic retail:Concentrated demand through the country's organic supermarket channel is pulling premium-priced, certified organic dried mango and cranberry volumes.
Market Restraints
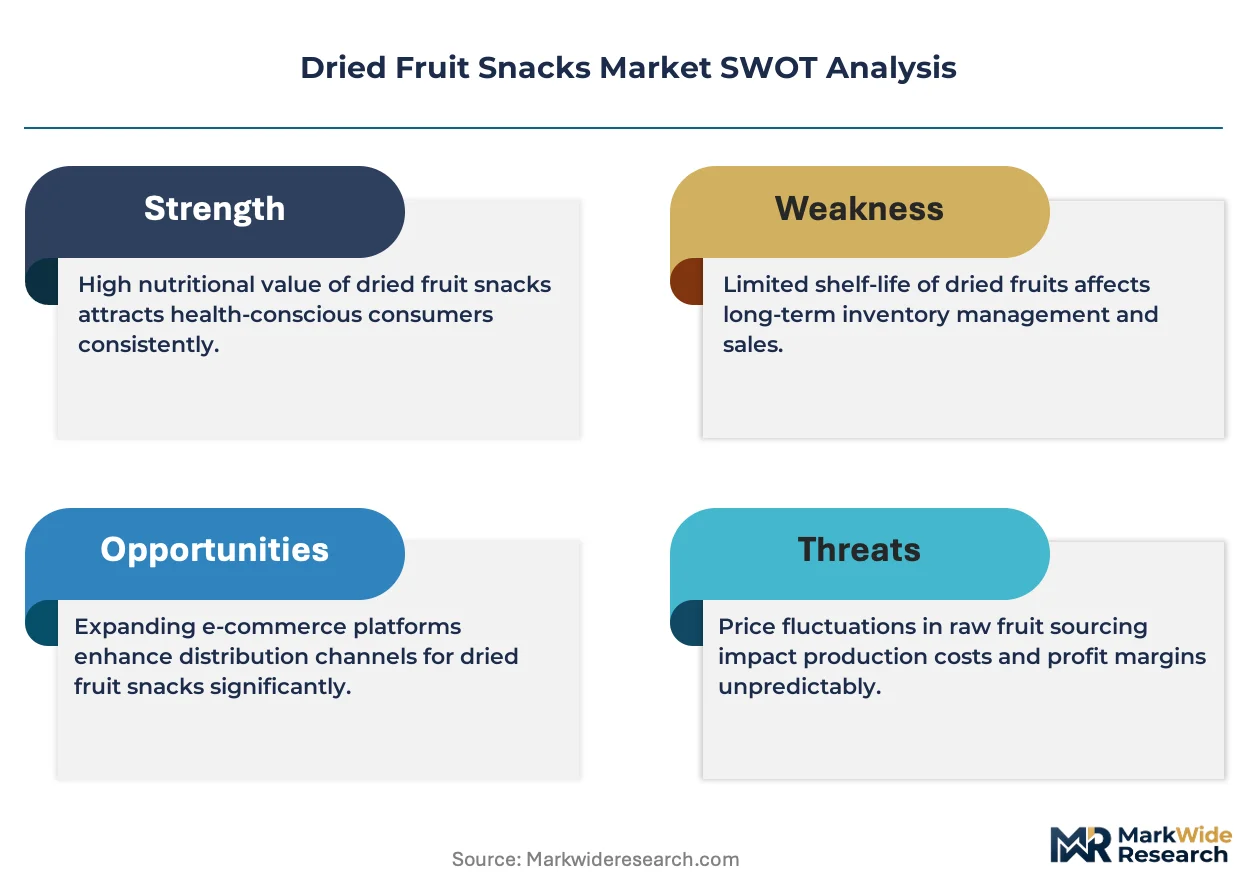
- Input cost volatility:Fresh fruit procurement costs fluctuate with California Central Valley water allocation cycles and Turkish apricot harvest variability, compressing packer margins during deficit years.
- Supply concentration risk:Premium organic dried mango supply concentrates in Thai and Philippine processing clusters, exposing buyers to climate-driven yield shocks and port congestion.
- Regulatory friction:Divergent USDA organic and EU organic certification pathways create dual compliance burdens that segment export eligibility and inflate documentation costs.
Strategic Opportunities
- Freeze-drying convergence:Integration of microwave-assisted drying with modified atmosphere packaging is opening premium texture-positioned products for direct-to-consumer channels.
- India underpenetration:The country's nascent organized retail and airport concession channels present first-mover positioning for portion-controlled, resealable dried fruit formats.
- Farm to Fork tailwind:The EU strategy's traceability mandates are rewarding suppliers with integrated farm-processing operations and blockchain-enabled lot tracking.
Industry Challenges
- Preservation chemist scarcity:Formulation expertise in natural antioxidant systems and controlled water activity management commands premium compensation and extends R&D timelines.
- Capex intensity:Commercial-scale freeze-drying lines and optical sorter installations require substantial capital commitments that strain contract-reliant packers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Fruit Snacks Market |
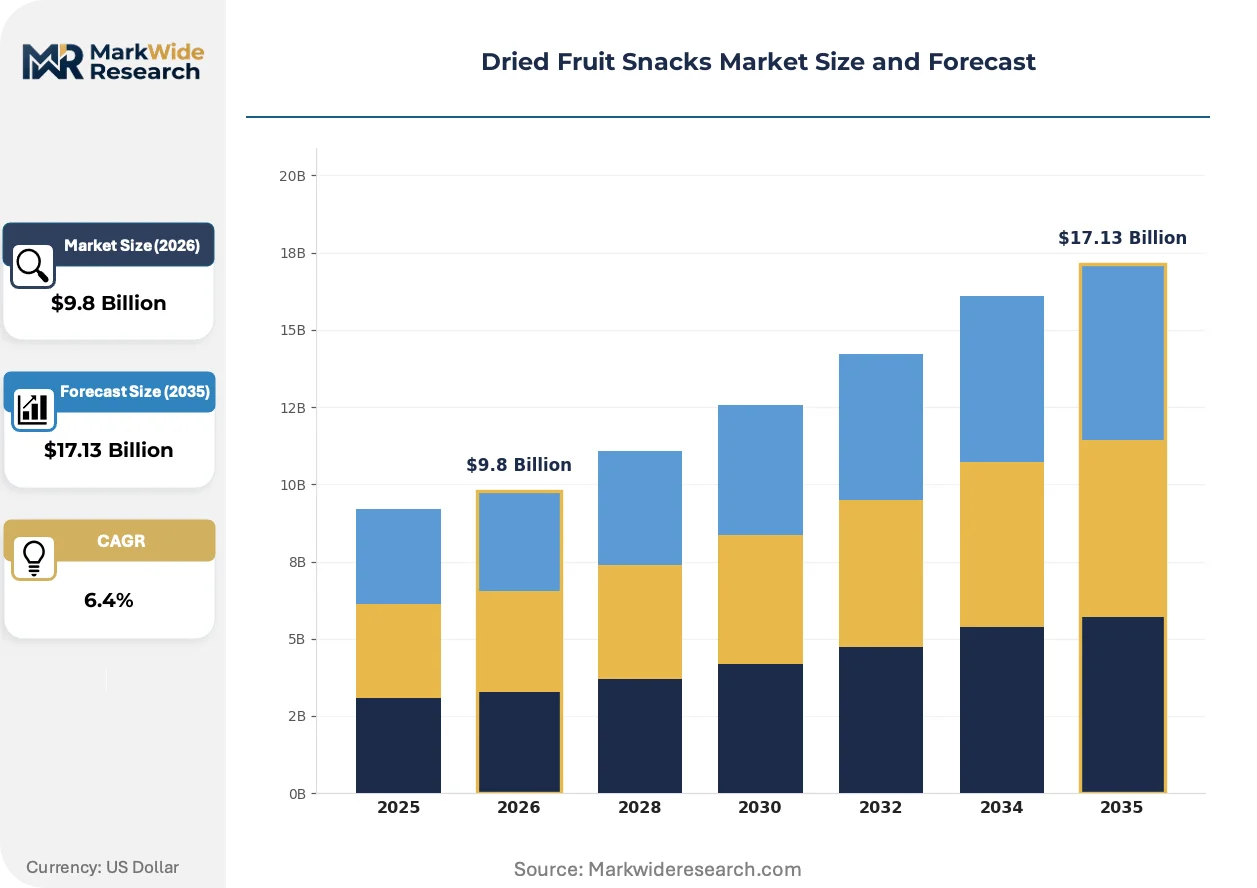
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried Apples, Dried Mangoes, Dried Apricots, Dried Cranberries Packaging Type: Resealable Bags, Bulk Packaging, Glass Jars, Pouches Distribution Channel: Online, Supermarkets, Health Food Stores, Convenience Stores End User: Retail Consumers, Food Manufacturers, Cafes, Snack Bars |
| Companies Covered | Sun-Maid Growers of California, Archer Daniels Midland Company, Meduri Farms, Chaucer Foods Ltd, Bergin Fruit and Nut Company, Brusco Food Group, AGRANA Beteiligungs-AG, Sunsweet Growers Inc, Graceland Fruit, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Fruit Snacks Market Trends and Innovations
Dehydration technology maturation and regulatory chemistry constraints are jointly redefining product format possibilities and procurement qualification standards.
Freeze-drying systems with integrated vacuum microwave stages are displacing conventional hot-air tunnels in premium product lines. Snack bar manufacturers and specialty retailers are specifying these textures for inclusion and private-label programs. The shift is compressing acceptable moisture uniformity tolerances and raising capital barriers for commodity packers.
REACH chemical authorization requirements are restricting traditional sulphite-based preservation aids in EU-bound shipments. Processors are reformulating with ascorbic acid, citric acid, and rosemary extract blends to maintain shelf stability. The transition is most acute in German and Dutch import channels, where organic certification overlap intensifies scrutiny.
Foodservice buyers are consolidating procurement through specialized ingredient distributors rather than commodity brokers. Dried fruit specification sheets now demand lot-level mycotoxin documentation and allergen segregation protocols. This behavioral shift is most visible in France and Italy, where artisan bakery and gelato manufacturer quality audits have tightened supplier qualification cycles.
Dried Fruit Snacks Market Segmentation
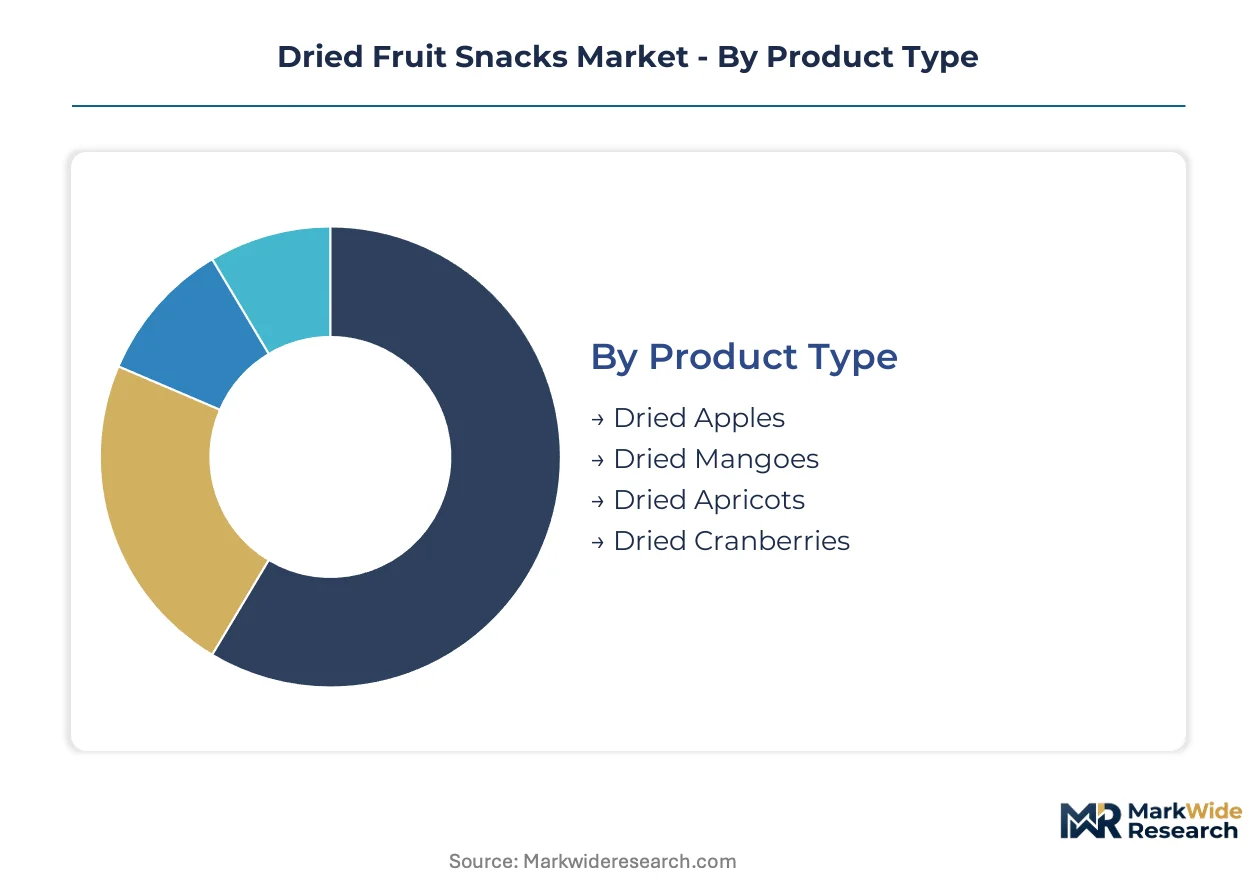
Segmentation in dried fruit snacks reveals how preservation chemistry, portion formats, and channel access create divergent margin pools. Procurement specifications from snack bar manufacturers and organic retailers now override traditional commodity grading, reshaping which product and packaging configurations command premium positioning.
Product Type:
Substitute pressure from fresh-cut fruit cups and ambient fruit purees hits sliced formats harder than whole-fruit pieces, concentrating investment in texture-differentiated lines.
- Dried Mangoes:Tropical flavor novelty drives snack bar inclusion demand, with Thai and Philippine processing clusters supplying clean-label, low-sulphite slices to German organic retailers. Freeze-dried variants capture shelf-space in airport concessions and specialty grocers seeking premium texture differentiation.
- Dried Cranberries:Functional berry positioning with proanthocyanidin content targets health-oriented snacking, particularly in North American trail-mix and cereal applications. EFSA sulphur dioxide thresholds force rapid reformulation with ascorbic acid and rosemary extract blends for EU-bound shipments.
- Dried Apples:Washington State and Chinese Shandong Province orchards supply conventional rings and dices for foodservice baking channels.
- Dried Apricots:Turkish Malatya and California Central Valley origins split between sulphured bright-orange commodity grades and organic brown natural-dried premium tiers.
Dried mangoes anchor the volume base while dried cranberries gain share at the steepest rate.
Packaging Type:
Cost tier separation between single-serve convenience formats and industrial-scale bulk supply determines which packers can serve both retail velocity and foodservice margin pools.
- Resealable Bags:Stand-up pouches with zip-lock closures dominate retail velocity through portion control and portability, particularly in German organic supermarket channels. Modified atmosphere lining extends shelf stability for clean-label products omitting sulphite preservatives.
- Bulk Packaging:Food manufacturers and industrial bakeries procure 10-25kg cartons or fiber drums, capturing margin pools unavailable to retail-focused packers. Optical sorting and metal detection capabilities now qualify suppliers for European snack bar manufacturer audits.
- Pouches:Single-serve 30-50g formats target convenience store impulse placement and airline catering contracts.
- Glass Jars:Premium gifting and pantry positioning in French and Italian retail favors visual product display with artisan branding cues.
Bulk packaging anchors the volume base while resealable bags expand most quickly.
Distribution Channel:
Customer type concentration in health-conscious urban demographics pulls volume toward channels with organic certification credibility and ingredient transparency protocols.
- Supermarkets:Mass-market penetration depends on slotting fees and promotional calendar alignment, with private-label programs squeezing branded suppliers on sulphite-free specifications. German REWE and EDEKA chains now mandate blockchain-enabled lot tracking for organic dried mango lines.
- Online:Direct-to-consumer subscription models and marketplace fulfillment bypass traditional distributor markups, enabling freeze-dried premium textures at accessible price points. Amazon and specialist health-food platforms drive trial of novel formats like dried fruit clusters.
- Health Food Stores:Bio-certificate verification and minimal-ingredient positioning support margin premiums unavailable in conventional grocery.
- Convenience Stores:Grab-and-go placement favors 100-calorie portion packs with high-visibility front-of-store positioning.
Supermarkets anchor the volume base while online climbs the fastest.
End User:
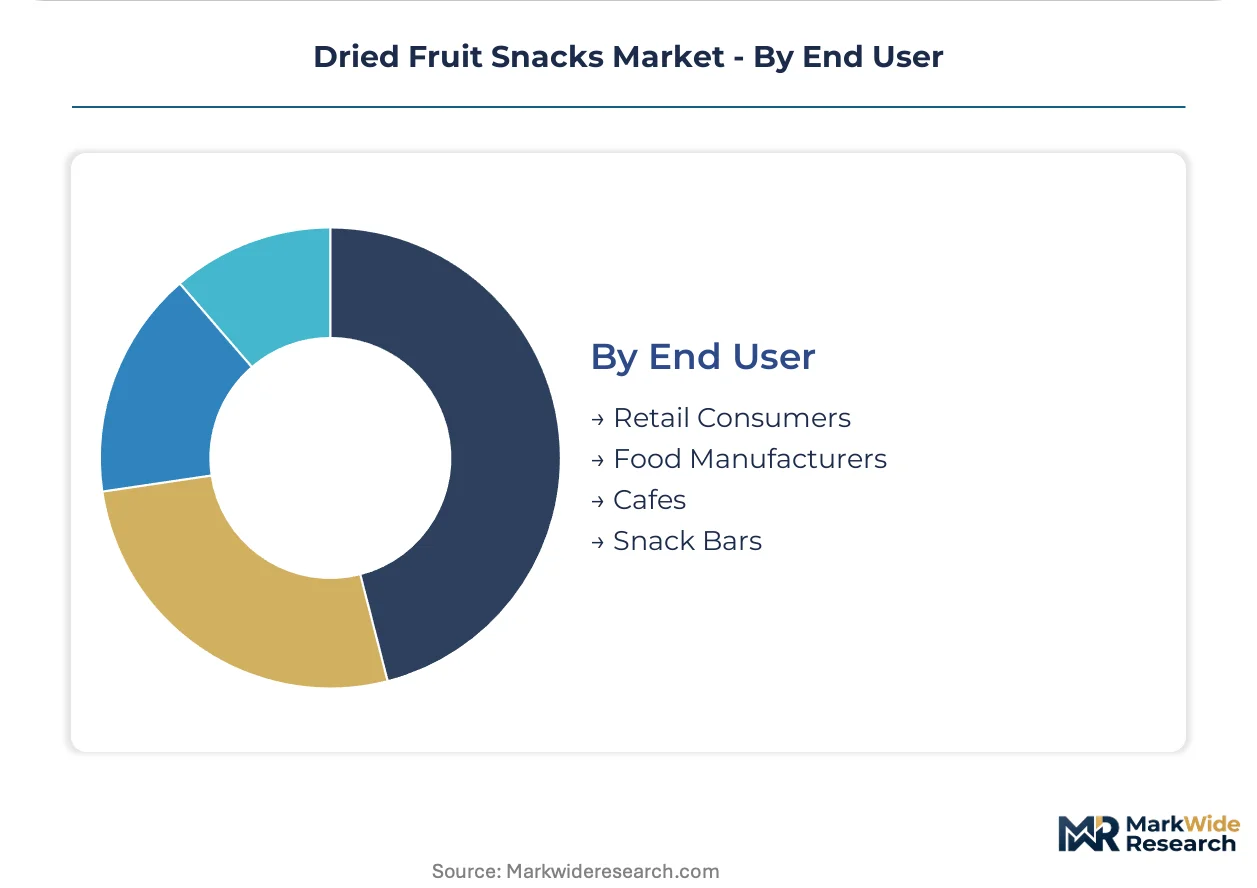
Application maturity separates established food manufacturing inclusion demand from emerging cafe and snack bar procurement with stricter clean-label mandates.
- Snack Bars:Clean-label procurement mandates compress sulphite tolerance thresholds, forcing packers to adopt ascorbic acid and citric acid preservation systems. Kind and Clif Bar specifications now require lot-level mycotoxin documentation and allergen segregation protocols.
- Food Manufacturers:Cereal, bakery, and confectionery inclusion demand concentrates volume in bulk supply contracts with multinational processors like Archer Daniels Midland. Specification sheets increasingly demand moisture uniformity tolerances achievable only through integrated drying operations.
- Cafes:Artisan bakery and gelato manufacturers in France and Italy conduct quality audits tightening supplier qualification cycles.
- Retail Consumers:Direct consumption demand fragments across impulse, pantry-stocking, and gifting occasions with divergent packaging expectations.
Food manufacturers anchor the volume base while snack bars gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in German organic retail channels exceeds mass-market margins in the United States by substantial multiples. This asymmetry reflects divergent regulatory stringency and certification premiums rather than raw material cost differentials. The following country breakdowns trace how local compliance regimes and channel structures reshape competitive returns.
Germany
Organic supermarket chains REWE and EDEKA mandate blockchain-enabled lot tracking for dried mango lines. EFSA sulphur dioxide thresholds under REACH chemical authorization force rapid reformulation with ascorbic acid and rosemary extract blends. Processing demand concentrates in Hamburg's import handling facilities, where optical sorting capabilities qualify suppliers for snack bar manufacturer audits.
United States
California Central Valley water allocation cycles compress packer margins during deficit years. FDA preventive controls under the Food Safety Modernization Act impose facility-level compliance burdens on dried fruit processors. Sun-Maid Growers leverages captive vineyard assets in the San Joaquin Valley to control raw material quality through the drying cycle.
Thailand
Clean-label dried mango supply concentrates in Bangkok-adjacent processing clusters for German organic retail export. Climate-driven yield shocks and port congestion expose buyers to supply interruption risks. Thai processors invest in microwave-assisted drying infrastructure to capture premium texture positioning for airport concession channels.
Turkey
Malatya Province orchards split output between sulphured bright-orange commodity grades and organic brown natural-dried premium tiers. Turkish apricot harvest variability creates input cost volatility for European-bound shipments. Local packers face tightening EFSA ochratoxin A maximum residue limits that accelerate investment in advanced sorting infrastructure.
France
Artisan bakery and gelato manufacturers in Provence-Alpes-Côte d'Azur conduct quality audits tightening supplier qualification cycles. ANSM and DGCCRF enforcement of sulphite labeling thresholds intensifies scrutiny of import documentation. Paris-based ingredient distributors consolidate foodservice procurement away from commodity brokers toward specialized supply chains.
Dried Fruit Snacks Market Competitive Landscape
Concentration sits with integrated grower-processors controlling captive orchard assets and contract-reliant packers dependent on spot procurement. The vendor base splits between scale-driven bulk ingredient suppliers, artisan small-batch specialists, and regional private-label fabricators. Strategic moves center on backward integration into orchard ownership and adoption of freeze-drying technology for premium texture differentiation.
Among California-based grower cooperatives, Sun-Maid Growers of California exemplifies the integrated archetype through captive vineyard control. Archer Daniels Midland Company anchors the bulk ingredient supply tier with multinational food manufacturer contracts. Meduri Farms occupies the artisan specialist position through small-batch drying technology deployment. These three patterns represent the dominant competitive configurations reshaping procurement qualification standards.
| Leading Market Players |
|---|
| Sun-Maid Growers of California |
| Archer Daniels Midland Company |
| Meduri Farms |
| Chaucer Foods Ltd |
| Bergin Fruit and Nut Company |
| Brusco Food Group |
| AGRANA Beteiligungs-AG |
| Sunsweet Growers Inc |
| Graceland Fruit, Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Thai dried mango processors and German organic retailers lock in supply access while providing price visibility against volatile harvest cycles. These contracts anchor premium positioning for clean-label shipments while insulating buyers from spot-market spikes triggered by climate-driven yield shocks in Southeast Asian processing clusters.
Pricing Analysis
Customization-premium spreads separate configured-to-order clean-label specifications from standard sulphite-treated commodity grades. Three-tier pricing structure across premium organic, standard conventional, and economy bulk tiers reflects certification level and moisture uniformity tolerances. Pricing pressure stems from California Central Valley water allocation cycles compressing packer margins during deficit years. Food manufacturers exhibit highest price sensitivity due to volume scale and substitution options, while German organic retailers absorb premiums for traceability guarantees.
Supply Chain Analysis
Thailand and the Philippines anchor clean-label dried mango supply for European health-snack channels. Raw material dependencies center on fresh fruit procurement from tropical orchard belts, sulphite-free preservation chemistry, and optical sorting equipment for mycotoxin compliance. Single-source vulnerability concentrates in Bangkok-adjacent processing clusters exposed to monsoon disruption and port congestion. Distribution runs through Hamburg import handling facilities and specialized ingredient distributors serving snack bar manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label dehydration technology and tightening EFSA contaminant thresholds are disrupting competitive positioning in dried fruit snacks. This regulatory-technological inflection rewards early movers in alternative preservation systems and traceability infrastructure.
For Market Incumbents: Compound defensive positioning through backward integration into captive orchard assets in California and Turkey. Acquire optical sorting capabilities to meet snack bar manufacturer audit requirements. Lock in long-term offtake agreements with German organic retailers before alternative preservation chemistry expertise becomes scarcer. For New Entrants and Emerging Players: Differentiate on freeze-dried texture positioning for airport concession and direct-to-consumer channels. Target India's underpenetrated organized retail sector with portion-controlled resealable formats. Pursue white-label partnerships with European snack bar brands seeking clean-label ingredient streams. For Investors and Strategic Acquirers: Integrated grower-processors with blockchain-enabled lot tracking capabilities represent the highest-conviction acquisition archetype. Monitor EFSA sulphur dioxide threshold enforcement as the signal indicating acceleration in alternative preservation technology deployment. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale alone.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Assets | Sun-Maid Growers leverages captive vineyard control to secure raw material quality through drying cycles. |
| Alternative Preservation Technology Adoption | Ascorbic acid and rosemary extract blends replace sulphite systems for REACH-compliant EU shipments. |
| Freeze-Drying Infrastructure Investment | Microwave-assisted drying captures premium texture positioning in specialty retail channels. |
| Blockchain-Enabled Traceability Deployment | REWE and EDEKA mandate lot tracking for organic dried mango procurement qualification. |
| Specialized Ingredient Distributor Partnerships | Foodservice buyers in France and Italy consolidate procurement away from commodity brokers. |
Research Methodology
A spread of perspectives from dried fruit packer operations managers, organic retailer category buyers, snack bar manufacturer procurement leads, and food safety compliance officers converged on the working assumptions. Primary fieldwork combined with secondary validation from FDA Food Safety Modernization Act filings, EFSA maximum residue limit documentation, USDA organic certification records, and customs trade data. Bottom-up volume modeling triangulated against top-down market sizing across product type, packaging format, and distribution channel dimensions.
Segmentation dimensions modeled include preservation chemistry tier, portion format scale, and end-use application maturity across the projection horizon. CAGRs derived from trend extrapolation anchored in historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs incorporated California Central Valley water allocation cycles and Turkish apricot harvest variability as supply-side constraints.
Material uncertainties — climate-driven yield shocks, regulatory threshold revisions, and preservation chemistry transition timelines — sit outside the modeled envelope. Forecasts reflect documented assumptions about clean-label adoption rates and EFSA enforcement intensity. Recalibration cycles align with material shifts in EU Farm to Fork Strategy implementation and alternative drying technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Better for You Snacks Market
Snacks
Salty Puffed Snacks Market
Snacks
France Energy Bar Market
Snacks
Pretzel Salts Market
Snacks
Healthy Fat-Free Snacks Market
Snacks
Low Calorie Crackers Market
Snacks
Poland Snack Bar Market
Snacks
South America Protein Bar Market
Snacks
Roasted Corn Market
Snacks
Australia Snack Bar Market
Snacks
Cereal Bars Market
Snacks
North America Savory Snacks Market
Snacks
Sweet Potato Chips Market
Snacks
China Snack Bar Market
Snacks
North America Potato Chips Market
Snacks
On-The-Go Healthy Snacks Market