
 Saudi Arabia Snack Bar Market | 2026-2036
Saudi Arabia Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Snack Bar Market Analytics
The capital-intensity divergence between multinational and domestic players is rotating competitive dynamics toward manufacturing scale and cold-chain infrastructure. Mondelez International, Inc leverages its global procurement networks to secure specialty nut and dried-fruit supplies at volume. Almarai anchors its position through backward integration into dairy-based protein ingredients and refrigerated distribution assets across the Kingdom. Nestle S.A. differentiates via formulation expertise in reduced-sugar binders and texture stabilization.
A snack bar is a compact, shelf-stable food product formed from cereals, proteins, fruits, or nuts bound by syrups, hydrocolloids, or dairy derivatives, typically ranging from 30 to 80 grams and engineered for portability with moisture contents below 15 percent to ensure ambient stability. Granola bars dominate retail shelf space due to established consumer familiarity and lower per-unit production complexity, while protein bars command premium positioning among fitness enthusiasts seeking macronutrient density. The ingredient dimension shows gluten-free and vegan claims gaining velocity as Saudi consumers with dietary restrictions expand beyond niche segments. Online retail channels are capturing disproportionate growth among busy professionals seeking subscription-based replenishment models.
SFDA mandates strict nutrition labeling and health-claim substantiation for packaged snacks, compelling reformulation investments across domestic and imported portfolios. Halal certification requirements administered by SASO and religious oversight bodies govern gelatin sourcing, flavor alcohol content, and cross-contamination protocols, effectively filtering market access for non-compliant suppliers. Stakeholders must monitor evolving sugar-tax discussions and front-of-pack labeling proposals that could reshape margin structures and portfolio prioritization decisions.
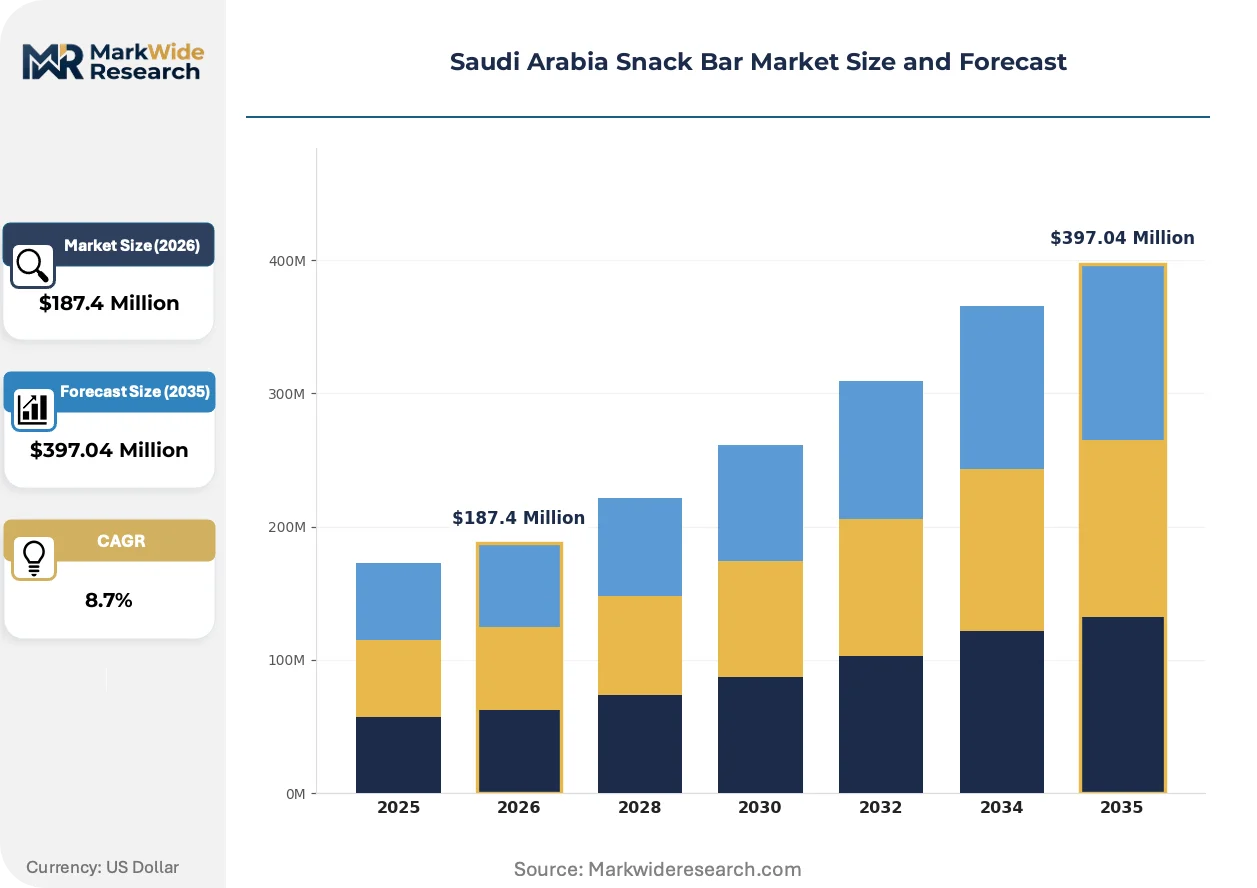
Market Dynamics
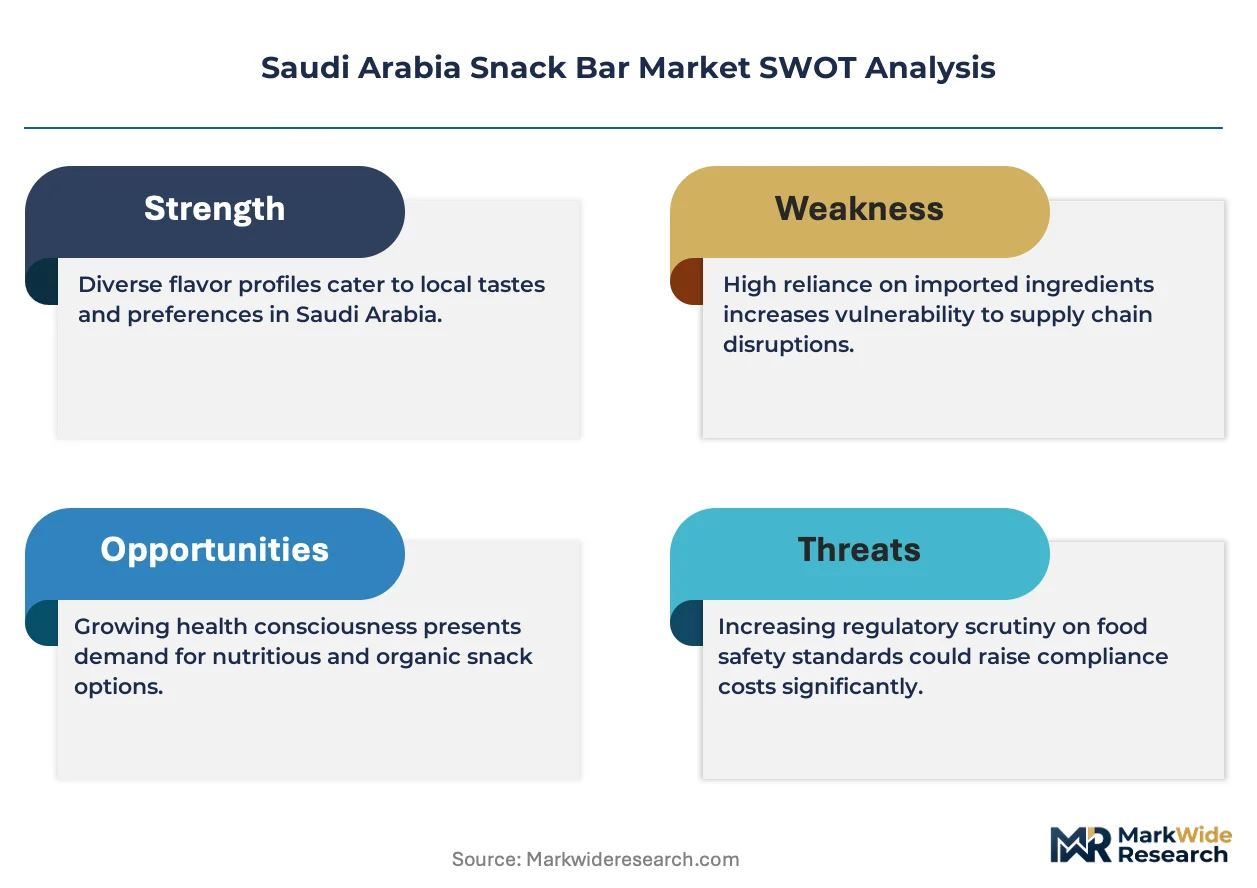
SFDA nutrition labeling mandates and halal certification protocols are compressing formulation flexibility while elevating compliance costs across Saudi Arabia's snack bar value chain.
Growth Catalysts
- Fitness Culture Expansion:Riyadh and Jeddah gym memberships are surging among urban professionals, creating concentrated demand for protein-fortified formats that deliver macronutrient density without meal preparation.
- Modern Retail Penetration:Hypermarket chains are dedicating expanded shelf space to functional snacking categories, with refrigerated sections enabling dairy-protein bar distribution previously limited to ambient-stable formats.
- SFDA Labeling Clarity:Standardized nutrition declarations are reducing consumer information asymmetry, accelerating trial conversion among health-conscious households previously skeptical of ingredient opacity.
Market Restraints
- Specialty Nut Import Dependence:Almonds, pistachios, and premium dried fruits enter through Jeddah Islamic Port, exposing margin structures to Red Sea shipping volatility and currency fluctuation against the dollar.
- Halal Certification Complexity:SASO cross-contamination protocols require dedicated production lines for gelatin-containing formulations, constraining contract manufacturing flexibility and elevating capital requirements for multi-format producers.
- Sugar-Tax Uncertainty:Pending Ministry of Finance discussions on sweetened-product taxation are freezing long-term portfolio planning, with reformulation investments delayed pending policy clarity.
Strategic Opportunities
- Eastern Province Underpenetration:Dammam and Khobar exhibit modern retail density below Riyadh levels, with expatriate professional populations showing comparable fitness engagement but reduced local brand awareness.
- Subscription Channel Development:Direct-to-consumer replenishment models bypass traditional distributor markups while capturing consumption data for personalized flavor and nutrition customization.
- Plant Protein Convergence:Pea and fava protein isolates combined with date-based binders satisfy vegan and allergen-free positioning simultaneously, opening positioning white space beyond whey-dominant portfolios.
Industry Challenges
- Cold-Chain Talent Scarcity:Refrigerated distribution network expansion requires qualified technicians for temperature-controlled logistics, with technical training programs lagging sector growth rates.
- Reformulation Timeline Compression:SFDA health-claim substantiation demands clinical validation or systematic literature reviews, extending new product development cycles by 8-14 months versus legacy protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Snack Bar Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Protein Bars, Nut Bars, Fruit Bars Ingredient: Organic, Non-GMO, Gluten-Free, Vegan Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Stores Target Consumer: Fitness Enthusiasts, Busy Professionals, Parents, Students |
| Companies Covered | Mondelez International, Inc, Simply Good Foods Co, PepsiCo Inc, Clif Bar & Company, Premier Nutrition Corporation, Kellanova, Nestle S.A., Almarai, General Mills, Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Snack Bar Market Evolving Landscape
Clean-label binding systems and precision fermentation are restructuring ingredient sourcing, while digital retail infrastructure enables direct consumer relationships that bypass traditional wholesale hierarchies.
Hydrocolloid alternatives derived from date syrup and acacia gum are displacing maltitol and corn syrup solids in premium formulations. Jeddah-based manufacturers are adopting these binders at accelerating rates to satisfy front-of-pack "no added sugar" positioning. The displacement is compressing traditional sweetener supplier margins while elevating local agricultural ingredient premiums.
SFDA's evolving front-of-pack labeling proposals are forcing portfolio rationalization across both domestic and imported brands. Manufacturers are preemptively reducing sugar content to avoid warning-label classification, with protein bar segments reformulating faster than granola formats. The regulatory pressure is most acute among children's positioning products, where parental purchase sensitivity to visual warnings exceeds price elasticity.
Busy professionals in Riyadh's financial district are consolidating replenishment decisions into subscription platforms that automate delivery cadence. Traditional supermarket impulse purchasing is losing share to curated box services that pre-select assortments based on stated dietary preferences. This behavioral shift concentrates customer acquisition investment into digital channels while reducing slotting fee dependence.
Saudi Arabia Snack Bar Market Segmentation
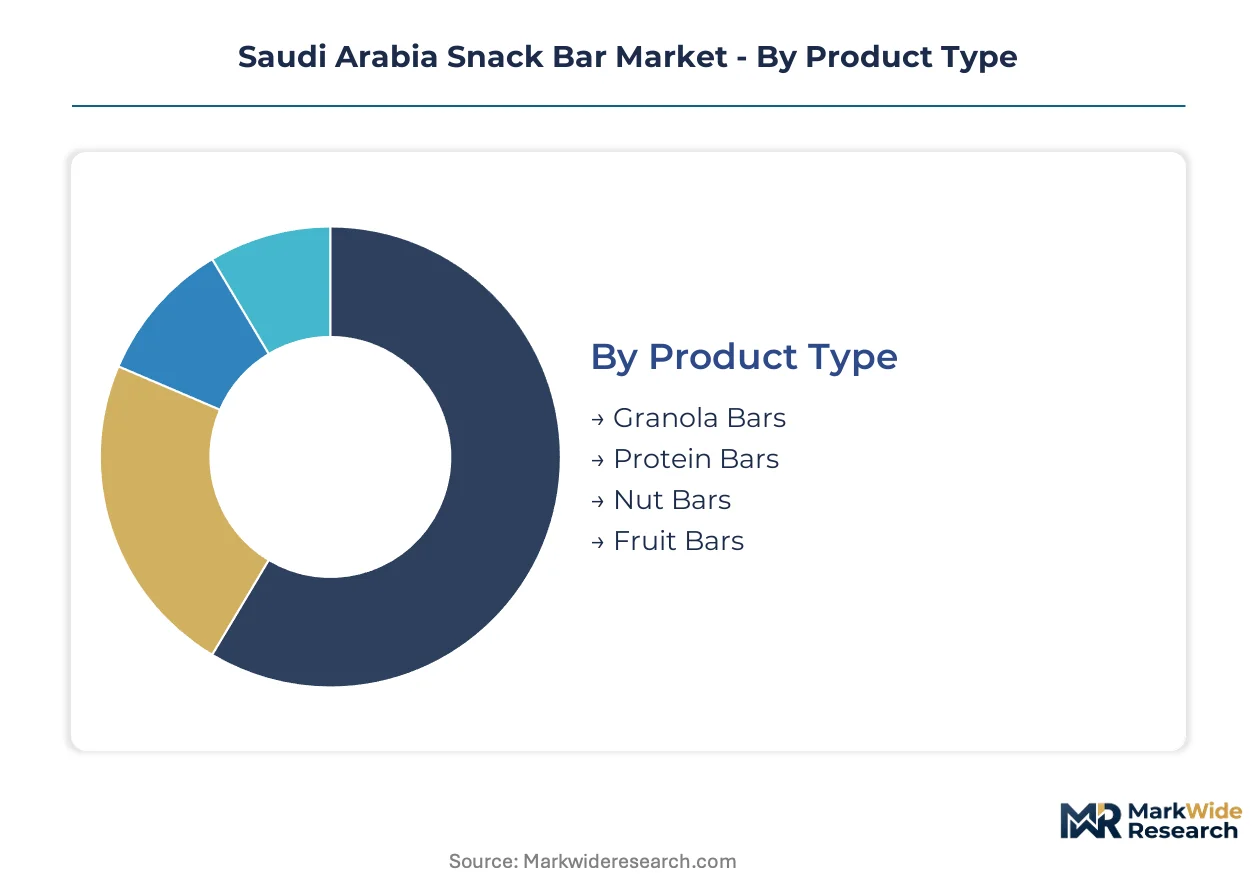
Segmentation in Saudi Arabia's snack bar market exposes divergent compliance burdens and channel economics. SFDA labeling mandates hit protein-forward formats harder than traditional cereal bars, while halal certification complexity varies sharply by ingredient sourcing.
Product Type:
Regulatory differentiation separates ambient-stable formats from refrigerated protein bars under SFDA storage-condition declarations and SASO cold-chain standards.
- Granola Bars:Oat and cereal-based formulations bound by honey or syrup achieve ambient stability with moisture content below 15 percent. Riyadh hypermarkets dedicate prime shelf space to these familiar formats, though parental purchase decisions are shifting toward lower-sugar alternatives under front-of-pack labeling pressure.
- Protein Bars:Whey or plant-isolate fortification delivers 15-25 grams protein per 60-gram serving, requiring precise moisture management and texture stabilization. Jeddah's fitness-district retail clusters show concentrated demand among gym members seeking post-workout macronutrient delivery without meal preparation.
- Nut Bars:Almond and pistachio-dominant compositions face import-dependency exposure through Red Sea shipping corridors.
- Fruit Bars:Date-based binders leverage local agricultural supply chains for halal-compliant sweetness without refined sugar.
Granola bars handle the majority of throughput; protein bars are climbing the fastest on share.
Ingredient:
Cost tier stratification places organic and non-GMO claims at premium price points while gluten-free and vegan positioning capture mid-market expansion.
- Organic:Certified ingredient sourcing through SFDA-accredited bodies commands 25-40 percent price premiums over conventional equivalents. Riyadh's high-income districts show sustained willingness-to-pay among households linking organic claims to child nutrition quality.
- Gluten-Free:Oat and alternative grain formulations eliminate wheat, barley, and rye proteins to serve celiac and sensitivity-diagnosed consumers. Dammam's expatriate professional population—heavier in South Asian and European nationals—drives disproportionate demand versus native Saudi prevalence rates.
- Non-GMO:Identity-preserved supply chains for corn and soy derivatives add traceability costs without allergen-related purchase triggers.
- Vegan:Plant-protein isolates and date syrups replace dairy and honey for ethically motivated and lactose-intolerant segments simultaneously.
Gluten-free claims anchor the volume base; vegan positioning shows steepest expansion trajectory.
Distribution Channel:
Application-based channel selection separates impulse replenishment from planned procurement, with digital infrastructure enabling subscription-based customer capture.
- Supermarkets:Hypermarket chains including Carrefour and Lulu dominate mass-market penetration with dedicated functional snacking aisles. Riyadh and Jeddah retail parks concentrate foot traffic for family-stock-up occasions where multi-pack formats outperform single-serve.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enable subscription automation and flavor customization. Busy professionals in Riyadh's financial district increasingly consolidate replenishment decisions into curated box services that bypass traditional distributor markups.
- Convenience Stores:Petrol-station and urban-corner formats capture immediate-consumption occasions with limited SKU depth.
- Health Stores:Pharmacy and dedicated nutrition retail channels command premium positioning through pharmacist endorsement and clinical adjacency.
Supermarkets move the bulk of units; online retail is gaining share fastest.
Target Consumer:
Customer-type concentration in urban corridors creates addressable density for fitness-focused and time-constrained segments alike.
- Fitness Enthusiasts:Gym members and amateur athletes prioritize protein density and macronutrient transparency in post-workout consumption. Jeddah's coastal fitness culture—swimming, running, cross-training—generates year-round demand versus seasonal patterns in interior regions.
- Busy Professionals:Corporate employees in Riyadh's King Abdullah Financial District substitute snack bars for skipped meals during extended workdays. Subscription platform adoption concentrates heavily in this segment due to income elasticity and time-scarcity tradeoffs.
- Parents:School-lunch and child-snack decisions prioritize clean-label claims and portion control.
- Students:University populations in Riyadh, Jeddah, and Dammam show price sensitivity but high trial willingness for novel flavors.
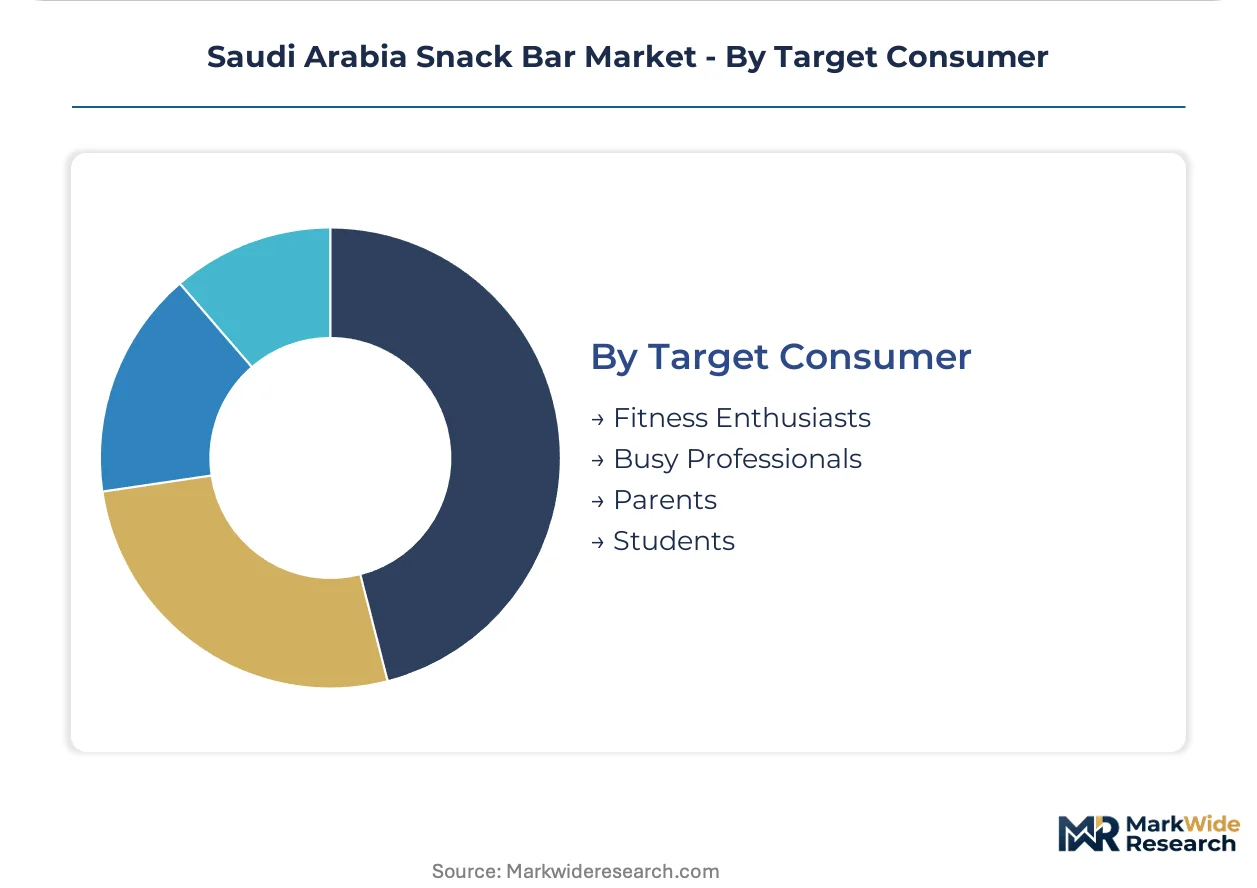
Fitness enthusiasts drive premium tier volume; busy professionals are expanding most quickly on segment share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Saudi Arabia's snack bar demand map. Riyadh and Jeddah consumers absorb premium protein-bar pricing with minimal elasticity, while Eastern Province buyers gravitate toward value-tier granola formats. Interior regions exhibit intermediate responsiveness where halal certification and local ingredient sourcing command modest premiums.
Riyadh
Fitness culture and corporate employment density concentrate protein-bar demand in Riyadh's King Abdullah Financial District. SFDA nutrition labeling mandates shape retail assortment decisions across hypermarket chains. The capital's retail parks host dedicated functional snacking aisles where refrigerated sections enable dairy-protein bar distribution previously limited to ambient formats.
Jeddah
Coastal fitness engagement—swimming, running, cross-training—generates year-round consumption unlike seasonal interior patterns. Halal certification protocols administered by SASO and religious oversight bodies govern gelatin sourcing and cross-contamination prevention. Jeddah Islamic Port serves as the primary entry point for specialty nut imports, exposing local manufacturers to Red Sea shipping volatility.
Eastern Province
Expatriate professional populations in Dammam and Khobar show comparable fitness engagement to Riyadh but reduced awareness of domestic and imported premium brands. Modern retail density lags the capital, constraining refrigerated distribution network reach. Local distributors are expanding ambient-stable protein bar SKUs to bridge this infrastructure gap.
Western Region
Makkah and Madinah pilgrimage traffic creates episodic demand spikes for portable, halal-certified nutrition products. Seasonal consumption patterns differ structurally from urban professional routines. Local manufacturers prioritize ambient-stable, date-based formulations that satisfy religious traveler requirements without cold-chain dependency.
NEOM Northwest
Giga-project construction and planned resident population growth are incubating demand for subscription-based replenishment models among incoming professional cohorts. Regulatory frameworks remain under development as the zone establishes distinct standards from national SFDA protocols. Early retail infrastructure investments emphasize digital-first distribution over traditional hypermarket expansion.
Saudi Arabia Snack Bar Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Saudi Arabia's snack bar value chain. Multinational food conglomerates leverage global procurement networks and formulation R&D, while domestic dairy giants exploit backward integration into protein ingredients and captive cold-chain assets. The competitive structure bifurcates between scale-driven ambient-bar specialists and refrigerated-format premium players. Dominant competitive moves include portfolio diversification into plant-protein alternatives and geographic expansion through modern retail shelf-space capture.
Within the multinational tier, Mondelez International, Inc and Nestle S.A. occupy positions anchored by global brand equity and cross-category distribution leverage. Almarai represents the integrated domestic archetype, with its dairy-protein ingredient base and Kingdom-wide refrigerated logistics network. These three entities exemplify the strategic divergence between import-dependent formulation expertise and captive supply-chain control.
| Leading Market Players |
|---|
| Mondelez International, Inc |
| Simply Good Foods Co |
| PepsiCo Inc |
| Clif Bar & Company |
| Premier Nutrition Corporation |
| Kellanova |
| Nestle S.A. |
| Almarai |
| General Mills, Inc |
| Others |
Value Network & Pricing Analysis
Date syrup and acacia gum displacement of maltitol and corn syrup solids is simultaneously relocating binder sourcing toward Jeddah-based agricultural processors and compressing traditional sweetener supplier margins. This substitution dynamic elevates local ingredient premiums while reducing import-dependency exposure for halal-compliant formulations.
Pricing Analysis
Subscription-based replenishment revenue drives lifetime customer value as busy professionals automate delivery cadence. Three-tier pricing structure across premium, standard, and economy levels separates protein-fortified formats from granola bars and private-label alternatives. Cost compression in the premium tier is intensifying because refrigerated distribution network expansion requires qualified technician investment. Parents purchasing children's positioning products show highest price sensitivity to visual front-of-pack warnings, while fitness enthusiasts in Riyadh and Jeddah absorb premium protein-bar pricing with minimal elasticity.
Supply Chain Analysis
The United States and Turkey anchor specialty nut and dried-fruit supply for Saudi manufacturers, with almonds and pistachios entering through Jeddah Islamic Port. Date syrup and local acacia gum feed from domestic agricultural networks, reducing Red Sea shipping exposure. Single-source vulnerability concentrates in whey protein isolate imports for dairy-based formulations. Distribution runs through hypermarket chains and direct-to-consumer platforms, with refrigerated sections enabling protein bar formats previously limited to ambient stability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription platform economics are restructuring customer acquisition investment away from slotting fees and toward digital-first distribution infrastructure. Interoperability between curated box services and fitness app ecosystems creates data-rich replenishment loops.
For Market Incumbents: Consolidate backward integration into dairy-based protein ingredients to defend against plant-protein substitution threats. Expand refrigerated distribution assets across the Kingdom's Eastern Province to preempt infrastructure gaps. Prioritize SFDA health-claim substantiation investment to compress new product development cycles.
For New Entrants and Emerging Players: Lead with plant-protein convergence positioning using pea and fava isolates combined with date-based binders to capture vegan and allergen-free white space. Target Dammam and Khobar's underpenetrated expatriate professional populations with comparable fitness engagement but reduced brand awareness. Deploy direct-to-consumer replenishment models to bypass traditional distributor markups.
For Investors and Strategic Acquirers: The market sits at a platform-expansion phase that favors cold-chain infrastructure specialists and digital-native subscription platforms. Long-term viability hinges on captive supply-chain control and regulatory compliance capabilities. Acquisition target archetypes include Jeddah-based manufacturers with halal-certified production lines and refrigerated logistics networks. Watch for sugar-tax policy clarity as the inflection signal for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Protein Ingredients | Almarai's dairy-protein captive supply reduces import dependency and margin volatility. |
| Direct-to-Consumer Platform Launch | Subscription automation captures Riyadh financial district professionals seeking curated replenishment. |
| Refrigerated Distribution Expansion | Cold-chain network buildout enables dairy-protein bar formats beyond ambient-stable portfolios. |
| Halal Certification Investment | SASO-compliant production lines filter market access and constrain contract manufacturing flexibility. |
| Plant-Protein Portfolio Diversification | Pea and fava isolates with date binders satisfy vegan positioning without whey dependency. |
Research Methodology
Cross-validation between primary interviews with category buyers at Carrefour and Lulu, supply planners at domestic manufacturers, and regulatory affairs leads navigating SFDA mandates anchors the qualitative findings. Secondary validation draws from SASO certification databases, SFDA nutrition labeling directives, customs import records through Jeddah Islamic Port, and Nielsen retail audit data. Bottom-up channel volume estimates and top-down macroeconomic consumption patterns complete the triangulation.
Sensitivity analysis across protein content tiers, distribution channel economics, and regional adoption patterns structures the analytical framework over the projection horizon. Segmentation dimensions include product type, ingredient claim positioning, distribution channel, and target consumer archetype. CAGRs derive from modeled volume trajectories adjusted for regulatory compliance timelines and cold-chain infrastructure buildout rates. Sugar-tax policy scenarios and front-of-pack labeling implementation pace serve as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside maintained SFDA regulatory stability and halal certification protocol continuity would require recalibration. Forecasts reflect assumptions around modern retail penetration rates and fitness culture expansion trajectories. Recalibration cycles align with material shifts in SFDA labeling mandates and Ministry of Finance taxation discussions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Pretzels (Savory Snacks) Market
Snacks
North America Potato Chips Market
Snacks
Global Fruit Snacks Market
Snacks
Kale Chips Market
Snacks
China Snack Bar Market
Snacks
Healthy Fruit and Vegetable Chips Market
Snacks
Snack Pellets Market
Snacks
On-The-Go Healthy Snacks Market
Snacks
Potato Chips Market
Snacks
Nutritional Bar Market
Snacks
RTE Popcorn Market
Snacks
Sweet Potato Fries Market
Snacks
Europe Popcorn Market
Snacks
Low Fat Sweet Snacks Market
Snacks
Forti Flakes Market
Snacks
Savoury Biscuits Market