
 Beverage Multipacks Market | 2026-2036
Beverage Multipacks Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Multipacks Market Outlook
Modular pack sizing is shifting how households and foodservice buyers select beverage formats, moving away from single-serve toward configurable bundles. Ardagh Metal Packaging leverages its aluminum can capacity to anchor supply for multi-can configurations across European retail. Amcor plc sustains flexible film innovation for multi-pouch packs in the Asia-Pacific region. Crown Holdings Inc. dominates steel beverage can multipacks through manufacturing scale in North America.
Beverage multipacks denote aggregated retail units containing two or more individual beverage containers joined by shrink film, paperboard carriers, or plastic rings, typically specified by pack counts ranging from four to twenty-four units and designed for transport efficiency and shelf-ready merchandising. Soft drinks and bottled water represent the highest-volume product categories, with multi-can packs and multi-bottle packs capturing the dominant share of packaging configurations. Wholesale clubs and supermarkets command the largest distribution channel positions, while premium and mid-range price tiers concentrate margin pools as brands differentiate through sustainable packaging claims.
The EPA regulates recycled content thresholds for beverage packaging materials in the United States, while the EU Green Deal and REACH framework impose extended producer responsibility and material restriction requirements across Europe. FDA food-contact material standards govern multipack secondary packaging for beverages distributed in the United States. Stakeholders must monitor evolving state-level bottle bill expansions and EU packaging waste directive implementations to anticipate compliance-driven format changes.
Market Dynamics
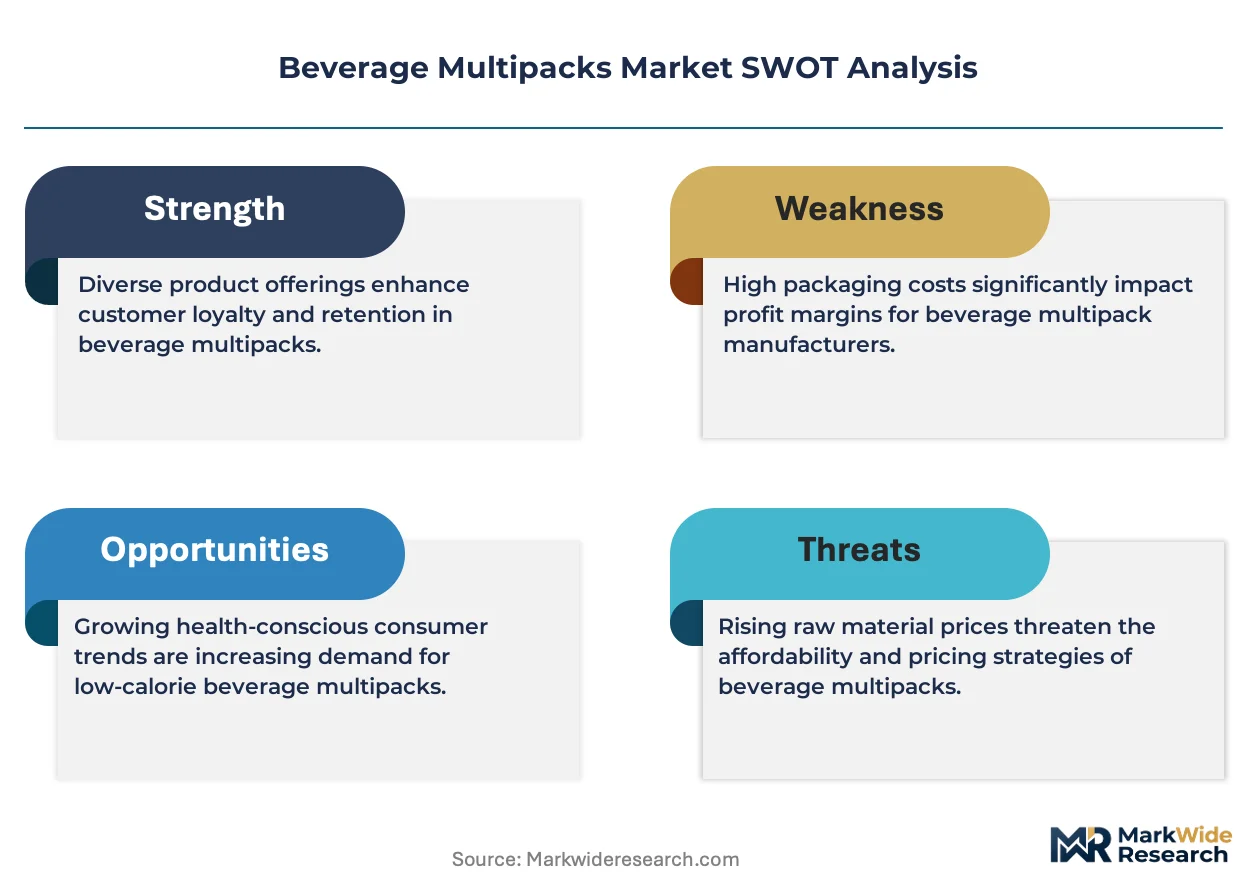
Shrink film substitution by fiber-based carriers is compressing secondary packaging costs while EU F-Gas Regulation accelerates material transition timelines across European retail networks.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility requirements are forcing beverage brands to redesign multipack formats around recyclable substrates, opening procurement slots for fiber-based carriers.
- Wholesale club format expansion:Costco and Sam's Club are expanding shelf allocation for 12-24 count beverage configurations as household stockpiling behavior persists post-pandemic.
- Aluminum can capacity concentration:Domestic smelter investments in the United States and Germany are stabilizing can sheet supply for multi-can multipack production.
Market Restraints
- Resin price volatility:Polypropylene and PET feedstock costs fluctuate with crude oil indices, compressing margins for shrink-wrapped multipack producers.
- Secondary packaging labor intensity:Automated multipack assembly lines require skilled technicians that concentrate in Germany and the United States, limiting expansion in emerging manufacturing zones.
- Paperboard moisture sensitivity:Fiber-based carriers degrade in humid climates, restricting their deployment in Southeast Asian and Gulf retail environments.
Strategic Opportunities
- India organized retail penetration:Reliance Fresh and D-Mart are expanding beverage multipack SKUs as urban household sizes shrink and refrigerator ownership rises.
- Deposit-return scheme alignment:Germany's DRS infrastructure creates pull-through for easy-separate multipack designs that simplify consumer sorting.
- Smart packaging integration:QR-coded multipack carriers are converging with loyalty program backends, enabling direct-to-consumer data capture for beverage brands.
Industry Challenges
- Retrofitting legacy filling lines:Converting single-serve bottling equipment to handle bundled formats requires capital outlays that mid-tier beverage co-packers struggle to finance.
- Food-contact certification timelines:FDA approval for novel adhesive formulations in carrier applications stretches 18-24 months, delaying format launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Multipacks Market |
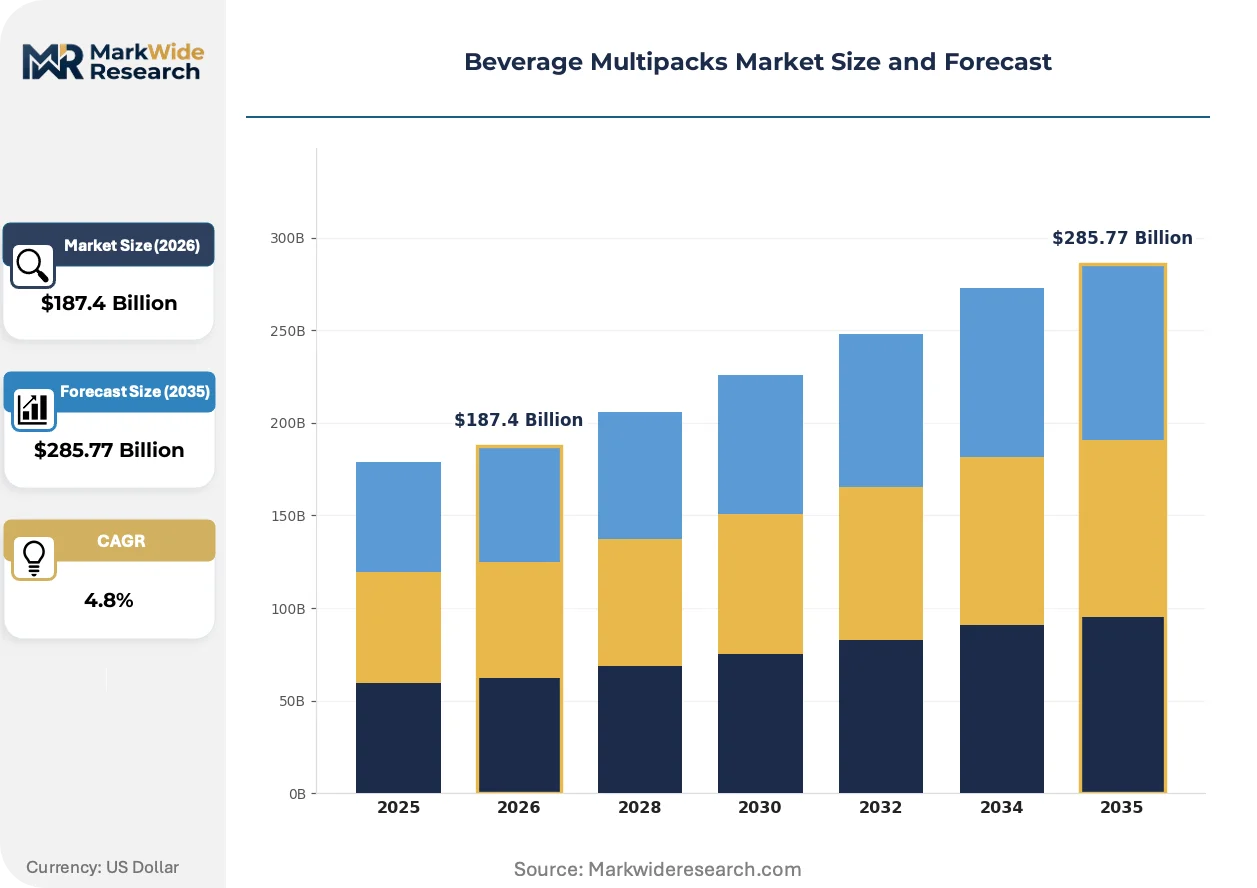
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Drinks, Juices, Energy Drinks, Bottled Water Packaging Type: Multi-Can Packs, Multi-Bottle Packs, Tetra Packs, Multi-Pouch Packs Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Wholesale Clubs Price Tier: Premium, Mid-Range, Value, Economy |
| Companies Covered | Ardagh Metal Packaging, Mondi Group, Amcor plc, Smurfit Kappa Group plc, DS Smith plc, Ball Corporation, Berry Global Inc., WestRock Company, Crown Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Multipacks Market Strategic Shifts
Active material science development is collapsing the performance gap between plastic and fiber-based multipack substrates, while regulatory pressure compresses transition timelines.
Water-based barrier coatings for paperboard carriers are converging with high-speed packaging line requirements, enabling fiber formats to match polyethylene moisture protection at line speeds above 600 units per minute. German retail chains are piloting these carriers for 4-pack and 6-pack beverage configurations. The technology is converging with automated case-packing systems, eliminating the throughput penalty that previously blocked paperboard adoption.
REACH substance restriction amendments are phasing out certain phthalate plasticizers in shrink film formulations, forcing European multipack producers to validate alternative flexibilizers. The industrial consequence is a 12-18 month reformulation cycle for film suppliers serving EU beverage accounts. Soft drink multipacks face the tightest compliance windows, with reformulated films requiring requalification on existing bundling equipment.
Direct-to-fridge purchasing patterns are reshaping household beverage procurement, with urban consumers in China and the United States favoring 8-12 count configurations that fit residential refrigeration constraints. E-commerce beverage subscription services are displacing traditional supermarket stock-up trips for these formats. This shift concentrates demand in warehouse club and online grocery channels, compressing convenience store multipack velocity in tier-one Chinese cities.
Beverage Multipacks Market Segmentation
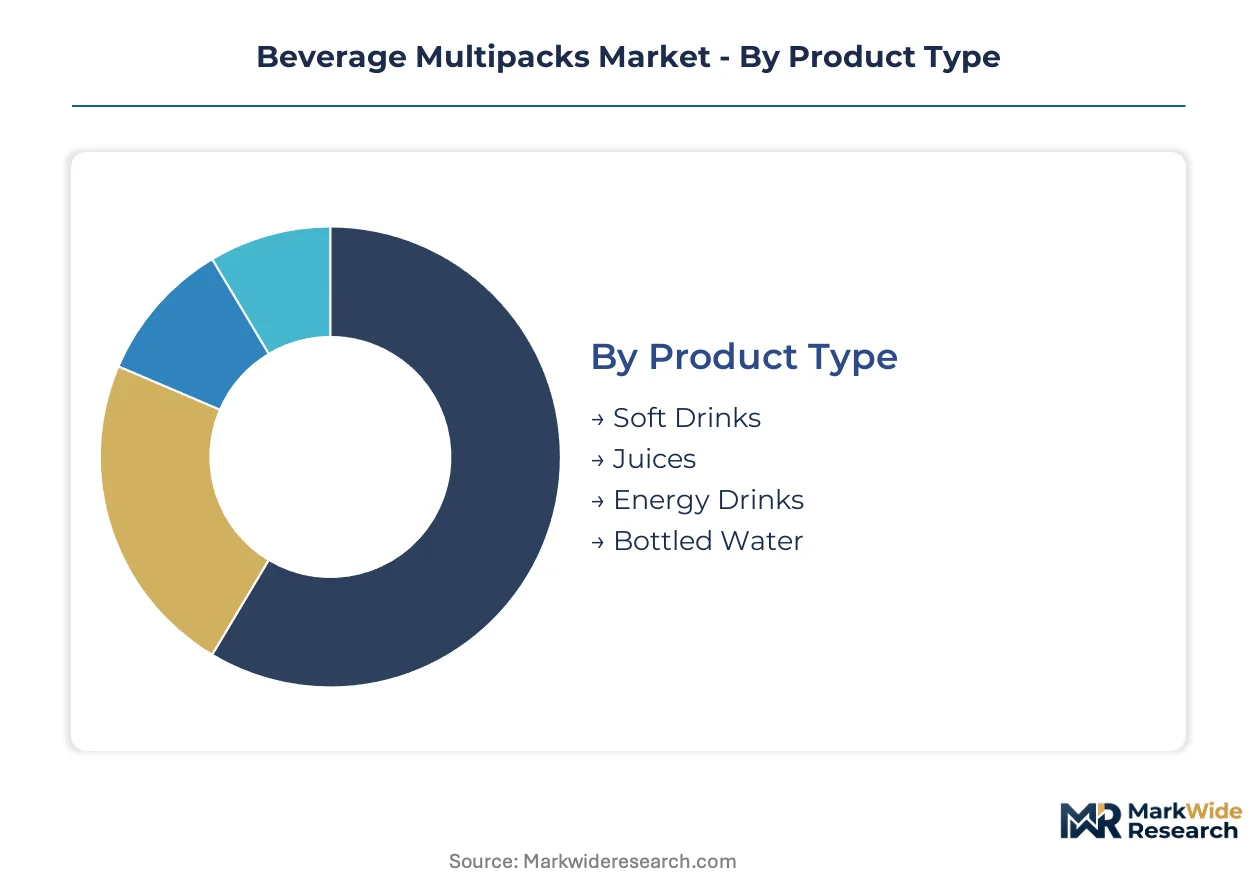
Segmentation in beverage multipacks determines capital allocation across filling line configurations, carrier material procurement, and retail channel partnerships. Distinct packaging formats and distribution pathways require specialized equipment investments that lock producers into specific operational footprints.
Product Type:
Capital intensity varies sharply across liquid categories, with carbonated soft drinks demanding pressurized filling infrastructure that multiplies upfront equipment costs relative to still beverages.
- Soft Drinks:Carbonated formulations require pressurized filling lines and CO2 injection systems that dominate capital expenditure budgets for multipack producers. Demand concentrates in Germany and the United States where retail buyers prioritize 12-can and 24-can configurations for household stockpiling; EU F-Gas Regulation is accelerating carrier material transitions for these high-volume SKUs.
- Bottled Water:Still water filling operates at lower pressure differentials, reducing line complexity and enabling faster format changeovers between pack counts. Growth clusters in China where urban refrigerator ownership is reshaping procurement toward 8-12 count configurations that fit residential cooling units; e-commerce subscription services are displacing traditional supermarket trips in tier-one cities.
- Juices:Aseptic filling requirements and refrigerated supply chains elevate capital thresholds for multi-bottle juice packs.
- Energy Drinks:Smaller pack counts and premium positioning command specialized marketing investments rather than filling line scale.
Soft drinks absorb the bulk of installed capacity; bottled water is expanding most quickly.
Packaging Type:
Material selection determines automation compatibility and regulatory compliance exposure across regional markets.
- Multi-Can Packs:Aluminum can aggregation through shrink film or paperboard carriers leverages existing beverage can capacity concentrated in the United States and Germany. German retail chains are piloting fiber-based carriers for 4-pack and 6-pack configurations as REACH substance restrictions phase out legacy plasticizers; water-based barrier coatings now match polyethylene moisture protection at line speeds above 600 units per minute.
- Multi-Bottle Packs:PET bottle multipacks require neck-ring carrier systems or shrink bundling that accommodates variable bottle geometries and label surfaces. Deployment concentrates in humid climates across Southeast Asia and the Gulf where paperboard moisture sensitivity restricts fiber carrier adoption; producers rely on reformulated shrink films pending flexibilizer requalification.
- Tetra Packs:Aseptic carton multipacks serve ambient juice and dairy-adjacent beverages with distinct shelf-stable logistics.
- Multi-Pouch Packs:Flexible film innovation in the Asia-Pacific region supports lightweight beverage pouches for single-serve aggregation.
Multi-can configurations command the deepest capital base; multi-pouch formats are climbing the fastest in emerging manufacturing zones.
Distribution Channel:
Channel mix dictates pack count standardization and palletization requirements that ripple backward through supply chain design.
- Wholesale Clubs:Costco and Sam's Club specifications for 12-24 count configurations drive filling line investments toward high-volume bundling equipment. Post-pandemic household stockpiling behavior persists in the United States, concentrating procurement in warehouse club channels that compress convenience store velocity.
- Supermarkets:Traditional grocery requires shelf-ready merchandising with variable pack counts that complicate automated case-packing system design.
- Convenience Stores:Smaller format retail in tier-one Chinese cities is losing multipack share to direct-to-fridge e-commerce subscriptions.
- Online Retailers:E-commerce beverage distribution demands damage-resistant secondary packaging for last-mile logistics.
Wholesale clubs anchor volume throughput; online retailers are gaining share fastest in urban China and the United States.
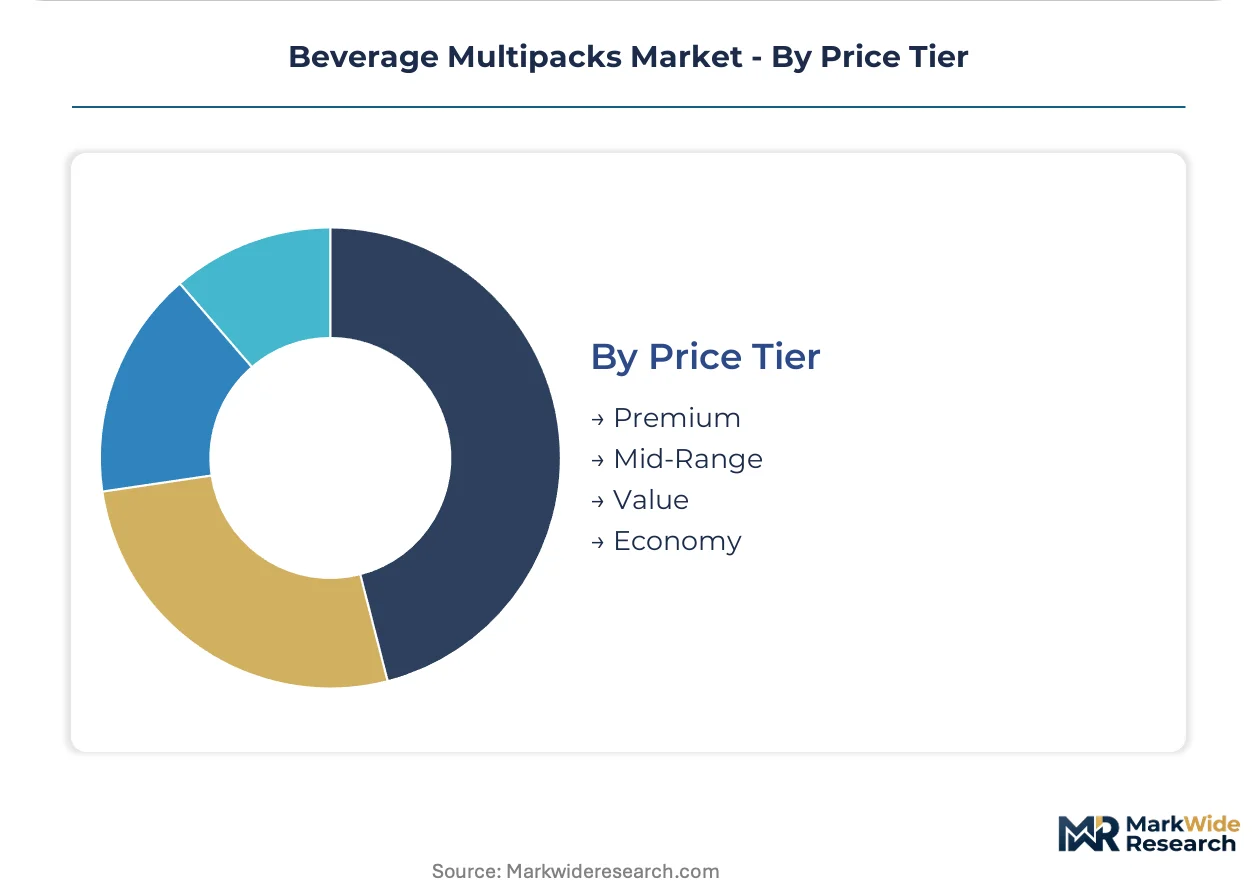
Price Tier:
Pricing stratification separates premium sustainable packaging claims from economy formats where material cost minimization dominates procurement decisions.
- Premium:Fiber-based carrier adoption and QR-coded smart packaging integration command price premiums justified by EU Green Deal compliance and loyalty program data capture. German deposit-return scheme alignment creates pull-through for easy-separate multipack designs that simplify consumer sorting.
- Mid-Range:Standard shrink film configurations balance material cost with line speed efficiency across mainstream soft drink and water multipacks.
- Value:Price-sensitive segments prioritize resin cost minimization over carrier innovation.
- Economy:Lowest-tier pricing accepts higher labor intensity in secondary packaging assembly where automated line technicians concentrate in Germany and the United States.
Mid-range tiers absorb the bulk of production volume; premium positioning is expanding most quickly on regulatory compliance tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and the United States while consumption gravitates toward urban centers in China and India. This geographic split creates logistics-intensive supply chains where aluminum can sheet moves across oceans to reach Asian filling lines. Regulatory divergence between EU packaging mandates and US recycling standards further complicates cross-border format standardization.
United States
Warehouse club expansion at Costco and Sam's Club drives procurement of 12-24 count configurations for household stockpiling behavior. EPA recycled content thresholds shape secondary packaging material selection for beverage brands. Manufacturing scale concentrates in Midwestern states where Crown Holdings Inc. anchors steel beverage can multipack production.
Germany
Deposit-return scheme infrastructure creates pull-through for easy-separate multipack designs that simplify consumer sorting behavior. EU F-Gas Regulation and REACH substance restrictions accelerate carrier material transitions away from legacy plasticizers. Ardagh Metal Packaging leverages aluminum can capacity to supply multi-can configurations across European retail networks.
China
Urban refrigerator ownership reshapes procurement toward 8-12 count configurations fitting residential cooling constraints. E-commerce beverage subscription services displace traditional supermarket stock-up trips in tier-one cities. Yangtze River Delta manufacturing clusters pilot water-based barrier coatings for fiber-based carriers at line speeds above 600 units per minute.
India
Organized retail penetration at Reliance Fresh and D-Mart expands beverage multipack SKUs as urban household sizes shrink. FSSAI food-contact standards govern secondary packaging materials for beverages distributed nationally. Maharashtra and Karnataka industrial corridors attract filling line investments targeting mid-range price tier configurations.
Beverage Multipacks Market Competitive Environment
The competitive structure tilts toward integrated packaging converters with captive aluminum and paperboard supply chains. Tiered specialization separates metal can specialists from fiber-based carrier innovators, with mid-cap regional players occupying price-sensitive segments. Strategic moves concentrate on capacity expansion in Germany and the United States alongside portfolio diversification into recyclable substrate formats.
Within the integrated metal packaging tier, Ardagh Metal Packaging and Ball Corporation represent archetypal positions anchored by aluminum can capacity concentration. Crown Holdings Inc. occupies a parallel position in steel beverage can multipacks through North American manufacturing scale. Among fiber-based specialists, Mondi Group and Smurfit Kappa Group plc exemplify European paperboard carrier innovation aligned with EU Green Deal compliance trajectories.
| Leading Market Players |
|---|
| Ardagh Metal Packaging |
| Mondi Group |
| Amcor plc |
| Smurfit Kappa Group plc |
| DS Smith plc |
| Ball Corporation |
| Berry Global Inc. |
| WestRock Company |
| Crown Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
Warehouse club procurement concentration at Costco and Sam's Club anchors contract-based long-term offtake agreements that compress spot-market pricing volatility for 12-24 count configurations. This buyer archetype leverage forces mid-tier co-packers into economy-tier margin pools where resin cost minimization dominates procurement decisions.
Pricing Analysis
Margin tightening in mid-range tiers reflects polypropylene and PET feedstock volatility tethered to crude oil indices. Three-tier pricing structure across premium, standard, and economy levels separates fiber-based carrier innovators from shrink film standard configurations and resin-dependent value formats. Price differentiation hinges on EU Green Deal compliance certification and volume scale commitments to wholesale club buyers. Economy segments exhibit highest price sensitivity as automated line technician scarcity in Germany and the United States elevates labor intensity costs.
Supply Chain Analysis
Direct-to-retail channels handle high-velocity warehouse club demand while specialized distributors serve supermarket and convenience store networks. Supply concentrates in Germany, the United States, and China where aluminum smelter investments and paperboard mill capacity anchor production. Raw material dependencies draw from aluminum can sheet, polypropylene resin, and kraft linerboard feedstocks. Single-source vulnerability in Southeast Asian shrink film supply chains amplifies risk as REACH substance restrictions force 12-18 month reformulation cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum can capacity scarcity in Asia-Pacific markets props pricing power for integrated converters with captive sheet supply. This supply-constrained structure rewards early positioning in fiber-based carrier transitions.
For Market Incumbents: Lock in backward integration into water-based barrier coating technologies before German retail chains scale pilot programs to network-wide deployment. Secure aluminum can sheet offtake agreements with Yangtze River Delta smelters to preempt Asian competitor expansion. Channel control through exclusive wholesale club partnerships represents the critical defensive lever against mid-tier co-packer consolidation. For New Entrants and Emerging Players: Enter via India's organized retail penetration at Reliance Fresh and D-Mart where urban household shrinkage and refrigerator ownership growth outpace incumbent filling line investments. Target mid-range price tier configurations in Maharashtra and Karnataka industrial corridors where FSSAI compliance creates barrier advantages over unorganized competitors. Direct-to-fridge e-commerce subscription models offer the most penetrable go-to-market angle in tier-one Chinese cities. For Investors and Strategic Acquirers: The window for entry favors integrated packaging converters with captive aluminum supply and fiber-based carrier R&D pipelines. Long-term viability rests on EU Green Deal compliance trajectory alignment and deposit-return scheme infrastructure capture. Watch for FDA food-contact certification timeline compression as the inflection signal indicating novel adhesive formulation readiness for market deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier Material Transition | Fiber-based formats aligned with EU F-Gas Regulation open procurement slots at German retail chains. |
| Aluminum Capacity Expansion | Domestic smelter investments in the United States stabilize can sheet supply for multi-can production. |
| Smart Packaging Integration | QR-coded carriers enable direct-to-consumer data capture converging with loyalty program backends. |
| Deposit-Return Alignment | Easy-separate multipack designs simplify consumer sorting behavior in Germany's DRS infrastructure. |
| Water-Based Barrier Development | Coating innovations match polyethylene moisture protection at line speeds above 600 units per minute. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with filling line engineers, retail category buyers, carrier material procurement managers, and beverage brand sustainability directors. EPA recycled content thresholds, EU REACH substance restrictions, and FSSAI food-contact standards provided regulatory boundary conditions. Bottom-up capacity assessments triangulated against top-down consumption estimates across wholesale club, supermarket, and e-commerce channels.
Granularity-level modeling deployed pack count configurations, carrier material types, and price tier positioning as core segmentation dimensions. CAGRs derived from production capacity expansion timelines and retail shelf allocation shifts across the analysis window. Aluminum can sheet supply curves, resin price indices, and deposit-return scheme adoption rates served as industry-specific forecast inputs.
Revisions become necessary when REACH substance restriction amendments accelerate beyond current 12-18 month reformulation cycles or when FDA adhesive certification timelines compress unexpectedly. Forecasts reflect assumptions regarding wholesale club format persistence and urban refrigerator ownership trajectories in China and India. Periodic stress-testing of base assumptions against EU packaging waste directive implementation schedules is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Packaged Cactus Water Market
Beverages
NFC JUICE Market
Beverages
Carbonated Beverages Market
Beverages
Sports and Energy Drinks Market
Beverages
Global Bottled Water Market
Beverages
United States Smoothie Market
Beverages
India Soy Beverages Market
Beverages
Fiber Fortified Beverages Market
Beverages
Asia-Pacific Energy Drink Market
Beverages
Hot Beverages Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Indonesia Bottled Water Market
Beverages
Caffeine Mint Market
Beverages
Detox Drinks Market
Beverages
Beverage Cooler Market
Beverages
North America Cold Pressed Juices Market