
 Digestion Aids Market | 2026-2036
Digestion Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Digestion Aids Market Analysis
Young adult sports nutrition buyers is collapsing as a share of total volume while senior wellness programs and clinical dietetics channels expand. Nestlé anchors its position through captive dairy fermentation infrastructure that secures probiotic strain supply. Abbott Laboratories differentiates via hospital discharge protocols that embed digestive enzymes into post-surgical recovery bundles. Yakult Honsha dominates single-serve fermented distribution through cold-chain vending networks across East Asian urban corridors.
Digestion aids comprise formulated ingestible products containing live microbial cultures, non-digestible oligosaccharides, hydrolytic enzymes, or soluble fiber matrices designed to accelerate nutrient breakdown, modulate intestinal flora composition, or enhance colonic transit efficiency. Probiotics lead value generation due to refrigerated shelf-life requirements that create margin-protective barriers against commodity entrants, while digestive enzymes represent the fastest-growing category as clinicians prescribe pancreatic and fungal-origin blends for post-antibiotic dysbiosis. Gummies capture outsized share among children's end users where palatability drives compliance, though tablet formulations retain professional channel preference for dose standardization.
The US FDA and EFSA jointly shape market access through divergent live culture count verification standards that force dual-label compliance for multinational suppliers. China's NMPA and SAMR enforce GB standards for genetically modified enzyme substrates that restrict import eligibility for certain fungal fermentation derivatives. India's FSSAI and CDSCO maintain overlapping jurisdiction that creates notification complexity for synbiotic products claiming dual structure-function and therapeutic positioning. Stakeholders must monitor regulatory harmonization negotiations between Codex Alimentarius and national agencies to anticipate whether unified microbial identity criteria will consolidate testing costs or fragment compliance architectures.
Market Dynamics
The digestion aids market restructures around microbiome personalization, where at-home gut sequencing kits enable consumers to match specific probiotic strains to their intestinal flora profiles, compressing brand loyalty and elevating formulation precision as the primary purchase driver.
Growth Catalysts
- Post-antibiotic dysbiosis protocols:Clinicians in Germany and the US increasingly prescribe enzyme-probiotic combinations for patients exiting hospital antibiotic regimens, creating institutional pull-through for synbiotic formulations.
- China's traditional medicine integration:SAMR guidelines now permit TCM-derived fermentation substrates in modern probiotic products, accelerating domestic R&D pipelines and reducing import dependency.
- Refrigerated cold-chain infrastructure:East Asian urban vending networks now maintain live culture viability through last-mile temperature control, expanding single-serve fermented distribution into convenience retail.
Market Restraints
- Dual-label compliance costs:EFSA's 10^8 CFU verification threshold diverges from FDA colony count methodologies, forcing multinational suppliers to maintain separate testing protocols and label claims for transatlantic shipments.
- Fungal fermentation substrate restrictions:China's GB standards block certain genetically modified enzyme precursors, excluding European and North American suppliers from import eligibility for specific pancreatic replacement blends.
- Live culture shelf-life volatility:Temperature excursions in ambient distribution channels degrade viable cell counts below therapeutic thresholds, limiting mass-market penetration outside cold-chain protected retail.
Strategic Opportunities
- Pediatric gummy compliance formats:Palatability-driven formulations capture children's adherence where tablet alternatives fail, opening household penetration through parent-driven purchase decisions.
- Hospital discharge bundle integration:Post-surgical recovery protocols embed digestive enzymes into standardized patient kits, creating institutional procurement contracts with multi-year lock-in potential.
- Geriatric wellness program channels:Senior living facilities and Medicare Advantage plans seek gut health maintenance products, shifting volume toward clinical dietetics and away from sports nutrition positioning.
Industry Challenges
- Overlapping regulatory jurisdiction:India's FSSAI and CDSCO maintain concurrent authority over synbiotic products claiming both structure-function and therapeutic benefits, creating notification complexity and timeline uncertainty for market entry.
- Strain-specific IP fragmentation:Probiotic culture patents reside across academic institutions, biotechnology startups, and dairy conglomerates, complicating licensing negotiations for multi-strain formulations.
- Cold-chain capex requirements:Live culture viability demands refrigerated manufacturing, warehousing, and distribution assets that commodity supplement entrants cannot replicate without substantial infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digestion Aids Market |
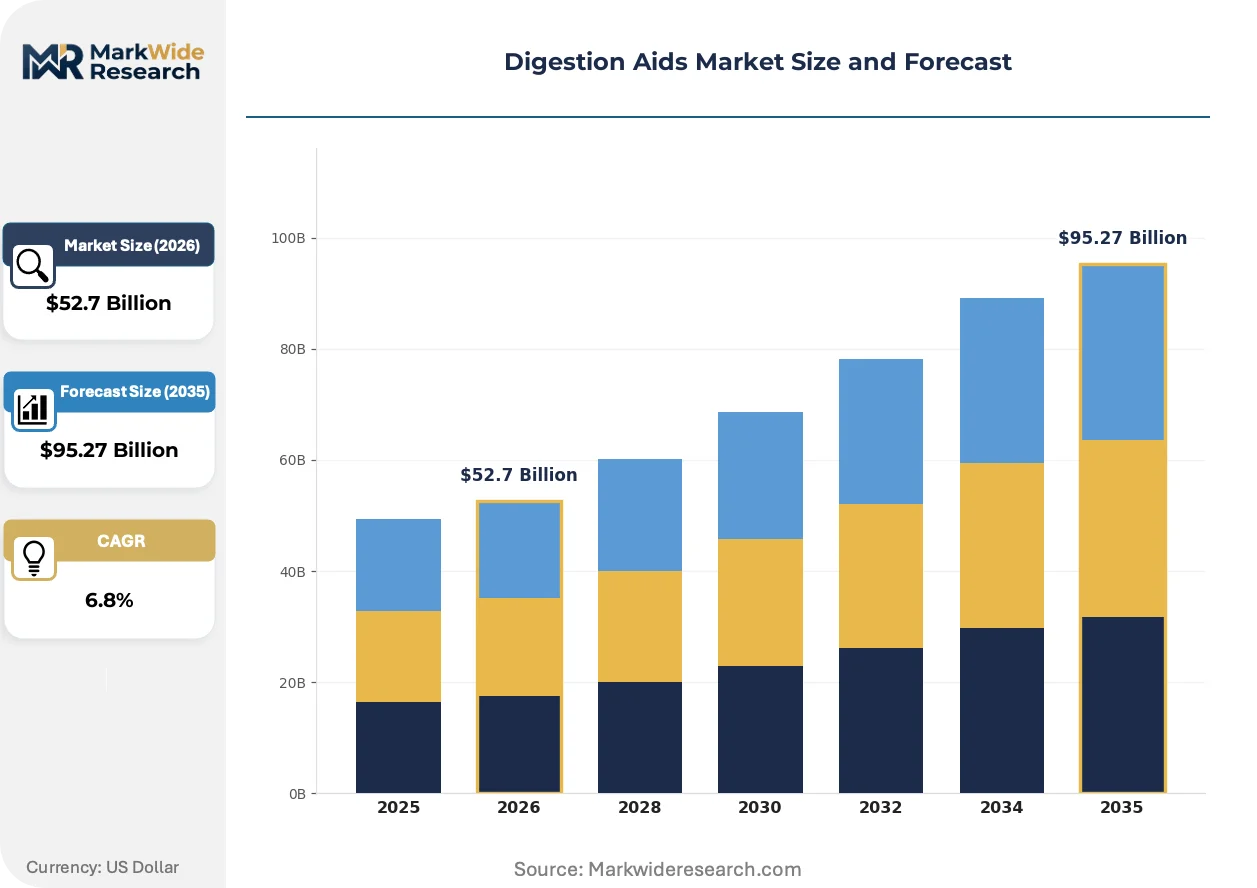
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Digestive Enzymes, Fiber Supplements Formulation: Tablets, Powders, Gummies, Liquids Distribution Channel: Retail Stores, Online Stores, Pharmacies, Supermarkets End User: Adults, Children, Seniors, Athletes |
| Companies Covered | Nestlé, Abbott Laboratories, GlaxoSmithKline, Yakult Honsha, Danone, Pfizer, Cargill, Chr. Hansen, Amway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digestion Aids Market Emerging Trajectories
Formulation science and distribution infrastructure are diverging into parallel tracks: precision microbiome targeting on one side, mass-market ambient-stable products on the other. This split redefines competitive positioning across the value chain.
Microbiome-matched synbiotics are bifurcating the premium segment from commodity probiotics. At-home gut testing services identify strain-specific deficiencies, directing consumers toward customized formulations rather than generic multi-strain products. This precision shift compresses margins for undifferentiated SKUs while enabling subscription-based replenishment models with elevated retention economics.
EFSA's evolving health claims framework tightens substantiation requirements for live culture benefits, forcing reformulation toward documented strains with clinical trial backing. Suppliers now retire legacy cultures lacking dossier depth, concentrating R&D investment on banked strains with established mechanism-of-action data. The professional channel—hospitals, dietetics practices, pharmacy counseling—absorbs these verified products while mass retail struggles with simplified messaging constraints.
Sports nutrition buyers are fragmenting into specialized sub-segments that reject one-size-fits-all digestive support. Endurance athletes prioritize gastric emptying acceleration through enzyme loading, while strength-focused consumers seek protein assimilation enhancement. This segmentation splits formerly consolidated marketing into vertical-specific positioning, complicating portfolio architecture for brands spanning multiple athletic disciplines.
Digestion Aids Market Segmentation
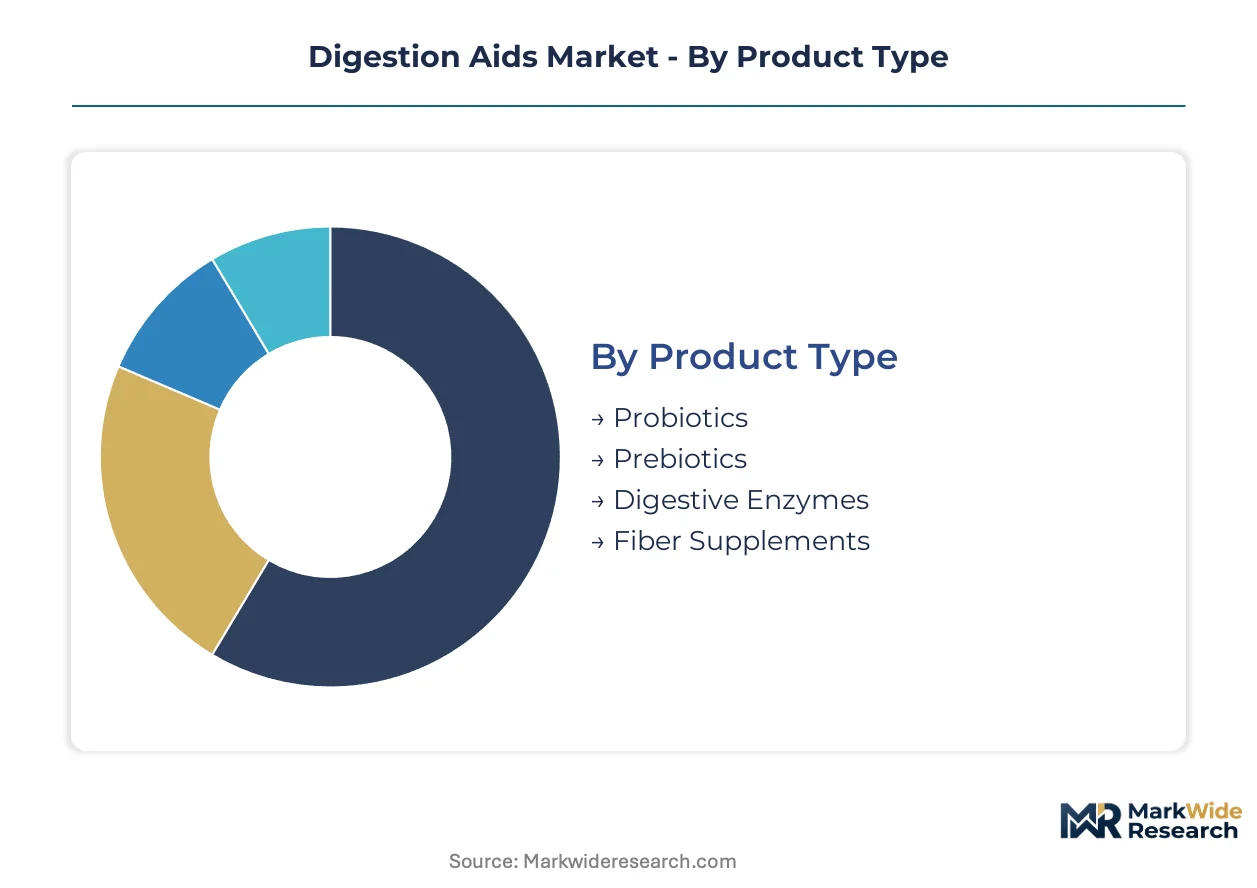
Segmentation in the digestion aids market reflects divergent regulatory thresholds for live culture viability, formulation stability requirements, and channel-specific compliance architectures. Each dimension carries distinct margin profiles and capital intensity demands that reshape competitive positioning across the value chain.
Product Type:
Regulatory differentiation separates live culture products from enzyme-based alternatives through divergent shelf-life verification protocols and import eligibility standards.
- Probiotics:Formulated products containing live microbial cultures—typically Lactobacillus, Bifidobacterium, and Saccharomyces genera—requiring refrigerated storage to maintain colony-forming unit viability above therapeutic thresholds. Demand concentrates in East Asian urban corridors where Yakult Honsha's cold-chain vending networks secure last-mile temperature control, though EFSA's 10^8 CFU verification threshold forces dual-label compliance for transatlantic suppliers.
- Digestive Enzymes:Hydrolytic protein, carbohydrate, and lipid breakdown agents derived from pancreatic, fungal, or microbial fermentation sources, prescribed increasingly for post-antibiotic dysbiosis protocols in German and US hospital discharge bundles. Clinicians embed these formulations into standardized post-surgical recovery kits, creating institutional procurement contracts with multi-year lock-in potential.
- Prebiotics:Non-digestible oligosaccharides—fructooligosaccharides, galactooligosaccharides, inulin—that selectively stimulate beneficial colonic bacteria growth.
- Fiber Supplements:Soluble and insoluble matrices enhancing colonic transit efficiency, spanning psyllium husk, methylcellulose, and wheat dextrin variants.
Probiotics handle the majority of throughput; digestive enzymes are climbing the fastest on share as clinical prescription protocols expand.
Formulation:
Cost tier differentiation separates professional-channel dose-standardized formats from mass-market palatability-driven alternatives.
- Tablets:Compressed solid dosage forms enabling precise milligram-standardized dosing and extended shelf stability without refrigeration, preferred by hospital pharmacies and clinical dietetics practices for therapeutic consistency. Professional channel procurement prioritizes tablet formulations despite slower gastric disintegration versus liquid alternatives.
- Gummies:Gelatin or pectin-based chewable matrices masking active ingredient bitterness through fruit flavoring systems, capturing children's adherence where tablet alternatives fail. Parent-driven purchase decisions in household settings elevate gummy SKUs despite higher per-dose manufacturing costs and moisture-sensitive packaging requirements.
- Powders:Granulated or micronized active blends enabling flexible dose titration and rapid dissolution in beverages.
- Liquids:Aqueous suspensions or emulsions offering fastest gastric emptying and absorption kinetics.
Tablets dominate institutional procurement volumes; gummies are expanding most quickly in household penetration metrics.
Distribution Channel:
Volume concentration follows cold-chain infrastructure availability, with ambient-stable products penetrating mass retail while live culture products remain channel-constrained.
- Retail Stores:Brick-and-mortar health food outlets, vitamin specialty chains, and general merchandise stores carrying ambient-stable fiber supplements and shelf-stable enzyme products. China's domestic formulation innovation accelerates retail shelf presence as SAMR guidelines permit TCM-derived fermentation substrates in modern probiotic products.
- Pharmacies:Licensed dispensaries and drugstore chains with refrigerated storage capacity and pharmacist counseling services, preferred channels for clinically positioned synbiotics and prescription-strength enzyme blends. India's overlapping FSSAI and CDSCO jurisdiction creates notification complexity for pharmacy-distributed products claiming dual structure-function and therapeutic positioning.
- Online Stores:Direct-to-consumer platforms and marketplace aggregators enabling subscription-based replenishment models for microbiome-matched personalized formulations.
- Supermarkets:Mass grocery retailers with limited refrigerated supplement sections, primarily distributing ambient-stable fiber and select stabilized probiotic strains.
Pharmacies handle the majority of live culture throughput; online stores are gaining share fastest through precision-matched subscription economics.
End User:
Customer type differentiation splits marketing architecture between geriatric wellness programs and fragmented athletic sub-segments.
- Seniors:Consumers aged 65+ seeking gut health maintenance through Medicare Advantage plan coverage and senior living facility procurement, representing the fastest-expanding buyer archetype as aging populations across developed economies drive clinical dietetics channel volume. Nestlé anchors supply to this segment through captive dairy fermentation infrastructure securing probiotic strain availability.
- Adults:General population consumers aged 18-64 purchasing self-directed digestive support without clinical supervision, fragmenting across mass retail and online channels.
- Children:Pediatric end users requiring palatability-driven compliance formats, with parent-mediated purchase decisions elevating gummy and liquid formulation demand.
- Athletes:Sports nutrition buyers fragmenting into endurance versus strength-focused sub-segments with divergent enzyme loading and protein assimilation priorities.
Seniors command the steepest expansion trajectory; adults retain the largest absolute volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian cold-chain rail corridors and North American refrigerated trucking networks anchor live culture distribution, while European pharmaceutical-grade enzyme corridors concentrate high-value formulation output.
United States
Medicare Advantage plans and senior living procurement drive geriatric gut health demand. FDA dietary supplement notification requirements tighten quality verification for imported probiotic cultures. Chicago and Minneapolis host clinical dietetics distribution hubs serving post-surgical recovery bundle integration.
China
Traditional medicine integration with microbiome science accelerates domestic R&D pipelines. SAMR guidelines now permit TCM-derived fermentation substrates in modern probiotic formulations. Shanghai and Guangzhou cold-chain vending networks secure last-mile live culture viability for single-serve distribution.
Germany
Hospital antibiotic discharge protocols institutionalize enzyme-probiotic combination prescriptions. EFSA's 10^8 CFU verification threshold shapes transatlantic label compliance strategies. Bavaria's pharmaceutical manufacturing clusters concentrate pancreatic replacement enzyme production for clinical channels.
Japan
Aging demographics concentrate demand in senior wellness programs and gut maintenance regimens. METI standards govern functional food claims for fermented dairy products. Tokyo and Osaka urban corridors maintain Yakult Honsha's refrigerated vending infrastructure dominance.
India
Synbiotic products face notification complexity from overlapping FSSAI and CDSCO jurisdiction. Mumbai and Bangalore pharmaceutical corridors navigate dual structure-function and therapeutic positioning requirements. Domestic fermentation capacity expands to reduce import dependency for enzyme substrates.
Digestion Aids Market Vendor Landscape
Listed leaders compete with private specialists across strain licensing and cold-chain infrastructure. The market structures around three tiers: dairy conglomerates with captive fermentation assets, pharmaceutical manufacturers embedding enzymes into clinical protocols, and biotechnology specialists licensing documented cultures. Strategic moves concentrate on backward integration into strain banking and geographic expansion through refrigerated distribution partnerships.
Within the dairy-anchored tier, Nestlé and Danone occupy positions secured by captive fermentation infrastructure. Abbott Laboratories exemplifies pharmaceutical-channel integration through hospital discharge bundle embedding. Yakult Honsha anchors single-serve fermented distribution through proprietary cold-chain vending networks across East Asian urban corridors.
| Leading Market Players |
|---|
| Nestlé |
| Abbott Laboratories |
| GlaxoSmithKline |
| Yakult Honsha |
| Danone |
| Pfizer |
| Cargill |
| Chr. Hansen |
| Amway |
| Others |
Supply Flow & Price Mechanics
Cold-chain infrastructure scale economies in East Asia and North America anchor supply concentration while setting price floors for live culture products that ambient-stable competitors cannot match. Manufacturers with captive fermentation assets leverage refrigerated warehousing networks to defend margin structures against commodity enzyme suppliers lacking temperature-controlled distribution capabilities.
Pricing Analysis
Volume-discount tiering structures separate institutional procurement contracts from direct-to-consumer subscription models. Three-tier pricing stratification across premium clinical-grade, standard pharmacy-channel, and economy mass-retail levels reflects certification depth and strain documentation quality. Cost compression in the economy tier intensifies as private-label enzyme suppliers erode branded share in ambient-stable categories. Hospital discharge bundle buyers exhibit lowest price sensitivity due to protocol standardization, while self-directed adult consumers in online channels demonstrate highest elasticity.
Supply Chain Analysis
Strait of Malacca transit routes and East Asian cold-chain rail corridors constitute critical chokepoints for fungal fermentation substrates and live culture concentrates. Manufacturing gravity centers on China, Germany, and Japan, with Bavarian pharmaceutical clusters and Shanghai fermentation parks anchoring enzyme and probiotic output respectively. Supply chains draw from pancreatic tissue, Aspergillus oryzae cultures, and prebiotic oligosaccharide feedstocks. Single-source vulnerability concentrates in refrigerated last-mile distribution assets. Distribution runs through pharmacy chains with cold storage, direct-to-consumer subscription platforms, and hospital procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strain banking capabilities and refrigerated logistics assets constitute scarce competitive moats that separate viable participants from commodity entrants lacking upstream control over live culture viability.
For Market Incumbents: Compound defensive positioning through backward integration into proprietary strain repositories and expansion of cold-chain vending partnerships in East Asian urban corridors. Nestlé and Yakult Honsha demonstrate how captive fermentation infrastructure blocks enzyme supplier encroachment into premium probiotic segments. Certification investment in EFSA-compliant clinical dossiers protects professional channel access against private-label displacement. For New Entrants and Emerging Players: Pediatric gummy formulation gaps expose incumbent under-service of taste-sensitive compliance segments where parent-mediated purchase decisions concentrate. White-space availability concentrates in microbiome-matched subscription services and post-antibiotic dysbiosis protocol positioning for German and US hospital discharge channels. Direct-to-consumer gut testing integration offers a go-to-market angle bypassing pharmacy cold-chain requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotechnology specialists with banked clinical strains over undifferentiated commodity enzyme suppliers. Five-to-ten year viability hinges on regulatory harmonization outcomes between Codex Alimentarius and national agencies. Acquisition targets should demonstrate documented mechanism-of-action data and refrigerated distribution partnerships. The signal to watch is SAMR guidance on TCM-fermentation substrate eligibility reshaping China import substitution dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Banking Investment | Proprietary culture repositories secure formulation differentiation against licensing cost escalation from academic institutions. |
| Cold-Chain Partnership Expansion | Refrigerated last-mile vending networks in Tokyo and Shanghai urban corridors defend live culture viability thresholds. |
| Clinical Dossier Development | EFSA-compliant health claim substantiation unlocks pharmacy channel access and professional recommendation pull-through. |
| TCM Substrate Integration | SAMR-permitted traditional fermentation inputs reduce import dependency and accelerate China domestic R&D pipelines. |
| Hospital Bundle Embedding | Post-surgical recovery protocol standardization creates multi-year institutional procurement lock-in for enzyme-probiotic combinations. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA dietary supplement notifications, EFSA health claim registers, SAMR guideline releases, and customs trade data for enzyme and probiotic imports. Primary inputs drew from fermentation technology directors, clinical dietetics procurement managers, pharmacy chain category buyers, and cold-chain logistics operators. Secondary validation incorporated hospital discharge protocol databases, Medicare Advantage plan formulary filings, and refrigerated warehousing capacity reports. Bottom-up strain-level demand modeling triangulated against top-down category expenditure estimates.
Segmentation dimensions modeled span product type, formulation format, distribution channel, and end-user archetype across the projection horizon. Patient population stratification by antibiotic exposure history and age cohort informed enzyme prescription trajectory assumptions. Regulatory cluster differentiation by FDA, EFSA, SAMR, and FSSAI jurisdiction shaped market access probability weights. CAGR derivation integrated historical cold-chain infrastructure expansion rates with geriatric population demographic projections.
Underlying assumptions cover sustained Medicare Advantage gut health benefit coverage, EFSA live culture count verification threshold stability, and China TCM-fermentation substrate guideline permissiveness, with deviation risk concentrated in regulatory harmonization negotiations and refrigerated logistics cost inflation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market
Probiotic Supplements
D-Lactate Free Probiotics Market
Probiotic Supplements
Microbial Food Culture Market
Probiotic Supplements
Europe Probiotics Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
Anti-Diarrheal Supplements Market
Probiotic Supplements
Multistrain Probiotics Market
Probiotic Supplements
Synbiotic Foods Market
Probiotic Supplements
Bifidobacterium Probiotics Market
Probiotic Supplements
South America Feed Probiotics Market
Probiotic Supplements
Bifidobacteria Lysates Market
Probiotic Supplements
Infant and Kids Probiotics Market
Probiotic Supplements
North America Oral Health Probiotics Market
Probiotic Supplements
Lactobacillus Acidophilus Market