
 Healthy Fruit and Vegetable Chips Market | 2026-2036
Healthy Fruit and Vegetable Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Healthy Fruit and Vegetable Chips Market Intelligence
The distinction between premium, organic vegetable chips and mass-market, conventional fruit snacks is hardening. Rhythm Superfoods specializes in nutrient-dense kale chips for niche health channels. The Hain Celestial Group leverages its established distribution network for its natural food brands. In contrast, PepsiCo competes on scale and broad market access through its extensive supermarket presence.
Healthy fruit and vegetable chips are thinly sliced produce processed via methods like vacuum frying or freeze-drying to minimize oil absorption and preserve nutrients. The primary commercial purpose is to offer a nutrient-denser alternative to traditional fried potato chips. Kale chips and beet chips represent high-margin product types often sold through specialty health food stores. The organic ingredient source segment commands a price premium, while online retailers are becoming a critical distribution channel for emerging brands.
Regulations from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern nutritional labeling and health claims. In India, FSSAI standards dictate permissible ingredients and processing aids. These rules directly impact packaging design and marketing language. Navigating the complex web of international organic certifications will be a key differentiator for brands seeking premium positioning.
Market Dynamics
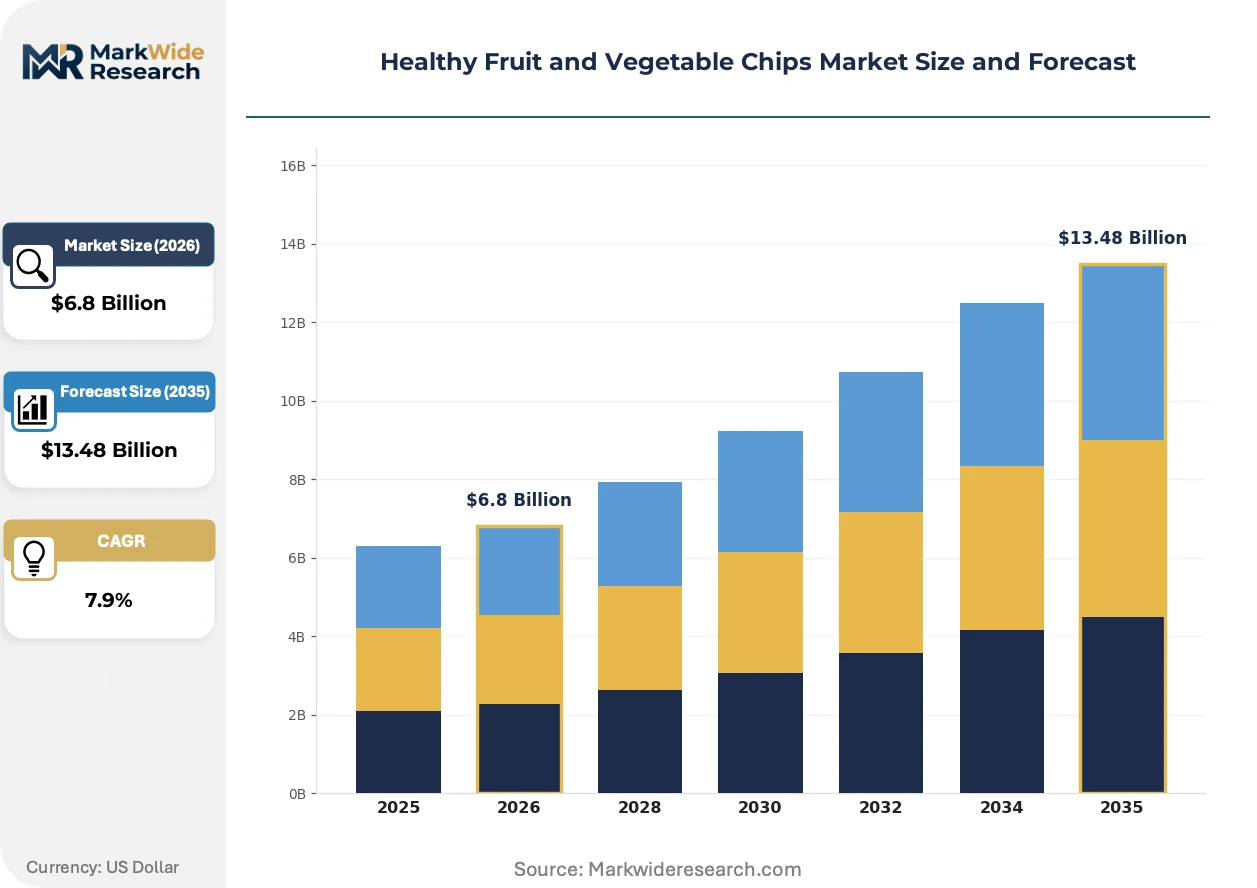
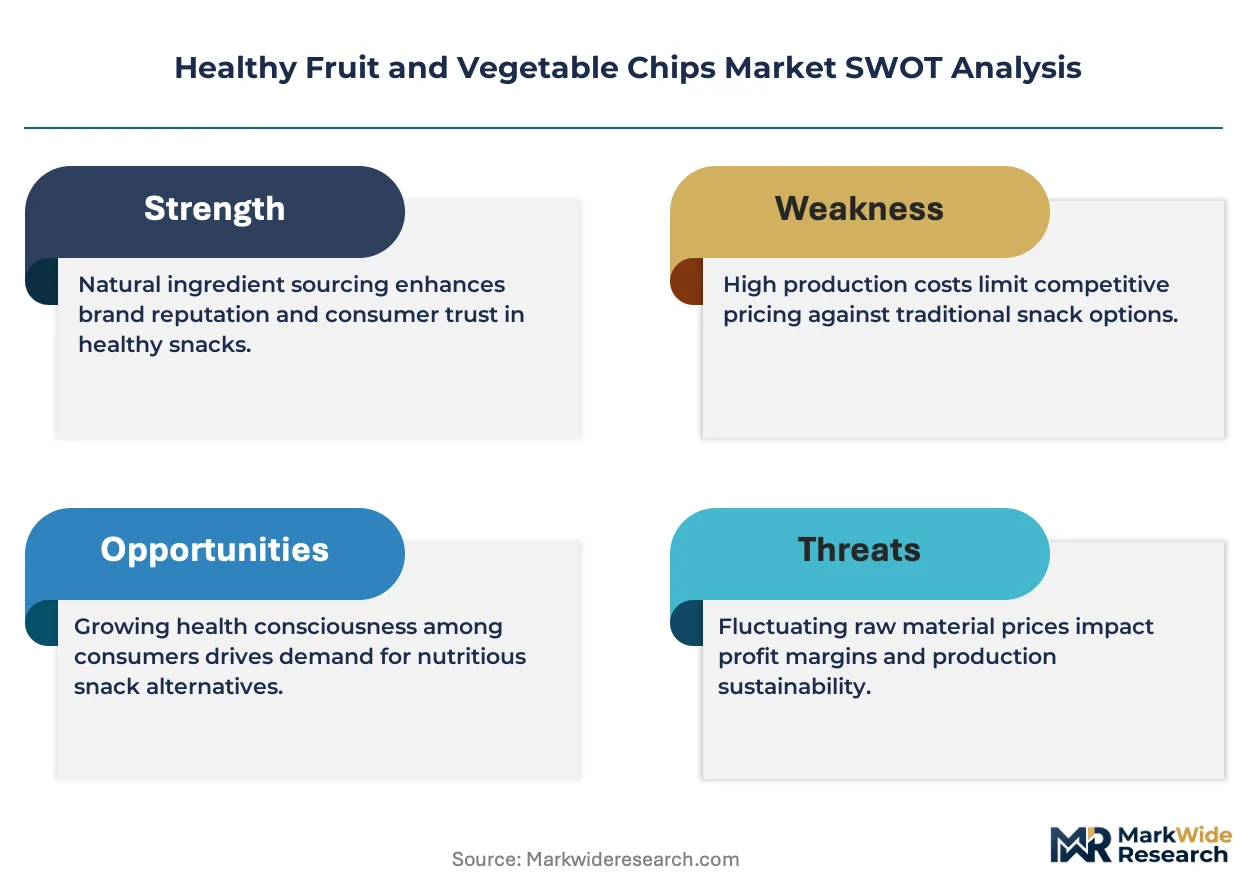
The market's primary structural force is the tension between consumer demand for clean-label, nutrient-dense snacks and the high processing costs and supply chain complexities inherent in producing them at a competitive price point against conventional alternatives.
Growth Catalysts
- Corporate Wellness Programs:Demand from corporate wellness initiatives in North America and Europe for healthy office snack alternatives is creating a significant B2B sales channel for bulk-packaged vegetable chips.
- Processing Technology:Innovations in vacuum-frying and freeze-drying technologies are enabling better retention of nutrients and texture, allowing brands to make more credible health claims and justify premium pricing.
- Regulatory Support:Government-backed healthy eating campaigns and updated nutritional guidelines for school cafeterias in countries like the United States and India are boosting institutional procurement of fruit and vegetable chips.
Market Restraints
- Input Cost Volatility:The market is sensitive to price fluctuations and seasonal availability of specialty produce, particularly organic kale and beets, which directly impacts final product cost and manufacturer margins.
- Substitution Threat:A wide array of other healthy snack options, including protein bars, nuts, and seeds, competes directly for the same health-conscious consumer base, limiting market share growth.
- Technical Hurdles:Achieving a desirable texture and a stable shelf life without using artificial preservatives remains a significant technical challenge, especially for emerging brands lacking scale and R&D resources.
Strategic Opportunities
- Channel Innovation:Direct-to-consumer subscription models offer a pathway for brands to build customer loyalty, gather valuable purchasing data, and bypass crowded retail shelf space.
- Geographic Expansion:There is significant potential in markets across the Middle East and Southeast Asia, where rising disposable incomes and a growing focus on wellness are creating new consumer segments.
- Ingredient Upcycling:Utilizing imperfect produce that is unsuitable for the fresh market presents an opportunity to reduce food waste, lower input costs, and build a sustainability-focused brand narrative.
Industry Challenges
- Certification Complexity:Brands targeting a premium position face significant administrative burdens and costs in securing and maintaining multiple organic and non-GMO certifications, such as USDA Organic and EU Organic, for international distribution.
- Labeling Regulation:Navigating the intricate and varied health claim regulations set by bodies like the FDA in the US and EFSA in Europe requires substantial legal and compliance investment.
- Capital Intensity:The high capital expenditure needed for specialized equipment like vacuum fryers and freeze-dryers creates a barrier to entry for smaller companies and limits production scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthy Fruit and Vegetable Chips Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Potato Chips, Kale Chips, Beet Chips, Apple Chips Ingredient Source: Organic, Non-GMO, Gluten-Free, Conventional Packaging Type: Resealable Bags, Snack Packs, Bulk Packaging, Cans Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Shops |
| Companies Covered | PepsiCo, Calbee Inc., Rhythm Superfoods, The Hain Celestial Group, Bare Snacks, General Mills, Seneca Foods Corporation, Walmart, Luke's Organic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthy Fruit and Vegetable Chips Market Strategic Shifts & Innovations
A clear bifurcation is defining the market, separating premium, nutrient-dense vegetable chips from mass-market fruit snacks that often compete on price. This split influences everything from processing technology choices to distribution strategies and marketing claims.
Vacuum-frying technology allows for processing at lower temperatures, which significantly reduces oil absorption and helps preserve the natural color and nutritional profile of the raw produce. Health-focused consumer segments are driving adoption of products made with this method. This processing capability is expanding into a wider variety of substrates, including root vegetables like parsnips and carrots, creating new high-margin product lines.
Stricter regulations governing front-of-pack nutritional labeling, such as those mandated by the FDA and considered by EFSA, are forcing a re-evaluation of product formulations. This regulatory pressure directly impacts fruit chip manufacturers, who must now contend with clearer declarations of total and added sugars. Consequently, vegetable chip brands are gaining a competitive advantage by emphasizing their naturally low-sugar content in marketing communications.
Consumer purchasing behavior is shifting from spontaneous, in-store purchases to deliberate, research-driven buys through online platforms and specialty health food retailers. This trend disrupts the dominance of large supermarkets and provides a direct channel for emerging brands to reach niche audiences. The shift is most pronounced within the United States, where a mature e-commerce infrastructure supports direct-to-consumer and subscription-based business models.
Healthy Fruit and Vegetable Chips Market Segmentation
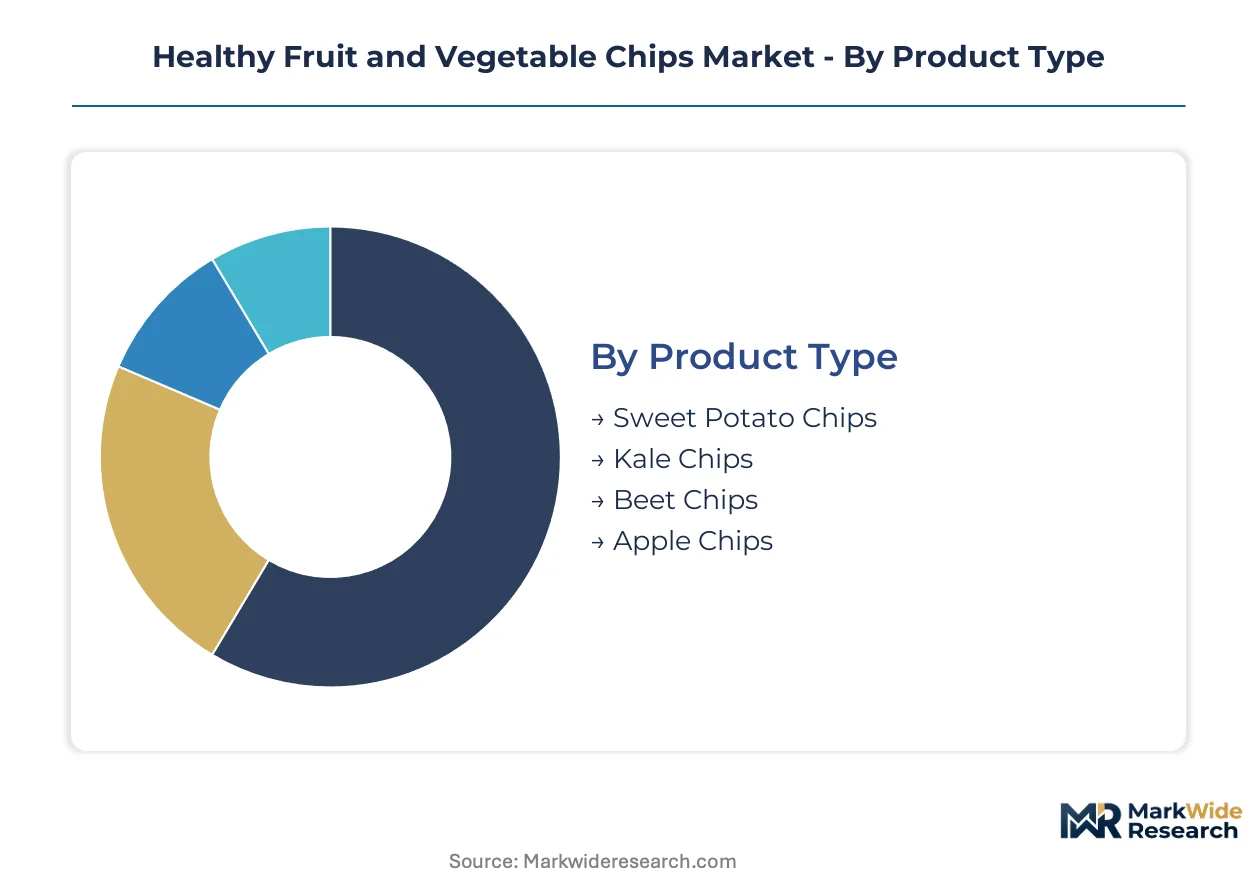
The healthy fruit and vegetable chips market exhibits distinct segmentation, reflecting diverse consumer preferences and operational strategies across the value chain. Understanding these segments helps manufacturers tailor product formulations, packaging, and distribution strategies to specific market demands. This granular view reveals where value accrues and competitive advantages are forged.
Product Type:
Supply concentration in the healthy fruit and vegetable chips market heavily influences product type availability and innovation cycles.
- Kale Chips:These nutrient-dense chips are typically vacuum-fried or air-dried to retain vitamins and minerals, offering a savory, crunchy texture. Demand concentrates within niche health channels and among United States consumers seeking clean-label, low-calorie snack options.
- Beet Chips:Characterized by their vibrant color and earthy sweetness, beet chips are often freeze-dried to preserve their natural flavor and nutritional profile. Demand is strong in specialty health food stores and among European wellness programs prioritizing functional foods.
- Sweet Potato Chips:Made from thinly sliced sweet potatoes, these chips offer a naturally sweet and fiber-rich alternative to traditional potato chips.
- Apple Chips:These fruit-based chips provide a crisp texture and natural sweetness, appealing particularly to younger consumers and school cafeterias.
Today's leader: Kale Chips. Tomorrow's challenger: Beet Chips.
Ingredient Source:
Cost tier differentiation significantly influences pricing within the ingredient source segment for healthy fruit and vegetable chips.
- Organic:Products in this segment use ingredients grown without synthetic pesticides, herbicides, or genetically modified organisms, requiring specific certifications. Demand concentrates among United States clean-label consumers and European health food stores willing to pay a premium.
- Non-GMO:This segment comprises products made from ingredients that have not been genetically engineered, addressing consumer concerns about food modification. Demand is particularly strong in the North American market and within corporate wellness programs emphasizing natural ingredients.
- Gluten-Free:These chips are formulated to exclude gluten-containing grains, catering specifically to individuals with celiac disease or gluten sensitivities.
- Conventional:This segment utilizes produce grown using standard agricultural practices, allowing for more competitive pricing and broader market accessibility.
The Organic segment is expanding most quickly, driven by consumer preference for natural products.
Packaging Type:
Packaging type is directly shaped by the intended application and consumption occasion for healthy fruit and vegetable chips.
- Resealable Bags:These flexible pouches feature a reclosable zipper, designed to maintain freshness and prevent spoilage after initial opening. Demand concentrates among individual consumers and through online retail platforms for convenience.
- Bulk Packaging:Large-format containers are used for cost-effective distribution of high volumes of chips, often targeting institutional or B2B clients. Demand is significant from corporate wellness programs and school cafeterias in North America.
- Snack Packs:Single-serving portions are designed for on-the-go consumption, providing portion control and convenience for busy lifestyles.
- Cans:Rigid, protective containers offer extended shelf life and protection from crushing, though they are less common for this product category.
Resealable Bags are gaining share fastest among individual consumers seeking convenience and freshness.
Distribution Channel:
Customer type dictates the most effective distribution channels for healthy fruit and vegetable chips.
- Online Retailers:E-commerce platforms, including direct-to-consumer websites and subscription services, offer brands a direct route to consumers. Demand is concentrated among United States consumers and emerging brands targeting niche audiences.
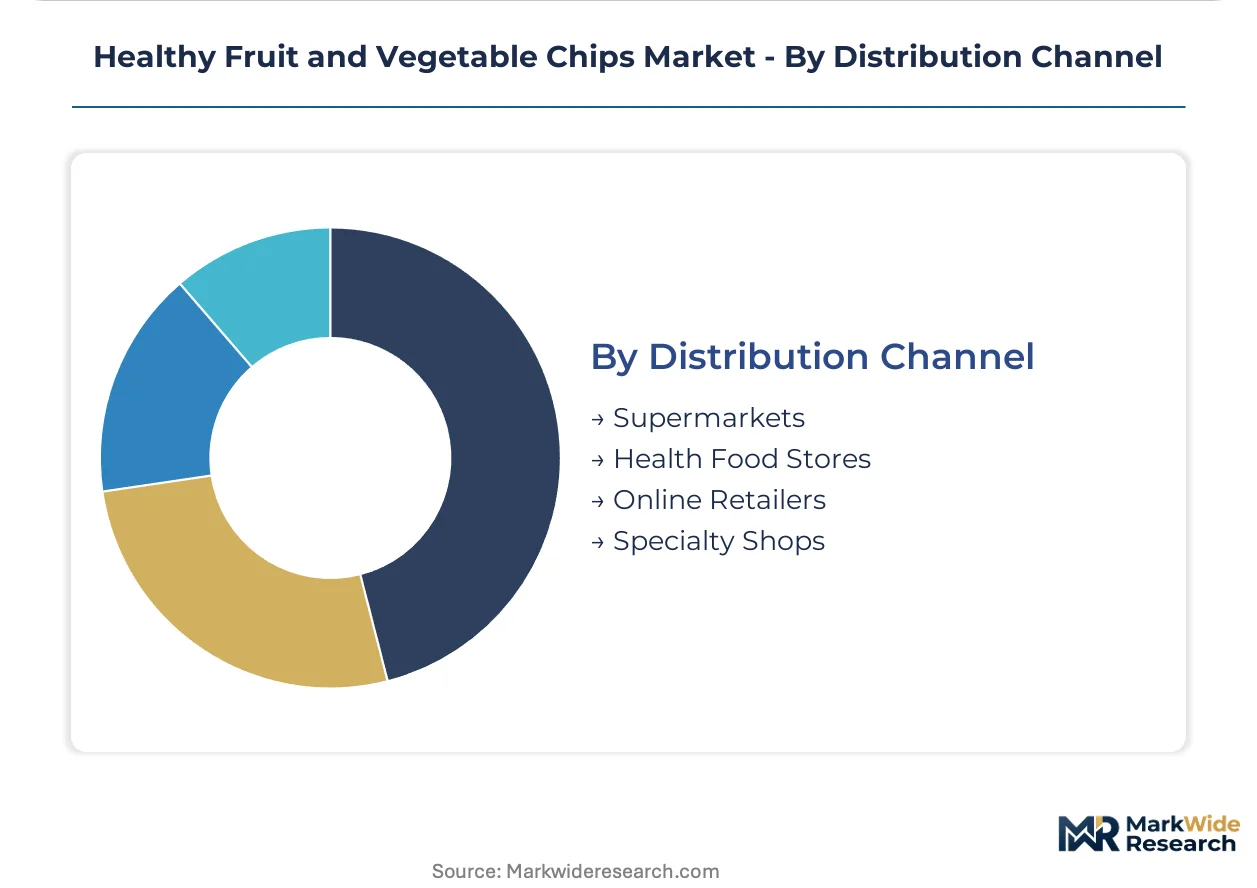
- Supermarkets:Large-format grocery stores provide broad consumer reach and high volume sales, serving as a primary channel for mass-market fruit snacks. Demand is driven by established brands leveraging extensive presence.
- Health Food Stores:These specialized retailers offer a curated selection of natural, organic, and health-focused products, catering to a specific health-conscious demographic.
- Specialty Shops:Boutique retailers often focus on premium, high-margin vegetable chips, offering unique product selections and personalized customer service.
Online Retailers show the steepest expansion trajectory, driven by evolving consumer purchasing behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States market emphasizes clean-label, low-calorie options, while European consumers prioritize functional foods and organic ingredients. This regional divergence shapes product development and distribution strategies across continents. Institutional demand from school cafeterias also creates distinct procurement patterns.
United States
Consumer demand for healthy, convenient snacks drives market expansion in the United States. The USDA's updated nutritional guidelines for school cafeterias boost institutional procurement of fruit and vegetable chips. Silicon Valley's corporate wellness programs frequently purchase bulk-packaged vegetable chips for employee benefits.
India
India's market growth is supported by government-backed healthy eating campaigns and FSSAI standards. These initiatives encourage healthier snack alternatives for the country's large youth population. Major metropolitan areas like Mumbai and Delhi show rising demand from health-conscious urban consumers.
Germany
German consumers increasingly seek organic-certified and non-GMO healthy snack options. The European Food Safety Authority (EFSA) regulations on nutritional labeling influence product formulation and marketing claims. Bavaria, a hub for organic food production, sees a concentration of specialty health food stores offering premium vegetable chips.
China
Rising disposable incomes and a growing focus on wellness are creating new consumer segments in China. The country's national food safety regulator dictates permissible ingredients and processing aids. Cities like Shanghai and Beijing are emerging as key markets for imported and locally produced healthy fruit and vegetable chips.
Japan
Japanese consumers prioritize product quality and innovative healthy food options. The Ministry of Health, Labour and Welfare (MHLW) sets standards for food additives and health claims. Tokyo's bustling urban centers drive demand for convenient, single-serving snack packs tailored to busy lifestyles.
Healthy Fruit and Vegetable Chips Market Key Industry Players
Top-tier vendors anchor the mass-market segment, while specialized health food brands target niche channels with premium offerings. The market structure exhibits a tiered approach, with large conglomerates coexisting with agile, emerging direct-to-consumer players. Strategic archetypes include scale-driven manufacturers focused on broad appeal, organic ingredient specialists, and technology-focused innovators using vacuum-frying. Dominant competitive moves involve geographic expansion into new markets and portfolio diversification to capture diverse consumer preferences across health and convenience.
Scale-driven enterprises like PepsiCo leverage extensive supermarket presence and broad market access for their diverse snack offerings, competing on price and availability. Meanwhile, specialized health food brands such as Rhythm Superfoods exemplify a focus on nutrient-dense kale chips, targeting niche health channels with premium, clean-label products. The Hain Celestial Group occupies a strategic position within the natural food brands segment, utilizing its established distribution network to offer a range of organic and health-conscious snacks. These players represent distinct approaches to market penetration and consumer engagement.
| Leading Market Players |
|---|
| PepsiCo |
| Calbee Inc. |
| Rhythm Superfoods |
| The Hain Celestial Group |
| Bare Snacks |
| General Mills |
| Seneca Foods Corporation |
| Walmart |
| Luke's Organic |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps dominate specialty produce sourcing, influencing pricing discipline through direct farm relationships and quality control. Their localized supply networks support premium product positioning against mass-market alternatives.
Pricing Analysis
Value-added product offerings dictate pricing in the healthy fruit and vegetable chips market, moving beyond simple per-unit transactional models. Price differentiation stems from USDA Organic and EU Organic certifications, alongside established brand premium for niche health brands like Rhythm Superfoods. Pricing softness affects conventional offerings due to widespread substitution threats from other snack categories. Health-conscious consumers show lower price sensitivity for organic options, while mass-market buyers prioritize affordability and broad availability.
Supply Chain Analysis
Organic kale and beet supply rests heavily on specialized agricultural regions within the United States and parts of Europe. These raw material dependencies, coupled with the need for specialized vacuum fryers and freeze-dryers, create significant capital intensity. Commodity price volatility for specialty organic produce represents a structural supply chain risk for manufacturers. Distribution runs through online retailers for emerging brands targeting niche audiences and extensive supermarket networks for established mass-market players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The healthy fruit and vegetable chips market presents a clear margin-expansion story, driven by consumer willingness to pay premiums for clean-label, nutrient-dense snacks. Ingredient upcycling offers a significant cost-down driver for manufacturers.
For Market Incumbents: Deepen strategic partnerships with organic produce suppliers to mitigate input cost volatility. Invest in advanced vacuum-frying technology to reinforce nutrient retention, countering the substitution threat from protein bars. Expand distribution into corporate wellness programs to secure B2B channels. Consolidate smaller, niche brands to gain market share and brand diversity.
For New Entrants and Emerging Players: Enter via direct-to-consumer subscription models, building customer loyalty and gathering valuable purchasing data. Target underpenetrated markets in the Middle East and Southeast Asia, where wellness trends are emerging. Focus on ingredient upcycling to reduce input costs and build a sustainability-focused brand narrative. Leverage online retailers as the most penetrable channel for niche product launches.
For Investors and Strategic Acquirers: Large CPG conglomerates are the most active acquirers in this space, seeking to diversify their snack portfolios with health-focused brands. The market demonstrates long-term viability over the next decade due to sustained consumer demand for healthier alternatives. Target acquisition archetypes include technology-focused innovators with proprietary processing capabilities. Watch for increased regulatory support for healthy eating campaigns as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Vacuum-Frying R&D | Improves nutrient retention and texture, supporting premium pricing and health claims. |
| Expand Direct-to-Consumer Channels | Builds customer loyalty and provides valuable purchasing data for emerging brands. |
| Pursue International Organic Certifications | Unlocks premium positioning and market access in European and Asian markets. |
| Implement Ingredient Upcycling Programs | Reduces food waste and input costs, enhancing sustainability-focused brand narratives. |
| Target Corporate Wellness Programs | Creates a significant B2B sales channel for bulk-packaged vegetable chips in North America. |
Research Approach
Coverage spans North America, Europe, and Asia, with primary inputs from each region. Analysts conducted interviews with brand managers, R&D directors, and procurement specialists across the value chain. Secondary validation leveraged USDA nutritional guidelines, EFSA reports, and FSSAI standards. This approach combined bottom-up data collection with top-down market sizing for robust analysis.
Granularity levels modeled product type, ingredient source, and distribution channel across key geographies. The analytical framework incorporated historical growth patterns and projected consumer behavior shifts throughout the forecast period. CAGRs were derived from a weighted average of segment-specific growth rates. Forecast inputs included evolving dietary guidelines and technological advancements in vacuum-frying.
Inputs from public financial reports and regulatory databases were available through the study window; gaps in emerging market consumption data introduce uncertainty bands. Forecasts reflect assumptions regarding consumer preference stability and raw material availability. Geopolitical events impacting global supply chains represent a specific risk factor. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Organic Snack Food Market
Snacks
Marshmallow Market
Snacks
Duck Neck (Chinese Snack) Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
United States Popcorn Market
Snacks
Middle East and Africa Frozen Snacks Market
Snacks
Asia-Pacific Popcorn Market
Snacks
Energy Bar Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
High Carb Low Fat Snack Market
Snacks
Extruded Snacks Market
Snacks
Snack Food Packaging Market
Snacks
Austria Snack Bar Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Global Rice Snacks Market
Snacks
Asia Pacific Tortilla Market