
 Premium Snacks Market | 2026-2036
Premium Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Premium Snacks Market Outlook
Consolidation among convenience retail chains and specialty grocers is restructuring procurement leverage across the premium snacks sector. Nestlé leverages its global distribution infrastructure to secure premium placement in consolidated retail channels. Mondelez International differentiates through R&D intensity in texture and flavor science. PepsiCo Inc. anchors its position with manufacturing scale that supports consistent supply to high-volume retail partners.
Premium snacks comprise value-added food products manufactured with superior ingredient grades, specialized processing techniques such as kettle-cooking or air-popping, and enhanced sensory profiles targeting discerning consumers. These products serve commercial purposes spanning impulse retail, on-premise hospitality, and direct-to-consumer subscription channels. Nuts and popcorn segments lead margin pools due to perceived health credentials and premium pricing tolerance. Organic and non-GMO ingredient quality tiers are expanding fastest as clean-label expectations migrate from niche to mainstream retail expectations. Resealable pouch packaging controls significant shelf-space economics by extending freshness perception and supporting premium price points.
FDA nutrition labeling requirements and EU EFSA health claim regulations shape permissible marketing language and ingredient transparency obligations across premium snack portfolios. REACH compliance and FDA food contact substance rules govern packaging material selection, directly influencing resealable and sustainable format adoption costs. Stakeholders must monitor evolving clean-label enforcement intensity and packaging sustainability mandates to preserve market access and margin structure.
Market Dynamics
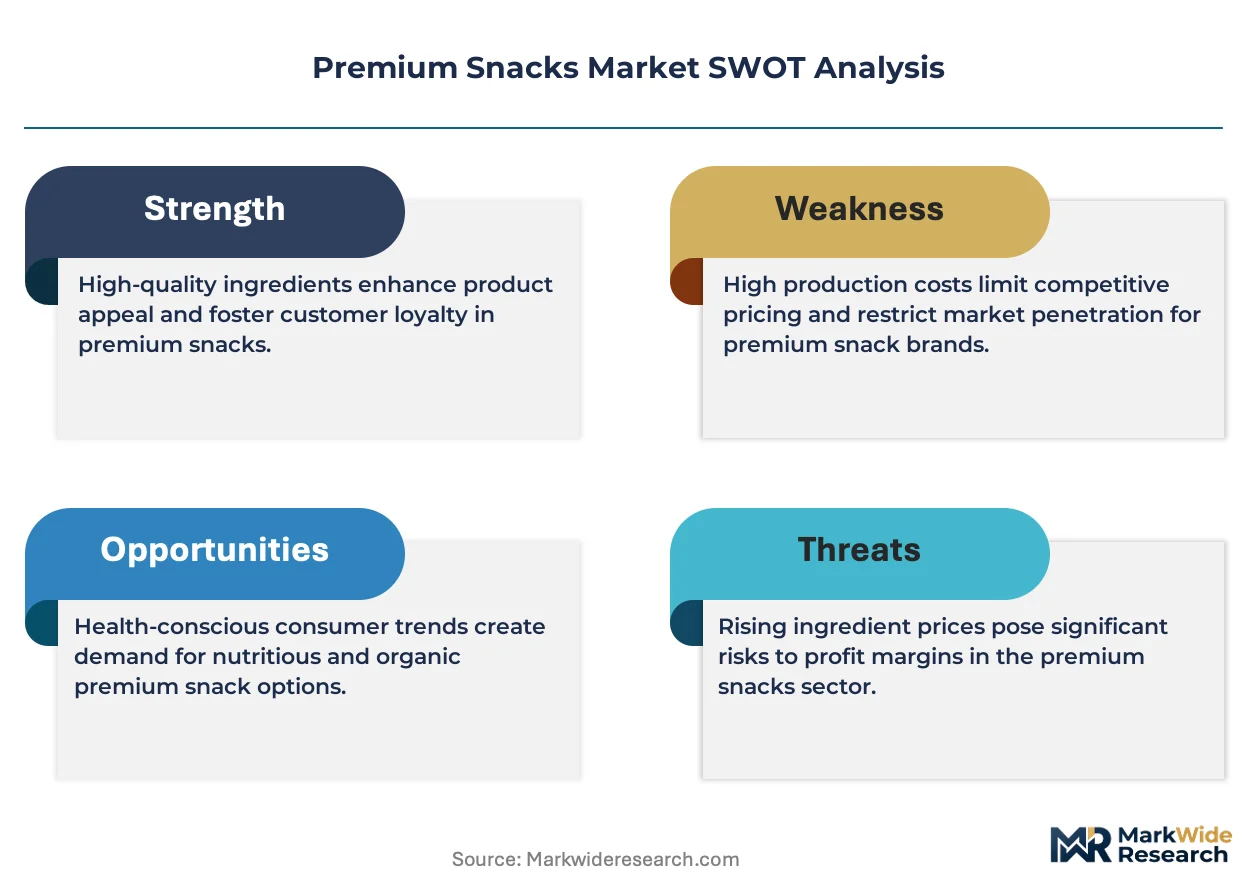
Clean-label enforcement intensity from FDA and EFSA is compressing formulation flexibility while consolidating procurement leverage among retailers with dedicated compliance infrastructure. This regulatory pressure is redistributing margin pools toward suppliers with vertically integrated ingredient traceability systems.
Growth Catalysts
- EU EFSA health claim regulations:Validated functional ingredient positioning unlocks premium pricing in German and Dutch retail channels.
- Kettle-cooking and air-popping processing methods:Sensory differentiation commands shelf-space allocation in consolidated convenience store chains.
- United States:Mature premium snacking habits sustain resealable pouch adoption rates and subscription channel penetration.
Market Restraints
- Organic and non-GMO input cost volatility:Sourcing concentration in specific agricultural regions exposes margin structures to climate-driven supply shocks.
- REACH compliance for packaging materials:Sustainable format adoption costs constrain mid-tier manufacturer participation in EU retail.
- Conventional mass-market snack substitution:Price-sensitive consumer segments in emerging markets delay premium category migration.
Strategic Opportunities
- Japan:Underpenetrated direct-to-consumer subscription models offer white space for texture-innovation specialists.
- Biodegradable resealable films:Convergence of barrier technology and compostable polymers enables regulatory-preemptive positioning.
- On-premise hospitality channel:Premium nut and popcorn portion formats capture unaddressed foodservice demand.
Industry Challenges
- Clean-label certification timelines:Third-party non-GMO and organic verification creates working capital intensity for new entrants.
- Flavor science talent scarcity:Specialized food technologist recruitment constrains R&D throughput for texture innovation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premium Snacks Market |
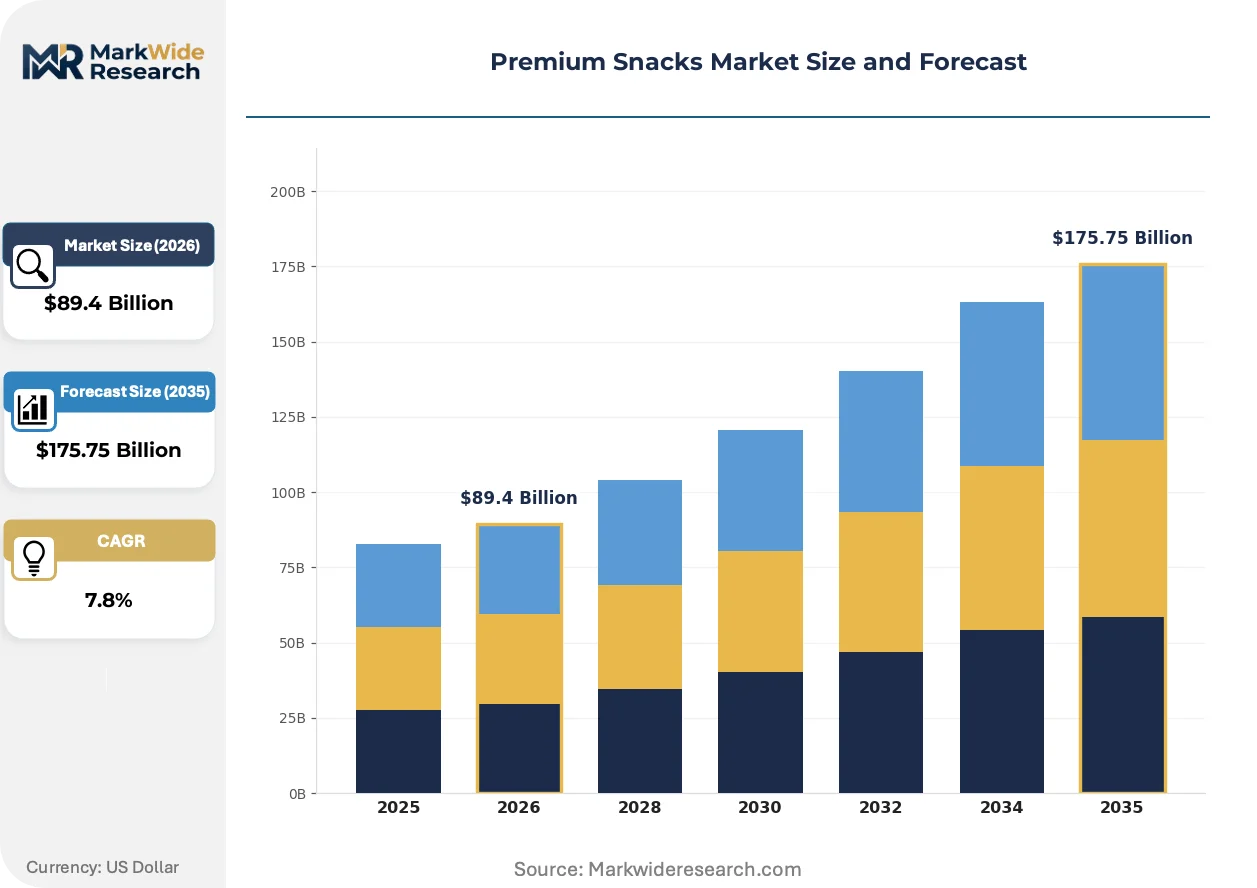
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $175.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Nuts, Crackers, Popcorn Flavor Profile: Sweet, Savory, Spicy, Tangy Packaging Type: Resealable Bags, Boxes, Pouches, Cans Ingredient Quality: Organic, Gluten-Free, Natural, Non-GMO |
| Companies Covered | Nestlé, Kellanov, PepsiCo Inc., Conagra Brands, Inc., General Mills Inc., Mondelez International, Ferrero, Unilever, Mars, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premium Snacks Market Strategic Shifts
Processing technology and packaging material science are converging to redefine freshness perception and sustainability credentials across premium snack portfolios. These developments are compressing traditional competitive moats while opening new regulatory-compliant positioning vectors.
High-pressure processing and modified atmosphere packaging is absorbing capital allocation from conventional thermal sterilization methods. Premium nut processors in California and Bavaria are adopting these systems to extend clean-label shelf stability without preservative inclusion. This technology shift is absorbing margin pressure from ingredient cost inflation by reducing spoilage write-downs and enabling direct-to-consumer fulfillment models.
EU Green Deal packaging sustainability mandates are accelerating biodegradable barrier film development across German and French supply chains. Industrial compostability certification requirements are disqualifying conventional multi-layer laminates from premium retail placement. Nut and popcorn segments face the steepest compliance curves due to high oil content demanding superior oxygen barrier performance.
Subscription-based replenishment purchasing is consolidating household pantry procurement into predictable automated cycles. Direct-to-consumer channels in the United States and Japan are displacing impulse-driven convenience store purchasing for core premium snack categories. This behavioral pivot concentrates demand forecasting accuracy requirements on fulfillment infrastructure rather than retail slotting negotiation.
Premium Snacks Market Segmentation
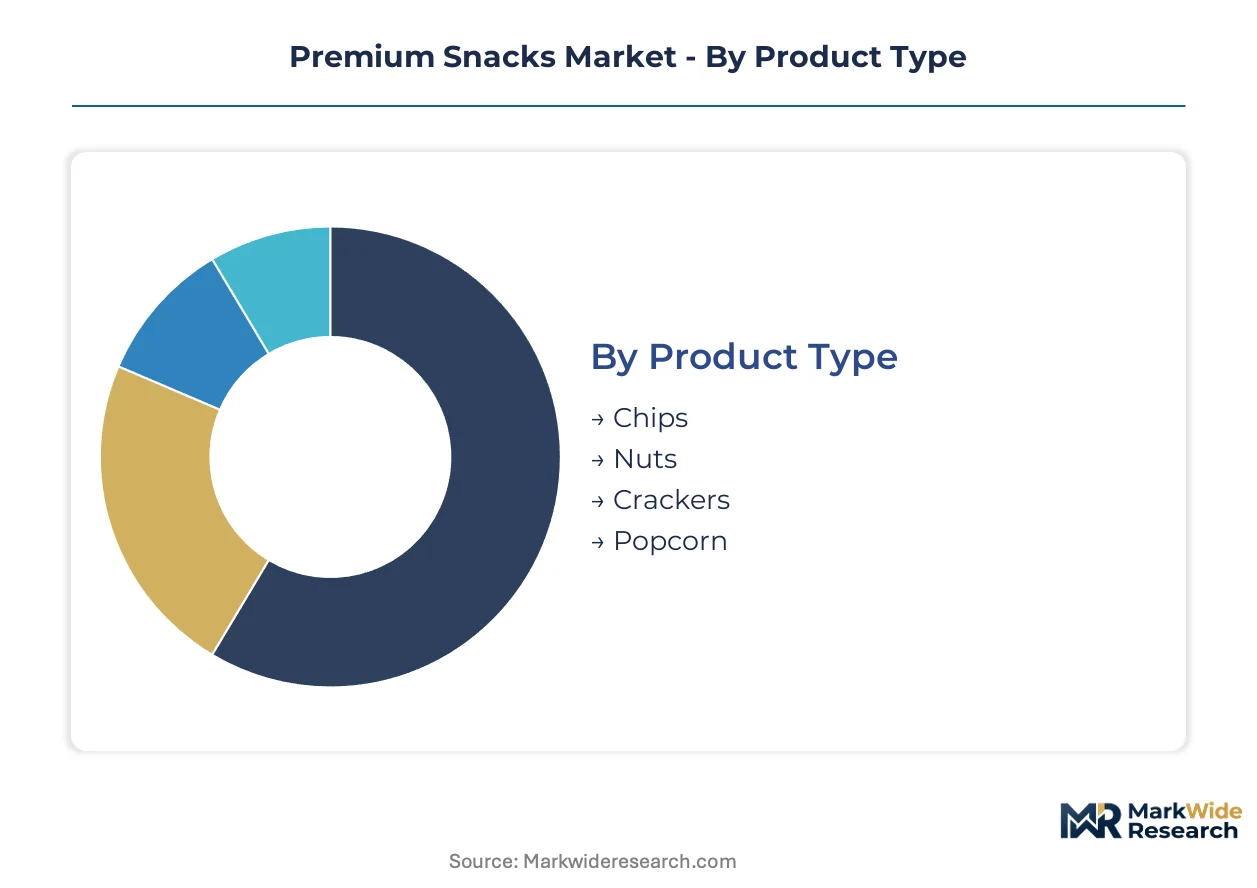
Premium snack manufacturers calibrate portfolio depth across four intersecting dimensions. Each segmentation layer carries distinct margin profiles, regulatory exposure, and shelf-space negotiation leverage that shapes capital allocation priorities.
Product Type:
Upgrade cycles accelerate where health credentials justify price premiums and processing complexity creates defensible positioning.
- Nuts:Almonds, cashews, and mixed varieties command the highest price tolerance through protein-density positioning and clean-label roasting methods. Demand concentrates in United States hospitality channels and Japanese gift-box retail, where portion-controlled formats satisfy wellness-oriented consumption rituals. California and Vietnam supply chains face climate-driven sourcing volatility.
- Popcorn:Air-popped and kettle-cooked variants leverage texture science to differentiate from commodity microwave alternatives. German and Dutch retail channels absorb the fastest volume growth as EFSA-validated whole-grain claims unlock premium placement. Compostable packaging mandates in the EU impose steep compliance costs on oil-heavy formulations.
- Chips:Kettle-cooked potato and vegetable root varieties compete on thickness and crisp retention.
- Crackers:Artisan fermentation and seed-inclusion recipes target charcuterie pairing occasions.
Volume placements concentrate in Nuts; the faster expansion belongs to Popcorn.
Flavor Profile:
Application context determines flavor investment intensity, with on-premise hospitality demanding more complex development cycles than retail impulse.
- Savory:Umami-forward formulations incorporating aged cheeses, miso, and fermented elements dominate United States craft brewery partnerships and Japanese izakaya channels. R&D intensity in yeast extract and hydrolyzed vegetable proteins separates premium positioning from commodity seasoning.
- Spicy:Capsaicin layering and regional pepper sourcing create geographic differentiation. Demand concentrates in Texas and California convenience retail, where Scoville-rated heat levels support trial-driven purchase behavior. FDA acidified food regulations constrain fermentation-based heat delivery methods.
- Sweet:Reduced-sugar fruit and chocolate inclusions target permissible indulgence positioning.
- Tangy:Vinegar-forward and citrus-acid profiles serve palate-cleansing functions in bar and restaurant settings.
Margin capture runs deepest in Savory; the steepest volume climb is occurring in Spicy.
Packaging Type:
Customer type dictates format selection, with subscription households prioritizing freshness extension over shelf visibility.
- Resealable Bags:Multi-layer laminates with oxygen scavengers and zipper mechanisms dominate United States pantry replenishment cycles. EU Green Deal mandates are accelerating biodegradable barrier film substitution, with German manufacturers absorbing the steepest reformulation costs. Zipper functionality failure rates directly impact subscription churn.
- Pouches:Stand-up formats with matte finishes and transparent windows support premium unboxing experiences in direct-to-consumer channels. Japanese beauty-inspired snack subscriptions favor minimalist pouch aesthetics that signal ingredient purity. REACH compliance for adhesives and inks constrains mid-tier supplier participation.
- Boxes:Rigid formats protect structural integrity for cracker and premium nut assortments.
- Cans:Metal formats preserve freshness for nut oil stability in warehouse club and hospitality bulk purchasing.
Subscription penetration concentrates in Resealable Bags; the format gaining share fastest is Pouches.
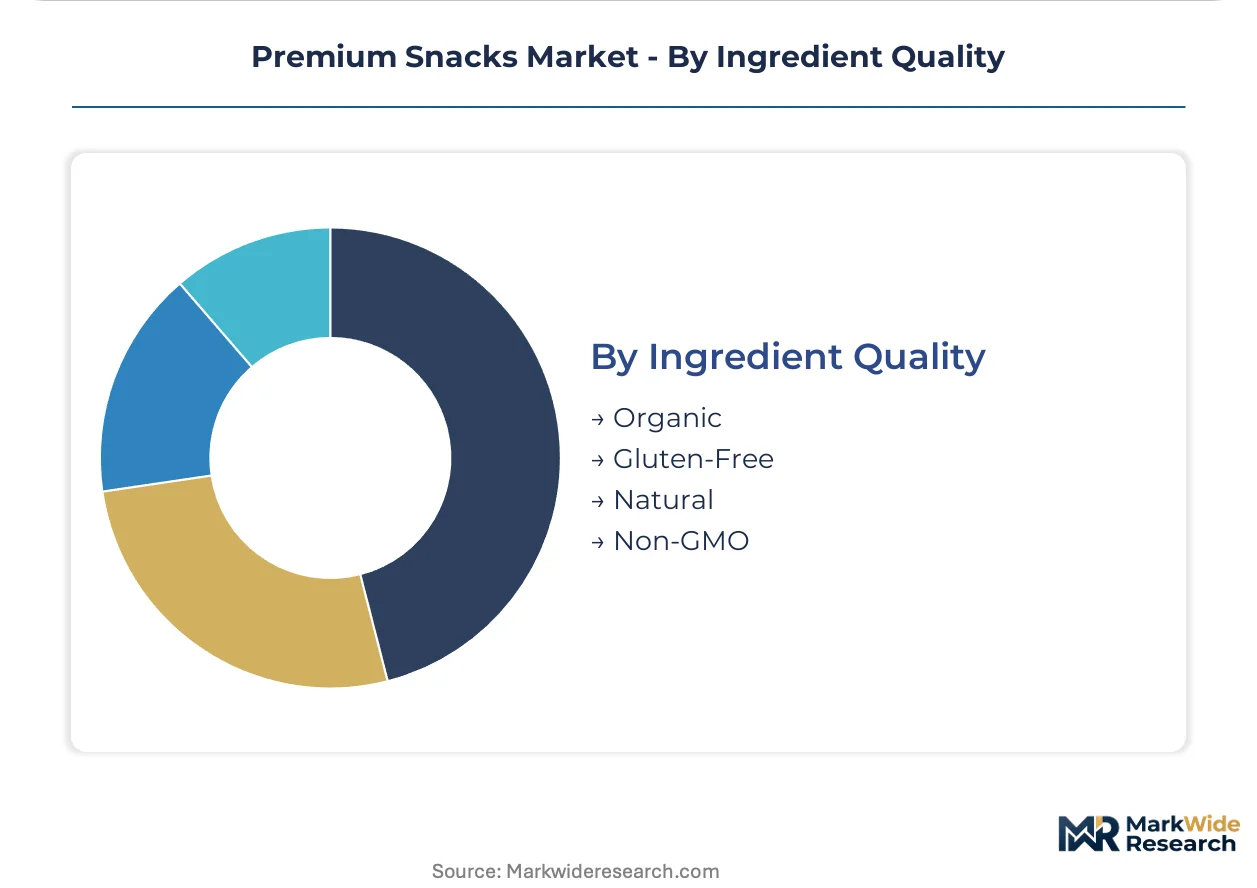
Ingredient Quality:
Supply concentration shapes cost tier stratification, with certified organic commanding the widest premium-to-commodity spread.
- Organic:USDA National Organic Program and EU Organic Regulation compliance requires three-year transition periods and segregated handling infrastructure. Demand concentrates in German bio-supermarkets and United States coastal metropolitan markets, where certification logos drive purchase decisions. Sourcing concentration in Turkey and California exposes margin structures to drought-driven supply shocks.
- Non-GMO:Non-GMO Project verification and EU GMO-free labeling create parallel certification tracks with overlapping but non-identical requirements. Japanese import channels increasingly require Non-GMO Project status for corn and soy-derived ingredients, compressing formulation flexibility for multinational portfolios.
- Gluten-Free:FDA gluten-free labeling rules and Codex Alimentarius standards govern permissible contamination thresholds.
- Natural:Absence of artificial colors, flavors, and preservatives without third-party certification carries the weakest pricing power.
Certification density concentrates in Organic; the quality tier climbing fastest is Non-GMO.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for premium snacks concentrates in the United States, Germany, and Japan, where mature snacking habits and elevated disposable incomes sustain premium price tolerance across retail and hospitality channels.
United States
Subscription-based replenishment purchasing and resealable pouch adoption dominate household procurement patterns. FDA nutrition labeling requirements and acidified food regulations constrain fermentation-based flavor innovation. California nut processors deploy high-pressure processing systems to extend clean-label shelf stability without preservative inclusion.
Germany
Bio-supermarket expansion and EFSA-validated whole-grain health claims accelerate popcorn segment volume growth. EU Green Deal packaging sustainability mandates and REACH compliance requirements impose steep reformulation costs on oil-heavy formulations. Bavarian supply chains absorb capital allocation toward biodegradable barrier film development.
Japan
Gift-box retail rituals and izakaya hospitality channels sustain demand for portion-controlled nut formats. METI standards and import requirements increasingly mandate Non-GMO Project verification for corn and soy-derived ingredients. Tokyo-based beauty-inspired snack subscriptions favor minimalist pouch aesthetics signaling ingredient purity.
United Kingdom
Craft brewery partnerships and charcuterie pairing occasions drive savory flavor profile demand across cracker and nut categories. FSA allergen labeling rules and post-Brexit divergence from EU organic regulations create parallel certification tracks. London metropolitan markets concentrate clean-label purchasing decisions around third-party certification logos.
Netherlands
EFSA health claim validation unlocks premium placement for functional ingredient positioning in Dutch retail channels. CSRD reporting requirements and extended producer responsibility frameworks accelerate sustainable packaging adoption. Rotterdam logistics hubs facilitate EU-wide distribution for compliant premium snack portfolios.
Premium Snacks Market Competitive Environment
United States producers anchor one tier; European specialists hold differentiated positioning through regulatory compliance infrastructure. The market structure consolidates around multinational conglomerates with global distribution networks and mid-tier regional players with ingredient traceability capabilities. Three archetypes dominate: scale-driven manufacturers with manufacturing footprint advantages, R&D-intensive innovators in texture and flavor science, and vertically integrated operators with captive ingredient sourcing. Competitive moves concentrate on strategic partnerships with consolidated retail chains and portfolio diversification into organic and non-GMO quality tiers.
Within the scale-driven tier, Nestlé and PepsiCo Inc. occupy positions defined by global distribution infrastructure and manufacturing scale. Mondelez International exemplifies the R&D-intensive archetype through its specialization in sensory differentiation. These three conglomerates anchor competitive dynamics by securing premium shelf-space allocation in consolidated convenience store chains and specialty grocer channels.
| Leading Market Players |
|---|
| Nestlé |
| Kellanov |
| PepsiCo Inc. |
| Conagra Brands, Inc. |
| General Mills Inc. |
| Mondelez International |
| Ferrero |
| Unilever |
| Mars, Inc. |
| Others |
Value Chain & Pricing Dynamics
Organic almond and cashew input costs from California and Vietnam flow through three distinct pricing tiers, with USDA National Organic Program certification commanding the widest spread over conventional grades. REACH compliance for biodegradable resealable films in German manufacturing clusters feeds cost absorption requirements back into premium pouch pricing, compressing mid-tier manufacturer participation.
Pricing Analysis
Volume placements concentrate in mass-market resealable bags while margin capture runs deepest in subscription-direct pouches with matte finishes and transparent windows. Price differentiation hinges on organic certification tier and EFSA-validated health claim status, with German bio-supermarkets absorbing the steepest premiums. Pricing pressure stems from climate-driven sourcing volatility in Turkish and California organic nut supply chains. Convenience retail chains exhibit the highest price sensitivity; Japanese gift-box and izakaya hospitality channels demonstrate the lowest.
Supply Chain Analysis
Reverse-logistics flows for expired organic inventory create working capital intensity, with California processors deploying high-pressure processing systems to extend shelf stability and reduce spoilage write-downs. Raw material sourcing draws from Vietnam for cashews, California for almonds, and Turkey for organic hazelnuts. Single-source vulnerability concentrates in California drought-exposed organic nut orchards. Distribution runs through consolidated convenience store chains in the United States, bio-supermarket networks in Germany, and direct-to-consumer subscription channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal packaging sustainability mandates and FDA clean-label enforcement intensity construct a cost-of-compliance barrier that favors incumbents with vertically integrated traceability systems and dedicated regulatory affairs infrastructure.
For Market Incumbents: Cement shelf-space allocation in consolidated convenience retail through exclusive resealable pouch format partnerships. Deepen backward integration into California and Vietnam organic nut sourcing to buffer climate-driven input volatility. Acquire specialized flavor science talent pools to defend R&D throughput against texture-innovation specialists.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting underpenetrated Japanese beauty-inspired snack segments with minimalist pouch aesthetics. Exploit white space in biodegradable barrier film technology for oil-heavy popcorn formulations facing EU compostability mandates. Prioritize EFSA health claim validation for functional ingredient positioning in Dutch retail channels.
For Investors and Strategic Acquirers: Biodegradable resealable film certification timelines extending beyond EU Green Deal compliance deadlines is the leading indicator that mid-tier manufacturers will face displacement pressure. Target vertically integrated operators with captive organic handling infrastructure and established FDA acidified food regulatory pathways. Monitor third-party organic verification backlog durations as the signal for working capital stress among new entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Barrier Film Certification | EU Green Deal mandates disqualify conventional multi-layer laminates from premium German retail placement. |
| Direct-to-Consumer Subscription Launch | Japanese beauty-inspired channels favor minimalist pouch aesthetics signaling ingredient purity. |
| High-Pressure Processing Deployment | California nut processors reduce spoilage write-downs while extending clean-label shelf stability. |
| EFSA Health Claim Validation | Dutch retail channels unlock premium placement for functional ingredient positioning in popcorn segments. |
| Organic Handling Infrastructure Investment | USDA National Organic Program compliance requires three-year transition periods and segregated supply chains. |
Study Parameters
Independent corroboration across primary interviews with category buyers at consolidated convenience chains, brand managers at multinational snack portfolios, and supply planners at California nut processors underwrites the qualitative findings. Secondary validation draws from FDA food contact substance filings, EFSA health claim registers, EU Green Deal packaging directive texts, and Nielsen retail audit data. Bottom-up segment sizing triangulates against top-down macroeconomic anchoring across the analysis window.
Comparable-period anchoring to mature premium snacking adoption patterns in the United States and Germany established the forecast baseline for projection horizon modeling. Segmentation dimensions span product type, flavor profile, packaging format, and ingredient quality tier, with regional regulatory cluster intensity as an additional premium snacks-specific dimension. CAGRs derive from trend extrapolation calibrated against historical volume penetration rates and subscription channel adoption curves.
Regulatory enforcement intensity shifts, climate-driven organic input supply shocks, and biodegradable film technology cost curves are the dominant revision risks to modeled outputs. Practitioners should monitor EU Green Deal implementation timelines, California drought severity indices, and industrial compostability certification backlogs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Qatar Potato Chips Market
Snacks
Global Snack Food Market
Snacks
Poland Snack Bar Market
Snacks
Spain Energy Bar Market
Snacks
Global Protein Snack Market
Snacks
Baked Savoury Snacks Market
Snacks
Salty Puffed Snacks Market
Snacks
Fat Free Meals and Snacks Market
Snacks
United States Popcorn Market
Snacks
Europe Nuts and Cereal Snacks Bar Market
Snacks
Oat-Based Snacks Market
Snacks
Nutritional Bar Market
Snacks
North America Pretzel Market
Snacks
Low Calorie Biscuits Market
Snacks
Dairy Protein Crisps Market
Snacks
Roasted Snacks Market