
 South America Cereal Bar Market | 2026-2036
South America Cereal Bar Market Size, Share, and Industry Trends Forecast 2026-2036
South America Cereal Bar Market Analytics
Subscription-based replenishment programs for cereal bars is pivoting how manufacturers monetize repeat consumption in South America. General Mills Inc. leverages its direct-to-consumer platform to secure recurring revenue streams in Brazilian metro areas. PepsiCo Inc. sustains wholesale club partnerships that anchor volume throughput across Argentina and Chile. The Kellogg Company competes through specialized sports-nutrition bundles targeting gym chain procurement officers.
A cereal bar is a baked or cold-pressed ready-to-eat snack composed of rolled oats, binding syrups, and functional additives such as whey protein or chicory root fiber, formed into a hand-held rectangular shape and packaged for ambient shelf stability. Granola bars occupy the mature volume base with established production infrastructure, while protein bars command premium shelf positioning and higher per-unit margins. Online retailers represent the fastest-growing distribution channel as logistics networks penetrate secondary cities, though supermarkets still control the majority of consumer touchpoints through end-cap placement and promotional cycles.
Brazil's national health surveillance agency ANVISA governs nutrition labeling and health claim substantiation, while Argentina's food code under its national administration for drugs, foods and medical technology restricts synthetic additive usage in products marketed to children. Mercosur's harmonized technical regulations for prepackaged foods create cross-border compliance obligations that favor manufacturers with centralized quality laboratories. Stakeholders must monitor evolving front-of-package warning label requirements that could reshape flavor formulation strategies and marketing claims across the region's largest economies.
Market Dynamics
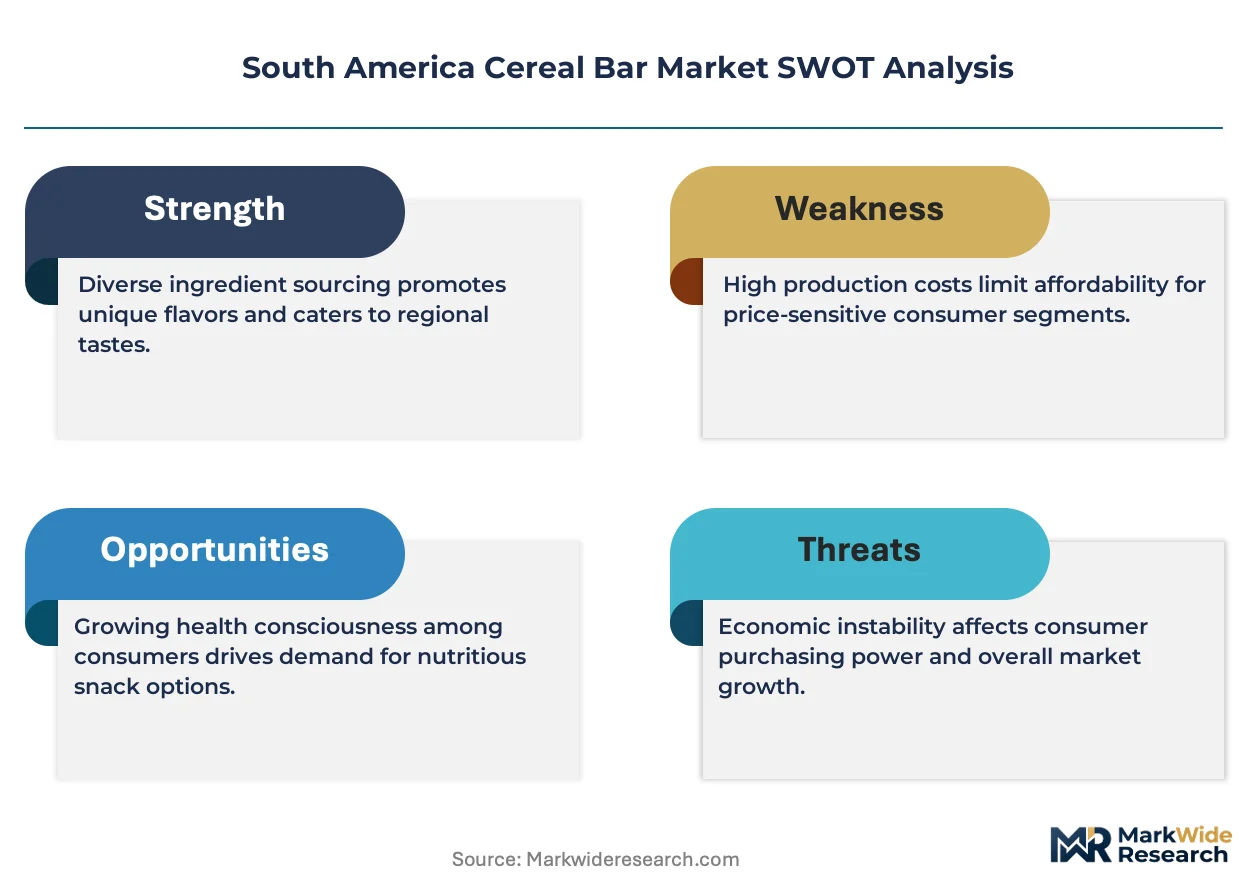
Clean-label ingredient mandates under Mercosur food safety protocols are forcing manufacturers to reformulate binding syrups and eliminate synthetic additives, compressing margin structures while creating compliance barriers for smaller producers across Brazil and Argentina.
Growth Catalysts
- Corporate wellness procurement:Gym chains and corporate cafeteria operators in São Paulo and Rio de Janeiro are integrating cereal bars into standardized snack portfolios, creating institutional demand anchors.
- ANVISA nutrition labeling modernization:Brazil's streamlined health claim substantiation pathways accelerate product registration timelines for functional variants targeting digestive wellness.
- Cold-pressed processing:Ambient-stable bar technologies reduce refrigeration requirements throughout distribution networks penetrating secondary cities.
Market Restraints
- Honey and tapioca syrup price volatility:Binding ingredient costs fluctuate with Brazilian agricultural output cycles, squeezing contract manufacturer margins.
- Import dependency for whey protein isolates:Argentina and Chile rely on concentrated Argentine dairy processing capacity, creating single-source vulnerability.
- Argentina's food code additive restrictions:Synthetic preservative prohibitions for children's marketed products limit shelf-life extension strategies.
Strategic Opportunities
- Colombian and Peruvian urban corridors:Bogotá and Lima metropolitan expansion lacks established cereal bar penetration relative to Brazilian benchmarks.
- Subscription direct-to-consumer platforms:Recurring replenishment models bypass traditional supermarket slotting fee structures.
- Chicory root fiber and prebiotic positioning:Digestive health claims align with ANVISA-approved functional ingredient categories.
Industry Challenges
- Food technologist specialization gaps:Formulation expertise in cold-pressed bar stability remains concentrated in São Paulo's technical institutes.
- Mercosur harmonization timeline friction:Cross-border technical regulation alignment delays centralized quality laboratory investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Cereal Bar Market |
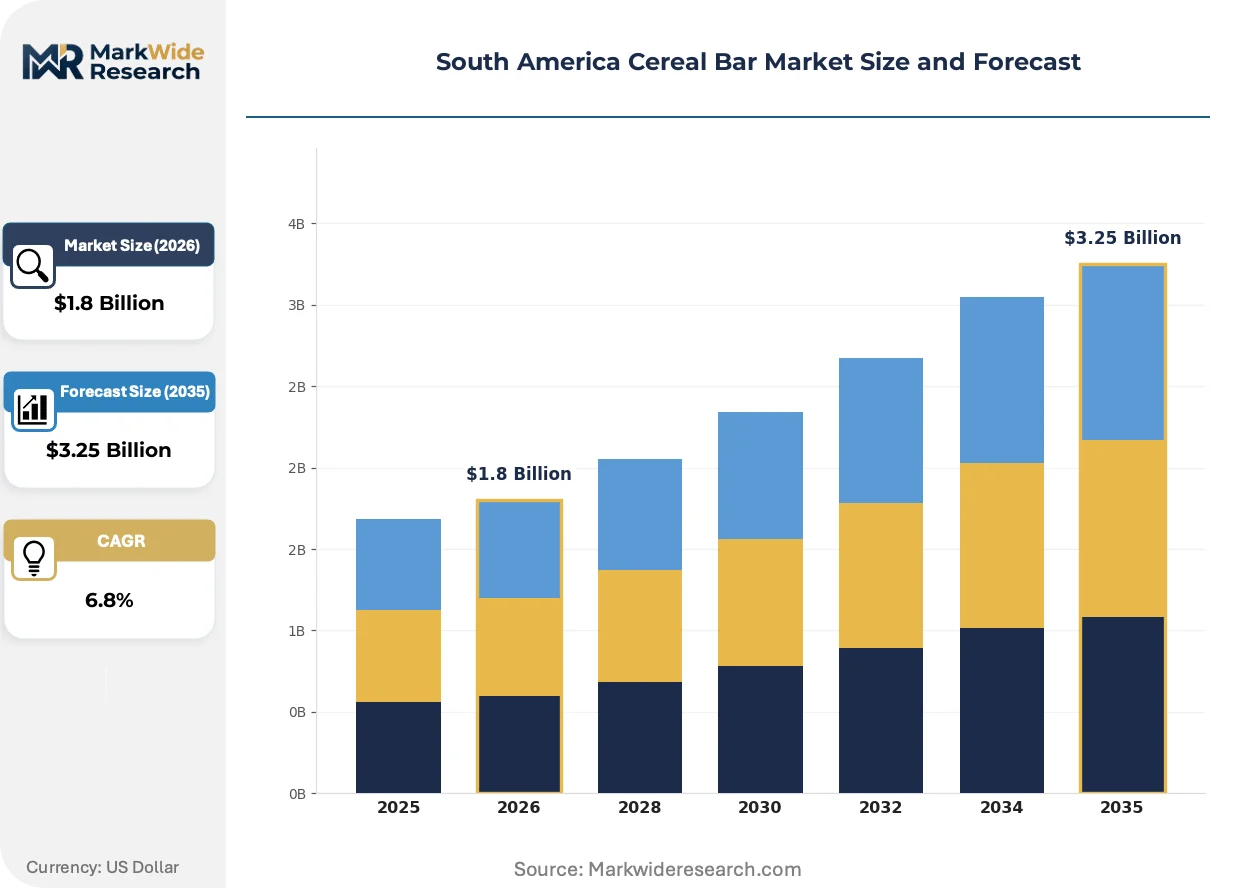
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut-Based, Granola, Protein, Fiber Distribution Channel: Supermarkets, Health Stores, Online Retailers, Convenience Stores Target Consumer: Health Conscious, Athletes, Busy Professionals, Students Flavor Profile: Chocolate, Berry, Peanut Butter, Coconut |
| Companies Covered | General Mills Inc., PepsiCo Inc., The Kellogg Company, Mondelez International, Nestle SA, Clif Bar & Company, Kind LLC, Post Holdings, Mars Inc., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Cereal Bar Market Evolving Landscape
Reformulation around clean-label binding systems and digital channel expansion are compressing traditional production and distribution hierarchies across the region's metropolitan corridors.
Chicory root fiber is expanding into premium bar formulations as a dual-function prebiotic and binding agent. Sports nutrition buyers in Brazilian gym chains are specifying this ingredient at accelerating rates. The technology is expanding into mass-market granola bars previously dependent on synthetic inulin.
Argentina's food code under its national administration for drugs, foods and medical technology is tightening synthetic additive prohibitions for youth-targeted packaging. Industrial consequence includes accelerated natural preservative R&D investments. Children's segment manufacturers are responding with accelerated clean-label certification timelines.
Urban consumers are consolidating purchases through mobile-enabled replenishment platforms. Supermarket end-cap placement faces displacement from direct-to-consumer subscription models. São Paulo's metropolitan corridor exhibits the most pronounced channel migration velocity.
South America Cereal Bar Market Segmentation
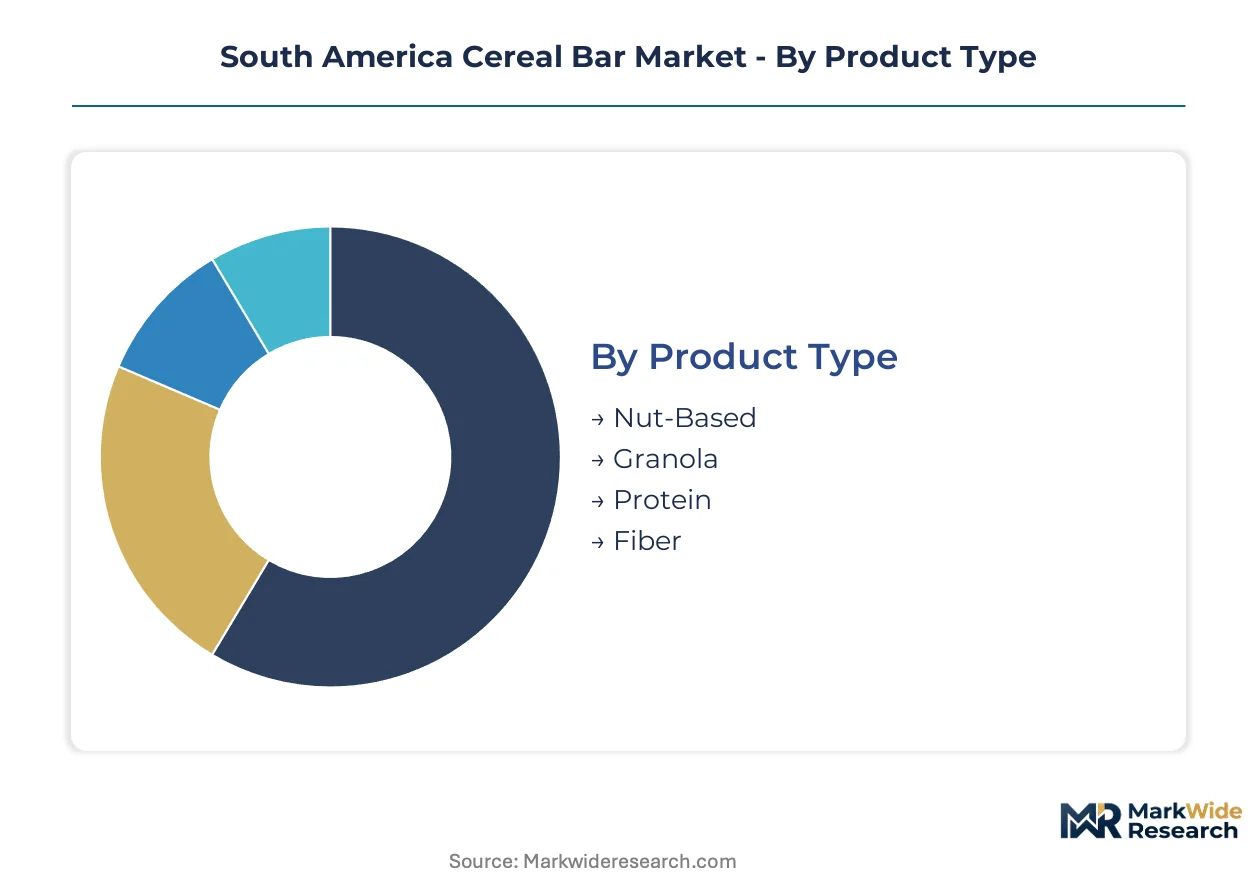
Product architecture in South America's cereal bar market concentrates manufacturing expertise around binding technologies and shelf-stability systems. Distinct formulation requirements across consumer occasions create specialized production lines with divergent margin profiles. Understanding segment boundaries reveals where capital deployment yields durable competitive positioning versus commoditized throughput.
Product Type:
Production gravity centers on São Paulo's industrial corridor, where cold-pressed and baked processing infrastructure cluster within shared supplier networks for chicory root fiber and tapioca syrup binding systems.
- Granola:Baked oat clusters bound with honey or tapioca syrup form the mature volume base. Brazilian supermarket chains in São Paulo's metropolitan corridor anchor procurement through promotional cycle commitments and end-cap placement fees.
- Protein:Whey protein isolate or plant-based concentrate formulations command premium shelf positioning. Gym chain procurement officers in Rio de Janeiro and Belo Horizonte specify these bars for institutional snack portfolios, creating demand anchors insulated from retail price competition.
- Nut-Based:Almond, cashew, and Brazil nut-dominant formulations target clean-label positioning under ANVISA nutrition labeling protocols.
- Fiber:Chicory root fiber and prebiotic inclusions align with digestive health claims approved through Brazil's streamlined registration pathways.
Today's leader: Granola. Tomorrow's challenger: Protein.
Distribution Channel:
Channel economics stratify sharply between high-touch retail slotting fees and digital-native customer acquisition costs, with margin structures diverging based on inventory velocity and promotional dependency.
- Supermarkets:Controlled by end-cap placement fees and promotional cycle commitments. São Paulo's metropolitan corridor exhibits concentrated buyer power among three dominant retail groups.
- Online Retailers:Logistics networks penetrating secondary cities enable direct-to-consumer replenishment models that bypass traditional slotting structures. Mobile-enabled platforms in Brazil's southeastern corridor show the most pronounced channel migration velocity.
- Health Stores:Curated shelf space favors certified clean-label and sports-nutrition positioning with trained staff recommendation influence.
- Convenience Stores:Impulse-driven velocity depends on ambient shelf stability and single-unit price points suited to cash transactions.
Supermarkets retain volume dominance. Online retailers expand most quickly.
Target Consumer:
Consumer occasion segmentation maps directly to protein loading requirements, portability needs, and price sensitivity thresholds across metropolitan employment corridors.
- Health Conscious:Clean-label ingredient scrutiny drives reformulation investments. ANVISA nutrition labeling modernization accelerates product registration for digestive wellness positioning.
- Athletes:Protein specification requirements from gym chain procurement officers in Brazil's southeastern corridor create institutional demand anchors with volume guarantees.
- Busy Professionals:Meal-replacement occasions favor high-fiber, moderate-protein formulations with extended satiety claims.
- Students:Price-sensitive trial driven by single-unit convenience store availability and social media-influenced flavor experimentation.
Athletes anchor premium pricing power. Health Conscious consumers drive reformulation investment cycles.
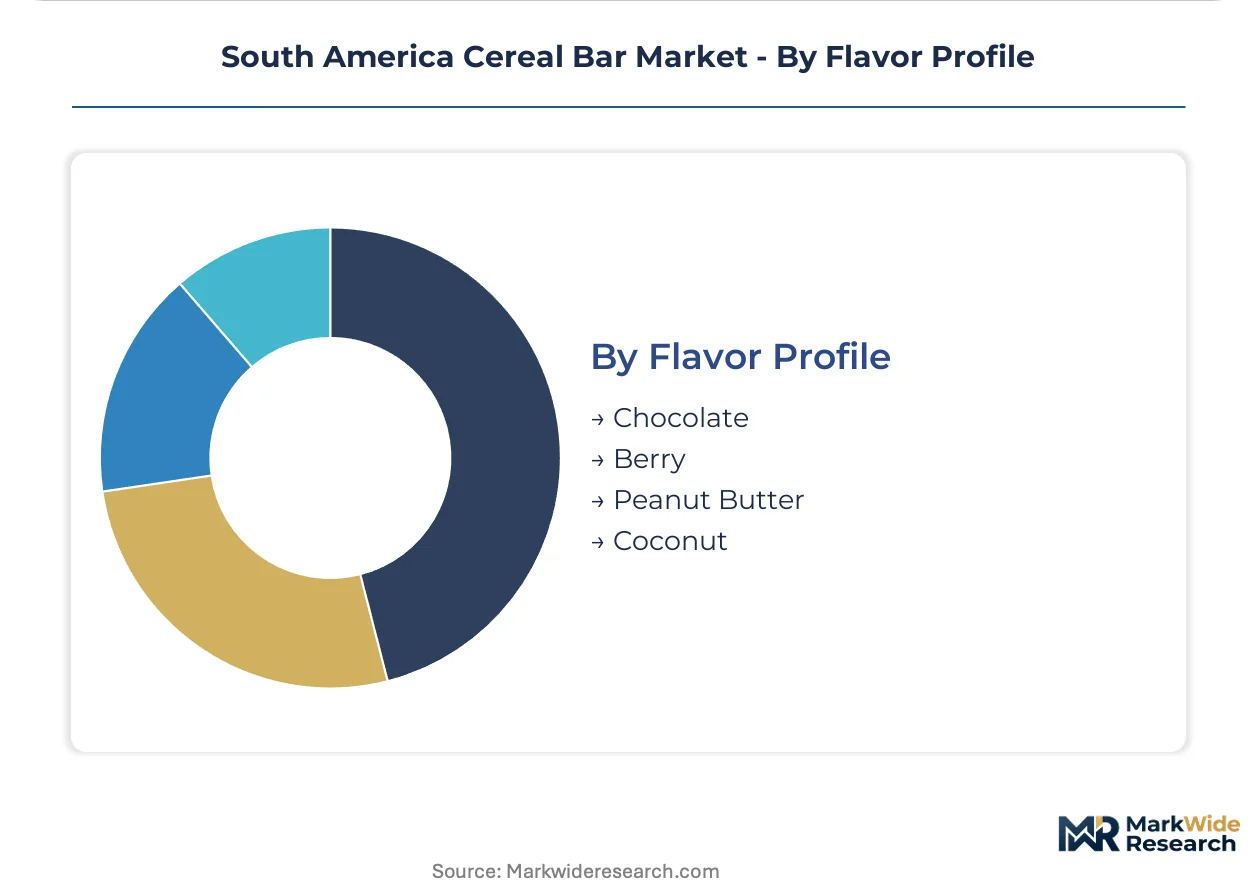
Flavor Profile:
Flavor development pipelines concentrate in São Paulo's technical institutes, where food technologist specialization in cold-pressed bar stability remains geographically concentrated.
- Chocolate:Cocoa-based coatings and inclusions dominate mass-market formulations. Brazilian agricultural output cycles for cocoa butter influence input cost volatility.
- Peanut Butter:Protein-bar staple with established supply chains from Argentine and Brazilian peanut processing capacity.
- Berry:Acai and native fruit inclusions target regional taste differentiation and antioxidant positioning claims.
- Coconut:Desiccated coconut and coconut oil binding systems align with clean-label fat source preferences.
Chocolate commands shelf presence. Berry formulations gain share fastest through regional taste differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands the dominant share of South America cereal bar consumption, while Argentina's regulatory environment shapes cross-border formulation standards through Mercosur harmonization pressures.
Brazil
Gym chain procurement officers in São Paulo and Rio de Janeiro institutionalize protein bar demand through corporate wellness contracts. ANVISA nutrition labeling modernization accelerates functional product registrations for digestive health positioning. São Paulo's southeastern metropolitan corridor clusters cold-pressed processing infrastructure and food technologist specialization.
Argentina
Corporate cafeteria operators in Buenos Aires anchor granola bar volume through standardized snack portfolio commitments. The national administration for drugs, foods and medical technology restricts synthetic additives in youth-marketed products, forcing natural preservative R&D. Córdoba's food processing belt concentrates contract manufacturing capacity for Mercosur export compliance.
Chile
Health-conscious consumers in Santiago's metropolitan region drive premium nut-based bar adoption through pharmacy and health store channels. The country's national health regulator enforces front-of-package warning label requirements that reshape flavor formulation strategies. Valparaíso's logistics hub enables cold-pressed bar distribution to secondary cities with reduced refrigeration requirements.
Colombia
Bogotá's urban corridor exhibits underpenetrated cereal bar adoption relative to Brazilian benchmarks, creating whitespace for subscription-based replenishment models. The national food and drug surveillance institute governs import registration timelines for whey protein isolate formulations. Medellín's emerging food tech cluster attracts regional headquarters for direct-to-consumer platform expansion.
Peru
Lima's metropolitan expansion lacks established cereal bar infrastructure, presenting first-mover opportunities for clean-label positioning. The national health authority's prepackaged food regulations align with Mercosur technical standards, easing cross-border product registration. Callao's port facilities concentrate import logistics for binding syrup ingredients from Brazilian agricultural suppliers.
South America Cereal Bar Market Competitive Landscape
Top-tier vendors anchor supermarket and gym chain procurement, while mid-tier specialists occupy health store and digital-native channels. The market structure reflects consolidated multinational presence alongside regional private-label fabricators. Three archetypes dominate: sports-nutrition bundlers, clean-label certification specialists, and direct-to-consumer platform operators. Capacity expansion and subscription infrastructure deployment constitute the dominant competitive moves across the analysis window.
Within the multinational tier, General Mills Inc., PepsiCo Inc., and The Kellogg Company exemplify divergent channel strategies. General Mills Inc. represents the direct-to-consumer platform archetype through recurring replenishment models in Brazilian metro areas. PepsiCo Inc. anchors wholesale club partnership structures across Argentina and Chile. The Kellogg Company occupies the sports-nutrition bundling position targeting gym chain procurement officers. These three entities collectively illustrate how scale, channel control, and institutional contract capture define competitive positioning in South America's cereal bar market.
| Leading Market Players |
|---|
| General Mills Inc. |
| PepsiCo Inc. |
| The Kellogg Company |
| Mondelez International |
| Nestle SA |
| Clif Bar & Company |
| Kind LLC |
| Post Holdings |
| Mars Inc. |
| Others |
Value Network & Pricing Analysis
Gym chain procurement officers in Brazil's southeastern corridor are mandating extended ambient shelf stability specifications, forcing contract manufacturers to source natural preservative systems and cold-pressed processing equipment that compress margin structures across the value chain.
Pricing Analysis
Capacity additions in São Paulo's cold-pressed processing corridor are reshaping price floors for premium protein bars. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade under ANVISA protocols and volume scale commitments from institutional buyers. Cost compression in the granola tier is intensifying because honey and tapioca syrup costs fluctuate with Brazilian agricultural cycles. Students purchasing single units at convenience stores exhibit highest price sensitivity, while gym chain procurement officers anchor premium tier demand with volume guarantees.
Supply Chain Analysis
Return flows of expired inventory from supermarket end-cap placements create reverse-logistics complexity for binding syrup reformulations. Raw material sourcing concentrates in Brazil, Argentina, and Chile, with whey protein isolate dependencies drawing from concentrated Argentine dairy processing capacity. Supply chain risk centers on single-source vulnerability for chicory root fiber imports. Distribution runs through supermarket retail groups in São Paulo's metropolitan corridor, with direct-to-consumer platforms bypassing traditional slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story: health-conscious urban consumers are consolidating purchases around clean-label certification and digestive wellness positioning, elevating premium specifications above commodity granola throughput.
For Market Incumbents: Acquire cold-pressed processing capacity in São Paulo's technical corridor to secure formulation expertise scarcity. Deepen backward integration into tapioca syrup supply from Brazilian agricultural suppliers to defend against honey price volatility. Anchor institutional contracts with gym chain procurement officers before subscription platforms displace supermarket slotting dominance. For New Entrants and Emerging Players: Cold-pressed bar stabilization technology offers a technology-first wedge against baked granola incumbents. Target Bogotá and Lima metropolitan corridors where cereal bar penetration lags Brazilian benchmarks. Launch direct-to-consumer replenishment platforms with mobile-enabled ordering to bypass established retail gatekeepers. For Investors and Strategic Acquirers: Asymmetric upside sits with clean-label certification specialists holding ANVISA-approved functional ingredient registrations. Five-to-ten year viability favors manufacturers with centralized quality laboratories serving Mercosur cross-border compliance. Monitor front-of-package warning label regulatory developments in Chile and Argentina as inflection indicators for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Subscription replenishment models bypass São Paulo supermarket slotting fees and anchor recurring revenue. |
| Clean-Label Certification Investment | ANVISA-approved prebiotic positioning accelerates product registration timelines for digestive wellness claims. |
| Cold-Pressed Processing Capacity Expansion | Ambient-stable bar technologies reduce refrigeration costs throughout distribution networks penetrating secondary cities. |
| Backward Integration into Binding Syrups | Captive supply of tapioca syrup from Brazilian agricultural sources hedges against honey price volatility. |
| Regional Headquarters Establishment | Medellín and Lima emerging food tech clusters enable first-mover positioning in underpenetrated Andean corridors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with gym chain procurement officers, ANVISA regulatory affairs specialists, supermarket category buyers, cold-pressed processing equipment vendors, and contract manufacturing plant managers with secondary validation through customs records, Nielsen retail audit data, Mercosur technical regulation filings, and food processing trade association reports. Bottom-up facility capacity assessments and top-down consumption estimates were triangulated to anchor volume figures.
Segment-weighting approaches modeled product type, distribution channel, target consumer occasion, and flavor profile dimensions across the analysis window. CAGRs were derived from fitted growth curves applied to granular segment trajectories. Forecast inputs incorporated ANVISA registration pathway timelines, gym chain expansion pipelines, and cold-pressed equipment installation schedules.
The model holds under stable Mercosur harmonization timelines and continued ANVISA streamlining of functional claim substantiation; deviation in front-of-package warning label enforcement or binding ingredient agricultural output shocks would shift trajectory. Practitioners should monitor regulatory developments in Chile's national health regulator and Argentine food code amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Europe Frozen Snacks Market
Snacks
Low Calorie Crackers Market
Snacks
North America Fruit Snacks Market
Snacks
Allergy-Free Snacks Market
Snacks
Tortilla Mix Market
Snacks
UK Snack Market
Snacks
Fat Free Snacks Market
Snacks
Snacks Market
Snacks
On-The-Go Healthy Snacks Market
Snacks
Marshmallow Market
Snacks
Premium Snacks Market
Snacks
Savory Snack Products Market
Snacks
Low-Calorie Savoury Snacks Market
Snacks
United Arab Emirates Energy Bar Market
Snacks
Healthy Fat-Free Snacks Market
Snacks
North America Savory Snacks Market