
 North America Energy Bar Market | 2026-2036
North America Energy Bar Market Size, Share, and Industry Trends Forecast 2026-2036
North America Energy Bar Market Analytics
A shift from outsourced co-manufacturing toward captive production is repositioning supply economics for major brands in the North America energy bar sector. Mars Incorporated leverages its extensive confectionery infrastructure to sustain manufacturing scale across multiple North American facilities. Clif Bar & Company anchors its competitive stance through deep organic supply chain relationships and employee-owned governance. PROBAR LLC specializes in plant-forward formulations that occupy a defensible premium niche against mass-market competitors.
North America energy bars are shelf-stable, nutrient-dense food products typically formulated with protein isolates, whole grains, nuts, and binding syrups, manufactured through cold-press extrusion or baked slab-and-cut processes, designed to deliver portable macronutrient replenishment for active consumers. Protein bars dominate current value generation due to entrenched gym-channel penetration and sports nutrition crossover appeal, while low-carb bars represent the fastest-expanding product type as ketogenic and glycemic-management diets gain adherence among health-conscious individuals. The ingredient dimension centered on nuts and seeds commands superior margin pools because of clean-label positioning and perceived functional density.
The FDA governs nutrition labeling and health claim substantiation for energy bars sold across the United States, while Health Canada and the PMRA enforce compositional standards and ingredient safety for the Canadian market, collectively elevating barrier costs for new entrants and rewarding incumbents with established regulatory affairs capabilities. USDA organic certification and Non-GMO Project verification function as de facto market access requirements for premium shelf placement in specialty retail channels. Stakeholders must monitor evolving positions on added-sugar thresholds and protein content claims across both national jurisdictions to anticipate reformulation cycles and portfolio rebalancing needs.
Market Dynamics
The North America energy bar sector is restructuring around captive manufacturing investments as major brands abandon co-manufacturing relationships to secure margin control and formulation confidentiality. This shift compresses third-party production capacity while elevating capital intensity thresholds for market participation.
Growth Catalysts
- Post-Workout Nutrition Professionalization:Fitness enthusiasts are systematizing recovery protocols, creating predictable demand cycles for protein-dense formulations across gym and specialty retail channels.
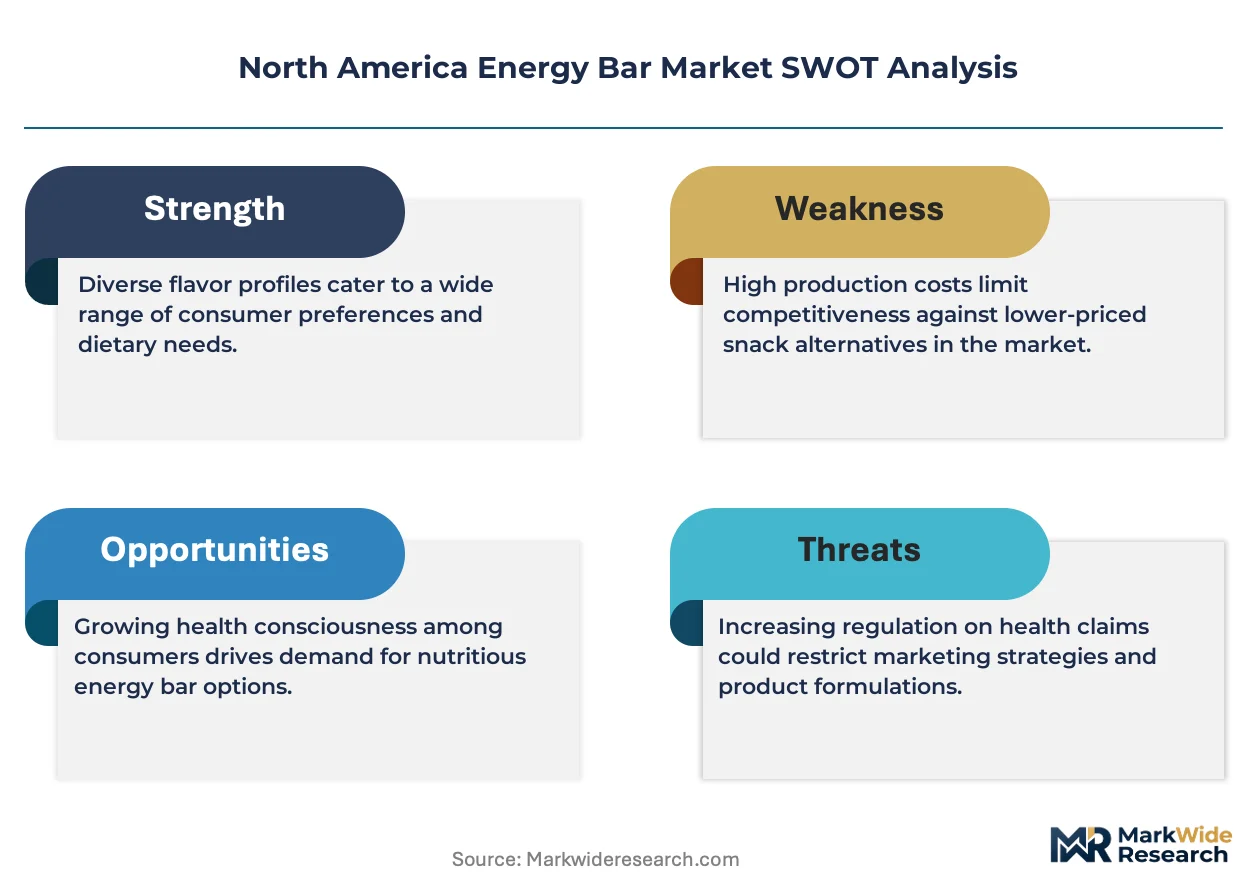
- FDA Added-Sugar Labeling Mandates:The updated Nutrition Facts requirements are accelerating reformulation toward low-glycemic binding agents and alternative sweeteners in premium product lines.
- California Retail Infrastructure Density:The state's concentration of health-conscious consumers and specialty grocery networks generates disproportionate revenue per capita for clean-label energy bar launches.
Market Restraints
- Organic Supply Concentration:USDA-certified ingredient sourcing clusters in specific agricultural regions, exposing brands to climate-driven crop volatility and procurement bottlenecks.
- Almond and Nut Input Cost Volatility:Water scarcity pressures in California's Central Valley generate recurring price instability for core protein and fat sources.
- Clean-Label Technical Limitations:Eliminating synthetic preservatives compresses shelf-life windows, constraining distribution reach and inventory turnover economics.
Strategic Opportunities
- Ketogenic Diet Adherence Expansion:Low-carb bar formulations are capturing glycemic-management consumers underserved by traditional high-carbohydrate energy products.
- Direct-to-Consumer Channel Development:Subscription models and brand-owned e-commerce platforms are bypassing slotting fee pressures from conventional retail consolidation.
- Canadian Market Underpenetration:Health Canada's distinct compositional standards create first-mover advantages for brands investing in dual-jurisdiction regulatory affairs capabilities.
Industry Challenges
- Dual-Jurisdiction Compliance Talent Scarcity:Simultaneous FDA and Health Canada navigation requires specialized regulatory affairs professionals in short supply across the food sector.
- Cold-Press Equipment Capex Intensity:In-house extrusion infrastructure demands seven-figure capital commitments that strain mid-tier brand balance sheets.
- Non-GMO Verification Timeline Compression:Supply chain documentation requirements for Project verification are extending new product development cycles by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Energy Bar Market |
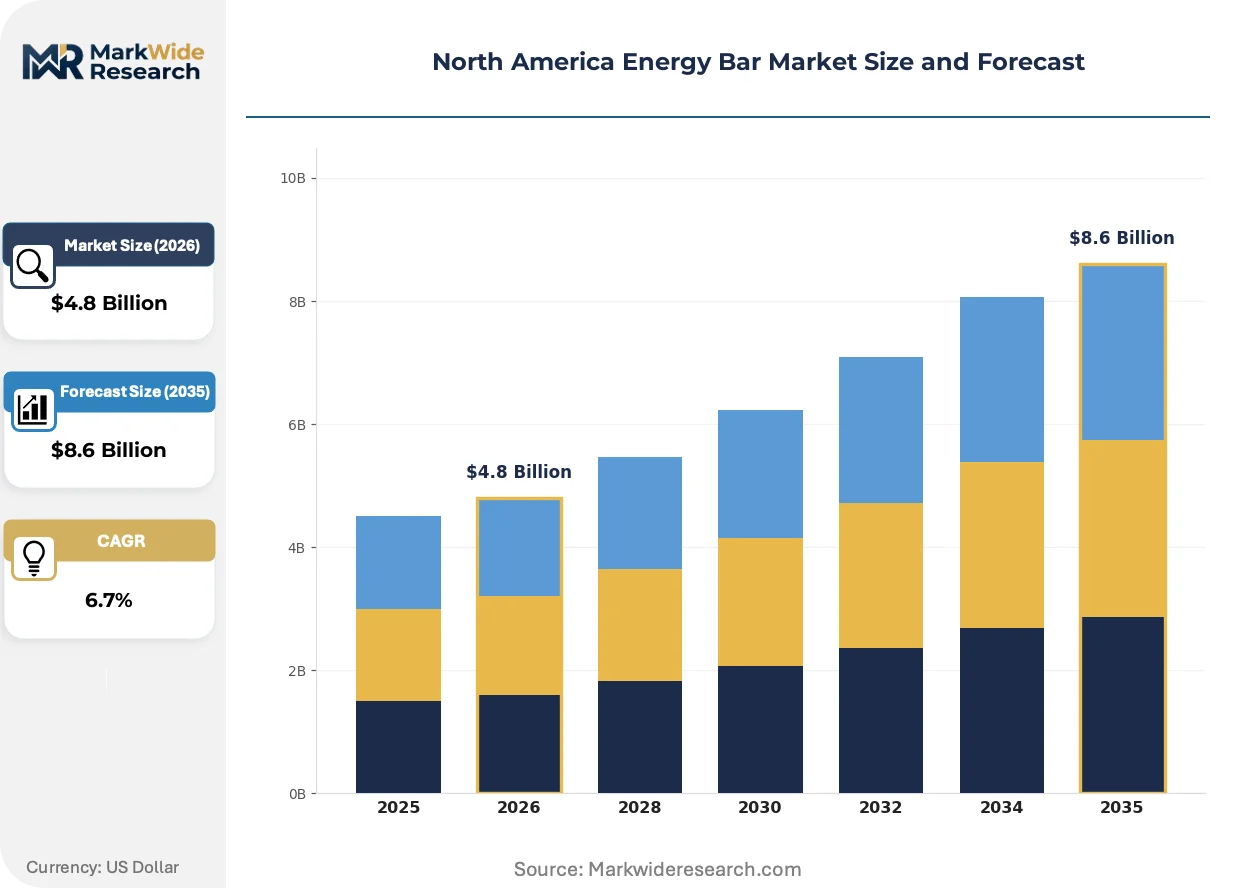
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Granola Bars, Low-Carb Bars, Meal Replacement Bars Ingredient Type: Nuts, Fruits, Grains, Seeds Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Convenience Stores Target Consumer: Fitness Enthusiasts, Busy Professionals, Students, Health-Conscious Individuals |
| Companies Covered | Mars Incorporated, Post Holdings Inc, General Mills Inc, PepsiCo Inc, PROBAR LLC, Mondelez International Inc, Clif Bar & Company, Nestlé SA, The Kellogg Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Energy Bar Market Evolving Landscape
Formulation science and supply chain transparency are converging to redefine competitive differentiation in North American energy bars. Brands now compete on ingredient provenance and processing integrity rather than macronutrient ratios alone.
Plant-protein extrusion technology is absorbing significant R&D investment as brands seek to replicate the texture and shelf stability of whey-based formulations without dairy inputs. Clean-label adopters in the premium segment are driving adoption curves faster than equipment suppliers can scale capacity. This absorption dynamic is compressing margins for brands caught between consumer expectations and processing limitations.
The FDA's updated Nutrition Facts labeling requirements for added sugars are forcing disclosure granularity that exposes previously hidden sweetener loads. Reformulation cycles have accelerated across mass-market portfolios as brands scramble to maintain permissible health claims. Protein bars positioned for sports nutrition crossover appeal face the steepest compliance costs due to existing binding syrup dependencies.
Subscription-based replenishment models are displacing conventional retail replenishment for core fitness enthusiasts who prioritize convenience and personalization. Direct channels capture higher lifetime value while reducing slotting fee exposure to consolidated grocery networks. This shift concentrates most visibly in California and Pacific Northwest metropolitan corridors where digital-native purchasing patterns dominate.
North America Energy Bar Market Segmentation
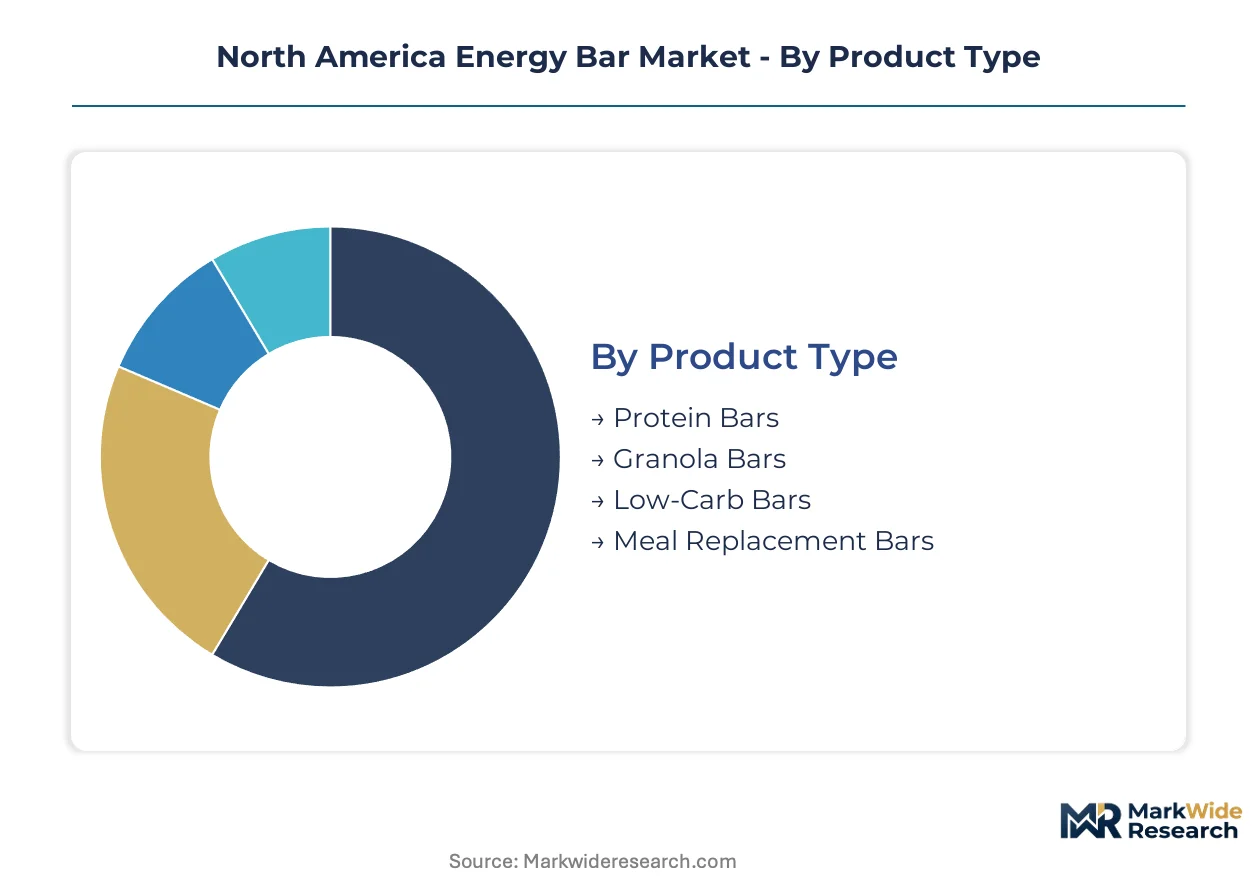
Energy bar purchasing patterns diverge sharply across usage occasions, ingredient preferences, and channel access. Manufacturers must align formulation architecture and distribution investments with distinct consumer workflows rather than treating the category as uniform.
Product Type:
Buyers in this category separate by macronutrient priority and consumption timing relative to physical activity.
- Protein Bars:Formulated with whey, casein, or plant isolates delivering 15-25g protein per serving, these products dominate gym-channel replenishment cycles. Demand concentrates among post-workout recovery protocols in California and Texas metropolitan fitness ecosystems, where subscription-based auto-replenishment is displacing retail purchase.
- Low-Carb Bars:Engineered with alternative sweeteners and fiber matrices to maintain sub-5g net carbohydrate profiles, these formulations serve ketogenic and glycemic-management protocols. Adherence expansion among prediabetic consumers in Florida and Arizona is accelerating faster than equipment suppliers can scale extrusion capacity.
- Granola Bars:Whole-grain and oat-based formulations with moderate protein content, positioned for portable breakfast replacement and school lunch compliance.
- Meal Replacement Bars:Calorie-dense formulations with micronutrient fortification targeting time-constrained professionals seeking complete nutrition in single servings.
Protein bars lead volumes today; low-carb bars are climbing the fastest.
Ingredient Type:
Raw material sourcing geography and clean-label positioning drive margin stratification across this dimension.
- Nuts:Almonds, peanuts, and cashews provide protein density and textural binding, with California Central Valley sourcing exposing brands to water-scarcity price volatility. Premium positioning depends on USDA organic certification and Non-GMO Project verification as baseline retail access requirements.
- Seeds:Chia, hemp, and pumpkin seeds deliver omega fatty acid profiles and allergen-friendly alternatives to tree nuts. Pacific Northwest cultivation clusters and Canadian prairie production are expanding fastest as brands diversify beyond almond dependency.
- Fruits:Dried berries, dates, and fruit purees supply binding sweetness and antioxidant positioning, with sourcing concentrated in Washington State and British Columbia.
- Grains:Oats, quinoa, and ancient grain flours provide structural integrity and fiber content, with organic supply contracting in the Upper Midwest and Prairie provinces.
Nuts anchor current revenue pools; seeds are expanding most quickly as allergen-conscious formulation spreads.
Distribution Channel:
Channel selection reflects consumer urgency, basket composition, and price sensitivity gradients.
- Online Retail:Direct-to-consumer platforms and marketplace presence capture subscription-driven replenishment with superior lifetime value economics. Fitness enthusiasts in Seattle, Denver, and Austin metro corridors drive disproportionate digital-native purchasing concentration.
- Specialty Stores:Natural grocers and sports nutrition boutiques deliver clean-label credibility and staff-curated assortment for ingredient-provenance-focused buyers. California's specialty retail infrastructure density outpaces all other North American jurisdictions.
- Supermarkets:Conventional grocery slotting fees compress margins but deliver mass-market penetration for established brands with formulation confidentiality secured through captive manufacturing.
- Convenience Stores:Impulse-oriented single-serve placement targets travel and emergency replenishment occasions with limited SKU breadth.
Specialty stores generate highest per-SKU margins today; online retail is gaining share fastest.
Target Consumer:
Life-stage constraints and health identity formation separate buyers by usage occasion predictability.
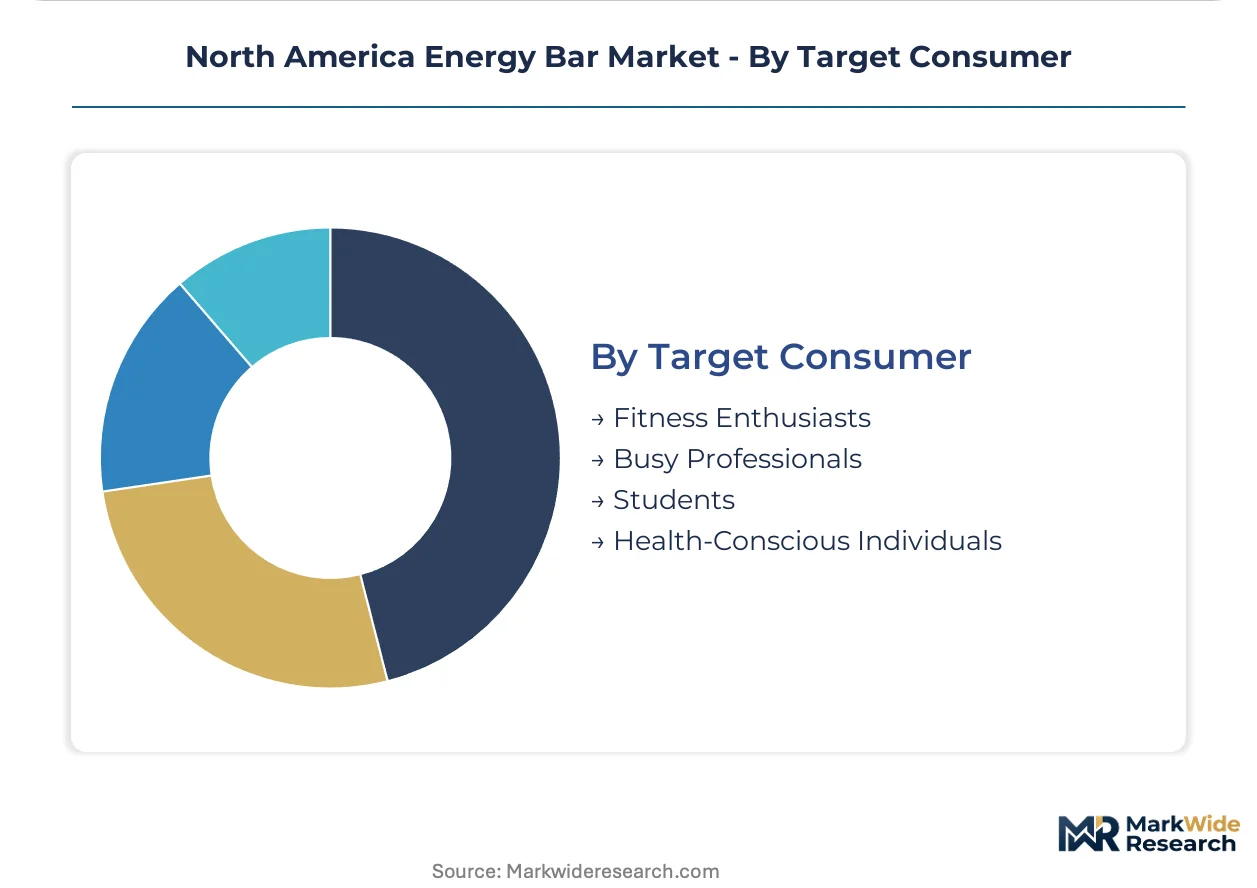
- Fitness Enthusiasts:Systematized training protocols create predictable demand cycles for protein-dense formulations with transparent amino acid profiles. Post-workout nutrition professionalization among CrossFit and endurance communities in Colorado and Southern California is restructuring product development priorities.
- Health-Conscious Individuals:Preventive wellness orientation drives clean-label scrutiny and ingredient provenance verification across all purchase occasions. FDA added-sugar labeling disclosure granularity is accelerating reformulation toward low-glycemic alternatives for this segment.
- Busy Professionals:Time compression and travel intensity favor meal replacement formats with complete micronutrient coverage and extended shelf stability.
- Students:Price sensitivity and portability requirements concentrate demand in granola and lower-protein formats through campus retail and convenience channels.
Fitness enthusiasts anchor volume concentration today; health-conscious individuals are expanding most quickly as preventive wellness protocols mainstream.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as brands evaluate FDA compliance costs against Health Canada standards. The United States anchors formulation innovation while Canada offers procurement advantages for organic ingredient sourcing. Mexico emerges as a nearshoring alternative for extrusion equipment manufacturing serving North American captive facilities.
United States
FDA added-sugar labeling mandates are accelerating reformulation cycles across California and Texas fitness corridors. The agency's disclosure granularity for binding syrups forces portfolio rebalancing toward low-glycemic alternatives. Los Angeles and Austin metropolitan clusters concentrate subscription-based direct-to-consumer launches for protein-dense formulations.
Canada
Health Canada compositional standards create first-mover advantages for brands investing in dual-jurisdiction regulatory affairs capabilities. The PMRA enforces ingredient safety thresholds that diverge from FDA approaches, elevating specialized compliance talent demand. British Columbia's specialty retail infrastructure and Prairie provinces' organic grain sourcing anchor clean-label supply chains.
California
Water scarcity pressures in the Central Valley generate recurring price instability for almond-dependent formulations. State-level clean-label consumer density outpaces all other North American jurisdictions, driving premium SKU proliferation. San Francisco and San Diego metro corridors host the densest concentration of plant-protein extrusion R&D facilities.
Texas
Post-workout nutrition professionalization among CrossFit communities creates predictable demand cycles for transparent amino acid profiles. The state's business-friendly regulatory environment attracts captive manufacturing investments from brands exiting co-manufacturing relationships. Dallas and Houston fitness ecosystems drive disproportionate protein bar volume through gym-channel penetration.
Pacific Northwest
Seattle and Denver digital-native purchasing patterns concentrate subscription-based replenishment model adoption. Washington State berry sourcing and Oregon hemp cultivation diversify ingredient portfolios beyond California almond dependency. The region's outdoor recreation culture sustains demand for portable macronutrient replenishment across endurance athlete segments.
North America Energy Bar Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue plant-forward premium positioning against mass-market incumbents. The sector exhibits tiered concentration with confectionery conglomerates leveraging captive manufacturing scale while employee-owned specialists defend organic supply chain relationships. Three archetypes dominate: diversified food conglomerates with confectionery infrastructure, mission-driven organic specialists, and plant-protein-focused premium challengers. Competitive moves center on backward integration into extrusion equipment ownership and direct-to-consumer channel development to bypass retail slotting fee compression.
Within the diversified conglomerate tier, Mars Incorporated and Mondelez International occupy positions anchored by extensive North American manufacturing footprints. Clif Bar & Company exemplifies the employee-owned organic specialist archetype through deep supply chain relationships. PROBAR LLC represents the plant-forward premium challenger segment with defensible niche positioning against mass-market competitors.
| Leading Market Players |
|---|
| Mars Incorporated |
| Post Holdings Inc |
| General Mills Inc |
| PepsiCo Inc |
| PROBAR LLC |
| Mondelez International Inc |
| Clif Bar & Company |
| Nestlé SA |
| The Kellogg Company |
| Others |
Value Network & Pricing Analysis
Plant-protein extrusion specialists in the Pacific Northwest command wage premiums that compress mid-tier margins while amplifying spreads between premium clean-label and economy formulations. This labor-cost differential reinforces the three-tier pricing structure across premium, standard, and economy levels as brands absorb technical talent scarcity into tier positioning.
Pricing Analysis
Retailer slotting fee compression drives margin restructuring across conventional grocery channels, forcing brands toward direct-to-consumer subscription models. Price differentiation hinges on USDA organic certification tier and captive manufacturing scale, with economy SKUs facing intensifying cost compression from almond input volatility. Fitness enthusiasts demonstrate lowest price sensitivity through subscription lock-in, while student segments concentrate demand in promotional-dependent convenience channels.
Supply Chain Analysis
Domestic-content preferences for North American-sourced protein isolates are reshaping procurement patterns away from Asian soy concentrate dependencies. Supply concentrates in California almonds, Canadian prairie grains, and Pacific Northwest berries, with extrusion equipment manufacturing increasingly nearshored to Mexico. Tariff exposure on Chinese packaging materials and binding syrup derivatives amplifies reformulation urgency. Distribution runs through consolidated specialty retail networks in California, direct-to-consumer platforms in Seattle and Denver, and mass-market grocery slotting agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market rest on captive manufacturing adoption and premium-tier clean-label repositioning, with almond-cost volatility creating cost-down urgency for backward-integrated operators.
For Market Incumbents: Deepen captive extrusion infrastructure ownership to secure formulation confidentiality against co-manufacturing leakage risks. Expand organic supply contracting in Canadian prairie grain regions to diversify beyond California water-scarcity exposure. Prioritize dual-jurisdiction FDA and Health Canada regulatory affairs capability as a defensive moat against mid-tier challengers. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting Texas CrossFit ecosystems and Pacific Northwest endurance athlete segments. Exploit Health Canada compositional standard gaps as first-mover white space against US-centric incumbents. Emphasize plant-protein extrusion R&D partnerships with San Diego and San Francisco metro facilities to bypass equipment capex barriers. For Investors and Strategic Acquirers: Confectionery conglomerates with dormant North American manufacturing footprints are the most active acquirer in this space, seeking clean-label capability adjacencies. Long-term viability favors targets with secured organic supply relationships and established Non-GMO Project verification pipelines. Monitor FDA added-sugar enforcement granularity as the key inflection signal for reformulation-cycle winners.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Manufacturing Investment | Mars Incorporated leverages confectionery infrastructure to secure margin control against co-manufacturing dependency. |
| Direct-to-Consumer Channel Launch | Subscription models in Austin and Denver metro corridors bypass slotting fee compression from consolidated grocery networks. |
| Dual-Jurisdiction Regulatory Capability | Health Canada PMRA navigation creates first-mover positioning against US-only compliance competitors. |
| Organic Supply Chain Deepening | Clif Bar's employee-owned governance anchors prairie grain contracting resilience against climate volatility. |
| Plant-Protein Extrusion R&D | PROBAR's Pacific Northwest facility partnerships replicate whey texture profiles without dairy input dependencies. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, category buyers at natural grocers, supply planners at ingredient distributors, and regulatory affairs leads at dual-jurisdiction operators. Secondary validation drew from FDA labeling guidance documents, Health Canada compositional standard updates, USDA organic certification databases, and Nielsen retail audit data. Bottom-up SKU-level volume estimates triangulated against top-down category spend analysis.
Historical reference periods anchored the projection horizon through verified shipment and consumption data, with CAGR derivation reflecting segment-specific growth trajectories across product type, ingredient sourcing tier, distribution channel, and target consumer archetype. Modeled dimensions included protein content tier, clean-label certification status, manufacturing ownership structure, and regional regulatory cluster. Forecast inputs incorporated almond price volatility indices, extrusion equipment capacity utilization, and subscription-model adoption curves.
Several conditions sit outside the modeled scope, including extreme climate events disrupting California Central Valley harvests, abrupt FDA enforcement shifts on protein content claims, and trade policy revisions affecting Mexican equipment sourcing. Forecasts reflect documented assumptions regarding consumer adherence persistence for ketogenic protocols and organic price-premium tolerance. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Global Rice Snacks Market
Snacks
South America Frozen Snacks Market
Snacks
UAE Cereal Bar Market
Snacks
Europe Snacks Food Market
Snacks
Snack Food Packaging Market
Snacks
RTE Popcorn Market
Snacks
Middle East and North Africa Extruded Snack Food Market
Snacks
Asia Pacific Snack Food Market
Snacks
Low Sugar Fruit Snacks Market
Snacks
South Africa Snack Bar Market
Snacks
Extruded Snacks Market
Snacks
Europe Energy Bar Market
Snacks
Mediterranean Lentil Crisps and Inclusion Bases Market
Snacks
Germany Energy Bar Market
Snacks
Energy Bar Market
Snacks
Kale Chips Market