
 Non-Potato Veggie Chips Market | 2026-2036
Non-Potato Veggie Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Potato Veggie Chips Market Analytics
Millennial and Gen Z consumers are rotating snack budgets from conventional potato chips toward vegetable-based alternatives with cleaner ingredient decks. Bare Snacks leverages its apple chip heritage to extend credibility into kale and beet formats. Rhythm Superfoods anchors its position through raw dehydration expertise rather than conventional frying. Terra Chips competes on vibrant visual differentiation using heirloom carrot and parsnip varieties that command premium placement.
Non-potato veggie chips comprise thin-sliced or extruded root vegetables, leafy greens, and legume bases that undergo baking, air-frying, or low-temperature dehydration to achieve crisp texture with reduced oil content. The category serves commercial and retail channels seeking alternatives to high-acrylamide potato products while delivering fiber, vitamins, and lower glycemic profiles. Savory flavor profiles dominate current shelf turnover, though spicy formulations are gaining velocity in specialty retail and foodservice accounts. Pouch packaging leads material cost efficiency and resealability for on-the-go consumption, while canister formats sustain premium positioning in club and gift channels.
FDA nutrition labeling rules and EFSA acrylamide benchmarks are tightening process controls for fried vegetable snacks, pushing manufacturers toward alternative thermal technologies. USDA organic certification and Non-GMO Project verification operate as gatekeepers for natural channel distribution in the United States. Stakeholders must monitor evolving front-of-pack labeling mandates across multiple jurisdictions, as these frameworks will determine which processing methods and ingredient declarations secure retail access in the decade ahead.
Market Dynamics
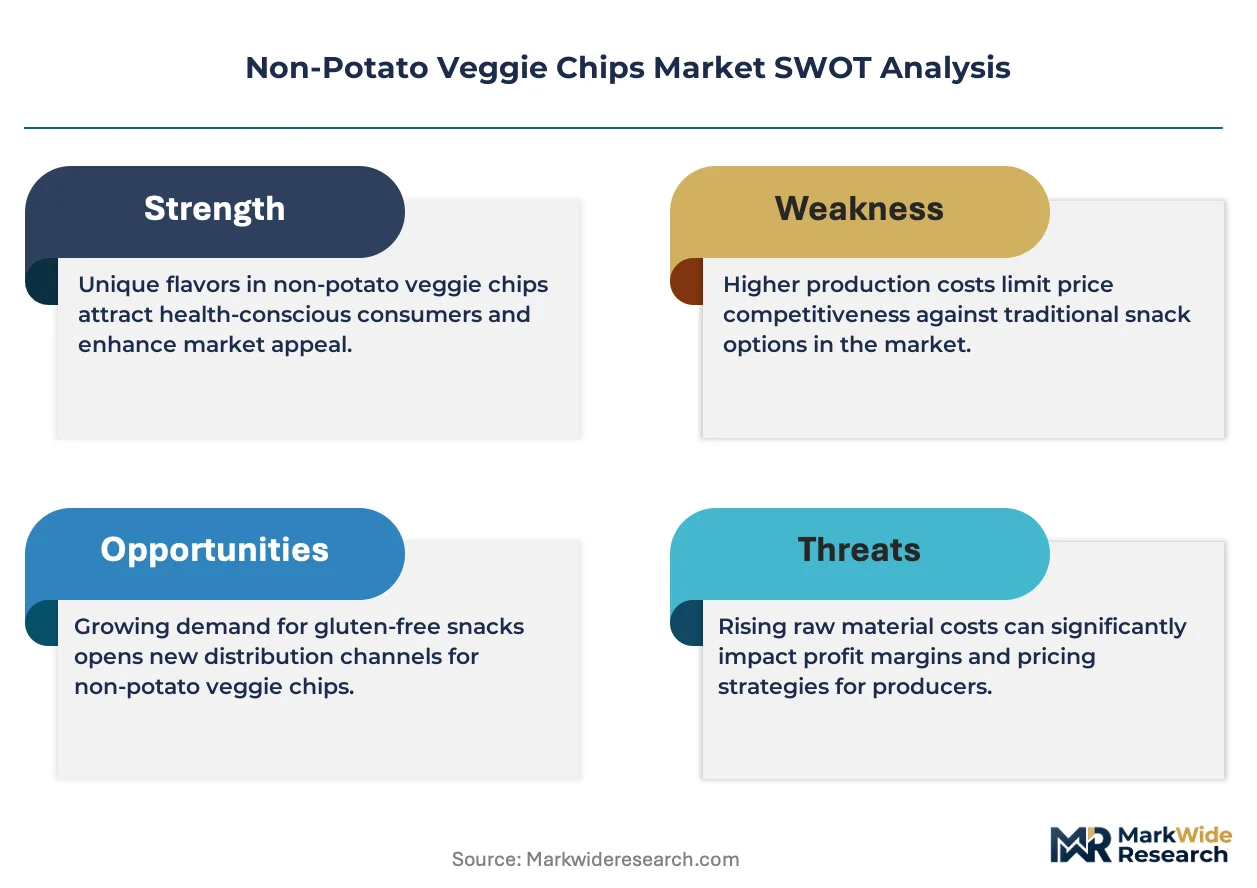
Clean-label mandates from FDA and EFSA are decomposing conventional frying infrastructure as manufacturers race to certify low-acrylamide thermal alternatives before front-of-pack labeling rules tighten in 2025-2026 windows.
Growth Catalysts
- EFSA Acrylamide Benchmarks:Binding exposure limits for fried foods are accelerating capital deployment into vacuum frying and infrared dehydration equipment across European contract manufacturing networks.
- Specialty Grocery Expansion:Natural channel retailers in the United States are dedicating incremental shelf footage to vegetable-forward snack lines with USDA Organic and Non-GMO Project verification.
- Air-Frying Technology:Rapid oil-reduction systems are enabling clean-label claims while preserving mouthfeel characteristics that previously required deep-fat frying.
Market Restraints
- Input Cost Volatility:Sunflower and avocado oil prices fluctuate with Black Sea supply disruptions and Mexican harvest cycles, compressing margin buffers for mid-tier producers.
- Supply Concentration Risk:Domestic sourcing of heirloom carrot and parsnip varieties clusters in California's Central Valley, exposing processors to drought-driven crop failures.
- Technical Limitation:Leafy green dehydration retains chlorophyll bitterness that masks savory flavor profiles, limiting kale chip penetration in mainstream retail.
Strategic Opportunities
- Underpenetrated Geography:German convenience retail channels carry minimal vegetable chip facings relative to potato alternatives, creating whitespace for certified organic entrants.
- Regulatory Tailwind:FDA's updated nutrition labeling rules prioritize fiber and potassium disclosure, advantaging root vegetable formulations over refined grain competitors.
- Distribution Innovation:Direct-to-subscription models bypass slotting fee barriers in consolidated US grocery retail, capturing lifetime value from repeat plant-based snack purchasers.
Industry Challenges
- Certification Timeline:USDA Organic and Non-GMO Project verification cycles extend 14-18 months, delaying product launches past optimal seasonal windows.
- Capex Intensity:Commercial-scale vacuum fryers require $2-4 million facility investments that strain balance sheets of emerging brands without private equity backing.
- Skill Gap:Food science talent with dual expertise in dehydration kinetics and clean-label formulation commands premium compensation that outpaces startup burn rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Potato Veggie Chips Market |
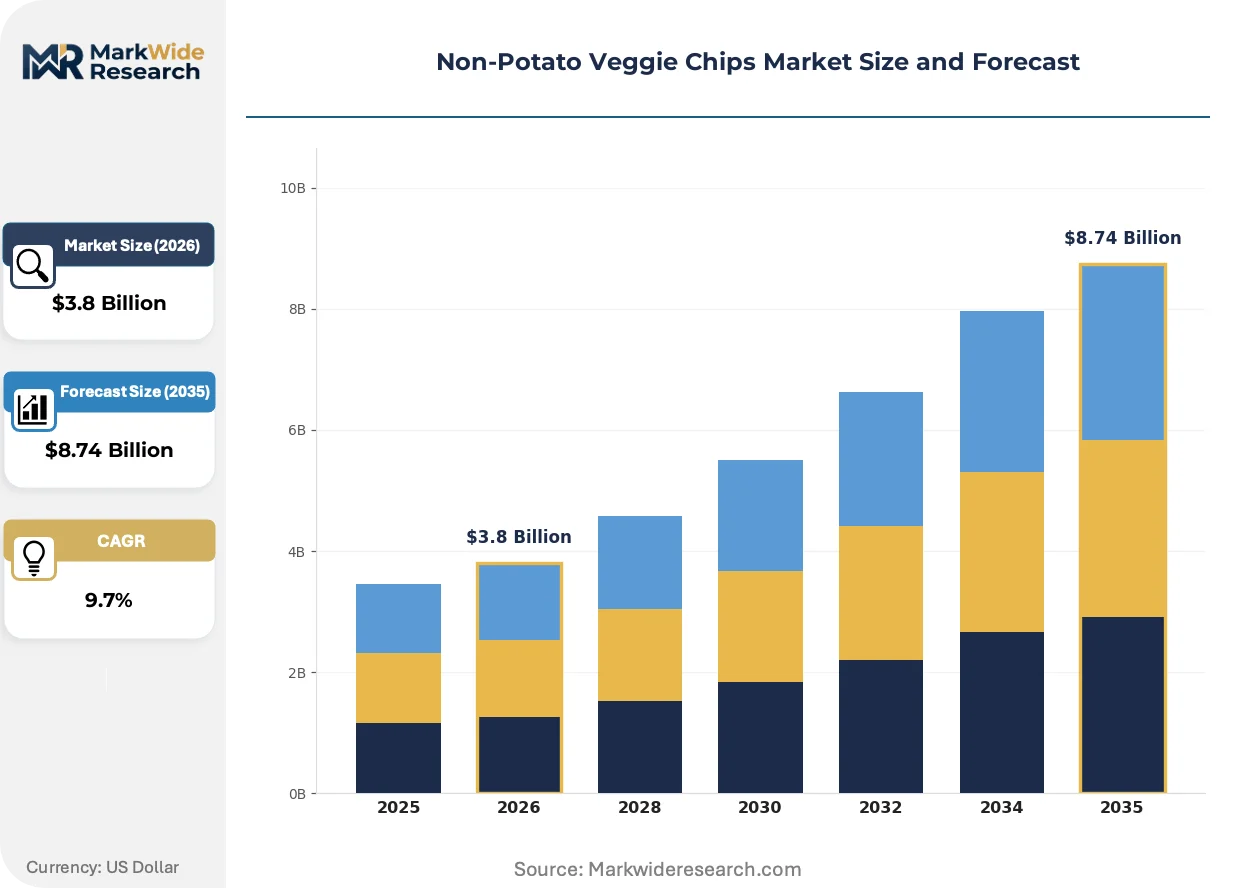
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beet, Carrot, Kale, Spinach Flavor Profile: Savory, Spicy, Sweet, Herb Packaging Type: Bag, Canister, Box, Pouch Distribution Channel: Supermarkets, Health Stores, Online, Specialty Shops |
| Companies Covered | Bare Snacks, Rhythm Superfoods, Terra Chips, Sensible Portions, Simply 7, Beanitos, Brad's Plant Based, Good Health, Kettle Brand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Potato Veggie Chips Market Evolving Landscape
Thermal processing patents and front-of-pack disclosure mandates are restructuring competitive advantage toward equipment-intensive manufacturers with regulatory compliance infrastructure.
Vacuum frying technology is decomposing the traditional trade-off between oil reduction and texture integrity. Premium snack producers in the United States are retrofitting production lines at 15-20% annual adoption rates. This shift is compressing market share for conventional kettle chip contract manufacturers unable to certify low-acrylamide outputs.
EFSA's 2023 acrylamide benchmark update tightens maximum levels for root vegetable snacks sold in European Union member states. Manufacturers must validate process controls through third-party laboratory testing to maintain retail access. German and French retail buyers are now requiring batch-level documentation before purchase order authorization.
Subscription-based replenishment models are displacing impulse-driven convenience store purchases among millennial and Gen Z households. Direct-to-consumer channels capture higher margins while generating consumption data that informs flavor development pipelines. This behavioral pivot concentrates in United States coastal metropolitan markets with established meal-kit delivery infrastructure.
Non-Potato Veggie Chips Market Segmentation
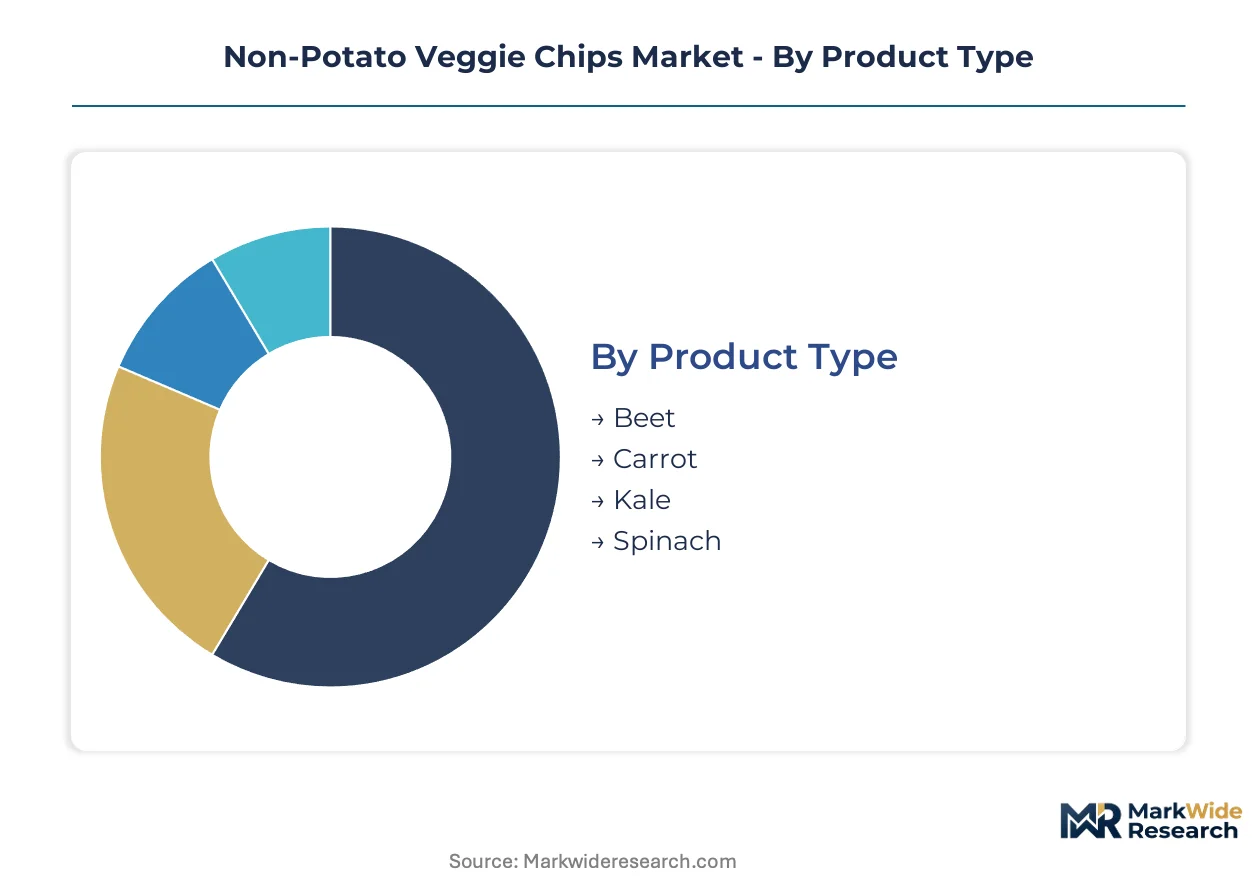
Non-potato veggie chip manufacturers configure product portfolios around thermal processing capabilities and retail channel certification requirements. Segment-specific formulations determine which FDA and EFSA compliance pathways apply, directly influencing capital allocation and geographic market access.
Product Type:
EFSA acrylamide benchmarks apply differentially across root vegetables versus leafy greens, creating distinct regulatory compliance burdens and equipment investment profiles.
- Beet:Deep pigmentation from betalain compounds delivers visual differentiation at shelf. Demand concentrates in United States specialty grocery channels where USDA Organic certification commands placement premiums; vacuum frying preserves color integrity that conventional frying degrades.
- Carrot:High natural sugar content caramelizes under thermal processing, creating flavor complexity without added sweeteners. California's Central Valley heirloom varieties supply premium positioning in natural channel retail, though drought exposure concentrates supply risk.
- Kale:Leafy structure requires low-temperature dehydration to avoid chlorophyll bitterness that limits mainstream acceptance. Technical constraints restrict penetration to health-focused retail formats with educated consumer bases.
- Spinach:Delicate cell structure demands precise moisture control during processing. Applications cluster in premium subscription boxes where texture consistency justifies price premiums.
Established volume favors carrot; emerging adoption favors beet.
Flavor Profile:
Clean-label formulation constraints eliminate artificial flavor systems, pushing developers toward spice and herb inclusions that satisfy regulatory disclosure requirements.
- Savory:Sea salt and nutritional yeast combinations dominate current shelf turnover. United States conventional grocery placement depends on sodium disclosure compliance under FDA updated labeling rules.
- Spicy:Chili and cayenne infusions gain velocity in foodservice accounts and specialty retail. Heat masking properties help offset bitterness in kale and spinach substrates.
- Sweet:Fruit juice concentrates and coconut sugar meet Non-GMO Project verification standards. Applications concentrate in club channel gift assortments where visual appeal drives purchase.
- Herb:Rosemary, thyme, and dill formulations align with Mediterranean diet positioning. European retail buyers require batch-level herb provenance documentation under EFSA traceability mandates.
Mainstream placement favors savory; premium expansion favors herb.
Packaging Type:
Material specifications interact with product moisture sensitivity and shelf-life requirements to determine format selection across channel types.
- Bag:Multi-layer barrier films with nitrogen flush dominate high-velocity retail. Cost efficiency at scale supports mid-tier pricing in United States supermarket chains.
- Canister:Rigid paperboard structures sustain premium positioning and resealability. Club channel and gift applications concentrate here despite higher per-unit material costs.
- Box:Corrugated secondary packaging enables multi-pack configurations. E-commerce fulfillment favors this format for shipping durability.
- Pouch:Stand-up flexible structures with zip-seal closures optimize on-the-go consumption. Direct-to-consumer subscription models standardize on this format for brand differentiation.
Volume concentration favors bag; margin expansion favors canister.
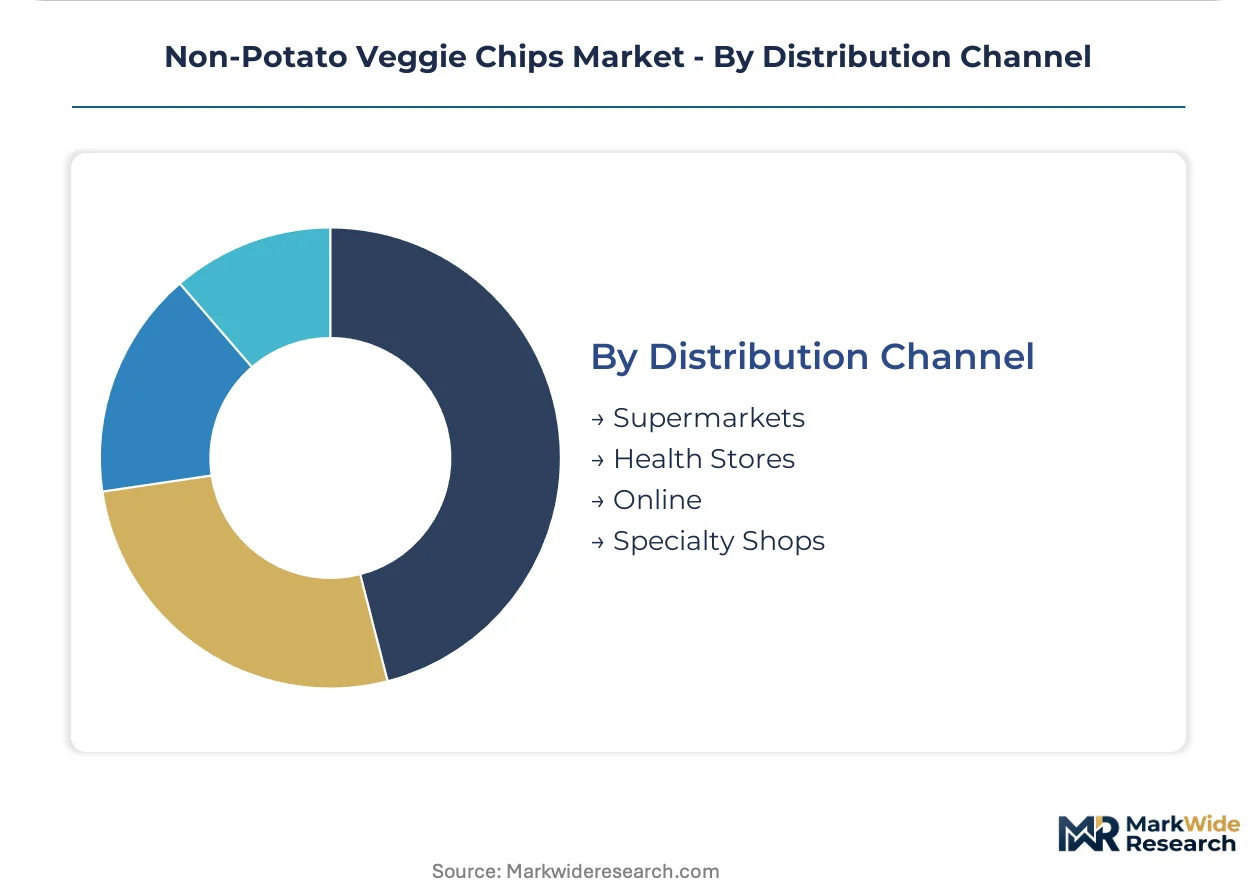
Distribution Channel:
Slotting fee structures and certification requirements fragment channel access, concentrating brand portfolios where compliance infrastructure aligns with buyer mandates.
- Supermarkets:Consolidated United States retail chains demand USDA Organic and Non-GMO Project verification as table stakes. Air-fried product lines gain incremental shelf footage as conventional fried alternatives face acrylamide scrutiny.
- Health Stores:Natural channel retailers prioritize clean-label ingredient decks and transparent supply chains. Raw dehydration expertise commands premium placement over conventional thermal processing.
- Online:Direct-to-consumer and third-party marketplace sales bypass slotting barriers. Subscription replenishment models capture lifetime value from repeat purchasers in coastal metropolitan markets.
- Specialty Shops:Independent retailers and foodservice accounts favor limited-batch and heirloom variety positioning. German convenience retail channels present whitespace opportunity relative to potato alternative saturation.
Revenue concentration favors supermarkets; growth trajectory favors online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley dominates heirloom carrot and parsnip cultivation for premium vegetable chip lines. Contract manufacturers cluster near raw material sources to minimize transport damage to delicate root structures. FDA and EFSA compliance infrastructure concentrates in coastal processing zones with established third-party laboratory networks.
United States
Millennial and Gen Z households in coastal metropolitan markets drive subscription-based replenishment models for plant-based snacks. FDA updated nutrition labeling rules prioritize fiber and potassium disclosure, advantaging root vegetable formulations in conventional grocery channels. California's Central Valley supplies heirloom varieties to natural channel retailers expanding shelf space for certified organic lines.
Germany
Convenience retail channels carry minimal vegetable chip facings relative to potato alternatives, creating whitespace for certified organic entrants. EFSA's 2023 acrylamide benchmark update mandates batch-level documentation for root vegetable snacks before purchase order authorization. Berlin and Hamburg processing facilities retrofit vacuum frying equipment to meet binding exposure limits.
France
Mediterranean diet positioning drives herb-flavored formulations requiring batch-level provenance documentation under EFSA traceability mandates. Lyon and Marseille retail buyers enforce third-party laboratory validation for process controls. Provence-Alpes-Côte d'Azur specialty retailers favor limited-batch heirloom positioning.
United Kingdom
London and Southeast England natural channel retailers prioritize clean-label ingredient decks with Non-GMO Project verification. Brexit-adjusted import frameworks reshape supply chain configurations for European-sourced raw materials. Midlands contract manufacturers invest in air-frying technology to reduce oil content while preserving texture integrity.
Canada
Health Canada front-of-pack labeling proposals align with FDA disclosure priorities for fiber and potassium. Ontario and Quebec specialty grocery chains expand shelf footage for vegetable-forward snack lines. British Columbia processing facilities leverage proximity to United States organic certification infrastructure.
Non-Potato Veggie Chips Market Competitive Landscape
Concentration sits with diversified snack conglomerates and specialized plant-based startups competing on thermal processing certification. The vendor base spans multinational CPG portfolios with existing distribution infrastructure and emerging brands built around single processing modalities. Two strategic archetypes dominate: equipment-intensive manufacturers with regulatory compliance infrastructure, and direct-to-consumer specialists capturing subscription lifetime value. Competitive moves center on vacuum frying technology licensing and geographic whitespace expansion into underpenetrated European convenience channels.
Within the clean-label specialist tier, Bare Snacks and Rhythm Superfoods exemplify divergent thermal processing strategies. Bare Snacks leverages apple chip heritage into beet and kale formats, while Rhythm Superfoods anchors positioning through raw dehydration expertise. Terra Chips occupies a position on vibrant visual differentiation using heirloom varieties. These three California-based entities represent the competitive tension between conventional thermal adaptation and alternative processing innovation.
| Leading Market Players |
|---|
| Bare Snacks |
| Rhythm Superfoods |
| Terra Chips |
| Sensible Portions |
| Simply 7 |
| Beanitos |
| Brad's Plant Based |
| Good Health |
| Kettle Brand |
| Others |
Value Network & Pricing Analysis
USDA Organic certification and Non-GMO Project verification operate as dual gatekeepers that simultaneously filter supply base qualification and stratify price positioning across retail channels. These certification cycles extend 14-18 months, creating scarcity premiums for compliant producers while compressing margins for mid-tier operators unable to absorb compliance costs.
Pricing Analysis
FDA updated nutrition labeling rules dictate the pricing tier structure by mandating fiber and potassium disclosure that advantages root vegetable formulations. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-fried heirloom varieties from air-fried conventional lines and extruded economy formats. Cost compression in the standard tier is intensifying because sunflower and avocado oil price volatility erodes margin buffers. Mass-market supermarket buyers exhibit highest price sensitivity, while specialty grocery and direct-to-consumer channels accept premium positioning for certified organic lines.
Supply Chain Analysis
California's Central Valley and select Mediterranean growing regions anchor heirloom carrot, parsnip, and beet cultivation for premium vegetable chip lines. Processing draws from delicate root structures requiring minimal transport damage, sunflower and avocado oils for thermal applications, and nitrogen-flush barrier films for packaging integrity. Single-source vulnerability concentrates in California drought exposure that threatens heirloom variety availability. Distribution runs through natural channel retailers and direct-to-subscription models that bypass consolidated grocery slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-potato veggie chips market is recovering from cyclical input cost compression as oil price volatility moderates and certification backlogs clear. This recovery phase rewards operators with established compliance infrastructure and penalizes capital-constrained entrants.
For Market Incumbents: Secure vacuum frying equipment licensing agreements before EFSA batch-level documentation mandates tighten procurement requirements. Lock in multi-year contracts with California Central Valley heirloom growers to defend against drought-driven supply disruption. Prioritize backward integration into dehydration technology R&D to outpace air-frying commoditization.
For New Entrants and Emerging Players: Lead with direct-to-consumer subscription models in German convenience retail channels where vegetable chip facings remain minimal relative to potato alternatives. Target certified organic positioning in underpenetrated European markets requiring EFSA-compliant process documentation. Anchor go-to-market strategy on batch-level traceability transparency that satisfies Lyon and Marseille retail buyer mandates.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across vacuum frying equipment deployment as commercial-scale retrofits require $2-4 million facility investments. Five-to-ten year viability favors equipment-intensive manufacturers with regulatory compliance infrastructure over brand-dependent startups lacking thermal processing expertise. Watch for inflection in EFSA enforcement patterns that would accelerate kettle chip contract manufacturer obsolescence.
| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Frying Equipment Retrofit | EFSA acrylamide benchmarks are decomposing conventional kettle chip manufacturing capacity. |
| Heirloom Variety Supply Contracts | California Central Valley drought exposure creates captive sourcing advantages for contracted processors. |
| Direct-to-Consumer Subscription Launch | Coastal metropolitan millennial households generate lifetime value data informing flavor pipelines. |
| USDA Organic Certification Investment | Natural channel retailers demand verification as table stakes for shelf placement premiums. |
| German Convenience Channel Expansion | Whitespace opportunity exists where potato alternative saturation has not yet reached vegetable chips. |
Research Methodology
A spread of perspectives from brand managers at plant-based snack companies, category buyers at natural channel retailers, supply planners managing heirloom root contracts, and thermal processing equipment vendors converged on the working assumptions. Primary interview insights combined with secondary validation from FDA nutrition labeling filings, EFSA acrylamide benchmark documentation, USDA organic certification databases, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down category spending analysis.
Segmentation dimensions modeled include thermal processing modality, root vegetable substrate type, flavor profile category, packaging format, and distribution channel tier across the analysis window. CAGRs derived from regression analysis against historical certified organic product velocity and projected clean-label mandate adoption curves. Industry-specific forecast inputs incorporated vacuum frying equipment deployment rates and EFSA enforcement pattern scenarios.
Forecasts assume regulatory continuity in FDA nutrition labeling rules and EFSA acrylamide benchmarks; material policy shifts would require re-modeling. Forecasts reflect assumptions regarding oil price volatility moderation and heirloom crop yield stability. Recalibration cycles align with material shifts in certification timeline durations and thermal technology adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Vegan Protein Balls Market
Snacks
Low Calorie Granola Market
Snacks
Low Calorie Snacks Market
Snacks
Potato Chips Market
Snacks
Snack Food Packaging Market
Snacks
Europe Energy Bar Market
Snacks
Roasted Snacks Market
Snacks
Extruded Snacks Market
Snacks
United States Popcorn Market
Snacks
Spain Snack Bar Market
Snacks
Baked Chips Market
Snacks
Baked Savoury Snacks Market
Snacks
North America Cereal Bar Market
Snacks
High Fiber Snack Foods Market
Snacks
Asia-Pacific Popcorn Market
Snacks
South Africa Snack Bar Market