
 South Africa Savory Snacks Market | 2026-2036
South Africa Savory Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Savory Snacks Market Analytics
South African savory snack manufacturing is consolidating around Gauteng-based production clusters and coastal processing corridors. PepsiCo Inc leverages its international supply infrastructure to secure shelf space across major retail banners. AVI Limited anchors its position through deep brand equity in local chip and cracker portfolios. Frimax Foods (Pty) Ltd competes aggressively on price in the informal trade channel, where volume turnover remains substantial.
South Africa savory snacks comprise processed, shelf-stable food items—typically extruded, fried, or baked—formulated with salt, seasoning blends, and lipid coatings to deliver palatability and extended ambient stability. These products serve as convenience-driven meal accompaniments and impulse purchases across formal and informal retail environments. Chips dominate current value contribution due to established consumption rituals and accessible price points, while popcorn registers the fastest structural ascent as health-conscious buyers seek lower-oil alternatives. Pouch packaging captures growing margin pools through resealability and portion-control features that resonate with urban commuters.
South Africa's Department of Health enforces front-of-pack labeling rules that pressure sodium reduction and allergen disclosure across savory snack portfolios. The country's national consumer protection regulator monitors advertising claims targeting children, constraining marketing tactics for cheese-flavored and barbecue-positioned lines. Stakeholders must track enforcement intensity around salt caps and plastic packaging levies, as compliance costs will reshape which flavor profiles and pack formats survive profitability tests.
Market Dynamics
South Africa's Department of Health front-of-pack labeling regulations are compressing formulation margins while simultaneously advantaging manufacturers with established sodium-reduction capabilities and clean-label portfolios.
Growth Catalysts
- Pretoria-Johannesburg retail corridor expansion:Urban retail chains in Gauteng province are absorbing higher packaged snack volumes as commuter density rises and convenience-store formats multiply along transport nodes.
- Sodium cap compliance:The Department of Health's salt reduction targets are creating competitive separation between reformulation-ready producers and laggards, rewarding early movers with shelf-space security.
- Extrusion technology upgrades:Continuous extrusion systems are enabling oil-content reduction in puffed snacks without texture degradation, opening health-positioned product lines.
Market Restraints
- Palm oil price volatility:Input cost swings in edible oils directly compress gross margins for fried snack categories, forcing hedging costs or formulation compromises.
- Gauteng production concentration:Manufacturing cluster density around Johannesburg creates single-point vulnerability for logistics disruption and labor action spillover.
- Plastic packaging levies:Environmental taxes on non-recyclable flexible films are elevating unit economics for pouch-format products disproportionately.
Strategic Opportunities
- Western Cape coastal processing:Port-proximate manufacturing in Cape Town and Gqeberha corridors offers export logistics advantages for regional Southern African Development Community penetration.
- Popcorn segment expansion:Air-popped and lower-oil variants are capturing health-conscious buyers seeking permissible indulgence alternatives to fried chips.
- Resealable pouch adoption:Zip-lock and portion-control packaging innovations are commanding premium shelf positioning in urban commuter channels.
Industry Challenges
- Reformulation R&D talent scarcity:Food technologists with sodium-reduction and clean-label expertise command premium compensation, constraining mid-tier manufacturer capability building.
- Allergen disclosure system implementation:Front-of-pack allergen labeling requirements demand IT infrastructure upgrades and supply-chain traceability investments that strain smaller producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Savory Snacks Market |
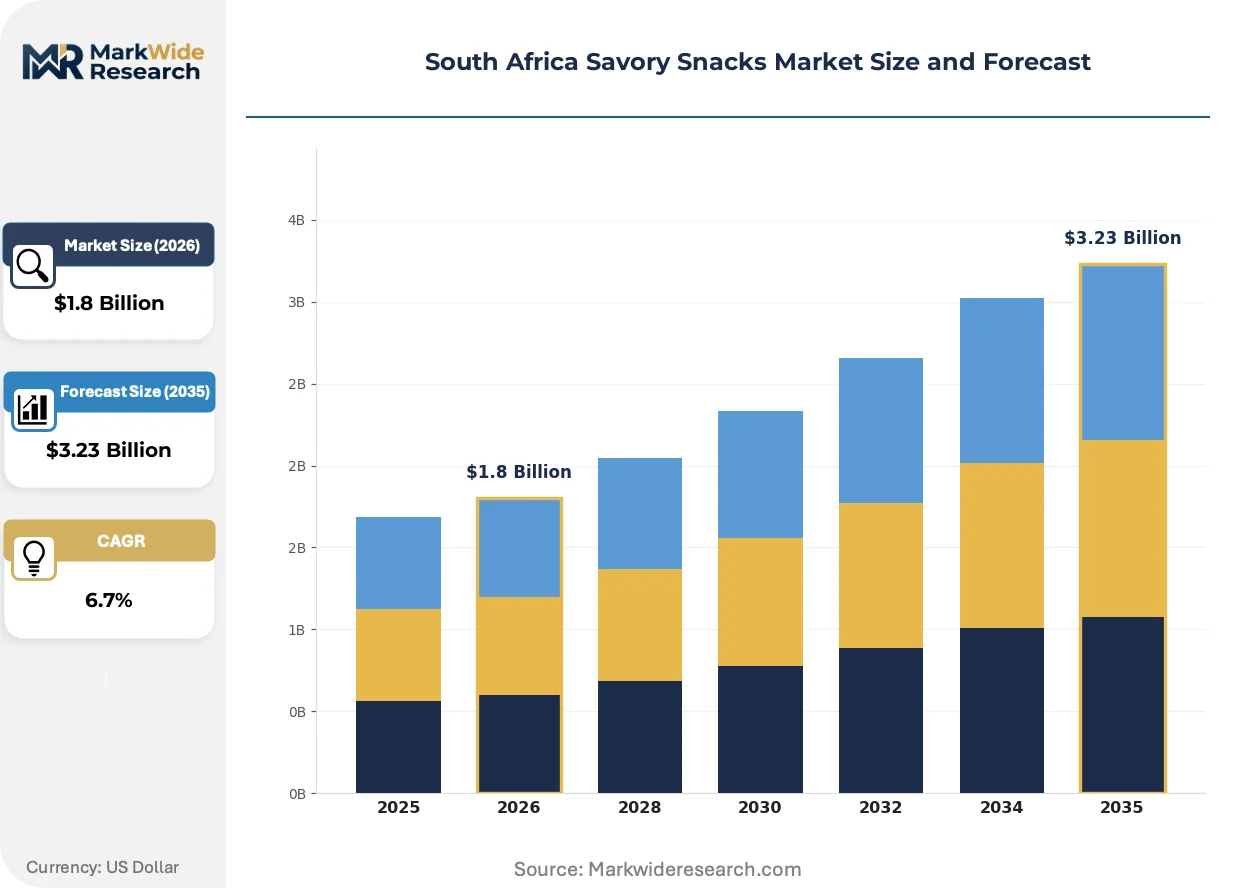
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Crackers, Nuts, Popcorn Flavor Profile: Spicy, Sweet & Savory, Cheese, Barbecue Packaging Type: Bags, Boxes, Cans, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online, Specialty Shops |
| Companies Covered | PepsiCo Inc, AVI Limited, The Kellogg Company, Frimax Foods (Pty) Ltd, Truda Foods (Pty) Ltd, Siyaya Brands Pty Ltd, Picola Foods, Super Snacks, Messaris Snack Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Savory Snacks Market Evolving Landscape
Active reshaping in South African savory snacks centers on processing technology modernization, regulatory compliance architecture, and urban consumption pattern evolution. These forces are compressing legacy operational models while opening margin pools for adaptive manufacturers.
Air-popping and reduced-oil extrusion systems are integrating into mainstream production lines as core health-positioning infrastructure. Health-conscious buyers in Gauteng and Western Cape urban corridors are accelerating adoption of these texture-preserving, fat-reducing technologies. This integration is enabling manufacturers to maintain palatability benchmarks while meeting Department of Health sodium and fat reduction targets, compressing the traditional trade-off between taste and nutrition claims.
South Africa's Department of Health front-of-pack labeling regulations are mandating sodium disclosure and warning icon placement on high-salt products. Industrial consequence includes accelerated R&D expenditure for reformulation and packaging redesign across established brand portfolios. Cheese-flavored and barbecue-positioned lines face disproportionate pressure, with manufacturers responding through gradual salt reduction and alternative umami delivery systems to maintain consumer acceptance.
Urban commuter purchasing is fragmenting across convenience-store, forecourt retail, and e-commerce quick-commerce channels. Traditional supermarket dominance in Johannesburg and Pretoria corridors is yielding to impulse-buy occasions at transport nodes and workplace proximity formats. This rotation is most visible in Gauteng province, where pouch-packaged, portion-controlled SKUs are displacing large-format sharing bags for solo consumption occasions.
South Africa Savory Snacks Market Segmentation
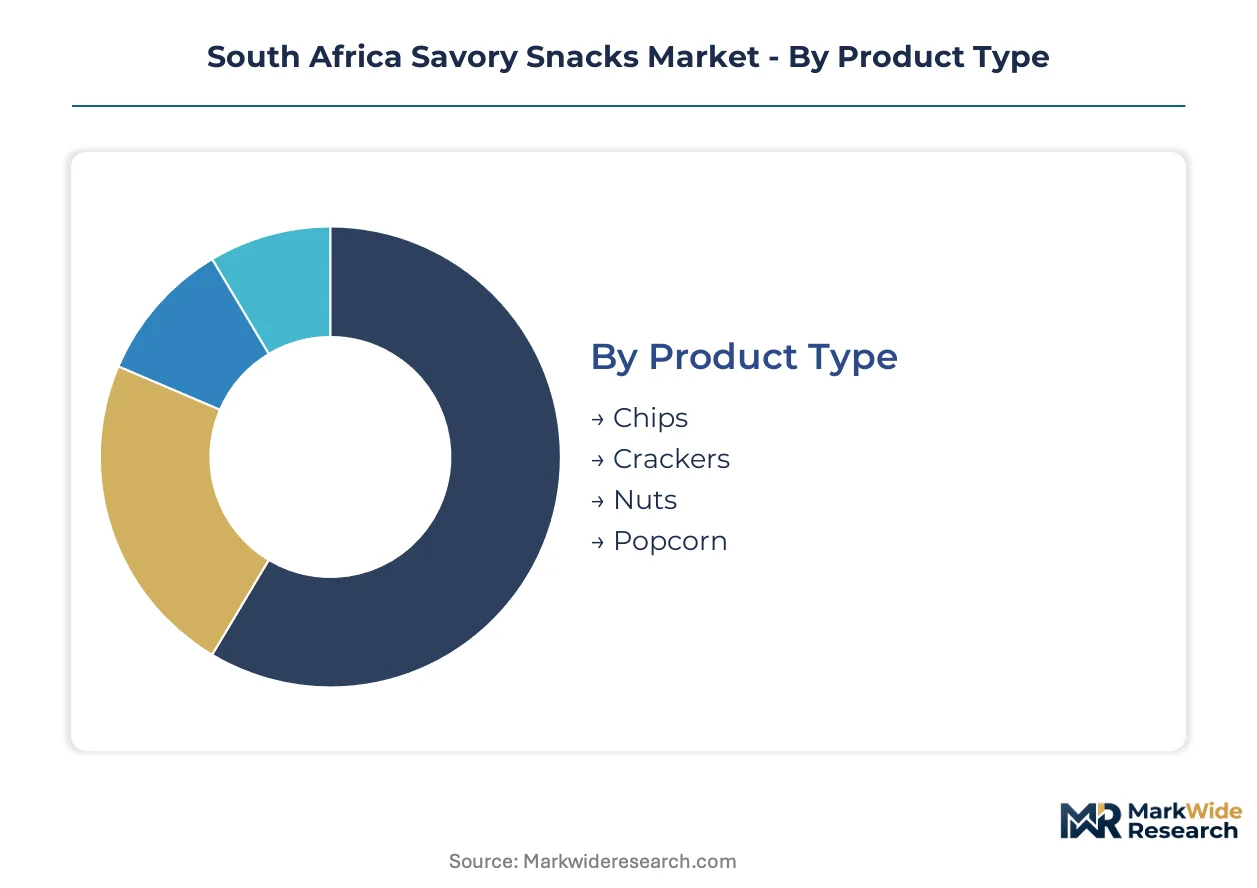
South Africa's savory snack segmentation reflects divergent processing technologies, consumption occasions, and retail channel economics. Manufacturers configure production assets and brand portfolios around these axes to capture volume in Gauteng corridors and margin in premium urban channels.
Product Type:
Extrusion and frying technologies define the manufacturing cost base across product categories.
- Chips:Thin-sliced potato or cassava substrates fried in palm or sunflower oil deliver the category's highest absolute volumes. Johannesburg and Pretoria retail corridors absorb the bulk of throughput, though sodium reduction mandates under Department of Health regulations are compressing margins for legacy formulations.
- Popcorn:Air-popped or low-oil extrusion systems enable permissible indulgence positioning with reduced fat content. Health-conscious buyers in Western Cape urban clusters are driving the steepest demand expansion as manufacturers deploy alternative umami delivery systems to maintain palatability without salt load.
- Crackers:Baked wheat or maize-based formats with extended ambient stability serve meal accompaniment occasions in formal retail.
- Nuts:Roasted and seasoned tree nuts or legumes command premium price tiers through protein content claims and portion-controlled formats.
Chips leads on scale; popcorn leads on momentum.
Flavor Profile:
Seasoning formulation intensity directly correlates with sodium content and regulatory exposure under front-of-pack labeling rules.
- Cheese:Dairy-derived or analog cheese powders deliver umami depth but carry high sodium loads that trigger warning icon placement. Reformulation investments are concentrating in AVI Limited and PepsiCo portfolios to maintain shelf-space security in Shoprite and Pick n Pay banners.
- Barbecue:Smoked paprika, tomato, and molasses-based seasoning systems face parallel sodium pressure. Manufacturers are deploying yeast extract and potassium chloride blends to reduce salt without sacrificing the flavor profile that dominates informal trade volumes.
- Spicy:Capsicum-derived heat allows sodium reduction while maintaining sensory impact through trigeminal stimulation.
- Sweet & Savory:Honey, caramel, or fruit-infused seasoning bridges snack and confectionery occasions in premium urban channels.
Cheese dominates current value contribution; spicy is climbing the fastest as heat-forward positioning aligns with clean-label sodium reduction strategies.
Packaging Type:
Material specifications and format functionality determine logistics economics and retail channel access.
- Pouches:Flexible multilayer films with resealable zip-lock closures command premium positioning in forecourt retail and workplace proximity formats. The format's elevated unit economics face pressure from plastic packaging levies, though portion-control features resonate with Gauteng commuter demand.
- Bags:Standard flexible packaging for large-format sharing occasions retains dominance in supermarket and informal trade channels.
- Boxes:Rigid paperboard formats for crackers and premium assortments enable shelf-ready display in formal retail.
- Cans:Metal containers for nuts and premium chips deliver extended shelf life and gifting positioning in specialty retail.
Bags leads on scale; pouches leads on momentum.
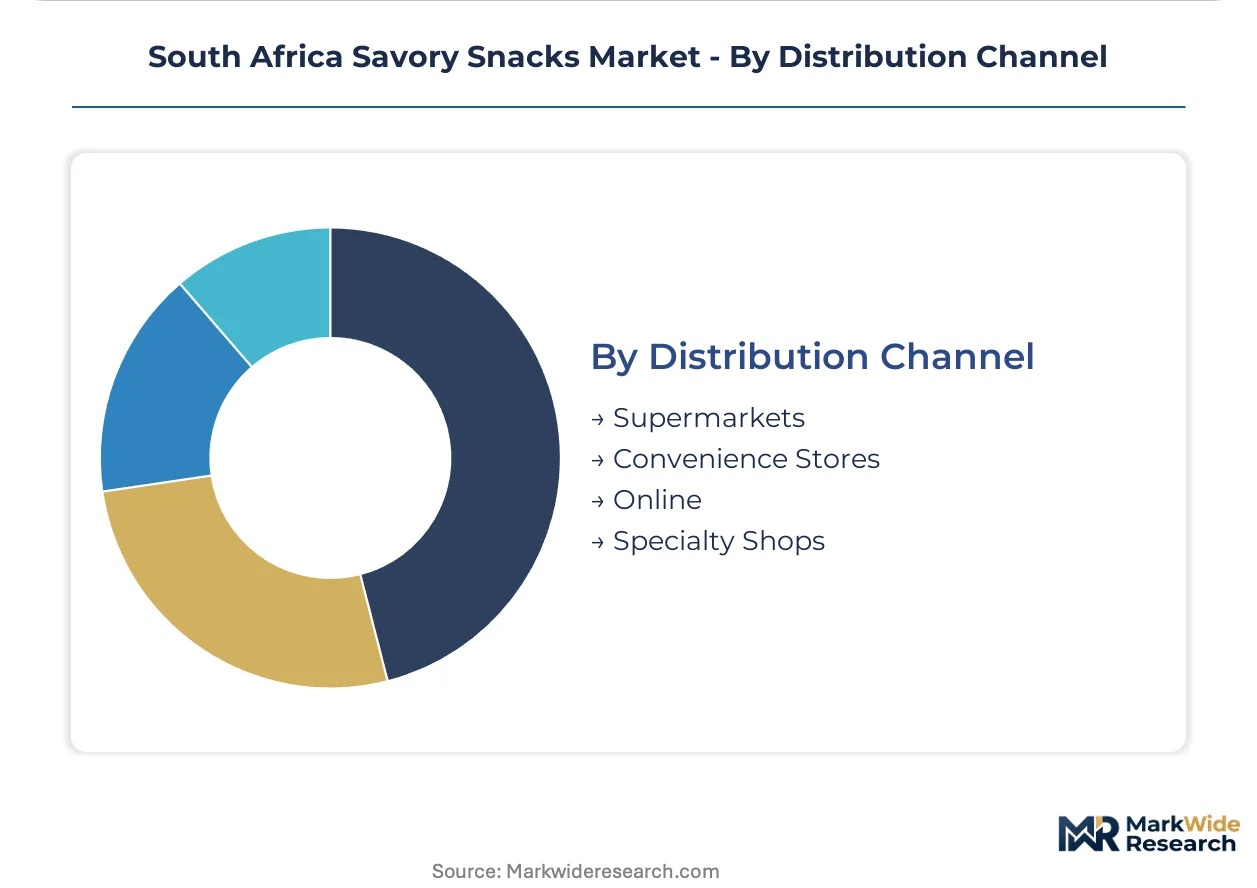
Distribution Channel:
Channel mix determines pricing architecture and brand portfolio segmentation for manufacturers.
- Supermarkets:Shoprite, Pick n Pay, and Spar banners anchor volume throughput with promotional-driven purchasing and family-format pack sizes. Shelf-space fees and listing requirements favor established players with national distribution infrastructure.
- Convenience Stores:Forecourt retail and urban convenience formats at transport nodes capture impulse occasions with single-serve and resealable SKUs. Gauteng province corridor density multiplies outlet count along Johannesburg-Pretoria transit routes.
- Online:Quick-commerce platforms and e-grocery services are fragmenting purchasing patterns with rapid delivery promises and subscription mechanics.
- Specialty Shops:Premium and imported positioning in delis and health-food retailers serves niche dietary requirements and gifting occasions.
Supermarkets leads on scale; convenience stores leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as manufacturers migrate toward provinces with lighter compliance burdens or superior logistics infrastructure. South Africa's Department of Health front-of-pack labeling rules create compliance cost gaps between manufacturing clusters. This dynamic concentrates investment in Gauteng's established corridors while pushing expansion toward Western Cape port access.
Gauteng
Johannesburg and Pretoria retail corridors absorb the highest packaged snack volumes in South Africa. The Department of Health's sodium reduction targets pressure local reformulation capabilities. Manufacturing density around Johannesburg creates logistics advantages for national distribution to Shoprite and Pick n Pay banners.
Western Cape
Cape Town and Gqeberha coastal processing corridors offer export logistics advantages for Southern African Development Community penetration. South Africa's plastic packaging levies hit flexible film formats harder here due to import-dependent supply chains. Port-proximate manufacturing enables regional market access with reduced inland freight costs.
KwaZulu-Natal
Durban's port infrastructure supports edible oil import flows critical for fried snack production. South Africa's Department of Health allergen disclosure requirements demand IT upgrades at Durban-based processors. The province's informal trade channels sustain volume turnover for price-competitive local brands.
Eastern Cape
Gqeberha manufacturing nodes leverage Coega Industrial Development Zone incentives for export-oriented production. South Africa's national consumer protection regulator monitors advertising claims targeting children across this corridor. Labor cost differentials relative to Gauteng attract mid-tier manufacturers seeking margin relief.
South Africa Savory Snacks Market Competitive Landscape
Gauteng-based producers anchor one tier; Western Cape specialists hold export-oriented positions. The market structure consolidates around three to four national-scale manufacturers with deep retail banner relationships, while regional specialists capture informal trade volumes through price positioning. Strategic archetypes include multinational portfolio players, domestic brand equity holders, and informal trade price competitors. Dominant competitive moves center on sodium-reduction R&D investment and resealable packaging format adoption.
Within the multinational tier, PepsiCo Inc and The Kellogg Company represent global supply infrastructure deployment. Among domestic specialists, AVI Limited and Frimax Foods (Pty) Ltd exemplify contrasting strategic positions—AVI Limited anchors brand equity in formal retail channels while Frimax Foods occupies aggressive price positioning in informal trade. These three named entities collectively illustrate the market's competitive segmentation between global scale and local responsiveness.
| Leading Market Players |
|---|
| PepsiCo Inc |
| AVI Limited |
| The Kellogg Company |
| Frimax Foods (Pty) Ltd |
| Truda Foods (Pty) Ltd |
| Siyaya Brands Pty Ltd |
| Picola Foods |
| Super Snacks |
| Messaris Snack Foods |
| Others |
Value Network & Pricing Analysis
Sodium reduction mandates from South Africa's Department of Health are forcing reformulation investments that compress margins for legacy producers while rewarding early movers with shelf-space security and pricing power in Gauteng retail corridors.
Pricing Analysis
Retailer markup layers in formal channels absorb margin pressure from plastic packaging levies and sodium compliance costs. Three-tier pricing structure across premium, standard, and economy levels stratifies by health-positioning intensity and resealable format features. Price differentiation hinges on clean-label certification and portion-control functionality. Pricing pressure stems from palm oil volatility in fried snack tiers. Informal trade buyers exhibit highest price sensitivity; premium urban commuters show lowest.
Supply Chain Analysis
Direct-to-retail distribution handles hyperscale volumes for Shoprite and Pick n Pick banners in Gauteng corridors. Manufacturing concentrates in South Africa's Johannesburg-Pretoria cluster and Western Cape port zones. Raw material flows draw from Malaysia and Indonesia for palm oil, Ukraine and Argentina for sunflower oil, and domestic maize and potato substrates. Single-source vulnerability runs through edible oil import dependencies. Distribution runs through formal retail banners, informal wholesale networks, and quick-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's savory snacks market functions as a regulatory compounder where Department of Health front-of-pack labeling milestones are accelerating R&D expenditure and reshaping competitive viability across formulation capabilities.
For Market Incumbents: Hedge against sodium-cap compliance gaps by acquiring clean-label technology assets and securing reformulation talent pools in Gauteng. Vertical integration into air-popping extrusion systems defends margin position against oil-price volatility. Channel control through resealable pouch format exclusivity with forecourt retailers locks in commuter loyalty. For New Entrants and Emerging Players: The mid-tier price gap between AVI Limited's premium positioning and Frimax Foods' economy aggression creates white-space for health-positioned challengers. Western Cape coastal processing corridors offer the most penetrable geography for export-oriented scale. A direct-to-quick-commerce launch targeting workplace proximity formats bypasses incumbent shelf-space dominance. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier manufacturers possessing sodium-reduction R&D capabilities and informal trade distribution infrastructure. Long-term viability across the analysis window favors targets with dual-channel presence and reformulation-ready production lines. Watch enforcement intensity around salt caps as the inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sodium Reduction Reformulation | Department of Health compliance secures shelf-space access in Shoprite and Pick n Pay banners. |
| Resealable Pouch Format Expansion | Zip-lock functionality captures premium positioning in Gauteng forecourt retail corridors. |
| Air-Popped Production Line Investment | Lower-oil extrusion technology opens health-conscious segments without taste degradation. |
| Western Cape Coastal Manufacturing | Port-proximate production enables Southern African Development Community export penetration. |
| Informal Trade Channel Deepening | Price-competitive SKUs sustain volume turnover where Frimax Foods currently dominates. |
Research Methodology
Multiple input streams — brand manager interviews, category buyer discussions, supply planner consultations, regulatory affairs dialogues — were reconciled against Nielsen retail audit data, customs import records, Department of Health filing documents, and SEC 10-K disclosures from multinational parents. Bottom-up volume modeling and top-down value triangulation validated segment-level estimates across the projection horizon.
Data-stream reconciliation anchored the analytical framework across product type, flavor profile, packaging format, distribution channel, and provincial demand cluster dimensions. CAGRs were derived from trend extrapolation and elasticity modeling. Forecast inputs incorporated sodium reduction compliance timelines and edible oil price trajectory assumptions.
Caveats apply where enforcement intensity shifts, palm oil supply disruptions, or plastic packaging levy escalations could materially shift the outlook. Forecasts reflect documented assumptions about regulatory adherence rates and urban commuter channel migration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
South America Energy Bar Market
Snacks
Low Calorie Snacks Market
Snacks
Low Fat Crackers Market
Snacks
Snack Pellets Market
Snacks
Australia Snack Bar Market
Snacks
Premium Snacks Market
Snacks
South America Frozen Snacks Market
Snacks
Savory Snack Products Market
Snacks
High Carb Low Fat Snack Market
Snacks
Meat Snacks Market
Snacks
Savoury Biscuits Market
Snacks
Asia-Pacific Snack Bar Market
Snacks
Europe Snacks Food Market
Snacks
Peanut Butter Keto Snacks Market
Snacks
Pretzel Salts Market
Snacks
Plant-Based Snacks Market