
 Spain Energy Bar Market | 2026-2036
Spain Energy Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Energy Bar Market Analytics
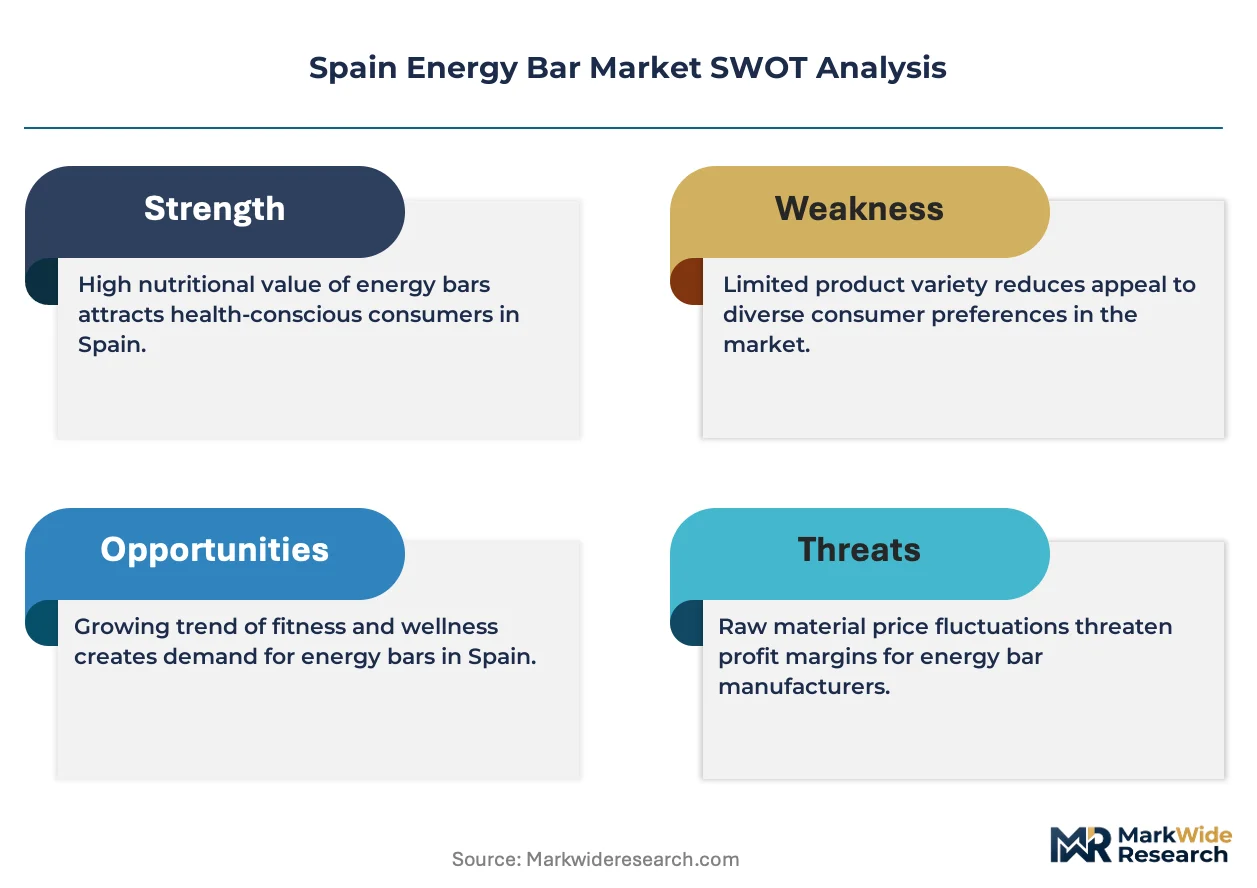
Multi-source ingredient procurement is hardening as Spanish energy bar manufacturers diversify away from single-origin nut and protein suppliers. General Mills Inc. leverages its pan-European procurement infrastructure to secure cost-stable whey and plant protein inputs. Nestlé S.A. anchors its position through extensive R&D facilities in Spain that refine texture and shelf-stability profiles. Nutrisport S.A. competes as a domestic specialist with deep pharmacy and gym channel control across Iberian retail networks.
Spain energy bars are shelf-stable, nutrient-dense food products typically formulated with proteins, carbohydrates, fats, and micronutrients, manufactured through cold-press extrusion or baked slab-and-cut processes, and designed to deliver rapid energy replenishment for physically active consumers. Protein-rich and nut-based formulations dominate current Spanish retail shelf space, while gluten-free variants sustain the fastest trajectory as celiac awareness and free-from labeling expand. Online Retailers capture expanding margin pools as direct-to-consumer subscription models bypass traditional supermarket slotting fees in dense urban markets.
Spain's energy bar sector operates under EFSA nutrition and health claims oversight, with FSSAI-aligned import checks on non-EU protein sources and national BIS-equivalent quality benchmarks enforced through Spain's Ministry of Consumer Affairs. These frameworks elevate compliance costs for new entrants while rewarding incumbents with established regulatory dossiers. Stakeholders must monitor evolving EU packaging waste directives and front-of-label nutrient scoring systems that will reshape formulation and marketing strategies.
Market Dynamics
EFSA nutrition and health claims enforcement is compressing formulation flexibility across Spain's energy bar sector, forcing manufacturers to rebuild product portfolios around substantiated functional benefits rather than marketing-driven positioning.
Growth Catalysts
- EFSA Claims Authorization:Approved health claims for protein and fiber enable functional positioning that commands shelf premium in Madrid and Barcelona pharmacy channels.
- Fitness Enthusiast Expansion:Boutique gym proliferation in Valencia and Seville creates concentrated demand nodes for performance-formulated bars with elevated protein density.
- Cold-Press Extrusion:Lower-temperature processing preserves heat-sensitive micronutrients, allowing clean-label positioning that differentiates against conventional baked alternatives.
Market Restraints
- Almond Supply Concentration:Spanish manufacturers source 60-70% of nut inputs from California Central Valley growers, exposing margins to irrigation policy volatility and dollar-euro fluctuations.
- Whey Protein Import Dependency:Non-EU dairy protein concentrates face FSSAI-aligned border checks that extend lead times and complicate just-in-time production scheduling.
- Gluten-Free Certification Cost:FACE (Federación de Asociaciones de Celíacos de España) endorsement requires dedicated production lines and testing protocols that raise unit economics for sub-scale brands.
Strategic Opportunities
- Andalusian Retail Penetration:Underdeveloped modern trade infrastructure in Córdoba and Málaga creates first-mover advantage for direct-to-gym distribution models bypassing supermarket slotting fees.
- EU Packaging Waste Directive Alignment:Early adoption of compostable film structures positions brands for mandatory extended producer responsibility schemes anticipated under revised EU waste frameworks.
- Pharmacy Channel Expansion:Nutrisport's established presence in farmacias demonstrates viable path for clinical-nutrition positioning targeting diabetic and weight-management segments.
Industry Challenges
- Formulation Talent Scarcity:Shortage of food technologists experienced in EFSA-compliant health claim dossier preparation delays new product commercialization timelines.
- Legacy Equipment Retrofit Costs:Cold-press extrusion adoption requires capital deployment that strains mid-tier manufacturers with depreciated baked-bar production assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Energy Bar Market |
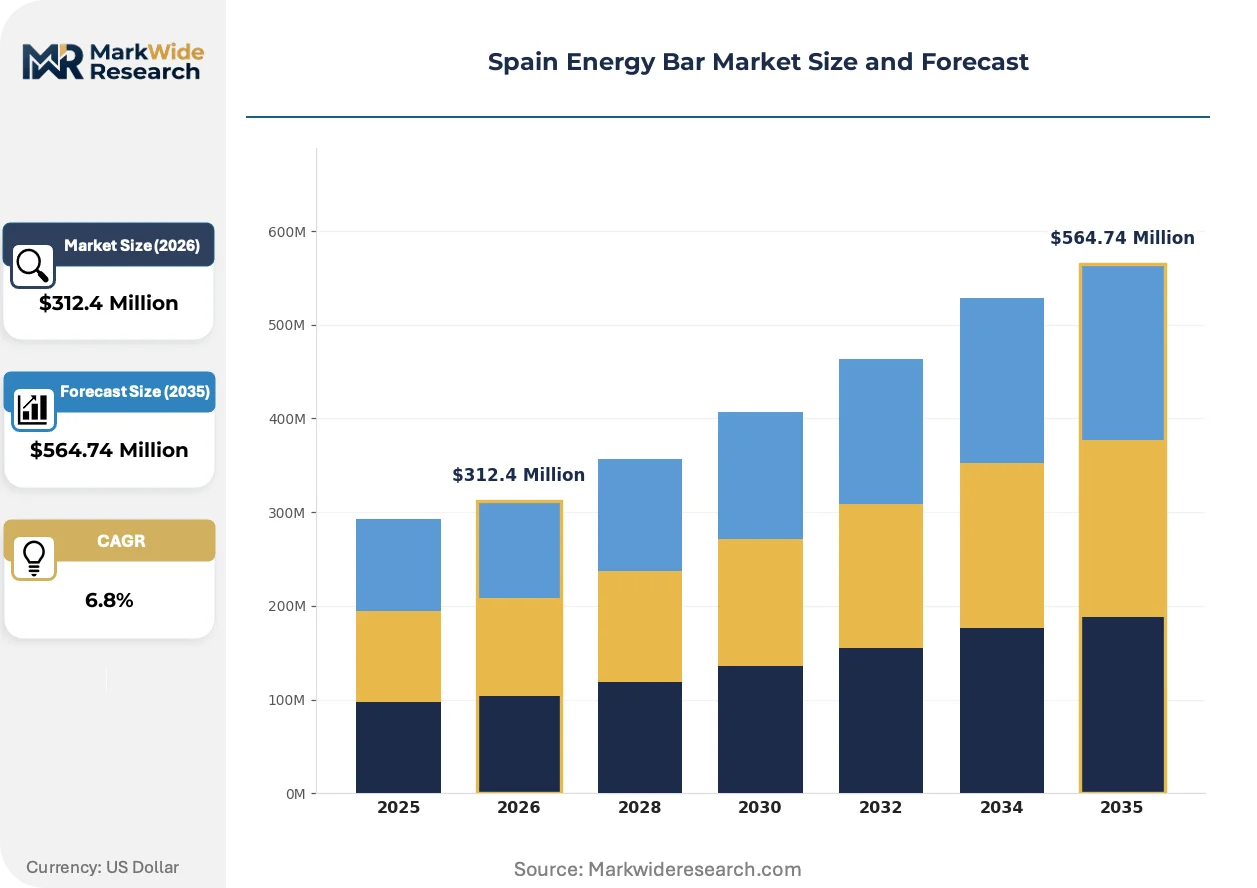
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut-based, Protein-rich, Gluten-free, Organic End User: Athletes, Fitness Enthusiasts, Busy Professionals, Students Distribution Channel: Supermarkets, Health Stores, Online Retailers, Convenience Stores Price Tier: Premium, Mid-range, Budget, Economy |
| Companies Covered | Simply Good Foods Company, General Mills Inc., Nestlé S.A., Glanbia PLC, Mars, Incorporated, Enervit S.p.A., Amway Corp., Nutrisport S.A., Mondelēz International, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Energy Bar Market Evolving Landscape
Texture engineering and regulatory substantiation are converging to reshape competitive advantage in Spain's energy bar sector, with shelf-stability and clean-label claims becoming inseparable technical requirements rather than optional premium features.
Pea-protein isolate with improved solubility profiles is rewriting formulation possibilities for Spanish manufacturers previously constrained by gritty mouthfeel in plant-based bars. Fitness Enthusiasts in Barcelona's CrossFit affiliate network are adopting these reformulated products at replacement rates exceeding conventional whey-based equivalents. The technology is compressing the performance gap between animal and plant protein sources, forcing legacy brands to accelerate R&D timelines or concede the vegan-positioned segment.
EU front-of-pack Nutri-Score labeling mandates are redistributing shelf space toward reformulated products with reduced saturated fat and added sugar profiles. Manufacturers achieving A or B ratings gain preferred placement in El Corte Inglés and Carrefour hypermarkets, while C-rated legacy SKUs face delisting pressure. The policy is most acutely affecting nut-dominant formulations historically reliant on caloric density for positioning.
Subscription-based replenishment models are displacing impulse purchases in dense urban markets, with Madrid consumers demonstrating highest adoption of automated monthly deliveries. Direct-to-consumer platforms bypass traditional distributor markups while capturing consumption data that informs flavor innovation cycles. This channel rotation is most visible among 25-40 year-old professionals prioritizing convenience over in-store browsing.
Spain Energy Bar Market Segmentation
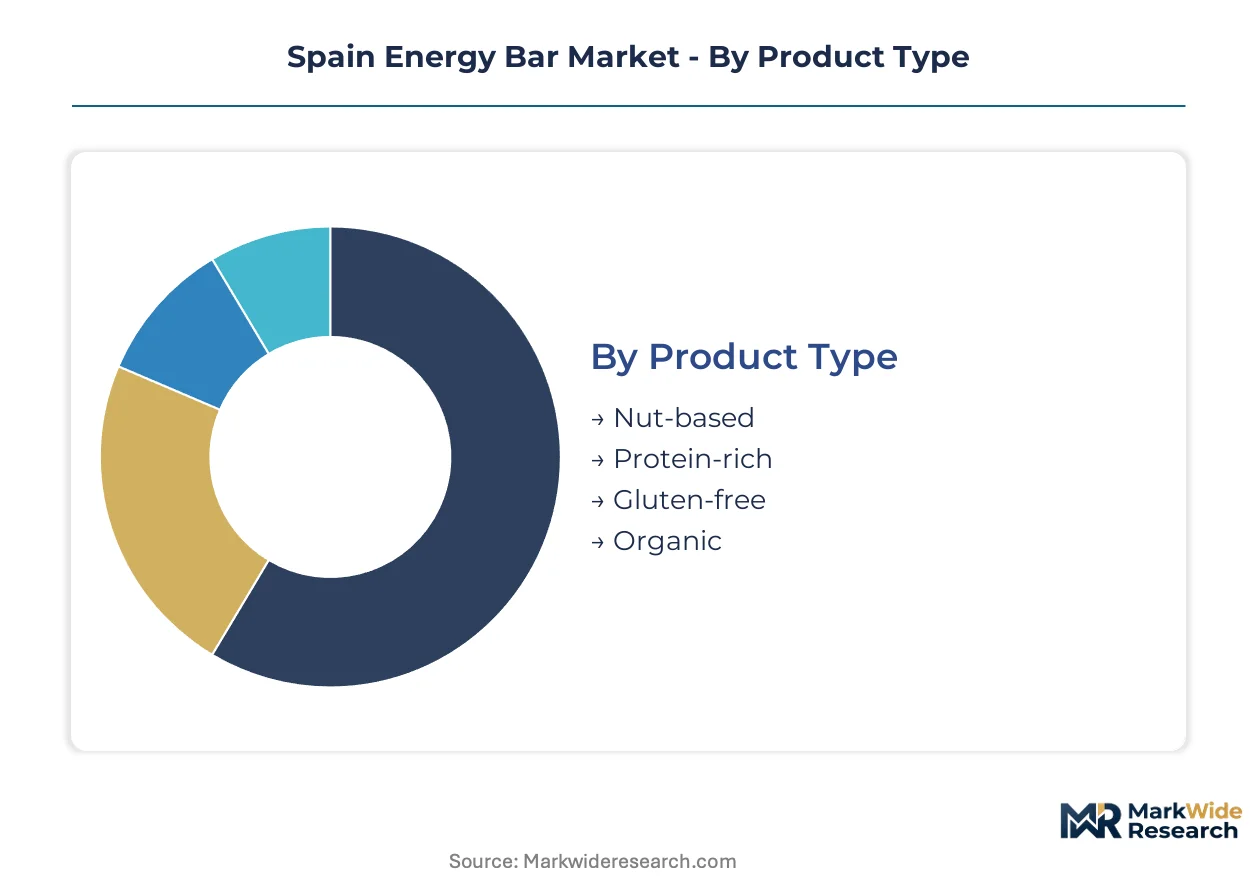
Energy bar manufacturers in Spain navigate distinct formulation, channel, and pricing architectures that determine margin capture and brand positioning. EFSA compliance requirements and regional consumption patterns create divergent investment priorities across each segmentation axis.
Product Type:
Formulation technology dictates shelf stability, protein bioavailability, and clean-label positioning in Spanish retail environments.
- Nut-based:Almond and hazelnut-dominant formulations leverage Spain's historical confectionery expertise. Madrid and Barcelona supermarkets allocate prime shelf space to heritage brands with established texture profiles, though California almond supply exposure compresses margin predictability.
- Protein-rich:Whey isolate and emerging pea-protein concentrates deliver 20g+ protein per serving for CrossFit affiliates and boutique gym networks. Valencia's fitness culture drives concentrated demand for performance-positioned bars with substantiated amino acid profiles.
- Gluten-free:FACE-certified production lines serve celiac consumers with dedicated facility protocols. Seville pharmacy channels demonstrate strongest pull for clinically positioned variants.
- Organic:EU organic logo compliance and shortened ingredient decks attract environmentally conscious segments in Basque Country urban centers.
Mature deployment sits with nut-based formulations. Newer deployment is concentrated in protein-rich extruded bars with enhanced micronutrient preservation.
End User:
Consumption occasion and nutritional literacy separate addressable segments by channel strategy and packaging format.
- Athletes:Competitive cyclists and triathletes in Catalonia demand isotonic-compatible bars with precise carbohydrate-to-protein ratios for training periodization.
- Fitness Enthusiasts:Boutique gym members in Madrid and Barcelona represent the steepest expansion trajectory, replacing post-workout shakes with portable protein solutions.
- Busy Professionals:Subscription-oriented 25-40 year olds prioritize convenience and Nutri-Score visibility over price sensitivity.
- Students:University campus proximity drives impulse purchases of budget-positioned single-serve formats in convenience channels.
Athletes command premium pricing tolerance. Fitness enthusiasts are gaining share fastest as gym penetration deepens in secondary Spanish cities.
Distribution Channel:
Channel economics determine margin retention and consumer data capture capabilities for Spanish energy bar brands.
- Supermarkets:El Corte Inglés and Carrefour hypermarkets enforce Nutri-Score placement algorithms that favor A-B rated SKUs with reduced saturated fat profiles.
- Health Stores:Independent herbolarios and dedicated nutrition retailers provide educated staff consultation for protein specification comparison.
- Online Retailers:Direct-to-consumer platforms bypass distributor markups while enabling subscription replenishment models with highest retention in dense Madrid postal codes.
- Convenience Stores:Impulse-oriented single-serve placement targets commuter corridors with limited flavor variety and higher unit economics.
Established volume flows through supermarkets. Emerging margin pools concentrate in online retailers with first-party data advantages.
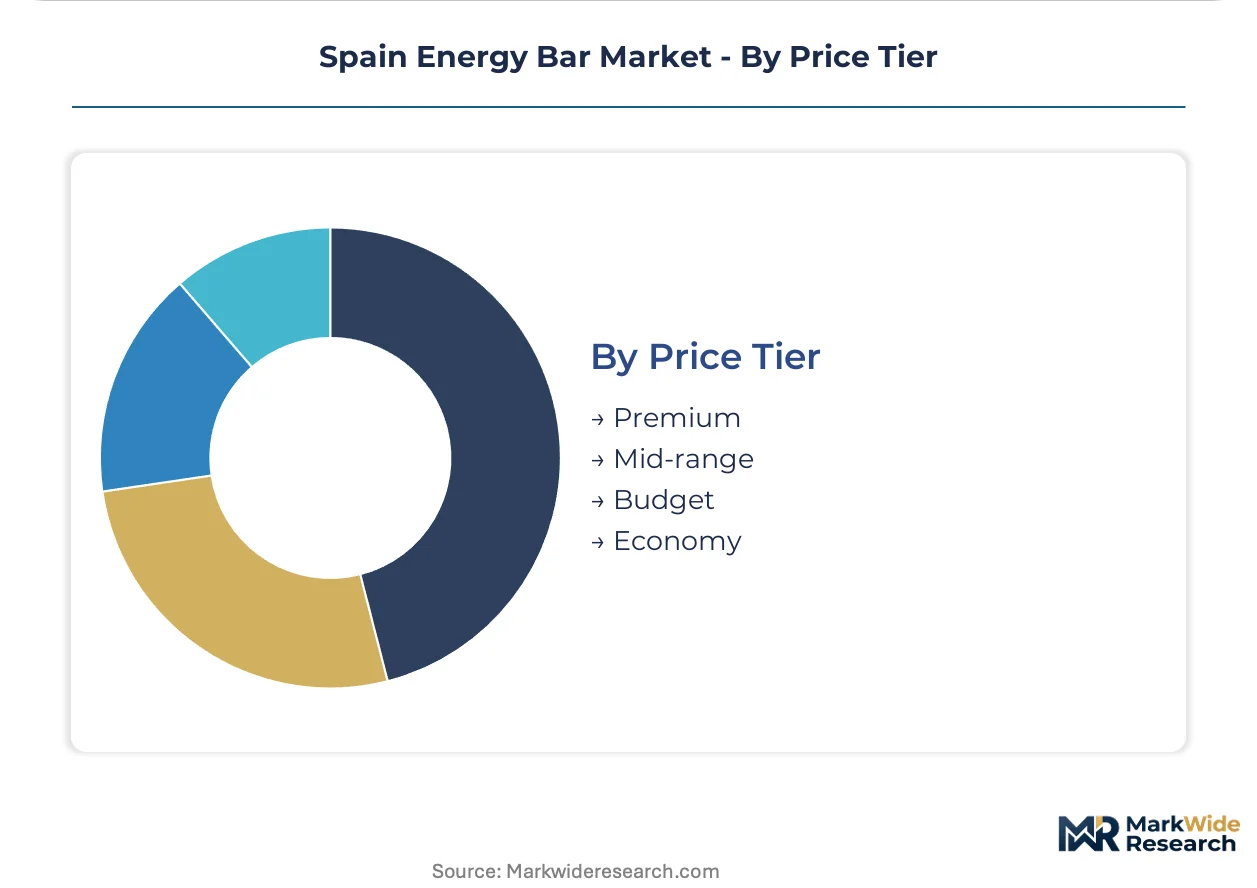
Price Tier:
Price architecture reflects ingredient sourcing intensity, certification burden, and channel slotting fee structures.
- Premium:Cold-press extruded bars with organic certification and compostable packaging command pharmacy and specialty retail placement.
- Mid-range:Conventional baked formulations with EFSA-substantiated protein claims dominate El Corte Inglés mainstream shelving.
- Budget:Private-label supermarket offerings compete on unit price with simplified ingredient decks and conventional packaging.
- Economy:Value-channel bulk formats target price-sensitive households with minimal functional positioning.
Premium tier anchors brand equity. Mid-range tier captures volume concentration as private-label quality improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish almond orchards in Valencia and Murcia supply critical nut inputs, while Madrid and Barcelona concentrate formulation R&D and premium retail distribution for energy bar manufacturers serving Iberian and export markets.
Madrid
Corporate headquarters for Nutrisport S.A. and major fitness chain procurement offices drive demand for performance-formulated bars. EFSA nutrition claim dossiers undergo review through Spanish Agency for Food Safety and Nutrition coordination. Alcobendas and Pozuelo de Alarcón host cold-press extrusion pilot facilities testing reduced-sugar formulations.
Catalonia
CrossFit affiliate density in Barcelona exceeds national averages, creating concentrated demand for 20g+ protein bars. EU organic logo certification requirements shape ingredient sourcing for export-oriented manufacturers. Sant Cugat del Vallès and Mataró cluster co-manufacturing facilities serving French and Italian retail channels.
Basque Country
Environmental certification preferences exceed national baselines in Bilbao and San Sebastián urban centers. Spain's Ministry of Consumer Affairs enforces front-of-pack Nutri-Score labeling compliance through regional inspectorates. Vitoria-Gasteiz anchors compostable packaging material suppliers serving premium bar brands.
Andalusia
Underdeveloped modern trade infrastructure in Córdoba and Málaga creates direct-to-gym distribution opportunities bypassing supermarket slotting fees. Federación de Asociaciones de Celíacos de España certifies dedicated gluten-free production lines in Seville pharmaceutical manufacturing zones. Granada university corridors sustain impulse demand for single-serve budget formats.
Valencia
Boutique gym proliferation drives fastest-growing demand for post-workout protein solutions outside Madrid-Barcelona axis. EU packaging waste directive anticipation accelerates biodegradable film trials among regional contract manufacturers. Castellón de la Plana hosts nut processing facilities supplying almond and hazelnut inputs to national formulators.
Spain Energy Bar Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and channel access, creating a tiered structure where multinational CPG conglomerates hold pharmacy and hypermarket shelf space while domestic specialists control gym and farmacia networks. Three archetypes dominate: diversified nutrition conglomerates with pan-European procurement infrastructure, domestic specialists with deep Iberian channel relationships, and private-label manufacturers serving supermarket economy tiers. Competitive moves concentrate on cold-press extrusion capacity expansion and direct-to-consumer platform development.
Among diversified nutrition conglomerates, General Mills Inc. and Nestlé S.A. exemplify archetypes leveraging scale-driven ingredient sourcing and regulatory dossier expertise. General Mills anchors procurement stability through established whey and plant protein supply networks. Nestlé occupies a position emphasizing texture engineering and shelf-stability R&D. Domestic specialist Nutrisport S.A. represents the regional champion archetype with concentrated pharmacy and gym channel penetration across Iberian retail networks.
| Leading Market Players |
|---|
| Simply Good Foods Company |
| General Mills Inc. |
| Nestlé S.A. |
| Glanbia PLC |
| Mars, Incorporated |
| Enervit S.p.A. |
| Amway Corp. |
| Nutrisport S.A. |
| Mondelēz International, Inc. |
| Others |
Value Network & Pricing Analysis
California almond procurement costs cascade through Spain's energy bar pricing tiers, with irrigation policy volatility in the Central Valley translating directly into margin compression for nut-dominant formulations and premium positioning in Madrid pharmacy channels.
Pricing Analysis
Warranty-like certification bundling separates premium cold-press extruded bars from unbundled economy alternatives lacking FACE gluten-free or EU organic logo validation. Three-tier pricing structure across premium, standard, and economy levels reflects ingredient sourcing intensity and Nutri-Score rating achievement. Cost compression in the mid-range tier is intensifying as private-label quality improves at El Corte Inglés. Students in university corridors exhibit highest price sensitivity, while diabetic and weight-management segments in farmacias demonstrate lowest.
Supply Chain Analysis
EU organic logo and FACE certification requirements are reshaping domestic-content sourcing toward Valencia and Murcia almond orchards and Castellón de la Plana nut processing facilities. Spanish manufacturers draw from California Central Valley growers for 60-70% of nut inputs, alongside Irish and Dutch whey protein concentrates. Single-source vulnerability in California almond supply exposes margins to dollar-euro fluctuations and irrigation restrictions. Distribution runs through El Corte Inglés and Carrefour hypermarkets for volume, with direct-to-consumer platforms capturing expanding margin pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold-press extrusion technology is displacing conventional baked slab-and-cut processes, compressing the performance gap between legacy equipment and clean-label positioning while forcing capital deployment decisions across manufacturer tiers.
For Market Incumbents: Anticipate margin erosion from pea-protein isolate adoption by accelerating R&D timelines for texture-engineered plant-based formulations. Secure backward integration into Valencia almond processing to reduce California supply exposure. Prioritize EFSA-compliant health claim dossier investment to defend pharmacy channel placement against emerging entrants.
For New Entrants and Emerging Players: Launch via direct-to-gym distribution models in Andalusian secondary cities where modern trade infrastructure remains underdeveloped. Target Córdoba and Málaga boutique networks with performance-formulated samples bypassing supermarket slotting fees. Exploit formulation talent scarcity among mid-tier incumbents to compress commercialization timelines.
For Investors and Strategic Acquirers: Nutri-Score A or B rating achievement by previously C-rated legacy brands is the leading indicator that reformulation capex cycles are generating sustainable shelf placement advantages. Position for 5-10 year horizon consolidation around cold-press extrusion capacity and first-party data platforms. Target domestic specialists with concentrated pharmacy and gym channel control as acquisition archetypes.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Extrusion Capacity Expansion | Preserves heat-sensitive micronutrients for clean-label differentiation against baked alternatives. |
| Direct-to-Consumer Platform Development | Bypasses El Corte Inglés and Carrefour slotting fees while capturing consumption data in Madrid. |
| Compostable Packaging Early Adoption | Positions brands for EU packaging waste directive extended producer responsibility schemes. |
| EFSA Health Claim Dossier Investment | Enables functional protein and fiber positioning commanding pharmacy channel premiums. |
| Andalusian Gym Network Penetration | Exploits underdeveloped modern trade infrastructure in Córdoba and Málaga for first-mover advantage. |
Research Methodology
Multi-period observation of EFSA nutrition claim authorizations, Nutri-Score placement algorithms, and boutique gym proliferation anchored the trend analysis, supplemented by interviews with energy bar brand managers, category buyers at El Corte Inglés, procurement leads at General Mills Inc. and Nestlé S.A., pharmacy channel directors, and cold-press extrusion equipment suppliers. Secondary validation drew from EFSA health claim registers, EU packaging waste directive drafts, Nielsen retail audit data, and Federación de Asociaciones de Celíacos de España certification records. Bottom-up volume modeling triangulated against top-down macroeconomic indicators.
Input-output matrices mapped formulation technology adoption, protein source substitution patterns, and channel migration flows across the projection horizon. Segmentation dimensions included product type, end-user consumption occasion, distribution channel economics, and price tier architecture. CAGRs were derived from regression analysis of historical premiumization trends and forward-looking regulatory compliance cost trajectories. Forecast inputs incorporated EFSA substantiation timelines and EU organic logo certification penetration curves.
Regulatory enforcement intensity shifts, California almond supply disruptions, and cold-press extrusion equipment lead time extensions are the dominant revision risks that could alter trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
North America Pretzel Market
Snacks
Europe Nuts and Cereal Snacks Bar Market
Snacks
Popcorn Market
Snacks
Low-Fat Tortillas Market
Snacks
Protein Bars Market
Snacks
United Kingdom Snack Bar Market
Snacks
Europe Extruded Snack Food Market
Snacks
On-The-Go Healthy Snacks Market
Snacks
Thailand Snack Bar Market
Snacks
Low Calorie Biscuits Market
Snacks
Asia Pacific Tortilla Market
Snacks
North America Potato Chips Market
Snacks
Low Calorie Granola Market
Snacks
Middle East and Africa Frozen Snacks Market
Snacks
Low Sugar Fruit Snacks Market
Snacks
United States Energy Bar Market