
 Low Calorie Peanut Sauce Market | 2026-2036
Low Calorie Peanut Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Peanut Sauce Market Analytics
Asset-light contract manufacturing is reconfiguring competitive entry barriers for emerging low calorie peanut sauce brands. PBfit leverages its powder-format specialization to sustain direct-to-consumer margins without captive production. San-J anchors its position through gluten-free certification depth and Japanese brewing heritage that commands premium placement. Hormel Foods competes via refrigerated distribution infrastructure extending into condiment adjacencies.
Low calorie peanut sauce denotes a reduced-fat emulsion of roasted peanut meal, vinegar, and alternative sweeteners typically formulated below 45 calories per serving, serving commercial kitchens and home cooks seeking flavor density without caloric load. Organic and sugar-free product types capture the fastest expansion as clean-label procurement standards tighten across foodservice accounts. Pouch packaging dominates unit velocity in online channels where shipping-weight economics favor flexible formats over glass bottles.
FDA nutrition labeling requirements and USDA organic certification standards shape formulation decisions and retail access for domestic suppliers. The EPA oversees wastewater compliance at peanut processing facilities upstream, influencing ingredient cost structures for sauce manufacturers. Stakeholders must monitor evolving sweetener approval pathways and state-level sugar tax proposals that could recalibrate product positioning.
Market Dynamics
Reformulation pressure from FDA nutrition labeling rules is compressing calorie thresholds across retail condiment portfolios, forcing manufacturers to re-engineer emulsion stability and sweetener systems simultaneously.
Growth Catalysts
- Urban Fitness Cluster Density:Metro areas with expanding boutique grocery formats are allocating dedicated shelf space to functional condiments. Los Angeles, New York, and Austin drive velocity through specialized retail placement.
- FDA Nutrition Label Transparency:Serving-size disclosure requirements push brands toward sub-45-calorie formulations. Reformulated SKUs gain preferred positioning in conventional retail accounts.
- Roasted Peanut Meal Processing Advances:Defatted peanut flour milling technologies improve flavor retention at reduced oil content. Commercial kitchens adopt these inputs for scaled sauce production.
Market Restraints
- Peanut Input Cost Volatility:Drought cycles in Georgia and Texas growing regions create raw material price instability. Sauce manufacturers absorb margin compression or reformulate with alternative legumes.
- Alternative Sweetener Approval Pathways:Novel low-calorie sweeteners face extended FDA GRAS determination timelines. Product development cycles stall awaiting regulatory clearance.
- Glass Bottle Shipping Economics:Weight-based freight costs disadvantage rigid packaging in direct-to-consumer channels. Pouch formats capture unit velocity despite lower brand visibility.
Strategic Opportunities
- Foodservice Clean-Label Procurement:Institutional buyers in K-12 and healthcare sectors mandate reduced-sugar condiment options. USDA organic certification unlocks access to these contract streams.
- Powder-Format Convenience Positioning:Dry mix formats reduce shipping weights and extend shelf stability. Backpacking and emergency-prep segments represent underdeveloped demand pockets.
- State-Level Sugar Tax Preparations:Pending legislation in California and New York creates first-mover advantage for pre-reformulated low-calorie portfolios. Early compliance builds retail relationship depth.
Industry Challenges
- Emulsion Stability Expertise Scarcity:Food science talent capable of maintaining mouthfeel at reduced fat content commands premium compensation. Smaller brands struggle to secure qualified formulation chemists.
- Dual Certification Timeline Compression:Simultaneous pursuit of USDA organic and gluten-free credentials extends product launch windows by 8-14 months. Working capital requirements strain emerging competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Peanut Sauce Market |
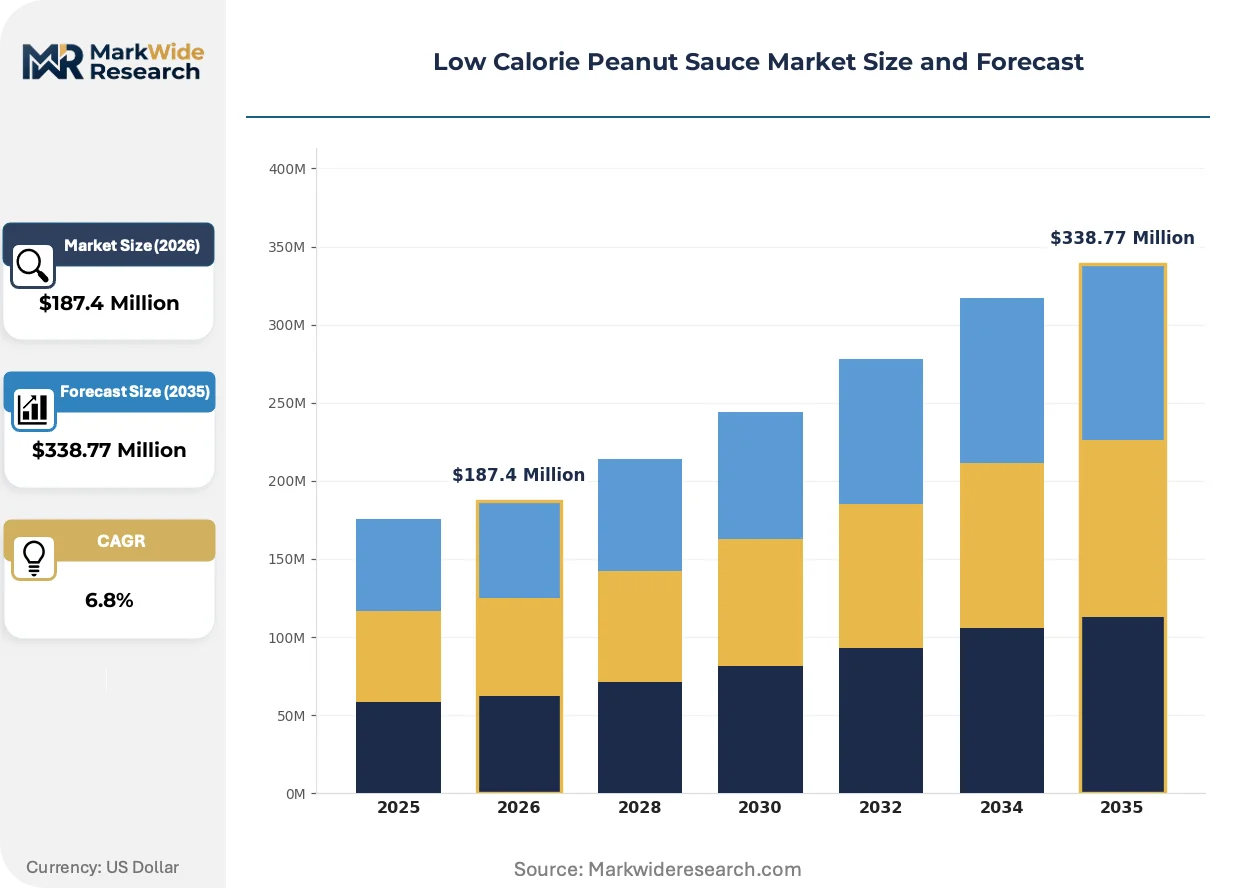
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Gluten-Free, Sugar-Free, Spicy End User: Fitness Enthusiasts, Health-Conscious Consumers, Restaurants, Food Retailers Packaging Type: Bottles, Pouches, Tubs, Sachets Distribution Channel: Online, Supermarkets, Specialty Stores, Convenience Stores |
| Companies Covered | Taste of Thai, San-J, Hormel Foods, McCormick & Company, Sun Luck, CJ Foods, Litehouse, Royal Pacific Foods, PBfit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Peanut Sauce Market Evolving Landscape
Digital traceability systems and alternative protein blending are restructuring how low-calorie peanut sauce moves from ingredient sourcing through final consumption, with packaging format innovation compressing traditional channel economics.
High-pressure processing equipment is digitizing quality assurance protocols across mid-scale sauce manufacturing operations. Regional co-packers in Texas and North Carolina deploy inline sensors that monitor emulsion stability in real-time. This infrastructure investment enables smaller brands to meet retailer food safety documentation requirements without captive laboratory facilities.
EPA wastewater compliance mandates at upstream peanut processing facilities are tightening discharge standards for oil and organic solids. Georgia and Alabama shelling operations face capital expenditure requirements for treatment system upgrades. Ingredient costs for sauce manufacturers reflect these environmental compliance investments through contracted peanut paste pricing adjustments.
Direct-to-consumer subscription models are displacing conventional retail replenishment cycles among fitness-oriented households. Specialty e-commerce platforms curate low-calorie condiment assortments with personalized macro-tracking integration. This channel shift concentrates highest-margin sales in coastal metro corridors where delivery density supports unit economics.
Low Calorie Peanut Sauce Market Segmentation
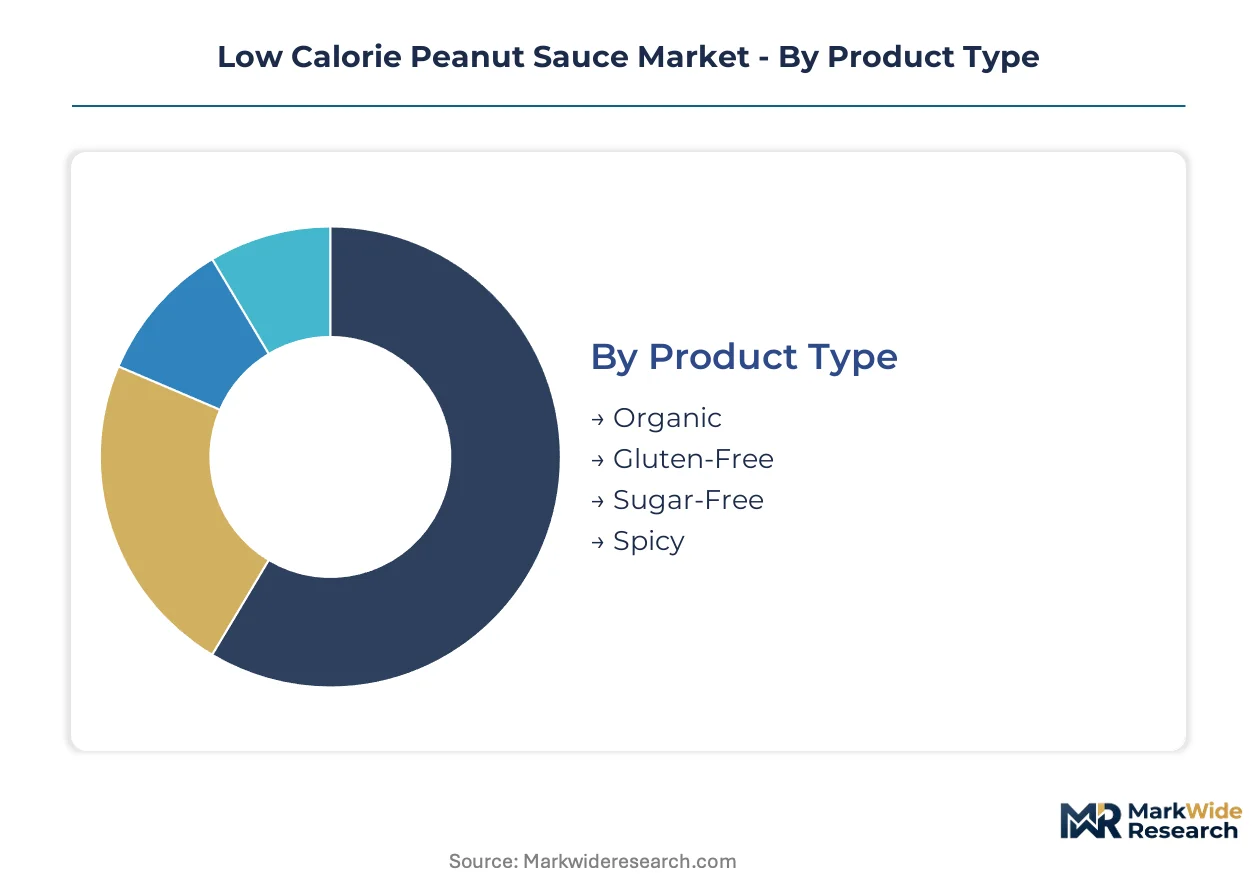
Segmentation in low calorie peanut sauce markets reveals distinct velocity patterns between health-driven premium tiers and convenience-oriented formats. Category boundaries blur as clean-label certifications compound and channel strategies fragment across direct-to-consumer and foodservice pathways.
Product Type:
Cycle times vary sharply across this category, with organic SKUs turning inventory slowest due to certification lead times while sugar-free variants refresh formulations fastest to chase evolving sweetener approvals.
- Organic:USDA-certified formulations require 18-24 month supplier qualification cycles and command shelf-space premiums in natural grocery channels. Demand concentrates in coastal metro households where disposable income supports certification markups. Supply bottlenecks at certified peanut shelling operations constrain volume scaling.
- Sugar-Free:Reformulated with monk fruit, allulose, or stevia blends to hit sub-5g sugar thresholds. Velocity runs highest in fitness-oriented e-commerce subscriptions where macro-tracking integration drives repeat purchase. FDA GRAS determinations for novel sweeteners stall some line extensions.
- Gluten-Free:Third-party tested formulations targeting celiac and wheat-sensitive populations. Restaurant and healthcare foodservice accounts mandate this specification for inclusive menu planning.
- Spicy:Chili-infused variants with Scoville-calibrated heat levels. Ethnic grocery and younger demographics in Texas and California metro clusters sustain niche velocity.
Organic dominates installed base. Sugar-Free is where expansion concentrates.
End User:
Customer archetypes in this market sort by procurement sophistication, with institutional buyers demanding documentation depth that individual consumers bypass entirely.
- Fitness Enthusiasts:Macro-tracking households purchasing through specialized e-commerce platforms with personalized nutrition integration. Los Angeles, Austin, and Miami metro corridors show highest per-capita consumption.
- Health-Conscious Consumers:Broad wellness-oriented households seeking clean-label condiments without strict dietary protocols. Supermarket perimeter placement and influencer endorsement drive trial conversion.
- Restaurants:Commercial kitchens requiring bulk formats with consistent emulsion stability across holding temperatures. USDA organic certification unlocks K-12 and healthcare contract eligibility.
- Food Retailers:Private-label procurement teams and category managers allocating shelf space based on velocity data and margin contribution. Pouch formats gain space in online-pickup fulfillment centers.
Health-Conscious Consumers anchor volume throughput. Fitness Enthusiasts is climbing the fastest.
Packaging Type:
Format selection in this category trades brand visibility against logistics economics, with weight and dimensional constraints dictating channel suitability.
- Pouches:Flexible film formats reducing shipping weights by 60-70% versus glass alternatives. Direct-to-consumer channels and backpacking specialty retailers favor this configuration despite lower shelf presence.
- Bottles:PET and glass containers preserving premium positioning in conventional retail. Brand recognition and pour control sustain placement in supermarket condiment aisles.
- Tubs:Wide-mouth containers targeting foodservice bulk procurement and commercial kitchen dispensing systems. Extended shelf stability requirements favor high-barrier plastic constructions.
- Sachets:Single-serve portions for foodservice condiment caddies and airline meal kits. Portion control specifications from institutional buyers drive format standardization.
Bottles retain dominant shelf presence. Pouches is gaining share fastest.
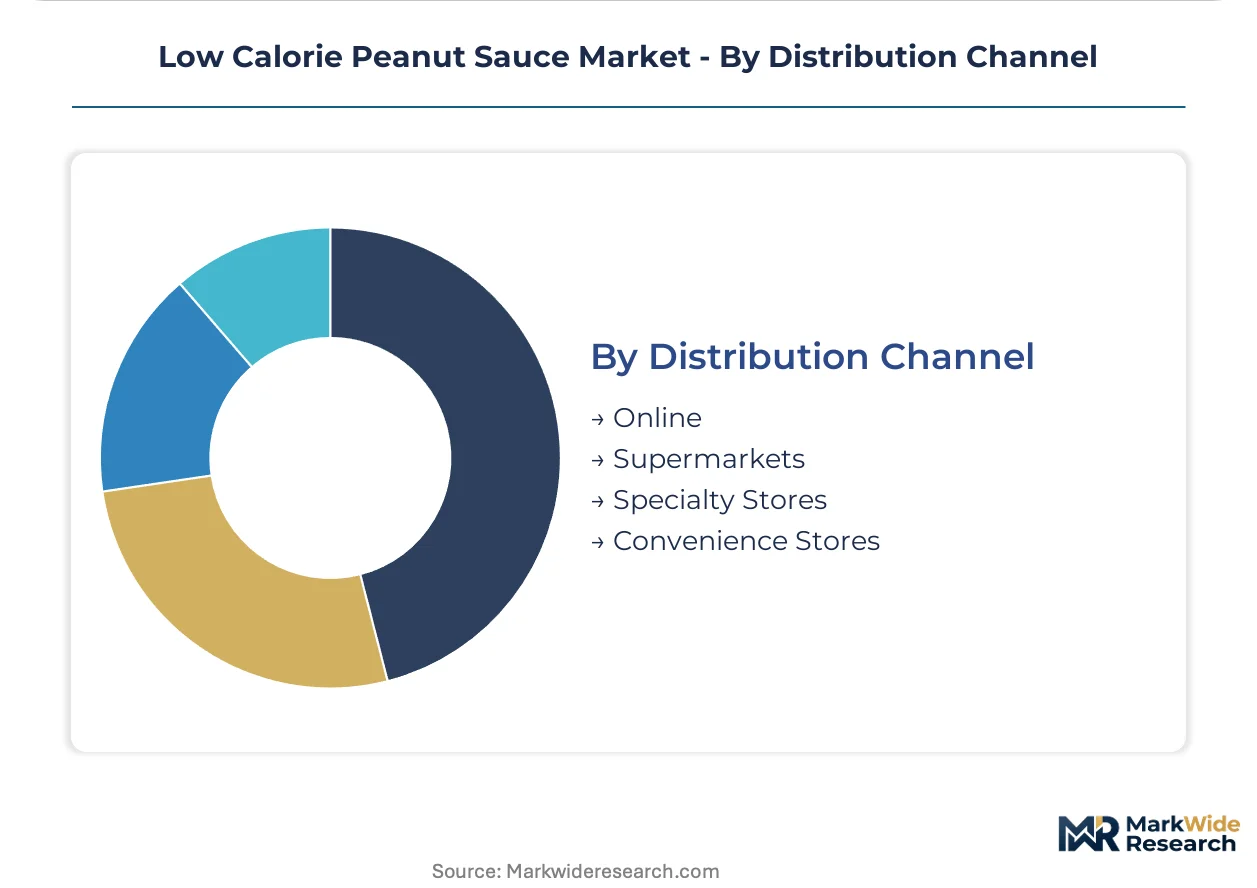
Distribution Channel:
Channel economics in low calorie peanut sauce diverge by fulfillment density and customer acquisition cost structures, with digital-native brands bypassing traditional slotting fee barriers.
- Online:Direct-to-consumer subscriptions and specialty e-commerce platforms curating functional condiment assortments. Coastal metro delivery density supports unit economics for refrigerated and ambient SKUs alike.
- Supermarkets:Conventional retail accounts demanding reformulated sub-45-calorie SKUs to meet FDA transparency positioning. Category management negotiations center on velocity guarantees and promotional calendar alignment.
- Specialty Stores:Natural grocery and boutique fitness retail formats with dedicated functional condiment sections. Staff education and sampling programs drive conversion in this high-touch environment.
- Convenience Stores:Grab-and-go placement for single-serve and travel-size formats. Urban commuter corridors and college-adjacent locations show strongest turn rates.
Supermarkets maintain broadest reach. Online is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness-oriented households cluster in coastal metro corridors where boutique grocery formats and direct-to-consumer delivery density support premium condiment adoption. Reformulation pressures from nutrition labeling mandates vary by jurisdiction, shaping where manufacturers prioritize low-calorie SKU launches.
United States
FDA nutrition labeling transparency rules compress calorie thresholds below 45 per serving, forcing reformulation of emulsion systems and sweetener blends. The EPA oversees wastewater discharge standards at Georgia and Texas peanut shelling facilities, passing compliance costs downstream. Los Angeles and New York metro areas drive velocity through specialized fitness retail placement and subscription e-commerce density.
Japan
Health-conscious consumers in Tokyo and Osaka metro areas demand clean-label condiments with reduced sugar profiles. METI guidelines on functional food labeling shape how manufacturers communicate calorie reduction claims. Kansai region brewing heritage anchors premium positioning for traditionally fermented sauce variants.
Germany
EU organic certification requirements under EFSA standards extend supplier qualification timelines for peanut paste inputs. The country's national food safety regulator enforces strict additive approval pathways for novel sweeteners. Berlin and Munich natural grocery channels allocate expanding shelf space to reduced-calorie ethnic condiments.
United Kingdom
Sugar tax proposals under Treasury consultation create first-mover incentives for pre-reformulated low-calorie portfolios. London and Southeast England concentrate demand through fitness-oriented direct-to-consumer platforms. National Health Service procurement standards for reduced-sugar options influence foodservice adoption.
Australia
FSANZ labeling standards mandate detailed added sugar disclosure, accelerating clean-label reformulation. Sydney and Melbourne metro fitness clusters sustain specialty e-commerce velocity for macro-tracking integrated condiments. Queensland peanut growing regions face water allocation pressures affecting input cost stability.
Low Calorie Peanut Sauce Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Refrigerated distribution infrastructure and gluten-free certification depth represent distinct moats. Three archetypes dominate: heritage Asian sauce specialists, diversified condiment conglomerates, and powder-format direct-to-consumer innovators. Strategic moves concentrate on co-manufacturing partnerships and state-level sugar tax compliance positioning.
Within the heritage specialist tier, San-J anchors premium placement through Japanese brewing credentials. PBfit occupies a position exemplifying asset-light powder-format specialization that bypasses captive production requirements. Hormel Foods sits within the diversified conglomerate archetype leveraging refrigerated logistics networks into condiment adjacencies.
| Leading Market Players |
|---|
| Taste of Thai |
| San-J |
| Hormel Foods |
| McCormick & Company |
| Sun Luck |
| CJ Foods |
| Litehouse |
| Royal Pacific Foods |
| PBfit |
| Others |
Value Network & Pricing Analysis
Undercapacity at USDA-certified peanut shelling operations in Georgia and Texas is tightening ingredient availability and pushing contract pricing upward for organic-tier sauce manufacturers. This utilization squeeze simultaneously compresses margins for mid-tier brands and accelerates consolidation toward vertically integrated processors with captive supply.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects USDA organic, gluten-free, and conventional grades respectively. Pricing pressure stems from drought-induced peanut input volatility and alternative sweetener approval delays. Foodservice buyers show highest price sensitivity due to volume procurement protocols, while fitness-oriented direct-to-consumer subscribers accept premium positioning for macro-tracking integration.
Supply Chain Analysis
Contract manufacturing concentrates with regional co-packers in Texas and North Carolina holding specialized high-pressure processing capacity. Ingredient sourcing draws from Georgia, Texas, and Alabama peanut growing regions with defatted flour milling clustered in the Southeast. Single-source vulnerability runs through certified organic shelling operations with limited supplier qualification. Distribution runs through refrigerated logistics networks for fresh formats and ambient parcel post for shelf-stable pouches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA nutrition labeling transparency and pending state-level sugar tax legislation are accelerating early-cycle adoption of reformulated low-calorie portfolios ahead of compliance deadlines.
For Market Incumbents: Pre-empt emerging powder-format specialists by securing exclusive co-manufacturing capacity at high-pressure processing facilities in Texas and North Carolina. Defend shelf position through accelerated dual certification timelines for USDA organic and gluten-free credentials before working capital constraints stall smaller competitors. For New Entrants and Emerging Players: Mid-market foodservice accounts in K-12 and healthcare sectors represent the most penetrable entry point given institutional procurement mandates for reduced-sugar options. Backpacking and emergency-prep segments offer underserved demand for dry-mix formats with extended shelf stability. Go-to-market through specialty e-commerce platforms with integrated macro-tracking APIs bypasses conventional retail slotting barriers. For Investors and Strategic Acquirers: Capital is best deployed toward asset-light powder-format specialists with direct-to-consumer margin structures and established subscription retention. Long-term viability hinges on formulation IP capable of maintaining emulsion stability below 45 calories per serving. Watch FDA GRAS determinations for novel sweeteners as the inflection signal for sugar-free line extension viability.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | USDA organic plus gluten-free credentials unlock K-12 and healthcare foodservice contract eligibility. |
| Powder-Format Line Extension | Dry mix configurations reduce shipping weights and capture backpacking segment demand with minimal capex. |
| Co-Manufacturing Partnership | Regional co-packer relationships in Texas bypass captive production requirements for emerging brands. |
| State Sugar Tax Pre-Positioning | Early reformulation to sub-45-calorie profiles builds retail relationship depth ahead of California and New York legislation. |
| Direct-to-Consumer Platform Launch | Subscription models with macro-tracking integration concentrate highest-margin sales in coastal metro corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA GRAS notifications, USDA organic certification databases, and EPA wastewater compliance records at peanut processing facilities. Primary inputs drew from interviews with condiment brand managers, foodservice procurement directors at K-12 districts, co-manufacturing operations managers, and retail category buyers. Secondary validation incorporated Nielsen retail audit data, customs import records for defatted peanut flour, and SEC filings from diversified condiment conglomerates. Bottom-up SKU velocity modeling and top-down category sizing triangulated volume estimates.
Forecast inputs span product type segmentation across organic, sugar-free, gluten-free, and spicy variants alongside packaging format and distribution channel dimensions. End-user archetypes modeled include fitness enthusiasts, health-conscious consumers, restaurants, and food retailers. CAGRs derived from trend extrapolation of reformulation adoption curves and channel shift velocity toward direct-to-consumer platforms. Industry-specific inputs incorporate FDA sweetener approval timelines and state-level sugar tax legislative tracking.
Macroeconomic conditions sit as an overlay; deviation in peanut commodity pricing, freight rate volatility, or consumer discretionary spending would shift the trajectory. Forecasts reflect assumptions regarding regulatory approval pathways and certification timeline stability. Quarterly review of FDA GRAS determination queues, drought monitoring for Georgia and Texas growing regions, and state legislative committee calendars is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Oyster Sauce Market
Condiments & Sauces
Vegan Sauces Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
Sweet and Savory Spread Market
Condiments & Sauces
Salad Dressings Market
Condiments & Sauces
Vegan Cheese Sauce Market
Condiments & Sauces
Vegan Sauces, Dressings and Spreads Market
Condiments & Sauces
Egg-Free Mayonnaise Market
Condiments & Sauces
Sauces and Condiments Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Sauces, Condiments, and Dressings Market
Condiments & Sauces
Low Fat Spaghetti Sauce Market
Condiments & Sauces
Condiments Market