
 Facade Materials Market | 2026-2036
Facade Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Facade Materials Market Foresight
Modular cladding packages is restructuring buyer procurement patterns across large-scale construction projects. Saint-Gobain leverages its integrated glass-to-insulation portfolio to capture bundled envelope contracts. Kingspan Group anchors its position through controlled manufacturing of insulated metal panel systems. Lindner Group specializes in precision-engineered unitized solutions for premium commercial towers.
Facade materials comprise the exterior envelope components—glass curtain walls, metal panels, stone cladding, and wood systems—engineered to manage thermal transmittance, air infiltration, and structural wind loads while defining architectural aesthetics. Glass dominates value capture in high-rise commercial towers where solar control coatings and low-emissivity laminates drive specification. Metal segments compete on speed of installation and recyclability credentials in industrial and logistics facilities. Unitized installation methods are displacing stick-built approaches on congested urban sites where labor constraints and weather sensitivity favor factory-controlled assembly.
China's MEE enforces dual carbon compliance through escalating building envelope performance codes. The EU Green Deal and F-Gas Regulation constrain hydrofluorocarbon use in insulated panel cores across European projects. Stakeholders must track how regulatory tightening in multiple jurisdictions reshapes material substitution patterns and supplier qualification requirements.
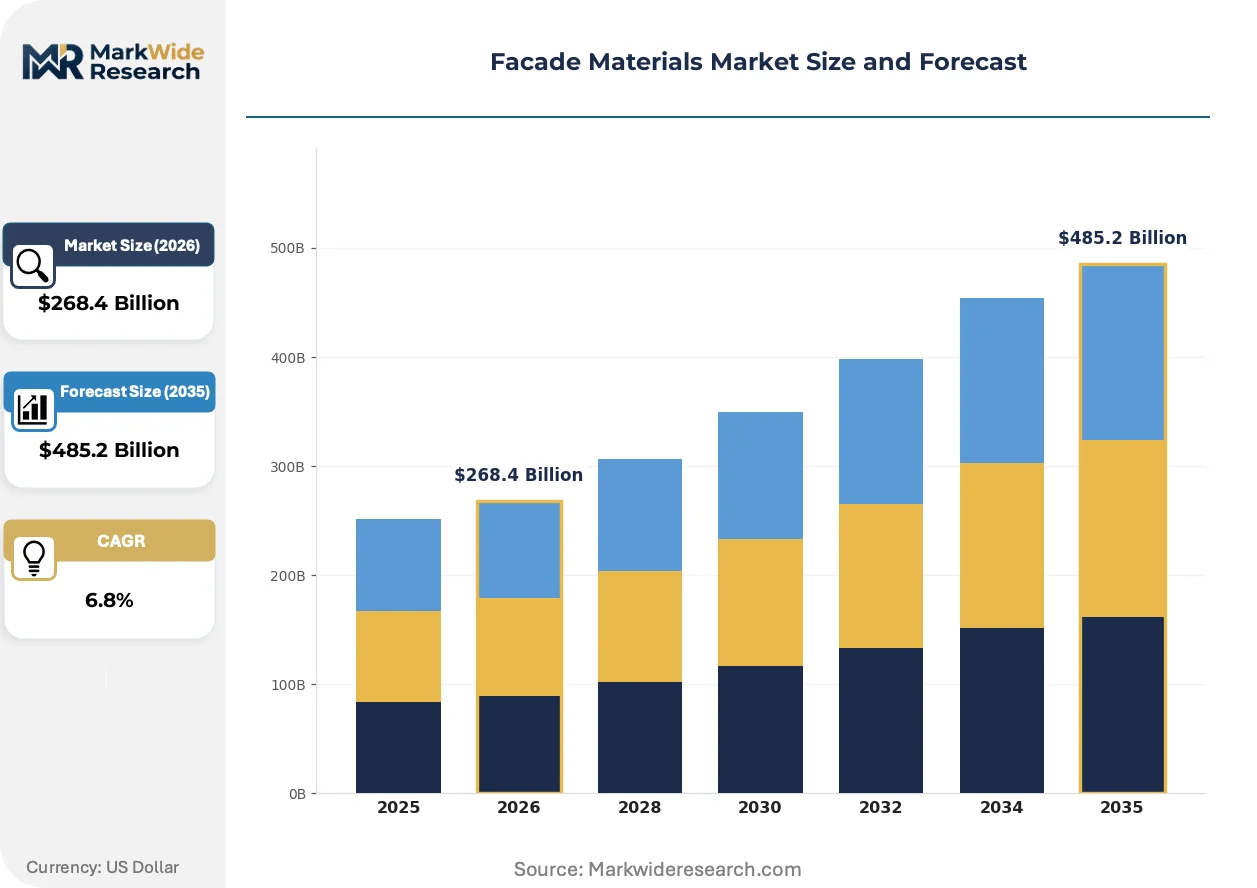
Market Dynamics
China's dual carbon goals enforced through MEE building envelope codes are compressing specification timelines and forcing rapid substitution toward high-performance composite systems. Developers now face binding energy intensity targets that eliminate conventional material options from commercial high-rise procurement.
Growth Catalysts
- MEE Performance Codes:China's escalating envelope thermal transmittance standards mandate triple-glazed unitized curtain walls in new commercial construction above 50,000 square meters.
- Logistics Facility Expansion:E-commerce fulfillment center construction across Germany and Poland drives specification of recyclable aluminum composite panels for speed-to-occupancy.
- Photovoltaic Integration:Building-integrated solar glazing is capturing facade surface area for energy generation in net-zero commercial towers.
Market Restraints
- Aluminum Price Volatility:LME aluminum input cost swings above 15% annually compress margin predictability for metal panel fabricators.
- Fluorinated Gas Constraints:EU F-Gas Regulation phase-down limits availability of high-performance blowing agents for insulated metal panel cores.
- Technical Limitation:Fire-rated glass above 60 minutes remains supply-constrained due to limited ion-exchange tempering furnace capacity.
Strategic Opportunities
- India Commercial Retrofit:BIS energy conservation building code expansion creates first-mover advantage for low-emissivity glazing in Mumbai and Bangalore office stock.
- Modular Hospital Construction:Controlled-environment panel systems address infection control and rapid deployment requirements in healthcare infrastructure.
- CSRD Reporting Alignment:EU corporate sustainability disclosure requirements position facade material suppliers with verified embodied carbon data to capture specification preference.
Industry Challenges
- Façade Engineer Shortage:Specialized curtain wall design capability concentrates in Shanghai, Milan, and Chicago, creating project bottleneck risk.
- Integration Complexity:Unitized systems require precision coordination between structural steel tolerances and glazing gasket compression specifications.
- Certification Timeline:CWCT sequence B testing for air and water penetration extends qualification cycles by 4-6 months for new system introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facade Materials Market |
| Market Size in 2026 | $268.4 Billion |
| Market Size in 2035 | $485.2 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Metal, Stone, Wood Application: Residential Buildings, Commercial Buildings, Industrial Facilities, Institutional Structures Installation Method: Pre-fabricated, Stick-built, Unitized, Rain Screen Finish Type: Polished, Textured, Coated, Painted |
| Companies Covered | Permasteelisa Group, Ramboll Group A/S, Saint-Gobain, Seele verwaltungs GmbH, Apogee Enterprises Inc, Lindner Group, Enclos Corp, Aluplex, Kingspan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facade Materials Market Shifts & Advancements
Active substitution between material categories is compressing traditional specification hierarchies. Performance verification protocols are tightening faster than supplier adaptation cycles.
Electrochromic glazing is consolidating daylight control and thermal management into single-surface solutions. High-rise developers in Singapore and San Francisco specify these systems to eliminate external shading hardware. This technology is consolidating mechanical HVAC load reduction claims into glazing performance warranties.
EU F-Gas Regulation constrains hydrofluorocarbon use in polyurethane insulated panel cores. European metal panel manufacturers accelerate hydrocarbon and hydrofluoroolefin alternative adoption. Cold-storage and food processing facilities face highest substitution pressure due to stringent thermal performance requirements.
Developer procurement teams now bundle envelope, MEP, and structural steel packages under single-contractor accountability. General contractors in London and Sydney absorb facade subcontractor risk to compress interface coordination. This reconfiguration transfers design liability upstream and compresses specialist fabricator margin negotiation leverage.
Facade Materials Market Segmentation
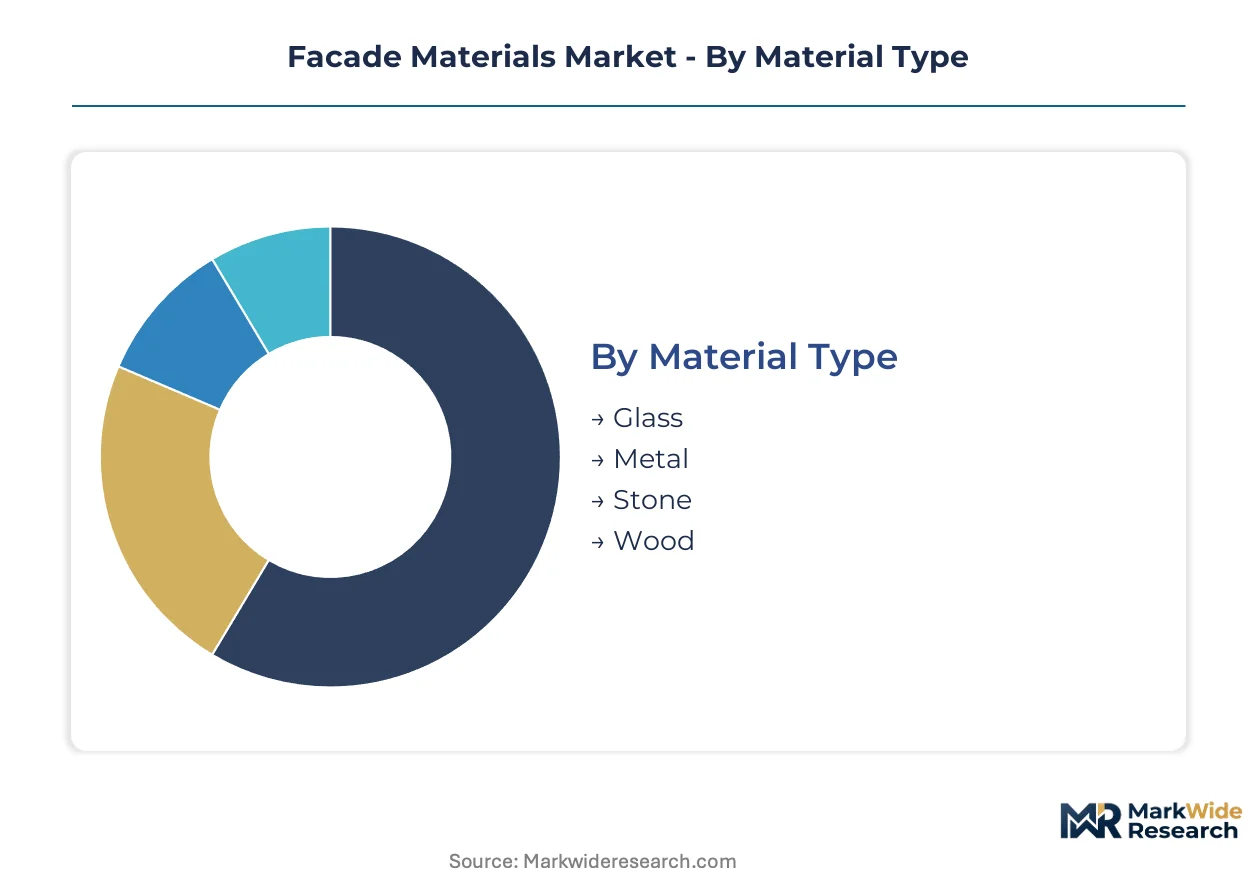
Facade material selection determines thermal performance certification pathways, installation labor requirements, and long-term maintenance obligations across building lifecycles. Specification committees weight material categories against envelope energy codes, structural wind loads, and aesthetic integration demands. Understanding segment boundaries clarifies where supplier qualification requirements diverge and procurement complexity concentrates.
Material Type:
Glass and metal systems carry distinct certification burdens: glass requires CWCT sequence B air-water penetration testing plus thermal transmittance verification, while metal panels face fire reaction class approvals under EN 13501-1. Stone and wood systems navigate regional quarry sustainability documentation and treated timber emission standards respectively.
- Glass:Low-emissivity coatings and solar control laminates manage thermal transmittance in high-rise commercial towers. MEE envelope codes in China mandate triple-glazed configurations for projects exceeding 50,000 square meters, compressing specification timelines toward unitized curtain wall systems.
- Metal:Aluminum composite panels and insulated metal systems compete on speed of installation and recyclability credentials. E-commerce fulfillment center construction across Germany and Poland drives specification for rapid enclosure in logistics corridors.
- Stone:Granite and limestone cladding systems anchor prestige commercial and institutional facades with natural material credentials.
- Wood:Cross-laminated timber and modified wood systems address carbon sequestration targets in Nordic residential and educational construction.
Leading the category by volume: Metal. Growing fastest: Glass.
Application:
End-use segments separate by performance warranty duration, facade access complexity, and tenant turnover exposure. Commercial towers demand 25-year system warranties with integrated maintenance protocols, while industrial facilities prioritize damage resistance and rapid panel replacement.
- Commercial Buildings:High-rise office and retail towers specify unitized curtain walls with integrated electrochromic glazing for daylight harvesting. Singapore and San Francisco developers eliminate external shading hardware through dynamic glass performance warranties.
- Industrial Facilities:Cold-storage and food processing construction across Europe faces F-Gas Regulation pressure on insulated panel core blowing agents, accelerating hydrocarbon alternative adoption.
- Residential Buildings:Multi-family housing concentrates rain screen and ventilated facade uptake for moisture management in temperate climates.
- Institutional Structures:Healthcare and education projects specify infection-control panel surfaces with accelerated deployment timelines.
Dominant by project value: Commercial Buildings. Expanding most quickly: Industrial Facilities.
Installation Method:
Method selection trades factory precision against site flexibility, with unitized and pre-fabricated systems requiring qualified installer networks that concentrate in Shanghai, Milan, and Chicago. Stick-built approaches retain relevance where structural tolerances or access constraints complicate module crane logistics.
- Unitized:Factory-assembled modules with integrated glazing and gaskets compress on-site labor exposure and weather risk. China's congested urban construction corridors favor this method where labor constraints and envelope performance codes tighten simultaneously.
- Pre-fabricated:Large-format panel systems with completed finishes reduce site activity duration for rapid-occupancy logistics and healthcare projects.
- Stick-built:Field-assembled components retain specification where project scale or structural irregularity defeats module standardization economics.
- Rain Screen:Ventilated cavity systems manage moisture drive in maritime and high-precipitation climates through pressure-equalized drainage.
Highest volume capture: Unitized. Steepest adoption climb: Pre-fabricated.
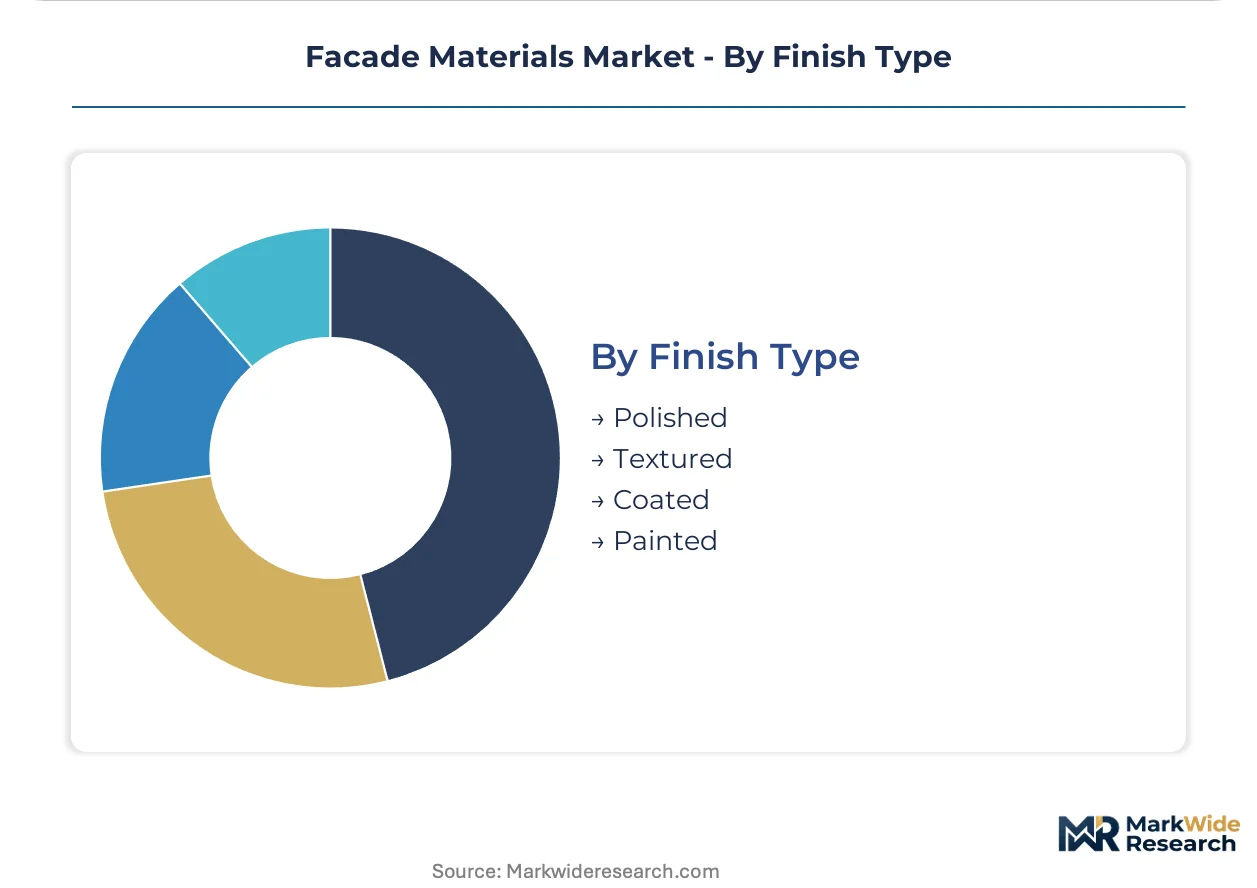
Finish Type:
Surface treatments differentiate by maintenance cycle intensity, solar reflectance requirements, and regional aesthetic conventions. Coated and painted finishes face volatile organic compound regulations that vary by manufacturing jurisdiction, while polished surfaces demand precision substrate preparation.
- Coated:Fluoropolymer and ceramic coatings deliver color stability and self-cleaning properties for high-rise access-challenged facades.
- Painted:Liquid and powder coating systems offer cost-efficient color customization with shorter lead times than anodized alternatives.
- Polished:Mirror and satin surface refinement concentrates in stone and metal applications for prestige commercial and institutional visibility.
- Textured:Embossed and patterned finishes manage glare and provide tactile variation in pedestrian-scale building zones.
Standard specification share: Coated. Gaining preference fastest: Textured.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Lingang Special Area and Germany's Industrieparks concentrate high-performance facade manufacturing capacity near deepwater ports and steel processing clusters. Tax incentives for green building materials accelerate facility placement in these zones.
China
Commercial tower construction in Shanghai and Shenzhen drives specification of triple-glazed unitized curtain walls. MEE building envelope performance codes mandate thermal transmittance thresholds that eliminate conventional glazing options. The Yangtze River Delta cluster hosts precision-engineered facade module assembly for domestic and export markets.
Germany
E-commerce fulfillment center construction across the Rhine-Ruhr and Bavaria accelerates demand for recyclable aluminum composite panels. EU F-Gas Regulation constrains hydrofluorocarbon use in insulated panel cores, forcing blowing agent substitution. Stuttgart and Munich engineering consultancies specialize in unitized system integration for premium commercial towers.
United States
High-rise development in San Francisco and New York specifies electrochromic glazing to eliminate external shading hardware. Local energy codes in California and New York City tighten envelope performance requirements faster than federal standards. Chicago anchors North American curtain wall engineering capability with specialized design firms concentrated in the Loop district.
India
Office stock retrofit in Mumbai and Bangalore creates demand for low-emissivity glazing as BIS energy conservation building codes expand to commercial structures. PLI scheme incentives for green building materials attract domestic manufacturing investment. The Delhi-Mumbai Industrial Corridor clusters facade component fabrication near logistics hubs.
Singapore
Net-zero commercial tower development drives building-integrated photovoltaic glazing adoption for energy generation. BCA Green Mark certification mandates stringent envelope thermal performance for new construction above 2,000 square meters. The Jurong Innovation District concentrates facade system testing and R&D facilities.
Facade Materials Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material categories and installation methods. Market structure tilts toward consolidation in glass processing and fragmentation in metal panel fabrication. Three archetypes dominate: integrated material-to-system suppliers, precision engineering specialists, and scale-driven panel fabricators. M&A activity concentrates on glazing technology assets, while capacity expansion targets hydrocarbon blowing agent conversion for EU regulatory compliance.
Among European-based fabricators, Saint-Gobain and Kingspan Group exemplify the integrated material-to-system archetype through captive glass and insulation supply chains. Lindner Group occupies a position within the precision engineering tier, specializing in unitized solutions for premium commercial applications. These three companies represent contrasting strategic postures on vertical integration depth and project-scale targeting.
| Leading Market Players |
|---|
| Permasteelisa Group |
| Ramboll Group A/S |
| Saint-Gobain |
| Seele verwaltungs GmbH |
| Apogee Enterprises Inc |
| Lindner Group |
| Enclos Corp |
| Aluplex |
| Kingspan Group |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between CWCT-tested unitized systems and commodity stick-built alternatives manifests in both 40-60% procurement cost spreads and supplier qualification bottlenecks that concentrate fabrication capacity in Shanghai, Milan, and Chicago. MEE envelope code compliance in China and EU F-Gas Regulation adherence in Europe create tiered supplier pools where certified fabricators command project premiums while uncertified competitors face specification exclusion.
Pricing Analysis
Short lead-time premiums of 15-25% apply to unitized curtain wall modules with CWCT sequence B certification, while spot inventory of non-certified aluminum composite panels trades at discounts. Project-based pricing dominates, with differentiation driven by thermal performance grade and MEE/F-Gas regulatory compliance tier. Cost compression in standard-grade metal panels intensifies due to LME aluminum volatility. Logistics developers in Germany and Poland show highest price sensitivity; premium commercial tower developers in Singapore and San Francisco exhibit lowest.
Supply Chain Analysis
Skilled facade engineer scarcity in Shanghai, Milan, and Chicago constrains module output expansion despite capital availability. Manufacturing concentrates in China, Germany, and the United States, drawing from float glass, aluminum extrusion, and polyurethane core feedstocks. Single-source vulnerability runs through ion-exchange tempering furnace capacity for fire-rated glass above 60 minutes. Distribution runs through general contractors absorbing subcontractor risk in London and Sydney.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facade materials function as a cost-of-compliance market where MEE building envelope codes and EU F-Gas Regulation erect qualification barriers that protect incumbent positions from price-based competition. Regulatory moats deepen as certification timelines extend and testing capacity concentrates.
For Market Incumbents: Cement market position through captive control over CWCT testing relationships and triple-glazed unitized production lines. Defend against hydrocarbon blowing agent substitution pressure by accelerating EU regulatory-compliant core manufacturing. Prioritize capacity addition in Yangtze River Delta clusters serving domestic and export demand.
For New Entrants and Emerging Players: Mid-tier office retrofit projects in Mumbai and Bangalore offer specification entry points where BIS code expansion outpaces established supplier presence. Target healthcare modular construction for infection-control panel demand with accelerated deployment requirements. Pursue partnership routes with general contractors absorbing facade risk in bundled procurement structures.
For Investors and Strategic Acquirers: Re-rating potential sits with hydrocarbon-ready insulated panel fabricators given EU F-Gas Regulation phase-down timelines. Five-to-ten year viability favors suppliers with verified embodied carbon data aligned to CSRD disclosure requirements. Monitor CWCT testing queue lengths as inflection signal for qualification bottleneck severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Float Glass Supply | Saint-Gobain's captive glass production secures thermal coating capacity for MEE-compliant triple-glazed units. |
| Hydrocarbon Blowing Agent Conversion | Kingspan's polyurethane core retooling addresses EU F-Gas Regulation constraints on cold-storage panel specifications. |
| CWCT Testing Capacity Expansion | Lindner's sequence B certification pipeline compression accelerates premium tower project capture in Milan and Chicago. |
| Building-Integrated Photovoltaic Glazing Partnership | Singapore BCA Green Mark compliance drives net-zero tower specification for energy-generating facade surfaces. |
| Modular Healthcare Panel System Launch | Controlled-environment fabrication addresses infection control and rapid deployment in European hospital infrastructure. |
Research Methodology
Multi-period observation of MEE code enforcement timelines, EU F-Gas Regulation implementation phases, and CWCT certification queue lengths anchored the trend analysis, supplemented by interviews with curtain wall engineering directors, general contractor procurement leads, facade fabricator plant managers, and healthcare facility development officers. Secondary validation drew from MEE policy circulars, EU regulatory filings, CWCT test result databases, and construction project tender records. Bottom-up project pipeline assessment and top-down envelope spend allocation triangulated market sizing.
Input-output matrices modeled material type, application end-use, installation method, and finish type dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against regulatory enforcement calendars and construction starts data. Forecast inputs incorporated aluminum LME price trajectory assumptions and hydrocarbon blowing agent adoption curves.
Revisions become necessary when MEE code enforcement intensity shifts, EU F-Gas Regulation phase-down accelerates, or ion-exchange tempering furnace capacity expands materially. Forecasts reflect documented assumptions on regulatory timelines and substitution elasticity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Red Brick Market
Building & Construction Materials
Oriented Strand Board (OSB) Market
Building & Construction Materials
Europe Construction Chemicals Market
Building & Construction Materials
Garage and Overhead Doors Market
Building & Construction Materials
Roofing Underlay Market
Building & Construction Materials
India Pipe Fabrication Market
Building & Construction Materials
Balustrade Market
Building & Construction Materials
Storefront Glass Market
Building & Construction Materials
Sanitary Ware Market
Building & Construction Materials
Pervious Concrete Market
Building & Construction Materials
Prefabricated Bathroom Modules Market
Building & Construction Materials
Foldable Container House Market
Building & Construction Materials
Limestone Aggregates Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
China Concrete Superplasticizer Market
Building & Construction Materials
Particleboard Market