
 Steel Casing Pipes Market | 2026-2036
Steel Casing Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Casing Pipes Market Analytics
API 5CT P110 and Q125 premium-grade specifications is unwinding legacy procurement patterns across the steel casing pipes sector. Tenaris leverages integrated seamless mills in Argentina and Mexico to sustain cost discipline on high-yield grades. Vallourec anchors European supply for sour-service applications through its French and German facilities. Nippon Steel Corporation dominates East Asian premium casing demand with advanced quench-and-temper capabilities.
Steel casing pipes are thick-walled tubular products manufactured from carbon or low-alloy steel, typically produced through seamless extrusion or electric-resistance welding to achieve burst pressures exceeding 10,000 psi in downhole environments. Their primary purpose is to stabilize wellbore walls, isolate formation fluids, and contain annular pressure throughout drilling, completion, and production operations. Seamless products command the dominant margin pool due to superior reliability in high-pressure sour wells, while welded variants compete aggressively on cost in standard onshore applications. Oil and Gas end users generate the largest volume commitment, though Infrastructure and Geothermal segments are expanding fastest as civil tunneling and binary power projects multiply.
API 5CT standards govern North American material certification, while EU Pressure Equipment Directive and REACH chemical compliance constrain European import sourcing. China's GB/T 19830 and NMPA-equivalent quality protocols shape domestic procurement for state-directed drilling campaigns. Stakeholders must monitor regulatory divergence between API sour-service protocols and emerging hydrogen embrittlement test methods before committing to long-dated mill contracts.
Market Dynamics
Deepwater drilling programs are forcing API 5CT specification upgrades across mill portfolios as operators target reservoirs below 15,000 feet. This pressure cascade from exploration depth to metallurgical complexity is restructuring procurement relationships between oilfield service companies and seamless pipe producers.
Growth Catalysts
- API 5CT sour-service grade mandates:North American regulators are tightening H2S corrosion resistance requirements for Permian Basin production, compelling replacement of legacy P110 inventory with enhanced Q125 and super-13Cr grades.
- Pre-salt carbonate formations:Brazil's offshore Santos Basin is driving demand for premium casing with collapse ratings exceeding 12,000 psi, requiring seamless products with controlled yield-strength scatter.
- Enhanced geothermal systems:Binary power projects in Nevada and Iceland are specifying high-chromium alloys for 300°C brine environments, opening volume commitments outside traditional oil and gas.
Market Restraints
- Scrap steel price volatility:Electric-arc furnace operators face margin compression when shredded auto scrap exceeds seamless billet conversion economics, particularly affecting welded casing competitiveness.
- Quench-and-temper capacity concentration:Premium heat-treatment capability clusters in Japan, Germany, and Argentina, creating geographic single-source risk for high-yield sour-service orders.
- Hydrogen embrittlement testing gaps:Absence of standardized ISO protocols for H2-compatible casing steels delays certification timelines for carbon capture and hydrogen storage applications.
Strategic Opportunities
- Carbon capture well construction:EPA Class VI injection well rules are mandating corrosion-resistant casing for CO2 sequestration projects, creating new specification demand in the US Gulf Coast.
- Tunnel boring machine segment:Urban metro expansion in India and Saudi Arabia is specifying thick-walled casing for ground stabilization, diverting mill capacity from hydrocarbon applications.
- Digital thread integration:Blockchain-tracked mill certificates are enabling premium pricing for full-provenance seamless products in North Sea decommissioning-sensitive fields.
Industry Challenges
- Non-destructive testing technician scarcity:Ultrasonic and electromagnetic inspection certification programs cannot match recruitment needs for high-specification sour-service production lines.
- API 5CT edition transition friction:Mills face simultaneous compliance with 2023 specification revisions while fulfilling legacy purchase orders tied to 2018 standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Casing Pipes Market |
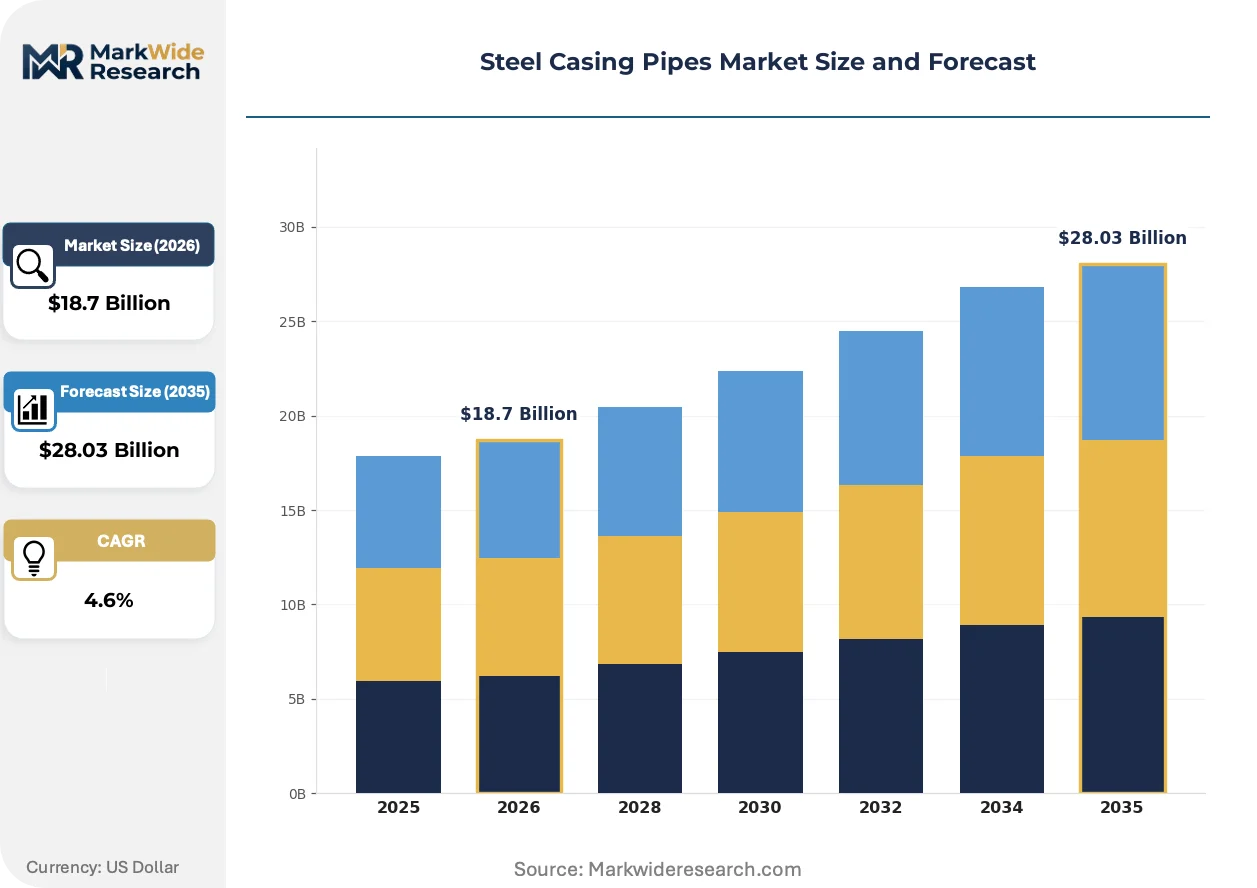
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless, Welded, Spiral, Lined Application: Oil Extraction, Water Wells, Structural Supports, Geothermal End User: Oil & Gas, Construction, Mining, Infrastructure Manufacturing Stage: Raw Material, Finished Goods, Intermediate Products, Specialty Items |
| Companies Covered | ArcelorMittal, United States Steel Corporation, Nippon Steel Corporation, Tata Steel, Jindal Steel & Power, Tenaris, Nucor Corporation, TMK, Vallourec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Casing Pipes Market Evolving Landscape
Metallurgical innovation is compressing the performance gap between welded and seamless products while digital certification tools are shortening qualification timelines for new mill entrants.
Advanced quench-and-temper process control is fragmenting the traditional seamless premium segment. Continuous cooling transformation modeling now permits welded producers to achieve yield-strength consistency within 5% scatter bands. North American distributors are qualifying these enhanced electric-resistance welded products for intermediate-pressure gas wells. The technology is fragmenting procurement pools that historically reserved seamless grades for all sour-service applications.
EU REACH chemical compliance is constraining import sourcing for European offshore projects. The regulation mandates full material disclosure for chromium and molybdenum alloying elements above 0.1% threshold. North Sea operators are responding by consolidating purchase orders with mills holding ECHA-registered substance portfolios. This regulatory friction is compressing the qualified supplier base for Barents Sea exploration campaigns.
Operator consortiums are consolidating technical specifications into unified procurement frameworks. Majors in the Permian Basin are harmonizing collapse-test protocols across previously distinct drilling divisions. Third-party inspection houses are displacing mill-direct certification for critical well applications. This consolidation is most visible in Texas and New Mexico, where standardized sourcing is reducing qualification overhead for multi-rig development programs.
Steel Casing Pipes Market Segmentation
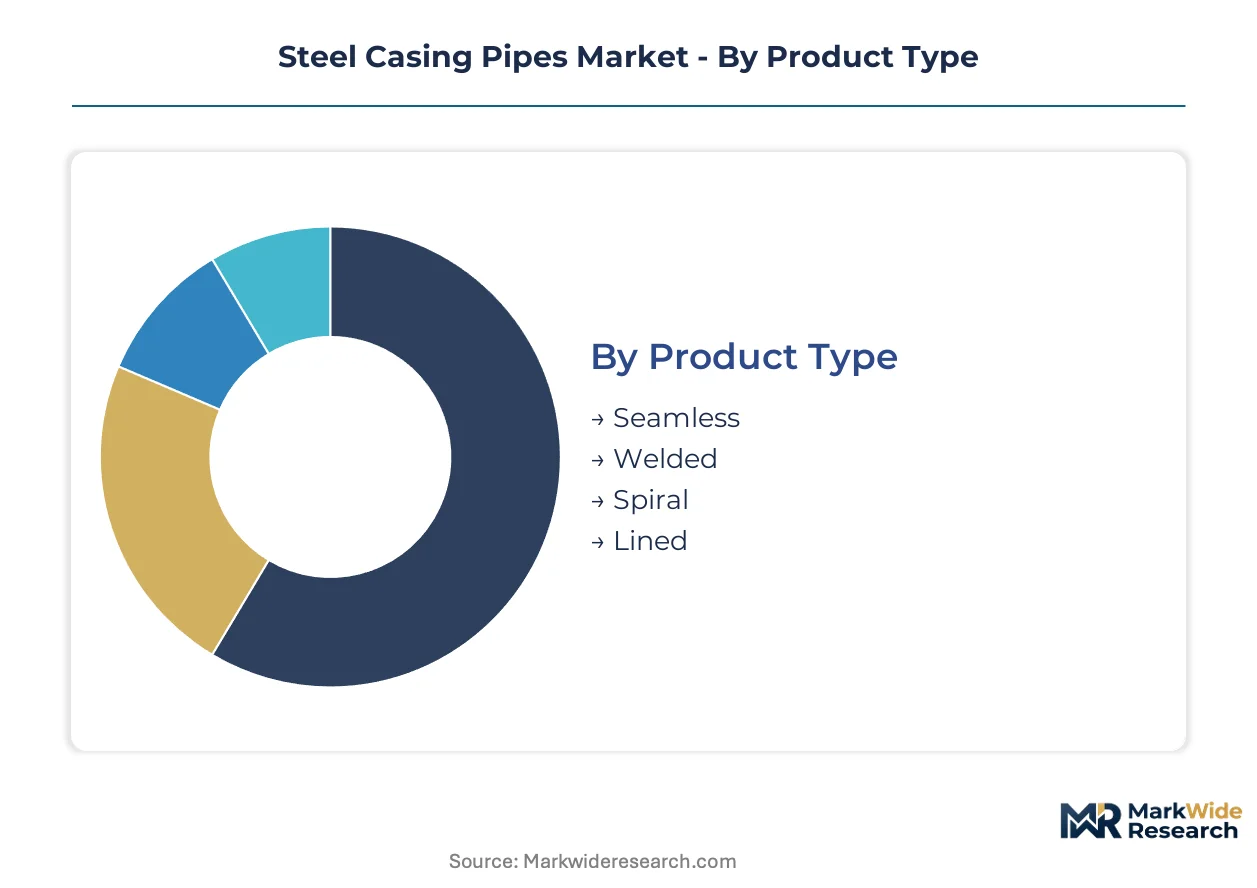
Steel casing pipe procurement splits across metallurgical grades, pressure ratings, and corrosion specifications that determine mill qualification requirements. Regulatory divergence between API sour-service protocols and emerging hydrogen embrittlement standards is fragmenting supplier eligibility across end-use categories.
Product Type:
API 5CT certification tiers separate seamless mills from welded competitors in sour-service procurement pools.
- Seamless:Produced through rotary piercing and extrusion of solid billets to achieve uniform wall thickness without longitudinal weld seams. Demand concentrates in Brazil's Santos Basin pre-salt formations where collapse ratings must exceed 12,000 psi for reservoirs below 15,000 feet.
- Welded:Manufactured via electric-resistance welding or submerged-arc processes from hot-rolled coil feedstock. North American distributors are qualifying enhanced ERW products for intermediate-pressure gas wells as continuous cooling transformation modeling tightens yield-strength scatter bands.
- Spiral:Helical seam construction from coiled strip enables large-diameter production for low-pressure water transmission and piling applications.
- Lined:Internal polymer or corrosion-resistant alloy coatings extend service life in CO2 injection and geothermal brine environments.
Established volume favors Seamless; emerging adoption favors Welded.
Application:
Pressure containment requirements scale with reservoir depth and formation chemistry across extraction environments.
- Oil Extraction:Primary demand driver spanning conventional onshore, unconventional shale, and deepwater offshore drilling programs. API 5CT specification revisions are compelling replacement of legacy P110 inventory with enhanced Q125 grades in Permian Basin H2S zones.
- Geothermal:Binary power projects in Nevada and Iceland specify high-chromium alloys for 300°C brine circulation systems. This segment climbs the fastest as renewable baseload capacity expands outside hydrocarbon applications.
- Water Wells:Municipal and agricultural groundwater extraction employs standard carbon steel grades with cement bond requirements.
- Structural Supports:Foundation piling and micropile applications compete for mill capacity with energy sector orders.
Revenue concentration sits with Oil Extraction; specification innovation concentrates in Geothermal.
End User:
Procurement scale and technical qualification thresholds vary sharply across industrial buyer categories.
- Oil & Gas:Integrated operators and drilling contractors generate the largest volume commitments with mill-direct contracting for premium grades. Sour-service mandates from North American regulators are tightening material standards for Permian Basin development.
- Infrastructure:Urban metro expansion in India and Saudi Arabia is specifying thick-walled casing for tunnel boring machine ground stabilization, diverting capacity from hydrocarbon applications.
- Construction:Building foundation and marine structure applications consume standard welded grades through distributor channels.
- Mining:Shaft sinking and dewatering operations require corrosion-resistant specifications for acidic groundwater conditions.
Contract value concentrates with Oil & Gas; project velocity favors Infrastructure.
Manufacturing Stage:
Value capture points diverge between commodity feedstock and certified finished goods.
- Finished Goods:Heat-treated, threaded, and inspected products commanding premium pricing through full API 5CT traceability. Mills in Japan, Germany, and Argentina dominate high-yield sour-service heat-treatment capacity.
- Specialty Items:Premium connections, expandable casing, and corrosion-resistant alloy grades for ultra-deepwater and CO2 sequestration applications.
- Raw Material:Seamless billets and hot-rolled coil positioned for third-party processing or integrated mill consumption.
- Intermediate Products:Unfinished pipe requiring additional heat treatment, threading, or inspection services.
Margin retention favors Finished Goods; supply security concerns elevate Specialty Items.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil and the United States show the lowest price elasticity, absorbing premium grades for deepwater pre-salt and sour-service applications. Indian and Chinese procurement remains highly elastic, favoring welded alternatives and domestic GB/T-certified inventory.
United States
Permian Basin operators are replacing legacy P110 casing with Q125 and super-13Cr grades under tightening EPA sour-service mandates. The EPA's Class VI injection well rules are mandating corrosion-resistant specifications for CO2 sequestration projects across the Gulf Coast. Houston anchors North American procurement consolidation, where majors harmonize collapse-test protocols across multi-rig development programs.
Brazil
Pre-salt carbonate formations in the Santos Basin drive demand for seamless casing with collapse ratings exceeding 12,000 psi. ANP regulatory frameworks enforce stringent material traceability for ultra-deepwater completions. Rio de Janeiro concentrates engineering and procurement functions for Petrobras-directed drilling campaigns.
China
State-directed drilling campaigns under NMPA-equivalent quality protocols shape domestic procurement for shale gas development in Sichuan and Tarim basins. GB/T 19830 standards govern material certification, constraining import sourcing for critical sour-service applications. Shanghai and Tianjin cluster trading and distribution infrastructure for both domestic mills and strategic petroleum reserve injection projects.
Germany
North Sea decommissioning-sensitive fields are consolidating purchase orders with mills holding ECHA-registered substance portfolios under EU REACH chemical compliance. The EU Pressure Equipment Directive constrains import sourcing for Barents Sea exploration campaigns. Düsseldorf-Ruhr industrial corridor hosts heat-treatment capacity and third-party inspection houses displacing mill-direct certification.
India
Urban metro expansion in Mumbai and Delhi is specifying thick-walled casing for tunnel boring machine ground stabilization, diverting mill capacity from hydrocarbon applications. BIS quality protocols govern infrastructure-grade procurement while oil and gas sourcing follows API 5CT with domestic content preferences. Gujarat and Maharashtra host integrated seamless mills serving Middle East export markets.
Steel Casing Pipes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the steel casing pipes sector. Seamless producers with quench-and-temper capabilities capture premium margins in sour-service and ultra-deepwater segments, while welded specialists compete on conversion economics for standard onshore gas wells. The market structure tiers into integrated metallurgical specialists, regional welded fabricators, and state-affiliated national champions. Dominant competitive moves include capacity expansion in heat-treatment capabilities and strategic partnerships for digital certification platforms.
Among integrated seamless specialists, Tenaris, Vallourec, and Nippon Steel Corporation occupy positions defined by geographic heat-treatment clustering and sour-service qualification depth. Tenaris exemplifies the vertically integrated Latin American archetype with seamless mill control across Argentina and Mexico. Vallourec anchors European supply for REACH-constrained North Sea applications. Nippon Steel Corporation represents East Asian premium casing capability through advanced metallurgical process control. These three entities illustrate how quench-and-temper capacity concentration in Japan, Germany, and Argentina creates geographic single-source risk for high-yield orders.
| Leading Market Players |
|---|
| ArcelorMittal |
| United States Steel Corporation |
| Nippon Steel Corporation |
| Tata Steel |
| Jindal Steel & Power |
| Tenaris |
| Nucor Corporation |
| TMK |
| Vallourec |
| Others |
Value Network & Pricing Analysis
Six-month order backlogs for Q125 sour-service grades signal supply-chain rigidity that hands pricing power to mills with certified heat-treatment capacity in Japan, Germany, and Argentina. This lead-time compression reinforces premium capture for seamless producers while forcing welded competitors toward aggressive spot-market discounting.
Pricing Analysis
After-market threading and inspection services now generate lifetime value exceeding original pipe sales for ultra-deepwater deployments. Three-tier pricing structure across premium API Q125, standard P110, and economy welded grades anchors contract negotiations, with differentiation resting on H2S certification depth and mill-direct traceability. Cost compression in welded segments is intensifying because electric-arc furnace operators face shredded scrap volatility against seamless billet economics. National oil companies in Brazil and the United States show the lowest price elasticity, while Indian infrastructure buyers drive hard volume discounts.
Supply Chain Analysis
Inventory buffers for super-13Cr alloys rarely exceed 45 days given concentrated quench-and-temper capacity in Japan, Germany, and Argentina. Raw material flows draw from Brazilian iron ore fines, Australian metallurgical coal, and Venezuelan heavy crude for seamless billet production. Single-source vulnerability concentrates in premium heat-treatment capability for collapse ratings above 12,000 psi. Distribution runs through Houston trading houses for North American oilfield service companies and through Rotterdam for North Sea offshore campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steel casing procurement is approaching a platform-economics inflection as blockchain-tracked mill certificates enable premium pricing for full-provenance products, interoperability between operator consortiums and third-party inspection houses.
For Market Incumbents: Fortify sour-service qualification depth through captive heat-treatment investments in Argentina or Germany, insulating against emerging welded-product metallurgical advances. Consolidate channel control by displacing mill-direct certification with third-party inspection partnerships in North Sea decommissioning-sensitive fields.
For New Entrants and Emerging Players: Differentiate on digital certification integration for carbon capture well construction, where EPA Class VI rules create specification whitespace outside traditional oil and gas procurement pools. Target geothermal binary power projects in Nevada and Iceland with high-chromium alloy sourcing from non-traditional feedstock channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated steel majors seeking to divest non-core oilfield tubular divisions amid energy transition portfolio rebalancing. Five-to-ten year viability hinges on hydrogen storage certification readiness; watch for ISO protocol finalization on hydrogen embrittlement testing as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treatment Capacity Expansion | Captures premium margin pool for Q125 and super-13Cr sour-service grades in Permian Basin. |
| Digital Certification Platform Partnership | Enables blockchain-tracked provenance pricing for North Sea decommissioning-sensitive fields. |
| Backward Integration into Seamless Billet Supply | Secures feedstock against scrap volatility for electric-arc furnace welded casing competitors. |
| Geothermal Alloy Qualification Program | Opens volume commitments outside hydrocarbon applications for 300°C brine environments. |
| Third-Party Inspection House Acquisition | Displaces mill-direct certification and captures value from operator consortium consolidation. |
Research Methodology
Initial hypotheses were tested against primary input from drilling engineers at national oil companies, procurement directors at oilfield service companies, metallurgical quality managers at seamless mills, and aftermarket threading facility operators, then refined against customs trade data, API certification registries, SEC 10-K filings from listed tubular producers, and EPA injection well permit databases. Bottom-up volume estimates from mill capacity utilization and top-down demand calibration from rig count trajectories were triangulated to anchor forecast ranges.
Variance decomposition across product type, metallurgical grade, pressure rating tier, corrosion specification, and end-use application shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate blending weighted by revenue contribution. Forecast inputs incorporated pre-salt drilling campaign schedules from Brazil's ANP, Permian Basin sour-service regulatory timelines from EPA regional offices, and geothermal project development pipelines from Nevada Bureau of Land Management filings.
The analysis sits within stated boundaries; outcomes outside sustained offshore capital commitment or accelerated hydrogen storage infrastructure buildout would require recalibration. Forecasts reflect documented assumptions on specification transition timelines and scrap-to-billet conversion economics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Insulated Metal Panels Market
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Roofing Materials Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
Architectural Acoustic Panels Market
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
Asphalt Shingles Market
Building & Construction Materials
Technical Insulation Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
Remodeling Market
Building & Construction Materials
Composite Insulated Panels Market
Building & Construction Materials
Architectural Window Films Market
Building & Construction Materials
Lightweight Composite External Access Panels and Doors Market
Building & Construction Materials
Glass Tiles Market
Building & Construction Materials
Europe Faucet Market