
 Railway Ballast Binder Market | 2026-2036
Railway Ballast Binder Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Ballast Binder Market Analytics
German chemical producers is shifting capacity toward railway-grade polymer systems as infrastructure budgets expand across OECD rail networks. BASF leverages its polyurethane expertise to anchor European supply for high-speed track stabilization. Sika AG competes through specialized epoxy resin formulations designed for extreme climate rail corridors. Henkel AG & Co. KGaA differentiates via adhesive technologies that sustain performance under cyclic loading conditions.
Railway ballast binder denotes engineered binding agents—typically cementitious, bituminous, or polymer-based compounds with compressive strengths exceeding 25 MPa—that chemically or physically consolidate loose aggregate to prevent track geometry degradation. These materials function primarily to reduce ballast settlement, control moisture infiltration, and extend maintenance intervals on heavy-haul and passenger rail lines. Cement-based formulations occupy the largest volume share due to cost accessibility and compatibility with conventional track renewal equipment. Synthetic polymers represent the fastest-expanding category, driven by demand for rapid-curing systems that minimize track possession windows. Epoxy resin applications concentrate in premium segments where strength improvement specifications justify higher material expenditure.
The European Union Agency for Railways enforces Technical Specifications for Interoperability that mandate ballast binder performance under dynamic stress testing, directly shaping product certification requirements for suppliers seeking network access. India's Ministry of Railways and the Central Pollution Control Board jointly influence material selection through emissions controls on bitumen processing and construction waste protocols. China's Ministry of Ecology and Environment imposes dual carbon goals that restrict high-energy cement production, redirecting procurement toward low-carbon polymer alternatives. Stakeholders must monitor evolving national carbon accounting rules and their downstream effects on binder specification in public tenders.
Market Dynamics
Polymer-modified binder systems are compressing track possession windows from days to hours, forcing cementitious suppliers to accelerate cure chemistry or cede heavy-haul contracts to synthetic alternatives. This technological displacement is restructuring procurement criteria across European and Asian rail networks.
Growth Catalysts
- EU Technical Specifications for Interoperability:Mandated dynamic stress testing for ballast stabilization materials is certifying polymer systems for cross-border freight corridors. Suppliers achieving TSI compliance unlock network access across Germany, France, and Italy.
- China's high-speed rail expansion:Track construction exceeding 40,000 kilometers demands rapid-curing binders that minimize service interruptions. Polyurethane formulations are displacing conventional cement in new line commissioning.
- India's Dedicated Freight Corridor:Monsoon-induced soil instability in Gujarat and Maharashtra corridors is driving procurement of synthetic polymer binders with verified moisture resistance. The Ministry of Railways is specifying these materials in DFC tender documents.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane and epoxy resin formulations face margin compression when crude-derived isocyanates and bisphenol-A experience price spikes. European chemical producers pass through 60-80% of input cost swings.
- Specialized applicator concentration:Certified installation crews for polymer injection systems cluster in Germany, Japan, and eastern China. Infrastructure projects in Africa and Latin America face 8-14 week mobilization delays.
- Cement cost accessibility:Ordinary Portland cement maintains 3-4x price advantage per treated ton. Budget-constrained operators in India and Southeast Asia default to cementitious stabilization despite shorter maintenance intervals.
Strategic Opportunities
- Brazil's Ferrovia Norte-Sul expansion:The 1,500-kilometer northern corridor upgrade lacks established polymer applicator networks. First-mover contractors can anchor regional supply infrastructure before competitor mobilization.
- EU Green Deal carbon accounting:Low-carbon polymer binders earn preferential scoring in public tenders. Suppliers with verified lifecycle assessments capture incremental volume in French and Dutch track renewal programs.
- Sensor-integrated smart binders:Convergence of piezoelectric sensing particles with polyurethane matrices enables real-time track geometry monitoring. Early deployments are concentrating in Japan's Shinkansen maintenance divisions.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for railway-grade systems requires 8-12 years specialized experience. European suppliers report 15-20% vacancy rates in technical service roles.
- Legacy track compatibility:Polymer injection into century-old ballast beds with variable aggregate gradation produces unpredictable cure profiles. Contractors carry performance risk on heterogeneous substrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Ballast Binder Market |
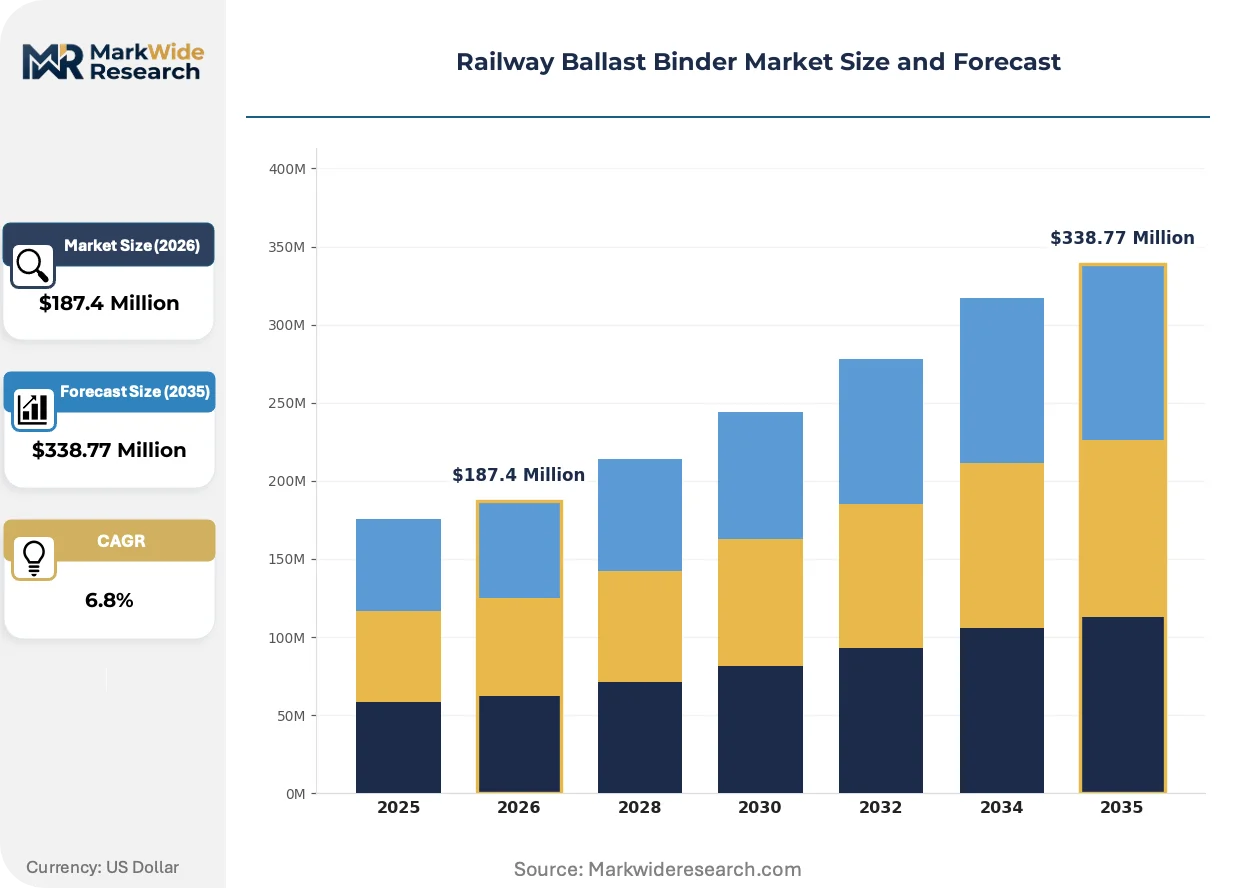
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement, Bitumen, Synthetic Polymers, Epoxy Resin Application: Track Stabilization, Soil Compatibility, Strength Improvement, Moisture Control End User: Railway Construction, Maintenance Services, Engineering Firms, Infrastructure Developers Distribution Channel: Direct Sales, Distributors, Online Retail, Contractors |
| Companies Covered | BASF, Alchemy Spetec, Sika AG, Henkel AG & Co. KGaA, Arkema Group, Jing Jiang City Specific Adhesive, Jiangsu Baoli International, Henan Zhuonengda, Beijing Zhuochuang Hexin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Ballast Binder Market Evolving Landscape
Material science advances and regulatory carbon accounting are converging to elevate polymer systems from niche applications to standard specification in premium rail corridors. Three developments are compressing adoption timelines.
Self-healing polyurethane formulations incorporating microencapsulated repair agents are integrating into high-speed track maintenance protocols. Deutsche Bahn and SNCF are piloting these systems on stress-critical switches and crossings. The technology is integrating predictive maintenance algorithms with material performance, enabling condition-based renewal rather than calendar-driven replacement.
China's Ministry of Ecology and Environment dual carbon goals are restricting clinker production in Shandong and Jiangsu provinces. Provincial procurement guidelines now require carbon intensity disclosures for cementitious binders. Domestic polymer suppliers are capturing volume in coastal corridor projects where low-carbon credentials determine tender scoring.
Rail operators are unbundling material supply from installation service contracts. British Network Rail and Italian RFI are separating binder procurement from applicator selection, enabling direct manufacturer relationships. This disintermediation is most visible in Western European markets where operator technical capabilities support direct specification management.
Railway Ballast Binder Market Segmentation
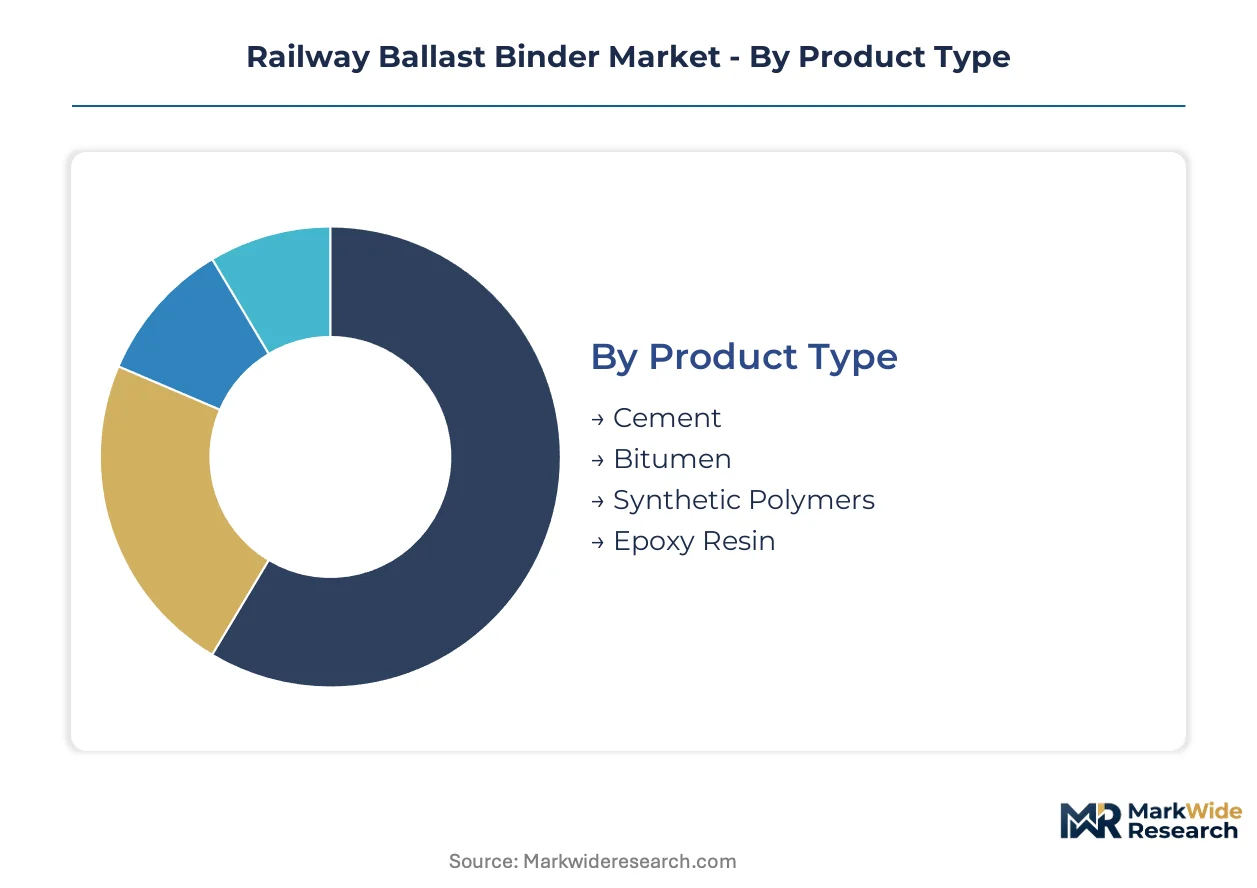
Railway ballast binder procurement splits sharply between standalone material supply and integrated installation contracts. Understanding these segment boundaries clarifies where manufacturers capture margin versus where applicators extract value.
Product Type:
Cementitious formulations operate as standalone commodities with minimal technical service attachment, while synthetic systems demand embedded applicator partnerships for performance guarantees.
- Cement:Ordinary Portland cement dominates procurement volumes through cost accessibility and compatibility with conventional track renewal equipment. Indian Dedicated Freight Corridor projects specify cementitious stabilization for budget-constrained earthwork sections despite requiring shorter maintenance intervals.
- Synthetic Polymers:Polyurethane and acrylic formulations deliver rapid cure profiles that compress track possession windows from days to hours. China's high-speed rail expansion is concentrating procurement of these systems where service continuity commands premium material expenditure.
- Bitumen:Bituminous binders occupy mid-tier applications in heavy-haul corridors with moderate axle loads and controlled moisture exposure.
- Epoxy Resin:Epoxy systems concentrate in premium track segments requiring compressive strength exceeding 40 MPa under dynamic cyclic loading.
Volume placements concentrate in cement; the faster expansion belongs to synthetic polymers.
Application:
Functional requirements determine whether binders deploy as surface treatments or full-depth injection systems, reshaping material specification and contractor certification needs.
- Track Stabilization:Ballast consolidation to prevent geometry degradation under dynamic train loading represents the core functional demand across all rail networks. Deutsche Bahn and SNCF specify polymer-modified systems for high-speed switches where settlement tolerances are tightest.
- Moisture Control:Hydrophobic polymer formulations address monsoon-induced subgrade instability in India's western corridor states. The Ministry of Railways mandates verified moisture resistance certification for DFC tender eligibility.
- Soil Compatibility:Binder selection adapts to expansive clay and loose sandy substrates requiring chemical stabilization beyond mechanical compaction.
- Strength Improvement:High-performance specifications for heavy-haul mineral corridors drive epoxy and advanced polymer adoption where bearing capacity must increase substantially.
Track stabilization commands the largest material offtake; moisture control applications are climbing the fastest as climate adaptation budgets expand.
End User:
Technical capability differentiation separates operators who self-specify materials from those relying on turnkey contractor packages.
- Railway Construction:Greenfield track builders integrate binder selection into permanent way design, enabling upfront polymer specification where speed-to-commissioning drives returns. China's state rail constructors maintain in-house technical teams capable of direct material qualification.
- Maintenance Services:Renewal contractors prioritize rapid-curing systems that minimize track possession windows during operational rail corridors. European infrastructure managers are unbundling material supply from installation to enable direct manufacturer relationships.
- Engineering Firms:Design consultants influence binder specification through performance-based trackbed design standards.
- Infrastructure Developers:Private concession holders in Brazil's Ferrovia Norte-Sul expansion evaluate lifecycle cost models that favor extended maintenance intervals over lowest first-cost materials.
Railway construction absorbs the heaviest volumes; maintenance services are gaining share fastest as renewal cycles accelerate across mature networks.
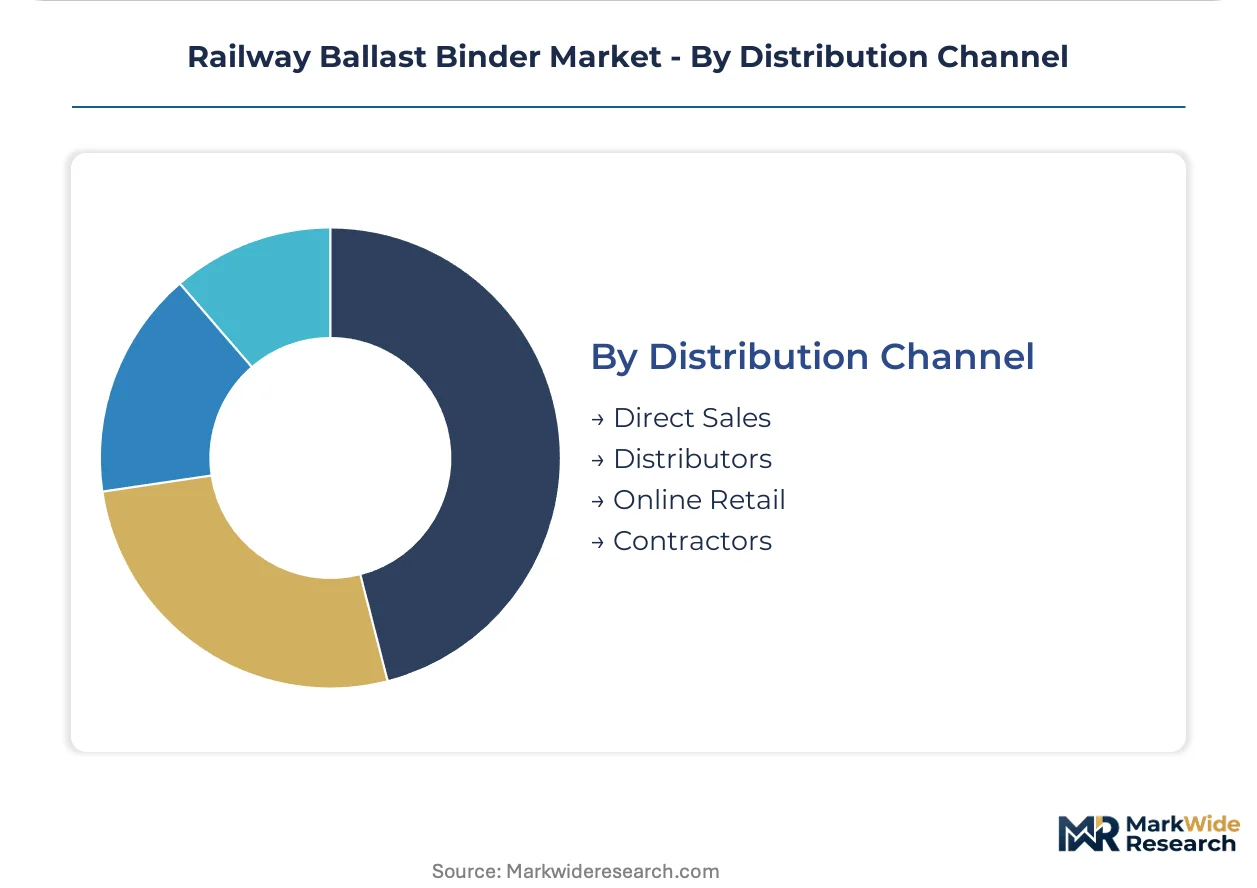
Distribution Channel:
Channel structure reflects the technical complexity of application and the geographic concentration of certified installation capacity.
- Direct Sales:Major polymer suppliers bypass distribution layers for large European rail operators with internal technical specification teams. British Network Rail and Italian RFI procurement frameworks enable direct manufacturer contracting.
- Contractors:Installation-centric channels dominate polymer system delivery where performance guarantees require applicator certification. Certified crews cluster in Germany, Japan, and eastern China, creating regional supply constraints.
- Distributors:Regional stockists serve cementitious and bitumen products for maintenance depots with standardized material requirements.
- Online Retail:Digital channels capture ancillary consumables and small-volume emergency replenishment for remote maintenance sites.
Contractor-integrated channels handle the largest polymer volumes; direct sales are expanding most quickly as operator technical capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Limestone deposits in China's Shandong province anchor cementitious binder production, while petrochemical clusters along Germany's Rhine corridor supply polyurethane feedstocks for European rail networks. Regional procurement patterns diverge sharply between cost-sensitive emerging corridors and premium-performance mature networks.
China
High-speed rail construction exceeding 40,000 kilometers drives polyurethane formulation demand for rapid-curing track stabilization. The Ministry of Ecology and Environment imposes dual carbon goals that restrict clinker production in Shandong and Jiangsu provinces. Domestic polymer suppliers capture volume in coastal corridor projects where low-carbon credentials determine tender scoring.
Germany
Deutsche Bahn's switch and crossing renewal programs specify polymer-modified systems for settlement-critical infrastructure. The EU Agency for Railways enforces Technical Specifications for Interoperability mandating dynamic stress testing for network access. BASF leverages its Ludwigshafen polyurethane expertise to anchor supply for cross-border freight corridors through the Rhine-Ruhr industrial cluster.
India
The Dedicated Freight Corridor projects in Gujarat and Maharashtra drive synthetic polymer procurement for monsoon-induced soil instability. The Ministry of Railways and Central Pollution Control Board jointly influence material selection through emissions controls on bitumen processing. Regional applicator networks concentrate in Mumbai-Pune and Ahmedabad-Vadodara industrial belts.
United States
Class I railroads prioritize extended maintenance intervals on heavy-haul mineral corridors, favoring epoxy systems for bearing capacity enhancement. The Federal Railroad Administration oversees track safety standards without mandating specific binder chemistries. Polymer applicator capacity clusters in Chicago-Gary and Houston-Galveston petrochemical corridors.
Brazil
The Ferrovia Norte-Sul 1,500-kilometer northern corridor upgrade lacks established polymer applicator networks. ANVISA regulates chemical product registration for construction materials without rail-specific protocols. First-mover contractors can anchor regional supply infrastructure in São Paulo state before competitor mobilization.
Railway Ballast Binder Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and installation certification capacity. The vendor base separates into petrochemical conglomerates with polymer research depth, specialized adhesive manufacturers with rail-specific portfolios, and emerging Chinese suppliers with cost-optimized production. Three archetypes dominate: integrated chemical producers, construction chemical specialists, and regional applicator-integrated contractors. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers secure certified installation networks.
Among European chemical producers, BASF SE and Sika AG occupy positions exemplifying integrated research depth and construction chemical specialization respectively. Henkel AG & Co. KGaA represents adhesive technology expertise within the premium performance tier. Chinese suppliers including Jing Jiang City Specific Adhesive and Henan Zhuonengda anchor the cost-optimized production archetype serving domestic high-speed rail expansion.
| Leading Market Players |
|---|
| BASF |
| Alchemy Spetec |
| Sika AG |
| Henkel AG & Co. KGaA |
| Arkema Group |
| Jing Jiang City Specific Adhesive |
| Jiangsu Baoli International |
| Henan Zhuonengda |
| Beijing Zhuochuang Hexin |
| Others |
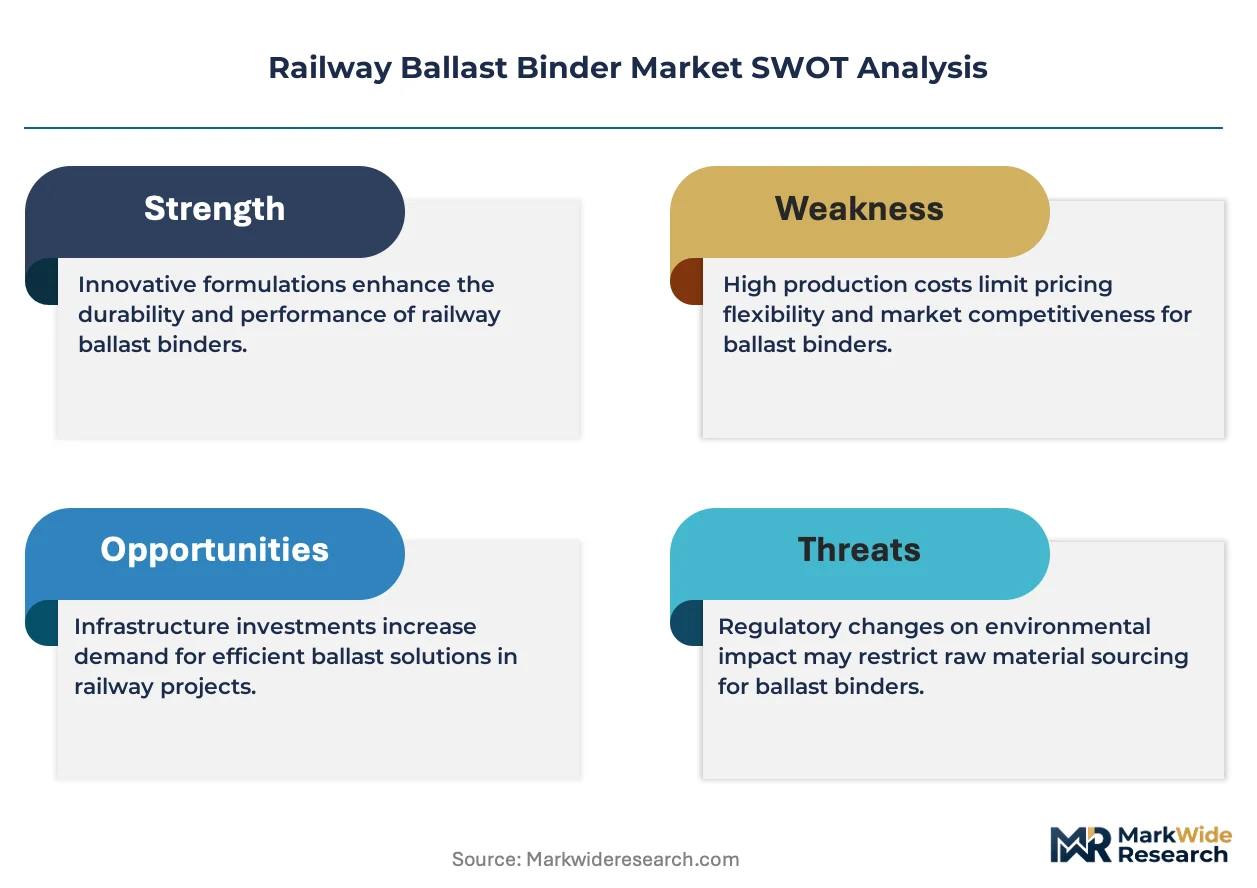
Value Network & Pricing Analysis
China's Ministry of Ecology and Environment dual carbon goals gate qualified supply for polymer-modified railway ballast binders, restricting clinker-intensive cement production in Shandong and Jiangsu provinces while elevating low-carbon polyurethane systems to premium-tier pricing access. Procurement officers in coastal corridor projects now face carbon-intensity disclosures as mandatory tender scoring criteria, compressing margins for conventional suppliers and rewarding certified low-carbon alternatives with pricing power.
Pricing Analysis
Warranty and performance-guarantee bundling separates polymer system pricing tiers, with applicator-integrated contracts commanding substantial premiums over standalone material supply. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with EU Technical Specifications for Interoperability compliance unlocking cross-border network access at the top tier. Cost compression in cementitious formulations is intensifying because of energy price volatility and carbon allowance costs, while budget-constrained operators in India and Southeast Asia exhibit highest price sensitivity. Premium epoxy resin specifications for heavy-haul mineral corridors show lowest price elasticity, with bearing capacity requirements justifying material expenditure.
Supply Chain Analysis
Certification under EU Technical Specifications for Interoperability and India's Ministry of Railways moisture resistance protocols gates supplier participation, filtering uncertified producers from qualified bidder pools. Manufacturing gravity centers on Germany's Rhine-Ruhr petrochemical corridor, China's Shandong-Jiangsu industrial belt, and India's Mumbai-Pune applicator clusters. Feedstock supply draws from crude-derived isocyanates, bisphenol-A, and limestone-based clinker, with petrochemical price volatility transmitting 60-80% of input cost swings to end pricing. Single-source vulnerability concentrates in certified applicator crews clustering in Germany, Japan, and eastern China, creating 8-14 week mobilization delays for projects in Africa and Latin America. Distribution runs through contractor-integrated channels for polymer systems and regional stockists for cementitious commodities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Railway ballast binder competition has become a vertical-integration race, with suppliers pursuing backward integration into petrochemical feedstocks to secure margin control against crude price volatility and carbon-accounting disclosure requirements.
For Market Incumbents: Anticipate displacement pressure from rapid-cure polymer systems by accelerating in-house formulation expertise for polyurethane chemistry or acquiring certified applicator networks in underserved geographies. Cementitious suppliers face margin compression from dual carbon goals restricting clinker production; defensive consolidation through captive limestone reserves in Shandong and low-carbon process retrofits preserves network access. Priority lever: securing EU TSI certification maintenance through dynamic stress testing investment. For New Entrants and Emerging Players: Begin with Brazil's Ferrovia Norte-Sul corridor expansion, where 1,500 kilometers of track upgrade lacks established polymer applicator infrastructure and ANVISA registration protocols remain non-rail-specific. White-space targets include sensor-integrated smart binder development for Japan's Shinkansen maintenance divisions and moisture-resistant formulations for India's western Dedicated Freight Corridor states. Go-to-market angle: direct manufacturer contracting with infrastructure developers evaluating lifecycle cost models over first-cost procurement. For Investors and Strategic Acquirers: Deutsche Bahn and SNCF pilot deployments of self-healing polyurethane formulations are the leading indicator that condition-based renewal protocols will displace calendar-driven replacement schedules, extending addressable market duration for advanced material suppliers. Long-term viability centers on formulation IP depth and certified installation network density rather than commodity scale. Acquisition target archetype: mid-cap polymer specialists with 8-12 year formulation expertise and existing EU TSI compliance. Signal to watch: unbundling of material supply from installation contracts in British Network Rail and Italian RFI procurement frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Applicator Network Expansion | Certified crew mobilization in São Paulo and Ahmedabad-Vadodara corridors captures first-mover infrastructure before competitor entry. |
| Low-Carbon Formulation Development | Polyurethane systems with verified lifecycle assessments earn preferential tender scoring under EU Green Deal carbon accounting rules. |
| Sensor-Integrated Smart Binder R&D | Piezoelectric particle convergence with polyurethane matrices enables real-time track geometry monitoring for Shinkansen operators. |
| Direct Manufacturer Contracting | Bypassing distributor layers with British Network Rail and Italian RFI strengthens margin retention and specification influence. |
| Feedstock Backward Integration | Captive isocyanate supply from Ludwigshafen and Rhine-Ruhr clusters insulates BASF from petrochemical price volatility transmission. |
Research Methodology
Multi-period observation of polymer formulation patent filings, EU TSI certification registrations, and high-speed rail construction permits anchored the trend analysis, supplemented by interviews with track maintenance directors at Deutsche Bahn and SNCF, polymer R&D leads at German chemical producers, procurement officers at India's Dedicated Freight Corridor Corporation, and certified applicator contractors in Japan and eastern China. Secondary validation incorporated customs trade data for isocyanate and bisphenol-A flows, SEC 10-K disclosures from listed chemical conglomerates, ECHA REACH registration databases, and infrastructure tender documents from British Network Rail and Italian RFI. Bottom-up volume estimates from country-level rail construction pipelines triangulated against top-down market sizing from petrochemical feedstock demand modeling.
Input-output matrices mapped polymer binder consumption to high-speed track kilometers commissioned, heavy-haul renewal cycles, and climate-adaptation budgets across the analysis window. Segmentation dimensions included product type tier, application function, end-user technical capability, and distribution channel structure. CAGRs derived from logistic diffusion curves fitted to polymer adoption rates in premium corridor projects, cross-referenced with carbon-accounting policy implementation timelines. Industry-specific forecast inputs incorporated clinker production restrictions under China's dual carbon goals and EU Green Deal preferential scoring mechanics.
Underlying measurement precision varies by segment; synthetic polymer volumes carry tighter precision than cementitious estimates due to concentrated supplier reporting and certification tracking. Forecasts reflect assumptions on rail infrastructure budget continuity, petrochemical feedstock price band stability, and applicator certification pipeline throughput. A model refresh is warranted upon material change in EU carbon border adjustment implementation or China's provincial clinker quota revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Reamer Market
Construction and Engineering
Concrete Protective Liners Market
Construction and Engineering
Work Order Management Market
Construction and Engineering
Drain Cleaning Equipment Market
Construction and Engineering
Horizontal Machining Center Market
Construction and Engineering
Excavation Equipment Market
Construction and Engineering
Construction Project Management Services Market
Construction and Engineering
Woodworking Machines Market
Construction and Engineering
Heavy Movable Bridges Market
Construction and Engineering
HVAC Actuators Market
Construction and Engineering
Italy Metal Fabrication Equipment Market
Construction and Engineering
Draw Heat Setting Winder Market
Construction and Engineering
US Residential and Commercial Roofing Materials Market
Construction and Engineering
Austria Prefabricated Housing Market
Construction and Engineering
China Transportation Infrastructure Construction Market
Construction and Engineering
Canada Manufactured Homes Market